
 Asia-Pacific Bunker Fuel Market | 2026-2036
Asia-Pacific Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bunker Fuel Market Outlook
ISO 8217:2017 marine fuel quality standards are rotating the competitive landscape by disqualifying suppliers lacking certified laboratory networks and traceable custody chains. Shell leverages its integrated trading and terminal infrastructure to sustain supply continuity across Singapore and Hong Kong hubs. PetroChina Company Limited anchors volumes through captive refinery output and dedicated coastal blending facilities. Minerva Bunkering competes on agile barge scheduling and niche port coverage where larger traders maintain lighter presences.
Asia-Pacific bunker fuel denotes residual and distillate marine fuels meeting ISO 8217 density, viscosity, and sulfur specifications, combusted in two-stroke low-speed diesel engines or four-stroke medium-speed propulsion systems to generate shaft power for commercial vessel operation. Heavy fuel oil remains the dominant fuel type by volume despite regulatory compression, while low sulfur fuel oil captures margin pools as the default compliance pathway for vessels without exhaust gas cleaning systems. Container ships and tankers concentrate demand within the vessel type split, with port supply and barge delivery methods commanding infrastructure investment due to draft limitations and alongside bunkering preferences at mega-ports.
IMO 2020 sulfur regulations, China's MEE domestic emission control area designations, and Singapore's MPA mass flow metering mandate collectively reshape product specifications, delivery verification protocols, and supplier licensing requirements across the region. Japan's METI and South Korea's MFDS coordinate national LNG bunkering roadmaps that introduce alternative fuel pathways alongside conventional distillate supply chains. Stakeholders must monitor ECA expansion timelines, alternative fuel pilot project scalability, and refinery upgrade cycles to align procurement strategies with evolving compliance architectures.
Market Dynamics
IMO 2020 sulfur regulations and China's MEE emission control area designations are compressing heavy fuel oil demand while redirecting capital toward LNG bunkering infrastructure and low-sulfur blending capacity across the region's mega-ports.
Growth Catalysts
- MEE ECAs:China's Ministry of Ecology and Environment has designated eleven coastal emission control areas, mandating low-sulfur fuel use and accelerating bonded bunker infrastructure investment along the Pearl River and Yangtze River Delta corridors.
- LNG bunkering pilots:Japan's METI and South Korea's MFDS have published coordinated national roadmaps that establish LNG as a compliance pathway for vessels operating within expanded regional ECAs.
- Mass flow metering:Singapore's MPA mandate for custody-transfer accuracy is standardizing delivery verification protocols and disqualifying suppliers lacking certified laboratory networks.
Market Restraints
- Refinery upgrade cycles:State-owned refiners in China require sustained capital deployment to shift residual fuel output toward low-sulfur specifications, constraining near-term supply elasticity.
- Barge fleet concentration:Licensed bunker barge capacity concentrates in Singapore and Shanghai, creating logistical bottlenecks for vessels calling at secondary ports across Southeast Asia.
- Crude sulfur differentials:Input cost volatility for sour crude streams directly compresses blending margins for low-sulfur fuel oil producers serving the Asia-Pacific compliance market.
Strategic Opportunities
- Vietnam port expansion:Cai Mep and Haiphong container terminals are developing alongside bunkering capabilities that remain underdeveloped relative to vessel throughput growth.
- Biofuel blending pilots:Singapore's MPA and the Maritime and Port Authority of Singapore are trialing B24 marine biofuel deliveries for container lines seeking beyond-compliance carbon intensity reductions.
- Digital bunkering platforms:Real-time barge scheduling and inventory transparency tools are penetrating procurement workflows at mid-size tramp operators previously dependent on voice-brokered spot purchases.
Industry Challenges
- ISO 8217:2017 compliance timelines:Suppliers must maintain traceable custody chains and certified laboratory networks to retain port licenses, compressing smaller traders without integrated quality infrastructure.
- Dual-fuel engineering talent:LNG bunkering operations require specialized cryogenic handling and engine conversion expertise that remains concentrated among Singapore-based technical service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bunker Fuel Market |
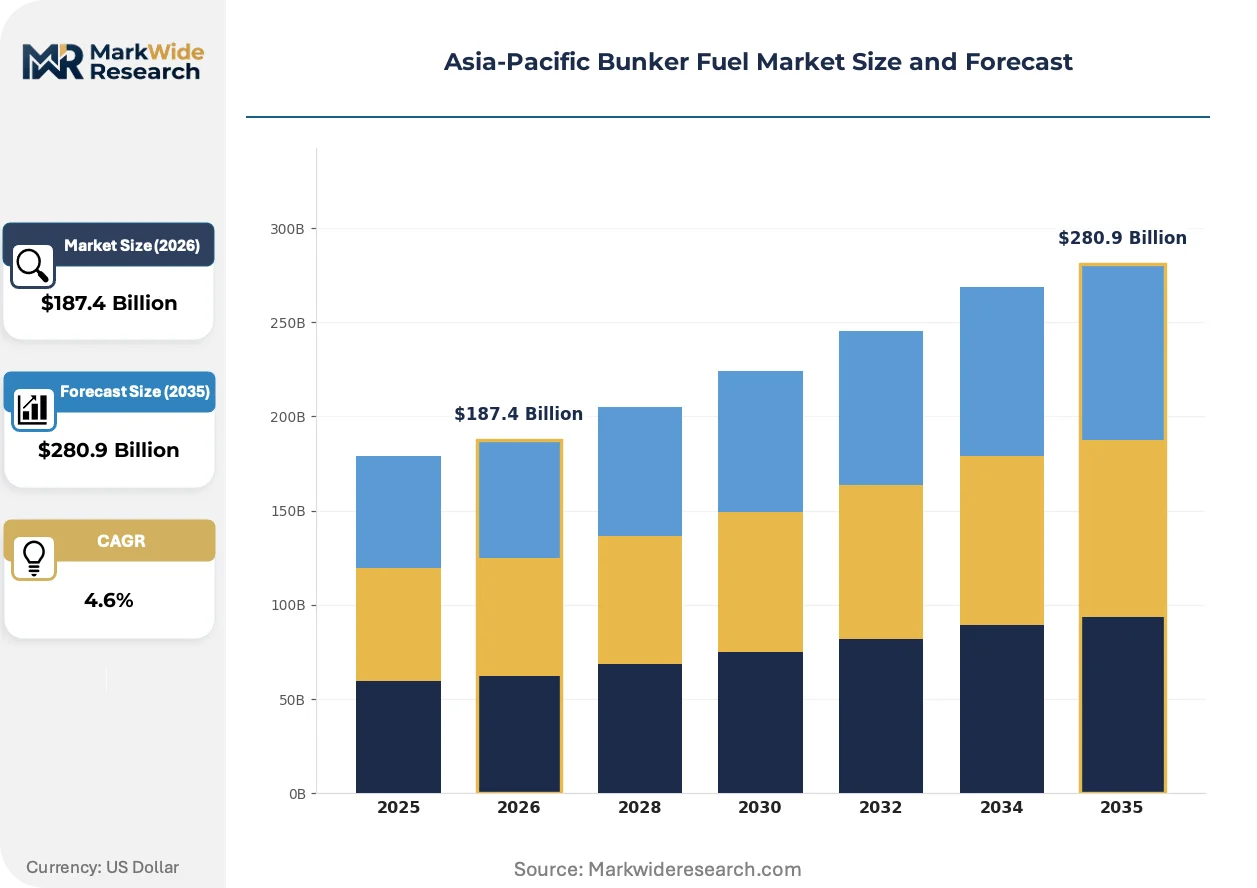
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Marine Diesel Oil, Heavy Fuel Oil, Low Sulfur Fuel Oil, Ultra-Low Sulfur Fuel Oil Delivery Method: Pipeline Supply, Barge Supply, Truck Supply, Port Supply End User: Shipping Companies, Offshore Support Vessels, Cruise Lines, Fishing Industry Vessel Type: Container Ships, Tankers, Bulk Carriers, Feeder Vessels |
| Companies Covered | Vitol Bunkers, Shell, TotalEnergies, Chevron Corporation, ExxonMobil Corporation, Minerva Bunkering, PetroChina Company Limited, Petroliam Nasional Berhad (PETRONAS), TFG Marine Pte. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bunker Fuel Market Strategic Shifts
Alternative fuel pathways and digital delivery verification are restructuring competitive positioning across the Asia-Pacific bunker supply chain, with regulatory mandates accelerating technology deployment ahead of pure economic returns.
Ammonia-ready vessel engineering is displacing conventional two-stroke low-speed diesel specifications in newbuild orders from Japanese and South Korean shipyards. Container lines including those operating Asia-Europe strings are inserting ammonia compatibility clauses into construction contracts despite the absence of established bunkering infrastructure. This technology commitment is compressing the planning horizon for port authorities evaluating multi-fuel terminal investments.
China's MEE has expanded domestic emission control area boundaries to cover the entire coastline, forcing vessels without exhaust gas cleaning systems to switch to low-sulfur fuel oil or marine gas oil prior to coastal entry. The regulation's industrial consequence is a demand spike for bonded bunker supply at Zhoushan and Qingdao relative to Singapore. Refiners with coastal blending facilities are capturing margin pools previously absorbed by traders.
Container shipping lines are consolidating procurement decisions at regional headquarters in Singapore, collapsing the number of counterparties that mid-size bunker suppliers must maintain. Long-term offtake agreements with integrated oil companies are replacing spot market exposure for vessels operating fixed liner schedules. This concentration is most visible among carriers headquartered in Copenhagen and Geneva that manage Asia-Pacific bunkering through dedicated Singapore trading desks.
Asia-Pacific Bunker Fuel Market Segmentation
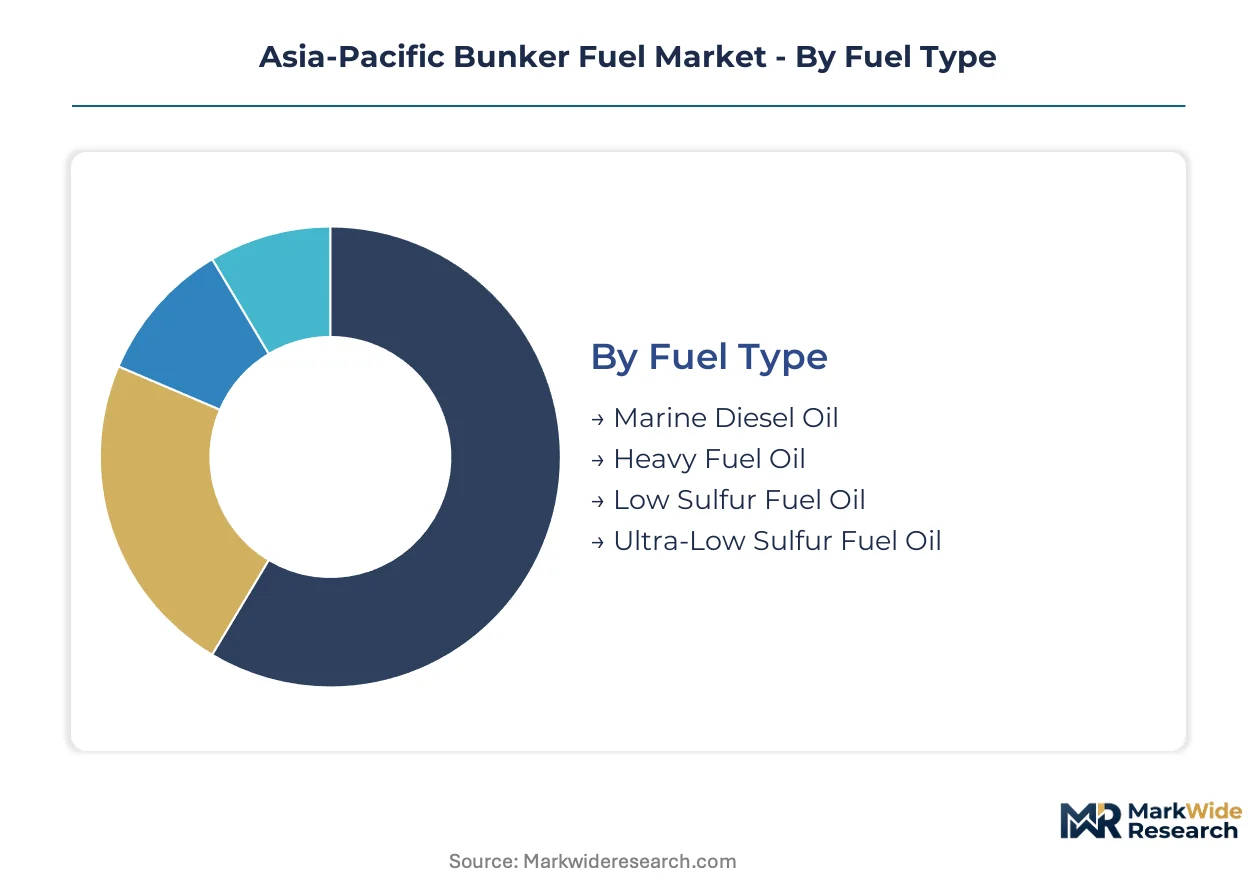
Segmentation in the Asia-Pacific bunker fuel market reveals how regulatory pressure and vessel specifications fragment procurement strategies. Fuel type and delivery method choices directly determine compliance costs and operational flexibility for operators across Singapore, Shanghai, and Busan.
Fuel Type:
Margin pools concentrate in low-sulfur blending operations where refinery upgrades and bonded storage infrastructure create defensive positions.
- Heavy Fuel Oil:Residual fuel with maximum sulfur content of 3.5% pre-IMO 2020, now restricted to vessels equipped with exhaust gas cleaning systems. Demand concentrates among bulk carriers operating Singapore-anchored routes where scrubber economics justify continued use despite regulatory compression.
- Low Sulfur Fuel Oil:Blended residual-distillate mixture meeting 0.5% sulfur caps through ISO 8217:2017 certification. Procurement volumes cluster at Zhoushan and Qingdao where Chinese state-owned refiners have expanded coastal blending capacity to capture margin pools previously absorbed by traders.
- Marine Diesel Oil:Distillate fuel with lower viscosity and energy density than residual grades, typically reserved for auxiliary engines and cold-weather operations. Fishing fleets along Japan's northern coast favor this specification for engine reliability.
- Ultra-Low Sulfur Fuel Oil:Distillate-grade fuel meeting 0.1% sulfur requirements for emission control area operations. Cruise lines calling at Shanghai and Shenzhen ports procure this grade to ensure compliance without operational switching delays.
The dominant share belongs to Low Sulfur Fuel Oil, while Ultra-Low Sulfur Fuel Oil is gaining share fastest as China's MEE expands coastal ECA boundaries.
Delivery Method:
Cost structures diverge sharply based on infrastructure density, with port-side concentration in Singapore and Shanghai creating tiered service availability.
- Barge Supply:Alongside fuel delivery via double-hulled bunker vessels represents the default method for container ships and tankers at mega-ports. Licensed barge capacity concentrates in Singapore and Shanghai, creating logistical constraints for vessels calling at secondary Southeast Asian ports.
- Port Supply:Terminal-based ex-pipe delivery from coastal storage facilities enables high-volume transfers for vessels with compatible manifold configurations. Zhoushan's bonded bunker infrastructure expansion has shifted procurement gravity toward this method for China-flagged tonnage.
- Pipeline Supply:Direct refinery-to-terminal transfer serving integrated supply chains at major hub ports. Limited to Rotterdam-scale infrastructure investments not replicated across most Asia-Pacific locations.
- Truck Supply:Road-based delivery for smaller vessels and offshore support craft at ports lacking dedicated marine fuel terminals. Feeder vessels at secondary Indonesian and Philippine ports rely on this method despite throughput limitations.
Barge Supply commands the largest operational footprint, though Port Supply is expanding most quickly as Chinese coastal infrastructure matures.
End User:
Procurement sophistication varies by fleet scale, with container lines consolidating decisions at Singapore headquarters while fragmented operators remain price-takers.
- Shipping Companies:Container lines and bulk operators managing global fleets anchor regional demand volumes. Copenhagen and Geneva-headquartered carriers have collapsed counterparty relationships to integrated oil companies through long-term offtake agreements.
- Offshore Support Vessels:Supply boats and anchor handlers serving oil and gas installations require marine gas oil for engine reliability in dynamic positioning operations. Demand clusters at Busan and Singapore where offshore fleet registries concentrate.
- Cruise Lines:Passenger vessel operators with stringent emissions profiles and brand-sensitive sustainability commitments. Operators trial B24 biofuel blends at Singapore under MPA pilot programs.
- Fishing Industry:Artisanal and industrial fleets with dispersed port calls and limited storage economics. Procurement remains spot-market dependent with minimal supplier loyalty.
Shipping Companies dominate procurement volumes, while Offshore Support Vessels are climbing the fastest as Southeast Asian offshore activity expands.
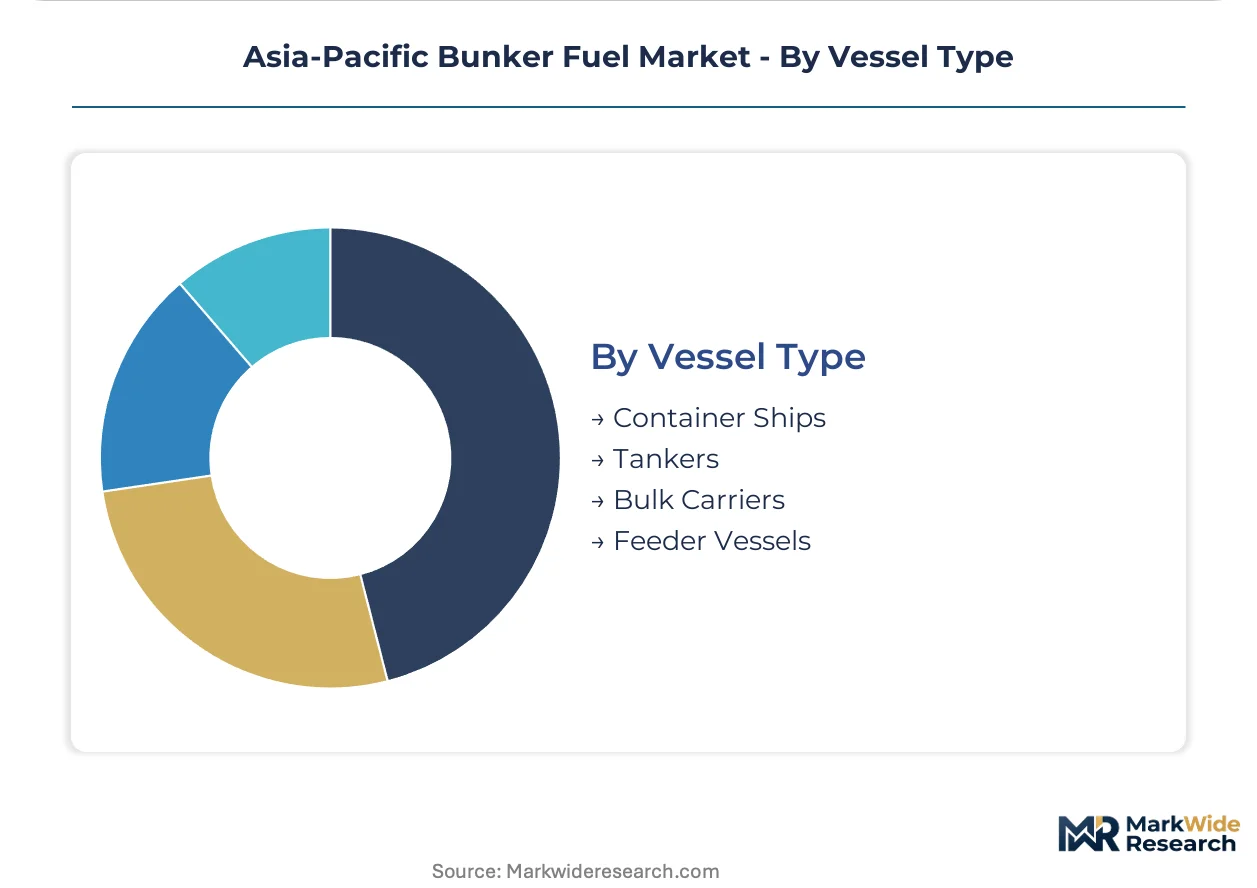
Vessel Type:
Engine specifications and trading patterns create distinct fuel consumption profiles that suppliers must match with inventory positioning.
- Container Ships:Two-stroke low-speed diesel engines optimized for continuous operation at design speeds. Asia-Europe string operators at Singapore and Shanghai anchor the region's largest consistent demand blocks.
- Tankers:Crude and product carriers with similar engine specifications but more variable routing patterns. Dirty tanker trades concentrate procurement at Zhoushan relative to clean product movements.
- Bulk Carriers:Capesize and Panamax vessels with scrubber-equipped fleets maintaining heavy fuel oil demand. Iron ore trades from Western Australia to China sustain this segment's fuel mix.
- Feeder Vessels:Smaller container and general cargo ships operating intra-regional routes with limited onboard storage. Short-haul patterns favor marine gas oil for operational flexibility at multiple port calls.
Container Ships retain the dominant demand share, though Feeder Vessels are expanding most quickly as intra-Asia trade lane density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore's mass flow metering infrastructure anchors regional bunkering integrity. Shanghai's bonded bunker terminals and Busan's LNG-ready facilities complete the tripartite hub structure. China's coastal refinery network redirects procurement gravity northward from traditional Singapore dominance.
China
Zhoushan and Qingdao bonded terminals capture container line volumes as MEE emission control areas force low-sulfur switching. State-owned refiners PetroChina and Sinopec expand coastal blending capacity along Yangtze River Delta corridors. Pearl River Delta port authorities at Shenzhen and Guangzhou develop dedicated marine fuel terminals to bypass Singapore intermediation.
Singapore
MPA custody-transfer mandates disqualify uncertified suppliers while preserving hub status for Geneva and Copenhagen-headquartered carriers. Mass flow metering infrastructure investment exceeds regional peers. Jurong Island storage and blending facilities anchor integrated supply chains for Asia-Europe string operators.
South Korea
Busan-Ulsan corridor develops LNG bunkering pilots under MFDS national roadmap coordination. Hyundai Heavy Industries and DSME newbuild orders incorporate ammonia-ready engine specifications. Korean Register certification requirements compress supplier eligibility to integrated oil companies with cryogenic handling capabilities.
Japan
METI coordinates LNG bunkering infrastructure at Yokohama and Nagoya alongside conventional marine gas oil supply. Fishing fleets along Hokkaido and northern Tohoku maintain distillate demand for auxiliary engine reliability. Japanese shipyards insert ammonia compatibility clauses into container vessel construction contracts despite absent bunkering infrastructure.
Vietnam
Cai Mep and Haiphong container terminals develop alongside bunkering capabilities lagging throughput growth. Secondary port status attracts mid-size traders with agile barge scheduling rather than integrated oil company presence. Draft limitations at Vietnamese ports favor truck supply methods for feeder vessels despite throughput constraints.
Asia-Pacific Bunker Fuel Market Competitive Environment
Listed leaders compete with private specialists across custody-chain certification and terminal infrastructure. The supplier base concentrates around integrated oil companies with captive refinery output and dedicated coastal storage. Three archetypes dominate: integrated majors leveraging trading and terminal networks, state-owned refiners controlling bonded blending capacity, and agile specialists competing on barge scheduling and niche port coverage. Competitive moves center on refinery upgrade cycles for low-sulfur production and LNG bunkering infrastructure partnerships with port authorities.
Within the integrated major tier, Shell and ExxonMobil anchor positions through Singapore and Hong Kong hub infrastructure. Vitol Bunkers occupies a position among trading houses with flexible cargo sourcing and floating storage capabilities. PetroChina Company Limited represents state-owned refiner archetypes with captive coastal blending facilities and bonded terminal control at Zhoushan. Minerva Bunkering exemplifies specialist competitors targeting secondary ports where larger traders maintain lighter presences.
| Leading Market Players |
|---|
| Vitol Bunkers |
| Shell |
| TotalEnergies |
| Chevron Corporation |
| ExxonMobil Corporation |
| Minerva Bunkering |
| PetroChina Company Limited |
| Petroliam Nasional Berhad (PETRONAS) |
| TFG Marine Pte. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between container lines and integrated oil companies lock in both supply access and price visibility, compressing spot market exposure for vessels operating fixed Asia-Europe schedules while Singapore's MPA mass flow metering mandate standardizes custody-transfer verification across bonded bunker terminals.
Pricing Analysis
Volume-discount tiering separates mega-container lines purchasing through annual contracts from tramp operators procuring on voice-brokered spot markets. Price differentiation hinges on ISO 8217:2017 certification grade and barge scheduling flexibility, with premium tiers commanding certainty at Singapore and Zhoushan hubs. Pricing pressure intensifies as Chinese state-owned refiners expand coastal blending capacity, eroding trader margins previously protected by supply scarcity. Tramp operators exhibit highest price sensitivity due to fragmented procurement decisions and limited storage economics, while Copenhagen and Geneva-headquartered carriers leverage consolidated volumes for contractual discounts.
Supply Chain Analysis
Malacca Strait transit underwrites feedstock flows to Singapore's Jurong Island storage and blending facilities, creating a logistical chokepoint where vessel queuing directly impacts delivery scheduling across Southeast Asian ports. Supply concentrates in Singapore, Shanghai, and Zhoushan, with bonded terminal capacity expanding fastest along China's Yangtze River Delta corridors. Raw material dependencies include sour crude streams from Middle Eastern exporters and low-sulfur distillate components from South Korean and Japanese refiners. Single-source vulnerability concentrates in licensed barge fleets where Singapore and Shanghai anchor regional capacity, constraining secondary port access. Distribution runs through integrated oil company terminal networks and specialist barge operators with MPA-certified custody chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific bunker fuel sits in early-cycle expansion as China's MEE emission control area designations accelerate bonded infrastructure investment and low-sulfur blending capacity buildout across coastal refinery networks.
For Market Incumbents: Consolidate terminal infrastructure control through dedicated coastal storage investments at Zhoushan and Qingdao, capturing margin pools as state-owned refiners displace trader intermediation. Deepen backward integration into refinery upgrade cycles for low-sulfur residual production, defending position against agile specialists competing on barge scheduling at secondary Vietnamese and Indonesian ports. For New Entrants and Emerging Players: Lead with digital bunkering platforms targeting mid-size tramp operators previously dependent on voice-brokered spot purchases, offering real-time inventory transparency and barge scheduling automation. Target Vietnam's Cai Mep and Haiphong container terminals where alongside bunkering capabilities lag throughput growth, establishing presence before integrated oil companies extend hub infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward specialist barge operators with MPA-certified laboratory networks and niche port coverage, as regulatory compliance timelines compress smaller traders lacking traceable custody chains. Watch LNG bunkering pilot scalability at Busan and Yokohama as the inflection indicator for alternative fuel pathway viability beyond conventional low-sulfur blends.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Upgrade for Low-Sulfur Production | PetroChina and Sinopec capture margin pools previously absorbed by traders at Zhoushan bonded terminals. |
| LNG Bunkering Infrastructure Partnership | Busan-Ulsan corridor pilots under MFDS roadmap establish cryogenic handling capabilities for dual-fuel vessels. |
| Mass Flow Metering Certification Investment | Singapore's MPA mandate disqualifies uncertified suppliers while preserving hub integrity for Geneva-headquartered carriers. |
| Digital Bunkering Platform Deployment | Real-time scheduling tools penetrate procurement workflows at mid-size tramp operators with fragmented counterparty relationships. |
| Biofuel Blending Pilot Expansion | Singapore's MPA B24 marine biofuel trials attract container lines seeking beyond-compliance carbon intensity reductions. |
Study Parameters
Cross-validation between bunker supplier procurement executives and port authority licensing officers anchors the qualitative findings, with secondary validation drawing from MPA regulatory filings, MEE emission control area designations, customs bonded terminal throughput data, and refinery capacity expansion disclosures. Primary interviews captured perspectives from Singapore-based trading desk heads, Zhoushan terminal operations managers, container line fuel procurement directors, and barge fleet scheduling coordinators. Bottom-up vessel demand modeling triangulates against top-down refinery output and bonded storage capacity assessments.
Sensitivity analysis across crude sulfur differential scenarios and ECA expansion timelines shapes the analytical framework, with segmentation dimensions spanning fuel type, delivery method, end user, and vessel type alongside regional regulatory cluster differentiation. CAGRs derive from compound growth trajectory analysis applied to procurement volume and infrastructure investment flows throughout the forecast period. Industry-specific inputs include scrubber-equipped fleet penetration rates and LNG bunkering pilot project scalability assumptions.
Forecasts assume regulatory continuity in China's MEE enforcement and Singapore's MPA custody-transfer mandates; material policy shifts would require re-modeling supply elasticity and compliance cost structures. Practitioners should keep alternative scenarios live as ammonia-ready vessel engineering commitments and biofuel blend commercialization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline Market
Fuels
Solid Recovered Fuel Market
Fuels
Heavy Fuel Oil Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Coal Trading Market
Fuels
Europe Bunker Fuel Market
Fuels
Wood Pellet Market
Fuels
Fuel Analyzer Market
Fuels
Biobutanol Market
Fuels
Oil Dispensing Stations Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Methane Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
China LNG Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market