
 Global Stem Cell Assay Market | 2026-2036
Global Stem Cell Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stem Cell Assay Market Foresight
Singapore is narrowing its gap with established Western biotech clusters through dedicated stem cell research parks and streamlined biosafety frameworks. Thermo Fisher Scientific leverages its end-to-end reagent-instrument ecosystem to dominate high-throughput screening workflows for induced pluripotent stem cell applications. Merck KGaA sustains competitive positioning through backward integration into cytokine and media formulations that anchor assay reproducibility. STEMCELL Technologies specializes in niche protocols for hematopoietic stem cell expansion, occupying a defensible position in blood disorder research segments.
Stem cell assays comprise standardized analytical protocols that measure cellular viability, differentiation capacity, genetic stability, and functional potency using fluorescence-based detection, reporter gene systems, and multi-parameter flow cytometry readouts; these methods serve the primary commercial purpose of qualifying cell therapy products for clinical release and supporting drug toxicity screening in preclinical pipelines. Cell viability and differentiation assay categories command the largest revenue share due to their mandatory inclusion in regulatory submission packages for cell-based therapeutics. Flow cytometry technology leads instrument-based spending, though PCR-based gene expression analysis is gaining fastest among emerging cell therapy developers seeking clonality and identity confirmation.
The FDA enforces Current Good Manufacturing Practice standards for assay validation in cell therapy manufacturing, while the EMA's Guideline on Quality, Non-Clinical and Clinical Aspects of Medicinal Products Comprised of Autologous Cells mandates specific potency assay designs that shape product development roadmaps in Europe. ISO 10993 biocompatibility testing standards and WHO guidance on cell substrate characterization further harmonize international quality expectations for assay reproducibility. Stakeholders must monitor evolving regulatory divergence between the FDA's risk-based framework and China's NMPA cell therapy guidelines, as this fragmentation will determine where developers prioritize clinical assay qualification investments.
Market Dynamics
The FDA's tightened assay validation requirements for cell therapy characterization are forcing developers to rebuild analytical pipelines from the ground up, compressing timelines and redistributing capital toward in-house qualification infrastructure.
Growth Catalysts
- Regulatory harmonization:The EMA's Guideline on Quality, Non-Clinical and Clinical Aspects of Medicinal Products Comprised of Autologous Cells mandates specific potency assay designs that accelerate product development roadmaps across Europe.
- Biomanufacturing infrastructure:Singapore's dedicated stem cell research parks and streamlined biosafety frameworks attract contract development organizations seeking lower regulatory friction than Western jurisdictions.
- Fluorescence-based detection:Advanced reporter gene systems and multi-parameter flow cytometry readouts enable simultaneous measurement of cellular viability, differentiation capacity, and genetic stability in single workflows.
Market Restraints
- Specialized reagent concentration:Cytokine and media formulation supply chains concentrate among limited qualified suppliers, creating input cost volatility for assay reproducibility.
- Validation timeline compression:Current Good Manufacturing Practice standards enforce extended qualification periods that delay clinical release of cell therapy products.
- Technical standardization gaps:Divergent WHO guidance on cell substrate characterization against ISO 10993 biocompatibility testing standards creates protocol fragmentation across international markets.
Strategic Opportunities
- Underpenetrated hematopoietic protocols:Blood disorder research segments in India lack standardized expansion assays, opening white space for specialized media formulations.
- PCR-based clonality confirmation:Emerging cell therapy developers in South Korea seek gene expression analysis for identity verification faster than traditional karyotyping permits.
- AI-driven image analysis:Machine learning convergence with high-content screening platforms automates morphological assessment of induced pluripotent stem cell colonies.
Industry Challenges
- Assay scientist scarcity:Multi-parameter flow cytometry expertise concentrates in academic centers, forcing commercial developers to compete for limited qualified talent.
- Equipment qualification burden:Instrument-based spending on cell sorting platforms requires substantial capex commitments that strain emerging biotech balance sheets.
- Cross-platform data integration:Legacy laboratory information management systems resist seamless incorporation of real-time potency tracking from novel reporter gene outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stem Cell Assay Market |
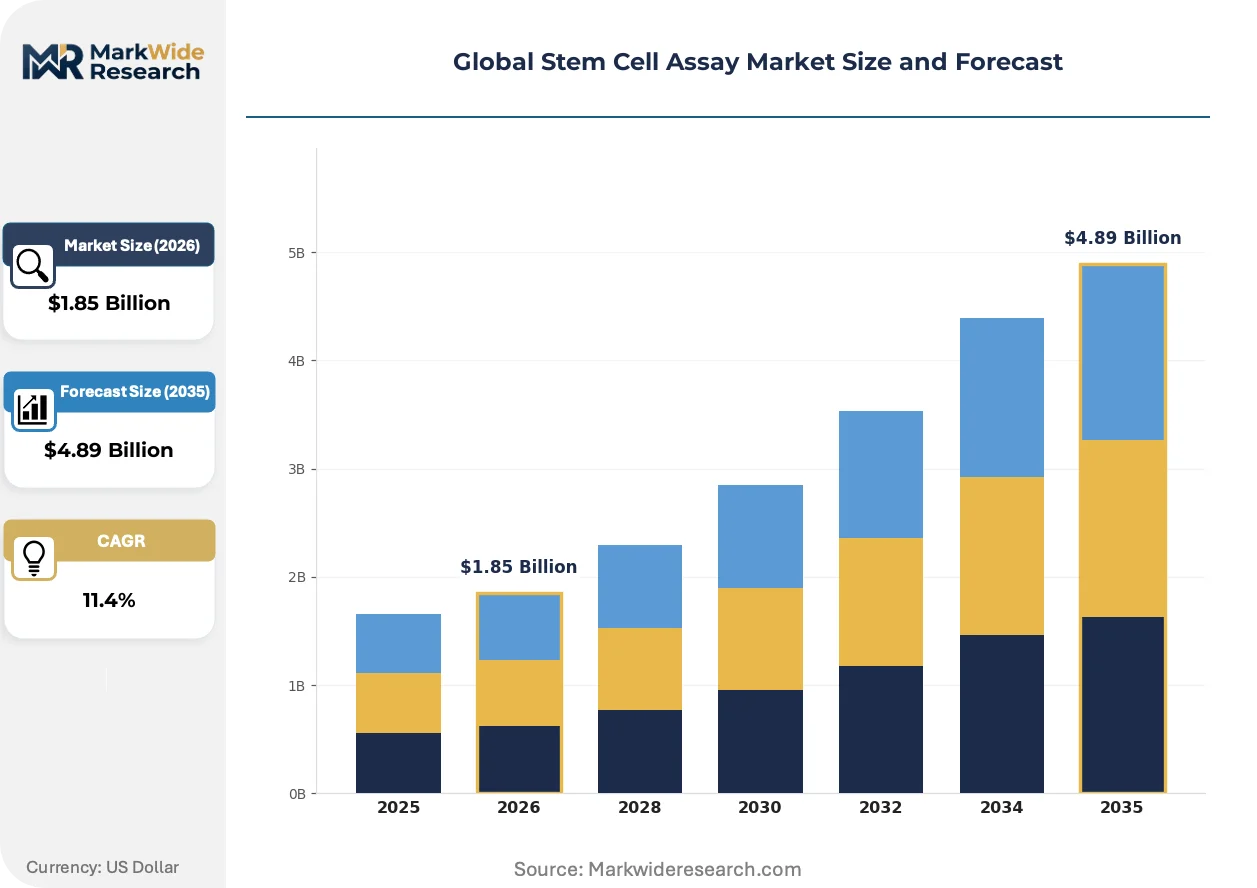
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assay Type: Cell Viability, Proliferation, Differentiation, Toxicity, Gene Expression End User: Contract Research Organizations, Academic Institutions, Pharmaceutical Companies, Biotech Firms, Diagnostic Labs Technology: Flow Cytometry, Immunocytochemistry, PCR, ELISA, Microscopy Sample Source: Embryonic Stem Cells, Induced Pluripotent Stem Cells, Mesenchymal Stem Cells, Hematopoietic Stem Cells, Neural Stem Cells |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, STEMCELL Technologies Inc., Corning Incorporated, Danaher Corporation, Bio-Rad Laboratories, Inc., Becton, Dickinson and Company, Lonza Group, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stem Cell Assay Market Shifts & Advancements
Digital twin architectures and computational modeling are compressing physical screening cycles, while regulatory agencies accelerate guidance publication to match technical velocity. These forces are reconfiguring how assay developers prioritize capital deployment.
Organ-on-chip platforms are virtualizing preclinical toxicity assessment by replicating human tissue microenvironments with vascularized stem cell-derived organoids. Large pharmaceutical developers now embed these systems into lead optimization workflows, replacing a portion of animal studies. This virtualization is compressing IND-enabling timelines and redirecting analytical chemistry resources toward in silico prediction validation.
The FDA's risk-based framework for cell therapy manufacturing now explicitly references process analytical technology principles that mandate real-time release testing. This industrial consequence forces developers to install continuous monitoring systems rather than batch-end qualification. Autologous cell therapy products face the steepest compliance burden, with manufacturers in the United States rebuilding facilities to accommodate automated in-process sampling.
Consolidated procurement functions at major biopharmaceutical buyers now demand outcome-based assay performance guarantees rather than reagent volume contracts. CDMOs and in-house manufacturing groups negotiate total-cost-per-qualified-batch agreements that transfer analytical failure risk upstream to reagent suppliers. This restructuring is most visible in the United States, where NIH-funded regenerative medicine consortia pilot consolidated purchasing for shared core facilities.
Global Stem Cell Assay Market Segmentation
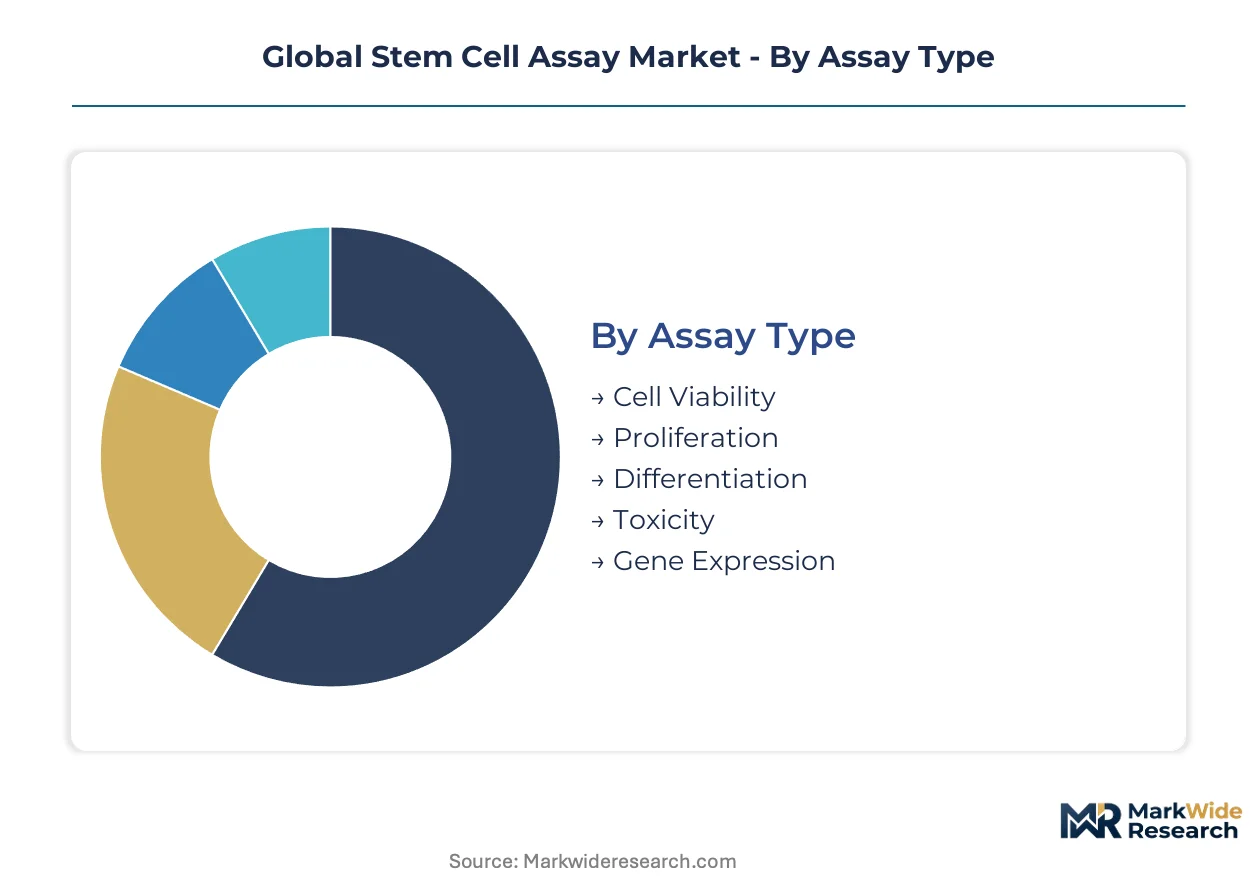
Stem cell assay segmentation reveals how technical specialization and regulatory pressure fragment purchasing decisions across distinct workflow requirements. Each dimension—assay purpose, user capability, detection platform, and cell source—creates separate vendor qualification criteria that reshape competitive positioning.
Assay Type:
Mature protocols dominate routine manufacturing release, while emerging analytical methods reshape early-stage characterization.
- Cell Viability:Fluorescence-based metabolic activity assays measure mitochondrial function through resazurin reduction or ATP quantification. Pharmaceutical companies in the United States embed these into FDA-mandated release specifications for autologous cell therapy products, compressing turnaround windows to under four hours.
- Proliferation:Bromodeoxyuridine incorporation and Ki-67 staining track division kinetics across expansion protocols. Academic institutions in Singapore leverage these assays to optimize feeder-free culture conditions for induced pluripotent stem cell banking.
- Differentiation:Lineage-specific marker panels confirm intended phenotypic outcomes in directed differentiation workflows.
- Toxicity:Hepatocyte and cardiomyocyte-derived assays screen compound liabilities before IND submission.
- Gene Expression:Quantitative PCR and RNA sequencing verify pluripotency marker retention and transgene integration.
Cell viability retains volume leadership; gene expression holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, from consolidated purchasing consortia to fragmented principal-investigator buying.
- Contract Research Organizations:CDMOs operate high-throughput screening platforms serving multiple sponsors under divergent quality agreements. Singapore's stem cell research parks attract these organizations seeking streamlined biosafety approvals and lower facility costs than Western jurisdictions permit.
- Academic Institutions:University core facilities balance service revenue against publication-driven method development. NIH-funded regenerative medicine consortia in the United States pilot shared assay qualification to reduce per-laboratory validation burdens.
- Pharmaceutical Companies:In-house manufacturing groups rebuild analytical pipelines to meet tightened FDA characterization guidance.
- Biotech Firms:Emerging developers outsource potency assay development to conserve capital for clinical manufacturing.
- Diagnostic Labs:Clinical reference laboratories adopt cell-based assays for rare disease diagnostic confirmation.
Pharmaceutical companies command the highest per-site spending; biotech firms are expanding most quickly.
Technology:
Detection platform selection trades throughput against information density and regulatory acceptance.
- Flow Cytometry:Multi-parameter cell sorting enables simultaneous viability, identity, and purity assessment in single workflows. The technology anchors instrument-based spending across commercial manufacturing sites, though equipment qualification consumes substantial capex.
- PCR:Quantitative amplification methods gain fastest among emerging cell therapy developers in South Korea seeking clonality and identity confirmation faster than traditional karyotyping permits.
- Immunocytochemistry:Antibody-based protein detection localizes lineage markers in adherent cultures.
- ELISA:Soluble factor quantification supports potency assay design for secreted product attributes.
- Microscopy:High-content imaging platforms automate morphological assessment with machine learning convergence.
Flow cytometry retains volume leadership; PCR holds the steepest expansion curve.
Sample Source:
Cell type determines assay complexity, from standardized immortal lines to patient-specific autologous materials.
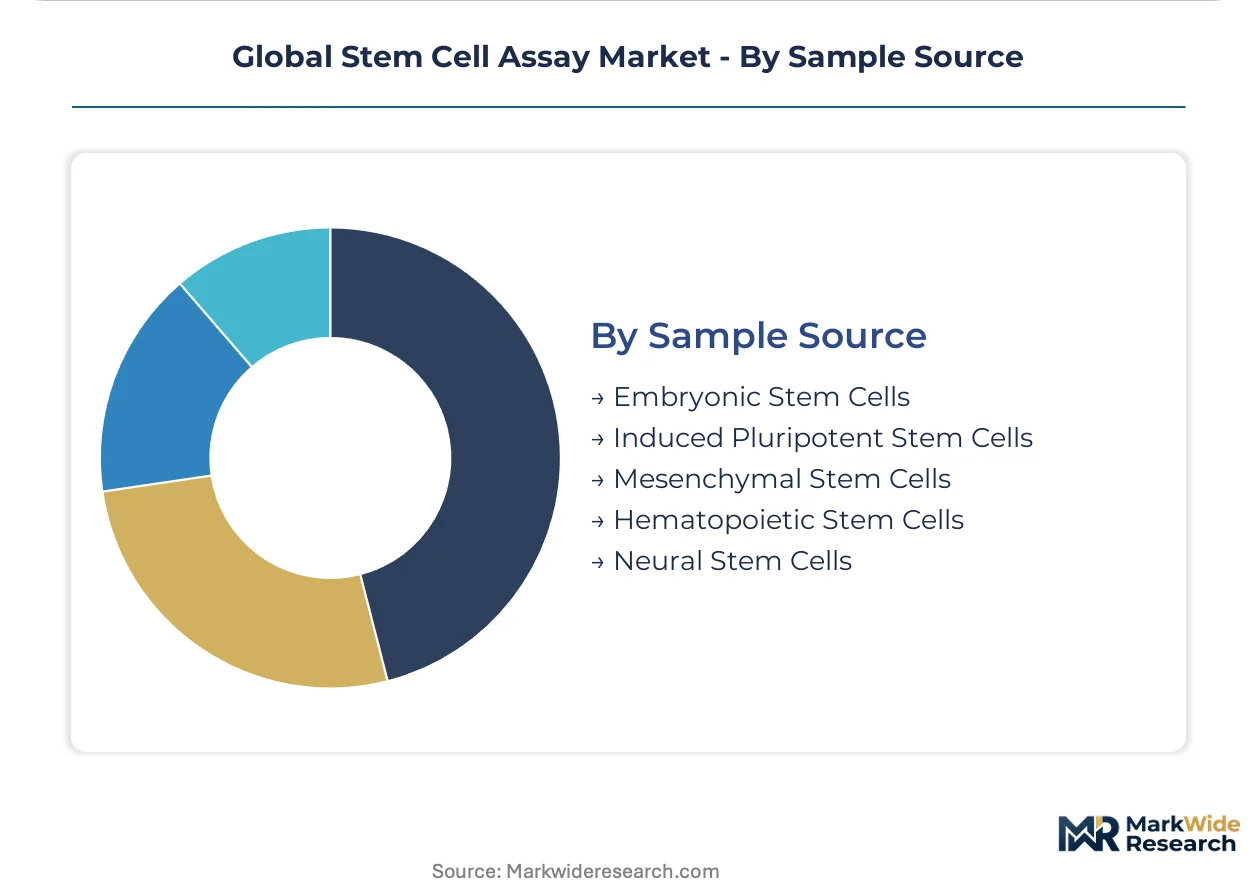
- Induced Pluripotent Stem Cells:Reprogrammed somatic cells enable disease modeling and allogeneic master cell bank construction. Thermo Fisher Scientific's end-to-end reagent-instrument ecosystem dominates high-throughput screening workflows for these applications.
- Hematopoietic Stem Cells:Blood-forming progenitors require specialized expansion protocols for bone marrow transplant and gene therapy manufacturing. STEMCELL Technologies occupies a defensible position through niche media formulations serving this segment.
- Mesenchymal Stem Cells:Stromal populations from bone marrow or adipose tissue dominate current clinical trials.
- Embryonic Stem Cells:Established lines retain utility in early discovery despite regulatory complexity.
- Neural Stem Cells:Central nervous system progenitors attract neurodegenerative disease research investment.
Mesenchymal stem cells retain volume leadership; induced pluripotent stem cells hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA assay validation requirements anchor the United States as the dominant geography, though Singapore, Germany, South Korea, and India are building specialized infrastructure that redistributes analytical capability across jurisdictions.
United States
NIH regenerative medicine consortia and private foundation funding sustain demand for high-throughput screening infrastructure. The FDA's Current Good Manufacturing Practice standards enforce extended qualification periods that compress clinical timelines. Greater Boston and the San Francisco Bay Area concentrate contract development organizations rebuilding analytical pipelines to meet tightened characterization guidance.
Singapore
Dedicated stem cell research parks attract biomanufacturing investment seeking lower regulatory friction than Western jurisdictions. Streamlined biosafety frameworks from the national biotech regulator accelerate facility licensing for contract research organizations. The one-north research corridor houses CDMOs serving regional sponsors under divergent quality agreements.
Germany
EMA potency assay mandates shape product development roadmaps for autologous cell therapies across European manufacturing sites. The Guideline on Quality, Non-Clinical and Clinical Aspects of Medicinal Products Comprised of Autologous Cells harmonizes validation requirements. Heidelberg and Munich anchor industrial clusters where pharmaceutical companies embed process analytical technology principles into automated facilities.
South Korea
MFDS cell therapy guidelines and emerging developer demand for faster identity verification drive PCR-based gene expression adoption. Clonality confirmation workflows displace traditional karyotyping in preclinical pipelines. Seoul Capital Area biotech clusters specialize in induced pluripotent stem cell applications for regional pharmaceutical sponsors.
India
Underpenetrated hematopoietic expansion protocols in blood disorder research create white space for specialized media formulations. CDSCO regulatory pathways for cell-based therapeutics remain less prescriptive than FDA or EMA frameworks, attracting cost-sensitive development programs. Maharashtra and Karnataka house academic core facilities piloting shared assay qualification to reduce per-laboratory validation burdens.
Global Stem Cell Assay Market Competitive Landscape
Capability concentration sits with diversified life science conglomerates; scale advantage sits with specialized reagent suppliers. The vendor base organizes around three tiers: end-to-end workflow providers, component specialists, and regional distributors. Strategic archetypes include integrated reagent-instrument ecosystems, backward-integrated cytokine formulators, and niche protocol developers. Dominant competitive moves encompass outcome-based performance guarantees and consolidated procurement negotiations that transfer analytical failure risk upstream.
Within the integrated ecosystem tier, Thermo Fisher Scientific Inc. exemplifies end-to-end reagent-instrument positioning for high-throughput applications. Merck KGaA represents backward-integrated supply control through captive cytokine and media formulation production. STEMCELL Technologies Inc. occupies a defensible specialist position in hematopoietic stem cell expansion protocols, anchoring blood disorder research segments where standardized assays remain underdeveloped.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| STEMCELL Technologies Inc. |
| Corning Incorporated |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Becton, Dickinson and Company |
| Lonza Group |
| PerkinElmer, Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on qualified cytokine suppliers from Switzerland and Germany determines both tiered reagent pricing spreads and the geographic shape of assay manufacturing networks. This concentration forces buyers into long-term offtake agreements that compress margins for emerging cell therapy developers while insulating established pharmaceutical manufacturers from spot price volatility.
Pricing Analysis
United States-based pharmaceutical manufacturers pay 30-40% premiums over Indian academic core facilities for identical GMP-grade viability assay kits. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated release specifications from research-use-only formulations and bulk unqualified reagents. Pricing pressure stems from consolidated procurement functions at NIH-funded consortia demanding outcome-based performance guarantees. Biotech firms exhibit highest price sensitivity due to capital constraints, while in-house manufacturing groups at major pharmas prioritize regulatory certainty over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for PCR enzyme and fluorescence dye sourcing. Manufacturing concentrates in Germany, Switzerland, and the United States for high-purity cytokines and cell culture media; China and South Korea supply plasticware and consumables. Raw material dependencies include recombinant growth factors, sterile filtration membranes, and certified reference standards. Single-source vulnerability persists for niche hematopoietic expansion formulations patented by specialized suppliers. Distribution runs through authorized distributor networks for regulated markets, with direct procurement relationships for high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent-instrument ecosystem convergence is transforming stem cell assay procurement into platform economics where interoperability locks determine switching costs and lifetime value capture.
For Market Incumbents: Harden defensive positions through captive cytokine fermentation capacity in Germany or Switzerland to insulate against supply disruption. Deepen backward integration into reporter gene vector production, as emerging CRISPR-based potency assays threaten traditional fluorescence workflows. Prioritize outcome-based contracting with consolidated NIH procurement consortia to anchor high-volume reference laboratory relationships before competitors qualify alternative suppliers. For New Entrants and Emerging Players: Blood disorder research segments in India represent the most penetrable entry point, where standardized hematopoietic expansion assays remain underdeveloped and CDSCO regulatory pathways impose lower validation burdens than FDA frameworks. PCR-based clonality confirmation workflows for South Korean induced pluripotent stem cell developers offer a second white-space target, displacing slower karyotyping methods. Lead with AI-driven image analysis partnerships that automate colony morphology scoring, reducing labor cost disadvantages against established flow cytometry incumbents. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors backward-integrated reagent formulators with captive GMP manufacturing infrastructure. Long-term viability across the analysis window hinges on positioning upstream of assay validation bottlenecks rather than competing in crowded detection platform categories. Acquisition targets should demonstrate qualified supplier status with at least two of the three major regulatory jurisdictions: FDA, EMA, or NMPA. The signal to watch is FDA guidance publication velocity on real-time release testing mandates, which will accelerate consolidation toward integrated workflow providers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA potency assay harmonization accelerates European autologous cell therapy commercialization timelines. |
| Backward Integration | Captive cytokine production insulates assay reproducibility from supply chain volatility in Switzerland and Germany. |
| Platform Integration | Reporter gene system convergence with flow cytometry anchors high-throughput screening workflows for induced pluripotent stem cell applications. |
| Geographic Expansion | Singapore's streamlined biosafety frameworks attract contract development organizations seeking lower regulatory friction than Western jurisdictions. |
| Acquisition of Specialist Firm | Hematopoietic expansion protocol expertise defends position in blood disorder research segments with underdeveloped standardized assays. |
Research Methodology
A standing panel of regulatory affairs leads at cell therapy developers, assay scientists at contract manufacturing organizations, procurement directors at NIH-funded core facilities, and quality control officers at reagent suppliers provided ongoing calibration across the study period. Primary interview data triangulated against FDA guidance documents, EMA scientific advice letters, ISO 10993 biocompatibility standards, and WHO cell substrate characterization guidelines. Secondary validation drew from ClinicalTrials.gov assay endpoint specifications, SEC 10-K filings from diversified life science conglomerates, and customs records for cytokine and media formulation trade flows. Bottom-up segment sizing across assay type, technology platform, and end-user category reconciled against top-down market boundary estimates.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory harmonization pathways throughout the forecast period. The analytical framework modeled segmentation dimensions including assay purpose, detection platform, cell source type, end-user capability tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical qualification timeline data and projected biomanufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated FDA process analytical technology adoption rates and EMA autologous cell therapy approval velocity.
Macroeconomic conditions sit as an overlay; deviation in NIH regenerative medicine funding levels or cell therapy developer capital markets access would shift the trajectory. Forecasts reflect assumptions regarding regulatory guidance publication timelines, supply chain qualification periods, and technology substitution rates for emerging detection platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Drug Delivery Technology Market