
 Cosmid DNA Isolation Market | 2026-2036
Cosmid DNA Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmid DNA Isolation Market Outlook
Consolidation among pharmaceutical buyers is realigning procurement volumes toward fewer, larger contracts with integrated kit suppliers. Qiagen leverages its silica-membrane intellectual property to sustain premium positioning in column-based workflows. Thermo Fisher Scientific anchors North American distribution through direct field service teams serving top-20 biopharma accounts.
Cosmid DNA isolation recovers large-insert cloning vectors from bacterial lysates through alkaline lysis followed by density-gradient or silica-column purification, yielding DNA fragments of 35–45 kilobases for genomic library construction. Reagents and kits capture the dominant share of product-type revenue because repeat-purchase consumables outlast capital equipment depreciation cycles. Column chromatography leads technology adoption in pharmaceutical quality-control labs, while electrophoresis retains share in academic settings where throughput requirements remain modest.
FDA guidance on nucleic acid-based gene therapy vectors and EMA's Advanced Therapy Medicinal Products framework shape purity and endotoxin specifications that filter kit selection at pharmaceutical companies. ISO 13485 quality management standards and CLIA laboratory certification requirements in the United States further constrain vendor qualification pools. Stakeholders must monitor evolving regulatory divergence between FDA and EMA vector-release criteria when configuring multi-region supply agreements.
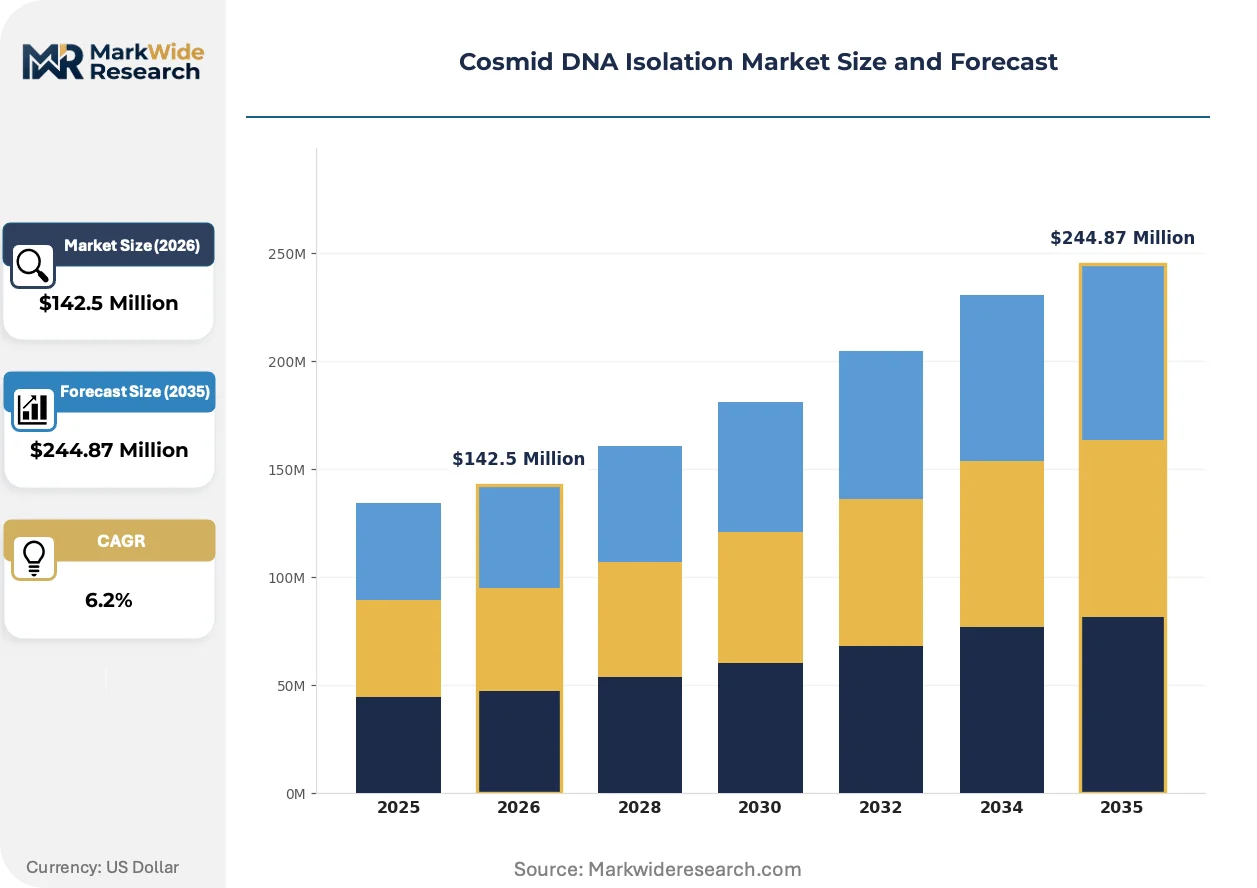
Market Dynamics
Automated silica-column workflows are compressing manual alkaline lysis protocols out of high-throughput pharmaceutical quality-control labs, redistributing equipment procurement toward integrated purification platforms.
Growth Catalysts
- CRISPR-based gene editing protocols:Academic institutions now deploy cosmid vectors for large-insert genomic library construction, accelerating kit consumption in research settings.
- EMA Advanced Therapy Medicinal Products framework:Purity and endotoxin specifications for nucleic acid-based gene therapy vectors mandate upgraded isolation workflows at European pharmaceutical manufacturers.
- Silica-membrane technology maturation:Column chromatography systems achieve reproducible 35–45 kilobase fragment recovery, displacing density-gradient methods in automated pipelines.
Market Restraints
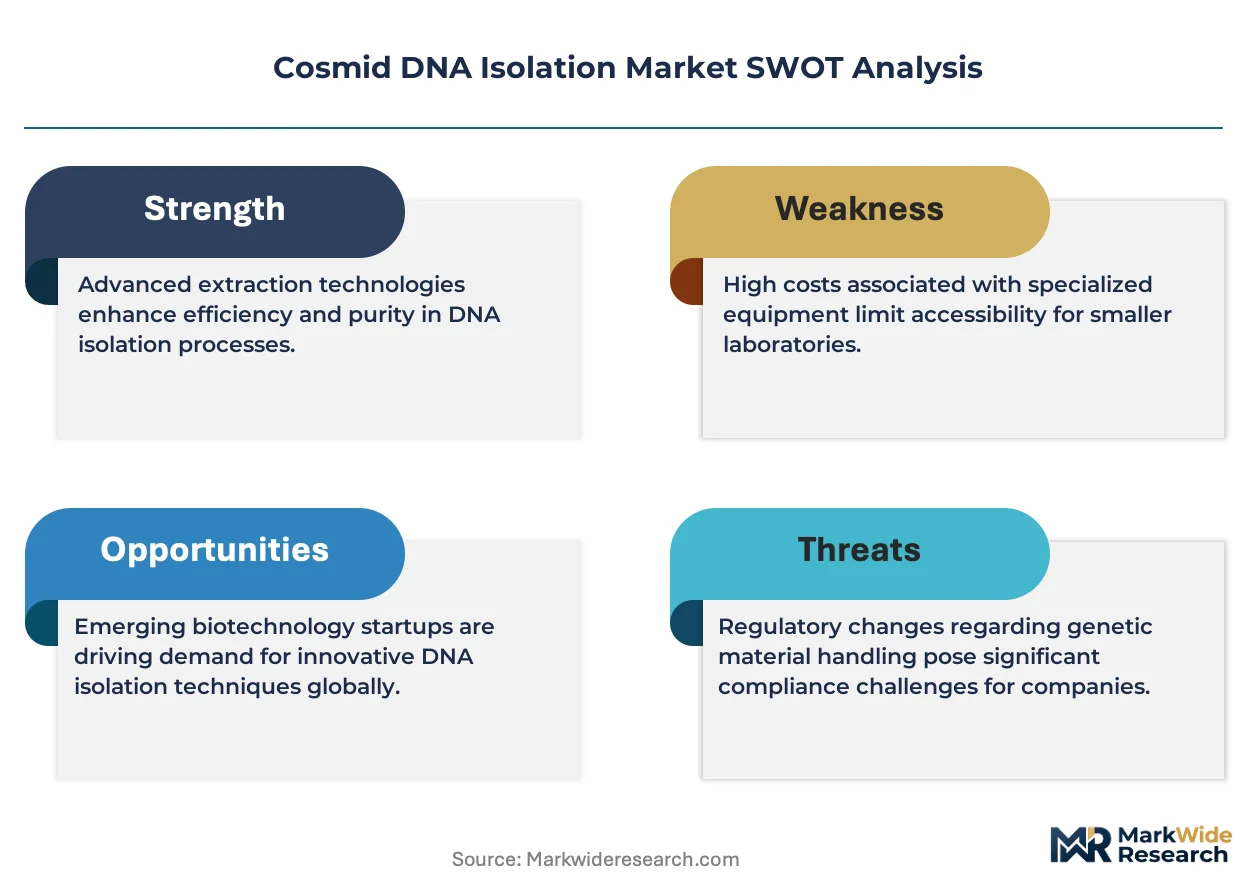
- Specialized resin input costs:Silica-membrane and anion-exchange resin prices fluctuate with petrochemical feedstock volatility, squeezing kit manufacturer margins.
- Vendor qualification concentration:ISO 13485 certification and CLIA laboratory requirements in the United States restrict approved supplier pools to established players with quality management infrastructure.
- Plasmid vector substitution:Smaller-insert cloning applications increasingly favor bacterial artificial chromosome and yeast artificial chromosome alternatives for genomic library construction.
Strategic Opportunities
- Contract research organization channel expansion:Third-party genomic service providers in Germany and Japan seek turnkey isolation platforms with embedded regulatory documentation.
- Single-use consumable integration:Pre-packed, gamma-irradiated columns eliminate cross-contamination risk in multi-product gene therapy manufacturing suites.
- Japanese genomic research initiative funding:METI-backed precision medicine programs sustain public-sector procurement volumes for high-capacity cosmid workflows.
Industry Challenges
- Multi-region regulatory divergence:FDA vector-release criteria and EMA nucleic acid specifications create compliance complexity for kit suppliers configuring transatlantic supply agreements.
- Skilled technician scarcity:Density-gradient ultracentrifugation expertise erodes as academic training programs pivot to automated chromatography curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmid DNA Isolation Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $244.87 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Equipment, Consumables Technology: Centrifugation, Electrophoresis, Column Chromatography, Precipitation End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Biotech Firms Application: Molecular Cloning, Gene Expression Analysis, Genome Mapping, DNA Sequencing |
| Companies Covered | Qiagen, Thermo Fisher Scientific, Promega Corporation, Takara Bio Inc., Agilent Technologies, Bio-Rad Laboratories, New England Biolabs, Zymo Research Corporation, Macherey-Nagel GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmid DNA Isolation Market Strategic Shifts
Workflow automation and regulatory harmonization pressures are converging to reshape how isolation platforms are specified, purchased, and validated across pharmaceutical and academic end-uses.
Magnetic bead-based purification is consolidating position in mid-throughput research settings where silica-column capital investment remains uneconomical. Core facilities at major US research universities adopt benchtop magnetic separation platforms for cosmid recovery from bacterial lysates. This consolidation is compressing the addressable market for traditional precipitation reagent kits in academic segments.
REACH chemical registration requirements in Europe now capture silica-based stationary phases and elution buffer constituents used in nucleic acid isolation workflows. Manufacturers reformulate proprietary buffer systems to eliminate SVHC-classified compounds ahead of sunset date enforcement. German and Swiss kit suppliers lead this reformulation push, securing advance positioning for EU Green Deal-aligned procurement criteria.
Consolidated purchasing through integrated biopharma procurement consortia now dominates North American kit acquisition for top-20 pharmaceutical accounts. Direct field service relationships displace distributor intermediaries for platform installation, training, and validation support. This channel compression is most visible in the Boston-Cambridge and San Diego biotech clusters where multi-site standardization drives sole-source agreements.
Cosmid DNA Isolation Market Segmentation
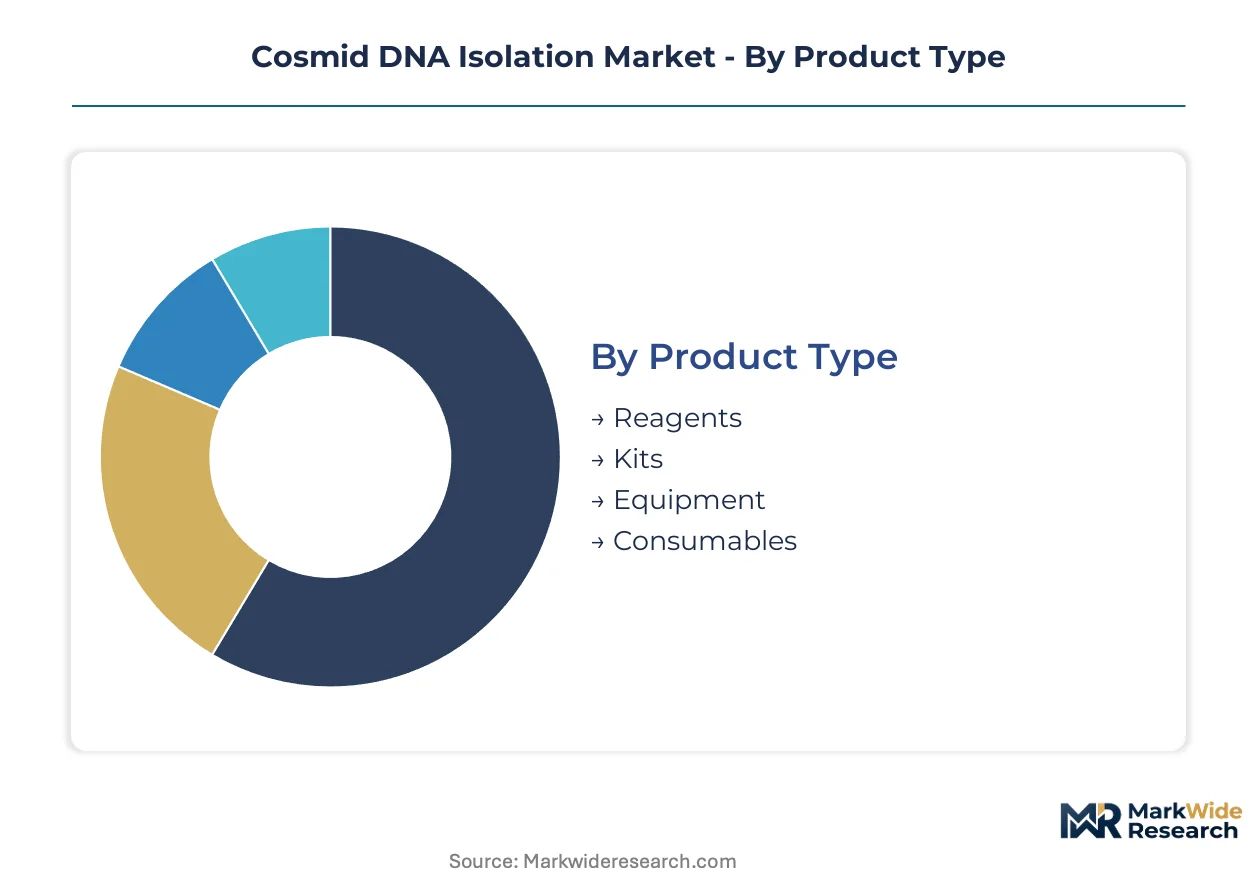
Segmentation in cosmid DNA isolation reveals how procurement priorities diverge between high-throughput pharmaceutical manufacturing and variable-scale academic research. Upgrade cycles and workflow automation investments differ sharply across product types, technologies, and end-user environments.
Product Type:
Replacement cycles accelerate where consumable dependencies lock laboratories into recurring reagent purchases rather than capital equipment refresh.
- Reagents:Alkaline lysis buffers, density-gradient media, and silica-binding solutions constitute the recurring cost base for most isolation workflows. Pharmaceutical quality-control labs in Germany and Japan negotiate multi-year supply agreements for endotoxin-certified reagent grades to satisfy EMA and PMDA vector-release criteria.
- Kits:Pre-formulated purification systems bundle reagents, columns, and protocols into validated workflows. Academic institutions in the United States favor kit formats that reduce protocol development time for CRISPR-based genomic library construction.
- Equipment:Automated liquid handlers and integrated purification platforms represent capital-intensive infrastructure. Biotech firms in Boston-Cambridge and San Diego clusters prioritize equipment with embedded compliance documentation for FDA gene therapy submissions.
- Consumables:Single-use columns, magnetic beads, and pre-packed cartridges eliminate cross-contamination risk in multi-product manufacturing suites. Swiss and German suppliers lead gamma-irradiated consumable production for EU GMP-aligned gene therapy facilities.
Volume placements concentrate in Reagents; the faster expansion belongs to Consumables.
Technology:
Cost tier stratification separates premium automated chromatography from budget manual methods, with mid-tier magnetic bead platforms capturing share in between.
- Column Chromatography:Silica-membrane and anion-exchange columns deliver reproducible 35–45 kilobase fragment recovery with endotoxin control. Pharmaceutical manufacturers in the United States deploy these systems for FDA-compliant gene therapy vector release.
- Centrifugation:Density-gradient ultracentrifugation remains the gold standard for highest-purity cosmid preparation. Academic core facilities retain this technology where throughput requirements remain modest and technician expertise persists.
- Electrophoresis:Agarose gel-based size selection and analytical verification supports protocol optimization in research settings. Japanese national laboratory networks specify electrophoresis confirmation steps for publicly funded genomic initiatives.
- Precipitation:Isopropanol or ethanol precipitation offers lowest-cost DNA recovery without specialized equipment. Budget-constrained teaching laboratories in India and Brazil rely on precipitation for introductory molecular biology curricula.
Revenue concentrates in Column Chromatography; magnetic bead hybrid methods are climbing the fastest as mid-throughput research demand expands.
End User:
Customer type determines validation burden, with pharmaceutical buyers demanding ISO 13485-certified supply chains that academic purchasers rarely require.
- Pharmaceutical Companies:Integrated biopharma procurement consortia dominate kit acquisition for top-20 accounts, consolidating toward sole-source agreements with embedded field service support.
- Academic Institutions:CRISPR protocol expansion drives fastest-growing demand for large-insert cloning workflows, with core facilities adopting benchtop automation to replace manual precipitation methods.
- Biotech Firms:Venture-funded startups in precision medicine clusters prioritize turnkey platforms with pre-validated regulatory documentation to accelerate IND timelines.
- Research Laboratories:Government and institutional labs balance throughput needs against fixed budget constraints, often maintaining hybrid workflows across multiple purification technologies.
Procurement volume concentrates in Pharmaceutical Companies; Academic Institutions are gaining share fastest as gene editing research funding expands.
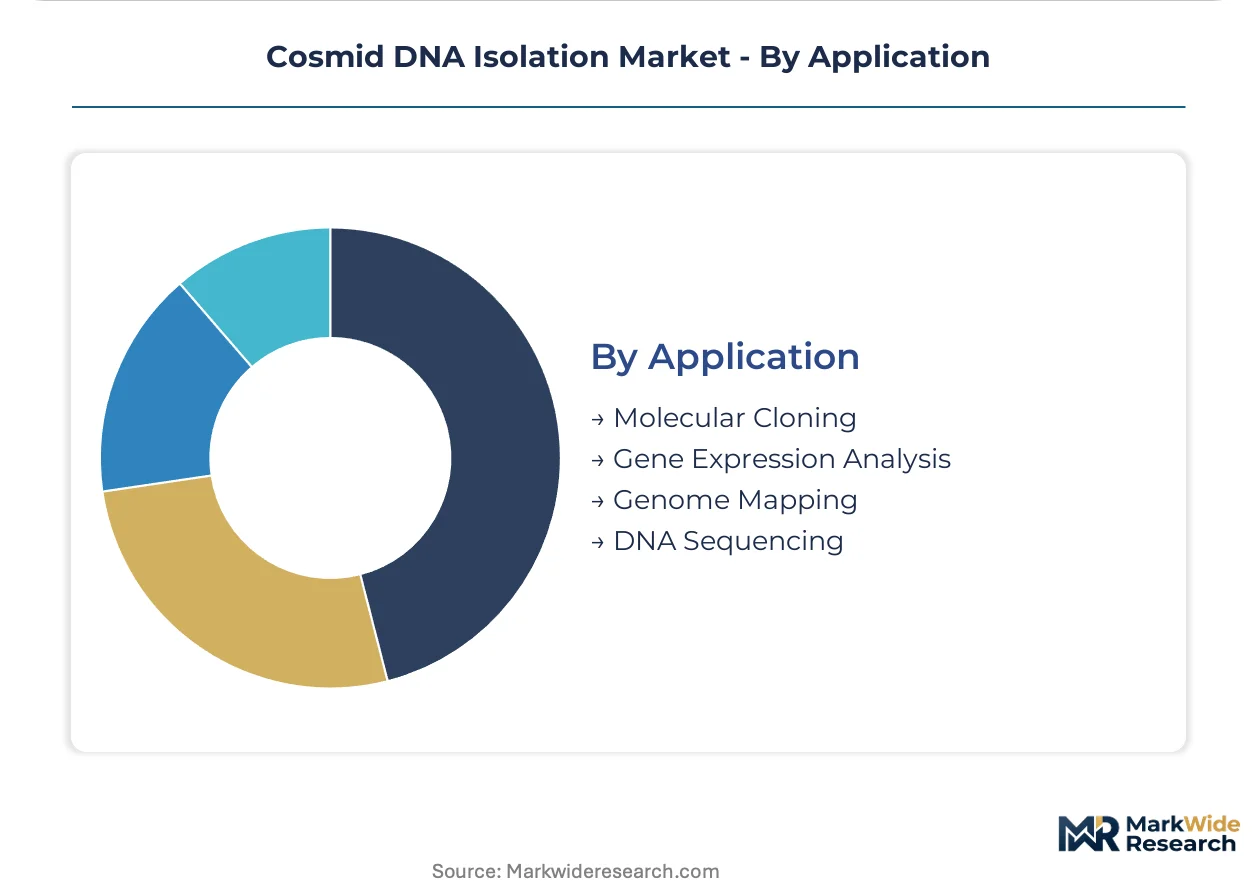
Application:
Maturity gradients separate established molecular cloning workflows from emerging gene therapy applications with steeper regulatory compliance requirements.
- Molecular Cloning:Cosmid vectors for 35–45 kilobase insert libraries remain foundational to genomic mapping projects. German and Japanese research consortia sustain demand for high-capacity cloning workflows in precision medicine programs.
- Gene Expression Analysis:Large-insert reporter constructs require cosmid-scale DNA preparation with minimal shearing. Biotech firms developing cell therapy manufacturing processes specify low-endotoxin grades for transfection-grade material.
- Genome Mapping:Physical mapping and contig assembly applications persist in agricultural genomics and evolutionary biology. Public-sector agricultural research stations in the United States and France maintain dedicated cosmid libraries for crop improvement.
- DNA Sequencing:Long-read sequencing platforms increasingly bypass traditional cloning, though cosmid-based approaches retain utility for complex region assembly. Core sequencing facilities evaluate cosmid preparation only for specialized metagenomic or structural variant projects.
Activity concentrates in Molecular Cloning; Gene Expression Analysis shows the steepest expansion trajectory as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized resin feedstock production concentrates in the petrochemical corridors of Germany and the United States, anchoring kit manufacturing capacity near these input sources. National biotechnology funding frameworks in three countries sustain procurement volumes for genomic research workflows. Regulatory divergence between FDA and EMA vector-release criteria shapes multi-region supply agreement configurations.
United States
Biopharma procurement consortia in Boston-Cambridge and San Diego drive consolidated purchasing toward sole-source agreements with embedded field service support. FDA gene therapy vector guidance mandates endotoxin-controlled isolation workflows for IND submissions. The Greater Boston cluster anchors North American demand for automated purification platforms serving top-20 pharmaceutical accounts.
Germany
EMA Advanced Therapy Medicinal Products framework enforces purity specifications that upgrade isolation workflows at pharmaceutical manufacturers. REACH chemical registration now captures silica-based stationary phases used in nucleic acid purification. The Rhine-Ruhr industrial corridor hosts kit suppliers reformulating buffer systems to eliminate SVHC-classified compounds ahead of sunset dates.
Japan
METI-backed precision medicine programs sustain public-sector procurement volumes for high-capacity cosmid workflows. PMDA vector-release criteria align with international standards while maintaining domestic documentation requirements. The Kanto region around Tokyo concentrates core facility investments in benchtop automation for CRISPR-based genomic library construction.
Switzerland
Swissmedic certification requirements constrain vendor qualification pools to established players with ISO 13485 quality management infrastructure. Gamma-irradiated consumable production for EU GMP-aligned gene therapy facilities concentrates near Basel. Swiss kit suppliers lead reformulation initiatives securing advance positioning for EU Green Deal-aligned procurement criteria.
United Kingdom
Academic core facilities in the Golden Triangle of London, Oxford, and Cambridge adopt magnetic bead-based purification where silica-column capital investment remains uneconomical. MHRA post-Brexit regulatory divergence creates compliance complexity for transatlantic kit suppliers. The Cambridge cluster maintains hybrid workflows across multiple purification technologies for variable-scale research demand.
Cosmid DNA Isolation Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent magnetic bead and single-use consumable spaces. The vendor base stratifies across three tiers: integrated life science conglomerates with direct field service networks, mid-scale specialists in silica-membrane intellectual property, and regional reagent formulators serving budget-constrained academic segments. Competitive moves concentrate on strategic partnerships for regulatory documentation bundles and backward integration into specialized resin supply.
Within the premium chromatography tier, Qiagen and Thermo Fisher Scientific exemplify archetypes of intellectual property holders and distribution anchors respectively. Qiagen occupies a position as a German-based GmbH representing silica-membrane technology maturation. Thermo Fisher Scientific anchors North American presence as a US-based Inc. with direct service infrastructure. Takara Bio Inc. sits within the Asia-Pacific specialist tier as a Japan-based entity serving regional genomic research initiatives.
| Leading Market Players |
|---|
| Qiagen |
| Thermo Fisher Scientific |
| Promega Corporation |
| Takara Bio Inc. |
| Agilent Technologies |
| Bio-Rad Laboratories |
| New England Biolabs |
| Zymo Research Corporation |
| Macherey-Nagel GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Captive silica-membrane production in Germany and the United States anchors both supply security and premium pricing power for established kit manufacturers serving pharmaceutical quality-control labs. This backward integration into specialized resin supply buffers margin compression from petrochemical feedstock volatility while locking in endotoxin-certified reagent grades demanded by FDA and EMA vector-release frameworks.
Pricing Analysis
Field service bundling separates premium chromatography platforms from unbundled academic kit formats, with installation and validation support embedded in pharmaceutical contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ISO 13485-certified workflows commanding substantial premiums. Pricing pressure stems from REACH-driven buffer reformulation costs squeezing mid-tier suppliers. Teaching laboratories in India and Brazil exhibit highest price sensitivity, while biopharma procurement consortia prioritize compliance documentation over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled resin shipments from the Rhine-Ruhr corridor to North Asian gene therapy facilities is reshaping regional inventory positioning. Manufacturing concentrates in Germany, the United States, and Switzerland, drawing from petrochemical feedstocks and specialized anion-exchange chemistries. Single-source vulnerability persists for gamma-irradiated consumable production near Basel. Distribution runs through direct field service teams for top-20 pharmaceutical accounts, compressing distributor intermediaries in Boston-Cambridge and San Diego clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into silica-membrane resin supply has become the decisive competitive lever, with manufacturers capturing margin pools that previously flowed to petrochemical intermediaries and specialized chemical suppliers.
For Market Incumbents: Deploy certification infrastructure as a moat. Qiagen and Thermo Fisher Scientific should accelerate ISO 13485 audit support for mid-tier academic core facilities seeking pharmaceutical-grade workflows, preempting magnetic bead substitution in CRISPR protocol expansion. Captive resin production buffers margin pressure from REACH chemical registration compliance costs. For New Entrants and Emerging Players: Budget-constrained teaching laboratories in India and Brazil represent the most penetrable entry point. Magnetic bead platform vendors can displace precipitation reagent kits in mid-throughput research settings where silica-column capital investment remains uneconomical. Partner with regional distributors offering embedded protocol translation services to bypass direct field service requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated life science conglomerates seeking regulatory documentation bundles. Five-to-ten year viability hinges on positioning for EU Green Deal-aligned procurement criteria as Swiss and German suppliers lead SVHC elimination reformulation. Watch for PMDA alignment with international vector-release standards as the signal for Japanese market consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive silica-membrane production secures margin pools and buffers petrochemical feedstock volatility for kit manufacturers. |
| Regulatory Documentation Bundling | Pre-validated FDA and EMA submission packages accelerate IND timelines for biotech firms in precision medicine clusters. |
| Single-Use Consumable Expansion | Gamma-irradiated columns eliminate cross-contamination risk in multi-product gene therapy manufacturing suites. |
| Magnetic Bead Platform Development | Benchtop automation captures mid-throughput research demand where silica-column investment remains uneconomical. |
| REACH Compliance Reformulation | Buffer system redesign eliminates SVHC-classified compounds ahead of EU sunset date enforcement. |
Study Parameters
SEC 10-K filings, EMA Advanced Therapy Medicinal Products framework documents, and METI precision medicine program disclosures formed the secondary backbone of this analysis. Primary interviews with purification platform product managers, regulatory affairs specialists at gene therapy developers, academic core facility directors, and GMP manufacturing quality officers supplied operating data on workflow adoption patterns. Bottom-up kit shipment estimates triangulated against top-down national biotechnology funding allocations across the United States, Germany, and Japan.
Historical trendline analysis of silica-membrane technology maturation and alkaline lysis protocol displacement informed projection frameworks across the analysis window. Segmentation modeling incorporated product type dependencies, technology cost tier stratification, end-user validation burden differentiation, and application maturity gradients. CAGR derivation weighted CRISPR protocol expansion rates against plasmid vector substitution threats in genomic library construction.
Revisions become necessary when FDA-EMA regulatory divergence widens, petrochemical feedstock volatility disrupts specialized resin pricing, or magnetic bead technology achieves cost parity with column chromatography in high-throughput settings. Forecasts reflect documented assumptions about academic funding continuity and gene therapy manufacturing scale-up timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
DNA Synthesis Market