
 Strand Displacement Amplification (SDA) Market | 2026-2036
Strand Displacement Amplification (SDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Strand Displacement Amplification (SDA) Market Analytics
The SDA market is decoupling into premium instrument-and-kit bundles and commodity reagent supply. New England Biolabs leverages its enzymology heritage to anchor high-margin reagent positions. Sherlock Biosciences competes through CRISPR-SDA integration for point-of-care infectious disease detection. Bio-Rad Laboratories dominates instrument placements in clinical laboratories with automated workflow solutions.
Strand displacement amplification is an isothermal nucleic acid amplification method operating at constant temperature, typically employing exonuclease-deficient DNA polymerase and restriction endonuclease to generate displaced single strands for exponential amplification. The technique eliminates thermal cycling requirements, enabling simpler instrument design and faster turnaround for pathogen detection and genetic analysis. Reagents capture the largest revenue pool due to recurring consumable demand across installed bases, while instruments represent the fastest-growing segment as laboratories upgrade to integrated SDA platforms. Kits for infectious diseases command premium pricing versus genetic testing applications, reflecting regulatory validation burdens and clinical reimbursement differentials.
FDA oversight of nucleic acid amplification-based diagnostics under the In Vitro Diagnostics Regulation framework shapes validation requirements and market entry timelines. ISO 13485 quality management standards govern manufacturing consistency for SDA products targeting clinical end users. Stakeholders must monitor evolving CMS reimbursement decisions for isothermal amplification tests versus established real-time PCR codes, as coverage determinations will influence laboratory platform selection and reagent commitment cycles.
Market Dynamics
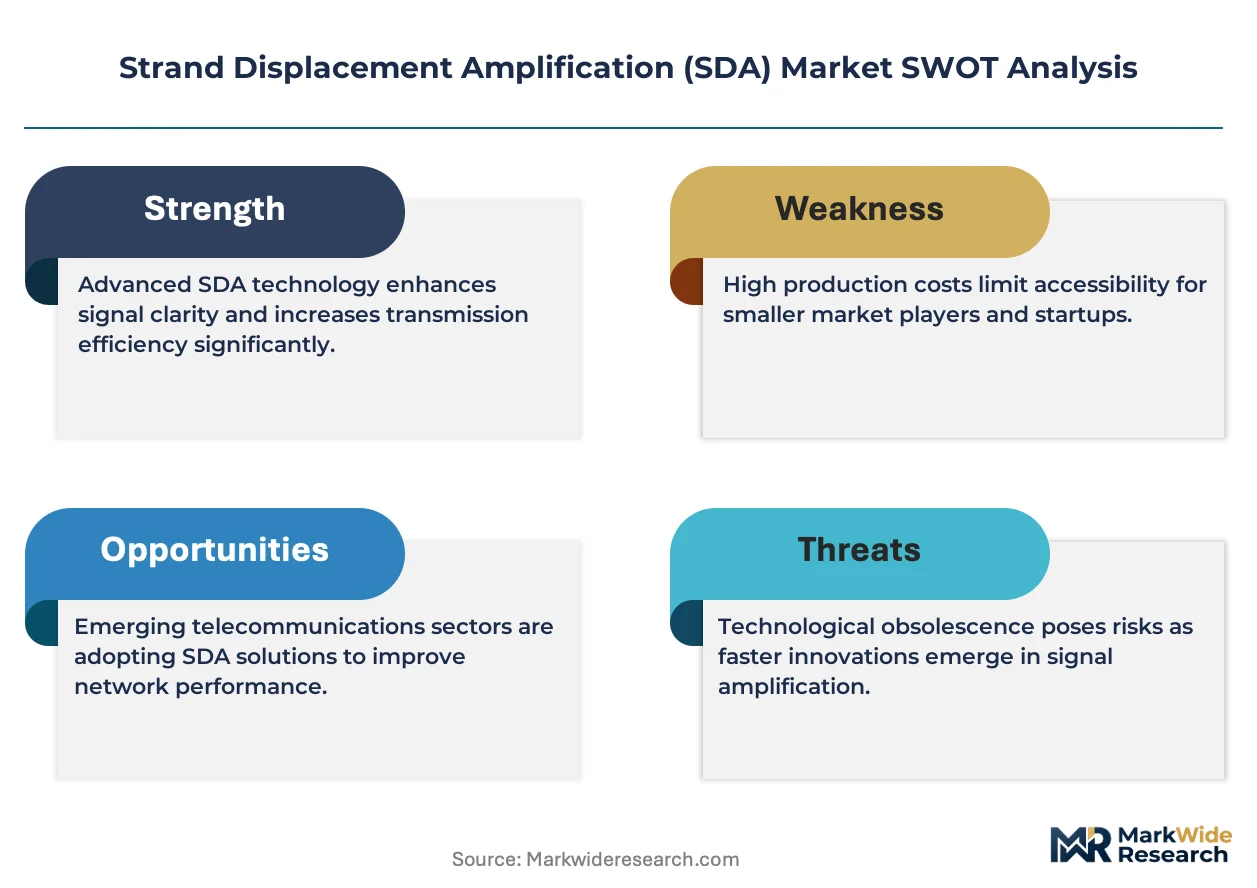
The FDA's intensifying oversight of nucleic acid amplification tests is compressing validation timelines while simultaneously elevating compliance costs, forcing SDA developers to front-load regulatory investment before clinical revenue materializes.
Growth Catalysts
- CMS reimbursement expansion:Coverage determinations for isothermal amplification tests in the United States are reducing out-of-pocket costs for infectious disease screening, accelerating laboratory platform adoption.
- Point-of-care decentralization:Clinical laboratories are deploying SDA systems outside centralized hospital labs to urgent care and pharmacy settings, extending molecular diagnostics reach.
- Enzyme engineering advances:Improved exonuclease-deficient polymerase formulations are reducing reaction failure rates and shortening time-to-result for pathogen detection workflows.
Market Restraints
- Input cost volatility:Restriction endonuclease prices fluctuate with fermentation capacity constraints at specialized bioreactor facilities, squeezing reagent margin stability.
- Substitution threat from CRISPR diagnostics:CRISPR-based detection platforms offer comparable sensitivity with simpler workflow integration, capturing pilot funding from SDA prospects.
- Regulatory friction from IVDR transition:The European Union's In Vitro Diagnostics Regulation is extending conformity assessment timelines for SDA kits, delaying market entry for mid-tier manufacturers.
Strategic Opportunities
- Underpenetrated veterinary diagnostics:Livestock and companion animal infectious disease testing in Brazil represents a greenfield application with lower regulatory barriers than human clinical markets.
- Technology convergence with microfluidics:Integration of SDA chemistry with cartridge-based sample preparation is enabling true sample-to-answer automation for resource-limited settings.
- Regulatory tailwind from pandemic preparedness mandates:National stockpiling requirements for rapid pathogen detection in the United States are creating dedicated procurement channels for isothermal amplification platforms.
Industry Challenges
- Multiplexing complexity:Simultaneous detection of multiple pathogens in a single SDA reaction requires sophisticated primer design and suffers from cross-reactivity validation burdens.
- Integration friction with LIMS infrastructure:Laboratory information management systems in established clinical laboratories run on PCR-centric data architectures, requiring custom middleware development for SDA output compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strand Displacement Amplification (SDA) Market |
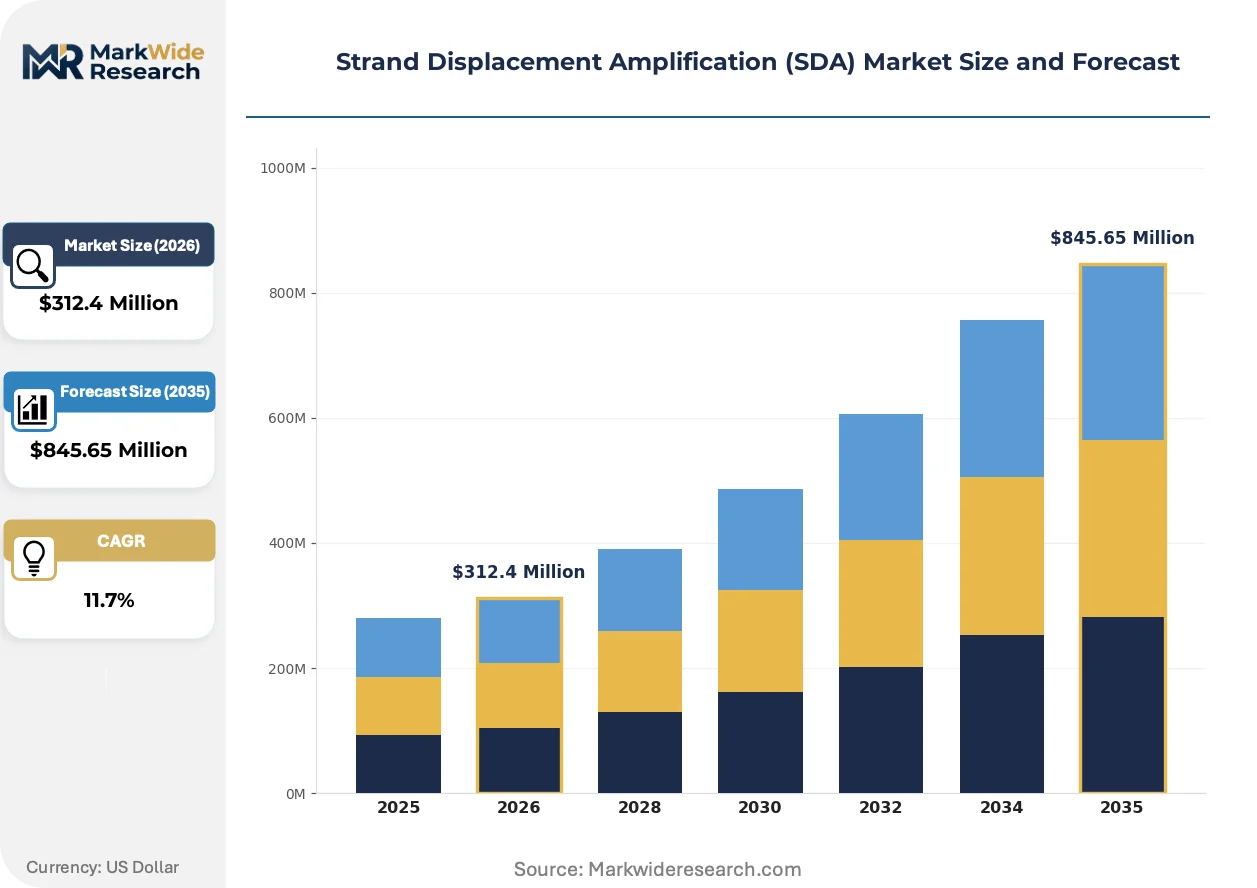
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Kits, Consumables End User: Clinical Laboratories, Research Institutes, Pharmaceutical Companies, Diagnostics Centers Application: Infectious Diseases, Genetic Testing, Oncology, Forensic Science Technology: Nucleic Acid Amplification, Real-time PCR, Isothermal Amplification, Microfluidics |
| Companies Covered | Hopax Fine Chemicals, Nippon Genetics Co. Ltd., New England Biolabs, Inc., NuProbe Global, Proteon Pharmaceuticals, Bio-Rad Laboratories, G-Biosciences, Sherlock Biosciences, Lucigen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strand Displacement Amplification (SDA) Market Evolving Landscape
SDA technology is absorbing capabilities from adjacent molecular diagnostics domains, blurring traditional boundaries between isothermal amplification and real-time detection modalities. This convergence is reshaping product architecture and competitive positioning across the value chain.
Digital SDA platforms incorporating real-time fluorescence monitoring are absorbing capabilities from quantitative PCR systems, enabling kinetic analysis previously unavailable in isothermal workflows. Large reference laboratories in the United States are piloting these instruments for quantitative viral load applications. The technology is absorbing market share from conventional endpoint SDA by offering clinicians actionable numerical thresholds rather than binary presence-absence calls.
The European Union's Medical Device Regulation is reclassifying SDA-based infectious disease tests from Class B to Class C devices, triggering notified body involvement for conformity assessment. Manufacturers must now submit clinical performance data from prospective studies rather than analytical validation alone. High-complexity molecular diagnostics laboratories in Germany and France are responding by consolidating supplier relationships to favor established players with dedicated regulatory affairs capacity.
Consolidated purchasing by hospital network procurement coalitions is displacing individual laboratory autonomy in reagent sourcing decisions. Integrated delivery networks in the United States are negotiating enterprise-wide SDA platform contracts with standardized menu commitments, extracting volume discounts unavailable to standalone facilities. This concentration is most visible in the Southeast and Midwest regions where regional health system mergers have created super-regional purchasing entities controlling hundreds of hospital laboratories.
Strand Displacement Amplification (SDA) Market Segmentation
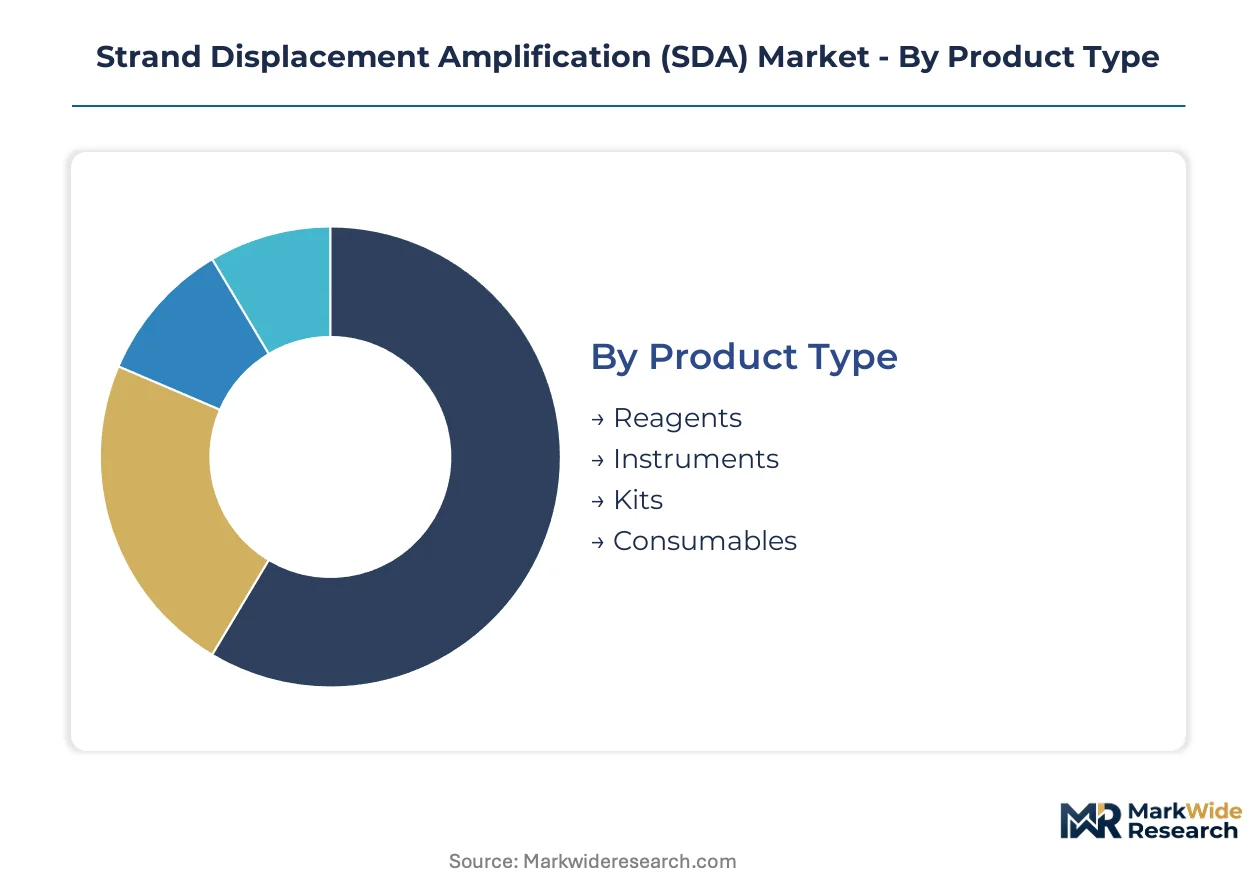
SDA market segmentation reveals distinct value capture patterns across the product lifecycle. Recurring consumable demand contrasts sharply with capital-intensive instrument placements. Application-specific regulatory burdens create pricing stratification that reshapes competitive entry decisions.
Product Type:
Technology specification dictates margin architecture across the SDA value chain.
- Reagents:Restriction endonucleases and exonuclease-deficient polymerases constitute the chemical core. Clinical laboratories in the United States generate recurring procurement cycles tied to CMS reimbursement codes for infectious disease panels.
- Instruments:Automated SDA platforms integrate thermal control modules with fluorescence detection optics. Diagnostics centers in Germany and France prioritize systems with LIMS middleware compatibility to minimize workflow disruption.
- Kits:Pre-formulated master mixes reduce operator error in high-throughput settings. FDA-cleared infectious disease kits command premium positioning versus research-use-only alternatives.
- Consumables:Reaction vessels and sealing films complete the disposable ecosystem. Volume procurement by hospital network coalitions in the US Southeast compresses per-unit margins.
Reagents lead on scale; instruments lead on momentum.
End User:
Customer procurement sophistication determines contract structure and loyalty mechanisms.
- Clinical Laboratories:High-complexity facilities process thousands of SDA reactions daily. Integrated delivery networks in the United States negotiate enterprise-wide contracts with standardized menu commitments.
- Research Institutes:Academic centers prioritize reagent flexibility over regulatory certification. Funding from the National Institutes of Health sustains exploratory SDA protocol development.
- Pharmaceutical Companies:Drug developers employ SDA for companion diagnostic co-development. Contract manufacturing organizations in Switzerland leverage ISO 13485-certified facilities to serve this segment.
- Diagnostics Centers:Point-of-care facilities demand cartridge-based sample-to-answer systems. Pharmacy chains in Japan pilot SDA deployment for influenza screening outside hospital settings.
Clinical laboratories anchor volume concentration; diagnostics centers are expanding most quickly.
Application:
Disease category regulatory intensity shapes validation investment requirements.
- Infectious Diseases:Respiratory and sexually transmitted pathogen panels dominate commercial deployment. FDA's In Vitro Diagnostics Regulation mandates clinical performance studies for SDA-based SARS-CoV-2 assays.
- Genetic Testing:Carrier screening and pharmacogenomic analysis leverage SDA's isothermal simplicity. Direct-to-consumer laboratories in California integrate SDA into ancestry-informed health risk reports.
- Oncology:Liquid biopsy applications detect circulating tumor DNA with minimal sample input. Memorial Sloan Kettering Cancer Center validates SDA protocols for minimal residual disease monitoring.
- Forensic Science:Degraded DNA samples from crime scenes amplify reliably under constant temperature conditions. FBI laboratory accreditation standards govern SDA adoption in federal evidence processing.
Infectious diseases command revenue concentration; oncology shows steepest expansion trajectory.
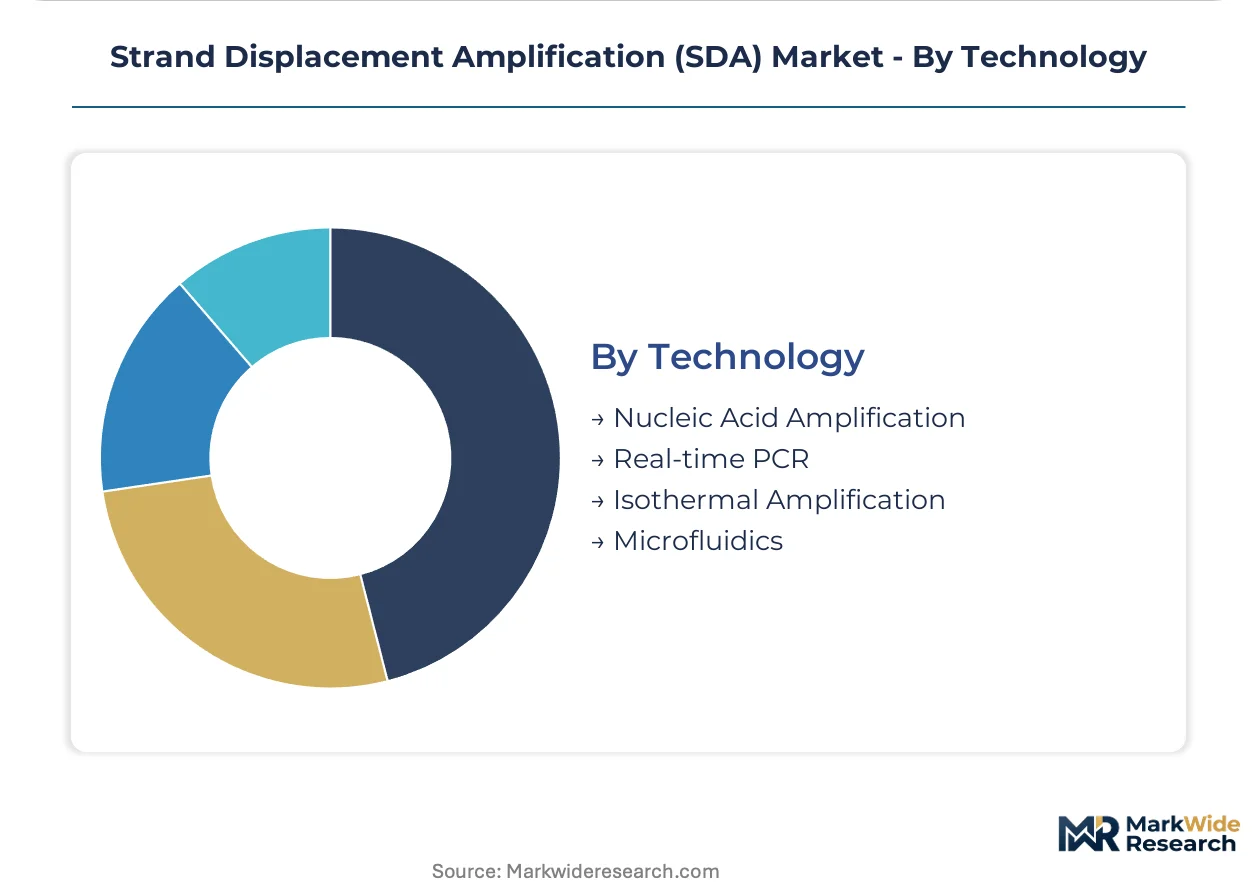
Technology:
Platform convergence is dissolving traditional boundaries between amplification modalities.
- Nucleic Acid Amplification:SDA's strand displacement mechanism generates exponential signal without thermal cycling. Core chemistry patents held by New England Biolabs structure licensing revenue flows.
- Real-time PCR:Quantitative fluorescence monitoring capabilities migrate into digital SDA platforms. Reference laboratories in Boston and San Francisco pilot kinetic viral load applications previously exclusive to PCR.
- Isothermal Amplification:LAMP and RPA compete directly with SDA for point-of-care positioning. Enzyme engineering advances at Sherlock Biosciences improve reaction kinetics for CRISPR-SDA hybrid systems.
- Microfluidics:Cartridge-based sample preparation enables true walk-away automation. Resource-limited clinics in Brazil evaluate microfluidic-SDA integration for dengue surveillance.
Isothermal amplification anchors installed base; microfluidics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular diagnostics specialists concentrate in the United States, Germany, and Japan, anchoring SDA platform development and clinical validation workflows. These talent pools drive regional adoption patterns.
United States
FDA-cleared SDA infectious disease panels process thousands of daily tests at high-complexity clinical laboratories. CMS reimbursement codes for isothermal amplification reduce out-of-pocket screening costs. The Boston-Cambridge corridor hosts enzyme engineering operations refining exonuclease-deficient polymerase formulations.
Germany
Notified body involvement under MDR reclassification demands clinical performance studies for SDA kit conformity assessment. ISO 13485-certified contract manufacturers in Baden-Württemberg serve pharmaceutical companion diagnostic programs. Reference laboratories in Munich pilot digital SDA platforms with real-time fluorescence monitoring.
Japan
PMDA oversight shapes validation timelines for SDA-based pathogen detection kits entering the domestic market. Pharmacy chains in Tokyo deploy cartridge-based SDA systems for influenza screening outside hospital settings. The Kansai region concentrates reagent supply operations serving diagnostics manufacturers.
China
NMPA registration requirements for nucleic acid amplification tests compress market entry timelines for domestic SDA developers. Yangtze River Delta biotech clusters manufacture restriction endonucleases for regional reagent supply. Shanghai-based research institutes explore CRISPR-SDA hybrid chemistries.
Brazil
ANVISA regulatory pathways for veterinary diagnostics offer lower barriers than human clinical markets for SDA kit developers. Livestock infectious disease testing in São Paulo state drives demand for isothermal amplification platforms. Federal university laboratories in Minas Gerais validate SDA protocols for dengue surveillance.
Strand Displacement Amplification (SDA) Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light reagent specialists for SDA revenue capture. The market structures around three tiers: established diagnostics conglomerates with automated workflow platforms, enzymology heritage suppliers anchoring high-margin chemical positions, and CRISPR-integrated point-of-care innovators. Consolidation pressures intensify as hospital network procurement coalitions negotiate enterprise-wide contracts. Technology licensing and strategic enzyme supply partnerships represent dominant competitive moves reshaping value chain positioning.
Within the enzymology heritage tier, New England Biolabs anchors reagent supply positions through polymerase and restriction endonuclease portfolios. Sherlock Biosciences exemplifies CRISPR-SDA integration archetypes targeting decentralized infectious disease detection. Bio-Rad Laboratories represents instrument-centric competitive positioning with automated platform placements in clinical laboratory settings.
| Leading Market Players |
|---|
| Hopax Fine Chemicals |
| Nippon Genetics Co. Ltd. |
| New England Biolabs, Inc. |
| NuProbe Global |
| Proteon Pharmaceuticals |
| Bio-Rad Laboratories |
| G-Biosciences |
| Sherlock Biosciences |
| Lucigen Corporation |
| Others |
Value Network & Pricing Analysis
Enzyme engineering specialists in the Boston-Cambridge corridor command wage premiums that widen spreads between premium instrument bundles and commodity reagent tiers. Their scarcity elevates labor costs for high-complexity SDA platform development while lower-skill assembly operations in secondary markets anchor economy pricing for consumables.
Pricing Analysis
Bundled instrument-and-kit contracts versus unbundled reagent supply splits the SDA market into divergent pricing architectures. FDA-cleared infectious disease kits command premium positioning against research-use-only alternatives, while volume procurement by hospital network coalitions compresses per-unit margins on consumables. Pricing pressure stems from consolidated purchasing power among integrated delivery networks. Clinical laboratories in enterprise contracts show lowest price sensitivity; standalone urgent care facilities exhibit highest.
Supply Chain Analysis
Direct-to-laboratory channels serve high-complexity clinical facilities with customized LIMS integration requirements. Restriction endonuclease production concentrates in China, Germany, and the United States. Exonuclease-deficient polymerase formulations and specialized bioreactor capacity constitute critical input dependencies. Single-source vulnerability around fermentation capacity at specialized facilities presents structural risk. Distribution runs through diagnostics distributors and GPO contracts for hospital network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SDA market compounds steadily as recurring reagent demand across installed instrument bases generates predictable revenue streams. CMS reimbursement expansion for isothermal amplification tests reinforces this stability by reducing customer churn.
For Market Incumbents: Hedge against CRISPR diagnostic substitution by securing exclusive enzyme supply partnerships with polymerase engineering specialists. Expand backward integration into restriction endonuclease fermentation capacity to buffer input cost volatility. Prioritize LIMS middleware development to defend instrument placements against workflow disruption threats.
For New Entrants and Emerging Players: Begin with veterinary diagnostics in Brazil where ANVISA regulatory pathways offer lower barriers than human clinical markets. Target livestock infectious disease testing in São Paulo state as the most penetrable white space. Pursue cartridge-based microfluidic integration as the go-to-market angle for resource-limited clinic deployment.
For Investors and Strategic Acquirers: Diagnostics conglomerates seeking point-of-care capabilities represent the most active acquirer category in this space. Five-to-ten year viability hinges on regulatory affairs capacity for IVDR and FDA navigation. Acquisition targets should demonstrate ISO 13485-certified manufacturing and established notified body relationships. Monitor CMS coverage determinations for isothermal amplification test codes as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-SDA Hybrid Development | Sherlock Biosciences validates point-of-care infectious disease detection workflows with enzymology convergence. |
| Microfluidic Cartridge Integration | Brazilian dengue surveillance programs evaluate true sample-to-answer automation for resource-limited settings. |
| LIMS Middleware Development | German reference laboratories demand fluorescence data compatibility with established PCR-centric information architectures. |
| Enzyme Supply Partnership | New England Biolabs structures licensing revenue through core chemistry patents on strand displacement mechanisms. |
| Reimbursement Strategy Investment | United States hospital networks prioritize platforms with established CMS coverage codes for infectious disease panels. |
Research Methodology
Bottom-up clinical laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core of this study. Primary interviews with molecular diagnostics directors, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at FDA-cleared kit developers informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Top-down supply tracking of restriction endonuclease and polymerase production capacity triangulated against bottom-up test volume estimates.
Historical trendline analysis of instrument placement cycles and reagent consumption patterns anchored the projection framework. Segmentation dimensions modeled include product type, end-user category, application area, and technology platform across the analysis window. CAGRs derived from fitted growth curves on normalized adoption S-cycles. Forecast inputs incorporated CMS coverage expansion trajectories and IVDR transition timelines for conformity assessment.
Several conditions sit outside the modeled scope, including pandemic-driven demand spikes, abrupt regulatory reclassification, and breakthrough CRISPR diagnostic platform launches. Forecasts reflect base-case assumptions around reimbursement stability and enzyme supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Bioprocess Technology Market