
 Wire Mesh Market | 2026-2036
Wire Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Mesh Market Outlook
REACH is repositioning the cost-of-entry calculus for European wire mesh suppliers by mandating full chemical substance disclosure across supply chains. Bekaert leverages its in-house steel wire rod production to absorb compliance costs without margin erosion. GKD Metal Fabrics anchors its premium position through architectural mesh specialization for facade systems. McNICHOLS Company sustains broad North American distribution by controlling extensive warehousing and same-day fulfillment networks.
Wire mesh consists of interlocked metal wires arranged in grid patterns through welding, weaving, or expansion processes, typically specified by mesh count, wire diameter, and open area percentage to deliver structural reinforcement, filtration, or security barrier functions. Stainless steel mesh commands durable margin pools in corrosive environment applications despite higher unit economics, while welded wire dominates construction volume through standardized rebar substitution in concrete slabs. Filtration applications in food processing and mining slurry separation represent the fastest-growing application cluster as particle retention standards tighten across regulated industries.
EMA chemical safety protocols, EPA industrial emissions guidelines, and ISO 9001 quality management standards collectively shape product certification requirements and factory audit thresholds for mesh suppliers seeking cross-border contracts. FDA food-contact material regulations in the United States and EU MDR medical device frameworks in Europe further bifurcate the addressable market between commodity construction grades and certified specialty mesh. Stakeholders must monitor evolving carbon border adjustment mechanisms to determine whether regional production investments or supply chain restructuring delivers lower landed compliance costs.
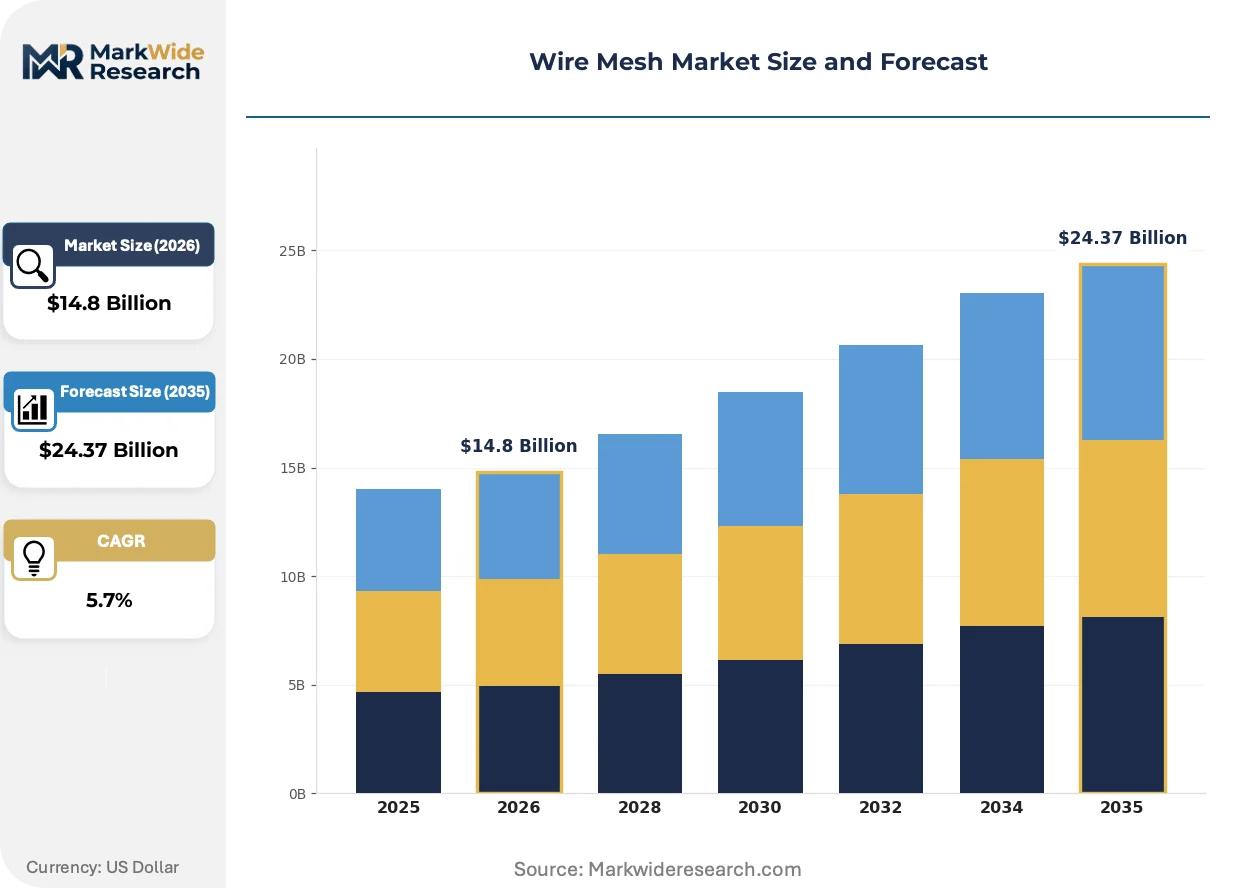
Market Dynamics
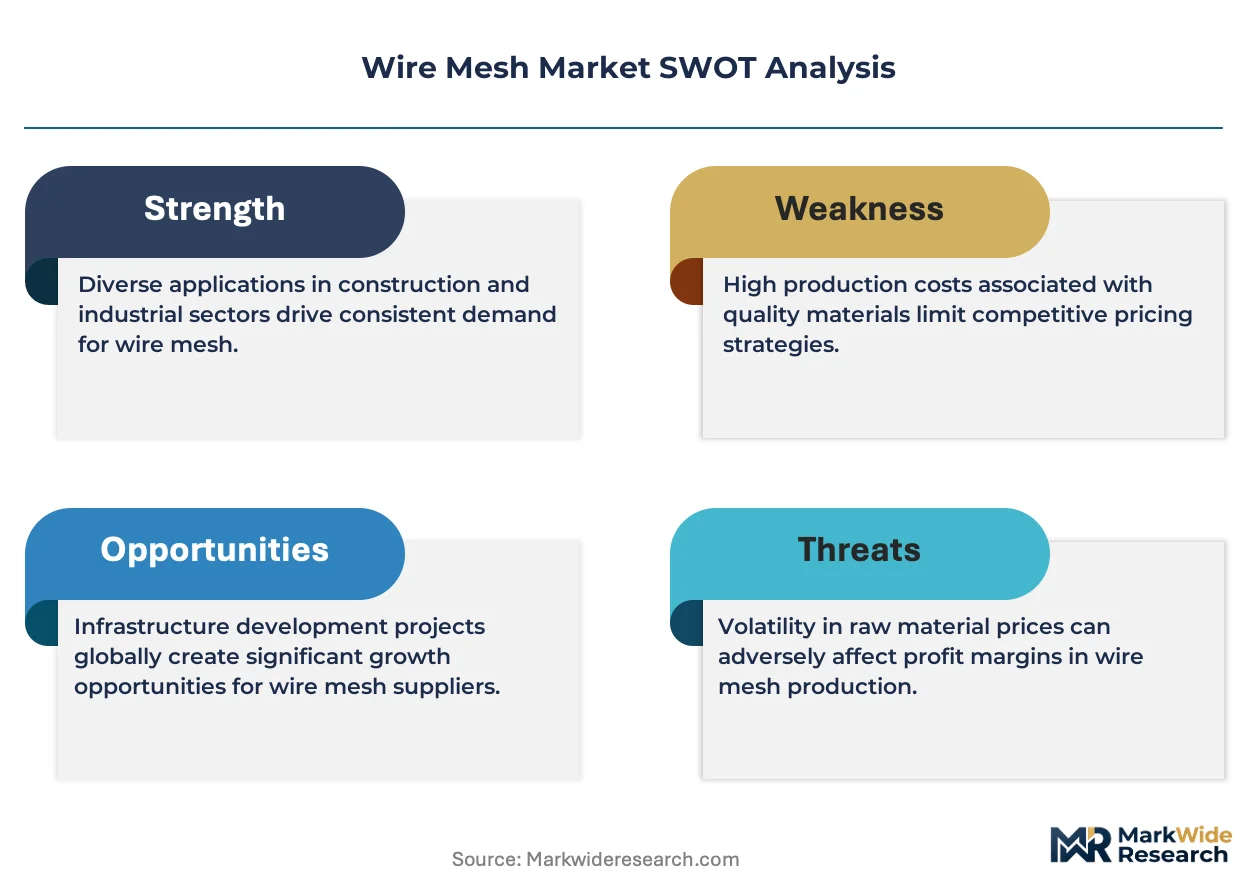
REACH chemical disclosure mandates are restructuring European wire mesh supply chains by forcing full substance traceability from raw steel rod through finished product, raising compliance costs for importers while advantaging integrated domestic producers with captive metallurgical operations.
Growth Catalysts
- Infrastructure concrete reinforcement:Federal highway and bridge programs in the United States are specifying welded wire mesh as rebar substitution in deck slabs and retaining walls, compressing installation timelines and labor costs for contractors.
- REACH low-carbon sourcing mandates:ECHA compliance deadlines are redirecting procurement toward galvanized grades with verified carbon footprints, creating preferential demand channels for mills with electric arc furnace capacity.
- Filtration specification tightening:FDA food-contact and EU MDR medical device frameworks are mandating finer mesh tolerances for particle retention, expanding addressable premium segments in pharmaceutical and food processing equipment.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing input costs fluctuate with London Metal Exchange zinc contracts, compressing margins for mesh producers without long-term concentrate offtake agreements.
- Ruhr industrial cluster concentration:German wire rod and mesh fabrication capacity concentrates around Dortmund and Duisburg, creating geographic supply risk from single-region logistics disruptions or energy price spikes.
- Composite reinforcement substitution:Carbon fiber and glass fiber rebar alternatives are capturing niche structural applications where corrosion immunity outweighs unit cost premiums.
Strategic Opportunities
- India infrastructure buildout:National highway and metro rail expansion programs are specifying welded wire fabric for concrete paving, creating volume demand from state-level public works departments.
- Architectural facade mesh specialization:Building envelope designers are specifying stainless steel and bronze woven mesh for solar shading and aesthetic screening, opening premium specification channels distinct from commodity construction grades.
- Carbon border adjustment preparation:EU CBAM transitional reporting requirements are creating first-mover advantage for mills with Scope 1-3 emissions documentation ready for customs declaration.
Industry Challenges
- Welding technician scarcity:Automated resistance welding operations require skilled calibration specialists for mesh count and tensile consistency, with training pipelines lagging plant expansion schedules.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EU MDR, and ISO 9001 audit schedules create backlog for specialty mesh suppliers seeking cross-border medical and food equipment contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Mesh Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welded Wire, Expanded Metal, Stainless Steel Mesh, Barbed Wire Application: Construction, Agriculture, Mining, Filtration End User: Aerospace, Automotive, Food Processing, Residential Material: Galvanized Steel, Aluminum, Copper, Fiberglass |
| Companies Covered | Parker Hannifin Corporation, GKD Metal Fabrics, McNICHOLS Company, W.S. Tyler, Riverdale Mills, Bekaert, Banker Wire, Dorstener Wire Tech, Haver & Boecker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Mesh Market Strategic Shifts
Digital traceability systems and low-carbon metallurgy are converging to reshape how wire mesh is specified, sourced, and certified across construction and industrial end-uses.
Electro-galvanized coating technology is absorbing incremental compliance costs from REACH substance restrictions while maintaining corrosion performance in moderate exposure environments. Infrastructure contractors in Germany and the Netherlands are specifying these grades for bridge decking and tunnel lining applications where full hot-dip coating exceeds functional requirements. The technology is absorbing margin pressure that would otherwise force price increases or market exit for smaller galvanizing operations.
EU Carbon Border Adjustment Mechanism transitional phase reporting is forcing importers to document embedded emissions in steel wire rod inputs. Customs authorities in Belgium and the Netherlands are piloting digital verification platforms that link mill certificates to import declarations. Asian exporters without verified emissions data face administrative detention risk, redirecting spot procurement toward European and Turkish mills with established carbon accounting.
Consolidated distributor procurement is compressing supplier bases as national construction material wholesalers demand single-source fulfillment across multiple mesh specifications. Buyers in France and Italy are reducing vendor counts from regional fragmentation toward integrated suppliers with warehousing networks covering multiple provinces. This concentration is visible in public tender documentation requiring pan-regional logistics capability as a qualification threshold.
Wire Mesh Market Segmentation
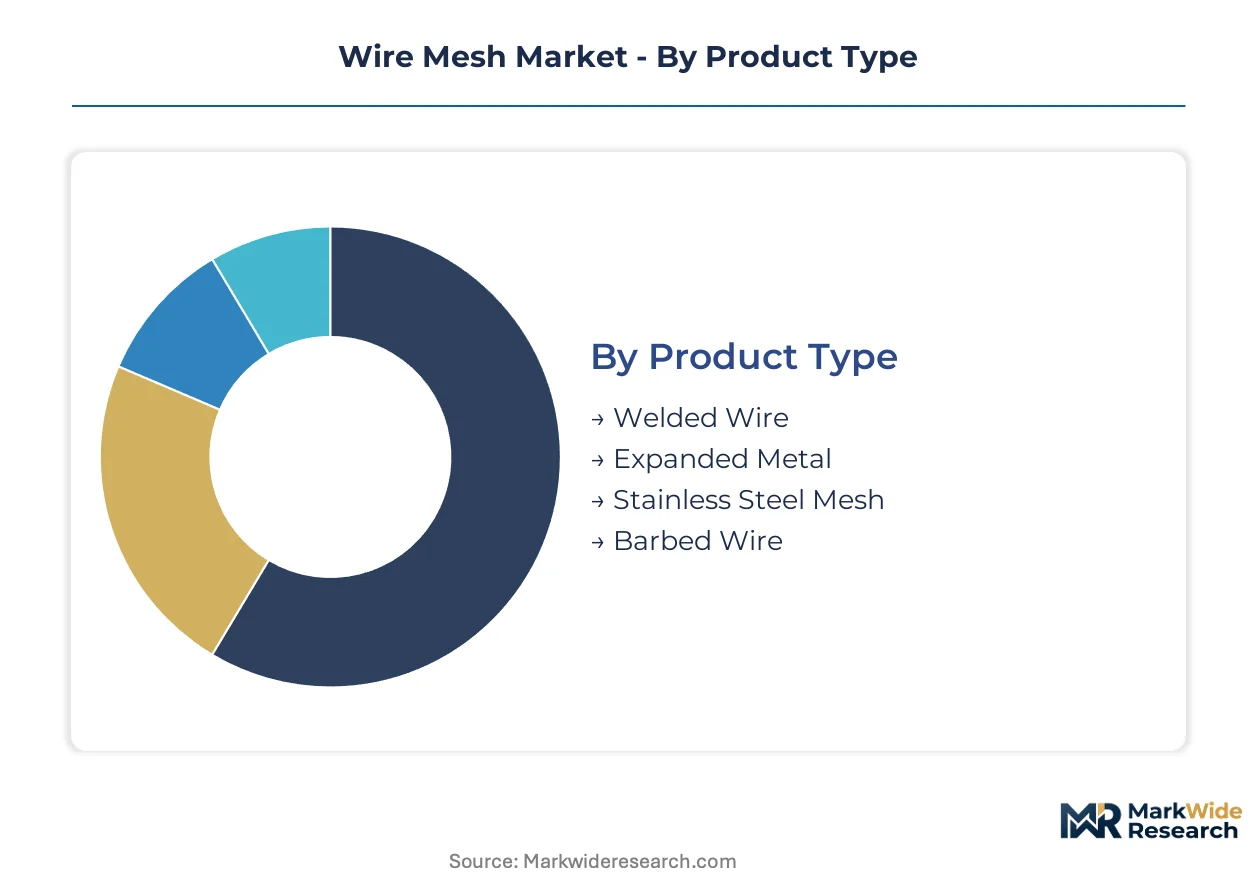
Wire mesh segmentation reveals how specification standards diverge across load-bearing, corrosion-resistant, and aesthetic functions. Product chemistry and weave geometry determine which regulatory frameworks apply, creating distinct certification pathways that reshape supplier economics.
Product Type:
Supply concentration in welded wire fabrication clusters around German Ruhr industrial corridors and Turkish EAF mills with integrated rod-to-mesh capabilities.
- Welded Wire:Intersecting steel wires fused at junctions through resistance welding deliver predictable load distribution for concrete reinforcement. Federal highway programs in the United States specify these grades for bridge deck slabs, compressing installation timelines versus traditional rebar placement. REACH low-carbon sourcing mandates are redirecting procurement toward mills with verified Scope 1-3 emissions documentation.
- Stainless Steel Mesh:Chromium-nickel alloy compositions achieve corrosion immunity in chemical processing and marine exposure environments. Food processing equipment manufacturers in the Netherlands and pharmaceutical filtration suppliers in Switzerland specify these grades for FDA and EU MDR compliance, absorbing premium unit economics for certified material traceability.
- Expanded Metal:Slit and stretched sheet metal creates diamond-pattern apertures for security screening and walkway gratings.
- Barbed Wire:Twisted strand configurations with puncture projections serve perimeter security and livestock containment applications.
Today's leader: Welded Wire. Tomorrow's challenger: Stainless Steel Mesh.
Application:
Cost tier differentiation separates specification-grade projects from commodity procurement, with certified filtration commanding multiples over construction volume.
- Construction:Concrete reinforcement, facade screening, and safety barriers consume standardized mesh specifications across infrastructure and commercial building verticals. India's national highway expansion and metro rail programs are specifying welded wire fabric for paving and structural elements, generating volume demand from state public works departments.
- Filtration:Particle retention applications in food processing, mining slurry separation, and pharmaceutical manufacturing demand tight tolerance mesh counts. FDA food-contact regulations and EU MDR medical device frameworks are mandating finer specifications, expanding premium addressable segments where certification documentation carries pricing power.
- Agriculture:Livestock fencing, grain storage, and greenhouse screening employ galvanized and PVC-coated grades for weather resistance.
- Mining:Ore classification, tailings containment, and safety screening require abrasion-resistant specifications for slurry and aggregate handling.
Construction maintains volume dominance. Filtration climbs the fastest on specification tightening and regulatory certification requirements.
End User:
Customer type fragmentation demands parallel certification tracks, with aerospace and food processing imposing the most stringent audit protocols.
- Food Processing:Hygienic design regulations from FDA and EFSA mandate stainless steel mesh for contact surfaces and filtration stages. Equipment OEMs in Germany and Italy require mill test certificates with full chemical composition disclosure, extending procurement cycles but locking in supplier relationships for multi-year equipment lifecycles.
- Aerospace:Lightweight aluminum and titanium mesh specifications for acoustic liners and debris screens require AS9100 quality management certification. Tier-1 suppliers in France and the United Kingdom source through qualified vendor lists with 24-month qualification timelines.
- Automotive:Grille inserts, battery enclosures, and filtration components specify coated steel and aluminum grades.
- Residential:Security screening, animal containment, and decorative applications drive standardized galvanized and vinyl-coated volume.
Food Processing commands certification premiums. Aerospace offers structural expansion as electric aviation platforms multiply mesh-intensive thermal and acoustic applications.
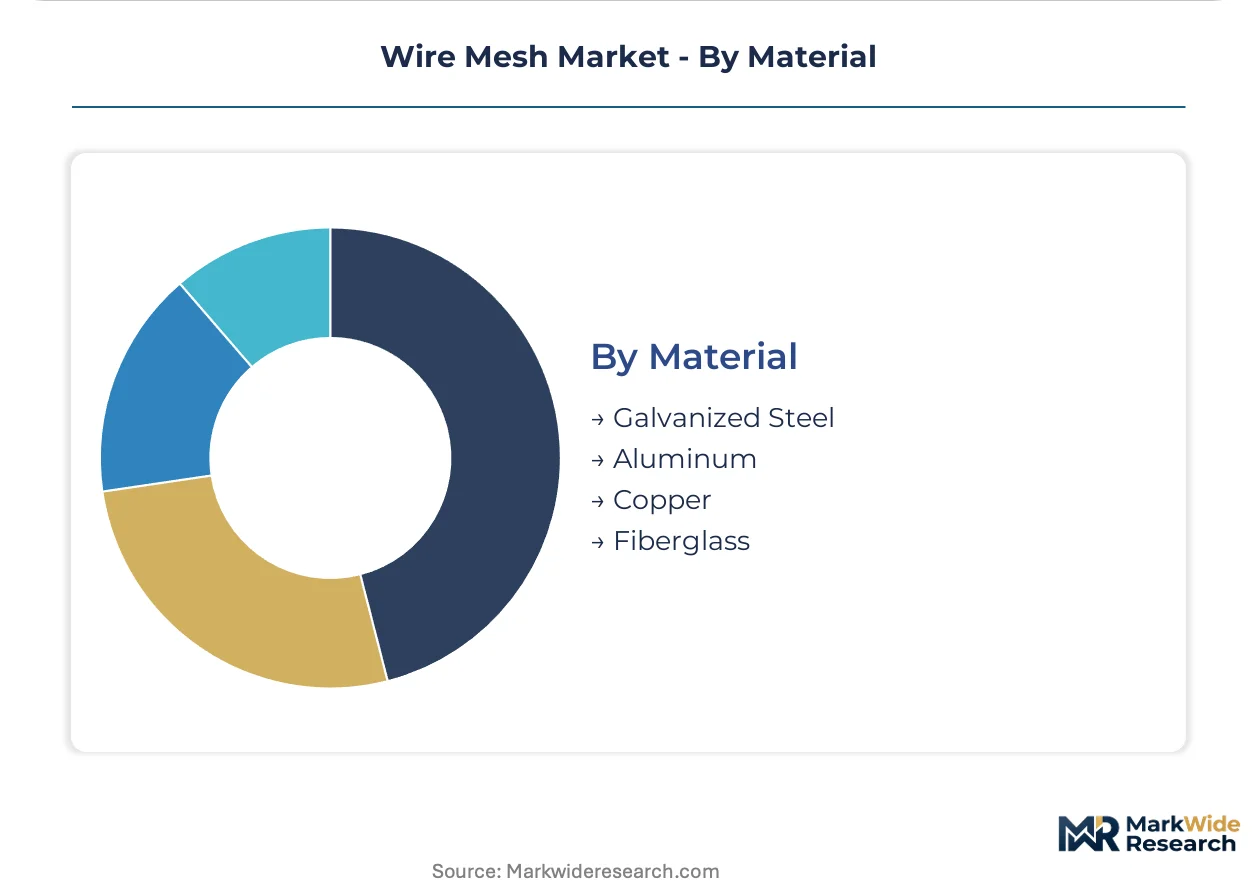
Material:
Margin pools concentrate in corrosion-resistant alloys where specification-grade chemistry commands lasting pricing power over commodity carbon steel.
- Galvanized Steel:Zinc coating layers protect carbon steel substrates in moderate exposure environments through hot-dip or electro-galvanizing processes. Bridge decking and tunnel lining specifications in Germany and the Netherlands are absorbing electro-galvanized grades where full hot-dip coating exceeds functional requirements, preserving margin for smaller galvanizing operations facing REACH compliance costs.
- Aluminum:Lightweight corrosion immunity suits architectural facade systems and transportation applications where mass reduction carries design priority. Building envelope designers in Belgium and France specify woven aluminum mesh for solar shading and aesthetic screening, opening specification channels distinct from commodity construction grades.
- Copper:Antimicrobial properties and electrical conductivity serve specialized medical and electromagnetic screening applications.
- Fiberglass:Non-conductive corrosion resistance addresses electrical utility and chemical processing niches where metal mesh risks galvanic reaction or spark hazard.
Galvanized Steel anchors construction volume. Aluminum gains specification share in building envelope and transportation lightweighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welding technicians and metallurgical engineers concentrate in Germany's Ruhr Valley and India's Gujarat industrial corridor, anchoring fabrication capacity for infrastructure-grade mesh.
United States
Federal highway and bridge rehabilitation programs specify welded wire mesh for deck slab reinforcement, compressing contractor installation timelines. EPA industrial emissions guidelines shape galvanizing facility permitting in the Ohio River Valley. Fabrication clusters around Pittsburgh and Cleveland supply DOT-certified grades for interstate infrastructure.
Germany
REACH compliance deadlines redirect procurement toward low-carbon galvanized grades with verified Scope 1-3 emissions. ECHA substance disclosure mandates force full traceability from steel rod through finished product. The Dortmund-Duisburg industrial corridor concentrates EAF-based wire rod and mesh fabrication capacity.
India
National highway expansion and metro rail programs specify welded wire fabric for concrete paving and structural elements. BIS quality standards govern construction-grade mesh certification for state public works tenders. Gujarat's industrial belt around Ahmedabad and Vadodara hosts integrated steel-to-mesh operations serving infrastructure procurement.
China
Dual carbon goals and MEE emissions enforcement reshape steel wire rod sourcing for mesh producers. GB standards specify tensile and coating requirements for construction and filtration applications. The Yangtze River Delta around Shanghai concentrates architectural mesh fabrication for building envelope exports.
Turkey
EAF-based steel production with integrated carbon accounting captures EU-bound mesh demand ahead of CBAM full implementation. Customs authorities in Belgium pilot digital verification linking Turkish mill certificates to import declarations. Izmir and Bursa industrial zones supply galvanized grades with documented embedded emissions.
Wire Mesh Market Competitive Environment
The competitive structure tilts toward integrated metallurgical players with captive wire rod supply. Market concentration splits between diversified industrial conglomerates and specialized mesh fabricators. Three archetypes dominate: steel majors with backward integration into wire drawing, dedicated mesh specialists with architectural differentiation, and regional distributors controlling warehousing networks. Capacity expansion and certification portfolio diversification represent the primary competitive vectors as compliance requirements fragment addressable markets.
Among European-integrated producers, Bekaert exemplifies the metallurgical-major archetype through in-house steel wire rod production that absorbs REACH compliance costs. GKD Metal Fabrics anchors the specialty-fabricator tier with architectural mesh positioning for facade systems. McNICHOLS Company occupies the distribution-centric position through North American warehousing and fulfillment network control. These three patterns represent how supplier economics diverge across compliance-heavy and specification-grade segments.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| GKD Metal Fabrics |
| McNICHOLS Company |
| W.S. Tyler |
| Riverdale Mills |
| Bekaert |
| Banker Wire |
| Dorstener Wire Tech |
| Haver & Boecker |
| Others |
Value Chain & Pricing Dynamics
Federal highway procurement mandates for welded wire reinforcement are compressing contractor budgets and forcing mills to absorb zinc coating cost volatility through long-term offtake structures rather than spot market exposure. This demand-side specification tightening is redrawing supplier economics toward integrated producers with captive wire rod capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified medical-grade mesh from construction commodity volumes. Price differentiation hinges on REACH compliance documentation and galvanizing process intensity, with electro-galvanized grades capturing margin from specification-grade buyers while hot-dip volumes face cost compression from zinc LME volatility. Public works departments exhibit highest price sensitivity through competitive tendering, whereas pharmaceutical OEMs absorb premium tiers for FDA-validated traceability.
Supply Chain Analysis
Steel wire rod supply rests on German Ruhr Valley EAF mills, Turkish integrated producers, and Chinese Yangtze Delta exporters. Raw material flows draw from zinc concentrate offtake, chromium-nickel alloy feedstock, and low-carbon metallurgical coal. Single-source vulnerability concentrates in the Dortmund-Duisburg corridor where energy price spikes disrupt fabrication schedules. Distribution runs through national construction wholesalers consolidating vendor bases toward pan-regional fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in low-carbon galvanized grades where REACH compliance documentation commands pricing power over commodity imports. Electro-galvanizing technology adoption is compressing production costs for specification-grade bridge decking and tunnel lining applications.
For Market Incumbents: Anchor defensive positioning through backward integration into EAF-based wire rod production to neutralize zinc price volatility and CBAM compliance costs. Secure long-term offtake agreements with German automotive and Dutch food processing OEMs before certification audit backlogs lengthen. Prioritize carbon accounting documentation to defend share against Turkish exporters with verified Scope 1-3 data. For New Entrants and Emerging Players: Regional distributors in France and Italy represent the most penetrable channel partners for white-space entry, as vendor consolidation creates openings for mills with pan-regional logistics capability. Target architectural facade mesh specialization in Belgium and the Netherlands where solar shading specifications outpace commodity construction growth. Pursue qualification through consolidated national wholesalers rather than fragmented regional procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with EAF-integrated mesh fabricators holding REACH-compliant carbon documentation ahead of CBAM full implementation. Five-to-ten year viability favors mills with electric arc furnace capacity and architectural-grade stainless steel weaving capabilities. Watch EU customs pilot programs for digital emissions verification as the inflection signal redirecting spot procurement toward documented suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EAF Wire Rod | Captive metallurgical supply absorbs REACH compliance costs and zinc price volatility for German and Turkish mills. |
| Carbon Border Adjustment Documentation | Verified Scope 1-3 emissions data secures preferential customs clearance through Belgian and Dutch pilot platforms. |
| Architectural Facade Mesh Specialization | Stainless steel and bronze woven specifications for solar shading open premium channels beyond commodity construction grades. |
| Consolidated Distributor Partnership | Pan-regional logistics capability meets French and Italian wholesaler vendor reduction requirements for public tender qualification. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EU MDR, and ISO 9001 audit completion locks in pharmaceutical and food equipment supplier relationships. |
Study Parameters
Multiple input streams — structured interviews with plant managers and procurement leads at downstream construction OEMs, technical discussions with galvanizing operations specialists, and validation sessions with distribution channel partners — were reconciled against customs trade data, ECHA substance registration databases, and SEC filings from integrated steel producers. Bottom-up volume estimates from mesh count specifications and top-down steel wire rod consumption patterns were triangulated to constrain forecast ranges.
Historical shipment patterns from German Ruhr industrial clusters and Turkish EAF-based exporters were cross-referenced against panel input from infrastructure contractors and food processing equipment manufacturers across the analysis window. Segmentation modeling incorporated product type chemistry tiers, application-grade certification requirements, end-user audit protocols, and regional production hub concentrations. CAGRs were derived from installation timeline compression in federal highway programs and specification tightening in pharmaceutical filtration equipment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to zinc LME price trajectories, CBAM enforcement stringency, and carbon accounting standard harmonization across EU customs authorities. Forecasts reflect documented assumptions on infrastructure spending continuity and REACH substance restriction timelines. A small set of named triggers — EAF capacity expansion announcements, digital emissions verification platform rollouts, and FDA food-contact regulation revisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polymer Bearing Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Argon Knife Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Fly Ash Market
Industrial Materials
Battery Separator Materials Market