
 Plastic Injection Mold Market | 2026-2036
Plastic Injection Mold Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Injection Mold Market Insights
Precision-grade multi-cavity tooling is collapsing the cost-per-part economics for high-volume automotive and medical programs. Amcor PLC leverages its packaging specialization to sustain tool qualification cycles across pharmaceutical clients. BASF SE anchors polymer-grade mold specifications through captive material science expertise. Proto Labs differentiates via digital quoting platforms that compress prototype-to-production timelines.
Plastic injection molds are precision-machined tooling systems, typically fabricated from hardened steel or aluminum alloys with tolerances reaching ±0.005 mm, designed to shape molten thermoplastic or thermoset polymers into net-shape components under controlled pressure, temperature, and cooling parameters. The primary commercial purpose centers on enabling mass production of geometrically complex parts with minimal post-processing waste. Multi-cavity and hot runner configurations command premium positioning due to cycle-time efficiency and material savings in high-volume packaging and automotive applications, while cold runner tooling retains cost advantages in lower-volume medical device and consumer electronics prototyping where material recovery economics prove less critical.
REACH compliance in Europe and FDA device-quality regulations in the United States are elevating surface-finish specifications, traceability requirements, and steel-grade documentation for molds serving medical and food-contact applications. China's SAMR enforcement of recycled-content thresholds under evolving GB standards is redirecting runner-system design priorities toward optimized cooling and reduced scrap generation. Stakeholders must weigh capital allocation between hot runner upgrades and modular cold runner platforms as regulatory divergence across major manufacturing jurisdictions intensifies tooling portfolio complexity.
Market Dynamics
Automotive lightweighting mandates are compressing cycle-time requirements and forcing moldmakers toward hot runner architectures with precision cooling corridors. The collision between polymer-grade specifications and recycled-content thresholds is fragmenting tooling portfolios across jurisdictions.
Growth Catalysts
- GB Standards Evolution:China's SAMR enforcement of recycled-content thresholds is redirecting runner-system design toward optimized cooling architectures that minimize scrap generation in high-cavity configurations.
- Medical Device Traceability:FDA device-quality regulations are elevating surface-finish specifications and steel-grade documentation requirements, creating premium positioning for qualified moldmakers serving pharmaceutical packaging.
- Stuttgart Precision Cluster:Germany's tooling belt around Stuttgart and Heilbronn is concentrating multi-cavity expertise for automotive programs demanding sub-0.005 mm tolerances.
Market Restraints
- H13 Steel Price Volatility:Tool steel input costs fluctuate with nickel and chromium supply disruptions, compressing margin buffers for mid-cap mold fabricators.
- Hot Runner Patent Concentration:Proprietary valve-gate and thermal-control IP resides with a narrow supplier base in Western Europe and Japan, limiting second-source options.
- REACH Documentation Burden:ECHA substance-of-very-high-concern declarations add 8-14 weeks to material qualification timelines for molds serving food-contact applications.
Strategic Opportunities
- India Medical Device Manufacturing:CDSCO production-linked incentive schemes are attracting contract manufacturers seeking local mold qualification for export markets.
- Conformal Cooling Integration:Additive-manufactured cooling channels merged with conventional CNC bases are collapsing thermal-cycle times in complex automotive geometries.
- Brazil ANVISA Harmonization:Emerging alignment between Brazilian pharmaceutical packaging rules and FDA standards is reducing dual-qualification costs for multinational mold programs.
Industry Challenges
- Five-Axis Programming Shortage:CAM specialists capable of complex cavity machining command wage premiums exceeding 40% above standard moldmaking rates.
- Hot-to-Cold Retrofit Complexity:Legacy tool frames require extensive base modifications to accommodate modern manifold systems, extending rebuild timelines.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA, EMA, and NMPA qualification demands create conflicting documentation standards for surface-finish validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Injection Mold Market |
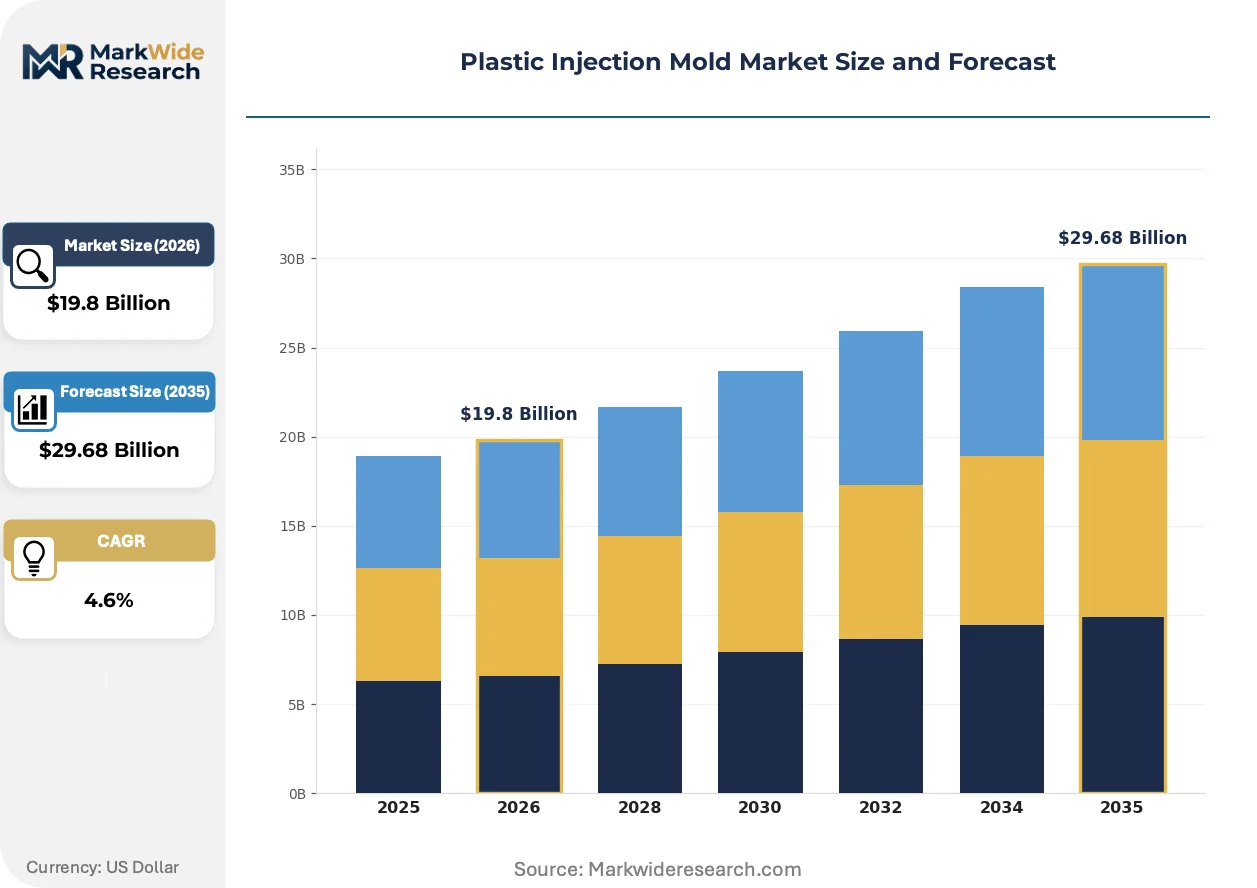
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cavity, Multi Cavity, Hot Runner, Cold Runner End User: Automotive Components, Consumer Electronics, Medical Devices, Packaging Solutions Material: Thermoplastics, Thermosets, Composites, Elastomers Manufacturing Stage: Prototyping, Production, Tooling, Maintenance |
| Companies Covered | ALPLA, Amcor PLC, AptarGroup, Inc., Silgan Holdings Inc., BASF SE, HTI Plastics, DuPont, LyondellBasell, Proto Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Injection Mold Market Trends and Innovations
Digital thread integration from CAD to CNC is collapsing prototype-to-production timelines while regulatory divergence is fragmenting tooling specifications across major manufacturing jurisdictions.
Conformal cooling channels produced through selective laser melting are supplanting straight-drilled circuits in automotive bumper and fascia molds. Tier-1 suppliers in Germany and Japan are adopting these architectures for programs above 500,000 annual units. The technology is supplanting conventional beryllium-copper inserts by delivering uniform heat extraction without galvanic corrosion risks in aggressive cooling chemistries.
REACH SVHC candidate list expansions are restricting chrome-plating options for high-gloss cavity surfaces. Moldmakers serving cosmetic packaging are migrating to physical vapor deposition and diamond-like carbon coatings to maintain release properties. European medical device programs are most affected, with qualification protocols now requiring third-party coating-substance declarations.
Consolidated procurement desks at multinational automotive OEMs are compressing supplier rosters from 12-15 mold vendors to 4-6 strategic partners. Tier-2 mold shops are responding by forming fabrication consortia that share five-axis capacity and thermal-simulation expertise. The restructuring is most visible in North American powertrain programs where platform consolidation has halved unique tool programs per vehicle line.
Plastic Injection Mold Market Segmentation
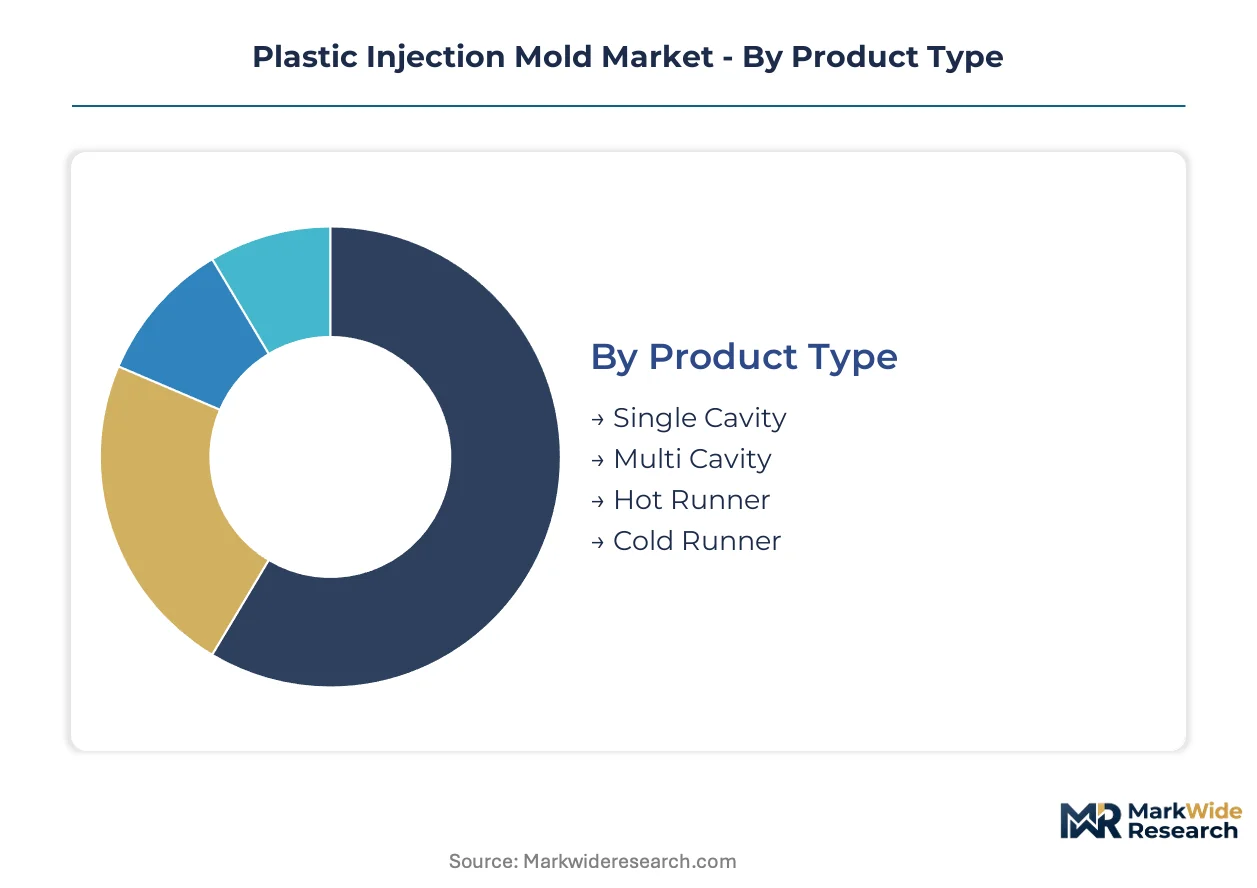
Plastic injection mold segmentation reveals divergent value capture across tooling architectures and end-use specifications. Each dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Hot runner configurations face the strongest substitution pressure from advancing cold runner designs in cost-sensitive prototyping segments.
- Multi Cavity:These configurations integrate 4-32 cavities within a single tool frame, enabling cycle-time compression for automotive and packaging programs demanding 500,000+ annual units. Stuttgart's precision tooling cluster concentrates expertise for sub-0.005 mm tolerance multi-cavity programs serving German automotive OEMs. China's SAMR recycled-content mandates are accelerating hot-to-multi-cavity conversions to minimize runner waste.
- Hot Runner:Valve-gate and thermal-control architectures eliminate solidified runners, reducing material scrap by 15-30% in high-cavity pharmaceutical packaging applications. Patent concentration in Western Europe and Japan limits second-source options and extends lead times for complex manifold systems. FDA device-quality regulations elevate surface-finish specifications for hot runner molds serving medical device clients.
- Single Cavity:Simplified tooling for low-volume medical device prototyping and custom automotive components where part complexity exceeds multi-cavity feasibility.
- Cold Runner:Conventional two-plate and three-plate designs retain cost advantages in consumer electronics prototyping and short-run medical device validation where material recovery economics prove less critical.
Multi cavity retains volume leadership; hot runner holds the steepest expansion curve.
End User:
Cost tier stratification separates qualification-heavy medical programs from price-elastic consumer electronics tooling.
- Automotive Components:Lightweighting mandates for bumper fascias, interior panels, and powertrain housings demand hot runner architectures with conformal cooling channels. Tier-1 suppliers in Germany and Japan are adopting selective laser melting cooling circuits for programs above 500,000 annual units. NHTSA crashworthiness standards and EPA fuel economy regulations simultaneously pressure wall-thinning and structural integrity.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations and EMA MDR requirements impose steel-grade documentation, surface-finish validation, and traceability protocols that extend qualification timelines. CDSCO production-linked incentive schemes in India are attracting contract manufacturers seeking local mold qualification for export markets.
- Packaging Solutions:Pharmaceutical blister packs, food containers, and cosmetic compacts drive high-cavity tooling demand with aggressive cycle-time targets.
- Consumer Electronics:Smartphone housings, laptop chassis, and wearable enclosures prioritize rapid prototyping turnaround over production efficiency.
Automotive components command the largest tooling spend; medical devices show the most rapid margin expansion.
Material:
Application maturity varies sharply across polymer families, with thermoplastics dominating established mass production.
- Thermoplastics:Polypropylene, ABS, and polycarbonate formulations enable regrind and recycling compatibility that aligns with China's evolving GB standards for recycled content. REACH SVHC restrictions on certain flame retardants are redirecting specification priorities for electrical housing applications.
- Thermosets:Epoxy and phenolic resins serve high-heat automotive underhood components and electrical insulators where dimensional stability exceeds recyclability concerns.
- Composites:Glass-fiber and carbon-fiber reinforced polymers are displacing metal in structural automotive applications, requiring hardened steel molds with specialized wear-resistant coatings.
- Elastomers:TPE and liquid silicone rubber molds serve medical seals, automotive gaskets, and consumer soft-touch interfaces with distinct thermal control requirements.
Thermoplastics anchor current volume; composites are gaining share fastest in automotive lightweighting programs.
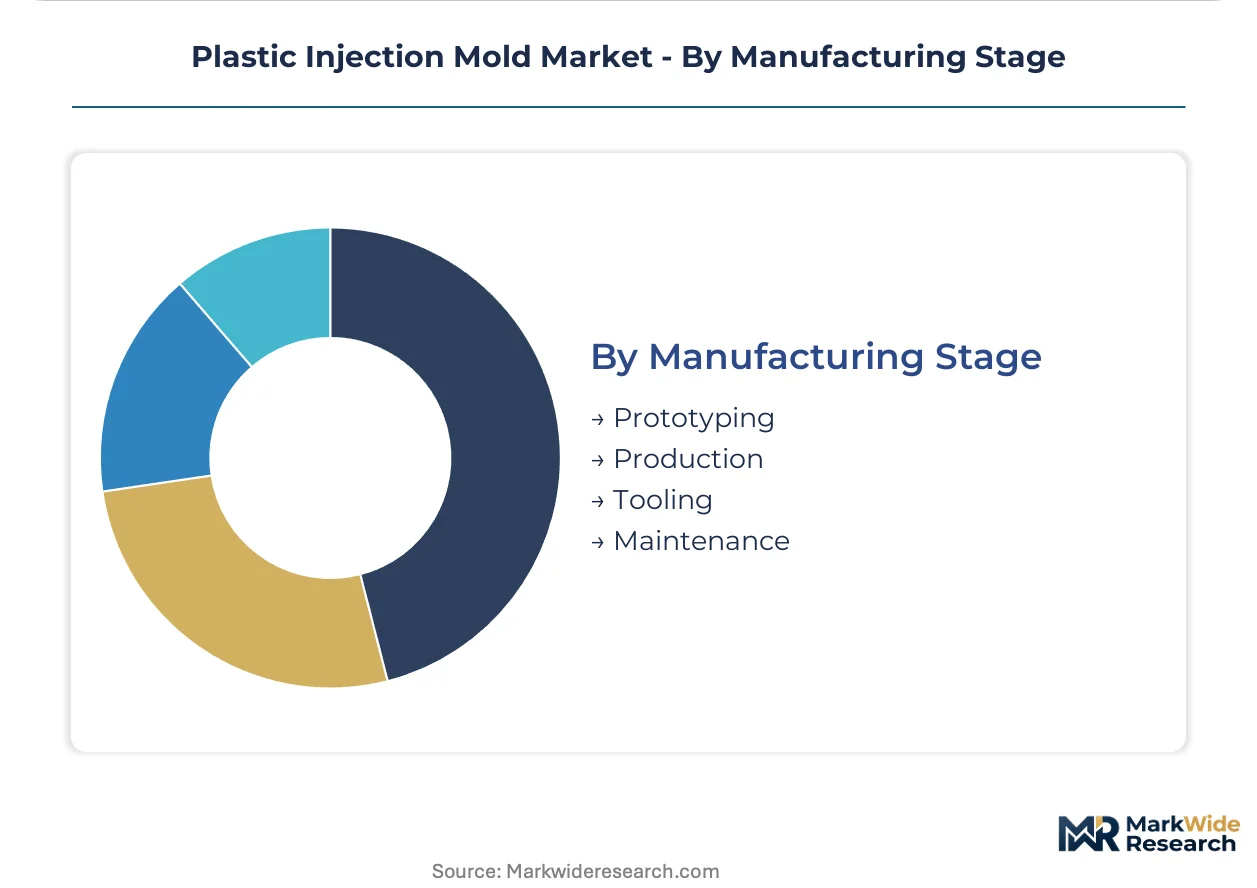
Manufacturing Stage:
Customer type fragmentation separates captive OEM tooling divisions from independent mold shops serving fragmented demand.
- Production:Full-scale manufacturing tooling represents the revenue core, with multi-year program commitments and integrated maintenance contracts. Consolidated procurement desks at multinational automotive OEMs have compressed supplier rosters from 12-15 vendors to 4-6 strategic partners.
- Prototyping:Bridge tooling and soft-tool aluminum molds enable design validation before hardened steel production commitment. Digital quoting platforms are compressing prototype-to-production timelines through automated DFM feedback.
- Tooling:Original mold fabrication encompasses design, CNC machining, heat treatment, and final assembly with qualification protocols.
- Maintenance:Refurbishment, repair, and engineering change services extend tool life cycles and capture recurring revenue from installed base programs.
Production dominates value capture; prototyping shows the steepest technology disruption from digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany and China as net mold exporters while the United States and India remain substantial importers of precision tooling. Trade flows concentrate high-value multi-cavity systems in Stuttgart and Shanghai while lower-complexity tooling migrates toward cost-optimized fabrication clusters.
China
SAMR enforcement of evolving GB standards for recycled content is redirecting runner-system design priorities across Guangdong and Zhejiang mold shops. NMPA medical device regulations are elevating surface-finish documentation requirements for export-bound pharmaceutical packaging tooling. The Yangtze River Delta concentrates the country's largest multi-cavity fabrication capacity serving automotive OEMs.
Germany
EMA MDR compliance timelines are extending qualification protocols for medical-grade mold exports to neighboring European markets. REACH SVHC declarations add material certification burdens for food-contact cavity surfaces. The Stuttgart-Heilbronn precision tooling belt anchors multi-cavity expertise for sub-0.005 mm tolerance automotive programs.
United States
FDA 21 CFR Part 820 quality system regulations impose steel-grade traceability requirements that extend procurement cycles for pharmaceutical clients. NHTSA lightweighting mandates are compressing cycle-time specifications for bumper fascia and interior panel tooling. Michigan and Ohio tooling corridors concentrate automotive mold maintenance and engineering change services.
Japan
METI industrial policy supports domestic mold fabrication for high-value automotive and electronics applications amid import substitution pressures. PMDA pharmaceutical packaging standards align with FDA benchmarks, reducing dual-qualification friction for export-oriented moldmakers. The Chubu region around Nagoya retains concentrated expertise in hot runner manifold systems.
India
CDSCO production-linked incentive schemes are attracting contract manufacturers seeking localized mold qualification for pharmaceutical export markets. BIS standards harmonization with ISO specifications is streamlining import substitution for packaging tooling. Maharashtra and Gujarat industrial corridors are emerging as fabrication hubs for medical device and consumer goods molds.
Plastic Injection Mold Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and qualification depth. The vendor base organizes into three tiers: multinational material-science conglomerates with captive tooling divisions, mid-cap independent fabricators with regional qualification expertise, and specialized prototype shops leveraging digital quoting platforms. Consolidation pressures favor scale-driven M&A among automotive-focused moldmakers while technology licensing agreements proliferate around conformal cooling patents.
Within the material-science conglomerate tier, BASF SE anchors polymer-grade mold specification authority through captive resin expertise. Among digital-native fabricators, Proto Labs exemplifies automated quoting platforms that compress prototype-to-production timelines. Amcor PLC occupies a position bridging packaging specialization with pharmaceutical client qualification cycles.
| Leading Market Players |
|---|
| ALPLA |
| Amcor PLC |
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| BASF SE |
| HTI Plastics |
| DuPont |
| LyondellBasell |
| Proto Labs |
| Others |
Pricing and Supply Chain Analysis
Selective laser melting is displacing conventional beryllium-copper inserts in conformal cooling applications, simultaneously shifting supply gravity toward additive manufacturing hubs in Germany and Japan while compressing thermal-management premiums in high-cavity automotive tooling.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with FDA-qualified medical molds commanding substantial premiums over unvalidated consumer electronics tooling. Cost compression in standard-tier cold runner configurations is intensifying because mid-cap fabricators face H13 steel price volatility. Tier-2 automotive suppliers exhibit the highest price sensitivity, while pharmaceutical packaging clients prioritize qualification depth over unit economics.
Supply Chain Analysis
Strategic stockpiling of tool steel dominates inventory strategy given nickel and chromium supply disruptions. Germany, China, and Japan concentrate multi-cavity fabrication capacity, with the Stuttgart-Heilbronn belt and Yangtze River Delta anchoring high-precision output. The supply chain draws from specialized H13 steel mills, hot runner manifold suppliers, and five-axis CAM service providers. Single-source vulnerability in proprietary valve-gate IP from Western Europe and Japan creates qualification bottlenecks. Distribution runs through Tier-1 supplier procurement desks and direct OEM mold engineering divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments tooling specifications, creating specialist niches for qualified moldmakers serving multi-jurisdiction pharmaceutical programs.
For Market Incumbents: Consolidate five-axis machining capacity and thermal-simulation expertise through fabrication consortia to defend against procurement desk compression at multinational automotive OEMs. Pursue backward integration into conformal cooling additive manufacturing to capture value migrating from conventional beryllium-copper inserts. Deepen certification investment in FDA 21 CFR Part 820 and EMA MDR protocols to sustain premium positioning.
For New Entrants and Emerging Players: Lead with digital quoting platforms and automated DFM feedback to compress prototype-to-production timelines for consumer electronics and medical device validation programs. Target India's CDSCO production-linked incentive corridors where localized mold qualification demand outpaces domestic fabrication capacity. Emphasize rapid-turn bridge tooling as the go-to-market wedge before hardened steel production commitment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with multi-jurisdiction qualification depth and captive additive manufacturing capabilities. Long-term viability hinges on exposure to automotive lightweighting mandates and pharmaceutical packaging traceability requirements. Acquisition targets should demonstrate integrated conformal cooling expertise and established FDA/EMA qualification protocols. Watch for inflection when hot runner patent concentration in Western Europe and Japan begins eroding through technology licensing agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Conformal Cooling Integration | Additive-manufactured thermal channels collapse cycle times for Stuttgart automotive programs above 500,000 annual units. |
| Multi-Jurisdiction Qualification | Simultaneous FDA, EMA, and NMPA certification captures pharmaceutical packaging premiums from export-oriented contract manufacturers. |
| Digital Quoting Platform | Automated DFM feedback compresses prototype-to-production timelines for medical device and consumer electronics clients. |
| Hot Runner Patent Licensing | Technology agreements erode Western Europe and Japan supplier concentration, expanding second-source options for valve-gate systems. |
| India Manufacturing Localization | CDSCO incentive schemes attract mold qualification capacity serving pharmaceutical export markets from Maharashtra and Gujarat corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across mold engineering divisions, Tier-1 automotive supplier procurement teams, pharmaceutical packaging quality directors, and medical device contract manufacturing executives. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, SAMR GB standard drafts, customs trade data for tool steel and finished mold imports, and SEC disclosures from material-science conglomerates with captive tooling divisions. Bottom-up fabrication capacity estimates were triangulated against top-down OEM tooling spend allocations across automotive, medical, and packaging verticals.
Across the projection horizon, the analytical framework modeled segmentation dimensions including tooling architecture, end-use industry, polymer material family, and manufacturing stage. CAGRs were derived from production volume trajectories in automotive lightweighting programs and pharmaceutical packaging unit demand. Industry-specific forecast inputs incorporated NHTSA fuel economy regulation timelines, REACH SVHC candidate list expansion schedules, and China SAMR recycled-content threshold enforcement patterns.
The analysis sits within stated boundaries; outcomes outside sustained automotive platform consolidation or accelerated EMA MDR compliance timelines would require recalibration. Forecasts reflect assumptions regarding H13 steel price stability, hot runner patent licensing velocity, and five-axis CAM specialist labor availability. Revision becomes warranted when regulatory divergence across FDA, EMA, and NMPA jurisdictions crosses thresholds that fragment tooling specifications beyond current qualification protocol adaptation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Cork Material Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Couplings Market
Industrial Materials
Injection Molding Market