
 Renal Denervation Devices Market | 2026-2036
Renal Denervation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Denervation Devices Market Outlook
Polymer jacketing on radiofrequency catheters is recalibrating thermal delivery economics by improving lesion predictability and reducing endothelial trauma. Medtronic plc leverages decades of interventional cardiology channel control to sustain physician training infrastructure across major health systems. Boston Scientific Corporation anchors its position through R&D intensity in multi-electrode array designs. ReCor Medical, Inc. differentiates with ultrasound-based energy delivery that avoids renal artery intimal disruption.
Renal denervation devices are catheter-delivered systems that ablate perivascular renal sympathetic nerves to modulate hypertension, typically operating at radiofrequency energies of 8–10 watts or ultrasound intensities sufficient to achieve 55–65°C tissue temperatures without vessel perforation. Ablation catheters command the dominant margin pool due to recurring procedural consumption, while ultrasound technology represents the fastest-growing modality as clinical data accumulates for resistant hypertension populations. Delivery mode segmentation shows cath lab settings retaining volume leadership, though outpatient migration is accelerating where same-day discharge protocols gain institutional approval.
FDA breakthrough device designation pathways and EU MDR conformity requirements are reshaping market access timelines, with the former compressing premarket review and the latter imposing stricter clinical evidence standards for active implantable devices. Japan's PMDA has established comparable fast-track frameworks for innovative cardiovascular interventions, creating a tri-regional regulatory convergence that favors companies with parallel submission capabilities. Stakeholders must monitor reimbursement determinations from CMS and analogous national health technology assessment bodies, as these decisions will determine whether procedural volumes shift from trial enrollment to commercial adoption.
Market Dynamics
Catheter-based renal denervation is pivoting from trial enrollment to commercial volume as FDA breakthrough pathways and EU MDR CE markings compress time-to-reimbursement, forcing hospital systems to choose between radiofrequency and ultrasound platforms before long-term outcome data matures.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's expedited review framework for innovative cardiovascular interventions compresses premarket timelines, enabling earlier hospital procurement decisions and accelerating catheter lab program launches across US tertiary cardiac centers.
- Resistant Hypertension Prevalence:Patient populations failing triple-drug regimens are expanding as lifestyle factors and comorbidities compound, creating addressable demand for sympathetic nerve modulation when pharmaceutical management plateaus.
- Ultrasound Energy Delivery:Non-thermal ablation modalities that preserve renal artery intimal integrity are accumulating clinical evidence, differentiating platforms in interventional cardiologist preference surveys and driving technology substitution in high-volume cath labs.
Market Restraints
- Reimbursement Uncertainty:CMS national coverage determinations and analogous health technology assessment bodies in Germany and Japan remain pending, freezing commercial procedural volumes in trial-to-practice transition zones.
- Supply Concentration:Specialty catheter manufacturing for multi-electrode radiofrequency arrays depends on concentrated polymer jacketing suppliers in Switzerland and Germany, creating vulnerability to medical-grade polymer allocation disruptions.
- Clinical Evidence Gaps:Long-term durability of blood pressure reduction beyond 36 months remains underpowered in registries, constraining payer willingness to expand indication coverage beyond resistant hypertension subsets.
Strategic Opportunities
- Outpatient Migration:Same-day discharge protocols gaining institutional approval in US ambulatory surgical centers and Japanese specialized hypertension clinics are opening volume expansion outside traditional hospital cath lab settings.
- EU MDR Parallel Submissions:Companies with integrated regulatory affairs capabilities can leverage CE marking clinical packages for PMDA fast-track pathways in Japan, compressing tri-regional market access timelines against single-region competitors.
- Heart Failure Comorbidity:Sympathetic hyperactivity in heart failure with preserved ejection fraction represents an adjacent indication where renal denervation mechanisms may address unmet need, pending dedicated trial outcomes.
Industry Challenges
- Interventional Cardiologist Training:Procedural proficiency for ultrasound-guided renal artery navigation requires simulator-based credentialing programs that strain hospital education budgets and extend sales cycle timelines.
- EU MDR Technical Documentation:Stricter clinical evidence standards for active implantable devices under the EU MDR are forcing retrospective data collection and post-market clinical follow-up investments that delay portfolio refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Denervation Devices Market |
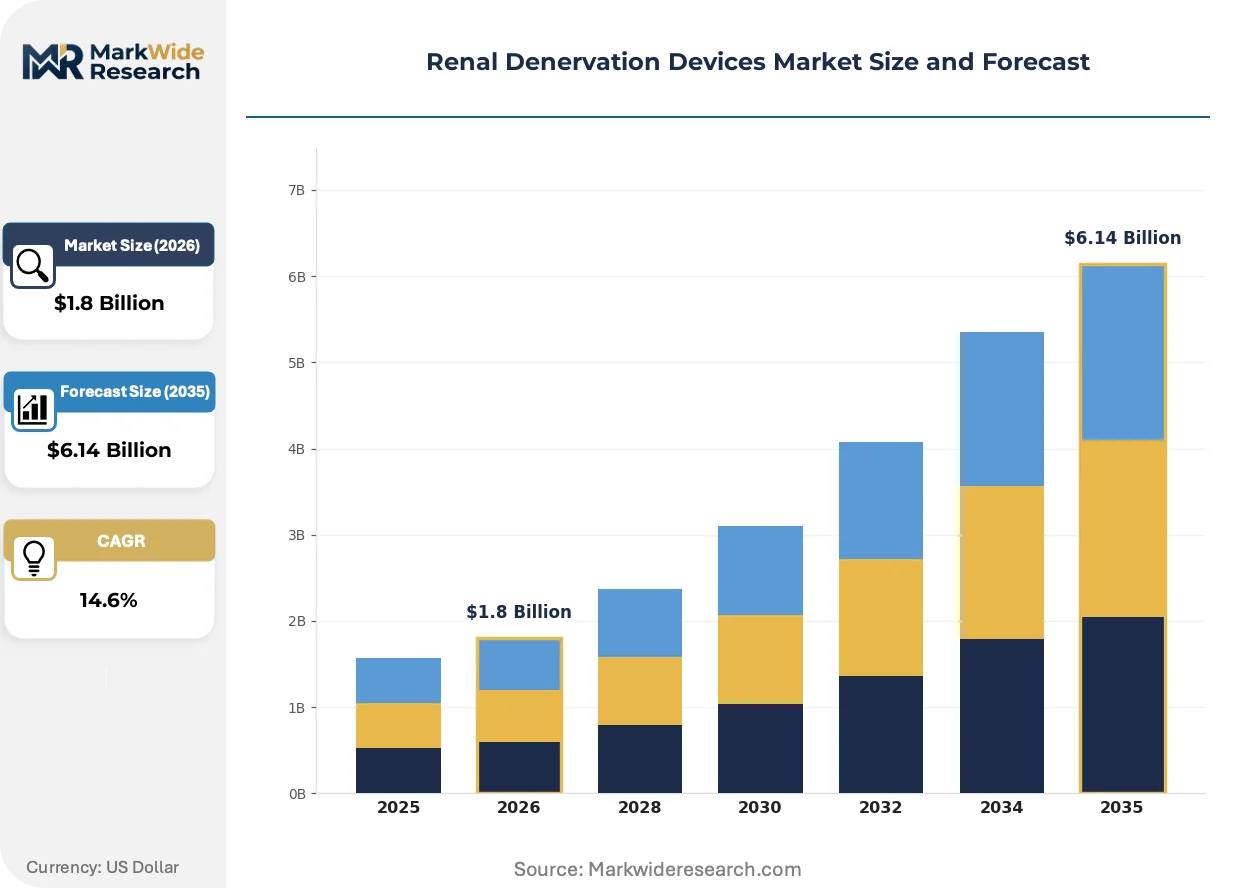
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ablation Catheters, Stimulation Devices, Surgical Tools, Accessories Delivery Mode: Cath Lab, Outpatient, Hospital, Home Care End User: Hospitals, Clinics, Research Institutions, Specialty Centers Technology: Radiofrequency, Ultrasound, Laser, Cryoablation |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, ReCor Medical, Inc., Ablative Solutions, Inc., Mercator MedSystems, Inc., Otsuka Medical Devices Co., Ltd., Terumo Corporation, Symple Surgical, Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Denervation Devices Market Strategic Shifts
Energy delivery modalities and procedural settings are diverging simultaneously as manufacturers bet on distinct thermal physics while hospital systems test economic boundaries between inpatient and outpatient venues.
Ultrasound-based renal denervation is decentralizing procedural site requirements by eliminating the need for continuous radiofrequency generator tethering and enabling portable console deployment. Ambulatory surgical centers in Texas and Florida are piloting same-day programs with mobile ultrasound platforms, compressing capital expenditure barriers that previously confined adoption to fixed cath lab infrastructure.
EU MDR conformity assessment for active implantable devices is elevating clinical evidence standards across the CE marking landscape. Notified bodies in Germany and the Netherlands are demanding extended follow-up data for renal denervation systems, extending time-to-market for second-generation catheters and favoring incumbents with established post-market surveillance registries.
Hospital procurement committees are consolidating vendor relationships around platforms offering bundled training and outcome tracking. Tertiary cardiac centers in Japan and the United States are negotiating multi-year supply agreements that embed proctoring services and quality dashboards, displacing transactional catheter purchasing with integrated hypertension program partnerships.
Renal Denervation Devices Market Segmentation
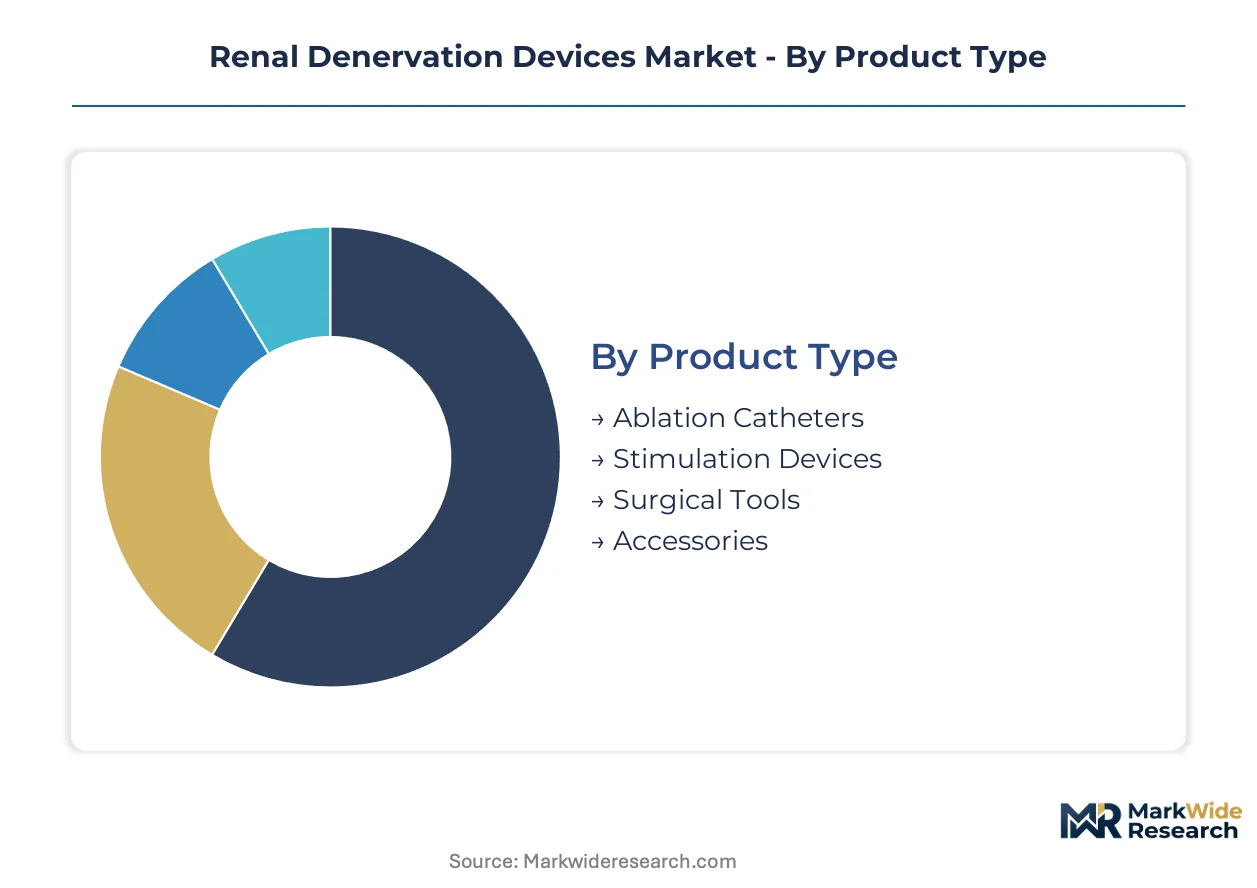
Segmentation in renal denervation devices reveals how energy delivery physics, procedural economics, and care setting migration interact to reshape vendor positioning. Manufacturers must align catheter specifications with cath lab infrastructure or ambulatory expansion strategies to capture procedural volume.
Product Type:
Product architecture determines recurring revenue economics and manufacturing complexity across the procedural lifecycle.
- Ablation Catheters:Multi-electrode radiofrequency arrays with polymer jacketing deliver thermal energy at 8–10 watts while preserving endothelial integrity. Tertiary cardiac centers in Germany and the United States concentrate procurement around platforms with integrated temperature monitoring, driven by lesion predictability requirements and physician training infrastructure investments.
- Stimulation Devices:Percutaneous neuromodulation systems apply low-frequency electrical pulses to renal sympathetic fibers without thermal destruction. Japanese specialized hypertension clinics are piloting these for patients with anatomical contraindications to ablation, constrained by limited long-term efficacy data in resistant hypertension populations.
- Surgical Tools:Laparoscopic and open surgical instruments for direct renal nerve transection.
- Accessories:Guidewires, introducer sheaths, and irrigation tubing supporting catheter placement.
Ablation catheters lead on scale; stimulation devices lead on momentum.
Delivery Mode:
Procedural site selection reflects institutional risk tolerance and reimbursement pathway maturity.
- Cath Lab:Fixed interventional suites with fluoroscopy and hemodynamic monitoring remain the dominant venue for radiofrequency procedures. Hospital systems across the United States and Japan anchor hypertension program investments here, constrained by capital equipment requirements and interventional cardiologist staffing.
- Outpatient:Ambulatory surgical centers and same-day discharge protocols are expanding fastest in Texas and Florida, enabled by ultrasound platform portability and reduced post-procedural monitoring needs.
- Hospital:Inpatient admission with overnight observation for complex cases or comorbid patients.
- Home Care:Remote blood pressure monitoring and medication management following procedural intervention.
Cath lab settings retain volume concentration; outpatient migration shows the steepest expansion trajectory.
End User:
Customer type segmentation tracks purchasing authority and clinical decision-making concentration.
- Hospitals:Tertiary cardiac centers with integrated cath labs command procurement decisions through value analysis committees, negotiating multi-year supply agreements that bundle proctoring services and quality dashboards.
- Clinics:Specialized hypertension and nephrology practices in Germany and Japan are gaining procedural volume as same-day protocols reduce admission requirements.
- Research Institutions:Academic medical centers conducting sham-controlled trials and registry enrollment.
- Specialty Centers:Dedicated cardiovascular intervention facilities with focused physician expertise.
Hospitals dominate current purchasing; clinics are gaining share fastest through outpatient protocol expansion.
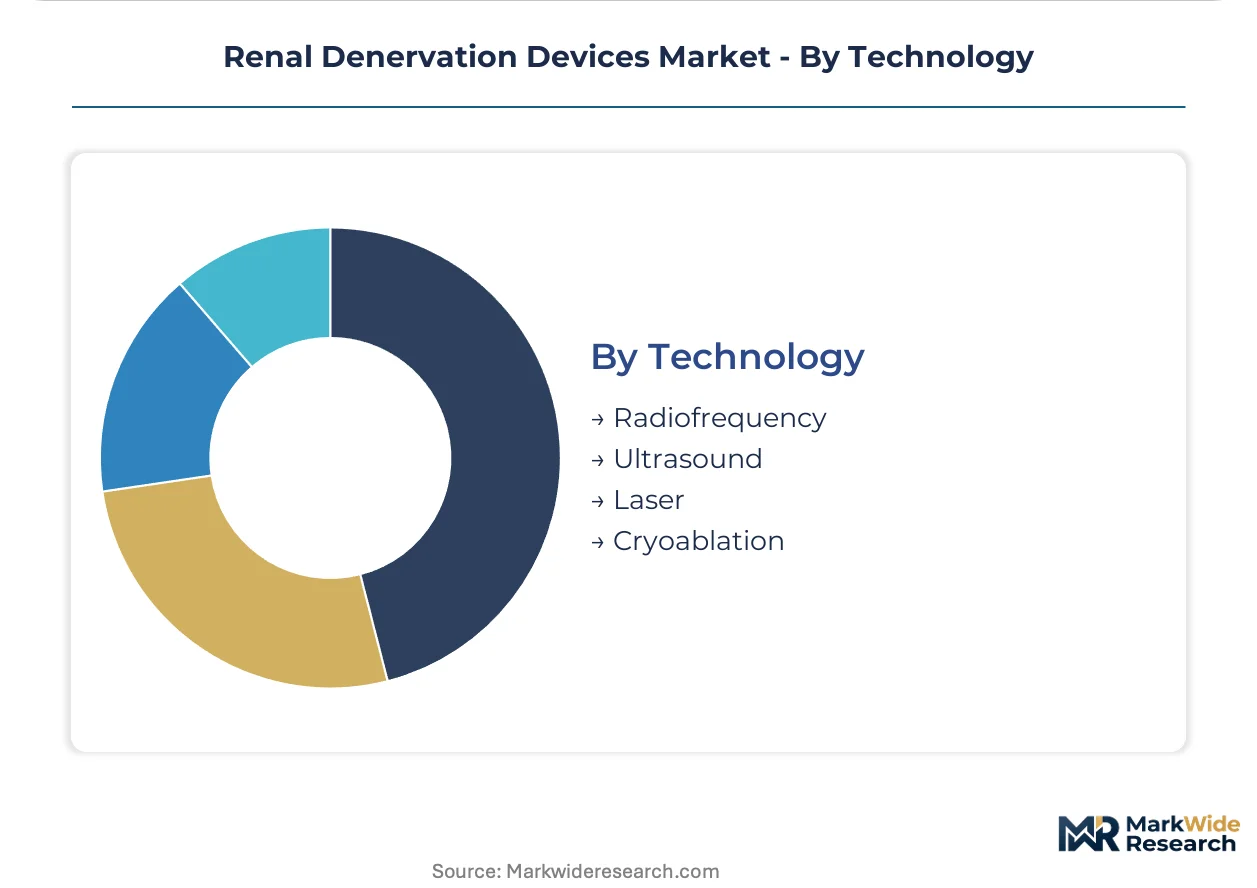
Technology:
Energy modality selection determines thermal physics, vascular safety profile, and regulatory evidence requirements.
- Radiofrequency:Resistive heating at 8–10 watts through multi-electrode arrays creates circumferential perivascular lesions. Medtronic plc and Boston Scientific Corporation anchor market presence here, with decades of interventional cardiology channel control supporting physician training infrastructure across major health systems.
- Ultrasound:High-intensity focused energy achieves 55–65°C tissue temperatures without electrode-tissue contact, preserving renal artery intimal integrity. ReCor Medical, Inc. differentiates on this platform, with clinical data accumulation in resistant hypertension populations driving interventional cardiologist preference in high-volume cath labs.
- Laser:Photothermal energy delivery through fiberoptic catheter systems.
- Cryoablation:Transmural freezing for nerve destruction with reduced thermal spread risk.
Radiofrequency leads on scale; ultrasound leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital systems anchor procedural volume expansion as tertiary cardiac centers in Munich and Berlin scale catheter-based hypertension programs. FDA breakthrough pathways in the United States and PMDA fast-track frameworks in Japan are compressing commercial timelines across three major markets simultaneously.
United States
Tertiary cardiac centers in Texas and Florida are piloting same-day discharge protocols for ultrasound-guided procedures. FDA breakthrough device designations for multiple platforms have accelerated hospital procurement decisions ahead of CMS national coverage determinations. The Cleveland Clinic and Mayo Clinic anchor training infrastructure investments across Midwestern health systems.
Germany
University hospitals in Munich, Heidelberg, and Berlin dominate European procedural volume as EU MDR CE markings validate second-generation catheter platforms. The country's statutory health insurance system awaits parallel reimbursement decisions from the Federal Joint Committee. Baden-Württemberg's medical device cluster supplies polymer jacketing components for multi-electrode radiofrequency arrays.
Japan
Specialized hypertension clinics in Tokyo and Osaka are gaining procedural volume through PMDA fast-track frameworks for innovative cardiovascular interventions. The aging demographic expands resistant hypertension prevalence beyond pharmaceutical management thresholds. Keio University Hospital anchors physician training networks across the Kanto region.
United Kingdom
NHS England's specialized commissioning frameworks are evaluating renal denervation for resistant hypertension inclusion in the national tariff. Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust lead registry enrollment and sham-controlled trial participation. London's concentration of interventional cardiologists supports rapid protocol adoption once reimbursement finalizes.
Switzerland
Medical-grade polymer suppliers in the Basel region and Zurich canton anchor the supply chain for radiofrequency catheter jacketing. University Hospital Zurich and Geneva University Hospitals participate in multinational post-market surveillance registries. Swissmedic's streamlined conformity assessment procedures attract early-stage device testing from international manufacturers.
Renal Denervation Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers align with hospital systems for integrated hypertension program deployment. The vendor base concentrates around three technology platforms with distinct energy delivery physics, creating tiered competitive positions based on clinical evidence accumulation and physician training infrastructure. Two strategic archetypes have emerged: diversified interventional cardiology conglomerates leveraging channel control, and ultrasound-focused specialists betting on non-thermal differentiation. M&A activity and multi-year supply agreements with bundled proctoring services represent the dominant competitive moves.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify positions built on decades of interventional cardiology channel relationships and multi-electrode radiofrequency platforms. ReCor Medical, Inc. occupies a specialist position anchored to ultrasound energy delivery and portable console deployment. These three companies collectively span the technology modality split reshaping interventional cardiologist preference in high-volume cath labs.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| ReCor Medical, Inc. |
| Ablative Solutions, Inc. |
| Mercator MedSystems, Inc. |
| Otsuka Medical Devices Co., Ltd. |
| Terumo Corporation |
| Symple Surgical, Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Ultrasound platform portability is recalibrating both capital expenditure economics and manufacturing location decisions, compressing cath lab infrastructure requirements while shifting component sourcing toward semiconductor-grade electronics suppliers in Taiwan and South Korea.
Pricing Analysis
Medical-grade polymer costs for radiofrequency catheter jacketing pass through directly to hospital procurement committees, with Swiss and German suppliers commanding premiums for endothelial-safe formulations. Three-tier pricing structure across premium multi-electrode arrays, standard single-electrode platforms, and economy stimulation devices reflects FDA breakthrough designation status and bundled training service levels. Pricing pressure stems from ultrasound modality competition as portable consoles reduce capital barriers. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiac centers with established cath labs prioritize lesion predictability over per-procedure cost.
Supply Chain Analysis
Freight costs for temperature-controlled polymer resin shipments from Basel to catheter manufacturing facilities in Germany and the United States add 8-12% to landed input costs, compressing margins on standard-tier radiofrequency arrays. Component sourcing draws from Switzerland for polymer jacketing, Taiwan for microelectronic sensors, and Japan for precision guidewire alloys. Single-source vulnerability concentrates in Swiss polymer suppliers serving multi-electrode array manufacturers. Distribution runs through hospital value analysis committees and group purchasing organizations, with direct-to-hospital contracting gaining share for bundled hypertension program partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultrasound platform economics as semiconductor manufacturing scale drives console cost-down curves, while premium-tier pricing power accrues to vendors with FDA breakthrough designations and integrated training infrastructure.
For Market Incumbents: Hedge radiofrequency portfolio exposure by accelerating ultrasound platform R&D partnerships or licensing agreements, as interventional cardiologist preference surveys show non-thermal modalities gaining share fastest. Defend channel control through multi-year supply agreements embedding proctoring services and quality dashboards, converting transactional catheter purchasing into sticky hypertension program partnerships that raise switching costs for hospital systems. For New Entrants and Emerging Players: Portable ultrasound console miniaturization offers a technology-first wedge into ambulatory surgical center expansion in Texas and Florida, where same-day discharge protocols are gaining institutional traction fastest. Target specialized hypertension clinics in Japan's Kanto region through PMDA fast-track pathway partnerships, leveraging streamlined regulatory timelines against slower-moving diversified conglomerates. Pursue direct-to-clinic distribution models that bypass hospital value analysis committee gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among second-generation catheter developers with EU MDR technical documentation already filed but CE marking pending, as notified body backlogs create temporary discount windows. Long-term viability favors platforms with demonstrated 36-month blood pressure durability data and established post-market surveillance registries. Watch CMS national coverage determination timing as the inflection signal separating trial-enrollment valuation from commercial-procedure multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Pathway Submission | Expedited premarket review compresses time-to-reimbursement for resistant hypertension indications. |
| EU MDR CE Marking Pathway | Stricter clinical evidence standards favor incumbents with established post-market surveillance infrastructure. |
| Hospital System Partnership | Bundled proctoring and quality dashboards convert transactional purchasing into multi-year supply agreements. |
| Software Companion Development | Integrated blood pressure monitoring platforms differentiate vendor offerings in value-based care contracts. |
| Reimbursement Strategy | CMS national coverage determination alignment determines shift from trial enrollment to commercial volume. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, PMDA submission records, and hospital procurement database extracts. Bottom-up catheter shipment modeling and top-down tertiary cardiac center capacity estimates were triangulated to constrain volume forecasts.
Comparable historical reference periods anchored the projection framework across the analysis window, with segmentation modeling across energy modality, procedural setting, and end-user type dimensions. CAGRs derived from installed base expansion rates, procedure frequency assumptions, and technology substitution curves. Forecast inputs incorporated EU MDR conformity assessment timelines, CMS reimbursement determination probabilities, and PMDA fast-track pathway completion rates.
The model holds under stable regulatory approval timelines and reimbursement pathway clarity; deviation in notified body backlogs, CMS coverage determination delays, or polymer supply disruptions would shift commercial adoption trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market