
 Wearable Defibrillators Market | 2026-2036
Wearable Defibrillators Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Defibrillators Market Insights
ISO 13485 certification is rotating as the decisive qualification cycle separating established suppliers from new entrants in wearable defibrillators. ZOLL Medical Corporation leverages its emergency response heritage to dominate hospital procurement channels. Medtronic anchors its position through deep cardiac rhythm management integration. Boston Scientific Corporation specializes in miniaturized electrode systems that reduce patient burden during extended wear.
Wearable defibrillators are battery-powered, garment-integrated systems that continuously monitor cardiac electrical activity and deliver automated biphasic shocks when ventricular fibrillation or tachycardia is detected, typically operating with energy outputs between 150 and 200 joules. Their primary purpose is bridging high-risk cardiac patients from hospital discharge to definitive therapy implantation or recovery. Automated defibrillators lead volume deployment while smart devices capture emerging margin pools through algorithm-enhanced arrhythmia discrimination. Home care providers represent the fastest-growing end user channel as payers shift reimbursement toward ambulatory monitoring models.
FDA 510(k) clearance requirements govern US market entry while CE marking under the EU MDR governs European commercialization, with both frameworks intensifying clinical evidence demands for software-as-medical-device components. The country's national pharmaceutical regulator in Japan adds PMDA quality system inspections that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving software validation standards that increasingly determine competitive access rather than hardware performance alone.
Market Dynamics
The wearable defibrillators market pivots on the tension between outpatient cardiac monitoring mandates and the hardware-software integration burden imposed by evolving FDA 510(k) and EU MDR requirements. Device manufacturers face compressed development cycles as regulatory frameworks intensify clinical evidence demands for algorithm-driven arrhythmia detection systems.
Growth Catalysts
- Cardiac rehabilitation expansion:Hospital systems in the United States, Germany, and Japan are embedding wearable defibrillators into post-discharge protocols, creating institutional procurement pull.
- FDA premarket notification streamlining:Predicate device pathways for hardware iterations accelerate clearance timelines relative to novel software-as-medical-device submissions.
- Ambulatory monitoring infrastructure:Payer reimbursement shifts toward home-based cardiac surveillance models expand addressable patient populations beyond acute care settings.
Market Restraints
- Lithium-ion battery supply concentration:Cell manufacturing gravity in East Asia exposes device assemblers to raw material logistics volatility and geopolitical sourcing friction.
- Electrode gel consumable costs:Extended wear protocols require frequent electrode replacement, elevating lifetime cost-of-ownership above implantable alternatives for multi-year bridging scenarios.
- Software validation overhead:FDA algorithm lockdown requirements and EU MDR clinical performance documentation extend development timelines 18-24 months beyond hardware-only devices.
Strategic Opportunities
- Pediatric channel expansion:Underserved congenital heart defect populations in specialized US children's hospital networks present untapped volume pools.
- Remote patient monitoring convergence:Integration with cloud-based cardiac telemetry platforms enables subscription revenue models alongside device sales.
- Japanese PMDA quality system harmonization:Mutual recognition agreements between FDA and Japan's pharmaceutical regulator reduce redundant facility inspections for dual-market entrants.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time arrhythmia classification competes with consumer electronics and automotive sectors for constrained talent pools.
- Legacy EHR integration complexity:Hospital IT departments resist adding proprietary data streams from wearable devices to already fragmented cardiac informatics architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Defibrillators Market |
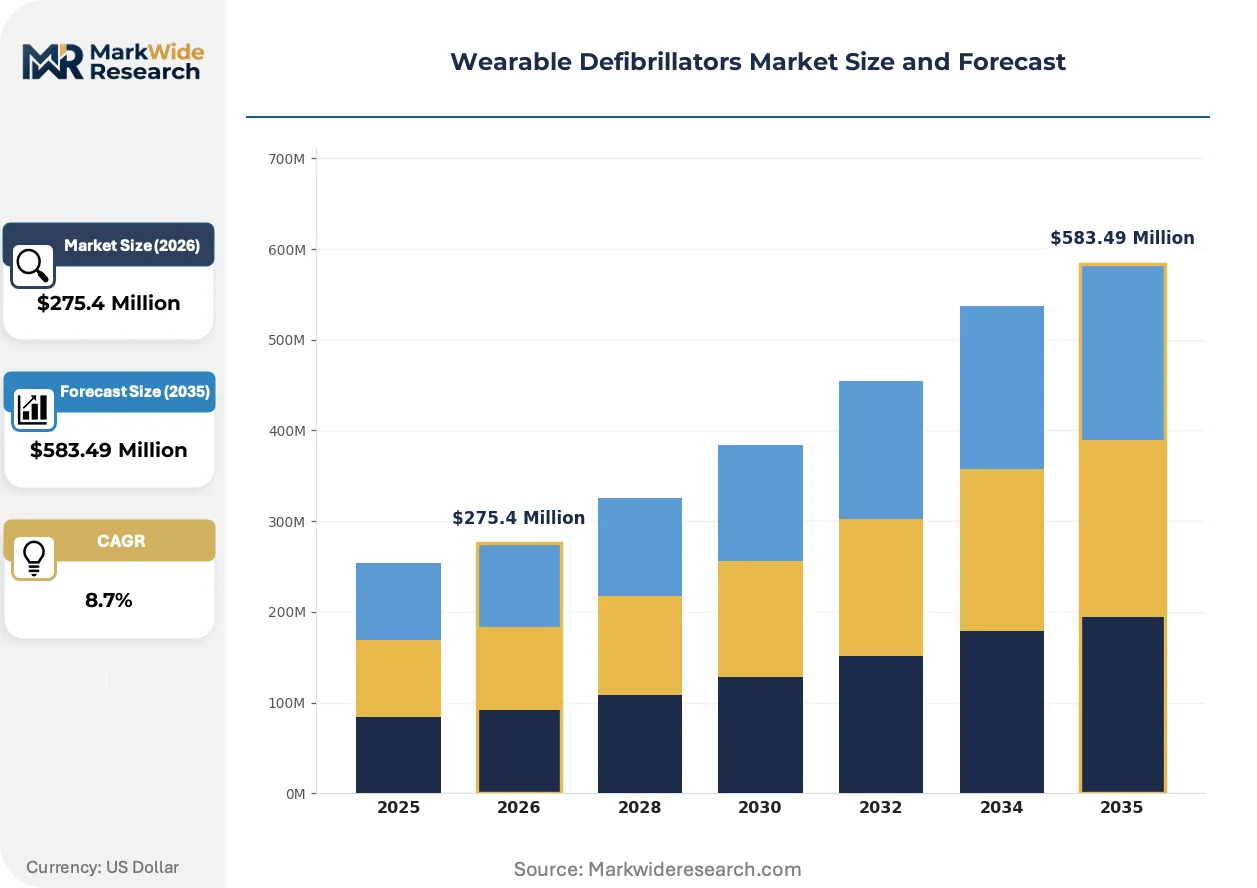
| Market Size in 2026 | $275.4 Million |
| Market Size in 2035 | $583.49 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Defibrillators, Automated Defibrillators, Wearable Monitors, Smart Devices Delivery Mode: Telehealth Solutions, Retail Distribution, Direct Sales, Online Sales End User: Hospitals, Emergency Services, Home Care Providers, Fitness Centers Technology: Bluetooth Connectivity, Wireless Communication, Cloud Integration, Mobile Application |
| Companies Covered | ZOLL Medical Corporation, Medtronic, Boston Scientific Corporation, LivaNova PLC, Konkinklijke Philips N.V., Element Science, Kestra Medical Technologies, Abbott, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Defibrillators Market Trends and Innovations
Algorithmic sophistication is compressing the gap between wearable and implantable therapeutic decision-making, while regulatory frameworks race to capture software iteration cycles within traditional hardware approval pathways.
Flexible dry electrode arrays are replacing hydrogel-based sensing systems in next-generation garment designs. Cardiac rehabilitation centers in Germany are piloting these configurations to reduce skin irritation during 90-day wear protocols. The technology is miniaturizing power and sensing electronics into textile-integrated form factors that approach consumer apparel comfort thresholds.
EU MDR clinical evidence requirements for software-as-medical-device components now mandate post-market performance surveillance comparable to implantable hardware. Boston Scientific and Medtronic have restructured European regulatory affairs teams to maintain continuous clinical data collection obligations. Small and mid-cap entrants lacking EU notified body relationships face exclusion from the continent's hospital procurement channels.
Home care providers are consolidating purchasing authority previously dispersed across individual cardiologist practices. United States durable medical equipment suppliers now negotiate enterprise contracts with national health systems for fleet deployments spanning multiple cardiac service lines. This concentration shifts price leverage toward buyers capable of standardizing device brands across outpatient networks.
Wearable Defibrillators Market Segmentation
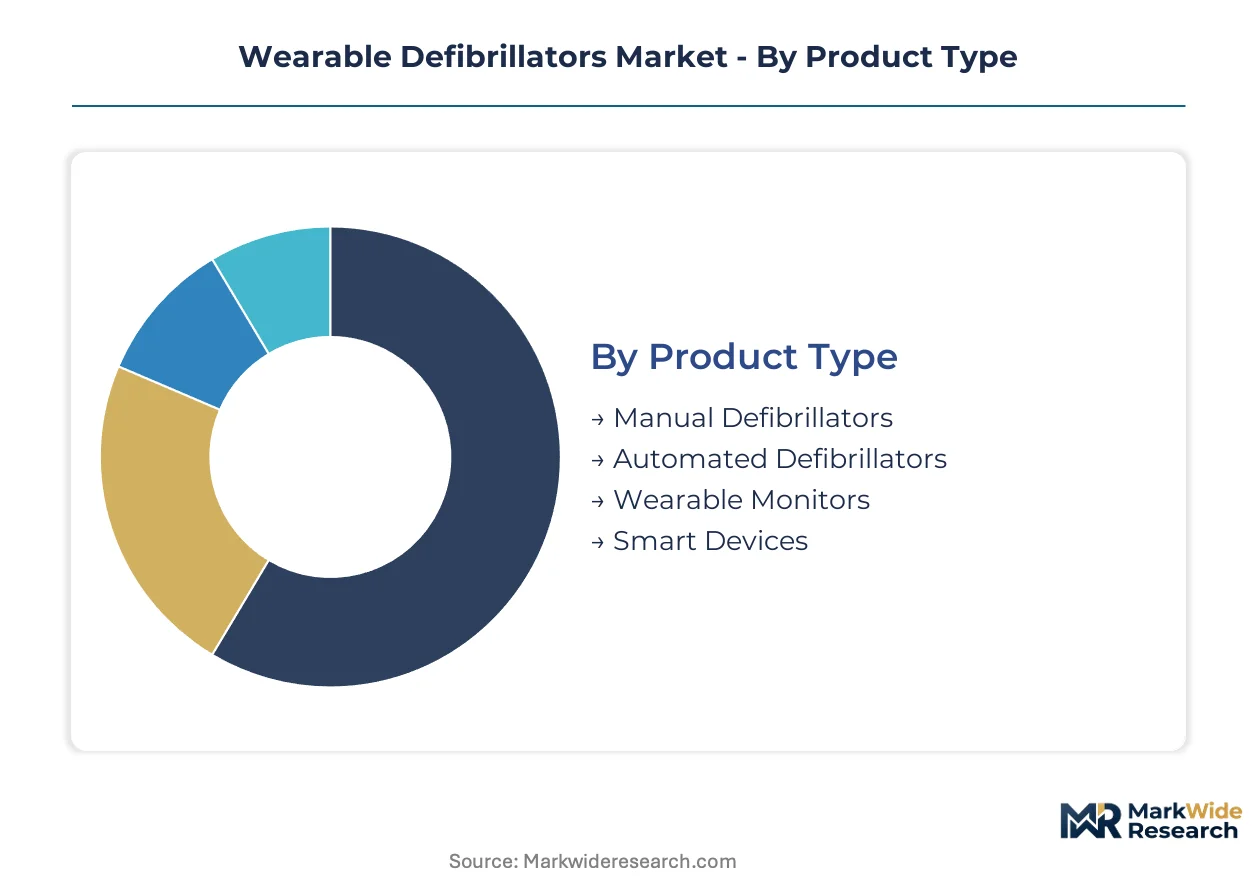
Wearable defibrillator segmentation reveals how device sophistication, distribution economics, and care setting migration reshape procurement patterns. Each dimension carries distinct margin profiles and regulatory burdens that determine competitive positioning across cardiac monitoring value chains.
Product Type:
Automated systems face the strongest substitution pressure from implantable cardioverter-defibrillators as bridging periods shorten and surgical risk profiles improve.
- Automated Defibrillators:Biphasic shock delivery systems operate at 150-200 joules with algorithm-driven arrhythmia detection. Hospital systems in the United States embed these into post-discharge protocols for high-risk cardiac patients awaiting definitive therapy. FDA 510(k) predicate pathways accelerate hardware iterations but software lockdown requirements extend validation cycles.
- Smart Devices:Algorithm-enhanced systems with machine learning-based arrhythmia discrimination capture emerging margin pools through subscription telemetry models. Germany's cardiac rehabilitation centers pilot these configurations for 90-day wear protocols with cloud-connected monitoring. EU MDR clinical evidence demands for software-as-medical-device components intensify post-market surveillance obligations.
- Manual Defibrillators:Clinician-operated units retain presence in emergency medical service fleets requiring direct control over shock timing and energy selection.
- Wearable Monitors:Diagnostic-only garments without therapeutic capability serve lower-risk populations in fitness and wellness applications.
Automated Defibrillators retain volume leadership; Smart Devices hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates enterprise procurement contracts from individual patient acquisition channels.
- Direct Sales:Manufacturer field forces negotiate fleet deployments with national health systems and durable medical equipment suppliers. United States hospital networks consolidate purchasing authority across multiple cardiac service lines, shifting price leverage toward standardized brand selection.
- Telehealth Solutions:Remote patient monitoring platforms bundle device provision with continuous telemetry subscription services. Japan's expanding outpatient monitoring infrastructure creates procurement pull through integrated cardiac surveillance contracts. PMDA quality system inspections extend approval timelines for foreign manufacturers entering this channel.
- Retail Distribution:Pharmacy and medical supply store networks serve individual patients with prescription-based device fulfillment.
- Online Sales:Direct-to-patient e-commerce channels bypass traditional durable medical equipment intermediaries for established users requiring electrode replacements or device upgrades.
Direct Sales commands the premium tier; Telehealth Solutions is climbing the fastest.
End User:
Customer type migration from acute care to ambulatory settings reconfigures service and support requirements.
- Home Care Providers:Durable medical equipment suppliers and visiting nurse organizations manage device deployment for post-discharge cardiac patients. Payer reimbursement shifts toward home-based surveillance models in the United States expand addressable populations beyond traditional hospital boundaries. Electrode gel consumable costs elevate lifetime ownership calculations for multi-year bridging scenarios.
- Hospitals:Cardiac rehabilitation programs and electrophysiology departments anchor institutional procurement with embedded device protocols. Germany's hospital systems integrate wearable defibrillators into structured post-infarction recovery pathways.
- Emergency Services:Ambulance and first responder fleets require ruggedized designs with rapid deployment characteristics for pre-hospital cardiac events.
- Fitness Centers:Corporate wellness programs and athletic facilities adopt diagnostic monitoring variants for liability mitigation in high-exertion environments.
Hospitals maintain installed base dominance; Home Care Providers is gaining share fastest.
Technology:
Supply concentration in embedded systems engineering constrains development velocity for connectivity-integrated platforms.
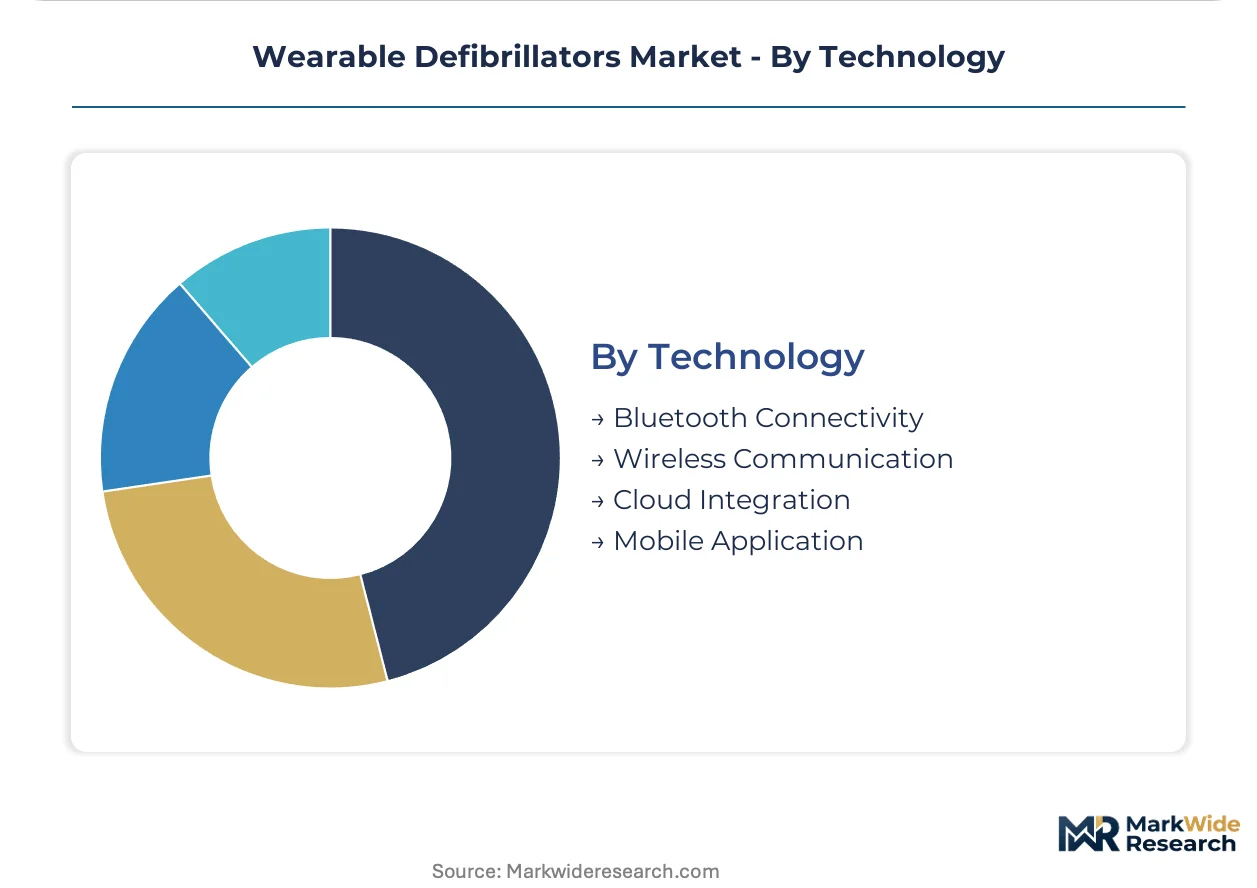
- Cloud Integration:Real-time data streaming to centralized cardiac telemetry platforms enables algorithm refinement and population-level outcome analysis. EU MDR mandates post-market performance surveillance comparable to implantable hardware. Boston Scientific and Medtronic have restructured European regulatory affairs teams to maintain continuous clinical data collection obligations.
- Wireless Communication:Cellular and proprietary radio protocols transmit arrhythmia alerts to monitoring centers without patient smartphone dependency. Japan's PMDA quality system inspections scrutinize foreign manufacturer cybersecurity documentation for network-connected devices.
- Bluetooth Connectivity:Short-range pairing with patient smartphones supports consumer-app interfaces for device status and event logging.
- Mobile Application:Software interfaces for patient engagement and caregiver notification face FDA 510(k) scrutiny as software-as-medical-device components.
Cloud Integration anchors the premium tier; Wireless Communication shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts toward ambulatory cardiac monitoring are accelerating wearable defibrillator deployment across hospital systems in the United States, Germany, and Japan. National regulators in each market impose distinct quality system requirements that shape manufacturer entry timelines. Industrial clusters in cardiac device manufacturing concentrate procurement relationships with specialized component suppliers.
United States
Hospital systems embed wearable defibrillators into post-discharge protocols for high-risk cardiac patients awaiting definitive therapy. FDA 510(k) premarket notification requirements govern clearance timelines for hardware iterations and software-as-medical-device components. The Minneapolis-St. Paul corridor anchors cardiac rhythm management device manufacturing with integrated supply chains for electrode arrays and battery systems.
Germany
Cardiac rehabilitation centers pilot flexible dry electrode configurations to reduce skin irritation during extended 90-day wear protocols. EU MDR clinical evidence mandates intensify post-market surveillance obligations for algorithm-driven arrhythmia detection systems. The Baden-Württemberg region concentrates medical technology manufacturing with specialized textile-integrated electronics capabilities.
Japan
Expanding outpatient monitoring infrastructure creates procurement pull through integrated cardiac surveillance contracts with home care providers. PMDA quality system inspections extend approval timelines for foreign manufacturers seeking market entry. The Tokyo-Osaka corridor hosts cardiac device distribution networks serving regional hospital systems.
United Kingdom
National Health Service cardiac rehabilitation programs drive institutional adoption of wearable monitoring solutions for post-infarction recovery pathways. CE marking under EU MDR governs commercialization with intensified clinical performance documentation requirements. The Oxford-Cambridge arc concentrates medical device regulatory affairs expertise serving European market access strategies.
Switzerland
Specialized cardiac centers in Zurich and Geneva integrate wearable defibrillators into bridging therapy protocols for transplant-eligible patients. Swissmedic quality system requirements align with EU MDR standards while maintaining distinct inspection protocols for foreign manufacturers. The Basel region anchors pharmaceutical and medical technology clusters with cross-border supply relationships into German and French hospital networks.
Wearable Defibrillators Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and cardiac rhythm management integration depth. The vendor base concentrates around emergency response heritage, deep implantable device portfolios, and miniaturized electrode system specializations. Three archetypes dominate: diversified cardiac rhythm management conglomerates, emergency medical device specialists, and emerging technology innovators focused on algorithm-enhanced monitoring. Competitive positioning hinges on M&A activity to acquire software validation capabilities and strategic partnerships with cloud-based telemetry platforms.
Within the diversified cardiac rhythm management tier, Medtronic anchors market positioning through deep integration with implantable cardioverter-defibrillator portfolios, while Boston Scientific Corporation exemplifies miniaturization specialization. ZOLL Medical Corporation represents the emergency response heritage archetype with dominant hospital procurement channel relationships. Among emerging technology innovators, Element Science and Kestra Medical Technologies occupy positions focused on next-generation garment-integrated form factors and algorithm-enhanced arrhythmia discrimination.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| Medtronic |
| Boston Scientific Corporation |
| LivaNova PLC |
| Konkinklijke Philips N.V. |
| Element Science |
| Kestra Medical Technologies |
| Abbott |
| Nihon Kohden Corporation |
| Others |
Pricing and Supply Chain Analysis
Component scale economies in lithium-ion cell manufacturing anchor price floors for wearable defibrillator assemblers, concentrating bargaining power with East Asian battery suppliers while compressing margins for garment-integrated electronics producers in the United States and Germany. FDA 510(k) validation cycles and EU MDR clinical evidence requirements layer fixed compliance costs that resist volume-driven unit cost reductions, creating asymmetric pricing power between established ISO 13485-certified suppliers and new entrants facing 18-24 month approval timelines.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread across pricing tiers, with predicate-cleared automated defibrillators commanding premium positioning against algorithm-enhanced smart devices in subscription telemetry models. Three-tier pricing structure across premium, standard, and economy levels separates enterprise fleet contracts from individual patient acquisition channels, with home care providers exhibiting highest price sensitivity due to electrode gel consumable cost accumulation over multi-year bridging protocols. Cost compression in the standard tier is intensifying because hospital procurement consolidation shifts volume leverage toward national health systems capable of standardizing brands across cardiac service lines.
Supply Chain Analysis
Inventory lead times for specialized cardiac electrodes and textile-integrated sensing arrays extend 12-16 weeks, constraining just-in-time assembly for garment-based form factors. Manufacturing gravity centers on China for lithium-ion cells, South Korea for advanced battery management systems, and Germany for precision textile electronics, with raw material dependencies spanning lithium carbonate, conductive polymers, and medical-grade hydrogels. Single-source vulnerability in East Asian cell production exposes device assemblers to geopolitical sourcing friction and logistics chokepoint risk. Distribution runs through durable medical equipment suppliers consolidating purchasing authority previously dispersed across individual cardiologist practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) predicate pathways and EU MDR notified body relationships create switching costs that defend incumbent positions against algorithm-focused challengers. Network effects in cloud-integrated telemetry platforms further deepen competitive moats for established cardiac rhythm management conglomerates.
For Market Incumbents: Shield market position by acquiring software validation capabilities to compress algorithm-driven arrhythmia detection development cycles, and deepen backward integration into electrode array manufacturing to capture consumable revenue streams threatened by dry electrode substitution. Priority lever rests on consolidating hospital procurement channel relationships before home care provider purchasing authority fully concentrates. For New Entrants and Emerging Players: Remote patient monitoring service-layer gaps in pediatric congenital heart defect populations present white-space targets underserved by incumbent algorithm portfolios. Telehealth-integrated cardiac surveillance contracts in Japan's expanding outpatient infrastructure offer the most penetrable geography for foreign manufacturers with PMDA quality system readiness. Go-to-market angle should emphasize cloud-native platform architecture bypassing legacy EHR integration complexity that hospital IT departments resist. For Investors and Strategic Acquirers: Algorithm-specialist mid-cap developers with FDA breakthrough device designation progress represent the acquisition target archetype most likely to command strategic premium. Long-term viability across the analysis window hinges on software-as-medical-device regulatory trajectory outpacing hardware commoditization. Signal to watch: mutual recognition agreement momentum between FDA and Japan's pharmaceutical regulator reducing redundant facility inspection burdens for dual-market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathways accelerate clearance timelines relative to novel software-as-medical-device submissions. |
| CE Marking Pathway | EU MDR clinical evidence mandates intensify post-market surveillance obligations for algorithm-driven systems. |
| Hospital System Partnership | Enterprise fleet deployments spanning multiple cardiac service lines consolidate purchasing authority toward standardized brands. |
| Software Companion Development | FDA algorithm lockdown requirements extend validation cycles 18-24 months beyond hardware-only devices. |
| Reimbursement Strategy | Payer shifts toward home-based ambulatory monitoring models expand addressable patient populations beyond acute care. |
Research Methodology
Cross-validation between primary interviews with cardiac electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up demand modeling triangulates against top-down market sizing across product type, delivery mode, end user, and technology segmentation dimensions.
Sensitivity analysis frames volume and value outputs across the projection horizon, with analytical framework approach modeling device shipment trajectories, electrode consumable replacement cycles, and telemetry subscription attach rates. Segmentation dimensions span automated versus smart device architectures, direct sales versus telehealth distribution channels, hospital versus home care provider end users, and cloud-integrated versus wireless communication technology tiers. CAGRs derive from regression analysis against cardiac rehabilitation program expansion rates and outpatient monitoring infrastructure investment flows.
Underlying assumptions cover regulatory approval timeline stability, lithium-ion supply chain continuity, and reimbursement policy trajectory toward ambulatory surveillance models, with deviation risk concentrated in FDA software validation standard evolution and geopolitical friction in East Asian battery component sourcing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Asia-Pacific Breast Biopsy Market