
 Global Cannabis Testing Market | 2026-2036
Global Cannabis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cannabis Testing Market Foresight
The shift from single-source to multi-source laboratory outsourcing is expanding across North American cannabis supply chains. Agilent Technologies leverages its chromatography portfolio to anchor instrument sales in state-mandated compliance labs. Shimadzu Corporation sustains competitive positioning through dedicated cannabis analytical workflows. Thermo Fisher Scientific dominates mass spectrometry placements among third-party testing facilities seeking ISO 17025 accreditation.
Cannabis testing comprises analytical protocols that quantify cannabinoid potency, detect residual pesticides, and screen for microbial contaminants using high-performance liquid chromatography with UV detection at 220 nm and mass-selective detection. These procedures ensure consumer safety and regulatory compliance before product release to dispensary channels. Chromatography methods occupy the largest installed base due to their versatility across potency and contaminant applications, while mass spectrometry segments attract premium instrument spending from laboratories pursuing lowest detection limits. The flower sample type generates the highest testing volume, though concentrates and extracts segments command elevated per-sample pricing reflecting complex matrix preparation requirements.
The FDA, EPA, and state-level regulators including Colorado's Marijuana Enforcement Division shape demand through evolving potency-labeling accuracy requirements and pesticide action limits. ISO 17025 accreditation has become a de facto market-access threshold for laboratories serving licensed cultivators and product manufacturers. Stakeholders must monitor harmonization gaps between state testing mandates and emerging federal frameworks to anticipate method-transfer investments and compliance restructuring needs.
Market Dynamics
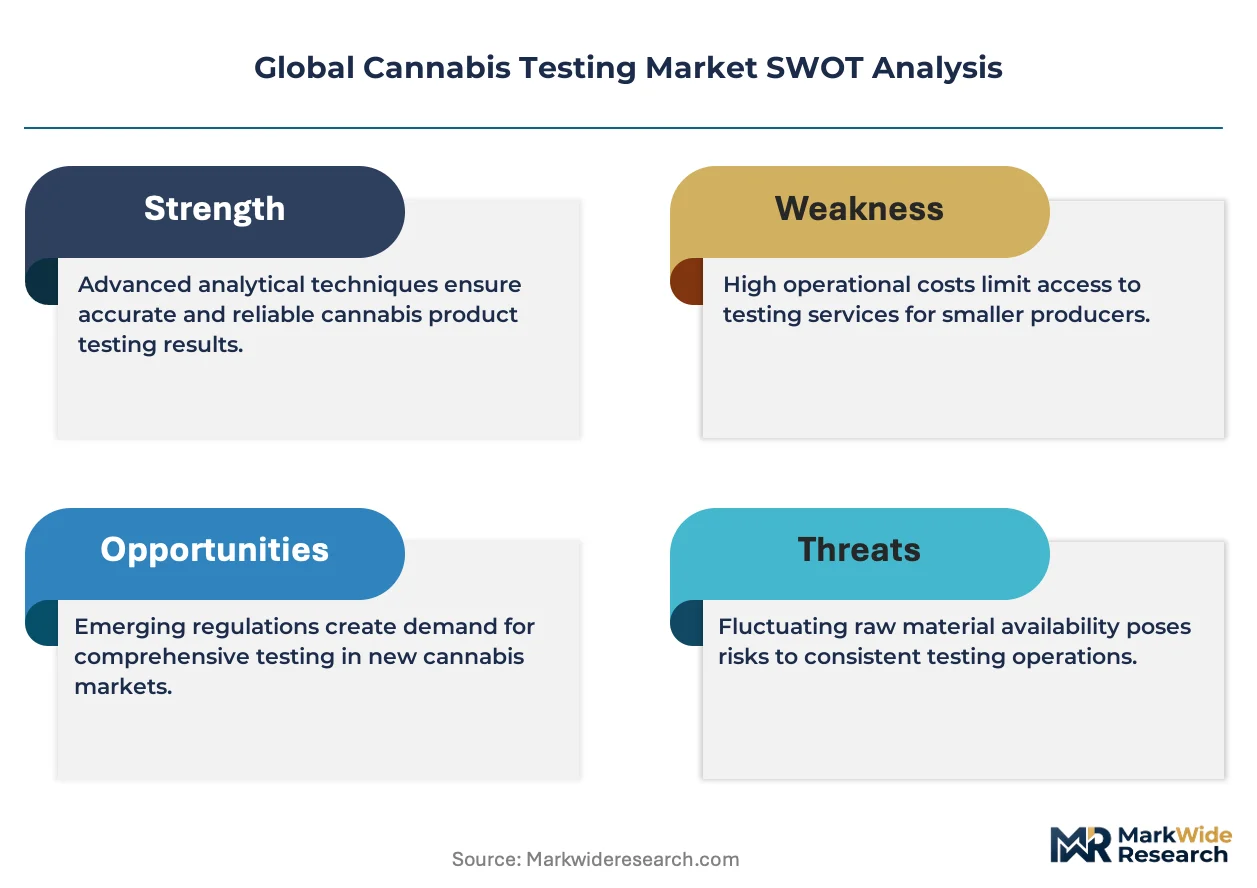
The transition from state-fragmented testing mandates toward harmonized analytical standards is compressing method-development cycles and forcing laboratory consolidation across jurisdictions with divergent pesticide action limits and potency-labeling requirements.
Growth Catalysts
- ISO 17025 Accreditation Mandates:Germany's national accreditation body now requires third-party validation for all potency claims on pharmaceutical-grade cannabis products, expanding outsourcing demand from domestic cultivators.
- California:The state's Bureau of Cannabis Control mandates comprehensive contaminant screening for all batches entering dispensary channels, sustaining high-throughput laboratory utilization in the Central Valley cluster.
- High-Resolution Mass Spectrometry:Detection sensitivity improvements for residual pesticides are enabling laboratories to meet tightening action limits without method redevelopment.
Market Restraints
- Reference Material Scarcity:Certified cannabinoid reference standards for novel acid forms remain concentrated with single-source suppliers in Switzerland, creating input cost volatility.
- Technical Limitation:Matrix interference from chlorophyll and lipids in raw flower samples degrades quantitative accuracy for HPLC-UV potency methods, requiring labor-intensive sample prep.
- Regulatory Friction:Colorado's Marijuana Enforcement Division maintains pesticide testing lists that diverge from EPA tolerance databases, forcing multi-state operators to maintain parallel method portfolios.
Strategic Opportunities
- Brazil:ANVISA's expanded medical cannabis framework creates first-mover positioning for laboratories offering stability testing and shelf-life validation services.
- On-Site Portable Spectroscopy:Handheld Raman devices are converging with cloud-based spectral libraries to enable cultivator-led pre-harvest potency screening.
- EU Green Deal Alignment:Sustainability reporting requirements under CSRD are creating demand for carbon-footprint validation of laboratory operations serving ESG-conscious cultivators.
Industry Challenges
- Analytical Chemist Shortage:Specialized expertise in mass spectrometry method development for complex cannabis matrices remains scarce in secondary US markets.
- ISO 17025 Certification Timelines:Accreditation body backlogs in Canada extend laboratory readiness timelines by eight to fourteen months.
- Legacy LIMS Integration:Cannabis-specific data integrity requirements conflict with validated laboratory information management systems deployed in adjacent pharmaceutical operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cannabis Testing Market |
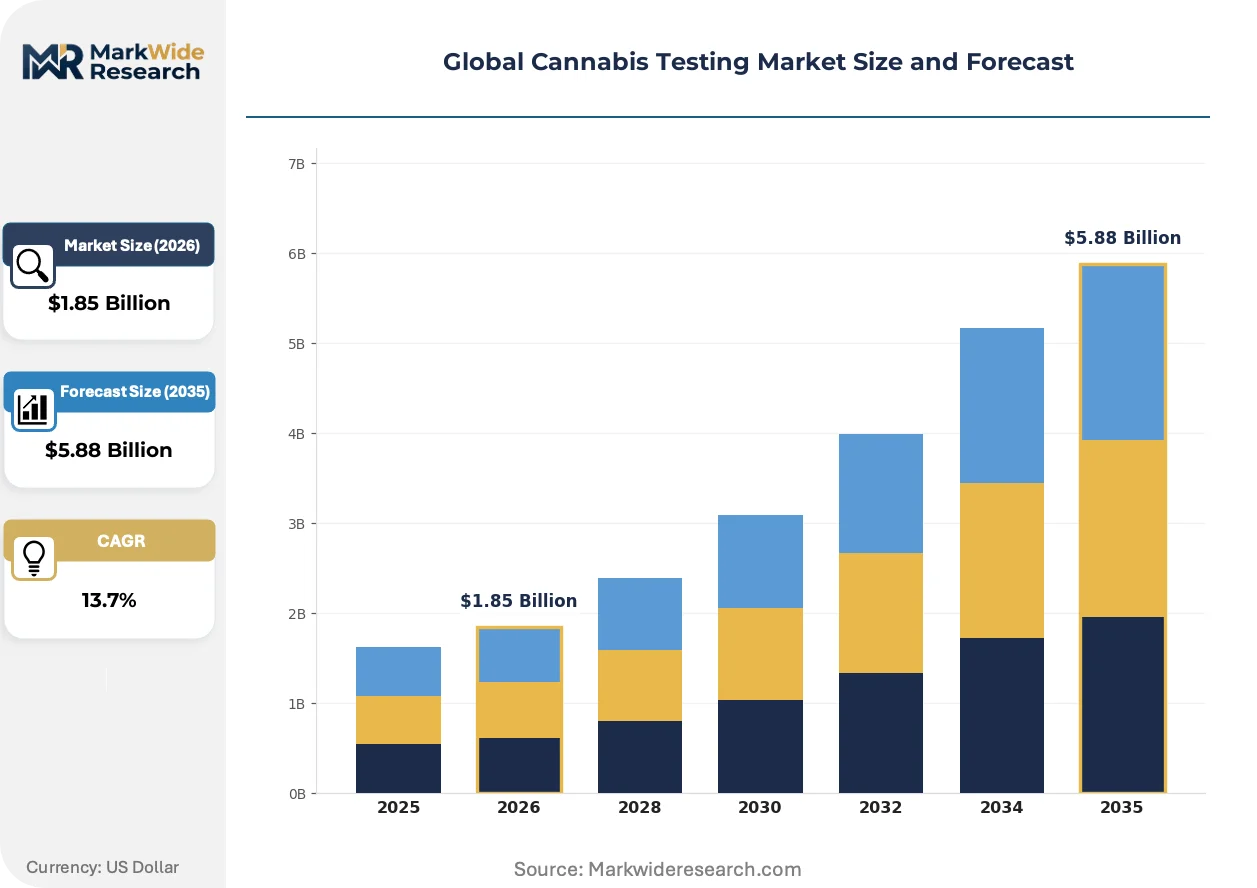
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Chromatography, Spectroscopy, Microscopy, Molecular Analysis, Mass Spectrometry, Microbiological Assay Sample Type: Flower, Concentrates, Edibles, Topicals, Seeds, Extracts End User: Laboratories, Quality Assurance Firms, Research Institutes, Regulatory Bodies Application: Potency Analysis, Contaminant Screening, Terpene Profiling, Pesticide Detection, Residual Solvent Testing |
| Companies Covered | Agilent Technologies Inc., Shimadzu Corporation, MERCK KGAA, Thermo Fisher Scientific, PerkinElmer Inc., Danaher Corporation, Restek Corporation, SC Laboratories Inc., Steep Hill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cannabis Testing Market Shifts & Advancements
Automation of sample preparation workflows and the convergence of chromatography with artificial intelligence-driven peak identification are compressing turnaround times while elevating data integrity standards across compliance laboratories.
Ultra-high-performance liquid chromatography paired with photodiode array detection is expanding into terpene profiling applications beyond traditional potency quantification. Vertically integrated cultivators in California's Central Valley are adopting these systems for in-house batch release. This capability expansion is compressing the addressable market for standalone terpene testing services previously outsourced to specialized laboratories.
REACH-aligned substance restrictions in the European Union are forcing laboratories to eliminate acetonitrile-based mobile phases in favor of greener alternatives. Industrial consequence includes accelerated method revalidation timelines and instrument reconfiguration costs. Testing facilities serving German pharmaceutical exporters are most affected, responding through collaborative solvent substitution studies with instrument manufacturers.
Buyer consolidation among multi-state operators is displacing fragmented single-laboratory contracts with centralized master service agreements spanning multiple jurisdictions. Distributor-owned testing facilities in California and Colorado are losing share to national third-party networks. This pattern is most visible among publicly traded cultivators seeking audit uniformity across state portfolios.
Global Cannabis Testing Market Segmentation
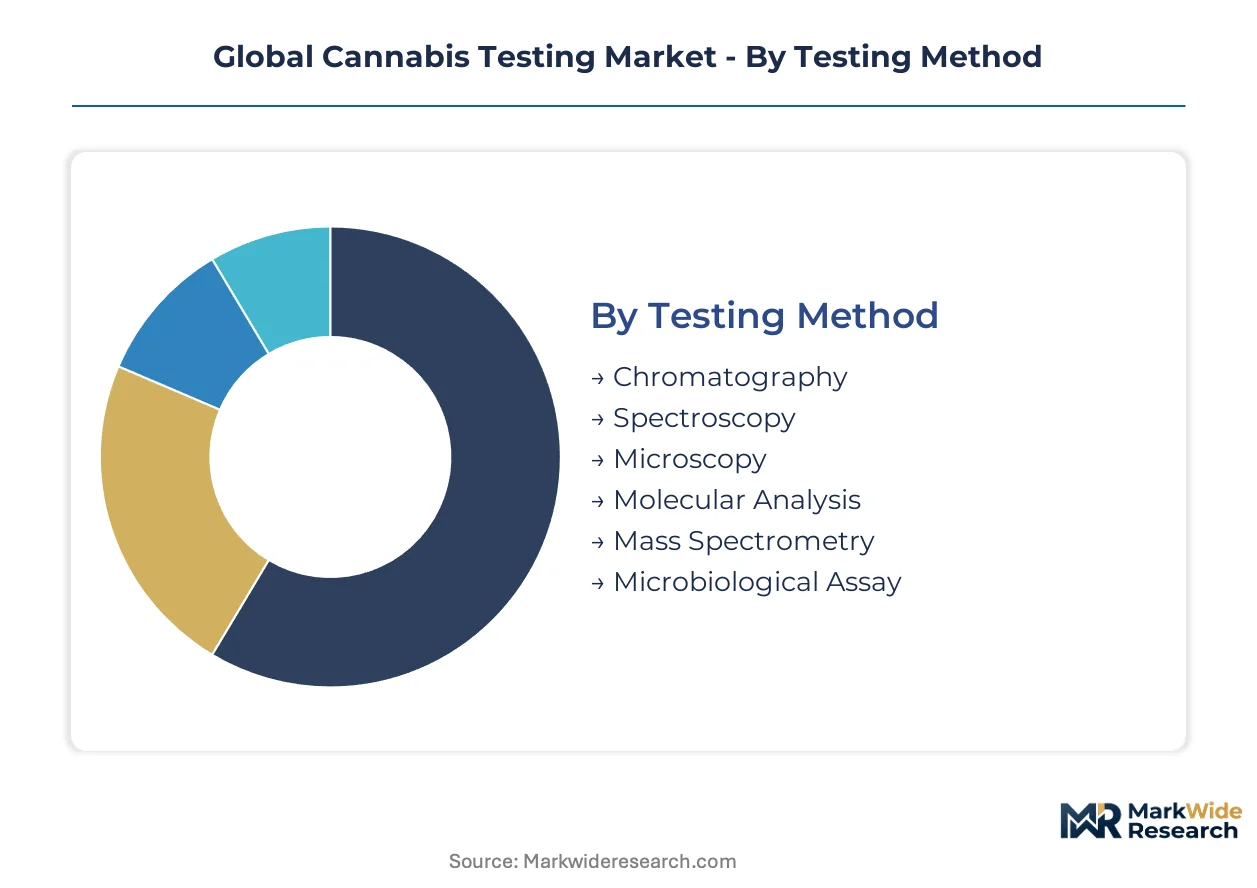
Cannabis testing segmentation reveals how buyer priorities diverge across compliance mandates, sample complexity, and analytical precision requirements. Laboratories configure instrument portfolios differently depending on whether their core customers seek routine potency verification or comprehensive contaminant screening for pharmaceutical-grade exports.
Testing Method:
Instrument selection hinges on detection limit requirements and method transfer flexibility across state and national regulatory frameworks.
- Chromatography:High-performance liquid chromatography with UV detection anchors potency quantification workflows due to its versatility across cannabinoid acid forms and neutral compounds. California's Central Valley cultivators deploy these systems for in-house batch release testing to meet Bureau of Cannabis Control mandates.
- Mass Spectrometry:Triple-quadrupole and high-resolution mass spectrometry platforms deliver sub-ppb pesticide detection limits required by Germany's pharmaceutical-grade cannabis regulations. Third-party facilities pursuing ISO 17025 accreditation prioritize these instruments despite premium capital costs.
- Spectroscopy:UV-Vis and infrared methods support rapid screening applications where quantitative precision is secondary to throughput speed.
- Microscopy:Optical and electron microscopy techniques identify physical contaminants and structural abnormalities in raw flower samples.
- Molecular Analysis:PCR-based methods detect genetic markers for strain verification and pathogen identification at the DNA level.
- Microbiological Assay:Culture-based and rapid ATP bioluminescence methods screen for bacterial and fungal contamination in consumable products.
Volume sits with Chromatography; growth tilts toward Mass Spectrometry.
Sample Type:
Matrix complexity determines preparation labor intensity and per-sample pricing tiers across testing service portfolios.
- Flower:Raw plant material generates the highest testing volume due to mandatory pre-distribution screening requirements. Chlorophyll and lipid interference degrades HPLC-UV accuracy, forcing labor-intensive sample prep protocols in high-throughput California laboratories.
- Extracts:Concentrated cannabinoid matrices command elevated per-sample pricing reflecting complex dilution and solvent compatibility verification. German pharmaceutical exporters require comprehensive residual solvent testing for ethanol and hydrocarbon extraction methods.
- Concentrates:High-potency products demand specialized calibration curves and matrix-matched reference standards for accurate quantification.
- Edibles:Food-matrix interference necessitates additional cleanup steps for lipid-soluble cannabinoid recovery.
- Topicals:Cream and lotion bases require modified extraction protocols to release active compounds from emulsion matrices.
- Seeds:Genetic purity and viability testing supports breeding program quality control with lower regulatory mandate penetration.
Revenue concentrates in Flower testing; margin expansion tracks Extracts.
End User:
Customer type dictates service level expectations, accreditation requirements, and contract structure preferences.
- Laboratories:Independent and captive testing facilities purchase instruments, consumables, and reference standards to maintain ISO 17025 compliance. California's vertically integrated cultivators operate captive laboratories to control batch-release timelines.
- Quality Assurance Firms:Third-party auditors validate laboratory performance and documentation integrity for multi-state operators seeking portfolio uniformity.
- Research Institutes:Academic and government laboratories pursue novel method development for emerging cannabinoid acid forms and minor terpene quantification.
- Regulatory Bodies:State enforcement divisions and national agencies contract proficiency testing and reference material production to harmonize analytical standards.
Instrument demand flows through Laboratories; outsourcing growth favors Quality Assurance Firms.
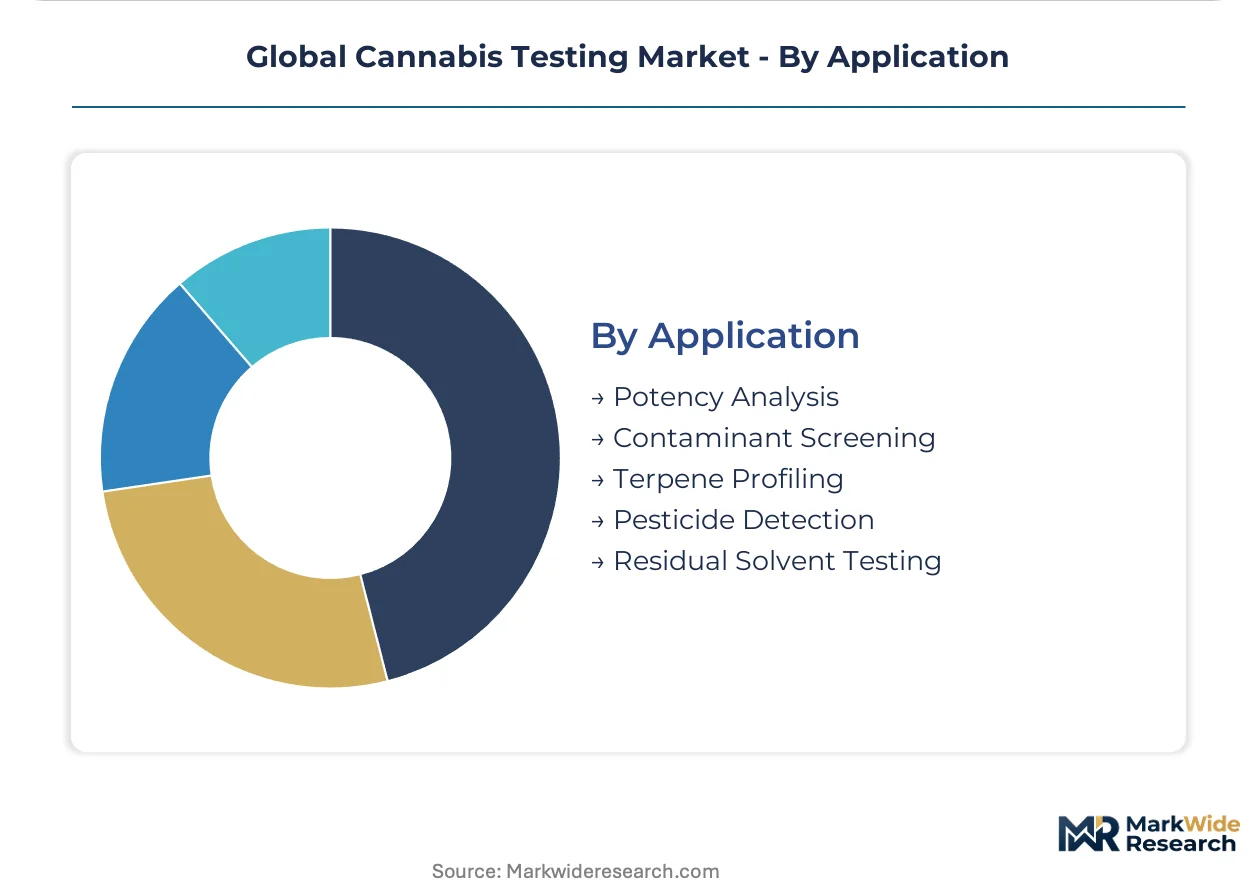
Application:
Regulatory mandate intensity varies by application, shaping laboratory capability investments and pricing power.
- Potency Analysis:Quantification of THC, CBD, and minor cannabinoids represents the baseline compliance requirement across all legal jurisdictions. Germany's national accreditation body now mandates third-party validation for all potency claims on pharmaceutical products.
- Contaminant Screening:Microbial, heavy metal, and mycotoxin detection protects consumer safety with action limits tightening in California and Colorado. Multi-state operators maintain parallel method portfolios where state pesticide lists diverge from EPA tolerance databases.
- Terpene Profiling:Volatile compound characterization supports product differentiation and strain authentication beyond baseline compliance.
- Pesticide Detection:Residual agrochemical screening faces harmonization gaps between state mandates and emerging federal frameworks.
- Residual Solvent Testing:Hydrocarbon and alcohol quantification applies primarily to extracted and concentrated product categories.
Testing volume clusters in Potency Analysis; capability differentiation centers on Contaminant Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley cultivators anchor the geographic concentration of cannabis testing demand, with vertically integrated operations driving captive laboratory investments. Germany's pharmaceutical-grade cannabis exporters generate premium instrument demand through ISO 17025 mandates. Brazil's emerging medical framework creates new accreditation requirements across South America.
United States
California's Bureau of Cannabis Control mandates comprehensive batch-release testing for all products entering dispensary channels. The FDA's 2023 guidance on cannabinoid analytical methods tightened validation requirements for commercial test kits nationwide. The Central Valley cluster hosts the densest concentration of vertically integrated cultivators operating captive laboratories to control release timelines.
Germany
Pharmaceutical laboratories now outsource potency validation to accredited third-party facilities serving medical cannabis exporters. The national accreditation body requires third-party validation for all potency claims on pharmaceutical-grade products. Industrial laboratories in Baden-Württemberg and Bavaria dominate high-resolution mass spectrometry placements for residual pesticide detection.
Canada
Health Canada and PMRA harmonization efforts are compressing method-development cycles for multi-jurisdictional operators. ISO 17025 accreditation body backlogs extend laboratory readiness timelines by eight to fourteen months in Ontario and British Columbia. Toronto and Vancouver host the primary clusters of third-party testing facilities serving licensed producers.
Brazil
ANVISA's expanded medical cannabis framework creates first-mover positioning for laboratories offering stability testing and shelf-life validation services. The national pharmaceutical regulator mandates GMP-aligned analytical protocols for imported medical cannabis products. São Paulo anchors the emerging laboratory infrastructure serving southeast Brazilian cultivators and importers.
Switzerland
Certified cannabinoid reference standards for novel acid forms remain concentrated with single-source suppliers creating input cost volatility across European markets. Swissmedic maintains stringent quality requirements for analytical reagents used in pharmaceutical-grade cannabis testing. Basel and Zurich host the primary reference material production facilities serving German and Austrian laboratories.
Global Cannabis Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument manufacturers align with accredited testing facilities to secure placement contracts. The vendor base separates into three tiers: diversified analytical conglomerates, specialized cannabis workflow providers, and regional service laboratories. Two archetypes define competitive positioning: chromatography-heavy instrument suppliers leveraging compliance mandates, and testing service networks pursuing multi-state accreditation coverage. M&A activity and ISO 17025 certification racing constitute the dominant competitive moves reshaping market structure.
Among diversified analytical conglomerates, Agilent Technologies Inc., Thermo Fisher Scientific, and Shimadzu Corporation exemplify the instrument-supplier archetype anchoring state-mandated compliance laboratory placements. These entities occupy positions spanning chromatography and mass spectrometry portfolios without cannabis-exclusive specialization. Their competitive stance derives from cross-industry method validation expertise transferable to emerging regulatory frameworks.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| Shimadzu Corporation |
| MERCK KGAA |
| Thermo Fisher Scientific |
| PerkinElmer Inc. |
| Danaher Corporation |
| Restek Corporation |
| SC Laboratories Inc. |
| Steep Hill Inc. |
| Others |
Supply & Pricing Matrix
Certified cannabinoid reference standards from Switzerland flow downstream through tiered pricing structures that separate pharmaceutical-grade ISO 17025-accredited laboratories from routine compliance testing facilities. Input cost volatility for novel acid forms propagates through per-sample pricing, with German pharmaceutical exporters absorbing premium tiers while California cultivators negotiate volume-based standard-tier contracts.
Pricing Analysis
Service bundling separates instrument manufacturers offering validation-inclusive packages from unbundled equipment vendors charging separately for method transfer and compliance documentation. Three-tier pricing structure across premium, standard, and economy levels tracks accreditation status, with ISO 17025-certified facilities commanding 40-60% markups over uncertified competitors. Cost compression in the standard tier is intensifying because multi-state operators consolidate testing contracts under master service agreements. Small independent laboratories in secondary US markets exhibit highest price sensitivity, while German pharmaceutical exporters demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Freight costs for temperature-controlled reference material shipments from Switzerland to German laboratories add 8-12% to input costs, with customs clearance complexity extending lead times. Supply concentrates in Switzerland for certified standards, the United States for chromatography instrumentation, and Germany for pharmaceutical-grade testing services. The supply chain draws from single-source dependencies for novel cannabinoid acid reference materials, high-purity solvent producers in the Netherlands, and precision optics manufacturers in Japan. Single-source vulnerability for Swiss reference standards creates systemic price risk. Distribution runs through direct instrument manufacturer relationships for large laboratories, regional distributors for mid-tier facilities, and group purchasing organizations for multi-state operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accreditation body processing capacity constraints in Canada and Germany prop pricing power for existing ISO 17025-certified facilities, creating a supply-constrained market structure that favors incumbents with established compliance infrastructure.
For Market Incumbents: Extend accreditation coverage across multiple jurisdictions before harmonization compresses regional differentiation advantages. Consolidate reference material supply agreements with Swiss suppliers to lock in pricing before further concentration. Defend against portable spectroscopy disruptors by embedding cloud-based data integrity features that handheld devices cannot replicate. Prioritize capacity expansion in Brazil ahead of ANVISA laboratory infrastructure maturation. For New Entrants and Emerging Players: National third-party testing networks offer the most penetrable channel partner type for circumventing incumbent distributor relationships in California and Colorado. Target stability testing and shelf-life validation services in Brazil where first-mover positioning remains available. Pursue on-site portable spectroscopy deployment for cultivator-led pre-harvest screening as the go-to-market angle, leveraging cloud-based spectral libraries to bypass capital-intensive laboratory infrastructure. For Investors and Strategic Acquirers: ISO 17025 accreditation body backlog reduction in Canada is the leading indicator that laboratory readiness timelines will compress, shifting competitive advantage from certification speed to operational scale. Frame long-term viability around consolidation of fragmented state-level testing mandates into harmonized federal frameworks. Target acquisition archetypes: mid-cap laboratories with existing multi-state accreditation coverage and proprietary LIMS platforms compatible with cannabis-specific data integrity requirements. Watch for FDA guidance harmonization with state testing mandates as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Multi-Jurisdiction Accreditation | Enables laboratories to serve multi-state operators under unified audit standards. |
| Reference Material Supply Agreement | Locks in pricing with Swiss suppliers against input cost volatility. |
| Portable Spectroscopy Platform Launch | Displaces centralized laboratory testing for cultivator-led pre-harvest screening. |
| LIMS Cannabis-Specific Integration | Resolves data integrity conflicts with legacy pharmaceutical systems. |
| Brazil Laboratory Infrastructure Buildout | Captures first-mover positioning under ANVISA's expanded medical framework. |
Research Methodology
Independent corroboration across laboratory operations directors, regulatory compliance officers, instrument manufacturer account executives, and multi-state operator quality assurance leads underwrites the qualitative findings. Primary interviews with ISO 17025 accreditation body assessors and reference material procurement specialists combined with secondary validation from FDA guidance documents, EPA pesticide tolerance databases, state cannabis control board regulations, and Health Canada/PMRA harmonization notices. Bottom-up testing volume estimates from state-mandated batch-release requirements triangulate against top-down instrument placement data from chromatography and mass spectrometry manufacturers.
Comparable-period anchoring to historical accreditation timelines and method-validation cycles established baseline growth assumptions across the analysis window. Segmentation dimensions modeled include testing method category, sample type complexity, end-user accreditation status, and application regulatory mandate intensity. CAGRs derived from instrument replacement cycles, laboratory capacity expansion plans, and evolving state testing mandates. Industry-specific forecast inputs incorporate ISO 17025 certification queue lengths and reference material supplier concentration metrics.
Several conditions sit outside the modeled scope, including unscheduled federal rescheduling actions, abrupt reference material supplier consolidation, and technology disruption from unvalidated portable analytical methods. Forecasts reflect assumptions about regulatory harmonization pace and accreditation body processing capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Thyroid Test Market
Testing Services
Platelet Function Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
At-Home Celiac Testing Market