
 Retrovirus Testing Market | 2026-2036
Retrovirus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Retrovirus Testing Market Analytics
Hospital laboratories is bifurcating from research institutions as the dominant procurement channel for retrovirus testing platforms. Roche anchors its position through integrated cobas systems that streamline high-throughput blood screening workflows. Abbott competes via Alinity m platform specialization in multiplex molecular diagnostics. DiaSorin extends its geographic footprint through LIAISON XL chemiluminescence analyzers targeting mid-volume hospital laboratories.
Retrovirus testing encompasses molecular, serological, and nucleic acid amplification methods designed to detect retroviral RNA, proviral DNA, or host antibodies with analytical sensitivity thresholds typically below 50 copies per milliliter. These platforms serve critical functions in blood safety, clinical diagnosis, and epidemiological surveillance by identifying HIV, HTLV, and other lentiviral infections before transfusion or therapeutic intervention. PCR technology leads the test type hierarchy due to its nucleic acid amplification precision and window-period reduction advantages. ELISA maintains volume dominance in resource-constrained settings where cost-per-test optimization outweighs sensitivity requirements. Gene amplification technology captures the fastest expansion trajectory as laboratories replace legacy serological workflows with automated real-time platforms.
FDA blood donor deferral policies and CLIA laboratory certification requirements shape instrument validation protocols and reagent approval pathways in the United States. EMA's CE-IVDR framework and WHO prequalification standards govern European and emerging market access respectively, creating layered compliance obligations for manufacturers. Stakeholders must monitor evolving nucleic acid testing mandates from national blood services and prepare for instrument connectivity requirements under diagnostic data interoperability regulations.
Market Dynamics
Blood services worldwide are consolidating nucleic acid testing mandates into unified screening protocols, compressing the window between infection and detection while forcing platform upgrades across hospital laboratories and blood banks.
Growth Catalysts
- CLIA Laboratory Certification:United States blood banks must maintain continuous compliance with FDA donor deferral policies, mandating real-time PCR instrumentation for high-throughput screening workflows.
- Automated Workflow Adoption:Hospital laboratories in Germany and Japan are replacing manual serological methods with integrated molecular platforms to reduce technician hands-on time.
- CE-IVDR Framework Implementation:European manufacturers face expanded technical documentation requirements for in vitro diagnostic devices, accelerating platform consolidation among mid-volume testing sites.
Market Restraints
- Reagent Supply Concentration:Critical PCR enzymes and fluorescent probes originate from a limited supplier base in North America, exposing laboratories to allocation risk during demand surges.
- Capital Equipment Intensity:Automated nucleic acid extraction systems require substantial upfront investment, constraining adoption in resource-limited settings where ELISA workflows persist.
- Window Period Technical Limitation:Serological antibody detection methods retain diagnostic blind spots during acute infection phases, forcing redundant testing protocols in safety-critical applications.
Strategic Opportunities
- Point-of-Care Molecular Expansion:Brazil and South Africa present underpenetrated demand for cartridge-based HIV viral load testing outside centralized laboratory infrastructure.
- Multiplex Platform Convergence:Simultaneous detection of HIV, HBV, and HCV on single automated instruments is reducing per-test operational costs for blood screening services.
- WHO Prequalification Pathway:Emerging market manufacturers can accelerate market access by aligning quality management systems with international procurement eligibility standards.
Industry Challenges
- Molecular Diagnostics Skill Gap:Hospital laboratories struggle to recruit technicians proficient in real-time PCR troubleshooting and contamination control protocols.
- Legacy System Integration Friction:New automated platforms must interface with existing laboratory information systems, extending validation timelines and requiring vendor-specific middleware solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retrovirus Testing Market |
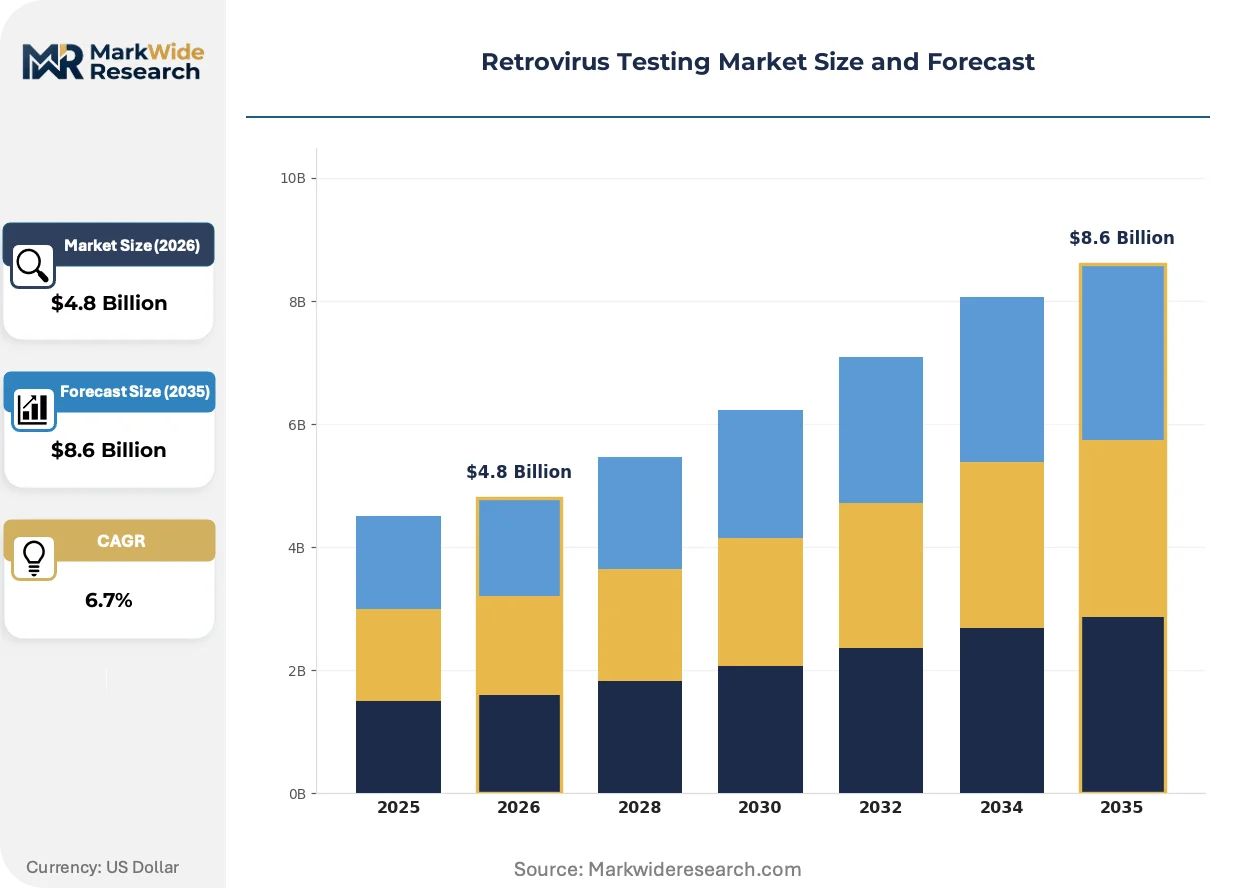
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, PCR, Rapid Test, Western Blot Application: Blood Screening, Diagnosis, Research, Epidemiological Studies End User: Hospitals, Laboratories, Blood Banks, Research Institutions Technology: Gene Amplification, Serological Test, Membrane Assay, Microarray |
| Companies Covered | Abbott, Roche, DiaSorin, bioMrieux, BD, BGI Genomics, Alere, Cepheid, Hybribio Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retrovirus Testing Market Evolving Landscape
Retrovirus testing is transitioning from reactive diagnostic confirmation to proactive screening automation, with platform architecture decisions increasingly dictated by connectivity requirements and throughput scalability rather than analytical sensitivity alone.
Gene amplification technology is displacing legacy ELISA workflows in mid-volume hospital laboratories. Automated real-time PCR platforms with sample-to-result capabilities are capturing procurement contracts from European blood services. This displacement is compressing the installed base of open-system serology analyzers and consolidating vendor relationships around closed instrument-reagent ecosystems.
EMA's CE-IVDR framework is elevating clinical evidence requirements for Class C and D in vitro diagnostics. Manufacturers must now generate prospective performance studies for retrovirus detection claims, extending time-to-market for novel assay introductions. German notified bodies are experiencing backlog congestion, prompting laboratories to accelerate validation of existing CE-marked platforms ahead of certificate expiration.
Blood bank procurement committees are consolidating supplier relationships around vendors offering comprehensive service contracts encompassing preventive maintenance, reagent supply guarantees, and regulatory documentation support. This behavioral shift is displacing transactional equipment purchasing models. The concentration is most visible in United States regional blood centers seeking operational risk transfer through multi-year partnership agreements.
Retrovirus Testing Market Segmentation
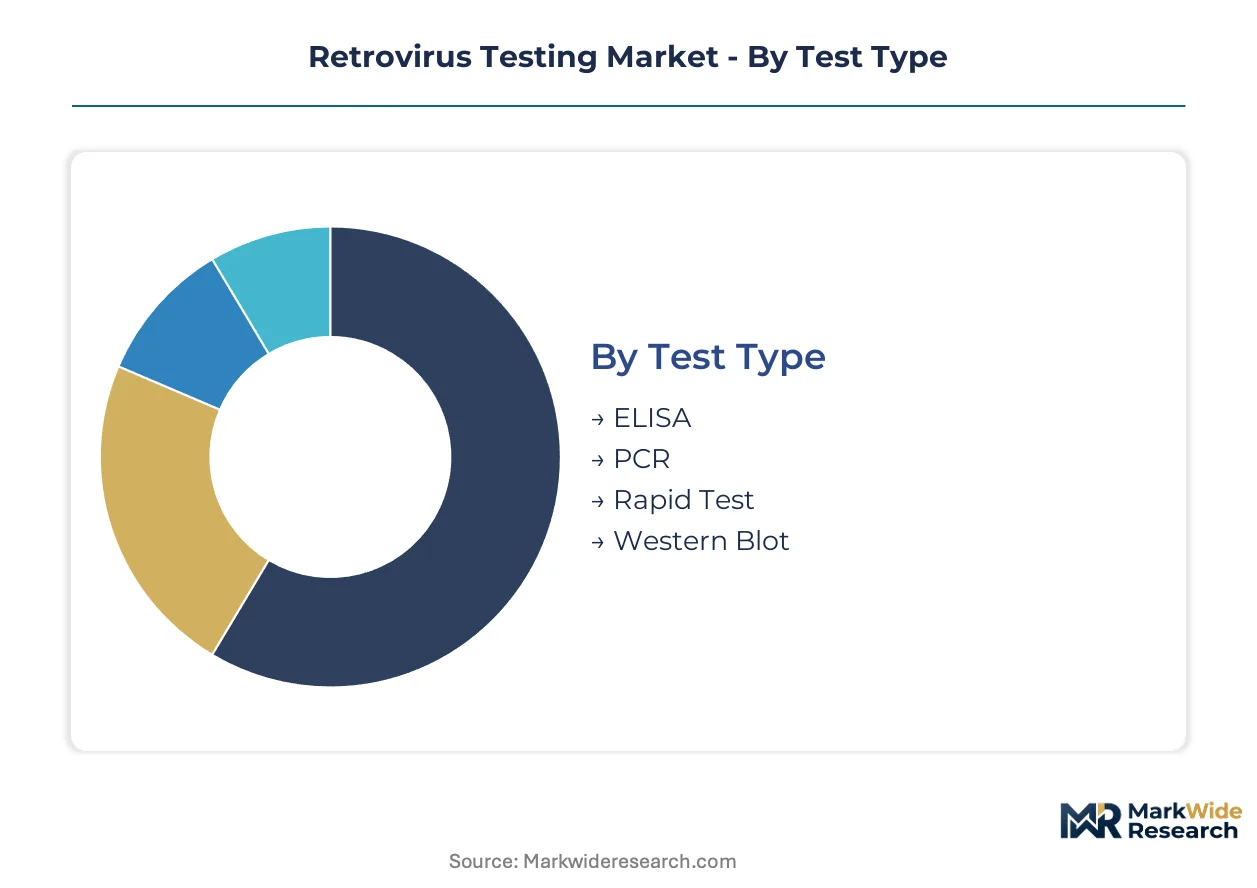
Retrovirus testing procurement channels fragment sharply across end-user types, with hospital laboratories and blood banks driving divergent technology specifications. Test type selection hinges on throughput requirements, regulatory mandates, and capital availability rather than analytical performance alone.
Test Type:
Hospital laboratories and blood banks channel distinct test type preferences based on throughput demands and regulatory compliance obligations.
- PCR:Nucleic acid amplification platforms detect viral RNA and proviral DNA with analytical sensitivity below 50 copies per milliliter. United States blood centers concentrate procurement here due to FDA nucleic acid testing mandates for donor screening.
- ELISA:Enzyme-linked immunosorbent assays detect host antibodies against retroviral antigens using standardized microplate formats. Resource-constrained settings in Brazil and India prioritize this segment for cost-per-test optimization despite longer window periods.
- Rapid Test:Lateral flow immunochromatographic devices deliver qualitative results within 20 minutes at point-of-care sites.
- Western Blot:Confirmatory protein electrophoresis methods resolve indeterminate serological results in reference laboratories.
By volume, ELISA leads. By growth pace, PCR is ahead.
Application:
Application demand distributes unevenly across public health infrastructure layers, with blood safety protocols commanding premium technology deployment.
- Blood Screening:Pre-transfusion nucleic acid testing protocols identify HIV, HTLV, and other lentiviral infections in donor populations. Regulatory agencies in Germany and Japan tighten mandates, forcing platform upgrades at regional blood centers.
- Diagnosis:Clinical confirmation of patient infection status guides therapeutic intervention decisions. Hospital laboratories in the United States automate these workflows to reduce technician hands-on time and report turnaround.
- Research:Academic and pharmaceutical investigators employ specialized assays for viral load quantification and drug resistance profiling.
- Epidemiological Studies:Population-level surveillance programs track infection prevalence and transmission dynamics across geographic clusters.
Blood Screening commands the highest per-test pricing. Diagnosis shows the steepest automation investment curve.
End User:
End-user procurement power concentrates in consolidated blood service organizations and hospital network central laboratories.
- Hospitals:Acute care facilities integrate retrovirus testing into infectious disease and pre-surgical screening protocols. Mid-volume sites favor automated platforms with random access capabilities.
- Blood Banks:Regional collection centers operate high-throughput screening lines with continuous processing requirements. These sites negotiate multi-year service contracts encompassing maintenance, reagents, and regulatory documentation.
- Laboratories:Independent diagnostic providers and public health reference labs handle overflow testing and confirmatory analysis.
- Research Institutions:Universities and biotechnology companies purchase specialized platforms for investigative protocols outside routine clinical workflows.
Blood Banks dominate capital expenditure. Hospitals are expanding fastest through network consolidation.
Technology:
Technology selection reflects a maturity gradient from established serological methods to emerging molecular platforms.
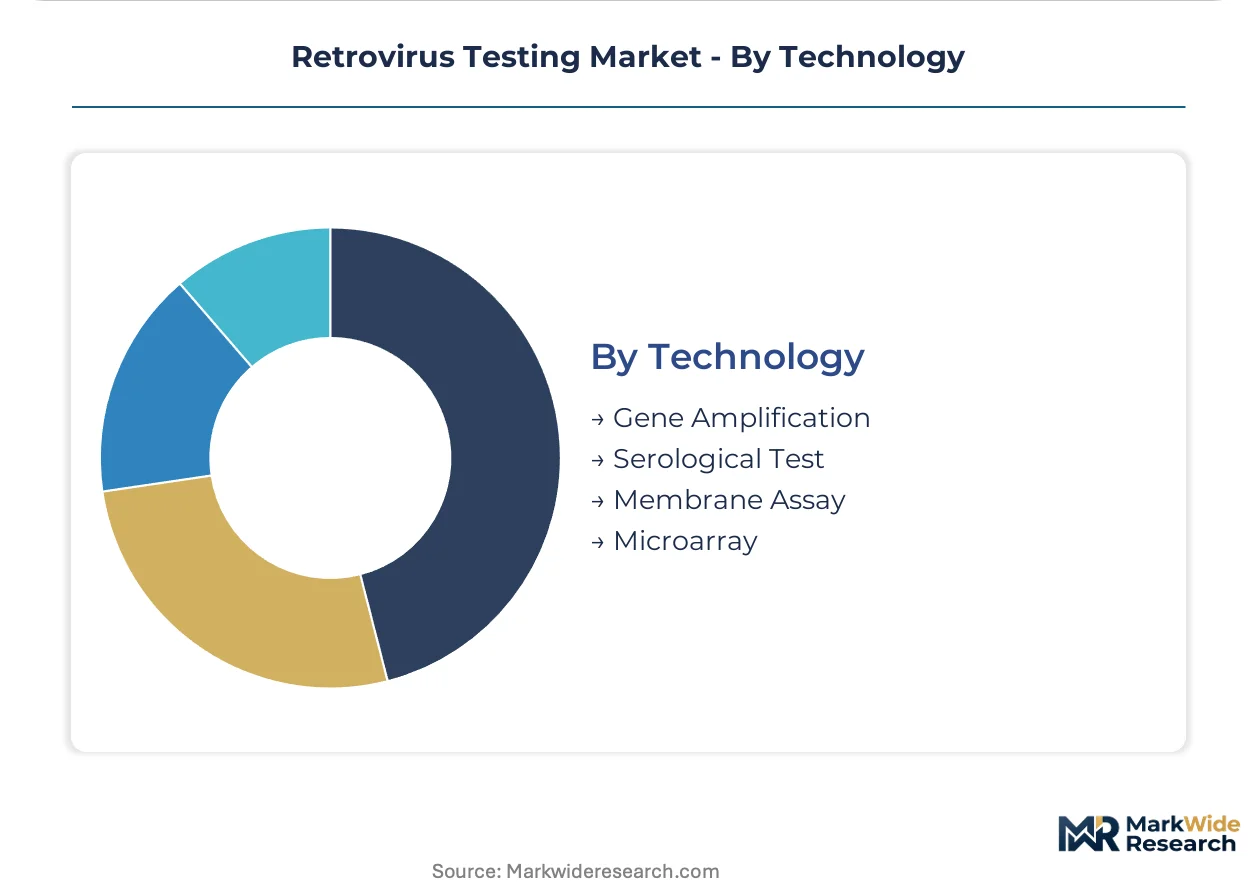
- Gene Amplification:Real-time PCR and transcription-mediated amplification platforms deliver quantitative viral load measurements with automated sample-to-result processing. European hospital laboratories displace legacy workflows fastest here.
- Serological Test:Antibody and antigen detection methods using chemiluminescence or enzyme immunoassay formats retain volume dominance in emerging markets.
- Membrane Assay:Immunochromatographic strip and cartridge devices enable decentralized testing outside centralized laboratory infrastructure.
- Microarray:High-density nucleic acid hybridization platforms support research applications requiring multiplex pathogen detection or resistance mutation profiling.
Serological Test retains installed base leadership. Gene Amplification gains share fastest through workflow automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports automated molecular diagnostic platforms to blood services across Central Europe, while the United States supplies PCR reagents and instrumentation to screening laboratories in Latin America and Southeast Asia.
United States
FDA nucleic acid testing mandates for blood donor screening drive platform upgrades at regional blood centers. CLIA certification requirements enforce continuous compliance with evolving donor deferral policies. The Boston-Cambridge biotechnology corridor hosts specialized assay developers advancing multiplex detection capabilities.
Germany
Hospital laboratories accelerate automated workflow adoption to reduce technician hands-on time in high-throughput environments. EMA's CE-IVDR framework elevates technical documentation requirements for Class C and D in vitro diagnostics. The Rhine-Ruhr metropolitan region concentrates blood service procurement committees negotiating multi-year service contracts.
Japan
PMDA regulatory pathways shape instrument validation protocols for molecular screening platforms entering clinical use. METI standards govern laboratory automation interoperability requirements. The Kanto region around Tokyo anchors hospital network central laboratories consolidating retrovirus testing into infectious disease screening protocols.
Brazil
Underpenetrated demand for cartridge-based HIV viral load testing outside centralized laboratory infrastructure creates procurement opportunities. ANVISA regulatory frameworks align with WHO prequalification standards for international procurement eligibility. São Paulo's public health reference laboratories handle overflow testing from resource-constrained settings where ELISA workflows persist.
South Africa
Point-of-care molecular expansion targets decentralized testing needs in rural and peri-urban healthcare facilities. The national blood service tightens nucleic acid testing mandates for donor screening protocols. Gauteng province's hospital networks pilot automated real-time PCR platforms with sample-to-result capabilities.
Retrovirus Testing Market Competitive Landscape
Player mix skews toward multinational diagnostics conglomerates with integrated instrument-reagent ecosystems. Consolidation concentrates around vendors offering comprehensive service contracts encompassing preventive maintenance, reagent supply guarantees, and regulatory documentation support. Two strategic archetypes dominate: closed-system platform specialists and open-architecture molecular assay developers. Competitive moves center on multi-year partnership agreements with regional blood centers and geographic expansion through WHO prequalification alignment.
Within the multinational diagnostics tier, Abbott, Roche, and DiaSorin represent the dominant competitive anchors. Abbott occupies a position exemplifying multiplex molecular platform specialization. Roche anchors the integrated high-throughput blood screening workflow segment. DiaSorin sits within the mid-volume hospital laboratory tier through chemiluminescence analyzer deployment. These three entities collectively illustrate how vendor relationships consolidate around closed instrument-reagent ecosystems rather than transactional equipment purchasing models.
| Leading Market Players |
|---|
| Abbott |
| Roche |
| DiaSorin |
| bioMrieux |
| BD |
| BGI Genomics |
| Alere |
| Cepheid |
| Hybribio Biotech |
| Others |
Value Network & Pricing Analysis
FDA nucleic acid testing mandates for blood donor screening gate both instrument qualification and price differentiation simultaneously, compressing procurement timelines while elevating certification premiums for PCR platform vendors serving United States regional blood centers.
Pricing Analysis
Next-generation automated sample-to-result PCR platforms command 40-60% price premiums over prior-generation open-system serology analyzers, while current-generation ELISA workflows occupy the economy tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, after-sales service bundling, and throughput scale. Cost compression in the ELISA tier is intensifying because hospital laboratories in resource-constrained settings prioritize cost-per-test optimization over sensitivity requirements. Blood banks demonstrate the lowest price sensitivity due to regulatory compliance imperatives, while independent diagnostic laboratories exhibit the highest.
Supply Chain Analysis
Fluorescent probe synthesis capacity in California and Massachusetts anchors global reagent supply for real-time PCR platforms. Critical enzymes and oligonucleotides draw from concentrated North American supplier bases, exposing laboratories to allocation risk during demand surges. Single-source vulnerability concentrates in thermostable polymerase production. Distribution runs through authorized distributor networks serving hospital procurement committees and blood service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene amplification technology displacement of legacy serology workflows constitutes a high-growth disruption, with EMA's CE-IVDR framework accelerating platform consolidation among mid-volume testing sites across the analysis window.
For Market Incumbents: Compound installed base advantages through multi-year service contracts encompassing preventive maintenance, reagent supply guarantees, and regulatory documentation support. Threaten emerging entrant positions by accelerating backward integration into critical PCR enzyme production. Prioritize certification investment in WHO prequalification alignment to defend access in emerging procurement markets. For New Entrants and Emerging Players: Lead with cartridge-based point-of-care molecular platforms targeting underpenetrated demand in Brazil and South Africa outside centralized laboratory infrastructure. Focus initial deployment on HIV viral load testing in rural and peri-urban healthcare facilities. Pursue hospital network pilot programs in Gauteng province and São Paulo's public health reference laboratories as referenceable proof points. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-cap diagnostics specialists possessing CE-IVDR transition capabilities but limited geographic scale. Long-term viability favors platforms with automated workflow integration and sample-to-result architectures. Monitor nucleic acid testing mandate expansion from national blood services as the primary inflection indicator for capacity expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Platform Convergence | Simultaneous HIV-HBV-HCV detection reduces per-test costs for German blood screening services. |
| CE-IVDR Technical Documentation Investment | Prospective performance studies extend time-to-market for novel retrovirus assay introductions. |
| Point-of-Care Molecular Expansion | Cartridge-based platforms penetrate decentralized testing infrastructure in Brazilian public health networks. |
| WHO Prequalification Alignment | Quality management system certification unlocks international procurement eligibility for emerging market manufacturers. |
| Automated Workflow Adoption | Sample-to-result capabilities reduce technician hands-on time in Japanese hospital network central laboratories. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA CE-IVDR technical documentation, hospital procurement databases, and GPO contracts. Conversations with blood bank procurement directors, hospital laboratory managers, biomedical engineers, regulatory affairs specialists, and IVD platform engineers inform demand-side validation. Top-down market sizing triangulates against bottom-up instrument installation base and reagent consumption estimates.
Segmentation dimensions modeled include test type, application, end user, technology, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical platform adoption curves and instrument replacement cycles. Forecast inputs incorporate nucleic acid testing mandate expansion timelines and automated workflow penetration rates in hospital laboratories.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of donor screening protocols or supply chain disruption in critical reagent categories would require recalibration. Practitioners should keep alternative scenarios live as EMA notified body backlog conditions and WHO prequalification pathway evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Sports Drug Testing Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Service Laboratory Market
Testing Services
Global Virology Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Arbovirus Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
In-Vitro Diagnostic Services Market