
 Esoteric Testing Market | 2026-2036
Esoteric Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Esoteric Testing Market Intelligence
A shift from single-source to multi-source esoteric testing partnerships is repositioning how health systems manage specialized diagnostic capacity. Quest Diagnostics leverages its national logistics network to sustain reference laboratory dominance across complex assay categories. Labcorp anchors hospital outsourcing relationships through integrated esoteric test menus and informatics platforms. Eurofins Scientific competes in genetic and toxicology testing through European laboratory density and CAP-accredited facility expansion.
Esoteric testing encompasses laboratory analyses requiring specialized instrumentation, rare reagents, or advanced technical expertise that exceeds the capabilities of routine clinical chemistry platforms, including mass spectrometry-based metabolic panels and next-generation sequencing for hereditary cancer screening. Its primary commercial purpose centers on delivering definitive diagnostic, prognostic, or therapeutic guidance for rare diseases, complex malignancies, and pharmacogenomic applications where standard assays prove insufficient. Genetic testing occupies the fastest-expanding margin pool as payer coverage broadens for hereditary condition screening and somatic tumor profiling. Reference laboratories command the highest test volume throughput, while academic institutions concentrate on assay development and clinical validation for emerging biomarker categories.
The FDA oversees laboratory-developed test oversight through risk-based classification proposals, while CAP accreditation governs analytical quality standards for esoteric assay performance. CLIA certification tiers determine which laboratories may perform high-complexity testing, directly constraining market access for new entrants. Stakeholders must monitor evolving reimbursement policies for multi-gene panels and companion diagnostics, as coverage decisions by CMS and private payers will determine which esoteric categories achieve sustainable commercial scale.
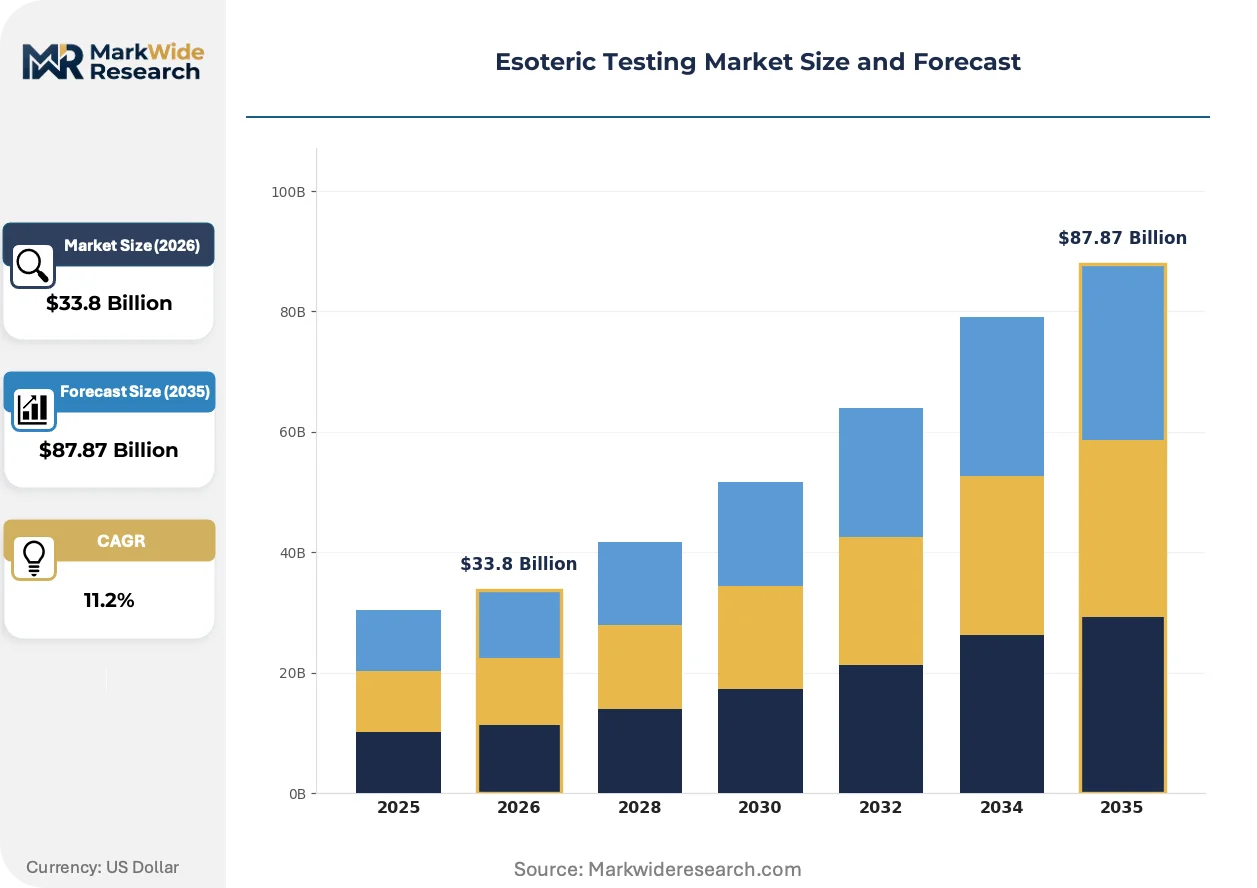
Market Dynamics
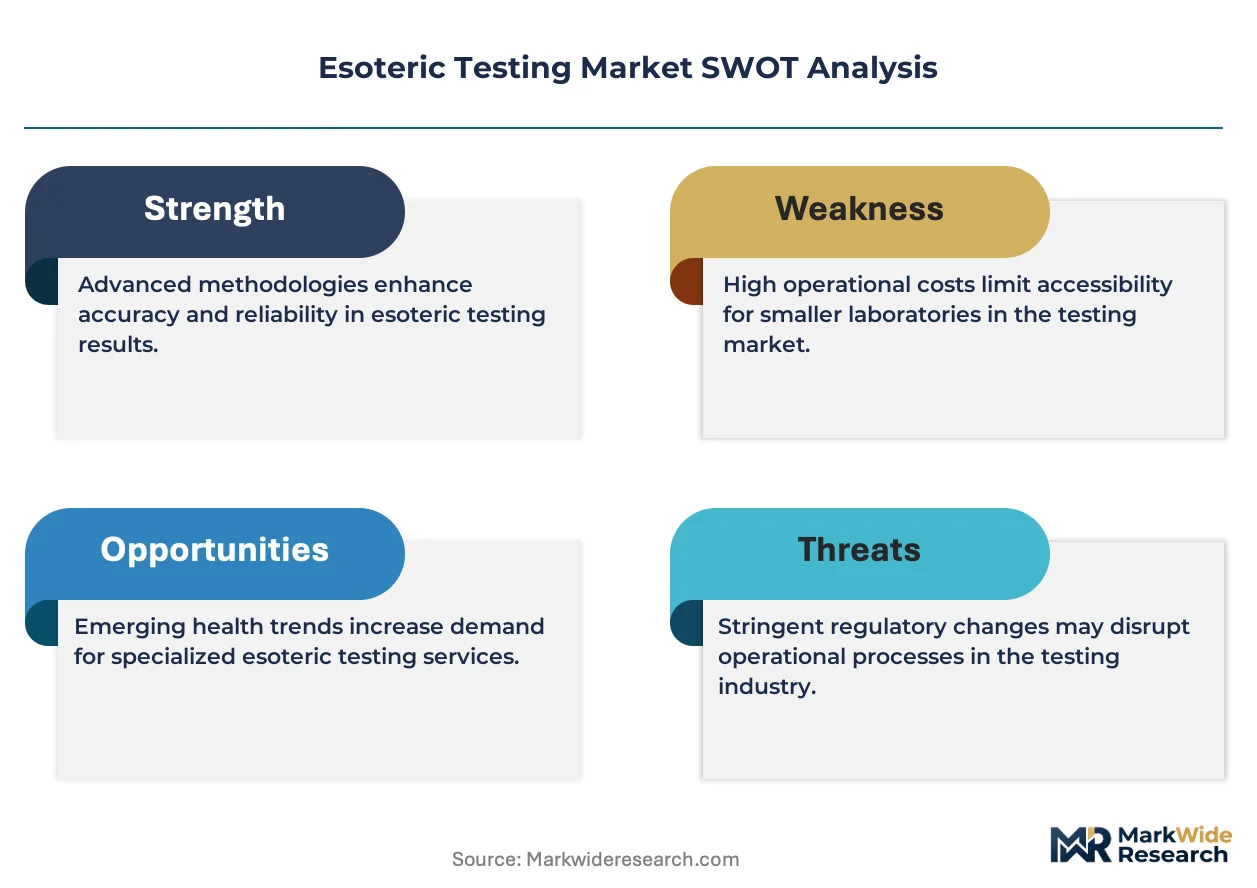
The FDA's risk-based classification framework for laboratory-developed tests is compressing commercialization timelines while fragmenting competitive positioning between high-complexity CLIA laboratories and emerging molecular diagnostic platforms.
Growth Catalysts
- Hereditary cancer screening expansion:Payer coverage broadening for BRCA and Lynch syndrome panels is pulling volume into reference laboratory networks. United States health systems are consolidating send-out contracts to capture economies of scale in next-generation sequencing workflows.
- CLIA high-complexity certification expansion:Academic medical centers are converting research-grade mass spectrometry assays into reimbursable clinical tests. This regulatory pathway enables direct commercialization without full FDA premarket review.
- Pharmacogenomic guideline integration:CPIC and DPWG therapeutic recommendations are embedding genetic testing into standard-of-care protocols for warfarin, clopidogrel, and psychiatric medication management.
Market Restraints
- Reimbursement compression:CMS gapfill pricing methodology for new CPT codes frequently undervalues complex multi-gene panels relative to laboratory investment in assay validation and bioinformatics infrastructure.
- Reagent supply concentration:Critical enzymes, modified nucleotides, and capture probe libraries concentrate among three dominant life science suppliers, creating single-source vulnerability for mid-tier laboratories.
- Analytical validation burden:CAP proficiency testing requirements for rare variant detection demand continuous specimen exchange between laboratories, consuming technical specialist hours without direct revenue offset.
Strategic Opportunities
- Direct-to-consumer regulatory pathway:FDA authorization of 23andMe-style carrier screening and pharmacogenomic reports is opening channel diversification beyond traditional health system contracting.
- Liquid biopsy minimal residual disease:ctDNA monitoring for post-surgical cancer recurrence detection represents an emerging application with limited incumbent competition and premium pricing potential.
- AI-assisted variant interpretation:Machine learning tools for VUS reclassification are converging with expanding ClinVar databases to reduce genetic counselor review burden and accelerate report turnaround.
Industry Challenges
- Bioinformatics talent scarcity:Variant curation and pipeline development require hybrid molecular biology-computational skill sets that outpace current fellowship program output.
- LIMS integration complexity:Legacy laboratory information systems require expensive middleware development to connect with cloud-based sequencing platforms and automated reporting tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esoteric Testing Market |
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $87.87 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genetic Testing, Metabolic Testing, Immunological Testing, Toxicology Testing Sample Type: Blood, Urine, Saliva, Tissue End User: Hospitals, Reference Laboratories, Academic Institutions, Clinics Technology: Polymerase Chain Reaction, Mass Spectrometry, Next-Generation Sequencing, Microarray |
| Companies Covered | OPKO Health, Inc., Kindstar Globalgene Technology, Inc., Labcorp, Mayo Foundation for Medical Education and Research, ARUP Laboratories, Quest Diagnostics, Sonic Healthcare Limited, Eurofins Scientific, H.U. Group Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esoteric Testing Market Strategic Shifts & Innovations
Automation and artificial intelligence are restructuring esoteric testing workflows from sample accessioning through variant reporting, compressing turnaround times while elevating quality control standards.
Mass spectrometry-based metabolic and toxicology panels are modularizing around standardized ionization sources and interchangeable chromatography columns. Mid-sized hospital laboratories are adopting these platforms to insource tests previously sent to national reference laboratories. This technology is modularizing the historical reference laboratory monopoly on specialized endocrinology and neonatal screening assays.
The FDA's proposed rulemaking on laboratory-developed tests is creating a bifurcated compliance landscape where high-risk assays face premarket submission requirements while moderate-complexity tests transition to quality system regulation. European laboratories under IVDR are experiencing parallel notification burdens for companion diagnostic performance claims. Academic medical centers in both jurisdictions are restructuring clinical laboratory improvement programs to anticipate dual regulatory compliance.
Health system procurement departments are consolidating esoteric testing contracts into multi-year exclusive arrangements with single reference laboratory partners. Independent physician practices and smaller hospitals are losing direct access to specialized menus as integrated delivery networks centralize laboratory spend. This concentration is most visible in United States metropolitan markets where three-to-five health systems control eighty percent of inpatient admissions and associated diagnostic volume.
Esoteric Testing Market Segmentation
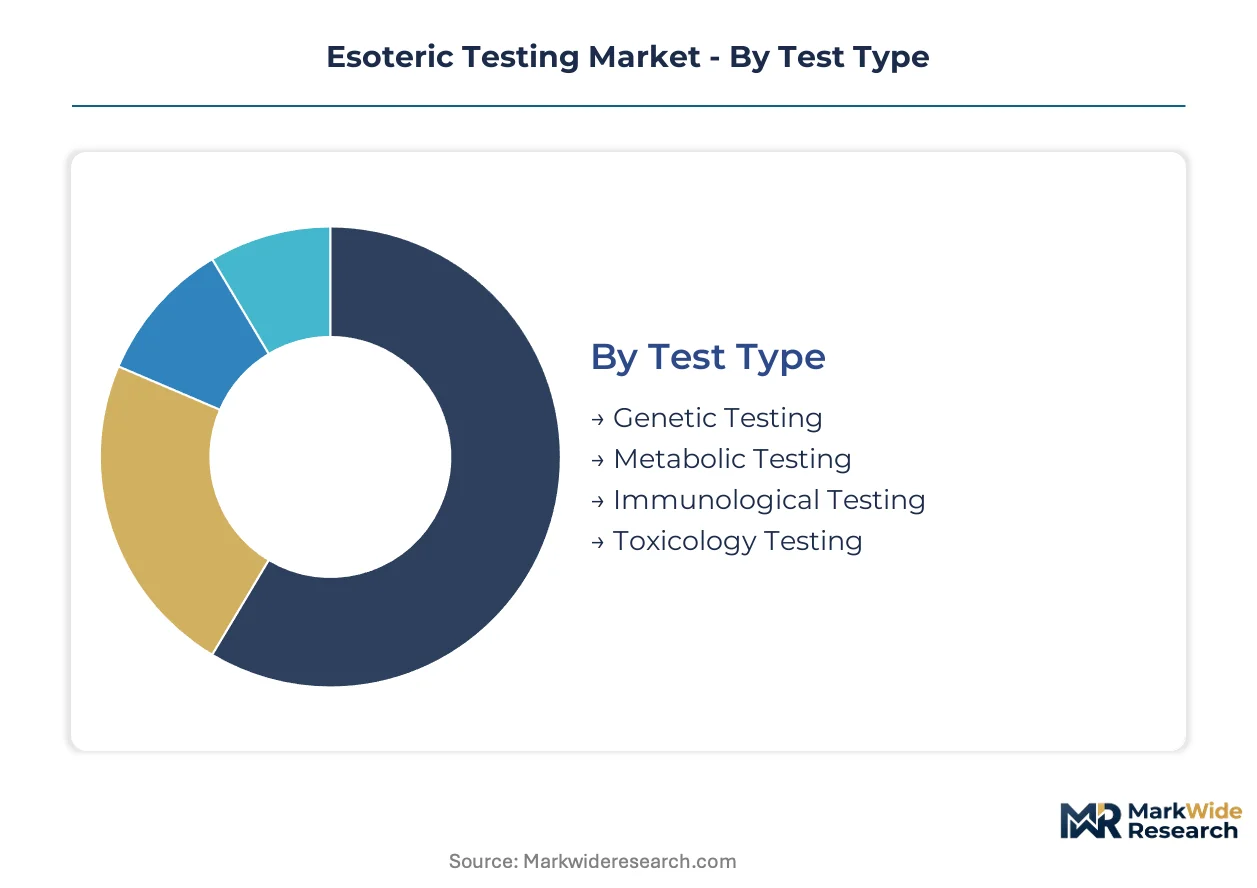
Esoteric testing segments fragment across technical complexity, biological specimen requirements, and institutional purchasing power. Certification tiers under CLIA and FDA frameworks create divergent margin structures across each dimension.
Test Type:
CLIA high-complexity certification governs three segments, while FDA premarket submission requirements apply variably based on diagnostic risk classification.
- Genetic Testing:Next-generation sequencing and PCR-based assays for hereditary conditions, oncology profiling, and pharmacogenomics. United States academic medical centers are converting research-grade assays into reimbursable clinical tests through CLIA pathways. Payer coverage expansion for BRCA and Lynch syndrome panels is pulling volume into reference laboratory networks.
- Metabolic Testing:Mass spectrometry-based panels for inborn errors of metabolism, endocrine disorders, and neonatal screening. Mid-sized hospital laboratories are adopting modular LC-MS platforms to insource tests previously sent to Quest Diagnostics and Labcorp. Reimbursement compression under CMS gapfill pricing constrains investment returns on complex multi-analyte validations.
- Immunological Testing:Specialized autoantibody and immunodeficiency panels requiring rare reagent sourcing.
- Toxicology Testing:Forensic and clinical drug screening through chromatographic methods.
Leading the category by volume: Metabolic Testing. Growing fastest: Genetic Testing.
Sample Type:
Collection logistics and stability requirements determine whether specimens route to centralized reference laboratories or remain within hospital systems.
- Blood:Serum and plasma specimens dominate esoteric test menus, particularly for metabolic and immunological assays. Hospital phlebotomy networks in the United States maintain same-day courier relationships with regional reference laboratories. Pre-analytical variables including hemolysis and temperature excursion create quality control burdens that favor high-volume operators.
- Tissue:Formalin-fixed paraffin-embedded samples and fresh biopsies for oncology molecular profiling. Academic medical centers with embedded pathology services are retaining complex somatic testing in-house rather than outsourcing to national laboratories. CAP proficiency testing requirements for rare variant detection demand continuous specimen exchange between validating institutions.
- Urine:Toxicology and metabolic screening with established collection protocols.
- Saliva:Direct-to-consumer genetic testing and carrier screening applications.
Blood specimens command the highest absolute test volume. Tissue-based oncology profiling shows the steepest expansion trajectory as companion diagnostic linkages deepen.
End User:
Purchasing consolidation is restructuring competitive access across institutional tiers.
- Reference Laboratories:National networks including Quest Diagnostics and Labcorp sustain economies of scale in next-generation sequencing workflows. These operators command exclusive multi-year contracts with integrated delivery networks controlling eighty percent of United States metropolitan inpatient admissions. Informatics platform integration anchors hospital outsourcing relationships.
- Academic Institutions:Medical centers concentrate on assay development and clinical validation for emerging biomarker categories. CLIA high-complexity certification enables direct commercialization without full FDA premarket review. Bioinformatics talent scarcity constrains pipeline expansion despite research-grade instrumentation availability.
- Hospitals:In-house esoteric testing capacity is expanding through mass spectrometry platform adoption.
- Clinics:Independent physician practices are losing direct menu access as health systems centralize laboratory spend.
Reference Laboratories lead by test volume. Academic Institutions are climbing fastest as research-to-clinic translation accelerates.
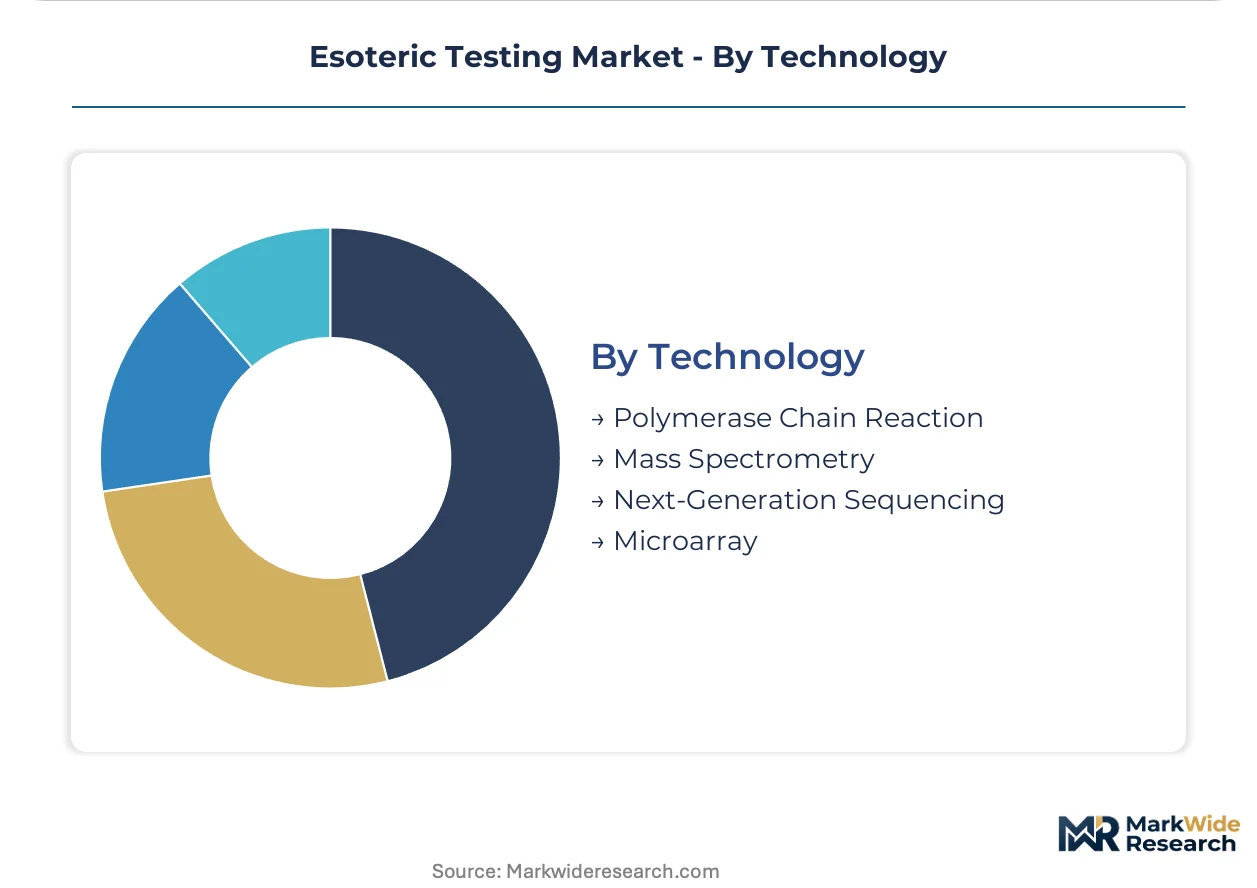
Technology:
Platform selection determines regulatory pathway, capital intensity, and reagent supply vulnerability.
- Next-Generation Sequencing:Targeted panels and whole-exome approaches for hereditary and somatic applications. Critical enzymes and modified nucleotides concentrate among three dominant life science suppliers, creating single-source vulnerability for mid-tier laboratories. AI-assisted variant interpretation tools are converging with expanding ClinVar databases to reduce genetic counselor review burden.
- Mass Spectrometry:LC-MS and GC-MS platforms for metabolic, toxicology, and endocrine testing. Standardized ionization sources and interchangeable chromatography columns are modularizing instrument configurations. European laboratories under IVDR are experiencing parallel notification burdens for performance claims.
- Polymerase Chain Reaction:Established real-time and digital PCR methods for targeted genetic analysis.
- Microarray:Comparative genomic hybridization and SNP arrays with declining share relative to sequencing.
Mass Spectrometry leads by installed base and test throughput. Next-Generation Sequencing is gaining share fastest as panel breadth expands and per-base costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for esoteric testing concentrates in health systems with embedded academic medical centers and dense reference laboratory networks. The United States anchors specialized diagnostic capacity through consolidated procurement arrangements. Regulatory divergence between FDA and IVDR frameworks is fragmenting commercialization pathways across major markets.
United States
Integrated delivery networks in metropolitan markets control eighty percent of inpatient admissions and associated esoteric test volume. FDA risk-based classification proposals for laboratory-developed tests are compressing timelines for high-complexity assay commercialization. The Boston-Cambridge corridor anchors genetic testing innovation through academic medical center partnerships with national reference laboratories.
Germany
IVDR notification burdens for companion diagnostic performance claims are restructuring laboratory compliance investments. The country's national pharmaceutical regulator enforces parallel quality system requirements for multi-gene panel validation. The Rhine-Ruhr metropolitan region concentrates CAP-accredited facility expansion serving cross-border European demand.
United Kingdom
NHS England procurement consolidation is centralizing specialized diagnostic contracts into multi-year exclusive arrangements. The national health technology assessment body evaluates coverage for next-generation sequencing panels through technology appraisal pathways. London anchors reference laboratory density with embedded academic pathology services retaining complex somatic testing in-house.
Japan
PMDA oversight of companion diagnostics is converging with global FDA frameworks for oncology biomarker validation. METI industrial policy supports domestic mass spectrometry platform adoption for metabolic and neonatal screening insourcing. The Kanto region concentrates hospital laboratory networks with same-day courier relationships to specialized testing facilities.
Australia
TGA regulation of laboratory-developed tests follows risk-based classification principles aligned with evolving FDA frameworks. Medicare reimbursement policies for multi-gene panels determine which esoteric categories achieve sustainable commercial scale. Melbourne and Sydney anchor specialized diagnostic capacity through academic medical center pathology services.
Esoteric Testing Market Key Industry Players
Strategic partnerships dominate the current landscape as health systems consolidate esoteric testing contracts into exclusive multi-year arrangements. The vendor base organizes around three tiers: national reference laboratory networks commanding economies of scale, academic medical centers converting research-grade assays into reimbursable clinical tests, and mid-sized hospital laboratories adopting modular platforms to insource previously outsourced volume. Dominant competitive moves include M&A for informatics platform integration and geographic expansion through CAP-accredited facility density.
Within the reference laboratory tier, Quest Diagnostics and Labcorp exemplify scale-driven operators anchoring hospital outsourcing relationships through integrated test menus. Eurofins Scientific occupies a position within the European specialist tier, competing through laboratory density and toxicology testing concentration. Mayo Foundation for Medical Education and Research represents the academic medical center archetype, leveraging CLIA high-complexity certification for direct assay commercialization without full FDA premarket review.
| Leading Market Players |
|---|
| OPKO Health, Inc. |
| Kindstar Globalgene Technology, Inc. |
| Labcorp |
| Mayo Foundation for Medical Education and Research |
| ARUP Laboratories |
| Quest Diagnostics |
| Sonic Healthcare Limited |
| Eurofins Scientific |
| H.U. Group Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Modified nucleotides and capture probe libraries flow from three dominant life science suppliers through CLIA-certified laboratories to health system procurement departments, with reagent concentration upstream enabling tiered pricing power downstream that separates premium reference laboratory contracts from mid-tier hospital laboratory arrangements.
Pricing Analysis
Volume-massive reference laboratories command favorable unit economics on next-generation sequencing workflows, while academic medical centers and mid-tier hospital laboratories absorb premium pricing on specialized reagent kits and bioinformatics infrastructure. Price differentiation rests on CLIA certification tier and health system contract scale, with integrated delivery networks extracting volume discounts through exclusive multi-year arrangements. Pricing pressure stems from CMS gapfill methodology undervaluing complex multi-gene panels relative to validation investment. Independent physician practices exhibit highest price sensitivity as health system consolidation removes direct menu access.
Supply Chain Analysis
Bioinformatics pipeline developers and variant curation specialists concentrate in the Boston-Cambridge corridor and San Francisco Bay Area, with workforce scarcity in these geographies constraining mid-tier laboratory expansion. Critical enzymes and modified nucleotides draw from United States, German, and Japanese chemical synthesis suppliers. Single-source vulnerability on capture probe libraries creates supply chain risk for laboratories lacking diversified reagent sourcing. Distribution runs through national logistics networks anchored by Quest Diagnostics and Labcorp, with same-day courier relationships governing specimen flow from hospital phlebotomy networks to regional reference facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The esoteric testing market is becoming a vertical-integration race, with players pursuing backward integration into reagent manufacturing and bioinformatics pipeline development to escape supplier concentration and talent scarcity constraints.
For Market Incumbents: Deepen captive supply relationships with enzyme and modified nucleotide manufacturers to insulate against reagent concentration risk. Expand CLIA high-complexity certification density in metropolitan markets where integrated delivery networks control inpatient admissions. Consolidate informatics platform integration to anchor hospital outsourcing relationships against emerging molecular diagnostic platforms. For New Entrants and Emerging Players: FDA's risk-based classification framework for laboratory-developed tests in the United States opens a window for direct-to-consumer pharmacogenomic and carrier screening pathways beyond traditional health system contracting. Target liquid biopsy minimal residual disease monitoring as an underpenetrated oncology application with limited incumbent competition. Pursue AI-assisted variant interpretation partnerships to reduce genetic counselor dependency and accelerate report turnaround. For Investors and Strategic Acquirers: Academic medical center conversion of research-grade mass spectrometry assays into reimbursable clinical tests is the leading indicator that CLIA pathway commercialization is scaling beyond traditional reference laboratory dominance. Target acquisition candidates with hybrid molecular biology-computational talent pipelines and embedded pathology services retaining complex somatic testing in-house. Watch for health system procurement consolidation signals as inflection indicators for contract exclusivity value.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Expansion | Academic medical centers convert research-grade mass spectrometry assays into reimbursable clinical tests without full FDA premarket review. |
| AI-Assisted Variant Interpretation Partnership | Machine learning tools for VUS reclassification converge with expanding ClinVar databases to reduce genetic counselor review burden. |
| Direct-to-Consumer Regulatory Pathway Development | FDA authorization of carrier screening and pharmacogenomic reports opens channel diversification beyond health system contracting. |
| Reagent Manufacturing Backward Integration | Captive supply of critical enzymes and modified nucleotides insulates laboratories against three-supplier concentration vulnerability. |
| Informatics Platform Integration | Cloud-based sequencing platforms and automated reporting tools anchor hospital outsourcing relationships through LIMS connectivity. |
Research Approach
Independent corroboration across laboratory directors at academic medical centers, reference laboratory operations executives, and health system procurement officers underwrites the qualitative findings, supplemented by FDA guidance documents, CAP proficiency testing requirements, CMS reimbursement databases, and CLIA certification records. Primary interviews with biomedical engineers and GPO contracts managers cross-validate secondary data on test volume flows and contract structures. Bottom-up test volume modeling and top-down health system spend analysis triangulate market sizing.
Comparable-period anchoring to historical CLIA certification expansion and CMS coverage determination timelines structures the forecast window across the analysis window. Segmentation dimensions include test type, sample type, end user, and technology platform, with regulatory pathway and payer coverage policy as industry-specific forecast inputs. CAGRs derive from test volume trajectory modeling and per-unit pricing trend analysis.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing platform standardization would alter the outlook. Forecasts reflect assumptions on FDA risk-based classification implementation timing and CMS gapfill pricing methodology evolution. Material deviation in payer coverage expansion for multi-gene panels or companion diagnostics warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Fertility Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Home Care Testing Market
Testing Services
Influenza Home Testing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Outsourced Testing Services Market
Testing Services
Cell Line Authentication and Characterization Tests Market