
 Aerospace and Life Science Testing Certification Market | 2026-2036
Aerospace and Life Science Testing Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Life Science Testing Certification Market Analysis
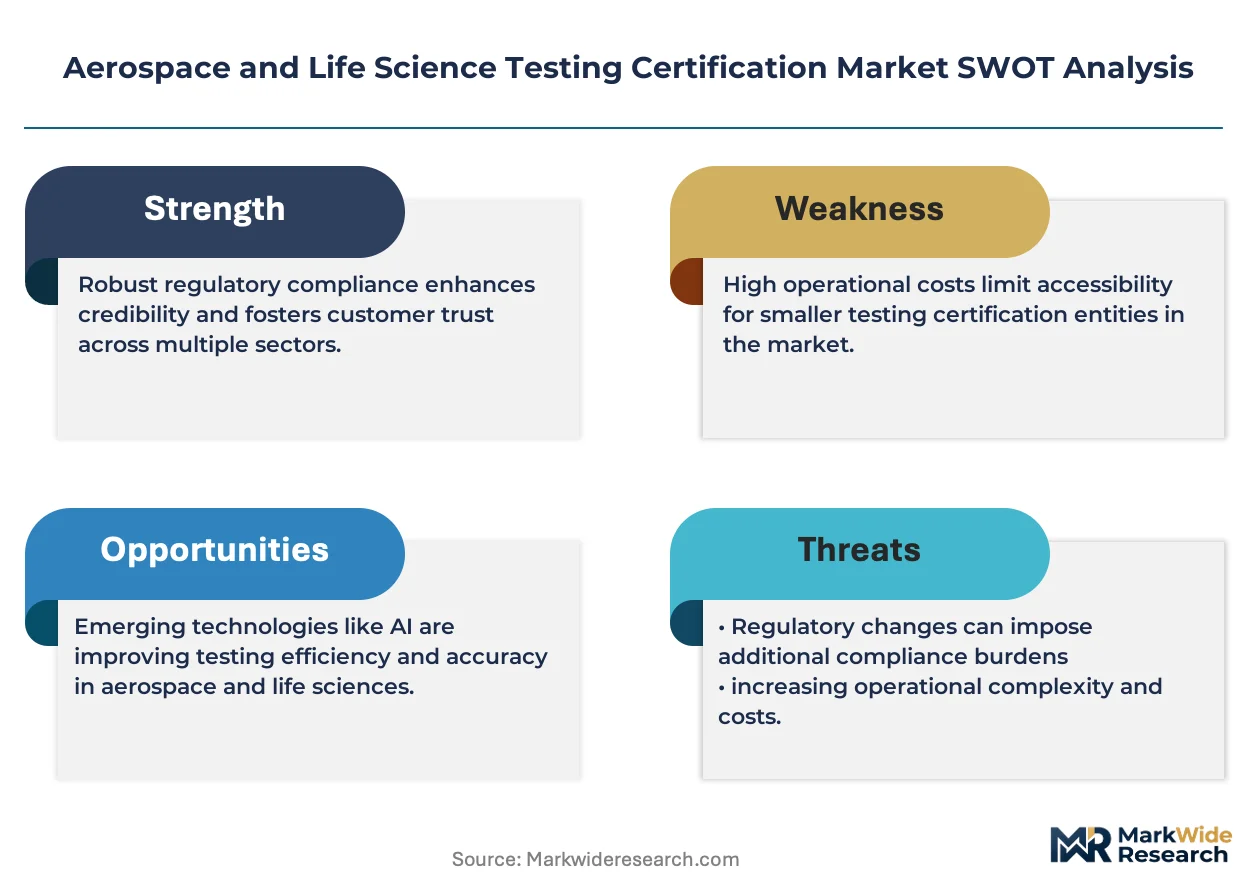
Modular service bundling is broadening buyer choice across the Aerospace and Life Science Testing Certification landscape. SGS leverages its multi-sector laboratory network to offer integrated material testing and regulatory compliance packages. Bureau Veritas anchors its position through deep specialization in aerospace component evaluation. Intertek Group competes by extending its software verification capabilities into medical device cybersecurity protocols.
Aerospace and Life Science Testing Certification encompasses the independent validation of materials, systems, components, and processes against statutory safety, efficacy, and performance benchmarks, employing mechanical stress analysis, chemical composition profiling, environmental simulation, and algorithmic verification to assure operational integrity. The service type dimension shows material testing occupying the largest revenue pool while software verification represents the fastest-expanding margin segment. Within industry verticals, medical devices command premium pricing due to FDA and EMA premarket submission complexity, whereas biotechnology process validation remains an emerging growth corridor.
FAA airworthiness directives, EASA certification specifications, and FDA quality system regulation collectively shape demand by mandating third-party validation for market access. The EU AI Act and MDR frameworks are expanding software verification requirements for connected medical devices. Stakeholders must monitor how converging aerospace digitization and pharmaceutical automation standards reshape competency requirements across testing portfolios.
Market Dynamics
Commercial aviation OEMs are consolidating validation partnerships as FAA and EASA airworthiness mandates tighten, forcing testing providers to absorb compliance complexity while maintaining throughput capacity across multi-year certification cycles.
Growth Catalysts
- MDR software verification mandates:The EU Medical Device Regulation now requires third-party algorithmic validation for connected diagnostics, expanding contract volumes for cybersecurity-capable laboratories in Germany and Switzerland.
- Biotechnology process automation:Cell therapy manufacturers in Massachusetts and North Carolina are outsourcing viral vector validation to specialized CDMO-affiliated testing facilities.
- FAA Part 25 Amendment 25-146:Updated fuel tank ignition source protection rules are driving retesting of legacy aircraft electrical systems, creating aftermarket certification demand.
Market Restraints
- Helium supply concentration:Mass spectrometry leak detection for aerospace components depends on Qatar and Algeria for gas supply, creating input cost volatility and allocation risk.
- Accreditation backlog at DAkkS:German testing laboratory recognition delays are extending time-to-market for pharmaceutical clients seeking EU MDR compliance.
- Computational fluid dynamics substitution:Wind tunnel testing for certain aerodynamic profiles faces displacement by high-fidelity simulation, compressing physical test demand in commercial aviation.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:NEOM and Red Sea tourism aviation infrastructure are creating greenfield demand for airworthiness certification services without incumbent provider saturation.
- AI Act conformity assessment:The EU AI Act's high-risk system classification for medical imaging algorithms creates a new validation category at the intersection of software verification and clinical performance testing.
- Digital twin integration:Convergence of physics-based simulation with real-time sensor validation is enabling predictive certification models that reduce physical prototype iterations for satellite components.
Industry Challenges
- AS9100D auditor scarcity:Aerospace quality management system certification faces bottlenecks as qualified lead auditors retire faster than training pipelines replenish.
- Multi-standard harmonization friction:FDA 21 CFR Part 11 electronic records requirements diverge from EMA Annex 11 implementation guides, forcing dual-track validation documentation for global device submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Life Science Testing Certification Market |
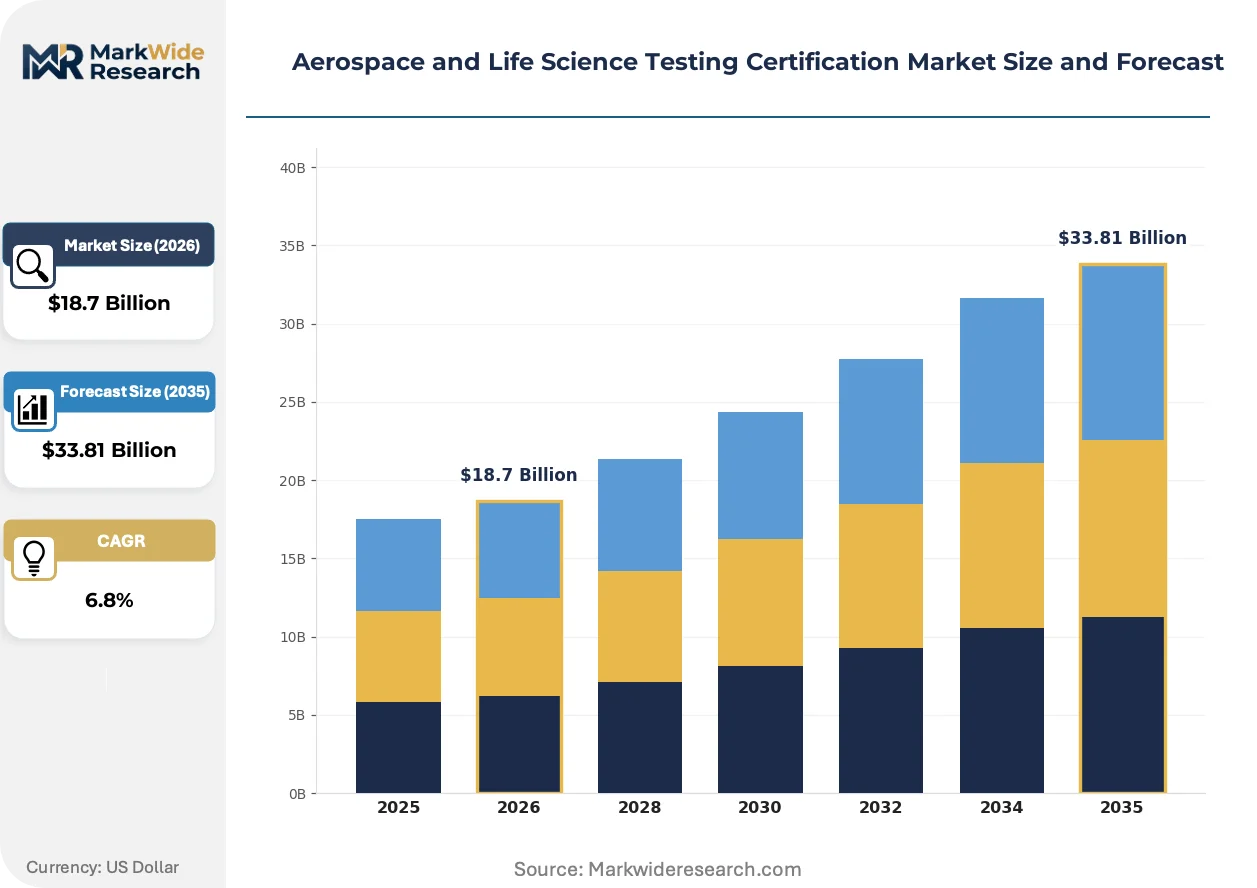
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Material Testing, System Certification, Component Evaluation, Process Validation Industry Vertical: Aerospace, Pharmaceuticals, Biotechnology, Medical Devices Technology: Mechanical Testing, Chemical Analysis, Environmental Testing, Software Verification Application: Quality Assurance, Regulatory Compliance, Research Development, Product Approval |
| Companies Covered | SGS, Bureau Veritas, Intertek Group, TÜV SÜD, Element Materials Technology, TÜV Rheinland, Applus+, Eurofins Scientific, DNV GL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Life Science Testing Certification Market Emerging Trajectories
Digital thread architectures are compressing the handoff between design verification and regulatory submission, collapsing traditional phase-gate timelines while demanding new competencies in data integrity and algorithmic transparency.
Blockchain-anchored test record systems are expanding into aerospace supply chain traceability, creating immutable chains of custody for composite material batch testing from fiber production through airframe assembly. Tier-1 suppliers at Airbus and Boeing are piloting these systems for resin pre-preg qualification. The technology is expanding into life science applications where FDA 21 CFR Part 11 compliance requires audit trail immutability for clinical trial device testing.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of aerospace sealants and medical device lubricants, triggering retesting of material compatibility and biocompatibility profiles. ECHA's 2023 PFAS restriction proposal is accelerating substitution programs among German and French testing clients. Medical device manufacturers are responding by engaging testing providers for extractables and leachables validation of replacement chemistries.
Consolidated vendor qualification programs are displacing discrete laboratory selection processes, as Medtronic and Johnson & Johnson implement preferred provider networks that bundle material, sterility, and software testing under master service agreements. This procurement restructuring favors multi-capability testing houses with geographic proximity to manufacturing clusters. The shift is most visible in Minnesota and California where device OEM headquarters concentration supports on-site laboratory partnerships.
Aerospace and Life Science Testing Certification Market Segmentation
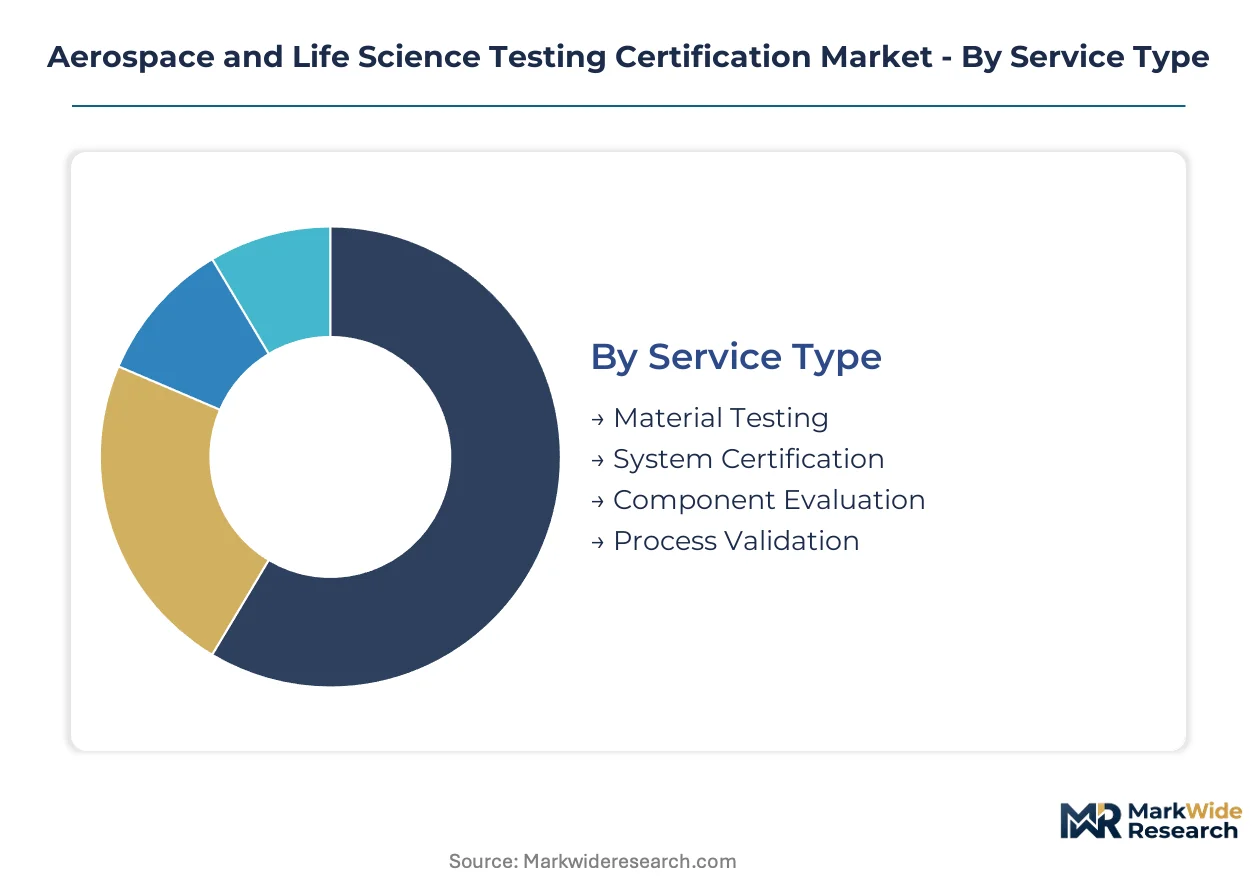
Testing providers structure service portfolios around distinct technical competencies and regulatory pathways. Segmentation clarity enables buyers to match validation requirements with laboratory specializations while revealing where certification complexity concentrates.
Service Type:
Technical sophistication and regulatory stringency define competitive positioning across service categories.
- Material Testing:Mechanical stress analysis, chemical composition profiling, and fatigue characterization of metals, composites, and polymers. Aerospace OEMs in Germany and France drive volume for composite airframe qualification under EASA CS-25 specifications.
- System Certification:Integrated validation of avionics, propulsion, and environmental control systems against airworthiness mandates. FAA Part 25 Amendment 25-146 retesting of fuel tank ignition protection is expanding contract volumes for legacy fleet electrical systems.
- Component Evaluation:Discrete part qualification spanning fasteners, sensors, and actuators to performance benchmarks. Medical device manufacturers in Massachusetts and Minnesota outsource biocompatibility and sterility validation for implantable components.
- Process Validation:Verification of manufacturing repeatability and quality system adherence. Cell therapy producers in North Carolina are contracting viral vector validation to CDMO-affiliated testing facilities.
Mature deployment sits with Material Testing. Newer deployment is concentrated in Process Validation.
Industry Vertical:
Regulatory architecture and product lifecycle length create divergent margin profiles across end-use sectors.
- Aerospace:Airframe, engine, and systems validation against FAA and EASA certification specifications. Commercial aviation OEMs are consolidating outsourced validation partnerships as airworthiness mandates tighten.
- Pharmaceuticals:Drug substance and product testing for FDA and EMA marketing authorization. REACH Annex XVII PFAS restrictions are forcing reformulation of excipients and packaging materials, triggering retesting cycles.
- Biotechnology:Cell and gene therapy process validation, viral safety testing, and biosimilar comparability studies. Massachusetts manufacturers are outsourcing vector validation to specialized facilities.
- Medical Devices:Premarket submission support, cybersecurity verification, and post-market surveillance. EU MDR software verification mandates for connected diagnostics are expanding contract volumes in Germany and Switzerland.
Established revenue concentration rests with Aerospace. Steepest expansion trajectory appears in Medical Devices.
Technology:
Instrumentation capital intensity and talent scarcity differentiate competitive viability across technical modalities.
- Mechanical Testing:Tensile, compression, fatigue, and fracture mechanics evaluation of structural materials. Wind tunnel testing faces displacement by computational fluid dynamics for certain aerodynamic profiles.
- Chemical Analysis:Mass spectrometry, chromatography, and spectroscopic methods for composition and contaminant detection. Helium supply concentration in Qatar and Algeria creates input cost volatility for leak detection applications.
- Environmental Testing:Thermal cycling, humidity exposure, vibration, and altitude simulation. Satellite component manufacturers are integrating digital twin architectures to compress physical test iterations.
- Software Verification:Algorithmic validation, cybersecurity assessment, and AI system conformity evaluation. EU AI Act high-risk system classification for medical imaging algorithms is creating a new validation category at the intersection of software and clinical performance testing.
Deep capability pools exist in Mechanical Testing. Capability building is accelerating fastest in Software Verification.
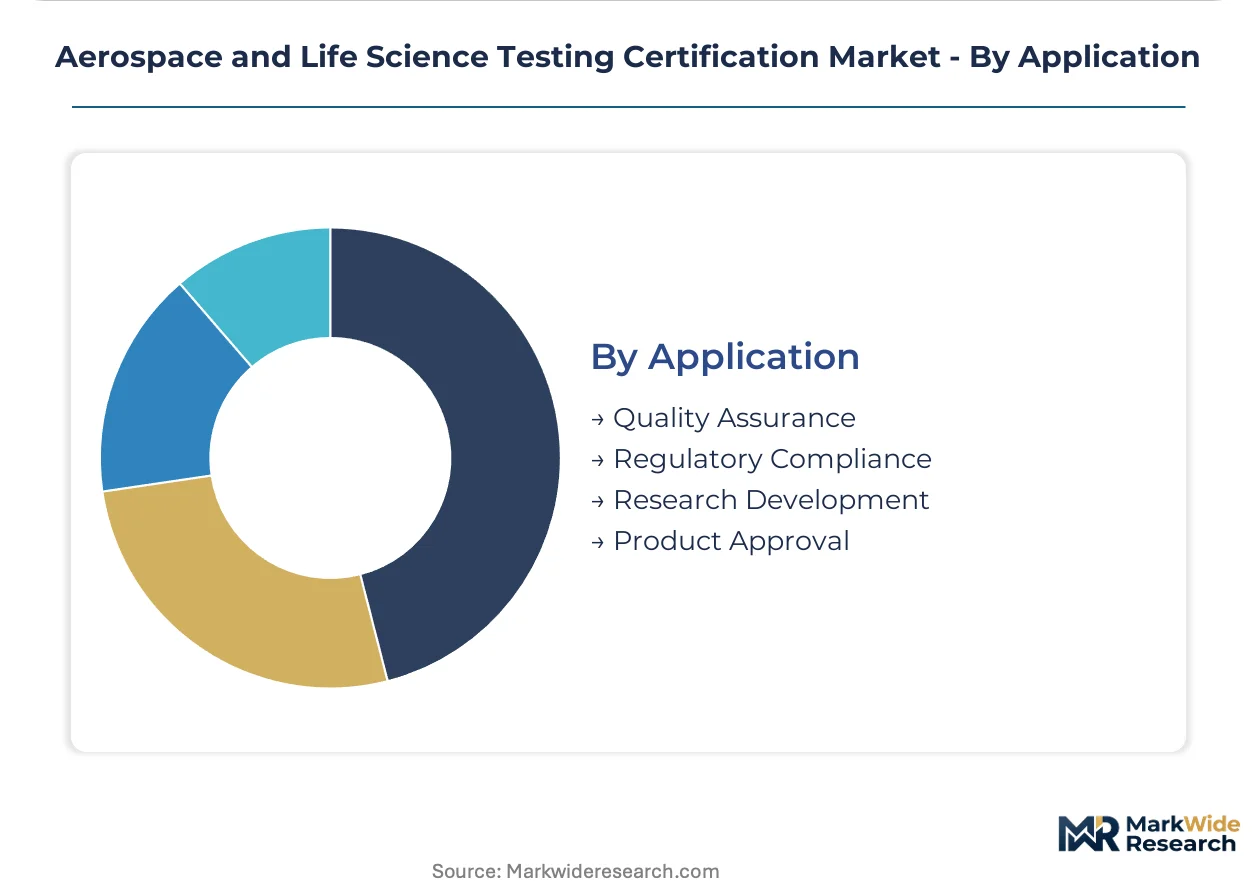
Application:
Procurement timing and documentation burden vary sharply across the validation workflow.
- Quality Assurance:In-process testing and supplier qualification to maintain manufacturing standards. AS9100D auditor scarcity is creating bottlenecks for aerospace quality management system certification.
- Regulatory Compliance:Formal submission support for FDA, EMA, and national regulator premarket approval. FDA 21 CFR Part 11 divergence from EMA Annex 11 implementation guides forces dual-track validation documentation.
- Research Development:Early-phase material characterization and prototype validation. Biotechnology firms are outsourcing viral vector validation during clinical scale-up.
- Product Approval:Final certification and market authorization documentation. EU MDR transition deadlines are extending time-to-market for pharmaceutical clients facing DAkkS accreditation backlogs.
Contract maturity centers on Quality Assurance. Procurement momentum is building strongest in Regulatory Compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing capacity concentrates in Germany and the United States while demand growth accelerates in Saudi Arabia and Switzerland. Production gravity favors established laboratory clusters with deep regulatory relationships.
Germany
TÜV SÜD and TÜV Rheinland anchor continental certification capacity for aerospace composites and pharmaceutical clients. EASA CS-25 airworthiness specifications and EU MDR transition deadlines drive contract volumes. Bavaria and North Rhine-Westphalia host concentrated laboratory infrastructure serving Airbus suppliers and medical device manufacturers.
United States
FAA Part 25 Amendment 25-146 retesting of fuel tank ignition systems creates aftermarket demand for legacy fleet electrical validation. FDA 21 CFR Part 11 electronic records requirements shape software verification procurement. Massachusetts and North Carolina biotechnology clusters outsource viral vector validation to specialized CDMO-affiliated facilities.
Switzerland
Swissmedic oversight of medical device premarket submissions attracts algorithmic validation contracts for connected diagnostics. EU AI Act high-risk system classification for medical imaging creates intersection demand between software verification and clinical performance testing. Basel and Zurich laboratories serve pharmaceutical headquarters concentration with proximity advantages.
Saudi Arabia
NEOM and Red Sea tourism aviation infrastructure generate greenfield airworthiness certification demand without incumbent provider saturation. General Authority of Civil Aviation modernization aligns with national giga-project timelines. Riyadh and the Eastern Province emerge as procurement origination points for imported testing services.
United Kingdom
MHRA post-Brexit regulatory autonomy diverges from EMA implementation guides, forcing dual-track validation documentation for global device submissions. CAA airworthiness mandates sustain aerospace testing relationships with Rolls-Royce and BAE Systems supply chains. Greater London and Midlands clusters concentrate laboratory capacity for pharmaceutical and defense applications.
Aerospace and Life Science Testing Certification Market Vendor Landscape
The competitive structure tilts toward diversified multi-sector networks over single-vertical specialists. Consolidated vendor qualification programs at Medtronic and Johnson & Johnson favor testing houses with bundled material, sterility, and software capabilities. Three archetypes dominate: pan-sector laboratory networks, aerospace-focused component evaluators, and pharmaceutical process validation specialists. M&A activity targets cybersecurity-capable laboratories and CDMO-affiliated testing facilities.
Within the diversified network tier, SGS leverages its multi-sector laboratory footprint to offer integrated compliance packages across geographies. Bureau Veritas anchors aerospace component evaluation through specialized technical depth. Intertek Group occupies a position at the software verification frontier, extending algorithmic validation into medical device cybersecurity protocols.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Intertek Group |
| TÜV SÜD |
| Element Materials Technology |
| TÜV Rheinland |
| Applus+ |
| Eurofins Scientific |
| DNV GL |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FAA Part 25 airworthiness validation and routine quality assurance testing manifests in divergent pricing power and supplier selection patterns. Premium-tier laboratories commanding EASA CS-25 accreditation capture margin premiums from Airbus and Boeing tier-1 suppliers, while commodity material testing faces procurement consolidation into preferred provider networks.
Pricing Analysis
Margin tightening in routine material testing reflects procurement consolidation by Medtronic and Johnson & Johnson into master service agreements bundling sterility, software, and mechanical validation. Three-tier pricing structure across accredited, pre-qualified, and spot-contract laboratory levels tracks certification depth and geographic proximity to manufacturing clusters. Cost-down pressure on environmental testing accelerates as digital twin simulation substitutes physical thermal cycling for satellite components. Medical device OEMs exhibit highest price sensitivity for software verification, while biotechnology viral vector validation shows inelastic demand due to CDMO capacity scarcity.
Supply Chain Analysis
Refurbishment flows for legacy aircraft electrical systems under FAA Part 25 Amendment 25-146 create aftermarket demand loops back to original testing providers. Laboratory capacity concentrates in Germany, Switzerland, and the United States, with TÜV SÜD and TÜV Rheinland anchoring European aerospace certification. Helium for mass spectrometry leak detection draws from Qatar and Algeria, exposing aerospace component testing to commodity allocation risk. Distribution runs through consolidated vendor qualification programs at headquarters-proximate facilities in Minnesota, Massachusetts, and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU MDR transition deadlines and AS9100D auditor scarcity will force sub-scale laboratories into strategic exits or acquisition over the projection horizon.
For Market Incumbents: Deploy cybersecurity capability acquisition to capture EU AI Act medical imaging algorithm validation contracts before specialized entrants establish footholds. Backward integration into CDMO-affiliated testing facilities in North Carolina and Massachusetts secures viral vector validation volume. Reinforce positioning through DAkkS accreditation investment to clear German pharmaceutical backlog bottlenecks. For New Entrants and Emerging Players: Enter via Saudi Arabia giga-project procurement channels for NEOM aviation infrastructure certification, bypassing incumbent saturation in European markets. White-space concentration sits with AI Act conformity assessment at the software-clinical performance intersection. Target Swissmedic-connected diagnostic algorithm validation through Basel-proximate laboratory partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with cybersecurity-capable laboratories given EU AI Act enforcement timeline acceleration. Long-term viability favors multi-sector networks with aerospace and pharmaceutical dual-certification depth. Monitor DAkkS accreditation queue clearance rates as inflection indicator for German market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Capability Acquisition | Captures EU AI Act medical imaging algorithm validation contracts before competition hardens. |
| CDMO Testing Facility Integration | Secures viral vector validation volume from Massachusetts and North Carolina cell therapy manufacturers. |
| Saudi Arabia Market Entry | Positions for NEOM and Red Sea tourism aviation infrastructure greenfield certification demand. |
| DAkkS Accreditation Investment | Clears German pharmaceutical client backlog and accelerates EU MDR compliance timelines. |
| Digital Twin Platform Development | Reduces physical prototype iterations for satellite component manufacturers integrating predictive certification. |
Methodological Framework
Document review covered EASA certification specifications, FDA 21 CFR Part 11 guidance, and EU MDR implementing acts, complemented by interviews with laboratory operations directors, aerospace quality managers, pharmaceutical regulatory affairs leads, and CDMO procurement officers. Secondary validation drew from FAA airworthiness directive filings, DAkkS accreditation registers, and Swissmedic premarket submission databases. Bottom-up service line modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-level outputs reflect disaggregation by service type, industry vertical, technology modality, and application workflow, with regional splits calibrated to laboratory capacity concentration in Germany, the United States, Switzerland, and Saudi Arabia. CAGRs derive from regression analysis of historical certification contract volumes against regulatory mandate implementation schedules. Forecast inputs incorporate EU AI Act enforcement timeline assumptions and helium supply concentration risk premiums.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA rulemaking or ECHA PFAS restriction escalation. Practitioners should monitor DAkkS queue lengths, helium allocation announcements from Qatar, and EU AI Act delegated act publication for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Mono Rapid Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Global Sterility Testing Market
Testing Services
Osmometer Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Retrovirus Testing Market
Testing Services
Allergy Skin Test Market