
 US C-Reactive Protein Testing Market | 2026-2036
US C-Reactive Protein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US C-Reactive Protein Testing Market Insights
US diagnostic reagent manufacturers is pivoting toward high-sensitivity CRP formats as health systems demand lower detection thresholds. Abbott Laboratories leverages its installed immunoassay base to sustain recurring consumable revenue across hospital networks. Thermo Fisher Scientific anchors its position through R&D intensity in multiplexed inflammation panels. Siemens Healthineers competes on manufacturing scale, dominating the mid-tier lab segment with standardized turbidimetric platforms.
C-reactive protein testing quantifies acute-phase inflammation via blood serum or plasma analysis, typically detecting concentrations below 0.3 mg/L in high-sensitivity configurations for cardiovascular risk prediction. Immunoturbidimetry leads the technology dimension due to throughput compatibility with core laboratory analyzers, while point-of-care devices represent the fastest-growing product type as urgent care networks decentralize testing. Cardiovascular risk assessment commands the largest application share, though autoimmune condition monitoring offers concentrated margin pools in specialty clinic settings.
FDA 510(k) pathways and CLIA complexity classifications shape product development priorities, with moderate-complexity waivers expanding addressable sites for point-of-care formats. The Centers for Medicare and Medicaid Services reimbursement schedules directly influence lab purchasing decisions for standardized versus high-sensitivity assay menus. Stakeholders must monitor pending FDA guidance on combined inflammation biomarker panels and evolving CMS coverage determinations for preventive cardiovascular screening protocols.
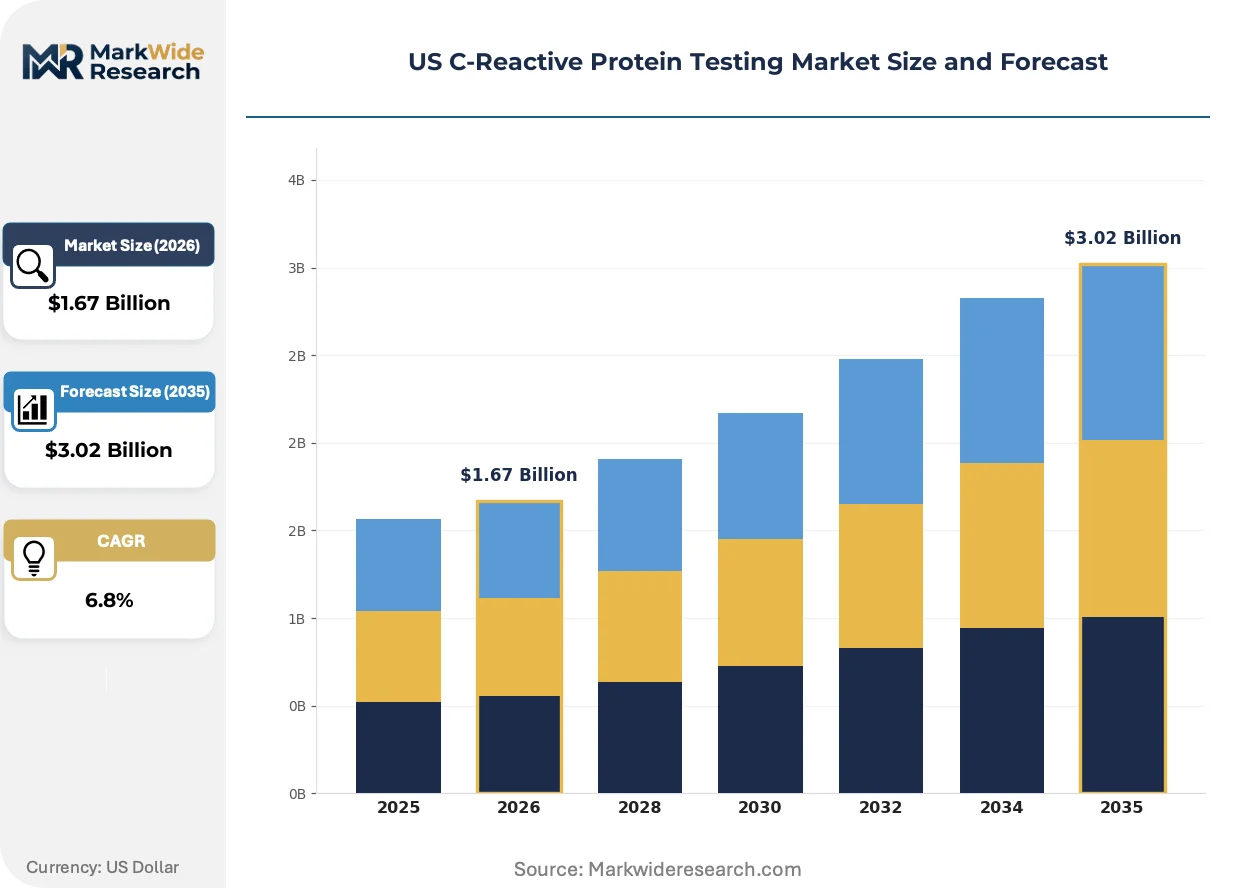
Market Dynamics
Hospital laboratories across the US are consolidating reference testing contracts under integrated delivery networks, compressing vendor margins while demanding higher-sensitivity assay formats for cardiovascular risk stratification.
Growth Catalysts
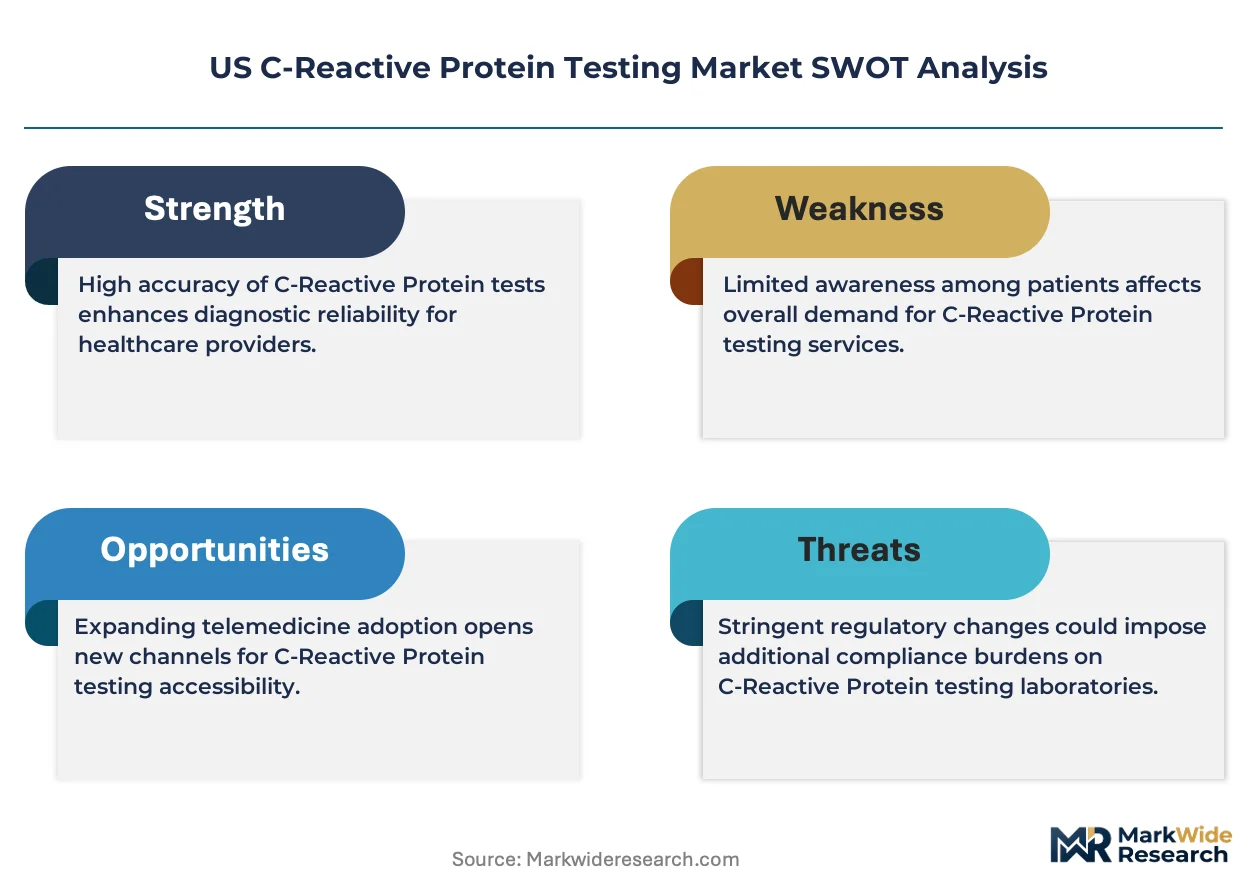
- FDA 510(k) Pathway Acceleration:Streamlined clearance timelines for high-sensitivity CRP assays are reducing time-to-market for new diagnostic entrants, expanding competitive supply.
- Cardiovascular Risk Stratification Protocols:Clinical guidelines from the American College of Cardiology are embedding hs-CRP into standard preventive screening workflows across hospital networks.
- Northeast Corridor IDN Consolidation:Integrated delivery networks in Massachusetts, New York, and Pennsylvania are standardizing on centralized lab platforms with multi-year consumable agreements.
Market Restraints
- Reagent Input Concentration:Purified antibody supplies for CRP immunoassays concentrate among a limited set of specialized bioreagent manufacturers, creating price volatility exposure.
- CLIA Moderate-Complexity Barriers:Point-of-care devices face restricted site eligibility under Clinical Laboratory Improvement Amendments complexity classifications, limiting decentralized deployment.
- Alternative Biomarker Substitution:Lipoprotein-associated phospholipase A2 and myeloperoxidase assays are capturing cardiovascular risk assessment share in specialty lipid clinics.
Strategic Opportunities
- Autoimmune Condition Monitoring:Rheumatology and immunology specialty clinics represent concentrated margin pools for high-frequency CRP monitoring in lupus and rheumatoid arthritis management.
- Multiplexed Inflammation Panels:Technology convergence between CRP, procalcitonin, and interleukin-6 detection is enabling single-sample sepsis and infection workups in emergency departments.
- CMS Preventive Screening Expansion:Pending coverage determinations for cardiovascular risk assessment in asymptomatic populations would unlock Medicare-reimbursed testing volumes.
Industry Challenges
- Legacy Analyzer Integration Complexity:Hospital laboratories face technical friction connecting new high-sensitivity assay modules to installed immunoassay platforms without full system replacement.
- Specialized Technologist Shortage:Core laboratory operations require trained personnel for quality control and calibration of turbidimetric systems, constraining testing expansion in rural health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US C-Reactive Protein Testing Market |
| Market Size in 2026 | $1.67 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Sensitivity CRP Kits, Standard CRP Assays, Point-of-Care Devices, ELISA Kits Technology: Immunoturbidimetry, Nephelometry, Enzyme-Linked Immunosorbent Assay, Latex Agglutination Application: Cardiovascular Risk Assessment, Infection Diagnosis, Inflammatory Disorders, Autoimmune Condition Monitoring End User: Diagnostic Laboratories, Specialty Clinics, Research Institutions, Blood Testing Centers |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Thermo Fisher Scientific, Siemens Healthineers, Danaher Corporation, Quest Diagnostics, Laboratory Corporation of America Holdings, Merck KGaA, Randox Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US C-Reactive Protein Testing Market Trends and Innovations
Diagnostic manufacturers are racing to compress detection thresholds while urgent care networks decentralize testing infrastructure, reshaping how inflammation biomarkers reach clinical decision-makers.
Immunoturbidimetry is consolidating its position as the dominant detection methodology for high-throughput CRP analysis in hospital core laboratories. Large health systems with installed analyzer bases from major vendors are standardizing on this format to maximize consumable pull-through and minimize reagent switching costs. The technology is consolidating vendor market power by locking laboratories into proprietary cartridge ecosystems with multi-year service contracts.
FDA guidance on combined inflammation biomarker panels is forcing diagnostic developers to redesign regulatory submission strategies for multiplexed assays. The agency's evolving stance on analytical validation requirements for multi-analyte claims is extending premarket timelines for novel platforms. Moderate-complexity point-of-care manufacturers are responding by pursuing 510(k) clearances for single-parameter CRP devices ahead of more complex submissions.
Integrated delivery networks are consolidating reference lab contracts under regional purchasing agreements that specify minimum annual testing volumes. Independent reference laboratories are losing access to health system accounts as IDNs centralize spend under exclusive vendor relationships. This concentration is most visible in the Northeast corridor, where Massachusetts General Brigham and Northwell Health have standardized on single-source CRP testing agreements.
US C-Reactive Protein Testing Market Segmentation
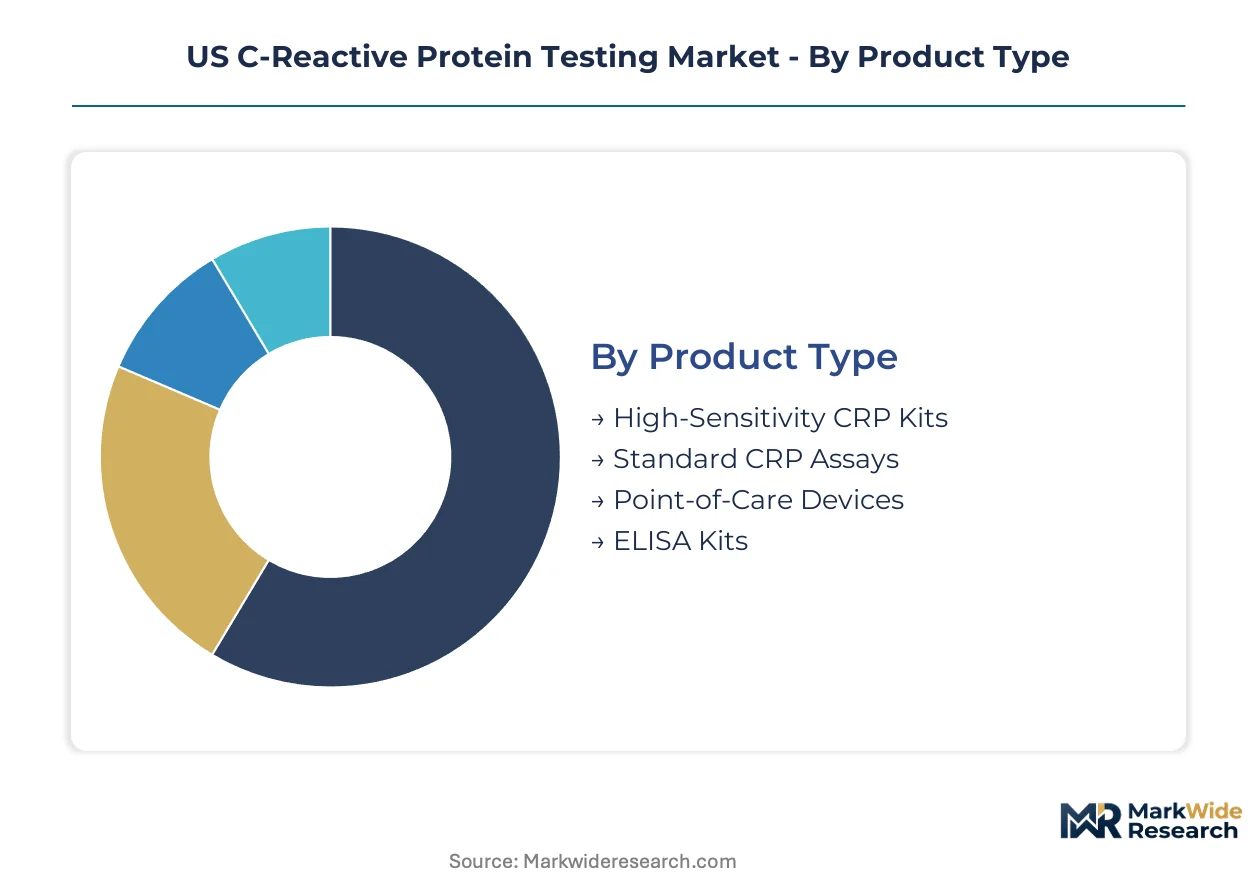
Segmentation in the US C-Reactive Protein Testing Market reveals how hospital laboratories prioritize assay formats during analyzer refresh cycles. Procurement committees weigh detection threshold requirements against installed base compatibility when consolidating vendor contracts under integrated delivery networks.
Product Type:
Hospital laboratories in Massachusetts, New York, and Pennsylvania are driving replacement cycles toward high-sensitivity formats as cardiovascular risk stratification protocols tighten detection requirements.
- High-Sensitivity CRP Kits:Detect concentrations below 0.3 mg/L using enhanced antibody specificity and signal amplification chemistry. Demand concentrates in Northeast corridor IDNs where ACC guidelines mandate hs-CRP for preventive screening workflows.
- Point-of-Care Devices:Portable analyzers deliver results within 15 minutes using fingerstick whole blood samples. Urgent care networks in Texas and Florida are decentralizing testing infrastructure to reduce core lab turnaround times.
- Standard CRP Assays:Turbidimetric platforms measuring 0.5-10 mg/L ranges dominate legacy analyzer installations in rural health systems.
- ELISA Kits:Research-grade formats with batch processing capabilities serve academic medical centers conducting longitudinal inflammation studies.
High-Sensitivity CRP Kits sit at the top of the volume ranking, with Point-of-Care Devices climbing the fastest.
Technology:
Cost tiering separates high-throughput hospital core laboratories from mid-tier facilities managing constrained capital budgets.
- Immunoturbidimetry:Dominates throughput-compatible detection using antigen-antibody complex light scattering. Large health systems with Abbott and Siemens installed bases lock into proprietary cartridge ecosystems spanning multi-year service agreements.
- Nephelometry:Measures forward-scattered light at 90-degree angles for enhanced sensitivity in low-concentration samples. Specialty reference laboratories in California deploy these systems for autoimmune panel multiplexing.
- Enzyme-Linked Immunosorbent Assay:Microplate-based quantification serves research institutions requiring customizable antibody pair configurations.
- Latex Agglutination:Visual endpoint detection persists in resource-limited settings and veterinary crossover applications.
Immunoturbidimetry commands the largest installed base, while Nephelometry gains share fastest among specialty laboratories.
Application:
Margin concentration varies sharply across clinical use cases, with cardiovascular protocols reimbursing at preventive care rates versus autoimmune monitoring at specialty tiers.
- Cardiovascular Risk Assessment:Quantifies systemic inflammation for 10-year ASCVD risk calculation. Hospital networks in Pennsylvania and New York embed hs-CRP into annual physical workflows for hypertensive patient populations.
- Autoimmune Condition Monitoring:Tracks disease activity in lupus and rheumatoid arthritis patients requiring monthly CRP surveillance. Rheumatology clinics in Massachusetts generate concentrated margin pools through high-frequency testing protocols.
- Infection Diagnosis:Differentiates bacterial from viral etiologies in emergency department triage protocols.
- Inflammatory Disorders:Monitors treatment response in inflammatory bowel disease and vasculitis management.
Cardiovascular Risk Assessment leads absolute volume, with Autoimmune Condition Monitoring expanding most quickly in specialty clinic settings.
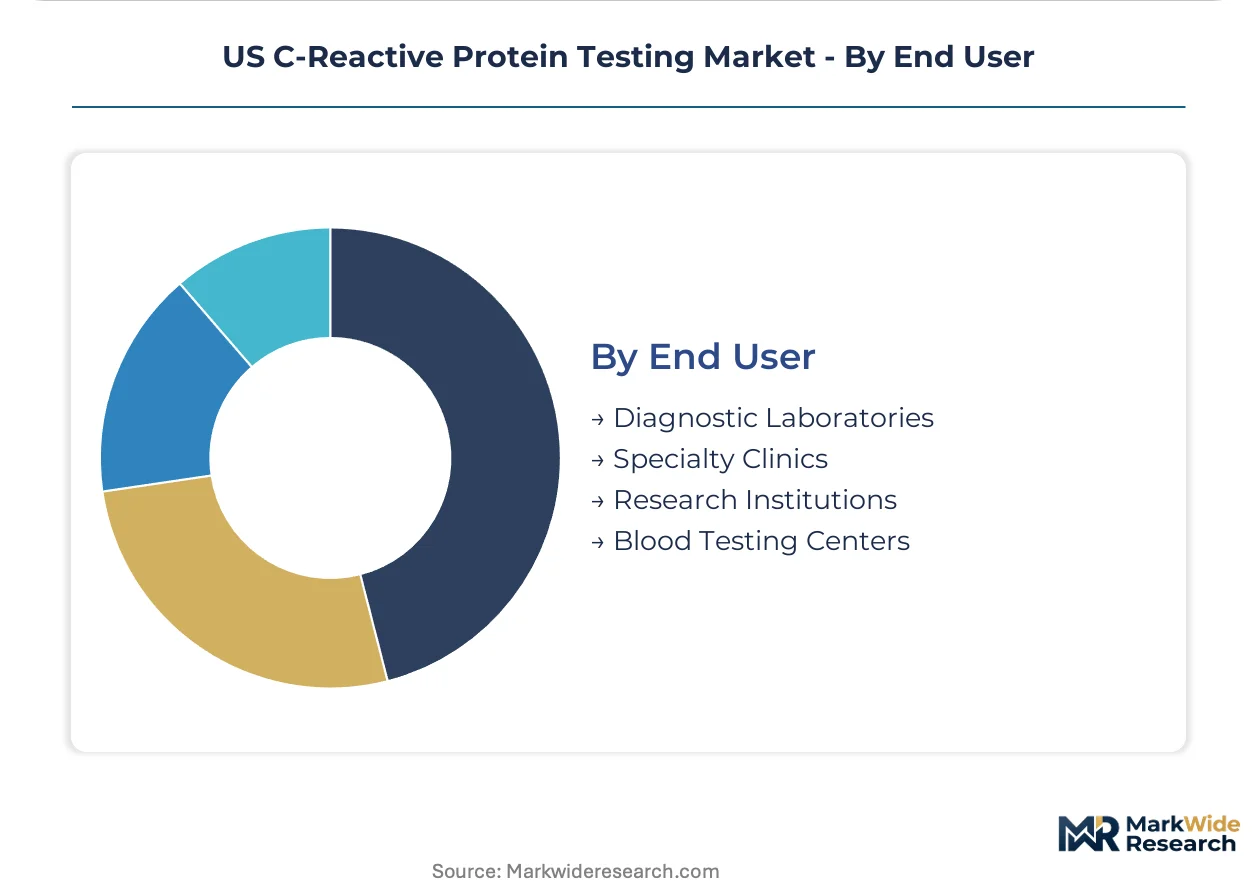
End User:
Customer type determines purchasing authority complexity, with IDN central procurement offices dictating terms versus independent specialty clinics negotiating directly.
- Diagnostic Laboratories:Core hospital and reference labs process 70-plus percent of US CRP testing volume under standardized turbidimetric platforms. Quest Diagnostics and LabCorp regional facilities anchor national testing infrastructure.
- Specialty Clinics:Rheumatology and cardiology practices in urban markets deploy point-of-care devices for same-day clinical decision-making. These sites prioritize moderate-complexity waived formats under CLIA regulations.
- Blood Testing Centers:Commercial phlebotomy networks in retail settings perform screening panels for wellness program enrollees.
- Research Institutions:Academic medical centers validate novel biomarker correlations in longitudinal cohort studies.
Diagnostic Laboratories dominate procurement scale, with Specialty Clinics driving the steepest expansion trajectory as decentralized testing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in CRP testing concentrate manufacturing investment in jurisdictions with streamlined FDA 510(k) pathways and favorable CLIA complexity classifications. Production gravitates toward states with established diagnostic reagent clusters and dense hospital network procurement offices.
Northeast Corridor
Massachusetts General Brigham and Northwell Health anchor integrated delivery network consolidation, standardizing high-sensitivity CRP protocols under multi-year consumable agreements. FDA 510(k) clearance timelines compress as Boston-area developers leverage proximity to agency reviewers. The Greater Boston biotech corridor hosts specialized antibody suppliers serving turbidimetric platform manufacturers.
Mid-Atlantic States
Pennsylvania hospital networks embed hs-CRP into hypertensive patient annual physical workflows, driving assay volume concentration. CMS reimbursement schedules for preventive cardiovascular screening directly influence Philadelphia and Pittsburgh lab purchasing committees. The Philadelphia metropolitan area concentrates reference laboratory infrastructure under Quest Diagnostics and LabCorp regional facilities.
Texas
Urgent care networks in Dallas-Fort Worth and Houston decentralize point-of-care CRP testing to reduce core laboratory turnaround times. CLIA moderate-complexity waivers expand addressable sites for fingerstick whole blood analyzers in retail clinic settings. The Texas Medical Center anchors specialty clinic demand for autoimmune condition monitoring in lupus and rheumatoid arthritis management.
California
Specialty reference laboratories in Los Angeles and San Francisco deploy nephelometry systems for autoimmune panel multiplexing with enhanced sensitivity. The state's Department of Public Health oversees clinical laboratory licensing that shapes point-of-care device deployment eligibility. Stanford and UCSF academic medical centers validate novel biomarker correlations in longitudinal inflammation cohort studies.
Florida
Commercial phlebotomy networks in Miami and Tampa perform screening panels for wellness program enrollees, expanding blood testing center volume. Medicare Advantage penetration rates in the state drive demand for preventive cardiovascular risk assessment protocols. The Orlando medical corridor concentrates rheumatology specialty clinics generating high-frequency CRP monitoring revenue pools.
US C-Reactive Protein Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care decentralization and multiplexed inflammation panels. The market structure reflects tiered consolidation around installed immunoassay bases and consumable lock-in contracts. Three archetypes dominate: diversified conglomerates with analyzer platforms, specialized reagent manufacturers with antibody expertise, and reference laboratory operators with captive testing volume. Competitive moves center on multi-year service contract extensions and regulatory pathway acceleration for moderate-complexity waived formats.
Among diversified diagnostic conglomerates, Abbott Laboratories and Siemens Healthineers exemplify the installed-base leverage archetype, anchoring hospital network relationships through proprietary cartridge ecosystems. Thermo Fisher Scientific occupies a position representing the R&D-intensive reagent specialist tier. These three entities collectively illustrate how market power concentrates around analyzer compatibility and recurring consumable revenue rather than discrete test kit sales alone.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Danaher Corporation |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Merck KGaA |
| Randox Laboratories |
| Others |
Pricing and Supply Chain Analysis
Captive antibody production within specialized bioreagent manufacturers anchors both supply security and pricing power for high-sensitivity CRP assays. This backward integration into purified monoclonal antibody supply insulates incumbent diagnostic conglomerates from raw material volatility while enabling premium positioning against reagent-switching costs.
Pricing Analysis
Distributor margin compression runs through the Northeast corridor IDN procurement offices, where multi-year consumable agreements lock laboratories into proprietary cartridge ecosystems. Three-tier pricing structure across premium hs-CRP, standard turbidimetric, and economy latex agglutination levels reflects FDA clearance tier and detection threshold performance. Pricing pressure stems from reference lab contract consolidation under Massachusetts General Brigham and Northwell Health purchasing committees. Independent rural health systems exhibit highest price sensitivity due to constrained capital budgets, while specialty rheumatology clinics absorb premium pricing for same-day point-of-care results.
Supply Chain Analysis
Dual-sourcing requirements from Quest Diagnostics and LabCorp regional facilities mandate multi-supplier qualification for purified CRP antibody lots, reducing single-source vulnerability. Geographic supply concentration centers on the Greater Boston biotech corridor for specialized antibody development, with manufacturing scale in Pennsylvania and Illinois for turbidimetric platform assembly. Raw material dependencies include affinity-purified monoclonal antibodies, polystyrene latex particles, and signal amplification chemiluminescent substrates. Tariff exposure on Chinese-sourced diagnostic plastics creates supply chain risk for point-of-care device housings. Distribution runs through GPO contracts managed by Vizient and Premier to hospital network central procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US C-Reactive Protein Testing Market represents a late-cycle quality story where demand gravitates toward hs-CRP formats with sub-0.3 mg/L detection thresholds as cardiovascular risk stratification protocols tighten clinical standards.
For Market Incumbents: To counter point-of-care decentralization by urgent care networks, extend multi-year service contracts with installed-base analyzer lock-in and accelerate moderate-complexity CLIA waiver submissions for fingerstick whole blood formats. Prioritize R&D investment in multiplexed inflammation panels combining CRP, procalcitonin, and interleukin-6 detection to defend reference lab volume against sepsis-triage substitution. For New Entrants and Emerging Players: Launch via direct-to-specialty-clinic distribution models targeting rheumatology practices in Texas and Florida with moderate-complexity waived devices bypassing GPO contract barriers. White-space concentration exists in autoimmune condition monitoring for lupus and rheumatoid arthritis patients requiring monthly CRP surveillance, where incumbent turbidimetric platforms lack same-day turnaround capability. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized bioreagent manufacturers possess captive antibody expertise but lack analyzer platform integration. Long-term viability favors targets with FDA-cleared hs-CRP assays and installed base conversion potential in mid-tier hospital laboratories. Watch pending CMS coverage determinations for preventive cardiovascular screening in asymptomatic populations as the inflection signal for Medicare-reimbursed volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for hs-CRP Assay | Accelerates market entry through streamlined premarket clearance pathways for cardiovascular risk applications. |
| Hospital System Partnership Agreement | Locks multi-year consumable revenue through integrated delivery network exclusive vendor relationships. |
| Moderate-Complexity CLIA Waiver Pursuit | Expands addressable sites for point-of-care deployment in urgent care and specialty clinic settings. |
| Multiplexed Inflammation Panel Development | Captures emergency department sepsis-triage volume through single-sample CRP-procalcitonin-IL-6 detection. |
| Reimbursement Strategy for Preventive Screening | Aligns assay menu design with pending CMS coverage determinations for asymptomatic cardiovascular risk assessment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, GPO contracts managers, diagnostic reagent procurement leads, and FDA regulatory affairs specialists with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement schedules, hospital procurement databases, and CLIA complexity classification records. Bottom-up testing volume estimates triangulated against top-down market sizing from installed analyzer base counts and consumable pull-through assumptions.
Comparable historical periods anchored the forecast window to analyzer replacement cycle timing and guideline adoption trajectories across the projection horizon. Segmentation modeling incorporated product type, detection technology, clinical application, and end-user facility tier dimensions. CAGRs derived from regression analysis of testing volume growth against hs-CRP protocol penetration rates and point-of-care decentralization trends. Industry-specific inputs included CLIA waiver expansion timelines and IDN contract consolidation velocity.
Several conditions sit outside the modeled scope, including specific FDA guidance issuance dates on combined inflammation biomarker panels and exact CMS national coverage determination schedules. Forecasts reflect assumptions about cardiovascular risk stratification protocol adoption and urgent care network expansion. Deviation in CLIA moderate-complexity waiver approval timelines or alternative biomarker substitution rates in specialty lipid clinics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Platelet Function Test Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Global Sterility Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Thyroid Test Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Allergy Skin Test Market