
 Influenza a/B Combo Testing Market | 2026-2036
Influenza a/B Combo Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza a/B Combo Testing Market Analytics
Fluorophore-labeled antibody conjugates are recalibrating cost structures in rapid influenza diagnostics by reducing reader-device complexity. Abbott Laboratories leverages integrated molecular-immunoassay platforms to sustain differentiation across hospital and clinic channels. F. Hoffmann-La Roche Ltd anchors high-throughput laboratory demand with automated sample-to-answer systems. QuidelOrtho Corporation specializes in lateral-flow chemistry that occupies the urgent-care segment with sub-15-minute turnaround specifications.
Influenza A/B combo testing denotes simultaneous detection of influenza A and influenza B viral antigens or nucleic acids within a single assay cartridge or strip, typically employing monoclonal antibodies against conserved nucleoproteins or reverse-transcriptase polymerase chain reaction with dual-primer sets targeting matrix and hemagglutinin genes. The primary purpose centers on differential diagnosis during respiratory illness surges, enabling clinicians to rule in or rule out influenza while guiding antiviral prescribing decisions and infection-control protocols. PCR Tests command premium positioning in hospital laboratories where sensitivity thresholds below 100 copies per milliliter justify longer turnaround times and higher reagent costs. Point-of-Care Testing represents the fastest-expanding delivery mode as retail health clinics and pharmacy chains deploy waived-complexity devices under Clinical Laboratory Improvement Amendments guidelines. Home Testing remains nascent but draws development investment from manufacturers seeking direct-to-consumer channels beyond institutional procurement cycles.
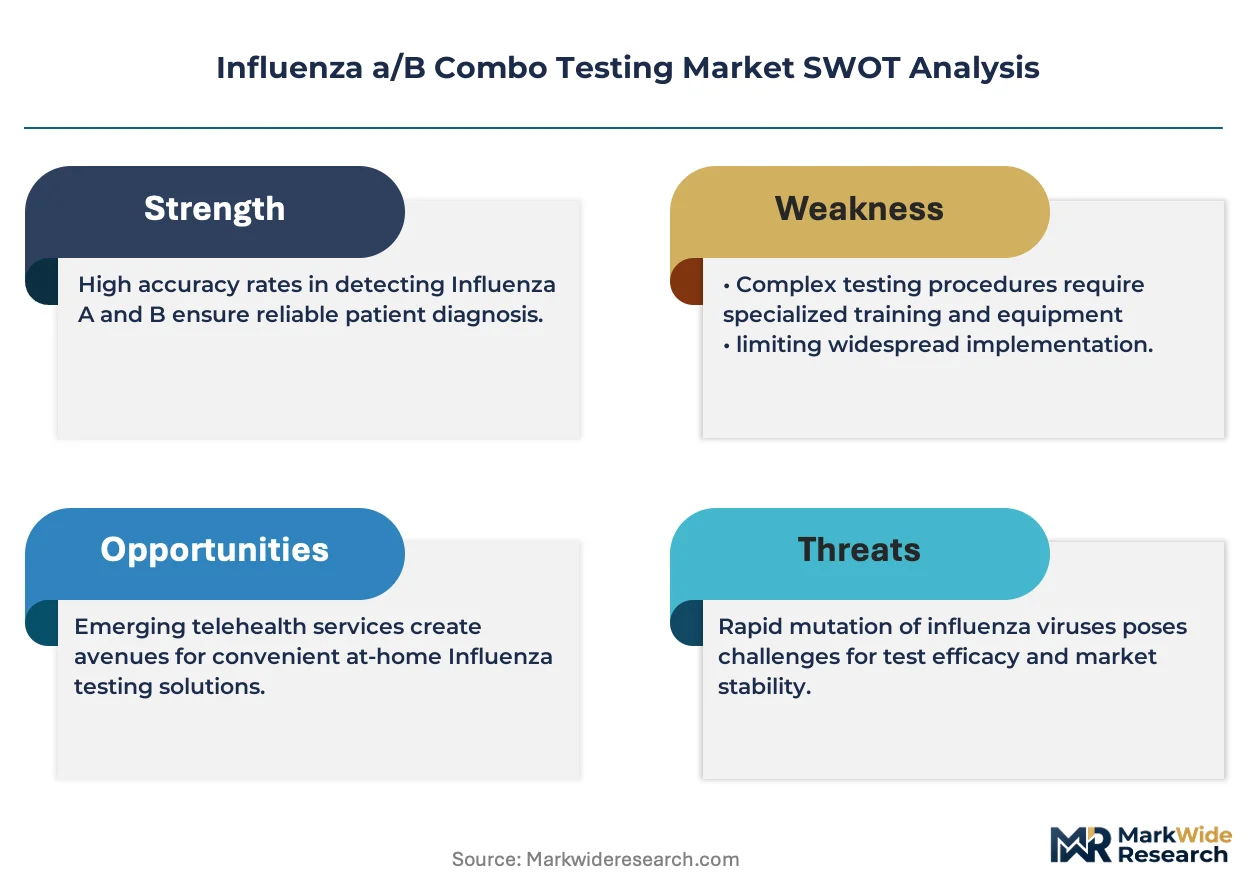
The FDA regulates influenza combo assays through premarket notification and emergency use authorization pathways, while the Clinical Laboratory Improvement Amendments program governs site-specific test complexity classifications that determine where devices may operate. The Centers for Medicare and Medicaid Services reimbursement schedules under the Clinical Laboratory Fee Schedule directly influence hospital laboratory purchasing committees and point-of-care capital allocation decisions. Stakeholders must monitor whether upcoming FDA guidance on over-the-counter respiratory multiplex tests opens home-testing segments or sustains clinic-based gatekeeping models.
Market Dynamics
Decentralized diagnostic workflows are compressing traditional laboratory testing volumes as health systems deploy waived-complexity devices to retail clinics and pharmacy chains, fundamentally restructuring where influenza A/B combo testing occurs and who controls patient access.
Growth Catalysts
- CLIA-waived device expansion:The Clinical Laboratory Improvement Amendments program enables non-laboratory sites to operate rapid influenza diagnostics, pulling testing volume from hospital core labs into urgent care and retail health settings.
- Antiviral stewardship mandates:Hospital infection-control protocols now require pathogen-specific diagnosis before neuraminidase inhibitor administration, institutionalizing dual-target assay procurement.
- Multiplex respiratory panel integration:Simultaneous detection of SARS-CoV-2, RSV, and influenza antigens within single cartridge formats is expanding test menu utility and justifying capital investment.
Market Restraints
- Reagent cost volatility:Fluorophore-labeled antibody conjugates and specialized polymerase enzymes concentrate supply among three contract manufacturers, exposing assay producers to input price shocks.
- Sensitivity-performance tradeoffs:Lateral-flow immunochromatography platforms detect viral loads above 10^5 copies per milliliter, generating false-negative rates that limit adoption in immunocompromised patient populations.
- Reimbursement compression:The Clinical Laboratory Fee Schedule reduces point-of-care test compensation annually, squeezing margin structures for waived-complexity device operators.
Strategic Opportunities
- Over-the-counter home testing authorization:FDA guidance on direct-to-consumer respiratory multiplex assays would unlock pharmacy retail channels beyond institutional procurement cycles.
- Telehealth-integrated result reporting:Bluetooth-enabled readers transmitting encrypted results to electronic health records platforms enable remote clinical oversight of home testing.
- Seasonal workforce surge protocols:Employer onsite clinics represent an underpenetrated channel for rapid influenza screening during Q4-Q1 peak transmission periods.
Industry Challenges
- Cross-reactivity elimination:Monoclonal antibody specificity against conserved nucleoproteins requires continuous strain surveillance and reagent reformulation to prevent rhinovirus interference.
- Legacy laboratory information system integration:Point-of-care devices must map to HL7 FHIR standards for seamless data transmission, extending deployment timelines and requiring specialized health informatics talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza a/B Combo Testing Market |
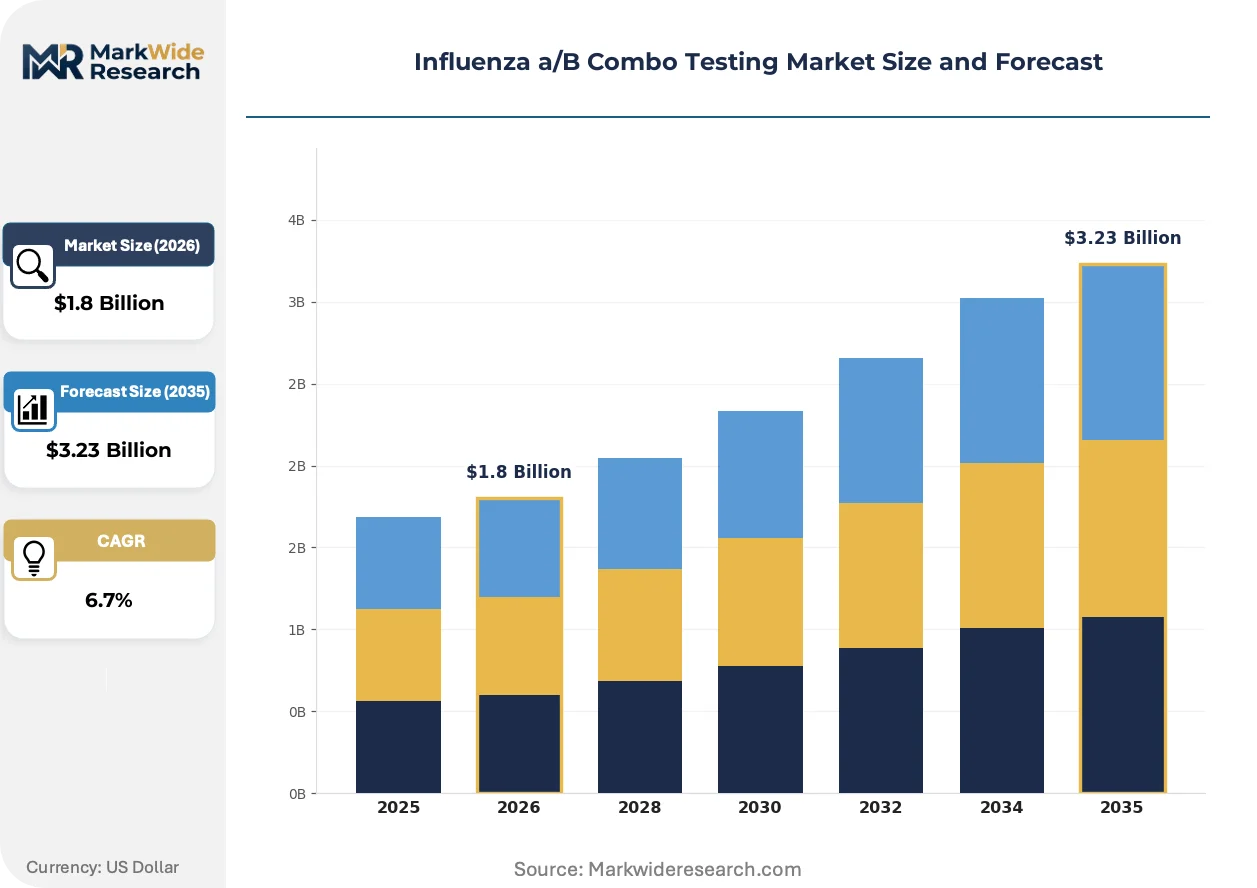
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Tests, Rapid Tests, Antigen Tests, Serology Tests Delivery Mode: Laboratory Testing, Point-of-Care Testing, Home Testing, Mobile Testing End User: Hospitals, Clinics, Laboratories, Urgent Care Centers Application: Diagnostic Testing, Surveillance, Epidemiological Studies, Research |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Becton Dickinson and Company, QuidelOrtho Corporation, Thermo Fisher Scientific, Hologic Inc, Meridian Bioscience, Sekisui Diagnostics, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza a/B Combo Testing Market Evolving Landscape
Molecular miniaturization and regulatory pathway evolution are converging to relocate influenza diagnostic authority from centralized laboratories to distributed care settings, compressing turnaround times and altering capital deployment patterns across the supply chain.
Isothermal nucleic acid amplification technology is decentralizing influenza A/B detection by eliminating thermal cycling hardware requirements. Urgent care chains and pharmacy-based clinics are adopting these battery-operated platforms at accelerating rates. The technology is decentralizing test authority from hospital laboratory directors to retail clinic staff with minimal training.
FDA emergency use authorization pathway refinements for multiplex respiratory panels are compressing product development timelines. Manufacturers now submit combined influenza-COVID-RSV assays under streamlined review procedures. Point-of-care device segments benefit most, with waived-complexity designations expanding eligible test sites.
Hospital purchasing committees now bundle influenza A/B combo assays into seasonal respiratory preparedness contracts rather than ad hoc ordering. Group purchasing organizations aggregate demand across health system networks, displacing individual laboratory procurement autonomy. This concentration is most visible in United States integrated delivery networks negotiating multi-year supply agreements.
Influenza a/B Combo Testing Market Segmentation
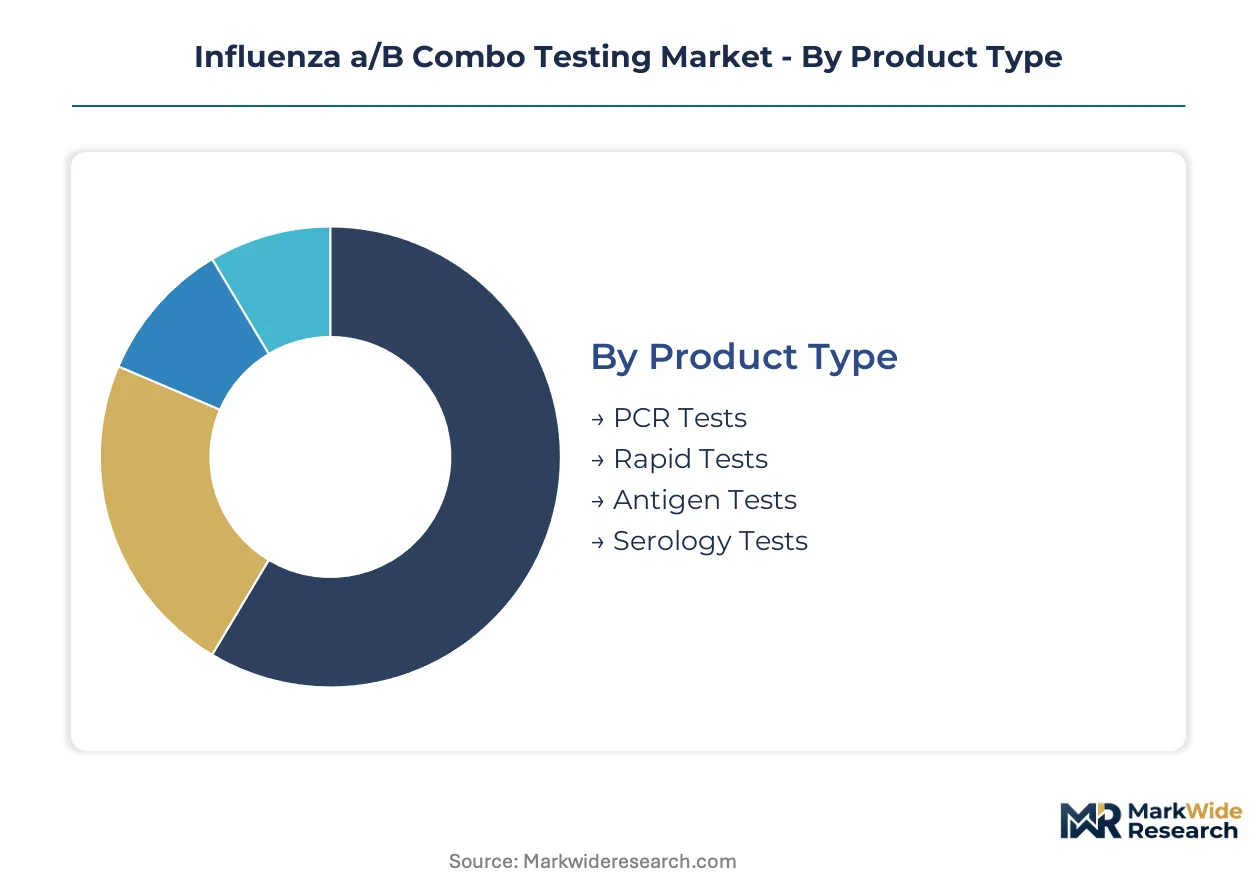
Segmentation in influenza A/B combo testing reveals how procurement authority, clinical workflow requirements, and regulatory complexity reshape vendor-customer relationships. Understanding these divides clarifies why PCR platforms command hospital capital budgets while lateral-flow strips dominate retail clinic shelves.
Product Type:
Hospital laboratory directors weigh sensitivity thresholds against capital expenditure cycles when selecting assay formats.
- PCR Tests:Nucleic acid amplification platforms detect viral loads below 100 copies per milliliter using reverse-transcriptase polymerase chain reaction with dual-primer sets targeting matrix and hemagglutinin genes. United States hospital core laboratories concentrate demand here, driven by antiviral stewardship mandates requiring pathogen-specific diagnosis before neuraminidase inhibitor administration.
- Rapid Tests:Lateral-flow immunochromatography strips deliver qualitative results within 15 minutes through monoclonal antibody binding to conserved nucleoproteins. United States urgent care chains and pharmacy clinics prioritize these CLIA-waived devices, pulled by reimbursement compression that favors lower-cost point-of-care alternatives over laboratory send-outs.
- Antigen Tests:Direct viral protein detection assays trade sensitivity for speed and operational simplicity.
- Serology Tests:Antibody detection platforms identify past infection rather than active viral shedding.
PCR Tests lead on scale; Rapid Tests lead on momentum.
Delivery Mode:
Site-of-care regulations determine where devices may legally operate and who captures the patient encounter.
- Point-of-Care Testing:Waived-complexity devices operate under Clinical Laboratory Improvement Amendments guidelines in non-laboratory settings, enabling retail health clinics and pharmacy chains to perform diagnostics without laboratory director oversight. United States retail health expansion concentrates demand here, fueled by health system strategies to decompress emergency department volumes during respiratory surges.
- Laboratory Testing:Moderate- and high-complexity assays require certified laboratory personnel and controlled environments for sample processing. United States hospital integrated delivery networks sustain procurement volumes through seasonal preparedness contracts that aggregate demand across multi-facility networks.
- Home Testing:Direct-to-consumer formats bypass institutional procurement entirely, pending FDA authorization pathways for over-the-counter respiratory multiplex assays.
- Mobile Testing:Deployable units serve temporary screening needs at employer sites, schools, or mass gathering events.
Laboratory Testing maintains installed base dominance; Point-of-Care Testing gains share fastest.
End User:
Capital allocation authority and patient volume patterns fragment the customer base across distinct procurement cultures.
- Hospitals:Infection-control committees and laboratory medicine departments coordinate dual-target assay procurement through group purchasing organizations, bundling influenza testing into broader respiratory preparedness contracts rather than standalone orders.
- Urgent Care Centers:Retail clinic operators prioritize sub-15-minute turnaround specifications to maintain patient throughput during peak transmission periods.
- Clinics:Primary care and specialty practices balance diagnostic certainty against operational constraints.
- Laboratories:Independent reference laboratories and hospital-affiliated core labs compete on test menu breadth and turnaround time guarantees.
Hospitals anchor procurement volume; Urgent Care Centers drive format innovation.
Application:
Intended use case shapes sensitivity requirements, documentation standards, and reimbursement eligibility.
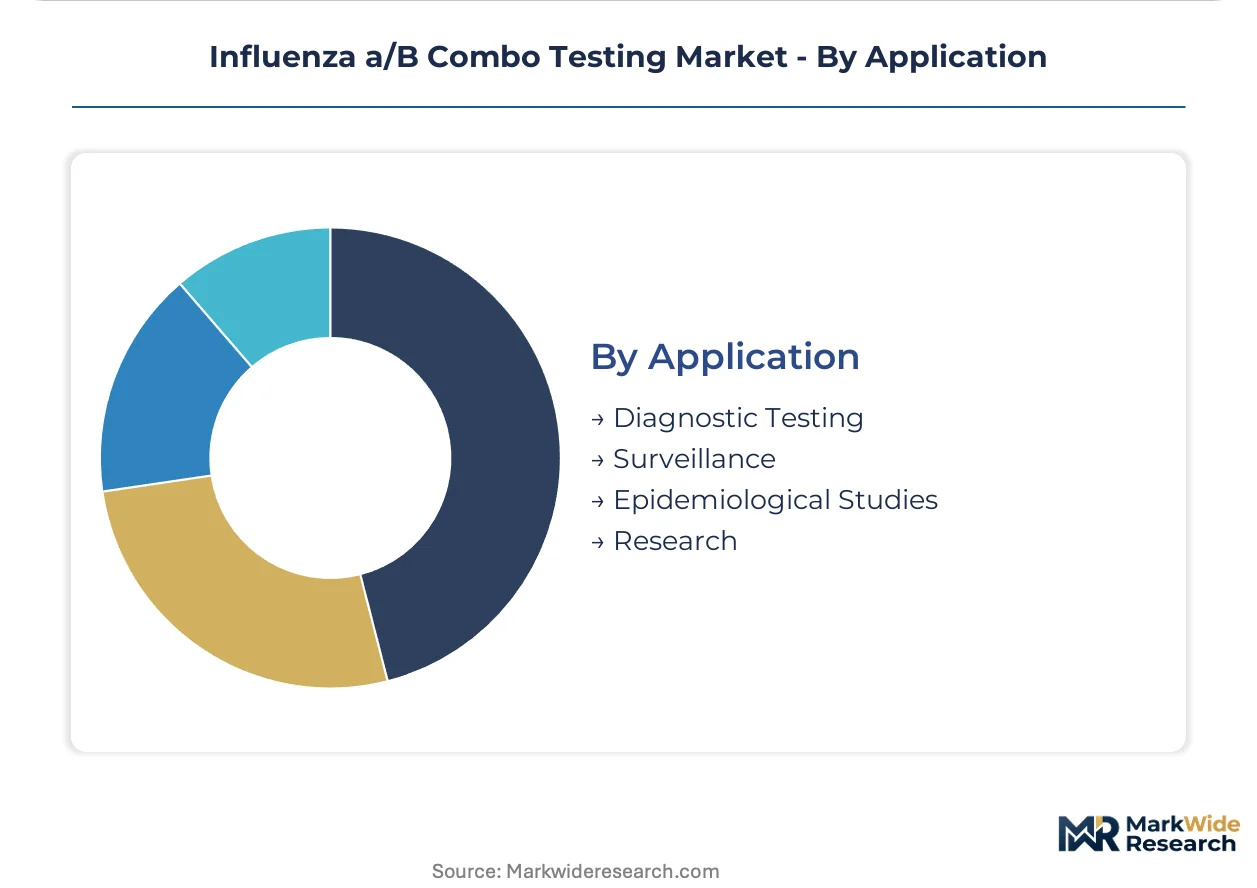
- Diagnostic Testing:Individual patient management applications require definitive pathogen identification to guide antiviral prescribing decisions and isolation protocols. United States emergency departments and inpatient units concentrate demand, compelled by Joint Commission standards for infection prevention.
- Surveillance:Population-level monitoring applications aggregate anonymized results to track strain circulation and antigenic drift patterns. United States public health laboratories coordinate this demand through CDC cooperative agreements.
- Epidemiological Studies:Research protocols generate data on transmission dynamics and vaccine effectiveness.
- Research:Academic and commercial investigators employ combo assays for assay development and clinical validation studies.
Diagnostic Testing commands revenue concentration; Surveillance expands most quickly with federal funding infusions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor concentrates influenza diagnostic R&D activity, drawing venture capital toward multiplex respiratory assay development. Health system consolidation across mature economies is reshaping procurement geography toward integrated delivery networks.
United States
Hospital preparedness mandates and seasonal immunization programs sustain dual-target assay procurement volumes. FDA emergency use authorization pathways for multiplex respiratory panels compress product development timelines. The Boston-Cambridge corridor anchors molecular diagnostic innovation, with point-of-care device manufacturers clustering around regulatory expertise.
Germany
Automated laboratory infrastructure investments drive demand for high-throughput sample-to-answer systems. CE marking under EU Medical Device Regulation governs market entry for combo assay platforms. The Rhine-Main biotech cluster around Frankfurt supports reagent manufacturing scale-up for European distribution.
Japan
Aging demographics and hospital infection-control protocols institutionalize rapid influenza screening. PMDA consultation pathways guide manufacturers through seasonal strain update requirements. The Kanto region around Tokyo concentrates diagnostic device engineering and health informatics integration capabilities.
China
Expanding retail health clinic networks pull testing volume toward decentralized point-of-care formats. NMPA regulatory reforms accelerate review timelines for waived-complexity respiratory devices. The Yangtze River Delta manufacturing base supplies fluorophore-labeled antibody conjugates to global assay producers.
India
Pharmacy chain expansion and telehealth integration create new channels for rapid diagnostic distribution. CDSCO streamlined approval mechanisms for WHO-prequalified in vitro diagnostics reduce market entry friction. The Hyderabad-Genome Valley cluster specializes in monoclonal antibody production for lateral-flow chemistry.
Influenza a/B Combo Testing Market Competitive Landscape
Global majors compete with regional champions across regulatory access and channel reach, producing a tiered structure where scale-driven conglomerates anchor hospital laboratory contracts while mid-cap specialists capture retail clinic volumes. Three archetypes dominate: integrated life science conglomerates with molecular-immunoassay platform breadth; lateral-flow chemistry specialists with waived-complexity device expertise; and contract manufacturers supplying critical reagents to branded assay producers. Competitive moves center on multiplex respiratory panel portfolio expansion and point-of-care device geographic registration.
Among integrated diagnostic conglomerates, Abbott Laboratories and F. Hoffmann-La Roche Ltd exemplify platform-scale positioning across hospital and laboratory channels. QuidelOrtho Corporation occupies a specialist position within the rapid-testing tier, representing the urgent-care segment focus that prioritizes sub-15-minute turnaround specifications. These three entities anchor distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton Dickinson and Company |
| QuidelOrtho Corporation |
| Thermo Fisher Scientific |
| Hologic Inc |
| Meridian Bioscience |
| Sekisui Diagnostics |
| bioMérieux |
| Others |
Value Network & Pricing Analysis
Monoclonal antibody engineering talent concentration in the Boston-Cambridge corridor and Hyderabad-Genome Valley drives labor-cost differentials that widen pricing-tier spreads between premium PCR platforms and economy lateral-flow strips.
Pricing Analysis
Input-cost pass-through from fluorophore-labeled antibody conjugates and specialized polymerase enzymes concentrates pricing power among three contract manufacturers. Pricing stratifies across premium, standard, and economy tiers based on sensitivity thresholds and CLIA complexity classification. Cost compression in the rapid-test segment is intensifying because reimbursement compression under the Clinical Laboratory Fee Schedule squeezes point-of-care operators. Pharmacy chains and urgent care centers exhibit highest price sensitivity; hospital integrated delivery networks prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for monoclonal antibodies and fluorophore conjugates mandate multi-supplier qualification among assay producers seeking to mitigate single-source vulnerability. Manufacturing concentrates in China, the United States, and India, with the Yangtze River Delta supplying antibody conjugates and Hyderabad specializing in lateral-flow chemistry. Raw material dependencies center on recombinant protein production, specialized polymerases, and nitrocellulose membranes. Tariff exposure on Chinese-sourced reagents creates margin volatility. Distribution runs through group purchasing organizations for hospital networks and direct wholesale for retail clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where antiviral stewardship mandates and infection-control protocols pull procurement toward premium-sensitivity PCR platforms over commodity rapid tests.
For Market Incumbents: Acquire isothermal amplification technology platforms to neutralize the threat from battery-operated molecular devices decentralizing test authority. Secure backward integration into fluorophore-labeled antibody production to defend margin position against reagent cost volatility. Anchor hospital laboratory contracts through multi-year respiratory preparedness bundles that displace standalone ordering. For New Entrants and Emerging Players: Capture employer onsite clinic channels during Q4-Q1 peak transmission periods, the most penetrable white-space segment currently served by ad hoc occupational health vendors. Target telehealth-integrated result reporting as the go-to-market angle, leveraging Bluetooth-enabled readers for remote clinical oversight of home testing protocols. For Investors and Strategic Acquirers: Integrated diagnostic conglomerates with molecular-immunoassay platform breadth are the most active acquirers in this space, consolidating lateral-flow specialists to complete point-of-care portfolios. Long-term viability hinges on multiplex respiratory panel authorization pathways expanding test menu utility. Watch FDA guidance on over-the-counter respiratory multiplex assays as the inflection indicator unlocking direct-to-consumer channels.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emergency Use Authorization Pathway | Streamlined review procedures compress product development timelines for multiplex respiratory panels. |
| CLIA-Waived Device Expansion | Non-laboratory site eligibility pulls testing volume from hospital core labs into retail settings. |
| Hospital System Partnership | Group purchasing organization contracts aggregate demand across multi-facility integrated delivery networks. |
| Reimbursement Strategy | Clinical Laboratory Fee Schedule navigation determines point-of-care capital allocation decisions. |
| Software Companion Development | HL7 FHIR standard integration enables seamless electronic health record transmission from point-of-care devices. |
Research Methodology
Multiple input streams — regulatory filing analysis, procurement database mining, and clinical workflow observation — were reconciled through bottom-up and top-down triangulation. Primary interviews with hospital laboratory directors, CLIA-waived device operators, GPO contracts managers, and biomedical engineers were validated against secondary sources including FDA 510(k) and EUA submissions, CMS Clinical Laboratory Fee Schedule archives, and hospital procurement records.
Historical volume trajectories were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and application. CAGRs were derived from regression analysis against seasonal immunization coverage rates and hospital preparedness mandate adoption curves.
Regulatory pathway delays, strain antigenic drift requiring reagent reformulation, and reimbursement schedule revisions are the dominant revision risks to modeled outputs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Specimen Validity Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Outsourced Testing Services Market
Testing Services
Phenytoin Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Global GI Stool Testing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
INR Test Meter Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Osmometer Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Gastrointestinal Testing Panels Market