
 At-Home Celiac Testing Market | 2026-2036
At-Home Celiac Testing Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Celiac Testing Market Analytics
Fragmentation among first-time diagnostic buyers across suburban and rural ZIP codes is repositioning channel strategy toward pharmacy partnerships and telehealth-integrated platforms. Everlywell leverages its direct-to-consumer brand infrastructure to sustain recurring revenue from subscription-based screening programs. LetsGetChecked competes through clinician-backed result interpretation that anchors trust among symptomatic but undiagnosed users. NanoRepro AG specializes in European regulatory compliance, occupying a distinct position through CE-marked lateral flow formats.
At-home celiac testing encompasses immunochromatographic and enzymatic assay systems designed for self-administered detection of tissue transglutaminase antibodies or gluten peptides in capillary blood, stool, or saliva specimens, with sensitivity thresholds typically calibrated to clinical laboratory equivalence for screening purposes. Lateral flow assays dominate unit volume due to shelf stability and minimal operator training, while molecular diagnostics segments command premium positioning through HLA-DQ2/DQ8 genotyping capabilities that exclude rather than confirm disease. Online retail channels capture the fastest-growing transaction flow as pharmacy benefit managers and employer wellness programs integrate these SKUs into preventive care stipends.
FDA regulates these products as in vitro diagnostics or laboratory-developed tests depending on analyte complexity, while CLIA certification requirements govern result validity for physician-acceptable documentation. The EU In Vitro Diagnostic Regulation imposes notified body oversight on self-testing devices, compressing market access timelines for non-CE-marked entrants. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for apps that interpret home test results, as this determination will reshape competitive moats between instrument manufacturers and digital health platforms.
Market Dynamics
Direct-to-consumer diagnostic platforms are compressing traditional laboratory channels by embedding telehealth interpretation and automated result delivery into self-testing workflows. This channel bypass is restructuring how undiagnosed symptomatic populations access celiac screening, forcing incumbent clinical laboratories to reposition toward hybrid service models.
Growth Catalysts
- CLIA-waived lateral flow certification:The FDA's streamlined pathway for waived complex testing enables pharmacy shelf placement without prescription requirements, expanding point-of-sale access in United States retail chains.
- Employer wellness program integration:Large self-insured employers in North America are adding at-home celiac panels to preventive care stipends, capturing asymptomatic screening demand among covered populations.
- Salivary IgA detection chemistry:Enzymatic assay advances eliminate fingerstick requirements, reducing activation friction for pediatric and needle-averse demographic segments.
Market Restraints
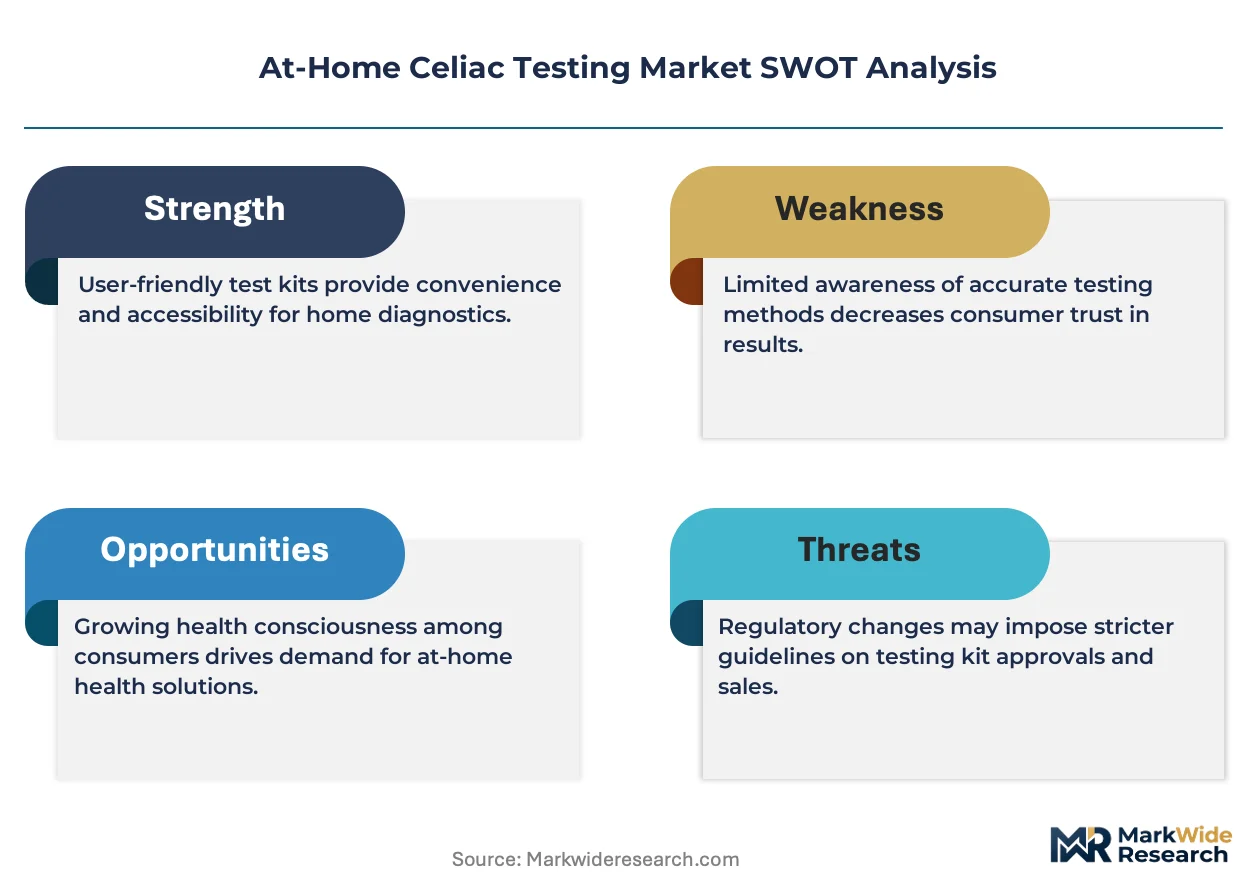
- Antibody test specificity ceilings:Tissue transglutaminase assays generate false positives in diabetes and autoimmune thyroid conditions, necessitating confirmatory endoscopy that undermines home-testing value propositions.
- European notified body backlog:The EU In Vitro Diagnostic Regulation's centralized conformity assessment creates 18-24 month approval delays for novel self-test formats, freezing market entry timelines.
- Gluten-free diet pre-test interference:Patient-initiated dietary elimination before screening suppresses serological markers, producing misleading negative results that erode clinical confidence in home-based detection.
Strategic Opportunities
- HLA-DQ2/DQ8 genetic exclusion testing:Cheek swab genotyping that rules out celiac susceptibility addresses the large symptomatic-negative population currently cycling through repeat serological screens.
- Subscription-based monitoring programs:Annual re-testing subscriptions for diagnosed celiac patients tracking dietary compliance create recurring revenue streams beyond one-time diagnostic purchases.
- Telehealth-integrated result platforms:Automated routing of positive home test results to gastroenterology networks for expedited biopsy scheduling captures care coordination value currently lost to fragmented follow-up.
Industry Challenges
- Software-as-medical-device classification uncertainty:FDA guidance ambiguity around algorithmic result interpretation apps creates compliance risk for platforms automating test-to-diagnosis pathways.
- Capillary blood volume standardization:Variable fingerstick technique across self-administered specimens produces insufficient sample volumes, triggering retest requests that degrade user experience and increase service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Celiac Testing Market |
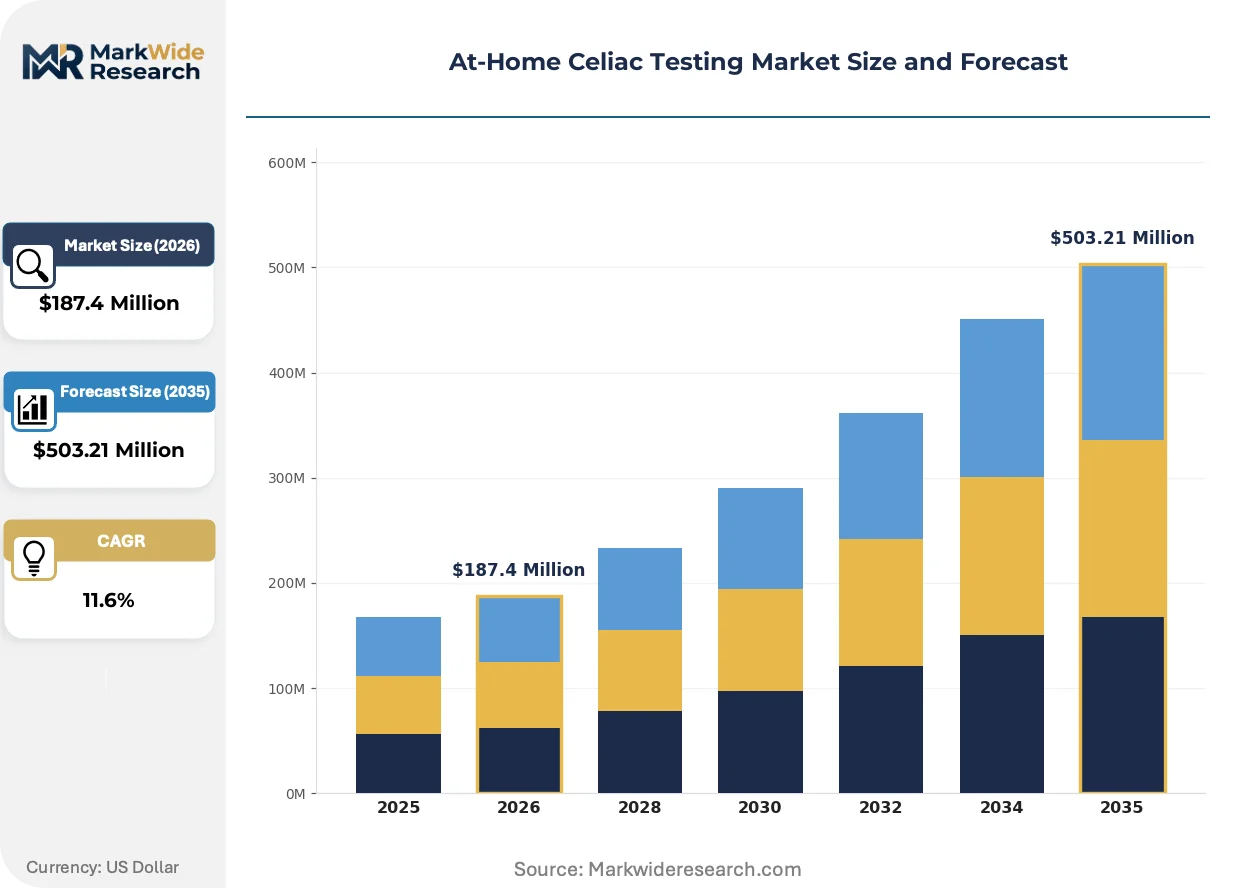
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Diagnostic Devices, Sample Collection Tools, Reagents Technology: Lateral Flow Assays, ELISA, Molecular Diagnostics, Immunoassays End User: Home Users, Healthcare Professionals, Laboratories, Research Institutions Distribution Channel: Online Retail, Pharmacies, Direct Sales, Healthcare Providers |
| Companies Covered | PRIMA Lab SA, Glutenostics Inc., NanoRepro AG, myLAB Box, Everlywell, LetsGetChecked, RxHomeTest, Targeted Genomics, Genovate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Celiac Testing Market Evolving Landscape
Multiplex biomarker detection is converging with smartphone-based image analysis to transform lateral flow devices from binary screening tools into quantitative diagnostic instruments. These convergent capabilities are compressing the gap between home-administered and laboratory-grade result precision.
Fluorescent nanoparticle conjugates are absorbing the sensitivity limitations of traditional colloidal gold lateral flow systems in celiac antibody detection. Direct-to-consumer brands adopting this substrate report quantitative titer correlation with ELISA reference methods. The technology is absorbing market share from enzymatic colorimetric formats in premium self-test segments.
The EU In Vitro Diagnostic Regulation's performance evaluation requirements are forcing manufacturers to generate clinical evidence from European populations rather than extrapolating United States trial data. This regulatory shift is segmenting product registrations by geography and creating parallel certification tracks. Smaller developers without dedicated European regulatory affairs capacity are withdrawing from CE-marked self-test categories.
Consumers with undiagnosed gluten sensitivity are bypassing primary care gatekeepers entirely, purchasing screening tests through e-commerce platforms before presenting results to clinicians. This behavior pattern is fragmenting the traditional diagnostic sequence and pressuring gastroenterology practices to develop rapid-confirmation protocols. The shift is most visible in United States metropolitan markets with established telehealth infrastructure and high digital health literacy indices.
At-Home Celiac Testing Market Segmentation
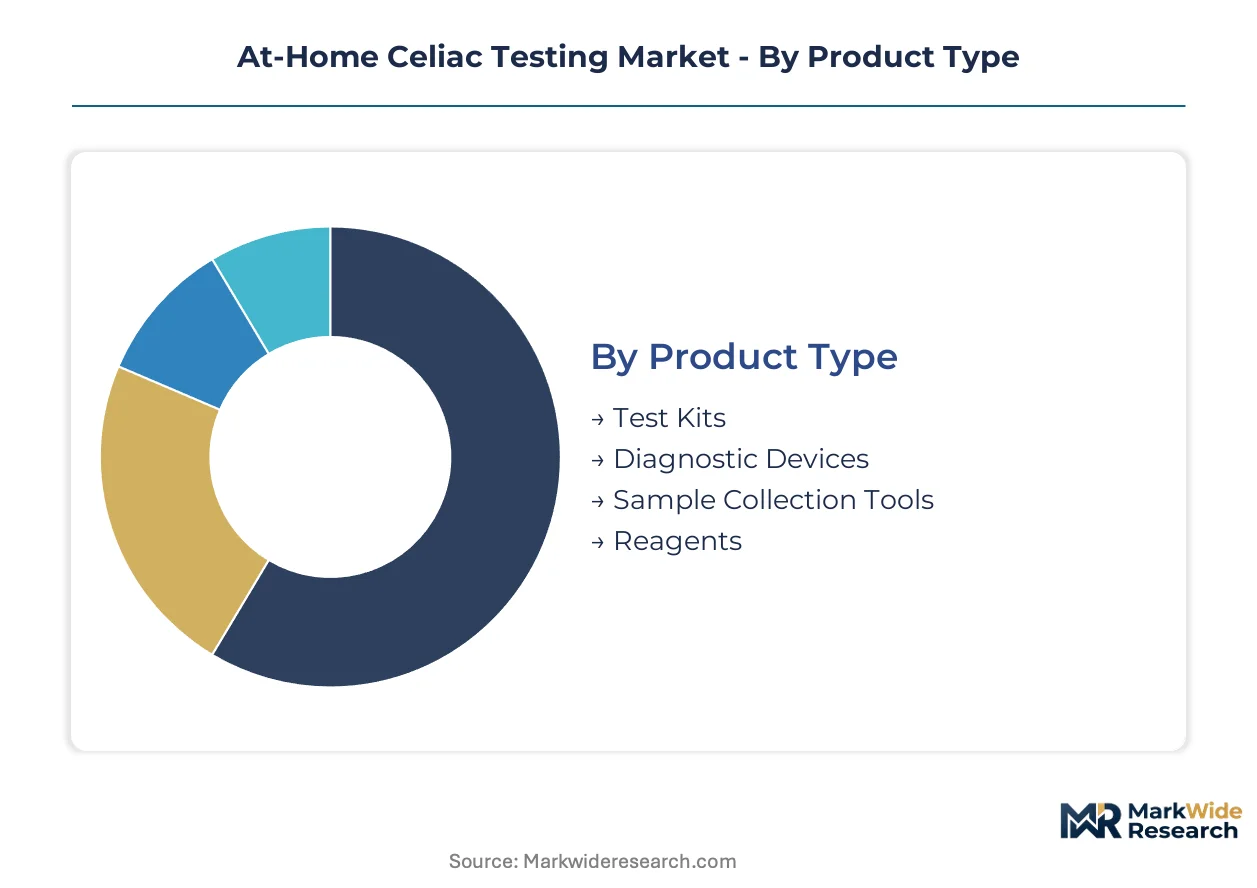
Segmentation in at-home celiac testing reveals how technology choices, channel access, and user sophistication fragment commercial opportunity. Manufacturers must align product specifications with distinct purchasing behaviors across self-directed consumers and institutional buyers.
Product Type:
Buyer differentiation in this category hinges on technical confidence and repeat testing frequency rather than price sensitivity alone.
- Test Kits:Pre-configured lateral flow cassettes with buffer solutions and collection accessories dominate unit economics through shelf-stable formats and minimal cold chain requirements. Demand clusters in United States suburban households with prior direct-to-consumer diagnostic experience, driven by pharmacy benefit manager coverage expansion. Lateral Flow Assays lead volumes today; Molecular Diagnostics is gaining share fastest.
- Diagnostic Devices:Smartphone-connected readers with quantitative fluorescence detection elevate result precision for users requiring titer tracking. Concentrated among employer wellness program enrollees in metropolitan markets with established telehealth infrastructure.
- Sample Collection Tools:Capillary blood lancets, saliva collection tubes, and stool specimen containers sold as standalone accessories for repeat monitoring protocols.
- Reagents:Enzyme conjugates and substrate solutions for user-initiated test replenishment, primarily serving diagnosed celiac patients on gluten-free diet compliance tracking programs.
Test Kits lead volumes today; Diagnostic Devices is gaining share fastest.
Technology:
Performance tier and regulatory pathway diverge sharply across detection chemistries, reshaping margin structures and geographic access.
- Lateral Flow Assays:Immunochromatographic strips using colloidal gold or fluorescent nanoparticle conjugates for IgA-tTG detection, optimized for ambient storage and untrained operator use. Volume concentrates in United States retail pharmacy chains leveraging CLIA-waived certification for over-the-counter placement.
- ELISA:Microplate-based enzymatic detection requiring laboratory-grade pipetting and incubation timing, positioned for healthcare professional oversight with higher analytical sensitivity.
- Molecular Diagnostics:HLA-DQ2/DQ8 genotyping via cheek swab extraction excludes celiac susceptibility rather than confirming active disease, commanding premium pricing in genetic counseling-integrated channels.
- Immunoassays:Broad category encompassing chemiluminescent and electrochemiluminescent platforms migrating from clinical laboratory formats into simplified home-use configurations.
Lateral Flow Assays lead volumes today; Molecular Diagnostics is climbing the fastest.
End User:
Channel strategy and result interpretation support requirements separate four distinct user archetypes with incompatible service expectations.
- Home Users:Self-directed consumers purchasing through e-commerce or pharmacy without clinical referral, requiring embedded telehealth routing for positive result follow-up. Concentrated in United States urban markets with high digital health literacy indices.
- Healthcare Professionals:Primary care and gastroenterology practices utilizing point-of-care formats for rapid screening before endoscopy referral, demanding CLIA-waived status for in-office administration.
- Laboratories:Reference and hospital-affiliated labs processing home-collected specimens through mail-in programs, requiring chain-of-custody documentation and automated result reporting integration.
- Research Institutions:Academic medical centers and population health studies employing standardized self-testing protocols for celiac prevalence surveillance and dietary intervention trials.
Home Users lead volumes today; Healthcare Professionals is expanding most quickly.
Distribution Channel:
Physical versus digital access patterns determine brand discovery mechanics and subscription attach rates for recurring revenue models.
- Online Retail:Direct-to-consumer platforms and marketplace listings capturing symptom-driven search traffic with automated subscription replenishment for monitoring programs. Dominant in metropolitan United States markets with same-day or two-day fulfillment infrastructure.
- Pharmacies:Chain and independent drugstore placement leveraging CLIA-waived status for prescription-free purchase, with pharmacist consultation as trust anchor for first-time diagnostic buyers.
- Direct Sales:Manufacturer-owned websites with bundled telehealth interpretation services, bypassing retail margin extraction for higher lifetime value capture.
- Healthcare Providers:Clinic-dispensed or prescribed formats with insurance pre-authorization, serving employer wellness program channels and value-based care networks.
Online Retail leads volumes today; Pharmacies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers purchase at-home celiac tests at triple the per-capita rate of German buyers, reflecting divergent healthcare access models and direct-to-consumer diagnostic maturity. Digital health infrastructure and employer wellness program penetration explain much of this transatlantic gap.
United States
Employer wellness stipends and pharmacy benefit manager coverage expansion drive suburban household adoption. FDA CLIA-waived certification pathways enable over-the-counter placement in retail chains without prescription requirements. The Dallas-Fort Worth metroplex anchors a cluster of telehealth-integrated diagnostic platforms routing positive results to gastroenterology networks.
Germany
High undiagnosed celiac prevalence among adult populations sustains demand for self-administered screening tools. The EU In Vitro Diagnostic Regulation imposes notified body oversight with 18-24 month conformity assessment timelines. Munich-based regulatory affairs consultancies specialize in CE-marked lateral flow format submissions for self-test categories.
United Kingdom
NHS waiting list pressures push symptomatic consumers toward private direct-to-consumer channels for expedited screening. MHRA alignment with EU MDR post-Brexit maintains stringent performance evaluation requirements. London's digital health startup cluster incubates smartphone-connected diagnostic readers with quantitative fluorescence detection.
Canada
Provincial healthcare coverage gaps for serological screening create private-pay demand among undiagnosed populations. Health Canada regulates self-testing devices as Class III medical devices requiring pre-market approval. Toronto's medtech corridor hosts mail-in specimen processing laboratories serving hybrid home-collection models.
Australia
High celiac disease genetic predisposition rates in European-descended populations sustain screening program interest. TGA inclusion of self-test devices on the Australian Register of Therapeutic Goods requires local clinical evidence generation. Melbourne's research institutions conduct population prevalence studies employing standardized self-testing protocols for dietary intervention trials.
At-Home Celiac Testing Market Competitive Landscape
United States producers anchor one tier of the competitive structure; German and Swiss specialists hold differentiated positions through European regulatory compliance capabilities. The vendor base separates into three functional tiers: direct-to-consumer platforms with subscription infrastructure, clinical laboratory-backed interpretation services, and CE-marked lateral flow manufacturers. Market consolidation remains limited due to divergent geographic certification requirements. Strategic moves concentrate on telehealth integration partnerships and pharmacy retail shelf placement negotiations.
Within the direct-to-consumer platform tier, Everlywell and LetsGetChecked exemplify divergent trust-building architectures—one leveraging brand infrastructure for recurring revenue capture, the other anchoring positioning through clinician-backed result interpretation. NanoRepro AG occupies a distinct regulatory specialization position through CE-marked format expertise. These three entities represent the primary competitive archetypes: subscription-scale platforms, clinical-credibility services, and European compliance specialists.
| Leading Market Players |
|---|
| PRIMA Lab SA |
| Glutenostics Inc. |
| NanoRepro AG |
| myLAB Box |
| Everlywell |
| LetsGetChecked |
| RxHomeTest |
| Targeted Genomics |
| Genovate |
| Others |
Value Network & Pricing Analysis
Fluorescent nanoparticle chemists in Boston and San Diego command wage premiums that widen manufacturing cost spreads between quantitative diagnostic devices and basic lateral flow cassettes. This labor-cost differential feeds directly into three-tier pricing structure across premium, standard, and economy levels for at-home celiac testing products.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for colloidal gold lateral flow substrates, compressing margins on entry-level test kits. Price differentiation hinges on FDA CLIA-waived certification tier and quantitative fluorescence detection capability. Pricing pressure stems from employer wellness program procurement officers consolidating vendor panels for volume discounts. Pediatric and needle-averse demographic segments show highest price sensitivity; employer-sponsored populations exhibit lowest sensitivity due to stipend coverage.
Supply Chain Analysis
Direct-to-consumer e-commerce channels handle individual subscriber demand, while pharmacy distribution networks manage retail chain replenishment for CLIA-waived products. Manufacturing concentrates in China for lateral flow membrane substrates, the United States for fluorescent reader assembly, and Germany for CE-marked genotyping reagents. Nitrocellulose membranes, recombinant tTG antigens, and nanoparticle conjugates constitute critical input dependencies. Single-source vulnerability for European notified body certification services creates 18-24 month approval bottlenecks that freeze market entry timelines for novel formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The at-home celiac testing market represents a late-cycle quality story where symptomatic consumers now demand quantitative titer precision previously reserved for clinical laboratories. This specification shift favors manufacturers with fluorescent detection chemistry and telehealth integration capabilities.
For Market Incumbents: Anticipate margin compression from emerging smartphone-connected reader platforms by deepening fluorescent nanoparticle IP portfolios and securing exclusive pharmacy benefit manager placement contracts. Vertical integration into cheek swab collection manufacturing reduces dependency on third-party logistics providers. Defensive priority rests on locking gastroenterology network partnerships for automated positive-result routing before competitors replicate telehealth integration workflows.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in HLA-DQ2/DQ8 genotyping creates entry opportunity for simplified exclusion-testing formats targeting undiagnosed symptomatic-negative populations cycling through repeat serological screens. White-space targets include subscription-based annual re-testing programs for diagnosed celiac patients and employer wellness channels seeking bundled preventive care stipends. Go-to-market angle should emphasize genetic counseling integration to differentiate from commodity antibody screening.
For Investors and Strategic Acquirers: Telehealth platforms with diagnostic routing infrastructure are the most active acquirer in this space, seeking captive laboratory access to complete care coordination value chains. Five-to-ten year viability depends on FDA software-as-medical-device classification clarity for algorithmic interpretation apps. Acquisition target archetype: CE-marked lateral flow manufacturers with European regulatory affairs capacity and dormant United States CLIA-waived certification pipelines. Signal to watch: employer wellness program stipend expansion rates for at-home diagnostic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Integration Partnership | Automated routing of positive home tests to gastroenterology networks captures care coordination value currently fragmented. |
| CLIA-Waived Certification Pathway | FDA streamlined approval enables pharmacy shelf placement without prescription requirements in United States retail chains. |
| Fluorescent Nanoparticle Substrate Adoption | Quantitative titer correlation with ELISA reference methods absorbs market share from enzymatic colorimetric formats. |
| Employer Wellness Program Integration | Large self-insured employers add at-home celiac panels to preventive care stipends, capturing asymptomatic screening demand. |
| CE Marking Pathway Investment | EU In Vitro Diagnostic Regulation compliance creates 18-24 month barriers that freeze non-CE-marked entrant timelines. |
Research Methodology
Direct dialogue with diagnostic platform executives, CLIA laboratory directors, regulatory affairs specialists at notified bodies, and pharmacy benefit manager formulary managers grounded qualitative assessment of commercialization pathways. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation summaries, hospital procurement databases, and employer wellness program vendor rosters. Bottom-up demand modeling across self-directed consumer and institutional buyer segments triangulated against top-down market sizing from direct-to-consumer diagnostic revenue disclosures.
Bottom-up unit economics modeled test kit volumes, diagnostic device placements, and subscription attach rates across the projection horizon. Segmentation dimensions included technology tier, distribution channel, and end-user archetype with geographic regulatory cluster overlays. CAGRs derived from installed base growth curves and replacement cycle assumptions for monitoring programs. Industry-specific forecast inputs incorporated CLIA-waived certification approval velocities and employer wellness stipend expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for salivary IgA detection chemistry displacing fingerstick blood collection would alter the outlook. Forecasts reflect assumptions regarding FDA software-as-medical-device classification timing and European notified body capacity expansion. Regulatory restriction tightening or gluten-free diet pre-test interference education campaigns could revise demand trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Friability Tester Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Global Bioburden Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Home DNA Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Global Lipid Panel Testing Market