
 Par-Baked Bread Market | 2026-2036
Par-Baked Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Par-Baked Bread Market Analytics
Food service operators are unwinding reliance on scratch baking in favor of par-baked solutions that cut labor costs and reduce waste. Europastry leverages its European manufacturing footprint to supply frozen par-baked lines across multiple channels. Lantmännen Unibake anchors Nordic and North American demand through specialized bakery portfolios. Grupo Bimbo competes on scale, extending distribution reach into Latin American food service markets.
Par-baked bread refers to dough that undergoes partial baking to approximately 80-90 percent completion, then undergoes rapid freezing for later finish-baking, with internal temperatures typically reaching 82-88°C before blast freezing at -35°C to preserve starch structure and crust development. Its primary commercial purpose is to deliver fresh-baked aroma and texture without requiring full on-site production infrastructure. Specialty bread commands premium positioning among retail consumers seeking artisan-style products with minimal preparation time. Whole wheat and multigrain variants are gaining fastest in food service channels where health-conscious menu labeling drives procurement decisions. White bread remains the mature volume base, though margin pools have shifted toward multigrain and specialty formats.
The FDA governs frozen dough labeling and allergen declarations in the United States, while EFSA sets acrylamide thresholds and additive restrictions across European markets. BIS certification requirements in India affect import access for frozen bakery intermediates, shaping where multinational suppliers establish local production. Stakeholders must monitor evolving clean-label standards and freezer-to-oven technology investments that determine operational efficiency across regional supply chains.
Market Dynamics
Food service operators are dismantling scratch-baking infrastructure in favor of freezer-to-oven workflows that compress labor hours and standardize output quality across dispersed locations.
Growth Catalysts
- Clean-label mandates:FDA and EFSA reformulation requirements are accelerating R&D investment in reduced-additive dough systems. This pressures conventional frozen dough suppliers to upgrade ingredient sourcing.
- Quick-service restaurant expansion:Drive-thru and delivery-optimized kitchen footprints in the United States favor par-baked solutions that eliminate proofing stations. Chains are specifying freezer-to-oven products in procurement contracts.
- Blast-freezing technology:Cryogenic tunnel systems operating at -35°C are preserving starch retrogradation patterns previously achievable only with fresh baking. Equipment manufacturers report rising orders from mid-scale bakeries.
Market Restraints
- Wheat price volatility:Input cost swings in North American grain markets compress margin predictability for contract manufacturers. Hedging instruments remain underutilized among smaller regional suppliers.
- Cold chain concentration:Third-party frozen logistics providers in Western Europe control last-mile temperature integrity. Capacity constraints during peak seasons force producers to absorb detention costs.
- Acrylamide thresholds:EFSA maximum levels for browned bakery products impose finish-baking protocol restrictions. This limits crust-darkening options that consumers associate with artisan quality.
Strategic Opportunities
- Indian food service penetration:BIS certification barriers have historically limited import access. Local production partnerships with domestic bakery groups unlock institutional catering contracts.
- Healthcare and senior living channels:Texture-modified and sodium-reduced par-baked lines address dietary compliance requirements. These segments command pricing premiums over conventional food service contracts.
- Renewable energy integration:IRA clean energy credits for industrial refrigeration retrofits reduce operational carbon intensity. Producers leveraging this incentive gain procurement preference from sustainability-mandated buyers.
Industry Challenges
- Freezer-to-oven technician scarcity:Equipment calibration and thermal profiling require specialized skills absent from conventional baking training programs. Vocational pipelines have not adapted to hybrid fresh-frozen production models.
- Legacy ERP integration:Inventory management systems designed for ambient or refrigerated goods struggle with lot-tracking requirements for frozen intermediates. Custom middleware development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Par-Baked Bread Market |
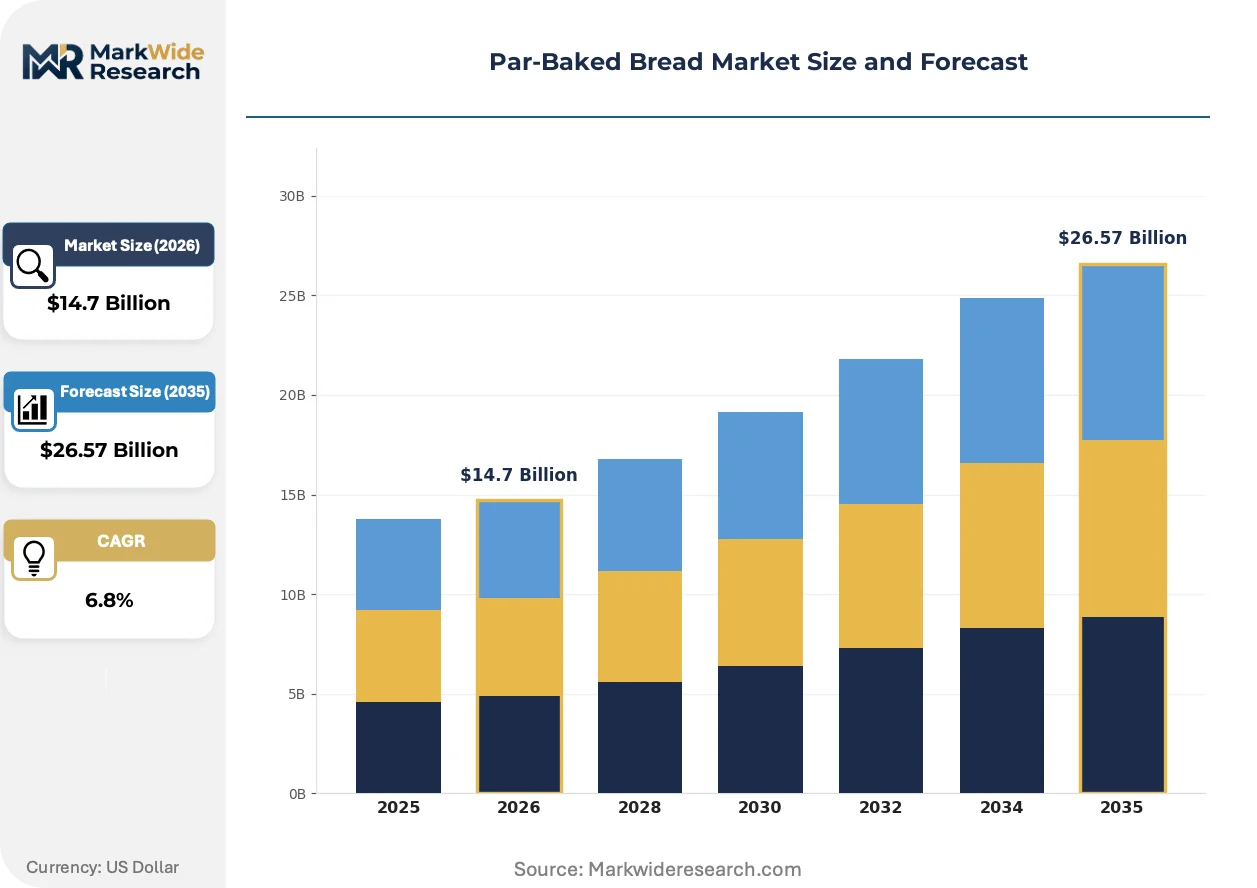
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Specialty Bread End User: Retail Consumers, Restaurants, Cafés, Food Service Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Packaging Type: Bags, Boxes, Trays, Films |
| Companies Covered | Europastry, Lantmännen Unibake, Grupo Bimbo, La Brea Bakery, Rich Products Corporation, Flowers Foods, Bridor, Bimbo Bakeries USA, Aryzta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Par-Baked Bread Market Evolving Landscape
Automation and regulatory precision are converging to redefine production economics and product positioning across frozen bakery supply chains.
High-velocity spiral freezers with nitrogen injection systems are displacing conventional blast-freezing methods in high-volume plants. These units reduce core temperature descent time from 90 minutes to under 20 minutes, preserving cellular structure in whole-grain formulations. Mid-scale bakeries in the United States are leasing this equipment through vendor financing to avoid capital commitment.
EFSA acrylamide mitigation guidelines are forcing reformulation of crust-development protocols across European manufacturing. Suppliers are deploying enzyme-based browning control and reduced-temperature finish-baking specifications. Retail private-label programs in Germany and France are auditing supplier compliance as a listing condition.
Direct procurement relationships between restaurant chains and frozen dough manufacturers are compressing distributor margins and rewiring channel economics. Food service buyers in the United States are negotiating multi-year supply agreements with volume commitments and technical service attachments. This pattern concentrates procurement influence among operators with national or super-regional scale.
Par-Baked Bread Market Segmentation
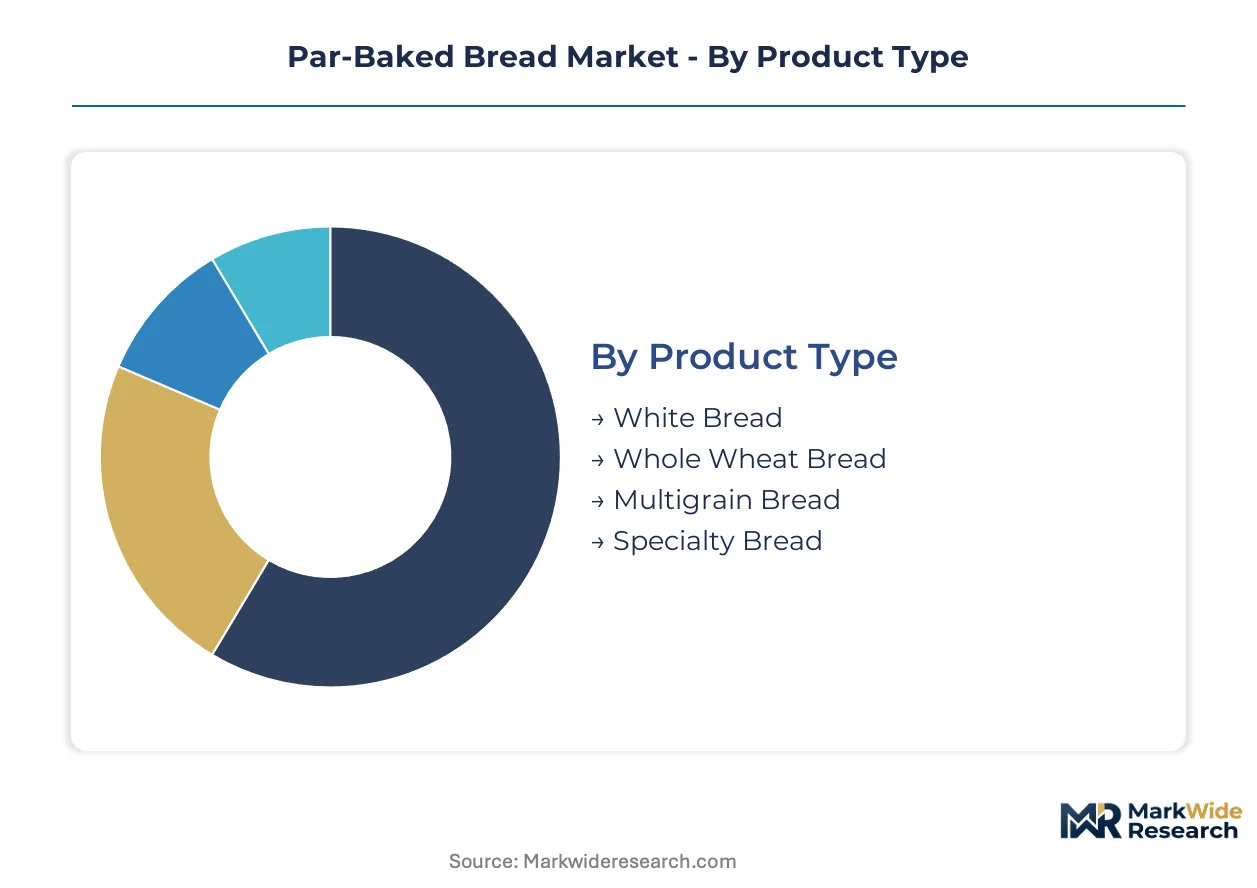
Segmentation in par-baked bread reveals where formulation investments concentrate and which channels absorb freezer-to-oven workflow investments. Product type and end-user splits determine margin architecture across frozen bakery supply chains.
Product Type:
Substitution pressure from fresh-baked alternatives weighs heaviest on commoditized formats, while health-positioned and artisan-style segments defend differentiation through ingredient sourcing and finish-baking protocols.
- White Bread:Standard refined-flour formulations with minimal bran content serve as the baseline volume driver across institutional food service contracts. Quick-service restaurant chains in the United States specify white bread for bun and roll applications where cost predictability outweighs nutritional positioning.
- Specialty Bread:Artisan-style formulations incorporating sourdough starters, ancient grains, or extended fermentation periods command premium placement in retail in-store bakery programs. Demand concentrates among United States supermarket chains seeking differentiated private-label offerings without scratch-baking labor.
- Whole Wheat Bread:Higher-fiber formulations meeting FDA whole-grain labeling criteria.
- Multigrain Bread:Seed and grain inclusions requiring modified freezing protocols to preserve texture.
White bread retains volume leadership; specialty bread holds the steepest expansion curve.
End User:
Cost tier separation between premium retail and efficiency-driven food service determines packaging specifications and minimum order quantities across frozen dough portfolios.
- Food Service:Institutional buyers including quick-service chains, contract caterers, and hospitality groups specify freezer-to-oven products with calibrated finish-baking windows. Procurement concentrates in United States national accounts where technical service attachments and volume commitments structure multi-year supply agreements.
- Retail Consumers:Home bakers and small households purchase smaller-format par-baked loaves through supermarket in-store bakery sections and online grocery platforms. Demand clusters in urban United States markets where apartment-sized kitchens lack full baking infrastructure.
- Restaurants:Full-service dining operations seeking breadbasket consistency without proofing equipment.
- Cafés:Coffee-focused formats prioritizing pastry and bread accompaniment programs.
Food service captures the dominant procurement volume; retail consumers are gaining share fastest through e-commerce penetration.
Distribution Channel:
Supply concentration among third-party frozen logistics providers shapes which channels can maintain temperature integrity from production through final delivery.
- Supermarkets:Grocery retailers with in-store bakery infrastructure represent the primary volume outlet for branded and private-label par-baked lines. United States chains specify direct-to-store delivery schedules aligned with freezer capacity and bakery labor shifts.
- Wholesale:Broadline food service distributors aggregate demand from independent restaurants and regional chains, consolidating frozen bakery into mixed-temperature truckloads. Cold chain constraints in Western Europe limit wholesale expansion during peak seasonal periods.
- Online Retail:Direct-to-consumer frozen delivery requiring specialized insulated packaging.
- Convenience Stores:Limited freezer space favors compact, high-velocity SKUs.
Supermarkets anchor channel volume; online retail shows the most rapid trajectory expansion.
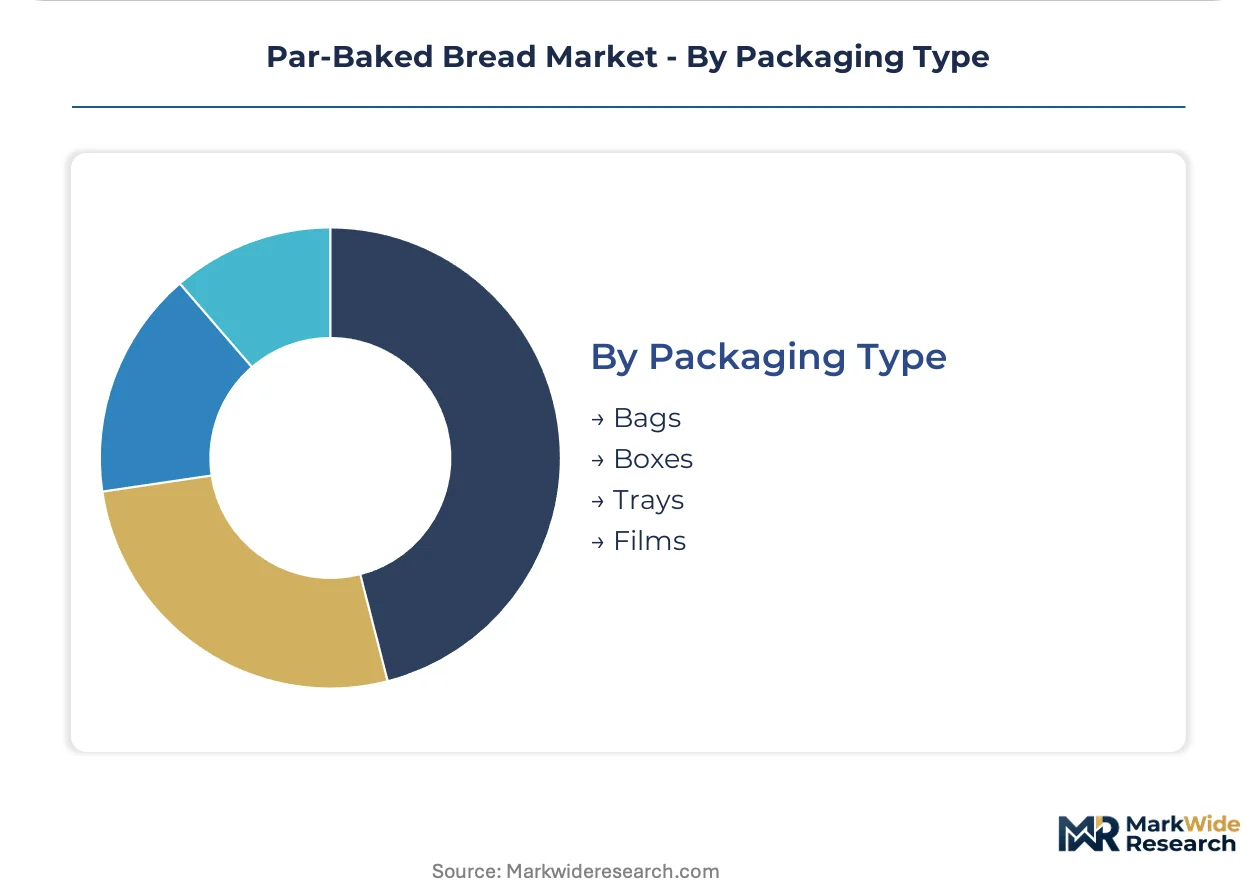
Packaging Type:
Packaging material selection tracks customer type and distribution distance, with film and bag formats dominating high-volume food service while rigid containers protect retail presentation.
- Bags:Polyethylene and laminated film bags provide cost-efficient barrier protection for high-velocity food service shipments. United States quick-service chains specify printed bags with finish-baking instructions and lot-coding for traceability compliance.
- Films:Cryovac and modified-atmosphere films extend shelf life for retail distribution channels requiring longer inventory turns. EFSA migration limits on food-contact plastics drive reformulation of adhesive layers in European market supply.
- Boxes:Corrugated containers for palletized wholesale shipments.
- Trays:Rigid plastic or aluminum formats for premium retail presentation.
Bags dominate unit volume; films are climbing the fastest on clean-label barrier requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Western Europe's frozen bakery distribution, while Union Pacific's refrigerated rail network anchors North American supply velocity.
United States
Quick-service restaurant chains and supermarket in-store bakery programs absorb the dominant procurement volume. FDA frozen dough labeling mandates and allergen declaration requirements structure formulation compliance. Chicago's food manufacturing corridor concentrates blast-freezing equipment installations serving national distribution networks.
Germany
Retail private-label programs and discount bakery chains drive par-baked adoption across Western European markets. EFSA acrylamide thresholds and additive restrictions impose finish-baking protocol constraints. Bavaria's industrial baking cluster hosts cryogenic tunnel system deployments for whole-grain formulations.
France
Artisan-style positioning in supermarket channels preserves premium pricing for sourdough and ancient-grain variants. ANSM food-contact material regulations and CNIL data governance affect packaging and traceability systems. Paris Basin production facilities supply freezer-to-oven lines across Benelux and Iberian markets.
India
Institutional catering contracts and quick-service penetration in metropolitan markets expand addressable demand. BIS certification requirements for frozen bakery intermediates shape local production partnerships. Maharashtra's food processing zones attract multinational joint ventures circumventing import barriers.
Brazil
Food service channel expansion and convenience retail formats accelerate par-baked adoption in Latin America's largest market. ANVISA frozen food safety protocols govern storage temperature documentation. São Paulo state's bakery ingredient manufacturing base supplies regional freezer-to-oven distributors.
Par-Baked Bread Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base stratifies between pan-regional scale operators and category-focused regional bakeries. Three archetypes dominate: European manufacturing specialists with multi-channel supply capabilities, North American scale players leveraging distribution density, and emerging-market joint ventures navigating certification barriers. Consolidation through acquisition and backward integration into ingredient sourcing represent the primary competitive vectors.
Among European-based specialists, Europastry and Lantmännen Unibake exemplify the manufacturing-footprint archetype, occupying positions that span retail private-label and food service contract supply. Grupo Bimbo represents the scale-driven end, anchoring Latin American market development through distribution infrastructure investments. These three entities collectively illustrate how geographic origin and corporate structure shape strategic positioning across frozen bakery value chains.
| Leading Market Players |
|---|
| Europastry |
| Lantmännen Unibake |
| Grupo Bimbo |
| La Brea Bakery |
| Rich Products Corporation |
| Flowers Foods |
| Bridor |
| Bimbo Bakeries USA |
| Aryzta |
| Others |
Value Network & Pricing Analysis
BIS certification requirements in India simultaneously gate supplier qualification and enable price premiums for compliant domestic producers versus import-dependent competitors. This dual-gate mechanism concentrates procurement leverage among multinational operators with established local manufacturing footprints, compressing margins for unqualified entrants while rewarding certification investment with contract pricing power.
Pricing Analysis
Volume-discount tiering structures dominate food service procurement contracts, with quick-service restaurant chains extracting graduated price reductions tied to annual tonnage commitments and multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates artisan-style specialty lines from commodity white bread formats, with whole-grain and multigrain variants commanding mid-tier positioning. Cost compression in standard white bread segments is intensifying because wheat price volatility erodes contract manufacturer hedging capacity. Quick-service chains exhibit highest price sensitivity due to menu cost engineering pressures, while healthcare and senior living channels tolerate premium pricing for texture-modified and sodium-reduced compliance formulations.
Supply Chain Analysis
The United States anchors North American blast-freezing equipment installations and cryogenic tunnel system deployments, while Germany and France concentrate European manufacturing for retail private-label and artisan-style lines. Wheat flour, nitrogen for cryogenic freezing, and laminated film packaging materials constitute the primary input dependencies, with sourcing strategies varying by regional grain market structure. Single-source vulnerability in third-party frozen logistics capacity during peak seasonal periods forces producers to absorb detention costs and compresses delivery reliability. Distribution runs through direct-to-store delivery schedules for supermarket in-store bakery programs and broadline food service distributors aggregating mixed-temperature truckloads for independent restaurant accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blast-freezing technology advancement represents a high-growth disruption, with cryogenic tunnel systems displacing conventional methods and rewiring production economics for mid-scale bakeries previously locked out of premium formulation supply.
For Market Incumbents: Fortify market position through backward integration into specialty grain sourcing and captive nitrogen supply arrangements that insulate margin structures from input volatility. Expand blast-freezing capacity in Chicago's food manufacturing corridor to secure national distribution velocity against regional competitors. EFSA acrylamide threshold compliance investments defend listing status with German and French retail private-label programs. For New Entrants and Emerging Players: Lead with healthcare and senior living channel penetration, where texture-modified and sodium-reduced par-baked lines face limited incumbent specialization and command pricing premiums over conventional food service contracts. Target Indian institutional catering through BIS certification partnerships with Maharashtra-based domestic bakery groups, circumventing import barriers that have historically constrained multinational access. Position around technical service attachments and calibrated finish-baking protocol support as differentiated go-to-market angle. For Investors and Strategic Acquirers: FDA and EFSA clean-label reformulation mandates reshape the acquisition landscape by elevating R&D-capable targets with reduced-additive dough systems over commodity-dependent legacy operators. Five-to-ten-year viability favors manufacturers with cryogenic tunnel deployment experience and established quick-service restaurant technical service relationships. Monitor blast-freezing equipment order backlogs from mid-scale United States bakeries as inflection indicator for production capacity expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Tunnel Deployment | Nitrogen injection systems preserve cellular structure in whole-grain formulations for premium positioning. |
| Backward Integration into Grain Sourcing | Captive wheat supply hedges North American price volatility and secures contract manufacturing margins. |
| Healthcare Channel Specialization | Texture-modified lines address dietary compliance requirements with pricing premiums over conventional contracts. |
| BIS Certification Partnership | Local production joint ventures unlock Indian institutional catering demand blocked to direct imports. |
| Direct Procurement Relationship Development | Multi-year supply agreements with technical service attachments concentrate influence among national-scale operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA frozen dough labeling guidance, EFSA acrylamide mitigation protocols, and BIS certification documentation for frozen bakery intermediates. Interviews with quick-service restaurant procurement directors, contract manufacturer plant managers, supermarket category buyers, and blast-freezing equipment vendors inform operational practice assessment. Secondary validation draws from customs trade data, food service distributor financial disclosures, and cold chain logistics provider capacity reports. Bottom-up demand modeling triangulates against top-down market sizing through production capacity and utilization rate analysis.
Segmentation dimensions modeled span product type, end-user channel, distribution pathway, and packaging format across the projection horizon. The analytical framework incorporates formulation compliance tier, freezer-to-oven technical service intensity, and regional regulatory cluster as industry-specific variables. CAGRs derive from production volume trajectory analysis calibrated against input cost indices and channel penetration rate assumptions. Forecast inputs include wheat price volatility scenarios, cryogenic equipment adoption curves, and quick-service restaurant footprint expansion patterns.
Forecasts assume regulatory continuity in FDA allergen declaration requirements and EFSA additive restrictions; material policy shifts would require re-modeling. Wheat price volatility, cold chain capacity constraints, and acrylamide threshold enforcement intensity constitute primary revision triggers. Recalibration cycles align with material shifts in clean-label mandate implementation and blast-freezing technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
Pancake Mixes Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Ezekiel Bread Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Pastry Premixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Global Cakes Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Global Cake Mix Market