
 Middle East and Africa Bakery Products Market | 2026-2036
Middle East and Africa Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bakery Products Market Foresight
Premium artisan and clean-label specification tiers is unwinding across the Middle East and Africa Bakery Products Market as consumers trade up from basic commoditized loaves. Almarai Group leverages its integrated dairy and bakery supply chain to dominate fresh distribution across Saudi Arabia and neighboring markets. Britannia Industries Limited anchors its position through deep specialization in packaged biscuits and rusk products tailored to regional taste profiles. Modern Bakery LLC sustains competitive relevance by controlling institutional channels and large-format retail supply agreements in the United Arab Emirates.
Middle East and Africa bakery products comprise wheat-based and alternative-grain formulations manufactured through mechanical dough development, fermentation control, and thermal processing to deliver shelf-stable or fresh-retail carbohydrate staples for household and commercial consumption. Industrial pan bread production typically employs high-speed mixing at controlled temperatures to achieve consistent crumb structure and extended freshness in hot-climate distribution. Breads commands the largest volume share across the product type dimension, though pastries accelerates fastest as Gulf hotel and aviation catering sectors expand. Supermarkets channels capture the dominant value flow within distribution channel segmentation, while online retail segments gain traction among urban millennials seeking subscription-based artisan delivery.
Saudi Food and Drug Authority labeling mandates and UAE Ministry of Climate Change and Environment halal certification protocols jointly reshape product formulation and import access requirements across the region. Egypt's General Authority for Supply Commodities wheat procurement policies directly determine flour cost structures and subsidized bread availability for mass-market producers. Stakeholders must monitor evolving Gulf Standards Organization harmonization efforts and their potential to consolidate cross-border manufacturing compliance burdens.
Market Dynamics
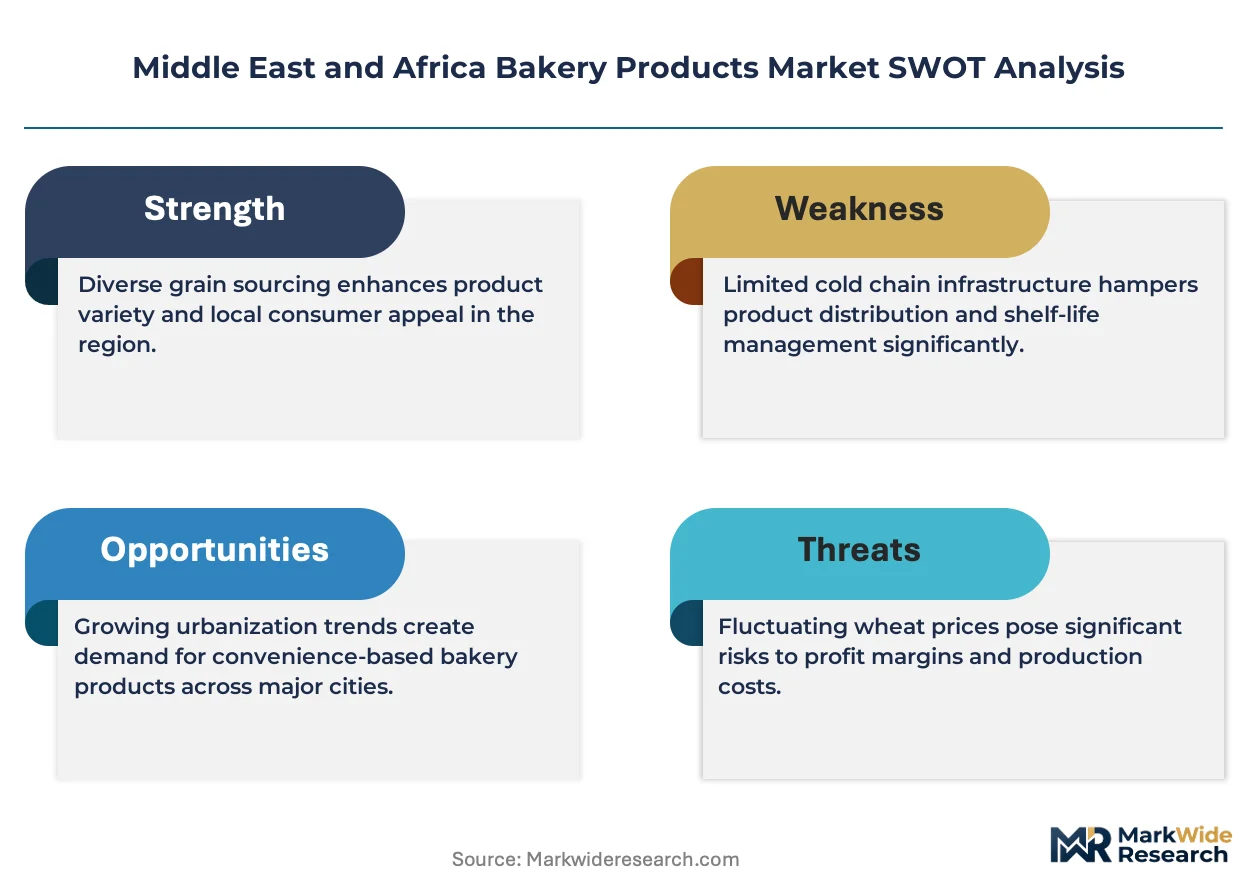
SFDA labeling mandates and UAE halal certification protocols are forcing wholesale reformulation across Middle East and Africa bakery manufacturing, compressing margins while accelerating clean-label migration.
Growth Catalysts
- Gulf aviation catering expansion:Emirates and Qatar Airways route networks are scaling artisan pastry procurement for premium cabin service, pulling specialized production capacity into Dubai and Doha free zones.
- Egyptian wheat subsidy infrastructure:The General Authority for Supply Commodities maintains flour cost stability that sustains mass-market bread accessibility for producers serving Cairo and Nile Delta population centers.
- Controlled-atmosphere packaging:Modified atmosphere technologies are extending ambient shelf life for packaged biscuits and rusks, enabling distribution reach into Nigerian and Kenyan retail networks previously inaccessible to regional suppliers.
Market Restraints
- Black Sea wheat price volatility:Egyptian and Moroccan millers face margin compression when Ukrainian and Russian grain flows disrupt, forcing reformulation toward alternative starches.
- Single-source enzyme dependence:Industrial pan bread producers across Saudi Arabia and UAE rely on concentrated European enzyme suppliers, creating vulnerability when maritime chokepoints delay shipments.
- Traditional sourdough fermentation timelines:Artisan producers cannot match industrial throughput speeds, ceding volume share to mechanical dough development systems in supermarket channel negotiations.
Strategic Opportunities
- Ethiopian teff grain commercialization:Injera flatbread traditions offer untapped export potential for gluten-free positioning in Gulf expatriate wellness segments.
- Direct-to-hotel subscription platforms:Dubai and Riyadh hospitality procurement teams are piloting weekly artisan bread drops bypassing traditional foodservice distributors.
- Saudi Vision 2035 food security localization:Domestic wheat milling and bakery manufacturing incentives are attracting greenfield investment into Jeddah and Dammam industrial zones.
Industry Challenges
- Halal certification timeline compression:SFDA and ESMA harmonization efforts are extending product registration cycles, delaying new SKU launches by four to six months.
- Thermal profile engineering expertise:Industrial ovens requiring Arabic bread-specific heat distribution configurations face scarcity of qualified commissioning engineers across North Africa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bakery Products Market |
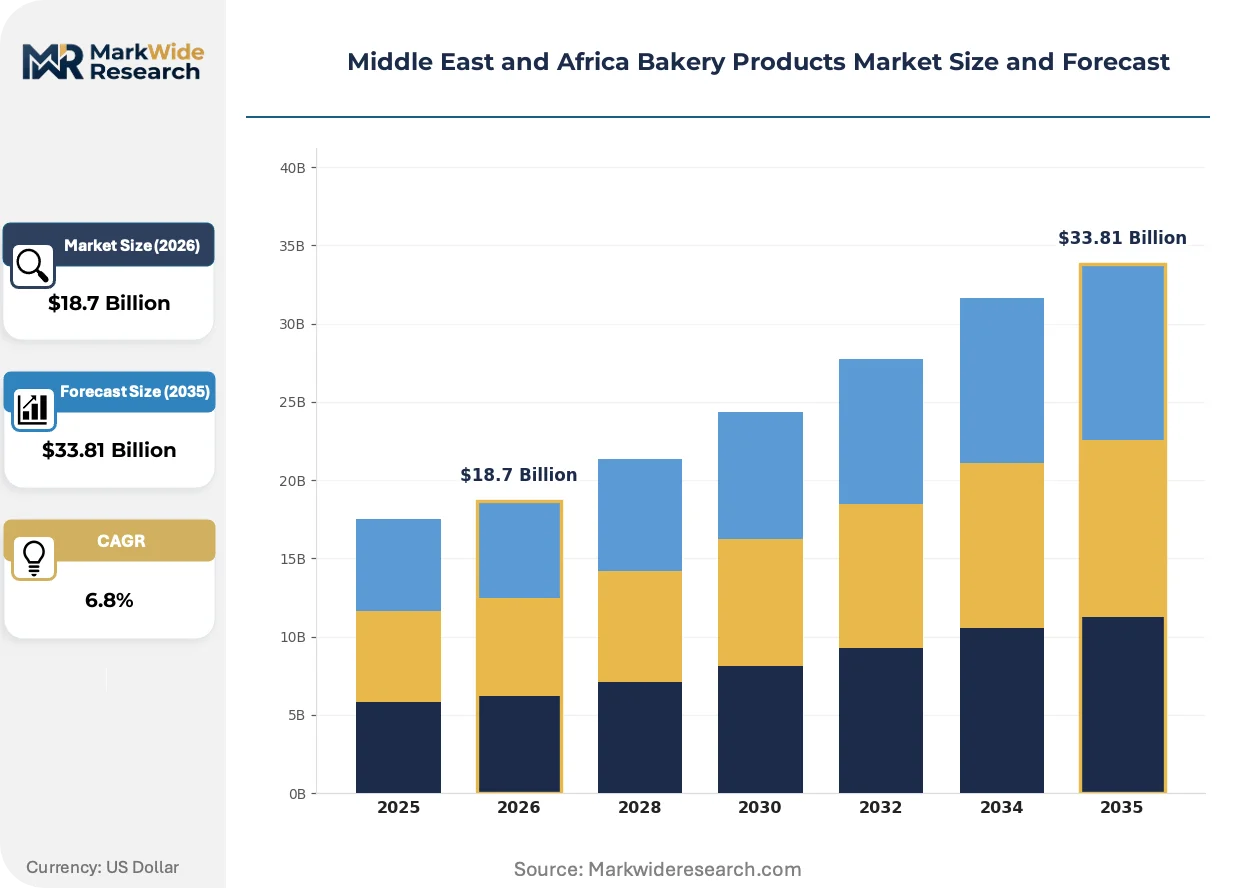
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cookies, Cakes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Packaging Type: Boxed, Bagged, Canned, Vacuum Sealed End User: Households, Food Service Providers, Cafés, Retail Outlets |
| Companies Covered | Lantmännen Unibake, Mondelez International, Modern Bakery LLC, Britannia Industries Limited, General Mills, Almarai Group, Agthia Group, Aryzta AG, Grupo Bimbo, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bakery Products Market Shifts & Advancements
Reformulation pressures and distribution cold-chain investments are converging to reshape product architecture across Middle East and Africa bakery categories, with implications for every tier from subsidized flatbread to luxury patisserie.
Retort pouch packaging for ambient-stable flatbreads is miniaturizing distribution infrastructure requirements, enabling Nigerian and Kenyan convenience store penetration without refrigerated logistics. Regional CPG manufacturers are adopting these formats at accelerating pace, collapsing the historical advantage of fresh-delivery networks in urban peripheries.
UAE Ministry of Climate Change and Environment extended producer responsibility frameworks now mandate recyclable or biodegradable packaging for bakery products sold in Dubai and Abu Dhabi retail channels. Manufacturers are responding with fiber-based trays and water-soluble films, though cost premiums currently restrict deployment to premium private-label lines.
Hotel and restaurant procurement teams across Jeddah, Riyadh, and Doha are consolidating supplier rosters, awarding multi-year bakery contracts to integrated dairy-bakery groups capable of delivering synchronized fresh deliveries. This concentration is displacing fragmented artisan bakery networks that previously served individual properties, compressing available vendor slots by half in competitive tenders.
Middle East and Africa Bakery Products Market Segmentation
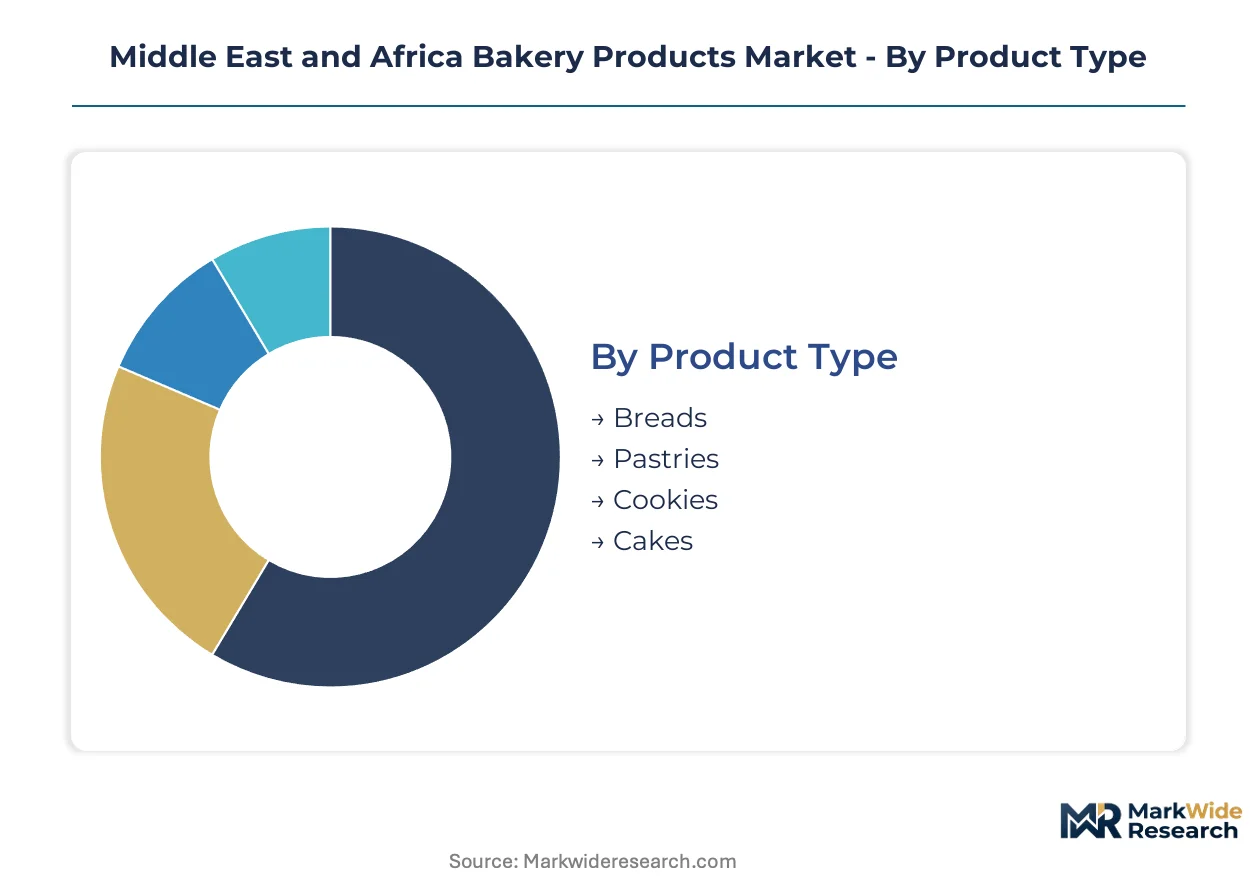
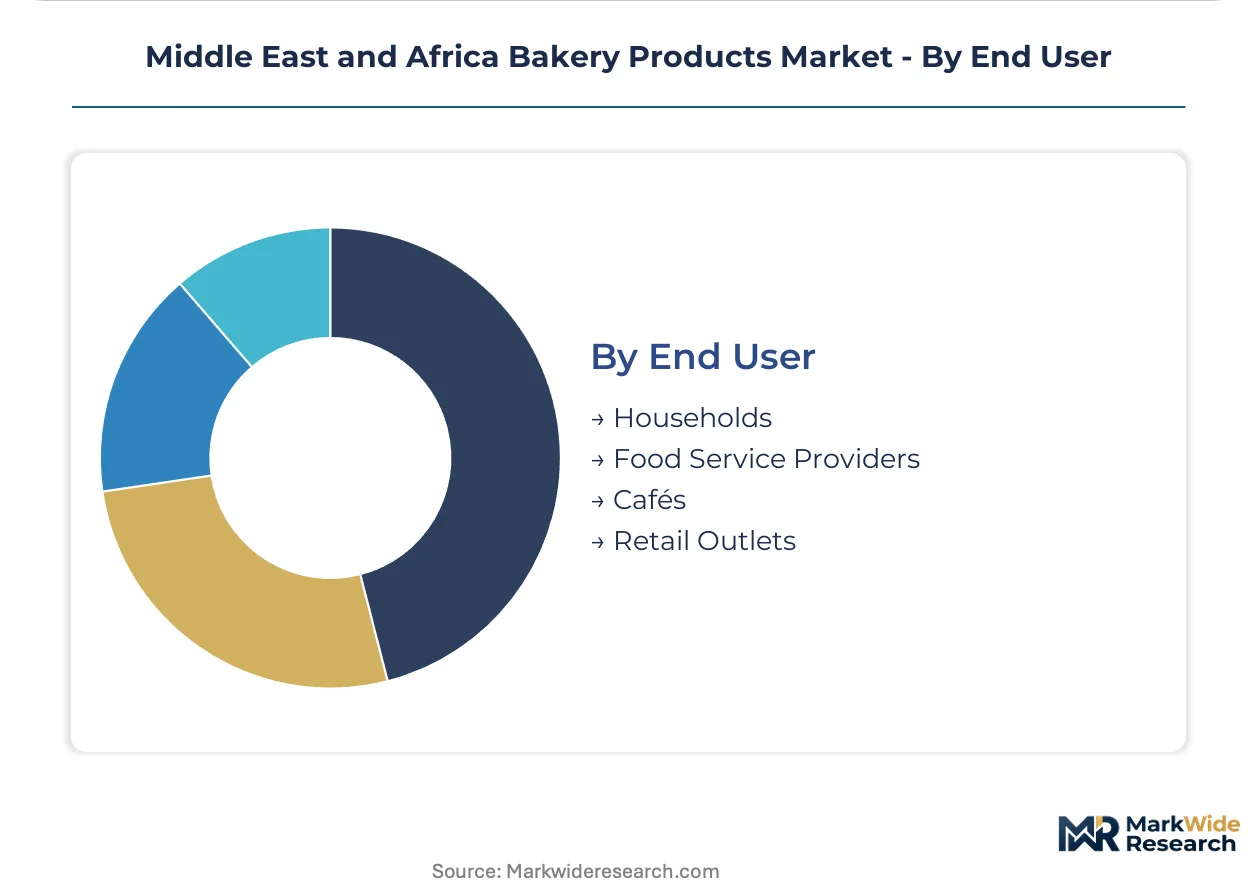
Segmentation in the Middle East and Africa bakery sector reveals divergent growth mechanics across consumption occasions and channel economics. Product architecture and packaging specifications must align with distinct thermal stability requirements and halal certification protocols governing cross-border trade.
Product Type:
Domestic production dominates wheat-based staples, while export-oriented capacity concentrates on premium pastry formats serving Gulf aviation and hospitality procurement.
- Breads:Industrial pan bread employs high-speed mechanical dough development to achieve consistent crumb structure under hot-climate distribution. Egyptian wheat subsidies sustain massive daily consumption across Cairo and Nile Delta population centers, though Black Sea supply disruptions force periodic reformulation toward alternative starches.
- Pastries:Laminated and choux-based formulations require controlled cold-chain logistics to preserve cream and butter integrity. Emirates and Qatar Airways premium cabin service procurement pulls specialized production capacity into Dubai and Doha free zones, accelerating artisan capacity expansion.
- Cookies:Packaged biscuits and rusks leverage modified atmosphere packaging to extend ambient shelf life for Nigerian and Kenyan retail penetration.
- Cakes:Celebration and portion-sized formats concentrate in Saudi and UAE supermarket channels, with clean-label migration accelerating under SFDA labeling mandates.
Breads commands the established base. The steepest expansion runs through pastries.
Distribution Channel:
Channel selection determines margin structure and certification burden, with modern retail imposing stricter halal and extended producer responsibility compliance than traditional trade.
- Supermarkets:Hypermarket and supermarket chains across Jeddah, Riyadh, and Dubai consolidate procurement through integrated dairy-bakery groups capable of synchronized fresh delivery. UAE Ministry of Climate Change and Environment packaging mandates now require recyclable or biodegradable materials for products sold in these channels.
- Convenience Stores:Retort pouch ambient-stable flatbreads are miniaturizing distribution infrastructure requirements, enabling Nigerian and Kenyan penetration without refrigerated logistics.
- Online Retail:Subscription-based artisan delivery gains traction among urban millennials in Gulf metropolitan areas, bypassing traditional foodservice distributor markups.
- Specialty Shops:Independent bakeries and patisseries serve premium positioning in Beirut, Casablanca, and Johannesburg affluent districts.
Supermarket channels capture the dominant value flow. Online retail segments are climbing the fastest.
Packaging Type:
Packaging economics stratify across shelf-life extension requirements and sustainability compliance tiers, with fiber-based solutions commanding premium positioning.
- Boxed:Rigid cardboard formats protect premium biscuits and gift assortments for Saudi and UAE retail gifting occasions. SFDA labeling mandates push manufacturers toward larger surface areas for ingredient disclosure.
- Bagged:Flexible polyethylene dominates mass-market bread and roll distribution, though UAE extended producer responsibility frameworks are accelerating migration toward biodegradable alternatives.
- Canned:Ambient-stable formats serve military, institutional, and remote mining camp procurement across North African and Sub-Saharan markets.
- Vacuum Sealed:Modified atmosphere technologies enable regional suppliers to reach Nigerian and Kenyan networks previously inaccessible due to spoilage constraints.
Bagged formats anchor volume throughput. Vacuum sealed applications are gaining share fastest.
End User:
End-use concentration determines formulation specifications, with food service procurement consolidating toward integrated suppliers while household demand fragments across quality tiers.
- Households:Daily bread consumption in Egypt exceeds one hundred million servings, sustained by General Authority for Supply Commodities flour subsidies that directly determine mass-market producer cost structures.
- Food Service Providers:Hotel and restaurant procurement teams across Jeddah, Riyadh, and Doha are consolidating supplier rosters, awarding multi-year contracts to integrated dairy-bakery groups and compressing available vendor slots by half in competitive tenders.
- Cafés:Independent coffee shop chains in Dubai, Cairo, and Lagos drive demand for artisan sourdough and viennoiserie, though traditional fermentation timelines constrain throughput scalability.
- Retail Outlets:Private-label bakery programs in Saudi and UAE supermarket chains are absorbing manufacturing capacity previously serving independent bakeries.
Household consumption commands the established base. Food service procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milling capacity and wheat procurement infrastructure concentrate in Egypt and Saudi Arabia, while Gulf aviation catering demand pulls specialized pastry production toward Dubai and Doha free zones. National subsidy programs and halal certification protocols fragment regulatory compliance across North African and Gulf markets.
Egypt
Daily bread consumption exceeds one hundred million servings across Cairo and Nile Delta population centers. The General Authority for Supply Commodities maintains flour cost stability through wheat procurement subsidies that directly determine mass-market producer economics. Alexandria and Damietta port complexes anchor grain import flows that feed industrial milling clusters.
Saudi Arabia
Domestic wheat milling and bakery manufacturing incentives under Vision 2035 food security localization are attracting greenfield investment into Jeddah and Dammam industrial zones. The Saudi Food and Drug Authority labeling mandates are compressing product registration timelines and accelerating clean-label reformulation. Riyadh and Jeddah metropolitan areas concentrate both retail demand and institutional procurement consolidation.
United Arab Emirates
Hotel and restaurant procurement teams in Dubai and Abu Dhabi are consolidating supplier rosters toward integrated dairy-bakery groups capable of synchronized fresh delivery. The Ministry of Climate Change and Environment extended producer responsibility frameworks mandate recyclable or biodegradable packaging for retail channels. Dubai Multi Commodities Centre and Jebel Ali free zones host specialized aviation catering production capacity.
South Africa
Packaged biscuit and rusk distribution networks leverage modified atmosphere packaging to extend ambient shelf life for Nigerian and Kenyan retail penetration. The country's national food safety regulator maintains standards alignment with regional export requirements. Gauteng province industrial corridors concentrate milling and manufacturing capacity serving Southern African Development Community markets.
Morocco
Black Sea wheat price volatility forces periodic reformulation toward alternative starches when Ukrainian and Russian grain flows disrupt. The country's national food safety authority enforces halal certification protocols governing cross-border trade with Gulf Cooperation Council states. Casablanca and Rabat industrial zones anchor milling infrastructure serving both domestic consumption and re-export channels.
Middle East and Africa Bakery Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa bakery sector. Gulf-based integrated dairy-bakery groups dominate fresh distribution through synchronized delivery capabilities, while European and North American multinationals anchor packaged biscuit and ambient-stable categories through brand equity and shelf-life engineering. Three archetypes define competitive positioning: integrated fresh-delivery specialists, multinational packaged goods platforms, and regional private-label manufacturers. Consolidation is accelerating through multi-year hospitality procurement contracts and cross-border milling joint ventures.
Among Gulf-based integrated groups, Almarai Group and Agthia Group exemplify the fresh-delivery archetype through dairy-bakery supply chain coordination. Britannia Industries Limited represents the regional packaged goods specialist with India-origin positioning. Lantmännen Unibake and Aryzta AG occupy positions within the European multinational technology-transfer tier serving aviation and hospitality procurement channels.
| Leading Market Players |
|---|
| Lantmännen Unibake |
| Mondelez International |
| Modern Bakery LLC |
| Britannia Industries Limited |
| General Mills |
| Almarai Group |
| Agthia Group |
| Aryzta AG |
| Grupo Bimbo |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Egyptian millers and the General Authority for Supply Commodities lock in flour cost visibility for mass-market bread producers while insulating subsidized tiers from Black Sea wheat volatility. These arrangements concentrate pricing power among state-linked procurement channels and compress margin flexibility for private manufacturers serving premium segments.
Pricing Analysis
SFDA labeling mandates dictate the pricing tier structure across Saudi and UAE retail channels, separating clean-label reformulated products from conventional formulations. Three-tier pricing structure across premium, standard, and economy levels reflects halal certification grade, volume scale, and packaging sustainability compliance. Pricing pressure stems from Egyptian wheat subsidy distortions that force private producers to absorb flour cost spikes. Household segments in Cairo and Nile Delta population centers exhibit highest price sensitivity, while Gulf hospitality procurement teams prioritize supply reliability over unit cost.
Supply Chain Analysis
Egypt and Morocco anchor wheat milling and flour production for regional bread manufacturing, while Turkey and European enzyme suppliers feed industrial pan bread formulation inputs. Supply chains draw from Black Sea grain corridors, European enzyme concentrates, and Gulf dairy-bakery integration for fresh distribution. Single-source enzyme dependence creates vulnerability when maritime chokepoints delay shipments. Distribution runs through integrated dairy-bakery groups controlling synchronized fresh delivery to Saudi and UAE supermarket and hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch ambient-stable flatbreads threaten fresh-delivery networks by collapsing distribution infrastructure requirements, forcing incumbents to defend positioning through supply chain reinvention.
For Market Incumbents: Secure backward integration into wheat milling under Saudi Vision 2035 localization incentives to insulate margin structures from import price volatility. Lock in multi-year hospitality procurement contracts before supplier roster consolidation halves available vendor slots, leveraging synchronized dairy-bakery delivery capabilities as the defensive moat against retort pouch substitutes. For New Entrants and Emerging Players: Anchor in Ethiopian teff grain commercialization for gluten-free positioning targeting Gulf expatriate wellness segments, where incumbent coverage remains thin. Target direct-to-hotel subscription platforms in Dubai and Riyadh bypassing traditional foodservice distributor markups, using weekly artisan bread drops as the go-to-market wedge. For Investors and Strategic Acquirers: Fresh-delivery specialists with halal certification infrastructure and Gulf retail network access represent the highest-conviction acquisition archetype for medium-term consolidation plays. Monitor SFDA-ESMA harmonization timeline compression as the signal indicating regulatory barrier height and M&A window viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Vision 2035 incentives in Jeddah and Dammam zones reduce import cost exposure for bread manufacturers. |
| Clean-Label Reformulation Investment | SFDA labeling mandates accelerate migration toward shorter ingredient decks in Saudi retail channels. |
| Direct-to-Hotel Subscription Platforms | Dubai and Riyadh hospitality procurement pilots bypass traditional foodservice distributor markups. |
| Teff Grain Commercialization | Ethiopian injera traditions unlock gluten-free export positioning for Gulf expatriate wellness demand. |
| Retort Pouch Format Adoption | Ambient-stable flatbreads enable Nigerian and Kenyan convenience store penetration without cold-chain investment. |
Research Methodology
A standing panel of bakery plant managers, retail category buyers at Saudi and UAE hypermarket chains, flour procurement officers at Egyptian milling cooperatives, and hospitality procurement directors at Dubai hotel groups provided ongoing calibration against secondary validation. Primary interviews combined with customs trade records, GASC wheat tender disclosures, SFDA regulatory filings, and Gulf Standards Organization harmonization documents. Bottom-up production capacity assessments triangulated against top-down consumption estimates across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional milling capacity utilization rates and aviation catering procurement disclosures from Emirates and Qatar Airways. Segmentation modeling spanned product type, distribution channel, packaging format, and end-user concentration across the projection horizon. CAGRs derived from annualized growth rate calculations applied to base-year market sizing, incorporating wheat price elasticity coefficients and halal certification penetration curves as industry-specific forecast inputs.
Material uncertainties — Black Sea supply disruptions, SFDA-ESMA harmonization delays, and retort pouch substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding subsidy policy continuity and aviation route network expansion. Recalibration cycles align with material shifts in wheat procurement policy, regulatory harmonization milestones, and packaging technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Market
Bakery Products
Fortified Bakery Market
Bakery Products
South America Bakery Products Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
Pastry Dough Market
Bakery Products
Bread Mix Market
Bakery Products
Banana Bread Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Europe Zwieback Market
Bakery Products
Baking Mats Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Pastry Margarine Market
Bakery Products
Biscuits Market
Bakery Products
Bread Premix Market