
 North America Par Baked Bread Market | 2026-2036
North America Par Baked Bread Market Size, Share, and Industry Trends Forecast 2026-2036
North America Par Baked Bread Market Analytics
Premium artisan specifications is unwinding commodity-grade volume dominance across the North America par baked bread category. Bimbo Bakeries USA leverages its continental plant network and direct-store-delivery infrastructure to sustain retail shelf presence in conventional supermarkets. La Brea Bakery specializes in crust-forward, long-fermentation par baked formats that anchor the premium food service channel for independent restaurants.
Par baked bread refers to dough that undergoes partial baking to set structure and develop flavor, then receives rapid chilling or freezing to arrest the Maillard reaction, with final baking completed at point of sale using convection or deck ovens at temperatures typically ranging from 350°F to 450°F. The product serves commercial kitchens seeking fresh-baked aroma and texture without skilled bakers or proofing equipment on premises. Artisan bread and gluten-free bread represent the fastest-expanding product type categories, as margin pools concentrate in differentiated formats rather than commoditized white bread. Food service dominates end user demand structurally, while supermarkets and online retail compete for household penetration through frozen and refrigerated case placement.
The FDA's Food Safety Modernization Act preventive controls rule shapes manufacturing facility design and hazard analysis requirements for par baked producers operating across state lines. USDA organic certification and non-GMO verification standards increasingly gate access to premium distribution channels in the United States and Canada. Stakeholders must monitor evolving state-level extended producer responsibility legislation for packaging, as plastic bags and tray packs face recycling mandate pressure that could shift cost structures across the supply base.
Market Dynamics
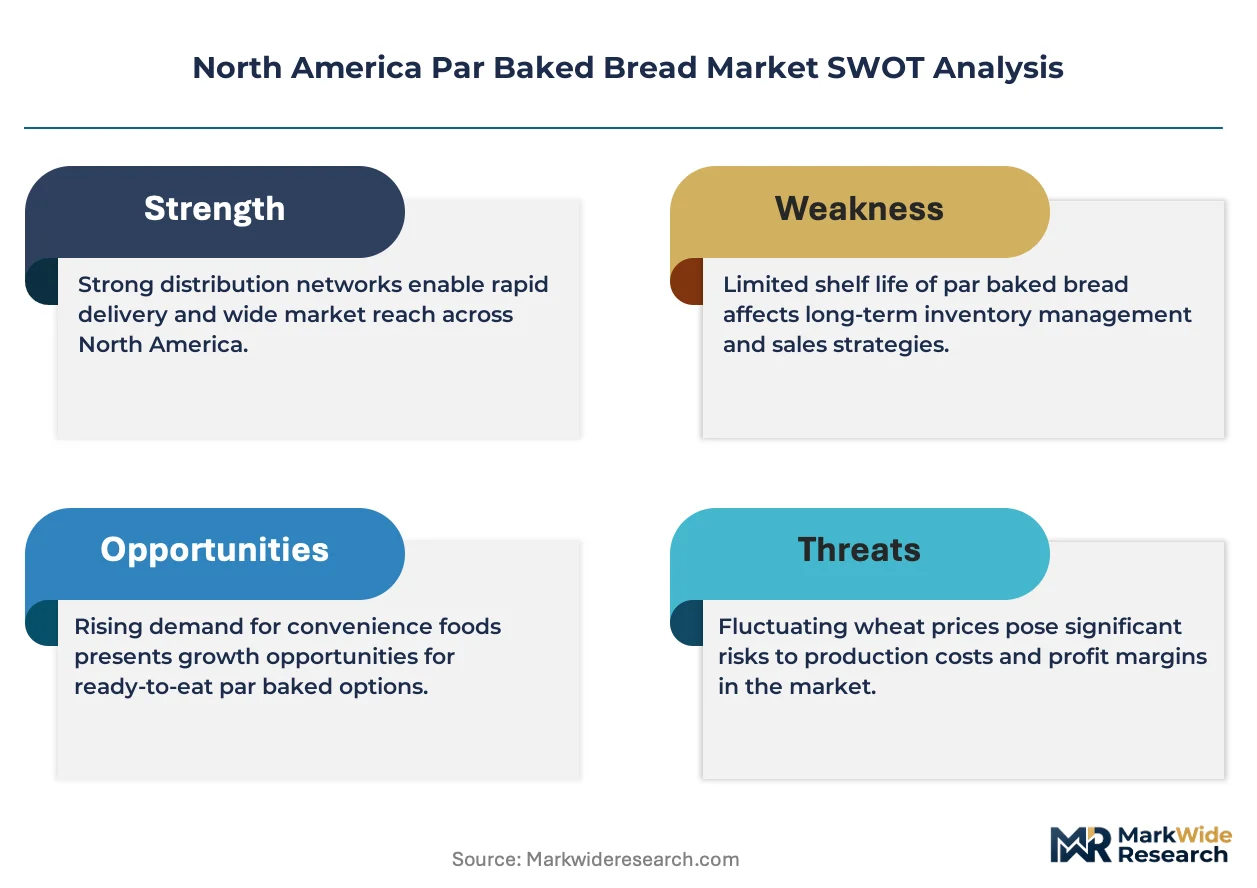
The FDA's Food Safety Modernization Act preventive controls rule is compressing artisan production into centralized industrial facilities, forcing regional bakeries to consolidate proofing and par baking operations or exit interstate commerce entirely.
Growth Catalysts
- Quick-service restaurant expansion:Chains are stripping in-house baking infrastructure from new locations, outsourcing par baked supply to reduce labor costs and real estate footprints. Frozen dough logistics networks now reach secondary US markets previously served by scratch kitchens.
- USDA organic certification demand:Premium food service channels in the US Northeast and Pacific Northwest now gate vendor access behind verified organic grain sourcing and non-GMO verification standards.
- Cold-chain infrastructure maturation:Refrigerated trucking density along the I-95 and I-80 corridors enables frozen par baked inventory to reach independent restaurants within 24 hours of production.
Market Restraints
- Wheat price volatility:Input cost swings for hard red winter and spring wheat varieties compress margins for commodity-grade par baked producers lacking long-term grain contracts.
- Supply concentration in Upper Midwest milling:Three grain processing clusters control bulk flour supply to North American par bakers, creating vulnerability to regional weather shocks and rail bottlenecks.
- Energy cost exposure:Natural gas and electricity price spikes in Ontario and Quebec directly impact blast freezing and controlled-atmosphere storage economics for Canadian producers.
Strategic Opportunities
- Gluten-free formulation white space:Celiac disease diagnosis rates in the US and Canada outpace dedicated gluten-free par baked capacity, opening shelf space for certified allergen-free entrants.
- Extended producer responsibility tailwinds:California and New York state packaging recycling mandates are accelerating compostable tray and cellulose film adoption, rewarding early format converters.
- Direct-to-restaurant platform channels:Food service purchasing cooperatives and B2B marketplace platforms are disintermediating traditional broadline distributors for independent restaurant accounts.
Industry Challenges
- Skilled fermentation technician scarcity:Long-fermentation artisan par baking requires trained staff capable of managing variable hydration doughs and retarding schedules, a competency gap in secondary US labor markets.
- Multi-certification timeline compression:Simultaneous pursuit of USDA organic, non-GMO Project verification, and SQF food safety certification creates 18-24 month product launch delays for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Par Baked Bread Market |
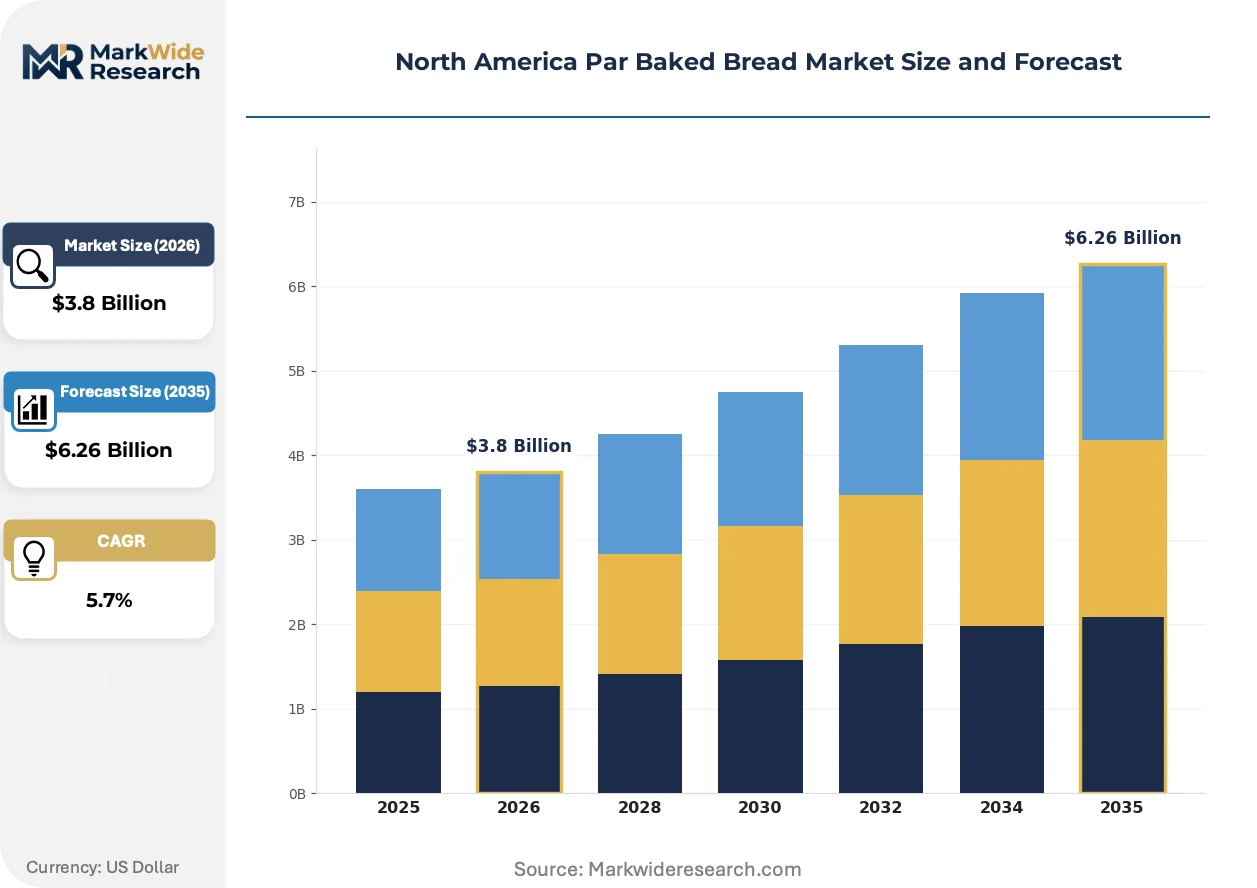
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Gluten-Free Bread, Artisan Bread Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Bakeries, Catering Services Packaging Type: Plastic Bags, Cardboard Boxes, Vacuum-Sealed, Tray Packs |
| Companies Covered | Richs USA, Lantmannen Unibake, Bimbo Bakeries USA, Flowers Foods, Canada Bread Company, Rich Products Corporation, CSM Bakery Solutions, La Brea Bakery, Maison Cousin, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Par Baked Bread Market Evolving Landscape
Controlled-atmosphere packaging and precision fermentation monitoring are compressing the gap between industrial scale and artisan quality claims, reshaping how par baked products are positioned across price tiers.
Modified atmosphere packaging with oxygen scavengers and nitrogen flushing is fragmenting the frozen-refrigerated binary that historically defined par baked distribution. Mid-sized regional bakeries in Michigan and Pennsylvania are adopting this technology to place crust-forward loaves in refrigerated rather than frozen cases. The structural consequence is fragmenting supermarket shelf allocation between conventional frozen dough and premium refrigerated formats that command higher slotting fees.
The FDA's updated Food Safety Modernization Act preventive controls for human food rule is mandating hazard analysis and risk-based preventive controls across all facilities shipping par baked products across state lines. Bakeries must now document supply chain verification for every flour lot and implement environmental monitoring for pathogens. Small and mid-sized producers in Vermont and Oregon are responding by consolidating into shared commercial kitchens or selling exclusively within single-state markets to avoid interstate compliance costs.
Food service buyers are unbundling after-sales technical support from product supply contracts, demanding standalone training on final baking protocols and equipment calibration. Independent restaurants in Chicago and Toronto are replacing bundled distributor relationships with direct procurement from par bakers plus third-party oven technician subscriptions. This pattern is most visible in the fast-casual segment, where menu differentiation depends on consistent crust texture that staff turnover threatens.
North America Par Baked Bread Market Segmentation
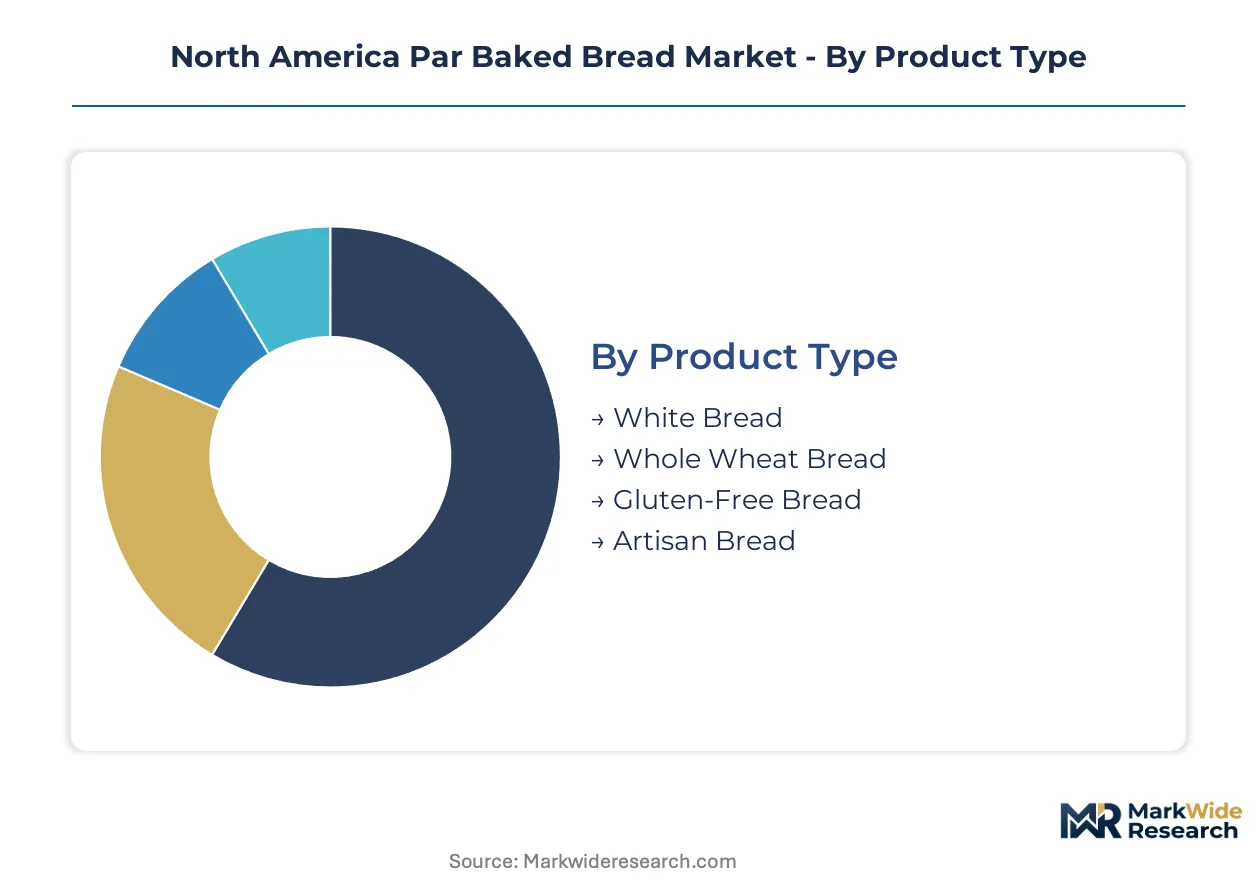
Par baked bread segmentation reveals how channel economics and end-use requirements fragment production specifications across North America. Product format, distribution pathway, and packaging technology each create distinct margin pools that bakeries must target with dedicated capacity investments.
Product Type:
Channel-mix dynamics split product type demand between commodity retail formats and premium food service specifications, with each tier demanding different fermentation protocols and shelf-life engineering.
- Artisan Bread:Long-fermentation sourdough and rustic European varieties command premium placement in independent restaurants across the US Northeast. Crust development and irregular crumb structure require specialized par baking curves that limit production to dedicated facilities. Food service buyers in Boston and Manhattan now specify minimum 12-hour cold fermentation as a procurement gate.
- Gluten-Free Bread:Rice flour and tapioca starch formulations with xanthan gum binding systems serve celiac-diagnosed consumers and allergen-sensitive food service accounts. Dedicated production lines prevent cross-contamination, constraining supply as diagnosis rates climb faster than certified capacity expansion in Ontario and Quebec.
- White Bread:Standardized commodity loaves dominate supermarket frozen cases with uniform crumb density and extended freezer stability. Quick-service restaurants in the US Midwest specify this format for sandwich platforms where cost control outweighs differentiation.
- Whole Wheat Bread:Hard red wheat flour blends with bran inclusion target health-positioned retail segments and institutional food service contracts. Bran particle size and hydration levels require adjusted par baking temperatures to prevent excessive moisture retention.
By volume, White Bread leads. By growth pace, Artisan Bread is ahead.
Distribution Channel:
Cost tier stratification separates frozen mass-market logistics from refrigerated premium distribution, with each channel imposing distinct working capital and slotting fee burdens on suppliers.
- Food Service:Broadline distributors and direct-to-restaurant platforms move frozen par baked inventory through temperature-controlled warehouses to commercial kitchens. Chains like Panera and Chipotle specify final-bake training protocols as contract attachments, unbundling technical support from product supply.
- Supermarkets:Frozen dough and refrigerated case placement compete for shelf space with scratch bakery programs, with premium formats gaining refrigerated allocation as controlled-atmosphere packaging matures. Slotting fees and promotional allowances compress margins for regional bakeries lacking national scale.
- Online Retail:Direct-to-consumer frozen shipments require insulated packaging and dry ice logistics that limit viable shipping radii to 48 hours from production facilities. Subscription models in California and New York concentrate demand for gluten-free and organic certified formats.
- Convenience Stores:Thaw-and-sell programs for breakfast sandwiches and grab-and-go bakery rely on extended shelf-life formulations and minimal equipment requirements at point of sale. Petroleum retail chains in Texas and Florida are expanding fresh-baked aroma programs to drive morning traffic.
Food Service captures the largest revenue share. Online Retail is climbing the fastest.
End User:
Application-specific requirements divide end user demand between consistency-dependent commercial operations and variety-seeking household consumption.
- Restaurants:Independent and fast-casual operators prioritize crust texture consistency and labor elimination, driving specification of par baked loaves with narrow final-bake temperature windows. Chicago and Toronto restaurant groups now procure through B2B platforms that disintermediate traditional distributors.
- Households:Supermarket and online purchases focus on convenience and perceived freshness, with refrigerated formats gaining preference over frozen as modified atmosphere packaging extends chilled shelf life. Weekend baking rituals support premium price acceptance for artisan-positioned products.
- Bakeries:Small retail bakeries use par baked bases to extend product variety without proofing equipment investment, particularly for seasonal and specialty items with intermittent demand. Rural and secondary market operations depend on this model to compete with supermarket in-store programs.
- Catering Services:Volume events and institutional contracts demand bulk formats with reliable yield and minimal final preparation time. Wedding and corporate catering operators in the US Northeast specify pull-apart rolls and baguette formats with synchronized bake completion timing.
Restaurants dominate procurement volume. Catering Services show the steepest expansion trajectory.
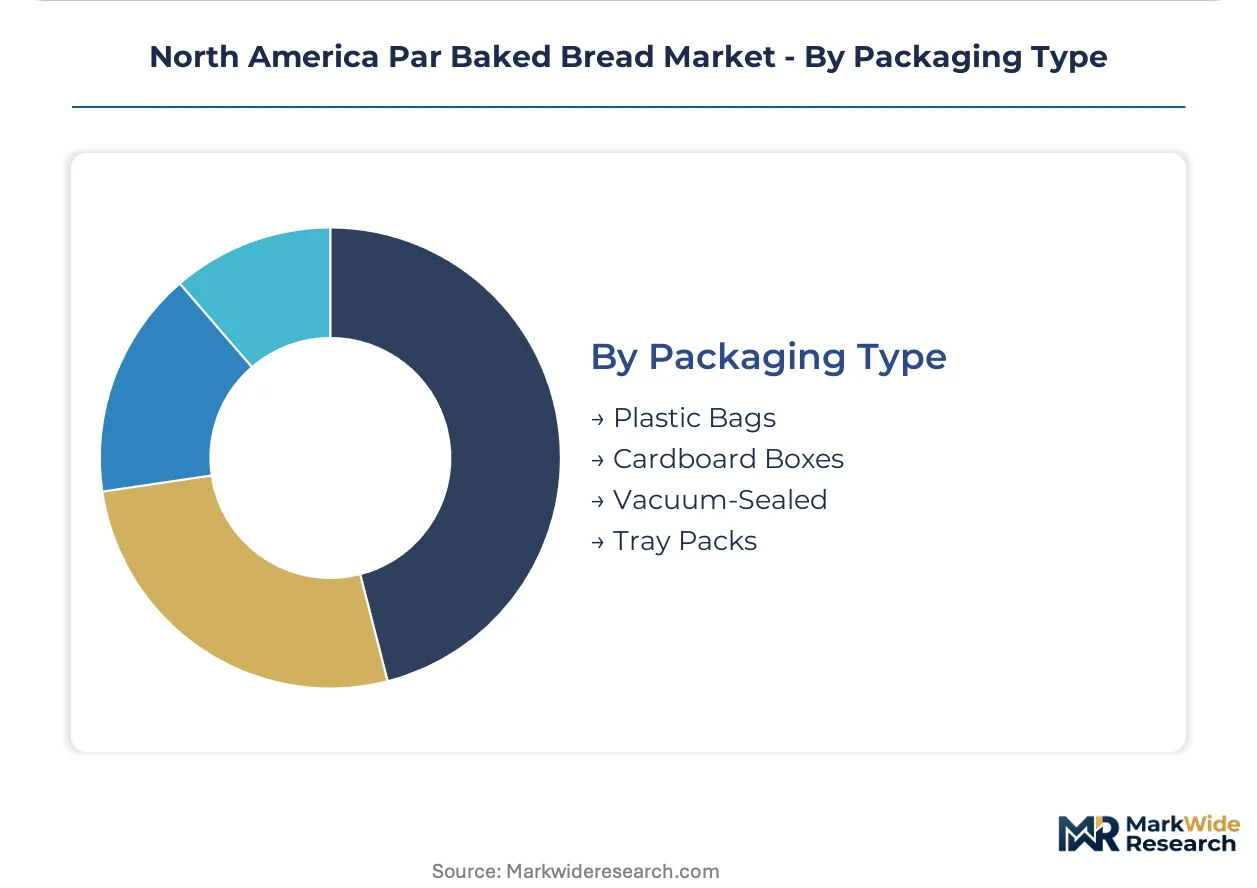
Packaging Type:
Margin concentration varies with packaging technology investment, as premium formats capture sustainability premiums while commodity formats face regulatory pressure.
- Vacuum-Sealed:Oxygen exclusion extends refrigerated shelf life to 21 days, enabling premium placement in supermarket deli cases and food service accounts with limited freezer capacity. Michigan and Pennsylvania regional bakeries have adopted this technology to access refrigerated distribution previously reserved for fresh baked goods.
- Tray Packs:Rigid plastic or molded fiber containers protect artisan loaves with fragile crust structures through distribution, commanding higher unit economics in premium channels. California and New York extended producer responsibility legislation is accelerating compostable tray adoption.
- Plastic Bags:Polyethylene and polypropylene film dominates frozen commodity formats with cost efficiency and moisture barrier performance. Recycling mandate pressure in Ontario and Quebec is forcing reformulation toward recyclable or biodegradable alternatives.
- Cardboard Boxes:Corrugated cases with moisture-resistant coatings serve bulk food service and institutional shipments where individual unit protection matters less than pallet efficiency. Quick-service restaurant distribution centers specify box dimensions optimized for automated handling systems.
Plastic Bags lead by shipment volume. Vacuum-Sealed formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America par baked bread market runs a structural trade surplus, with Canadian and US producers exporting frozen dough formats into Mexico while importing specialty grain varieties from the Upper Midwest milling belt.
United States
Quick-service restaurant chains strip in-house baking infrastructure from new locations across the Southeast and Southwest, outsourcing frozen par baked supply to reduce labor costs. The FDA's Food Safety Modernization Act preventive controls rule compresses artisan production into centralized industrial facilities, forcing regional bakeries to consolidate operations or exit interstate commerce. The Northeast corridor from Boston to Washington anchors premium food service demand, where dense restaurant infrastructure and cold-chain logistics networks support rapid distribution of frozen inventory.
Canada
Institutional food service contracts in Ontario and Quebec drive procurement of whole wheat and gluten-free par baked formats for healthcare and education sectors. Natural gas and electricity price spikes in Ontario and Quebec directly impact blast freezing and controlled-atmosphere storage economics for domestic producers. Toronto and Montreal host the primary production clusters, with regional bakeries adopting modified atmosphere packaging to access refrigerated supermarket placement previously reserved for fresh baked goods.
Mexico
Expanding quick-service restaurant footprints in Mexico City and Monterrey create import demand for frozen par baked bases from US and Canadian suppliers. The country's federal sanitary regulator enforces preventive control standards aligned with US FDA frameworks for cross-border food safety equivalence. Northern border states concentrate distribution infrastructure, with Nuevo León and Baja California serving as entry points for frozen dough logistics networks reaching central Mexican markets.
North America Par Baked Bread Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions, producing a tiered structure where scale-driven conglomerates anchor volume contracts while regional artisans capture premium food service margins. The vendor base stratifies into three archetypes: continental plant networks with direct-store-delivery infrastructure, crust-forward fermentation specialists serving independent restaurants, and diversified frozen food conglomerates leveraging cross-category cold-chain assets. Dominant competitive moves include M&A-driven consolidation of regional baking capacity and strategic partnerships with B2B marketplace platforms disintermediating traditional broadline distributors.
Within the scale-driven tier, Bimbo Bakeries USA and Flowers Foods exemplify continental coverage strategies, while La Brea Bakery occupies the premium artisan position with long-fermentation formats. Rich Products Corporation and CSM Bakery Solutions represent diversified frozen food conglomerates with cross-category cold-chain leverage. Lantmannen Unibake and Canada Bread Company anchor transnational supply relationships spanning the US-Canada border.
| Leading Market Players |
|---|
| Richs USA |
| Lantmannen Unibake |
| Bimbo Bakeries USA |
| Flowers Foods |
| Canada Bread Company |
| Rich Products Corporation |
| CSM Bakery Solutions |
| La Brea Bakery |
| Maison Cousin |
| Others |
Value Network & Pricing Analysis
USDA organic certification and non-GMO Project verification standards gate supply qualification for premium par baked bread channels while simultaneously enabling price premiums that commodity-grade producers cannot access. This dual-gating mechanism concentrates margin capture among certified facilities and fragments the competitive landscape into certification-tiered pricing bands.
Pricing Analysis
Industrial food service buyers anchor contract pricing through volume commitments and long-term supply agreements with frozen par baked suppliers. Three-tier pricing structure across premium artisan, standard commercial, and economy white bread levels reflects fermentation complexity and certification investment. Cost compression in commodity white bread intensifies because quick-service restaurant chains consolidate procurement through broadline distributors. Independent restaurants show least price sensitivity for long-fermentation artisan formats where crust texture consistency commands procurement priority.
Supply Chain Analysis
Frozen par baked inventory cycles through 30-45 day production-to-consumption windows, constraining working capital efficiency for regional bakeries without national distribution networks. Supply concentrates in the Upper Midwest milling belt of the United States and southern Ontario production clusters, with hard red winter wheat and specialty grain varieties drawing from Kansas, Nebraska, and Canadian prairie provinces. Single-source vulnerability runs through three dominant flour milling groups controlling bulk supply to North American par bakers. Distribution runs through temperature-controlled broadline distributor warehouses reaching commercial kitchens within 24 hours along I-95 and I-80 corridor density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in gluten-free and extended-shelf-life refrigerated formats where diagnosis rates and packaging innovation outpace dedicated production capacity. Unbundling of technical support from product supply contracts creates niche entry points for specialized service providers.
For Market Incumbents: Compound certification advantages by consolidating USDA organic and non-GMO verification into unified facility audits that reduce compliance overhead for multi-brand portfolios. Acquire regional artisan bakeries in Vermont and Oregon before interstate FDA preventive controls compliance costs force distressed exits. Cold-chain infrastructure leverage anchors defensive positioning against emerging B2B marketplace platforms disintermediating traditional distributor relationships. For New Entrants and Emerging Players: Differentiate on dedicated gluten-free production lines with third-party allergen certification to capture shelf space where celiac diagnosis rates outpace certified capacity expansion in Ontario and Quebec. Target independent fast-casual restaurants in Chicago and Toronto through direct procurement platforms that bypass broadline distributor markups. Lead with standalone final-bake training subscriptions unbundled from product supply to capture technical support revenue streams. For Investors and Strategic Acquirers: FDA Food Safety Modernization Act enforcement reshapes the acquisition landscape toward centralized industrial facilities with documented hazard analysis controls over fragmented regional artisan operations. Five-to-ten year viability favors transnational producers with cross-border cold-chain assets spanning US-Canada distribution networks. Signal to watch is California and New York extended producer responsibility legislation acceleration forcing packaging format conversion costs onto unprepared commodity-grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Consolidation | Unified USDA organic and SQF audits reduce compliance timeline from 18-24 months to 12-15 months for multi-product launches. |
| Modified Atmosphere Packaging Adoption | Oxygen scavenger and nitrogen flushing systems enable refrigerated case placement previously reserved for fresh baked goods. |
| Direct-to-Restaurant Platform Partnership | B2B marketplace integration disintermediates broadline distributors for independent restaurant accounts in dense urban corridors. |
| Gluten-Free Line Investment | Dedicated allergen-free capacity captures margin premiums where diagnosis rates exceed certified production expansion. |
| Compostable Packaging Conversion | Cellulose film and molded fiber tray adoption preempts California and New York extended producer responsibility compliance costs. |
Research Methodology
Operator-level perspectives from plant managers at regional bakeries, procurement directors at quick-service restaurant chains, category buyers at supermarket retailers, and cold-chain logistics coordinators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA preventive controls guidance documents, USDA organic certification databases, customs trade records for frozen dough shipments, and broadline distributor financial disclosures. Bottom-up capacity estimates from identified production facilities triangulated against top-down demand segmentation from food service procurement patterns.
Sensitivity analysis across wheat price volatility scenarios, energy cost shocks in Ontario and Quebec, and regulatory enforcement intensity variations informed projection robustness. Segmentation dimensions modeled include product type tier, distribution channel pathway, end-user application, and packaging technology format across the analysis window. CAGRs derived from historical shipment volume trajectories adjusted for channel-mix shifts and certification penetration curves. Forecast inputs incorporated cold-chain infrastructure expansion timelines and quick-service restaurant new-location buildout rates.
Material uncertainties — wheat commodity price spikes, interstate FDA enforcement intensity variations, and state-level packaging mandate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification adoption rates and frozen logistics network density expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Dough Improver Market
Bakery Products
Matcha Cookie Market
Bakery Products
Bread Premix Market
Bakery Products
Bread Crumbs Market
Bakery Products
Pastries Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Bakery Premixes Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Sourdough Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Lentil Bread Market