
 Global Calcium Hypochlorite Market | 2026-2036
Global Calcium Hypochlorite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calcium Hypochlorite Market Foresight
Aftermarket service revenue for technical-grade calcium hypochlorite supply contracts is reconfiguring profit pools away from commodity spot sales. Westlake Corporation leverages its integrated chlor-alkali operations to sustain cost advantages in North American distribution. Tianjin Kaifeng Chemical anchors its position through captive access to chlorine feedstock and regional logistics networks in northern China.
Calcium hypochlorite is an inorganic compound with the formula Ca(OCl)2, typically manufactured through the reaction of chlorine gas with slaked lime to yield a product containing 65-70% available chlorine; it functions primarily as a strong oxidizing agent for water disinfection, bleaching, and sanitization across municipal and industrial systems. Granular formulations dominate volume flows into municipal water treatment due to handling efficiency and controlled dissolution rates, while tablet formats are capturing expanded share in agricultural farm applications where precision dosing reduces waste. The pulp and paper application segment retains mature demand patterns in North America and Europe even as chemical manufacturing end uses in Asia-Pacific drive incremental volume growth.
The EPA regulates drinking water disinfectant residuals under the Safe Drinking Water Act, while China's MEE enforces GB standards for chlorine-based water treatment chemicals, and India's BIS certification mandates product quality benchmarks for municipal procurement—collectively elevating compliance costs for non-conforming suppliers and tightening market access. The EU REACH framework further restricts hazardous substance thresholds in imported calcium hypochlorite destined for European textile bleaching operations. Stakeholders must monitor evolving chlorate byproduct limits across jurisdictions and assess backward integration into lime sourcing as a buffer against feedstock volatility.
Market Dynamics
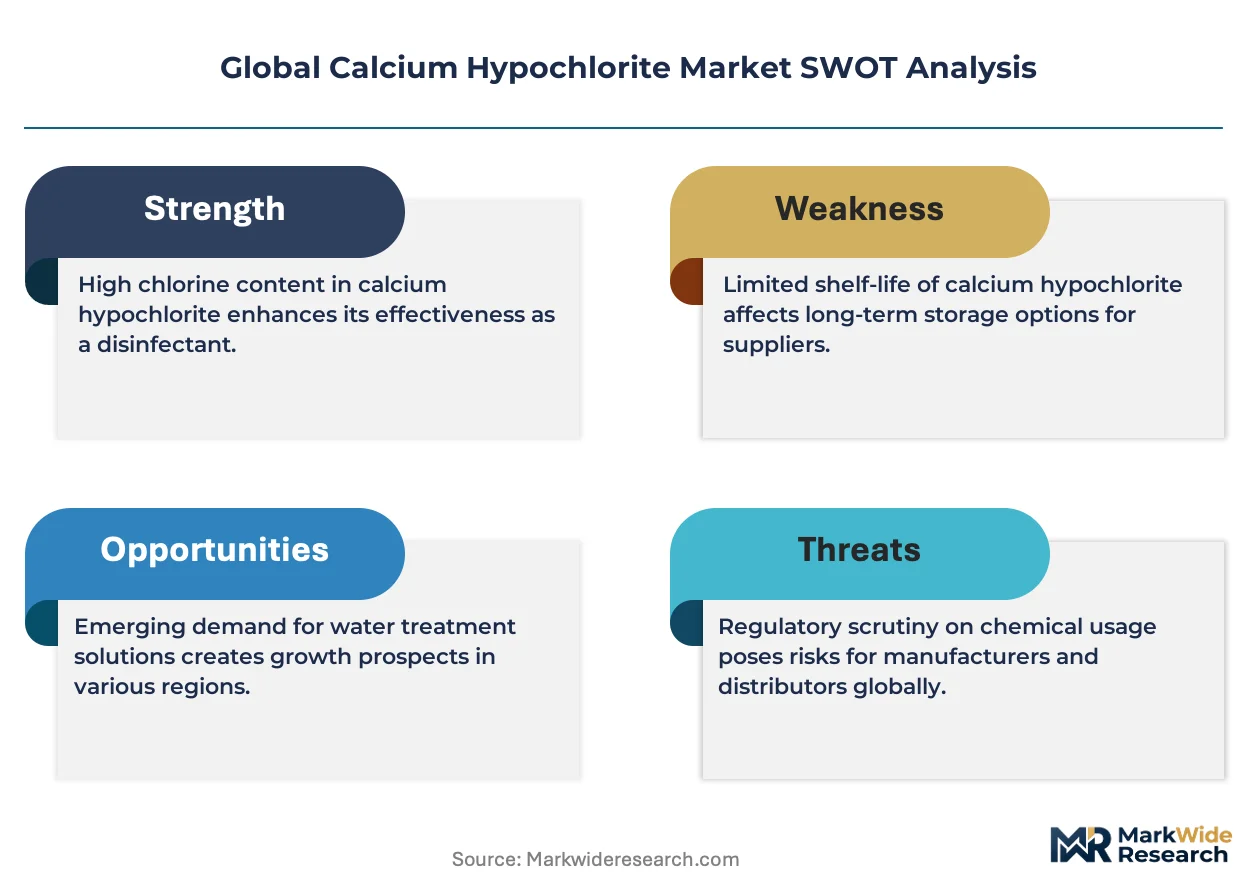
Feedstock volatility in chlor-alkali chains and tightening chlorate byproduct limits across multiple jurisdictions are compressing margins for non-integrated calcium hypochlorite suppliers while rewarding captive chlorine producers.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:Residual chlorine monitoring mandates in US municipal systems sustain specification-grade demand and displace lower-purity alternatives.
- Jal Jeevan Mission procurement:India's rural water infrastructure program generates bulk chemical purchases for decentralized chlorination stations.
- Tablet formulation advances:Controlled-release calcium hypochlorite tablets reduce dosing waste in agricultural irrigation systems and expand addressable farm applications.
Market Restraints
- Chlorine feedstock concentration:North American and Chinese chlor-alkali capacity clusters create geographic supply vulnerability for non-integrated compounders.
- EU REACH chlorate thresholds:Import restrictions on chlorite and chlorate byproducts in European textile bleaching applications limit market access for non-conforming suppliers.
- Sodium hypochlorite substitution:Liquid bleach systems capture share in small-scale municipal applications where storage infrastructure favors aqueous delivery.
Strategic Opportunities
- Indonesia municipal expansion:Urban water utility privatization in Jakarta and Surabaya creates specification-grade demand for granular disinfectant formats.
- On-site generation technology:Electrochlorination systems for remote industrial sites converge with calcium hypochlorite backup supply models.
- Brazilian agricultural export compliance:ANVISA sanitation mandates for produce processing drive tablet adoption in fruit and vegetable washing operations.
Industry Challenges
- Chlorate analytical certification:Multi-jurisdiction testing protocols for perchlorate and bromate byproducts extend product qualification timelines for new suppliers.
- Legacy lime sourcing integration:Backward integration into high-calcium limestone quarries demands capital deployment that mid-scale compounders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calcium Hypochlorite Market |
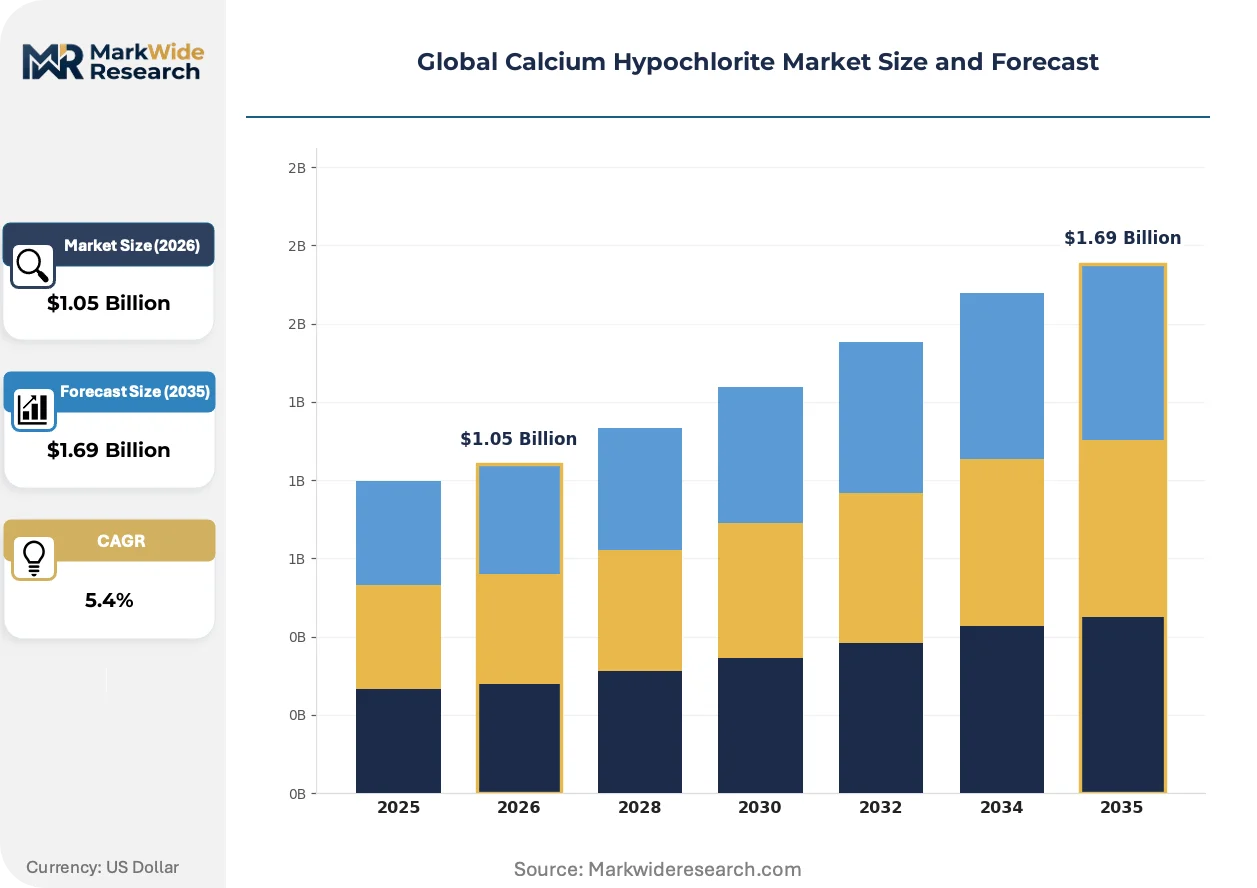
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Tablets, Powdered, Pellets Application: Water Treatment, Pulp & Paper, Textiles, Chemical Manufacturing End User Industry: Municipal Facilities, Industrial Plants, Food Processing Units, Agricultural Farms Packaging Type: 20 kg Bags, 25 kg Bags, Drums, Bulk Containers |
| Companies Covered | Westlake Corporation, Tianjin Kaifeng Chemical Co., Ltd., Tosoh Corporation, Nippon Soda Co., Ltd., Olin Corporation, Lonza Group Ltd, Sinopec, Grasim Industries Limited, Huanghua Kaifeng Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calcium Hypochlorite Market Shifts & Advancements
Digital monitoring systems and automated dosing infrastructure are reshaping how municipal buyers evaluate calcium hypochlorite suppliers, shifting procurement criteria from unit price to total system reliability.
Smart chlorine residual sensors are digitizing water treatment operations by enabling real-time dosage adjustment based on automated turbidity and flow readings. Municipal utilities in Germany and Japan deploy these systems to minimize over-chlorination and reduce chemical consumption. The technology is compressing supplier margins on commodity-grade material while creating service revenue attachments for integrated providers.
China's MEE enforcement of revised GB standards for chlorine-based disinfectants is elevating purity specifications for imported calcium hypochlorite. Domestic manufacturers must upgrade crystallization and drying processes to meet tightened chlorate limits. European textile bleaching operations sourcing from Chinese suppliers face extended qualification audits and third-party certification requirements.
Consolidated procurement by national water authorities is displacing fragmented municipal purchasing in Southeast Asia. Thailand's Metropolitan Waterworks Authority and Vietnam's provincial water companies now negotiate multi-year supply agreements directly with compounders, bypassing traditional distributor networks. This concentration is most visible in Bangkok and Ho Chi Minh City, where specification-grade granular contracts now run three to five years.
Global Calcium Hypochlorite Market Segmentation
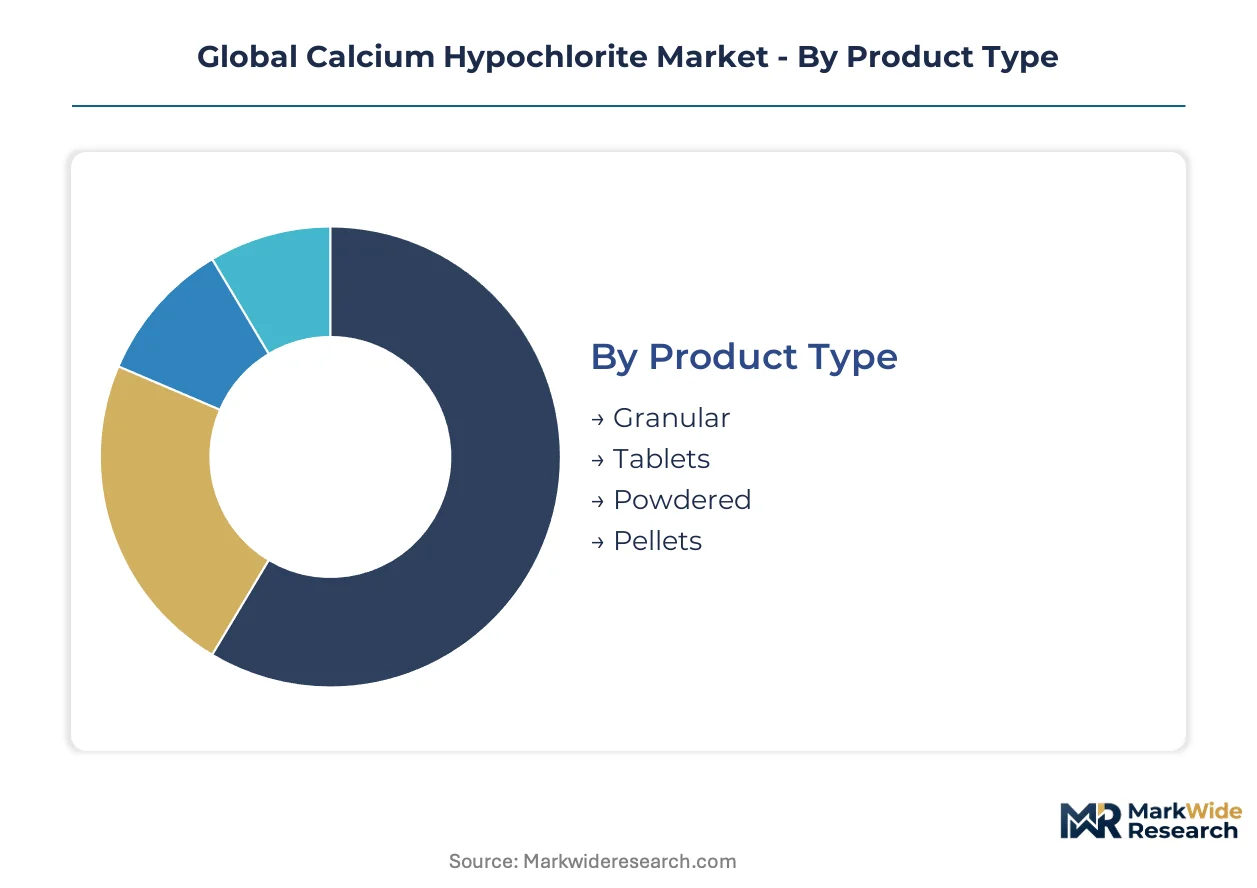
Calcium hypochlorite procurement patterns diverge sharply across formulation types, application environments, and packaging configurations. Specification requirements from municipal water authorities and industrial end users create distinct demand clusters that reward targeted product positioning.
Product Type:
Mature granular formats coexist with emerging tablet technologies as suppliers balance handling efficiency against precision dosing requirements.
- Granular:Irregular crystalline particles containing 65-70% available chlorine dissolve at controlled rates suited to large-scale municipal dosing systems. Procurement concentrates in Southeast Asian urban water utilities where Bangkok and Jakarta authorities specify flowable formats for automated feed equipment.
- Tablets:Compressed cylindrical forms enable measured release in agricultural irrigation and remote chlorination stations. India's Jal Jeevan Mission drives tablet adoption in rural decentralized systems where operator training limits liquid handling competence.
- Powdered:Fine particulate grades serve textile bleaching operations requiring rapid dispersion in heated wash liquors.
- Pellets:Uniform spherical particles reduce dust generation during pneumatic conveying in industrial chemical manufacturing.
Granular retains volume leadership; tablets hold the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade municipal contracts from commodity industrial volumes.
- Water Treatment:Drinking water disinfection consumes high-purity grades certified to EPA Stage 2 and China's GB standards. Procurement runs through multi-year agreements with national water authorities in Thailand and Vietnam.
- Pulp & Paper:Bleaching sequences in North American kraft mills employ calcium hypochlorite in oxygen-delignification stages. Demand patterns remain mature with limited technology substitution.
- Textiles:Cotton bleaching operations in India and Bangladesh source chlorate-compliant grades for export garment processing.
- Chemical Manufacturing:Organic synthesis and sanitization in Chinese and Indian specialty chemical plants drives incremental volume expansion.
Water treatment commands premium pricing tiers; chemical manufacturing delivers the fastest volume climb.
End User Industry:
Customer type determines certification burden and contract duration, with municipal facilities imposing the most stringent qualification protocols.
- Municipal Facilities:Urban water treatment plants in Indonesia and the Philippines specify granular disinfectants with third-party chlorate certification. Procurement cycles extend 36-60 months with penalty clauses for supply interruption.
- Industrial Plants:Power generation and oilfield operations in the United States and Brazil deploy calcium hypochlorite for cooling water and produced water treatment.
- Food Processing Units:ANVISA-mandated sanitation in Brazilian fruit washing and dairy equipment cleaning drives tablet specification.
- Agricultural Farms:Drip irrigation systems in California's Central Valley and Spain's Almería province adopt controlled-release tablets to prevent biofouling.
Municipal facilities anchor contract value; agricultural farms are expanding most quickly.
Packaging Type:
Volume scale and handling infrastructure dictate packaging selection across geographic markets.
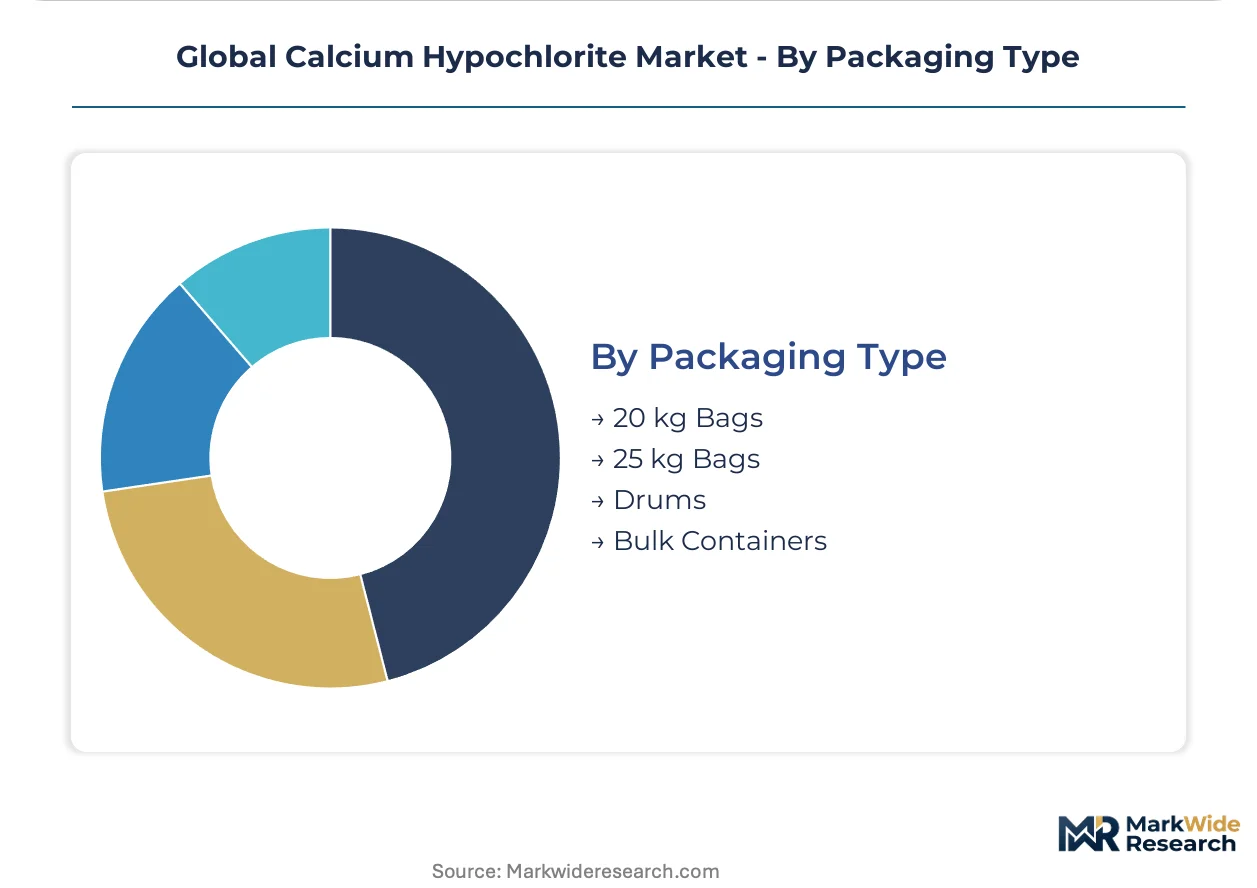
- 20 kg Bags:Standard unit loads for Southeast Asian distributor networks serving small municipal utilities.
- 25 kg Bags:European textile bleaching operations prefer this format for forklift handling compatibility.
- Drums:Industrial chemical plants in India and China receive drum shipments for direct feed system integration.
- Bulk Containers:Large municipal authorities in Bangkok and Ho Chi Minh City negotiate bulk deliveries to minimize packaging waste and handling labor.
25 kg bags retain procurement frequency leadership; bulk containers gain share fastest in consolidated purchasing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in municipal procurement varies sharply across geographies. Indian rural water authorities prioritize unit cost above all else, while German utilities absorb premium pricing for chlorate-certified grades. Southeast Asian urban buyers occupy the middle tier, balancing specification compliance against budget constraints.
United States
EPA Stage 2 residual monitoring mandates sustain demand for high-purity granular formats in municipal systems. The Safe Drinking Water Act enforcement elevates compliance costs for non-conforming imports. Chlor-alkali capacity clusters along the Gulf Coast anchor domestic supply chains serving Texas and Louisiana utilities.
China
MEE enforcement of revised GB standards is forcing crystallization process upgrades among domestic compounders. Dual carbon goals tighten energy intensity requirements for lime-chlorine reaction facilities. Tianjin and Shandong industrial corridors concentrate manufacturing capacity serving northern municipal markets.
India
Jal Jeevan Mission procurement volumes are accelerating tablet adoption in rural decentralized chlorination stations. BIS certification mandates create entry barriers for uncertified imports. Gujarat and Maharashtra chemical manufacturing zones supply bulk granular contracts to state water authorities.
Germany
Smart sensor deployment in municipal utilities minimizes over-chlorination and reduces chemical consumption intensity. REACH chlorate thresholds restrict textile bleaching imports to certified low-byproduct grades. Rhine-Ruhr industrial basin hosts specification-grade compounders serving Benelux export markets.
Brazil
ANVISA sanitation mandates for produce processing drive tablet specification in fruit washing operations. Agricultural export compliance requirements elevate certification burdens for chemical suppliers. São Paulo state water utility consolidation creates multi-year supply agreement opportunities for granular disinfectant providers.
Global Calcium Hypochlorite Market Competitive Landscape
Capability concentration sits with integrated chlor-alkali operators; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: captive chlorine producers with lime integration, regional compounders with distribution density, and import-dependent traders serving price-sensitive segments. Two dominant competitive moves are reshaping positioning: backward integration into high-calcium limestone quarries, and long-term municipal supply contracts that lock out spot-market competitors.
Among integrated North American operators, Westlake Corporation exemplifies the captive feedstock archetype through its Gulf Coast chlor-alkali infrastructure. Chinese compounders Tianjin Kaifeng Chemical Co., Ltd. and Huanghua Kaifeng Chemical Co., Ltd. anchor the regional logistics tier with northern China manufacturing concentration. Japanese specialists Tosoh Corporation and Nippon Soda Co., Ltd. occupy positions defined by precision process control and chlorate limit compliance for export textile markets.
| Leading Market Players |
|---|
| Westlake Corporation |
| Tianjin Kaifeng Chemical Co., Ltd. |
| Tosoh Corporation |
| Nippon Soda Co., Ltd. |
| Olin Corporation |
| Lonza Group Ltd |
| Sinopec |
| Grasim Industries Limited |
| Huanghua Kaifeng Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Chlor-alkali feedstock volatility in the United States and China determines both the premium-to-economy pricing spreads across specification grades and the geographic clustering of backward-integrated compounders versus import-dependent traders. EPA Stage 2 residual mandates and China's MEE chlorate limits amplify these spreads by disqualifying uncertified suppliers from municipal procurement tiers.
Pricing Analysis
Aftermarket service revenue from multi-year technical support contracts drives lifetime value more than commodity spot transactions. Three-tier pricing structure across premium EPA-certified, standard industrial-grade, and economy agricultural tiers separates municipal utilities from textile bleachers and farm operators. Cost compression in the economy tier is intensifying because Indian Jal Jeevan Mission buyers prioritize unit cost above certification. Municipal facilities in Germany and Japan absorb the widest premiums for chlorate-compliant granular formats, while rural Indian water authorities exhibit the highest price sensitivity.
Supply Chain Analysis
Contract-manufacturing concentration sits with captive chlor-alkali operators along the US Gulf Coast, Tianjin-Shandong corridor in northern China, and Gujarat-Maharashtra chemical zones in western India. Production draws from chlorine gas, high-calcium limestone, and slaked lime inputs with limited alternative sourcing. Single-source vulnerability concentrates in Chinese lime quarries serving northern compounders. Distribution runs through national water authority direct contracts in Southeast Asia, bypassing traditional distributor networks in Bangkok and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification barriers under EPA, MEE, and BIS standards create switching costs that lock municipal buyers into qualified supplier relationships.
For Market Incumbents: Pre-empt sodium hypochlorite substitution in small-scale municipal applications by embedding smart sensor service contracts that bundle granular supply with automated dosing infrastructure. Capture lime quarry assets in high-calcium limestone belts to secure feedstock autonomy against chlor-alkali volatility. The priority lever is backward integration into captive chlorine production. For New Entrants and Emerging Players: Pursue tablet formulation contracts in India's Jal Jeevan Mission rural stations where operator training gaps favor controlled-release formats over liquid handling. Target Brazilian agricultural compliance markets where ANVISA mandates drive fruit-washing sanitation demand. The penetrable entry point is ANVISA-certified tablet supply to São Paulo state produce processors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chlor-alkali operators with captive lime sourcing. Long-term viability over the next decade hinges on regulatory certification depth rather than commodity scale. The acquisition target archetype is regional compounders with BIS or EPA qualification pipelines and underutilized crystallization capacity. The signal to watch is chlorate limit tightening across additional Asian jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lime Quarries | Captive high-calcium limestone supply buffers Tianjin Kaifeng against feedstock volatility. |
| Smart Sensor Service Bundling | German utilities reduce chemical consumption through Tosoh Corporation's automated residual monitoring. |
| Tablet Formulation Scale-Up | Controlled-release formats penetrate India's Jal Jeevan Mission rural chlorination stations. |
| Multi-Year Municipal Supply Agreements | Thailand's Metropolitan Waterworks Authority locks out spot competitors with 36-month granular contracts. |
| Chlorate Compliance Certification | REACH thresholds restrict European textile bleaching imports to low-byproduct grades from Nippon Soda. |
Research Methodology
Desk research of customs trade databases, chlor-alkali industry association filings, and national water authority procurement records preceded structured interviews with municipal procurement managers, industrial chemical plant engineers, and distribution channel partners. Primary fieldwork with EPA-certified compounders and BIS-registered suppliers in India was cross-validated against secondary sources including SEC 10-K disclosures, MEE regulatory bulletins, and REACH compliance registries. Bottom-up volume estimates from end-use application segments were triangulated against top-down chlor-alkali capacity allocations.
Assumptions held fixed across the projection horizon include current EPA Stage 2 residual monitoring mandates, MEE GB standard enforcement levels, and Jal Jeevan Mission procurement volumes. Variables modeled across formulation type, application environment, end-user industry, and regional regulatory cluster drove segmentation outputs. CAGRs were derived from regression analysis of historical municipal water infrastructure spending and agricultural sanitation compliance trends, with chlorate limit trajectories and chlor-alkali capacity utilization serving as chemical-specific forecast inputs.
Sensitivities concentrate around MEE chlorate threshold revisions, Indian BIS certification timeline extensions, and Gulf Coast chlor-alkali outage events. Forecasts reflect these assumptions with acknowledged uncertainty in rural procurement acceleration rates. Quarterly review of national water authority tender announcements and MEE enforcement bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Allyl Chloride Market
Chemicals
South America Construction Chemicals Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Methylamines Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Guaiacol Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Menadione Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Morpholine Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Global Biotechnology-Based Chemical Market