
 Brazing Alloys Market | 2026-2036
Brazing Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Brazing Alloys Market Outlook
A capital-intensity divergence between integrated smelters and specialized alloy formulators is reorganizing competitive tiers in brazing alloys. Lucas-Milhaupt Inc. leverages captive wire-drawing and precision annealing capabilities to dominate North American supply for automotive HVAC joints. Umicore sustains a technology leadership position in low-cadmium silver alloy formulations through continuous R&D investment in Brussels and Toronto laboratories. Harris Products Group anchors its position via extensive distributor networks that control channel access for maintenance and repair end users across the United States.
Brazing alloys are non-ferrous metal filler materials, typically composed of copper-silver, nickel-chromium, or aluminum-silicon systems, that melt above 450°C but below the solidus of base metals to form metallurgical joints via capillary flow. Their primary industrial purpose is to join dissimilar metals in heat exchangers, turbine vanes, and electronic assemblies where welding would distort thin-gauge components or degrade base-metal properties. Silver-based alloys command premium positioning in aerospace and electronics applications where thermal conductivity and joint ductility justify material cost, while aluminum-based formulations are displacing mechanical fastening in automotive HVAC systems as OEMs pursue weight reduction targets. Nickel-based segments occupy specialized margin pools in power-generation and chemical-processing equipment where service temperatures exceed 800°C.
The EPA regulates brazing alloy composition under the Toxic Substances Control Act, particularly for cadmium-bearing formulations used in consumer-facing products, while REACH in Europe mandates disclosure of nickel and chromium content under SVHC protocols. China's GB standards through SAMR enforce compositional tolerances for imported filler metals used in pressure equipment, creating market-access friction for non-certified suppliers. Japan's METI energy-efficiency directives for HVAC equipment indirectly shape alloy demand by specifying minimum heat-exchanger performance thresholds that favor brazed designs. Stakeholders must monitor divergence between regional compositional standards and the pace of substitution toward cadmium-free silver systems.
Market Dynamics
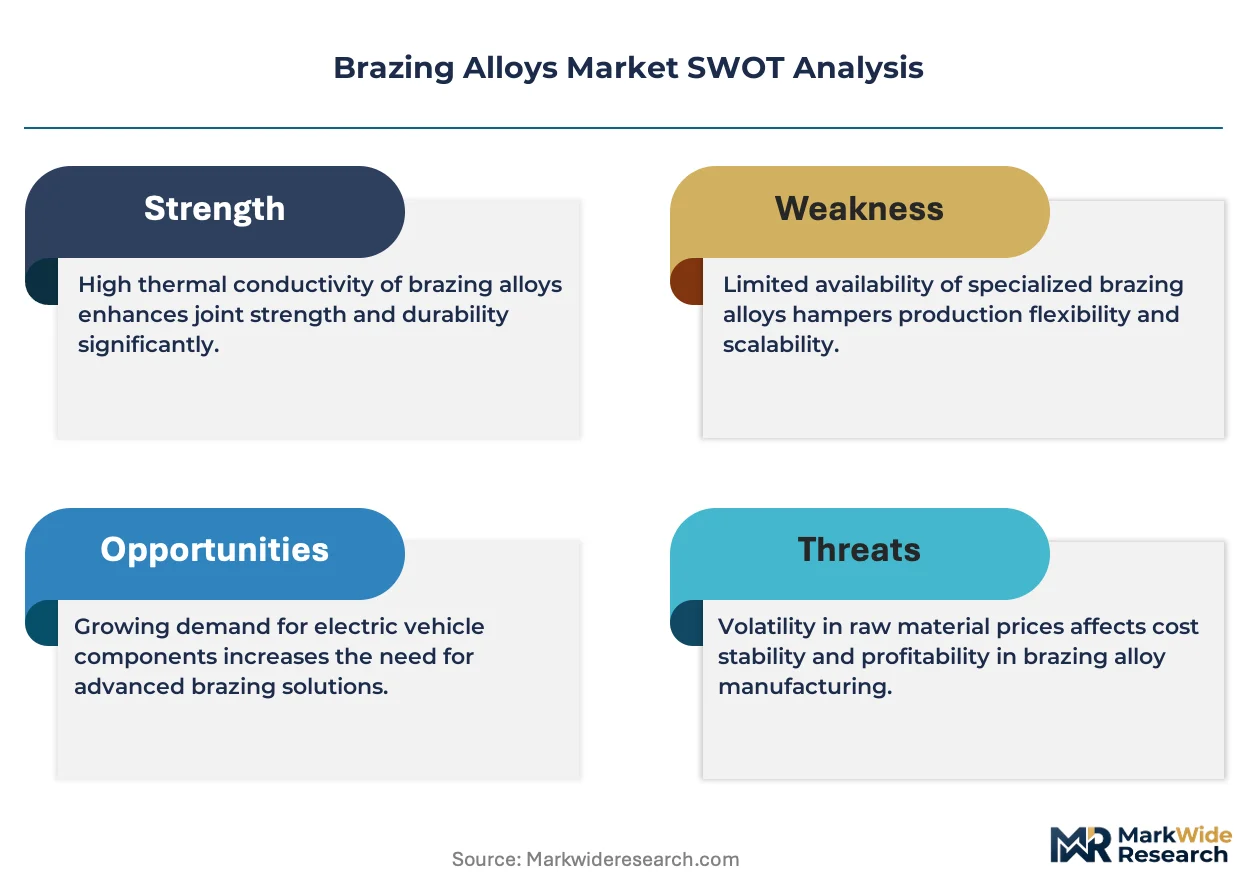
REACH cadmium restrictions and EPA Toxic Substances Control Act enforcement are forcing silver-alloy suppliers to reformulate legacy compositions, while nickel-based systems capture share in aerospace turbine applications as service temperature requirements escalate.
Growth Catalysts
- Aerospace Turbine Demand:United States and Germany manufacturers are expanding nickel-based filler metal procurement for jet engine assemblies. These alloys withstand service temperatures exceeding 800°C where conventional formulations fail.
- REACH Compliance Deadlines:European ECHA mandates are accelerating cadmium-free silver alloy adoption across electronics and consumer goods sectors. Suppliers with pre-certified low-cadmium portfolios capture switching demand from reformulation-lagged competitors.
- China HVAC Export Scaling:Eastern manufacturing corridor producers are ramping brazed heat exchanger output for Middle East and Southeast Asian climate-control markets. SAMR-certified filler metals are becoming mandatory for pressure-equipment export clearance.
Market Restraints
- Silver Price Volatility:Precious metal input costs swing with COMEX futures, compressing margin stability for alloy formulators without captive metal hedging programs.
- Specialized Smelter Concentration:High-purity nickel-chromium master alloy production clusters in German and Austrian integrated facilities, creating geographic supply vulnerability for Asia-Pacific fabricators.
- Aluminum Mechanical Fastening Substitution:Automotive OEMs in lightweighting programs occasionally specify self-piercing rivets for HVAC joint architectures, bypassing brazed solutions in cost-sensitive vehicle classes.
Strategic Opportunities
- India Industrial Infrastructure Buildout:BIS certification pathways for imported filler metals remain underpenetrated relative to projected power-generation and chemical-processing equipment demand through 2030.
- Hydrogen Economy Heat Exchangers:Electrolyzer and fuel-cell stack manufacturers are specifying corrosion-resistant nickel-brazed joints for high-purity hydrogen handling systems.
- Digital Alloy Specification Platforms:Technical distributors are deploying AI-assisted joint-design tools that match base-metal combinations to optimal filler compositions, capturing specification influence from traditional field sales channels.
Industry Challenges
- Metallurgical Talent Scarcity:Capillary flow modeling and joint-design expertise concentrates among aging specialists in German and Japanese technical centers, constraining formulation innovation velocity.
- Multi-Jurisdictional Certification Timelines:Parallel ASME, PED, and GB standard compliance testing extends product launch cycles by 18-24 months for unified global SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazing Alloys Market |
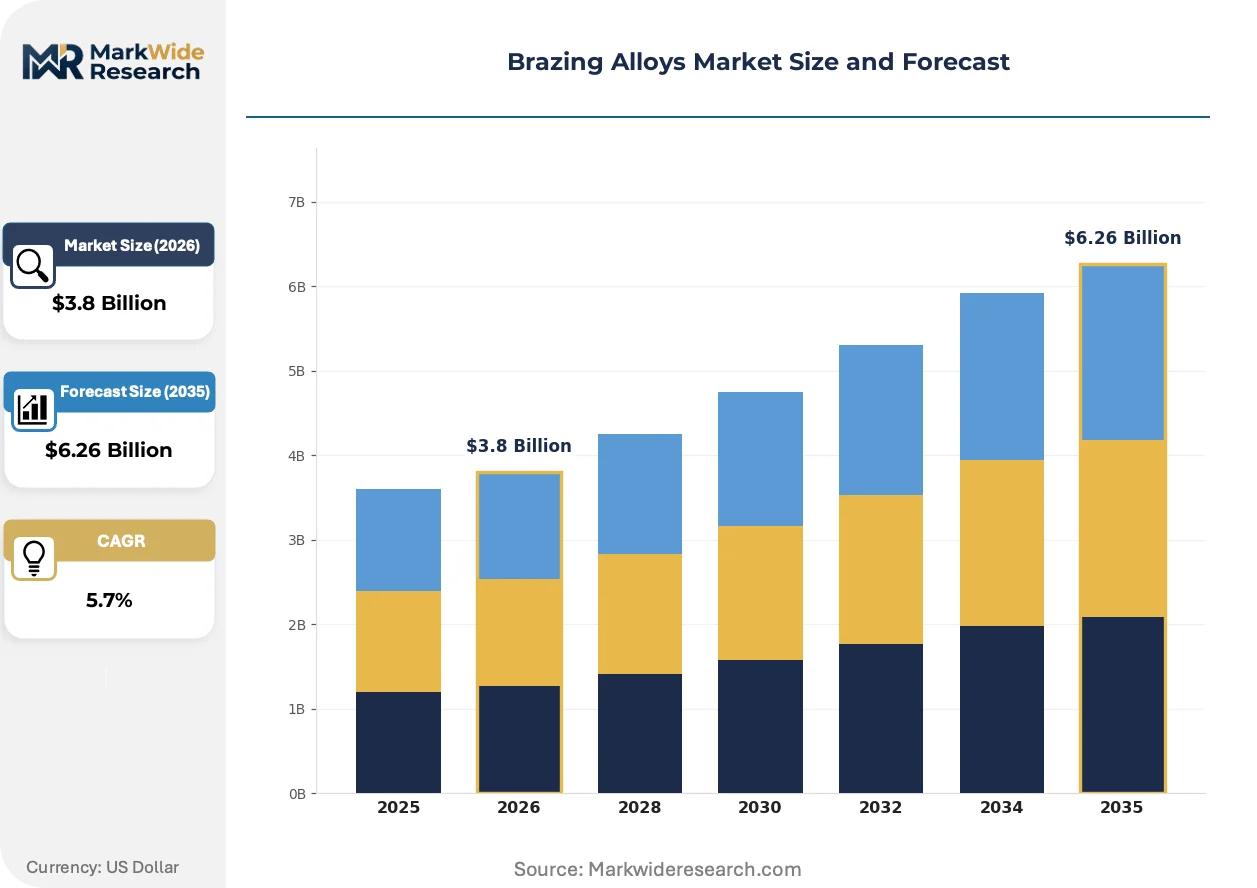
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-Based, Silver-Based, Aluminum-Based, Nickel-Based Application: Aerospace, Automotive, Electronics, HVAC End User: Manufacturing, Construction, Maintenance, Repair Form: Filler Rods, Pre-Forms, Powders, Sheets |
| Companies Covered | Lucas-Milhaupt Inc., Umicore, Harris Products Group, Prince & Izant Company, Johnson Matthey, Morgan Advanced Materials, Voestalpine Böhler Welding, Aimtek Inc., Wall Colmonoy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazing Alloys Market Strategic Shifts
Active brazing compounds with titanium or zirconium additions are reshaping ceramic-to-metal joint architectures, while digital supply-chain traceability tools are penetrating specification-sensitive end uses.
Active brazing formulations containing titanium hydride or zirconium interlayers are displacing conventional metallization-plus-brazing sequences in semiconductor packaging and power-module substrates. Ceramic substrate manufacturers in Japan and South Korea are adopting these single-step processes to reduce thermal resistance and assembly cost. The structural consequence is compression of the traditional multi-vendor ceramic metallization supply chain into integrated active-braze solution providers.
EPA cadmium enforcement under the Toxic Substances Control Act is tightening permissible content thresholds in consumer-facing silver alloys, compelling reformulation of legacy Cd-bearing compositions used in jewelry and plumbing applications. Alloy suppliers with Toronto and Brussels R&D footprints are accelerating cadmium-free silver-copper-zinc patent filings to secure composition-of-matter protection ahead of compliance deadlines. North American maintenance-and-repair distributors are experiencing the most acute product-transition friction as they dual-stock compliant and legacy SKUs.
Specification authority is migrating from end-user procurement departments to OEM engineering teams deploying digital joint-simulation platforms. Automotive HVAC system architects in Stuttgart and Detroit are increasingly mandating pre-validated filler metal grades from approved supplier lists, bypassing traditional distributor technical consultation. Germany's KBA type-approval documentation requirements for vehicle climate systems are accelerating this centralization of material specification authority.
Brazing Alloys Market Segmentation
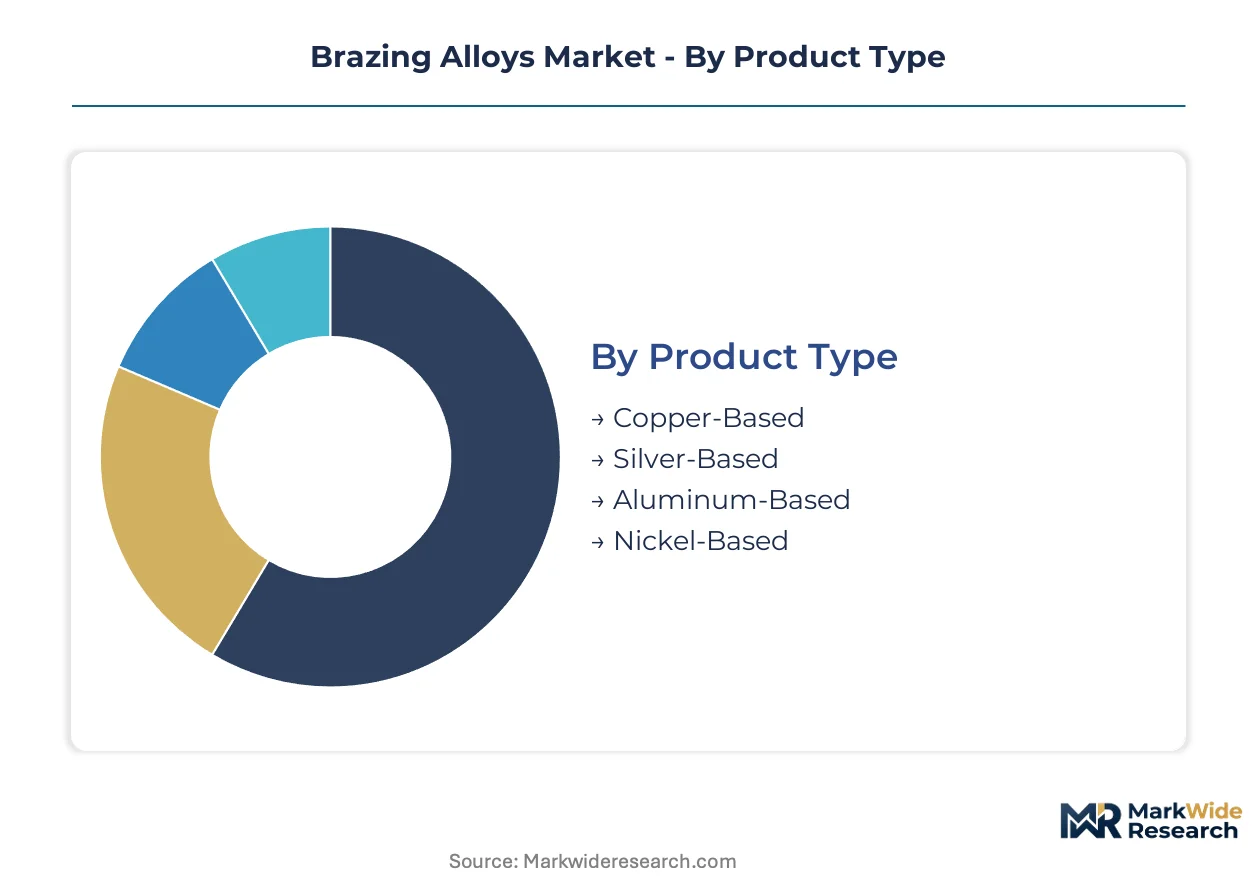
Segmentation in brazing alloys reflects divergent metallurgical requirements across temperature regimes, regulatory jurisdictions, and joint-performance specifications. Each category isolates distinct value pools where formulation expertise, certification assets, or channel control determines competitive position.
Product Type:
Regulatory differentiation in cadmium content thresholds and nickel disclosure requirements under REACH SVHC protocols and EPA Toxic Substances Control Act enforcement reshape competitive positioning across alloy families.
- Silver-Based:These copper-silver-zinc-cadmium or cadmium-free formulations dominate aerospace electronics and precision instrumentation where thermal conductivity exceeds 300 W/m·K and joint ductility is mandatory. ECHA cadmium restrictions are accelerating supplier migration toward compliant compositions, with pre-certified portfolios capturing switching demand from reformulation-lagged competitors in European electronics and North American plumbing applications.
- Nickel-Based:Nickel-chromium-boron-silicon systems withstand service temperatures exceeding 800°C in turbine engine hot sections and chemical process equipment. Demand concentrates in United States and German aerospace manufacturing corridors where OEMs specify these alloys for blade-to-disk joints and heat exchanger headers in power-generation systems.
- Copper-Based:Phosphorus-copper and copper-zinc formulations serve HVAC and plumbing applications where cost sensitivity dominates specification decisions.
- Aluminum-Based:Aluminum-silicon systems displace mechanical fastening in automotive climate-control modules as Stuttgart and Detroit OEMs pursue lightweighting targets.
Silver-based alloys handle the majority of premium-margin throughput; nickel-based alloys are expanding most quickly on share as aerospace temperature requirements escalate.
Application:
Application segmentation tracks customer specification authority migration from procurement departments toward OEM engineering teams deploying pre-validated supplier lists.
- Aerospace:Turbine engine manufacturers in the United States and Germany specify nickel-based fillers for hot-section assemblies and silver-based alloys for electronic packaging. FAA and EASA certification requirements for engine components mandate traceable metallurgical documentation from smelter through final form.
- Automotive:HVAC system architects in Stuttgart and Detroit increasingly mandate approved-supplier-list filler grades, bypassing traditional distributor consultation. KBA type-approval documentation requirements accelerate this centralization of material specification authority.
- Electronics:Semiconductor packaging and power-module substrates drive active brazing compound adoption with titanium or zirconium additions for ceramic-to-metal joints.
- HVAC:Brazed heat exchanger production in China's eastern manufacturing corridor scales for Middle East and Southeast Asian export markets.
Aerospace commands the steepest margin structure; automotive HVAC is climbing the fastest on volume as electric vehicle thermal management complexity increases.
End User:
End-user segmentation distinguishes between specification-controlled OEM procurement and price-sensitive maintenance channel demand.
- Manufacturing:Original equipment producers in aerospace, automotive, and electronics sectors dominate volume procurement with long-term supplier agreements and pre-validated filler specifications. These customers require ASME, PED, and GB standard compliance documentation extending product qualification cycles.
- Maintenance:Field service operations across United States industrial corridors depend on distributor technical consultation for joint-design matching, though digital specification platforms are eroding this channel influence.
- Construction:Commercial building HVAC installation specifies brazed copper piping systems where local plumbing codes determine allowable alloy compositions.
- Repair:Aftermarket turbine engine and heat exchanger refurbishment demands flexible procurement quantities with rapid metallurgical certification turnaround.
Manufacturing channels handle the majority of contract value; maintenance segments are gaining specification influence fastest through digital joint-simulation platform deployment.
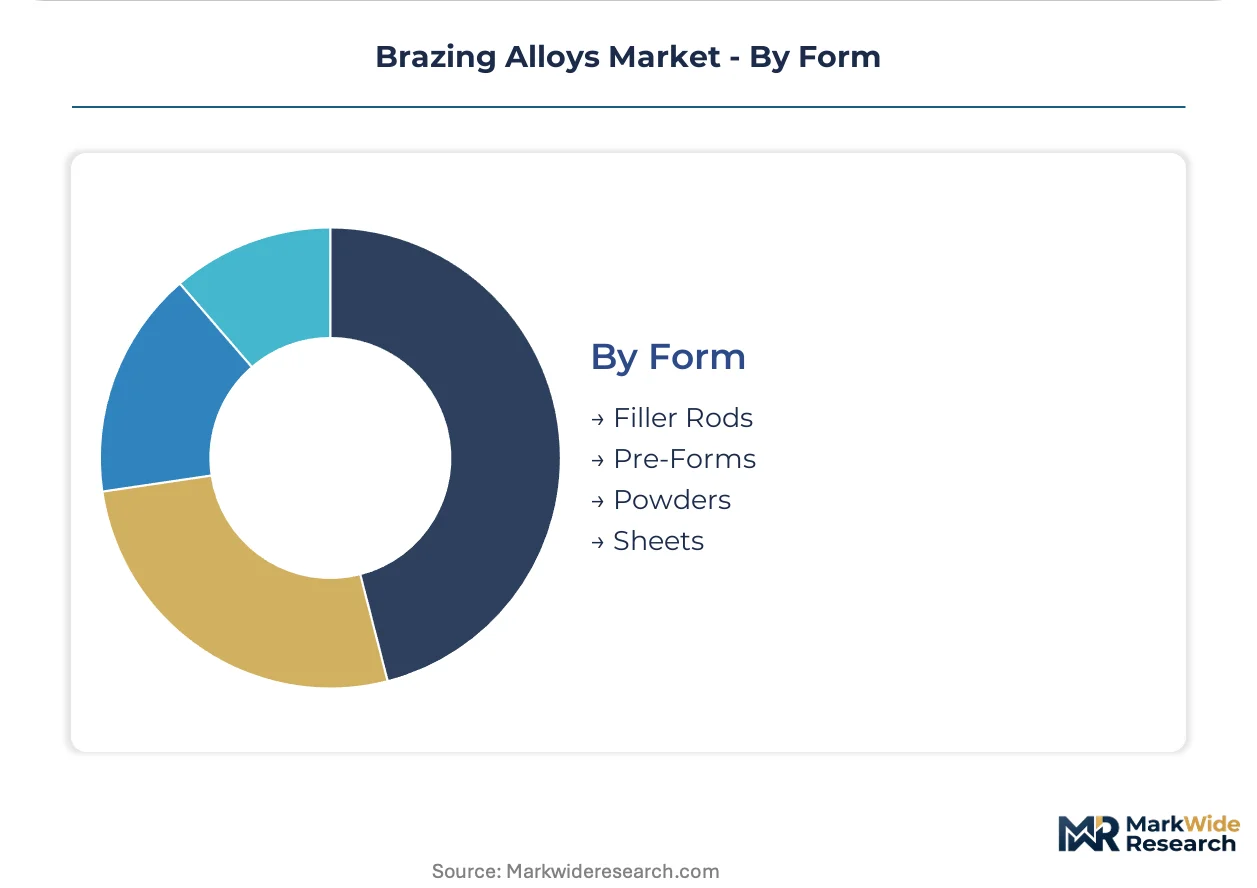
Form:
Form factor selection determines supply chain configuration from integrated smelter through precision fabrication or powder atomization.
- Filler Rods:Drawn wire products in standard and precision diameters serve manual and automated brazing operations across HVAC and automotive production lines. Lucas-Milhaupt's captive wire-drawing and annealing capabilities anchor North American automotive supply.
- Pre-Forms:Engineered rings, washers, and shapes eliminate manual filler placement in high-volume aerospace and electronics assembly. These forms command premium positioning through dimensional precision and metallurgical consistency.
- Powders:Gas-atomized and water-atomized particulate enables paste formulation and additive manufacturing feedstock for complex joint geometries.
- Sheets:Rolled foil and shim stock facilitate heat exchanger fin-to-tube joints and large-area ceramic substrate metallization.
Filler rods handle the majority of unit volume; pre-forms are expanding fastest on value as aerospace automation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in brazing alloys trace divergent metallurgical specialization across manufacturing corridors. Germany and the United States concentrate high-temperature nickel formulation output, while China's eastern provinces scale aluminum-silicon production for climate-control equipment destined for Middle Eastern and Southeast Asian markets.
United States
Aerospace turbine manufacturers in Connecticut and Ohio drive nickel-based filler metal procurement for jet engine hot-section assemblies. EPA cadmium enforcement under the Toxic Substances Control Act compels silver-alloy suppliers to reformulate legacy compositions for plumbing and consumer applications. Detroit automotive HVAC architects specify pre-validated filler grades from approved supplier lists, bypassing traditional distributor channels.
Germany
Stuttgart-based automotive OEMs mandate brazed aluminum joints in electric vehicle thermal management modules to achieve lightweighting targets. KBA type-approval documentation requirements for vehicle climate systems accelerate centralization of material specification authority. Bavarian and North Rhine-Westphalian integrated smelters concentrate high-purity nickel-chromium master alloy production for European aerospace fabricators.
China
Eastern manufacturing corridor producers in Jiangsu and Zhejiang provinces scale brazed heat exchanger output for export to Middle East and Southeast Asian climate-control markets. SAMR GB standards enforce compositional tolerances for imported filler metals used in pressure equipment, creating market-access friction for non-certified suppliers. Shanghai and Ningbo port infrastructure supports raw silver and copper feedstock import for domestic alloy formulation.
Japan
Osaka and Nagoya ceramic substrate manufacturers adopt active brazing compounds with titanium additions for semiconductor packaging applications. METI energy-efficiency directives for HVAC equipment specify minimum heat-exchanger performance thresholds that favor brazed designs over mechanical alternatives. Kyushu-based power-module producers drive single-step ceramic-to-metal joint process adoption.
India
Maharashtra and Gujarat industrial corridors generate demand for nickel-based fillers in power-generation and chemical-processing equipment buildouts. BIS certification pathways for imported filler metals remain underpenetrated relative to projected infrastructure demand through 2030. Tamil Nadu automotive component clusters increasingly specify aluminum-silicon alloys for climate-control module fabrication.
Brazing Alloys Market Competitive Environment
Concentration sits with integrated metallurgical houses possessing captive smelting and precision forming capabilities. The vendor base stratifies across three tiers: global diversified materials conglomerates with multi-metal portfolios, specialized brazing alloy formulators with regional certification depth, and technical distributors controlling maintenance channel access. Dominant competitive moves include backward integration into master alloy production and geographic expansion through ASME, PED, and GB standard pre-certification.
Among North American fabricators, Lucas-Milhaupt Inc. and Harris Products Group exemplify divergent strategic positioning—one representing integrated wire-drawing and precision annealing capabilities, the other anchoring distributor network control for field service procurement. Umicore occupies a position within the European low-cadmium formulation specialist tier, reflecting Brussels and Toronto laboratory investment in compliant silver alloy development.
| Leading Market Players |
|---|
| Lucas-Milhaupt Inc. |
| Umicore |
| Harris Products Group |
| Prince & Izant Company |
| Johnson Matthey |
| Morgan Advanced Materials |
| Voestalpine Böhler Welding |
| Aimtek Inc. |
| Wall Colmonoy Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH cadmium restrictions and EPA Toxic Substances Control Act enforcement simultaneously gate supplier qualification and stratify price tiers across silver-based alloy portfolios. Manufacturers holding pre-certified low-cadmium formulations extract premium positioning over reformulation-lagged competitors while standard-grade copper-phosphorus products compete on commodity metal pass-through economics.
Pricing Analysis
Configured-to-order pricing for aerospace-grade nickel-chromium pre-forms commands substantial premiums over standard filler rod catalog pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale effects. Cost compression in HVAC-grade copper-zinc segments is intensifying because Chinese eastern corridor producers are scaling export-oriented heat exchanger output. Maintenance channel buyers exhibit highest price sensitivity, while aerospace OEM procurement teams prioritize metallurgical traceability over unit cost.
Supply Chain Analysis
German and Austrian integrated smelter concentration for high-purity nickel-chromium master alloys creates geographic supply vulnerability for Asia-Pacific fabricators. Raw material sourcing draws from COMEX-traded silver, LME copper, and Russian-origin nickel feedstock subject to trade restriction uncertainty. Single-source vulnerability concentrates in gas-atomized powder production for active brazing compounds. Distribution runs through technical distributors controlling maintenance channel access alongside direct OEM supply agreements for volume automotive and aerospace procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical fastening substitution in automotive lightweighting programs and self-piercing rivet adoption in cost-sensitive vehicle classes threaten brazed joint volume. Incumbents must navigate this substitution pressure while defending metallurgical specification authority against digital platform intermediation.
For Market Incumbents: Consolidate backward integration into nickel-chromium master alloy production to secure supply continuity against German-Austrian smelter concentration risk. Deepen ASME, PED, and GB standard pre-certification investments to extend qualification moats against emerging Asian formulators. Defend against mechanical fastening substitution by embedding brazed joint simulation tools within OEM engineering workflows.
For New Entrants and Emerging Players: Lead with BIS certification pathway navigation for India's underpenetrated power-generation and chemical-processing equipment demand. Target hydrogen economy heat exchanger specifications where corrosion-resistant nickel-brazed joints face limited incumbent competition. Establish technical credibility through metallurgical documentation partnerships with electrolyzer stack manufacturers seeking high-purity hydrogen handling solutions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active brazing compound manufacturing due to titanium hydride handling requirements and powder atomization infrastructure. Long-term viability favors integrated houses possessing captive smelting, precision wire drawing, and R&D laboratory assets. Acquisition targets should demonstrate GB standard pre-certification for China pressure-equipment access alongside low-cadmium silver patent portfolios. The signal to watch is cadmium-free formulation patent grant velocity relative to REACH compliance deadline proximity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Master Alloy Production | Captive nickel-chromium supply secures margin control against German-Austrian smelter concentration. |
| Multi-Jurisdictional Certification Pre-Investment | Parallel ASME, PED, and GB compliance compresses product launch cycles for global OEM accounts. |
| Active Brazing Compound R&D Expansion | Titanium hydride formulation patents capture ceramic-to-metal joint demand from Japanese semiconductor packaging. |
| Digital Joint-Simulation Platform Deployment | AI-assisted specification tools migrate procurement influence from distributors to integrated suppliers. |
| Hydrogen Economy Heat Exchanger Qualification | Corrosion-resistant nickel-brazed certification opens electrolyzer and fuel-cell stack supply chains. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aerospace procurement directors, automotive HVAC system architects, technical distributor field engineers, and nickel alloy smelter operations managers. Secondary validation drew from EPA Toxic Substances Control Act enforcement records, ECHA SVHC disclosure databases, SAMR GB standard certification registries, and SEC filings from diversified materials conglomerates. Bottom-up volume estimates from end-use application sizing were triangulated against top-down alloy consumption figures from customs trade data.
Across the analysis window, projections integrate product type, application, end user, and form factor segmentation with regional regulatory cluster differentiation. CAGRs were derived from elasticity-adjusted demand modeling incorporating aerospace turbine temperature requirement escalation, REACH cadmium substitution timelines, and China HVAC export scaling trajectories. Forecast inputs include silver COMEX futures volatility bands, nickel alloy capacity utilization at German integrated smelters, and BIS certification penetration rates in Indian industrial corridors.
The analysis sits within stated boundaries; outcomes outside sustained aerospace production rates, REACH enforcement stringency levels, or China export financing conditions would require recalibration. Forecasts reflect documented assumptions regarding metallurgical talent availability and multi-jurisdictional certification timeline stability. Revision becomes warranted when silver price volatility crosses hedging program absorption thresholds or when mechanical fastening substitution rates in automotive lightweighting exceed baseline scenario parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
US Green Steel Market
Advanced Alloys
Forgings Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Global Ferroalloys Market