
 Ph Controlling Agents Market | 2026-2036
Ph Controlling Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Ph Controlling Agents Market Analytics
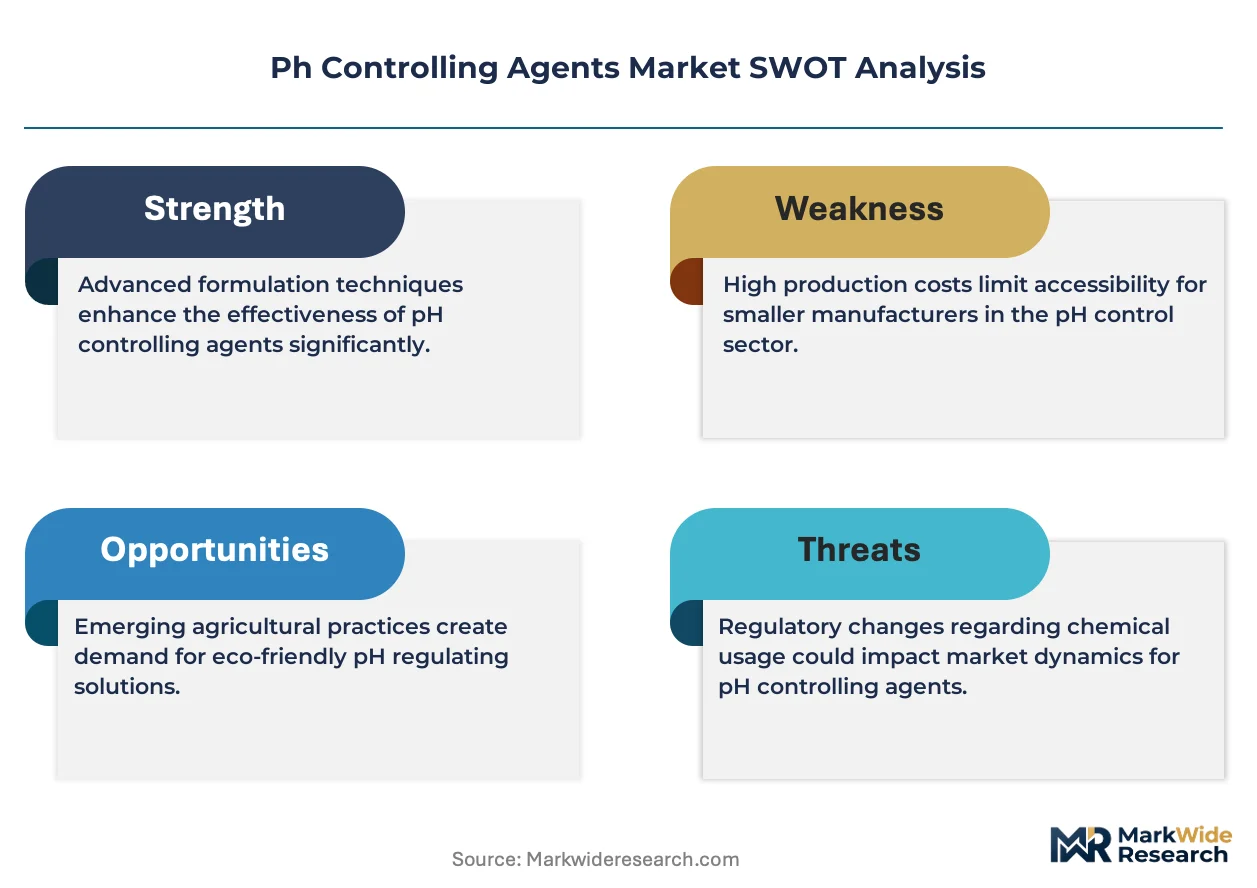
A widening capital-intensity gap between integrated chemical conglomerates and specialty ingredient suppliers is reorganizing competitive tiers in pH controlling agents. BASF SE leverages its backward integration into petrochemical feedstocks to dominate bulk acid production in Europe. Jungbunzlauer Suisse AG anchors its position through fermentation-derived organic acid specialization, competing on biosourced credentials rather than scale.
pH controlling agents comprise acids, bases, salts, and buffers formulated to adjust hydrogen ion concentration in aqueous systems, typically measured against standard buffer solutions traceable to NIST reference materials for accuracy within 0.01 pH units. These compounds serve critical functions in water treatment, pharmaceutical manufacturing, and food processing where precise acidity control determines product safety, reaction yield, or regulatory compliance. The product type dimension shows salts commanding the largest volume share due to their dual buffering capacity and lower corrosivity, while bases are gaining fastest in water treatment applications as utilities shift from chlorine gas to safer alkaline alternatives. Application segmentation reveals food processing as the most margin-rich vertical, with pharmaceutical-grade buffers extracting premium pricing through USP and EP certification requirements that generic industrial grades cannot satisfy.
The EPA enforces effluent pH limits under the Clean Water Act, compelling U.S. water utilities to maintain continuous alkalinity adjustment systems that consume lime and caustic soda at municipal scale. ECHA's REACH registration framework in Europe imposes full toxicological dossiers on acid and base importers, raising compliance costs that favor established registrants over new market entrants. Stakeholders must monitor evolving PFAS restrictions, as fluorinated buffer chemistries face prospective phase-outs that could displace incumbent formulations across pharmaceutical and semiconductor cleaning applications.
Market Dynamics
Water utilities across Germany, Japan, and Brazil are scaling acid and base procurement for municipal pH correction, tightening purity specifications under EPA and EU REACH enforcement while China's SAMR mandates stricter effluent neutrality standards in industrial corridors.
Growth Catalysts
- Clean Water Act enforcement:EPA effluent pH limits compel U.S. water utilities to maintain continuous alkalinity adjustment systems consuming lime and caustic soda at municipal scale.
- REACH registration requirements:ECHA's full toxicological dossier mandates on acid and base importers raise compliance costs that favor established registrants over new market entrants in Europe.
- Dual buffering capacity of salts:Salts command the largest volume share due to lower corrosivity and pH stabilization properties in food processing and pharmaceutical manufacturing applications.
Market Restraints
- Petrochemical feedstock volatility:Bulk acid production depends on naphtha and natural gas derivatives whose price swings compress margin predictability for European producers.
- Fluorinated buffer phase-out risk:Prospective PFAS restrictions threaten to displace incumbent buffer chemistries across pharmaceutical and semiconductor cleaning applications.
- Fermentation capacity constraints:Organic acid biosourcing requires dedicated bioreactor infrastructure that limits rapid scale-up for Jungbunzlauer-type specialists.
Strategic Opportunities
- USP and EP certification premiums:Pharmaceutical-grade buffers extract pricing multiples that generic industrial grades cannot satisfy through quality differentiation.
- Alkaline alternative adoption:Water treatment utilities shifting from chlorine gas to safer base chemistries create demand expansion for caustic soda and lime formulations.
- Semiconductor cleaning chemistry:Ultra-high purity acid and base requirements in wafer fabrication open specialty formulation markets with stringent particulate specifications.
Industry Challenges
- Analytical calibration expertise:NIST-traceable buffer solution preparation requires skilled technicians capable of maintaining 0.01 pH unit accuracy in quality control laboratories.
- Multi-jurisdiction dossier management:REACH, EPA TSCA, and SAMR registration timelines create parallel compliance burdens that strain regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ph Controlling Agents Market |
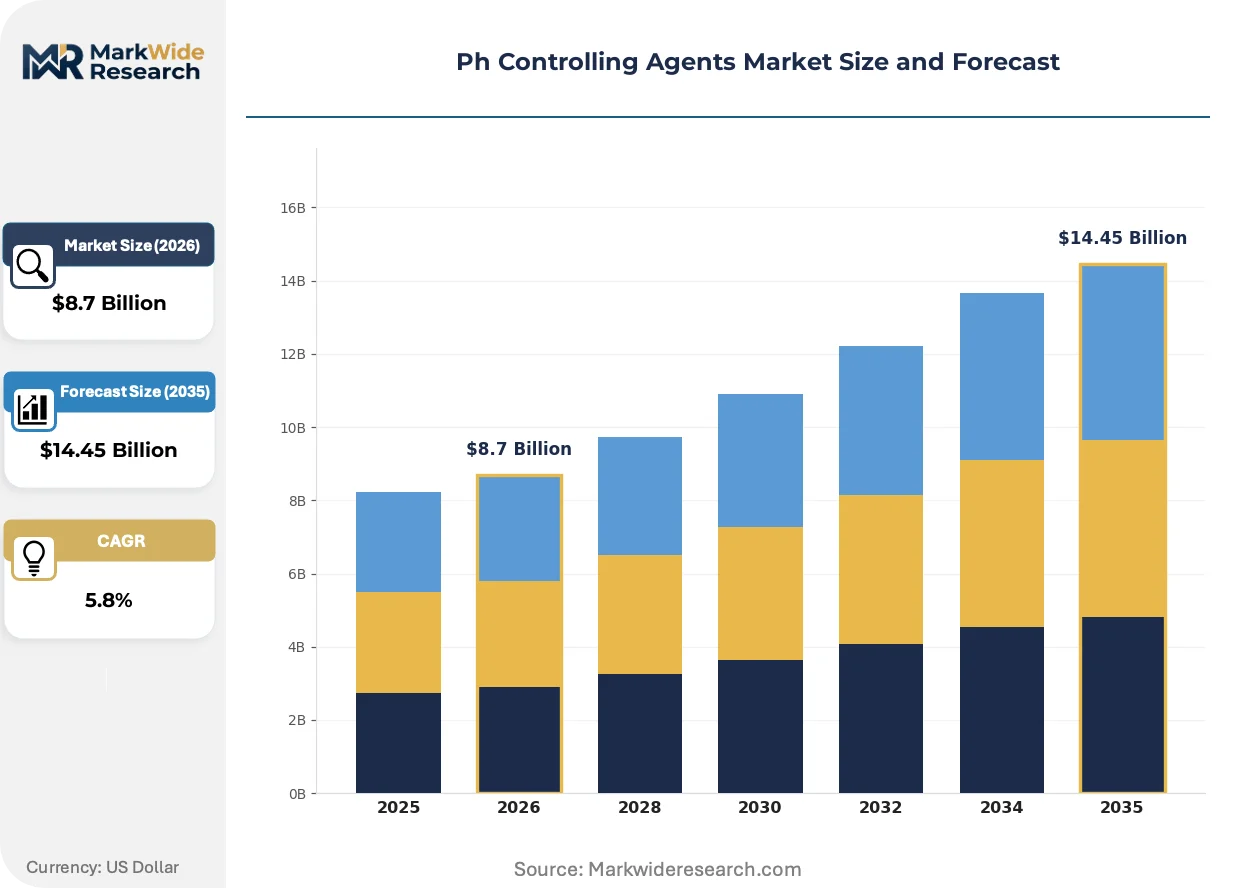
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Bases, Salts, Buffers Application: Agriculture, Water Treatment, Pharmaceuticals, Food Processing End User: Chemical Manufacturers, Water Utilities, Research Labs, Food Industry Delivery Mode: Liquid, Powder, Granular, Tablet |
| Companies Covered | Cargill, Archer Daniels Midland, Corbion, Jungbunzlauer Suisse AG, BASF SE, Dow Chemical Company, Tate & Lyle, Kerry Group, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ph Controlling Agents Market Evolving Landscape
Precision measurement technology and biosourced chemistry are compressing traditional mineral acid dominance while regulatory fragmentation forces formulation adaptation across pharmaceutical, food, and electronics verticals.
Electrochemical pH control systems are decomposing conventional batch dosing methods in municipal water treatment. German utilities deploy continuous alkalinity adjustment with real-time sensor feedback. This technology is decomposing lime and caustic soda consumption patterns toward demand-responsive chemical delivery.
REACH Annex XVII restrictions on hazardous substances are tightening purity thresholds for acid and salt formulations entering European manufacturing. ECHA's substance evaluation program extends compliance timelines for new market entrants. Pharmaceutical buffer suppliers with grandfathered registrations defend position through established toxicological dossiers.
Specification-driven sourcing now dominates pharmaceutical and food processing procurement. Buyers unbundle commodity chemical supply from technical service relationships, compressing distributor margins. This pattern concentrates most visibly in U.S. generic drug manufacturing clusters where USP-grade certification determines supplier qualification.
Ph Controlling Agents Market Segmentation
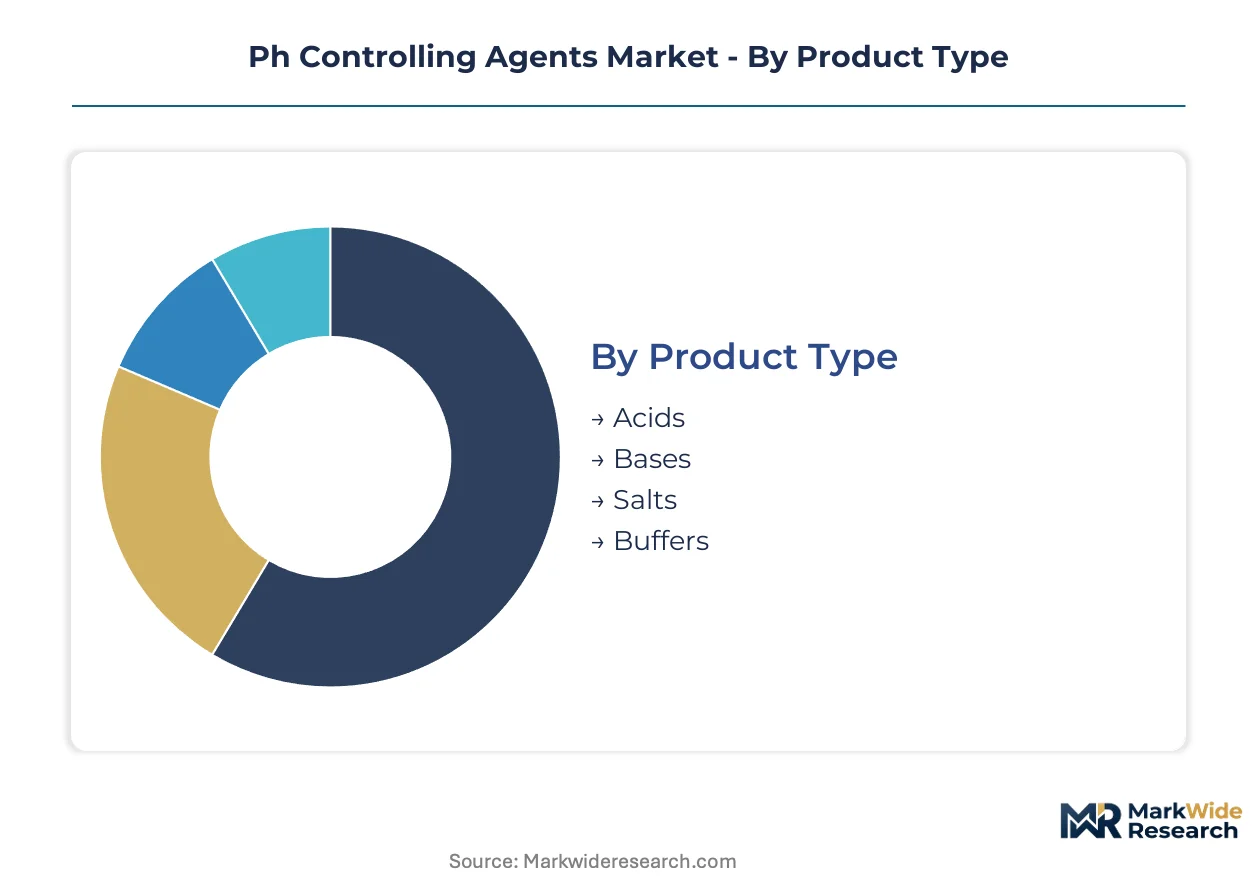
pH controlling agents serve heterogeneous technical requirements across water treatment, pharmaceutical manufacturing, and food processing verticals. Regulatory frameworks governing each application impose distinct purity thresholds and documentation burdens that fragment procurement specifications. Segmentation reveals how certification requirements reshape competitive positioning across product categories and delivery formats.
Product Type:
REACH registration tiers and USP certification pathways create divergent compliance economics across acid, base, salt, and buffer chemistries. ECHA's toxicological dossier requirements favor established registrants with grandfathered approvals, while pharmaceutical-grade buffers command premium positioning through validated manufacturing protocols.
- Acids:Mineral acids including sulfuric, hydrochloric, and nitric formulations dominate industrial wastewater neutralization. German chemical manufacturers consume bulk sulfuric acid for effluent pH correction under tightened MEE-equivalent discharge standards. Petrochemical feedstock volatility compresses margin predictability for European producers dependent on naphtha derivatives.
- Bases:Caustic soda and lime formulations serve municipal alkalinity adjustment systems. U.S. water utilities deploy continuous dosing infrastructure to maintain EPA-mandated effluent neutrality, with procurement scaling across Texas, California, and Great Lakes corridor treatment facilities. This segment is gaining share fastest as chlorine gas alternatives expand.
- Salts:Sodium carbonate and bicarbonate compounds provide dual buffering capacity with lower corrosivity profiles. Food processing applications in Japan and Brazil favor salt-based pH stabilization for ingredient safety compliance.
- Buffers:NIST-traceable formulations maintain 0.01 pH unit accuracy for analytical calibration. Pharmaceutical manufacturing in Switzerland and Massachusetts requires USP and EP certified grades with validated stability data.
Established volume favors salts; emerging adoption favors bases.
Application:
End-use specifications fragment procurement patterns across agriculture, water treatment, pharmaceuticals, and food processing verticals. Margin concentration tracks regulatory stringency, with pharmaceutical and food applications extracting premium pricing through certification requirements that commodity industrial grades cannot satisfy.
- Agriculture:Soil amendment and irrigation water pH correction consume bulk sulfuric and phosphoric acid formulations. Brazilian soybean corridor operations scale acid procurement for nutrient availability optimization in Cerrado cultivation zones.
- Water Treatment:Municipal and industrial effluent neutralization commands the largest absolute volume. Japanese utilities deploy electrochemical pH control with real-time sensor feedback, decomposing traditional batch dosing patterns toward demand-responsive chemical delivery.
- Pharmaceuticals:USP and EP certified buffers determine supplier qualification in U.S. generic drug manufacturing clusters. CDSCO-equivalent requirements in India impose parallel documentation burdens on active pharmaceutical ingredient producers.
- Food Processing:FSSAI, FDA, and EFSA compliance frameworks govern acidulant and buffer selection. Organic acid biosourcing from fermentation processes competes on clean-label credentials rather than cost position.
Volume concentrates in water treatment; margin extraction concentrates in pharmaceuticals.
End User:
Customer scale and technical capability determine whether procurement favors commodity supply relationships or integrated technical service partnerships. Specification-driven sourcing now dominates pharmaceutical and food verticals, compressing distributor margins while rewarding manufacturers with analytical calibration expertise.
- Chemical Manufacturers:Bulk acid and base consumption for derivative production and toll processing. Integrated conglomerates with backward integration into petrochemical feedstocks dominate European supply.
- Water Utilities:Municipal scale procurement of lime and caustic soda for continuous alkalinity adjustment. German and Japanese utilities lead electrochemical pH control adoption.
- Research Labs:NIST-traceable buffer solutions for analytical instrument calibration. Quality control laboratories require skilled technicians capable of maintaining reference standard integrity.
- Food Industry:Acidulant and buffer procurement for pH stabilization in processed foods. Clean-label trends favor fermentation-derived organic acids from specialized biosourcing operations.
Procurement scale favors water utilities; technical service intensity favors research labs.
Delivery Mode:
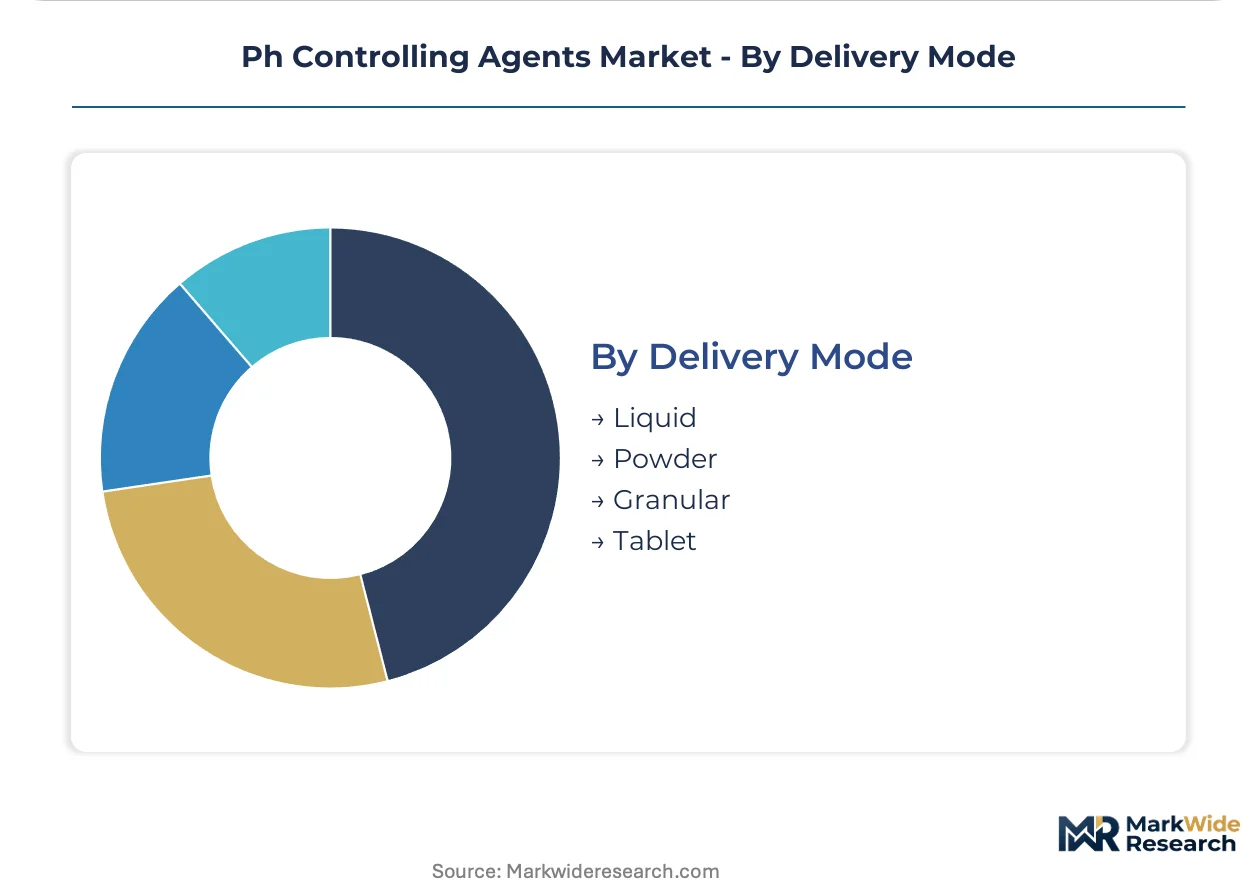
Physical form factors align with dosing infrastructure, storage constraints, and safety protocols across end-use environments. Liquid formats dominate high-volume continuous treatment systems, while solid forms reduce handling hazards in smaller-scale or remote applications.
- Liquid:Bulk tanker delivery for municipal water treatment and large-scale chemical manufacturing. Texas and California utilities specify liquid caustic soda for automated dosing compatibility.
- Powder:Dry acid and base formulations for agricultural soil amendment and food processing. Brazilian agricultural distributors favor powder sulfuric acid derivatives for storage stability.
- Granular:Controlled dissolution rates for pharmaceutical buffer preparation and laboratory use. Swiss and German manufacturers specify granular grades for precise weighing protocols.
- Tablet:Pre-measured units for field testing kits and small-scale water treatment. Portable alkalinity adjustment in remote Japanese facilities favors tablet convenience.
Continuous treatment infrastructure favors liquid; portability and precision favor tablet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes pH controlling agents primarily for industrial wastewater neutralization, whereas the United States deploys them at municipal scale under federal effluent mandates. China anchors volume expansion through SAMR-driven industrial corridor upgrades.
United States
Texas and California water utilities deploy continuous caustic soda dosing systems for EPA-mandated alkalinity adjustment. The Clean Water Act enforcement compels municipal procurement at scale across the Great Lakes corridor. Chicago and Milwaukee treatment facilities represent the densest concentration of lime consumption for pH correction infrastructure.
Germany
Ruhr Valley chemical manufacturers consume bulk sulfuric acid for effluent neutralization under tightened discharge standards. ECHA's REACH registration framework imposes full toxicological dossiers on acid importers, raising compliance costs. BASF SE's Ludwigshafen complex anchors European bulk acid production through captive petrochemical feedstock integration.
China
Yangtze River Delta industrial wastewater treatment corridors scale acid and base procurement under SAMR's stricter effluent neutrality mandates. The Ministry of Ecology and Environment enforces pH limits on manufacturing discharge. Shanghai and Suzhou chemical parks concentrate demand for high-purity neutralization agents.
Japan
Kanto region utilities pioneer electrochemical pH control with real-time sensor feedback, decomposing traditional batch dosing patterns. METI promotes demand-responsive chemical delivery systems for municipal water treatment. Tokyo and Yokohama treatment facilities lead adoption of automated alkalinity adjustment infrastructure.
Brazil
Cerrado soybean corridor operations scale sulfuric acid procurement for soil amendment and irrigation water pH correction. ANVISA governs agricultural chemical purity specifications for nutrient availability optimization. São Paulo state distributors favor powder acid derivatives for storage stability in remote cultivation zones.
Ph Controlling Agents Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pH controlling agents. Bulk mineral acid production concentrates among petrochemical conglomerates with backward integration into naphtha derivatives. Fermentation-derived organic acid specialists occupy a distinct credential-driven niche. Capacity expansion and biosourced certification represent the dominant competitive moves reshaping positioning.
Within the integrated chemical tier, BASF SE anchors European supply through Ludwigshafen-based production. Jungbunzlauer Suisse AG exemplifies the fermentation-specialist archetype competing on biosourced credentials. Cargill occupies a position bridging agricultural feedstock integration with industrial chemical supply.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Corbion |
| Jungbunzlauer Suisse AG |
| BASF SE |
| Dow Chemical Company |
| Tate & Lyle |
| Kerry Group |
| Ingredion |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for USP-grade buffers concentrate pricing power with established registrants holding grandfathered REACH dossiers, while spot-market mineral acids face cost compression from petrochemical feedstock volatility. Contract structures favor long-term offtake agreements for pharmaceutical-grade formulations where certification barriers lock in supplier relationships, whereas municipal water utilities negotiate volume-driven caustic soda procurement with shorter pricing reset windows.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade buffer procurement, with USP and EP certification tiers commanding three-to-five-fold premiums over generic industrial grades. Price differentiation rests on validated manufacturing protocols and toxicological dossier completeness under ECHA registration requirements. Cost compression runs through bulk mineral acid segments as naphtha derivative volatility squeezes European producer margins. Municipal water utilities exhibit highest price sensitivity due to budget-constrained procurement processes, while semiconductor fabs show lowest sensitivity given ultra-high purity specifications.
Supply Chain Analysis
Rhine River barge transit and Antwerp-Rotterdam-Amsterdam hub congestion create chokepoints for European acid and base distribution, concentrating supply risk in northwestern logistics corridors. Production gravity centers on Germany, China, and the United States, with BASF's Ludwigshafen complex and Yangtze River Delta chemical parks anchoring regional supply. Feedstock dependence draws from naphtha derivatives, fermentation biomass, and natural gas brine. Single-source vulnerability threatens organic acid biosourcing where Jungbunzlauer-type specialists control limited fermentation capacity. Distribution runs through bulk tanker networks for municipal utilities and specialized chemical distributors for pharmaceutical and food-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, ECHA, and SAMR jurisdictions fragments procurement specifications, creating specialized niches for certification-capable suppliers and regional formulation specialists.
For Market Incumbents: Shield established positions by deepening REACH registration moats through substance evaluation program participation, and expand captive petrochemical feedstock integration at Ludwigshafen-scale complexes to neutralize naphtha volatility. PFAS restriction timelines threaten fluorinated buffer incumbents; accelerate phosphate and organic acid alternative R&D.
For New Entrants and Emerging Players: Anchor in Brazilian Cerrado agricultural acid distribution where ANVISA compliance requirements remain less stringent than pharmaceutical-grade barriers, and Japanese electrochemical pH control system integration where METI automation incentives create technical service partnerships. Target fermentation-derived organic acid biosourcing for clean-label food processing procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH grandfathered registrations appreciate as compliance timelines extend for new entrants, and certification-intensive segments extract durable pricing premiums. Target acquisition archetype: mid-cap fermentation specialists with validated USP-grade buffer protocols. Watch ECHA substance evaluation program acceleration as inflection signal for registration scarcity value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | BASF's Ludwigshafen complex demonstrates margin protection against naphtha volatility through captive supply. |
| Fermentation Capacity Expansion | Jungbunzlauer-type biosourcing operations capture clean-label food processing demand with organic acid specialization. |
| USP and EP Certification Investment | Pharmaceutical-grade buffer suppliers extract pricing multiples unavailable to generic industrial grade competitors. |
| Electrochemical pH Control System Partnerships | German and Japanese utilities deploy real-time sensor feedback, creating technical service relationships beyond commodity supply. |
| Long-term Municipal Supply Agreements | Texas and California water utilities lock in caustic soda procurement through multi-year continuous dosing infrastructure contracts. |
Research Methodology
A standing panel of water utility procurement officers, pharmaceutical manufacturing quality directors, chemical plant managers, and food industry regulatory affairs leads provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with downstream formulation specialists and upstream feedstock procurement teams. Secondary validation drew from EPA enforcement databases, ECHA registration dossiers, SAMR effluent discharge records, and SEC chemical company filings. Bottom-up volume estimates triangulated against top-down industry association data from ACC and Cefic.
Consistency checks validated segment-level outputs against customs trade flows and regional production capacity disclosures. The analytical framework modeled product type, application vertical, certification grade, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from fitted growth curves anchored to disclosed capacity expansion timelines and regulatory implementation schedules. Forecast inputs incorporated electrochemical pH control adoption rates and PFAS restriction phase-out scenarios.
Material uncertainties — feedstock price volatility, REACH dossier evaluation delays, and PFAS regulatory acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation timelines and technology substitution rates. Practitioners should keep alternative scenarios live as ECHA substance evaluation priorities and SAMR effluent standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Elemental Formula Market