
 Saudi Arabia in-Vitro Diagnostics (IVD) Market | 2026-2036
Saudi Arabia in-Vitro Diagnostics (IVD) Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia in-Vitro Diagnostics (IVD) Market Intelligence
Domestic reagent blending facilities in Jeddah and Riyadh are restructuring supply chains to reduce import dependency for time-sensitive consumables. Roche Diagnostics leverages its centralized distribution hub in King Abdullah Economic City to sustain next-day replenishment across government hospital networks. Abbott Laboratories anchors its position through localized technical service teams embedded within Ministry of Health reference laboratories. Siemens Healthineers competes on integrated automation contracts that bundle analyzers with multi-year reagent supply agreements.
In-vitro diagnostics encompasses analytical systems, reagent kits, and consumables designed to detect disease markers, metabolic indicators, and infectious agents outside living organisms, typically requiring specimen volumes between 10 microliters and 10 milliliters depending on assay sensitivity. These technologies enable clinical decision-making through quantitative biochemical, immunological, or nucleic acid-based measurements performed on blood, serum, urine, or tissue samples. Reagent categories command recurring revenue streams that lock in multi-year hospital contracts, while molecular testing applications expand fastest as SFDA accelerates approval pathways for PCR-based oncology panels. ELISA technology segments retain dominance in routine serology screening across blood bank networks, though flow cytometry platforms gain share in specialized immunology reference centers.
SFDA implements pre-market registration and post-market surveillance frameworks that mandate local stability testing for temperature-sensitive reagents, while the Ministry of Health's National Transformation Program directs procurement standardization toward interoperable analyzer platforms. BIS-equivalent conformity assessments for electromagnetic compatibility constrain analyzer import timelines, pushing distributors toward pre-certified European OEM partnerships. Stakeholders must monitor SFDA's evolving software-as-medical-device guidance for cloud-connected analyzers, as remote diagnostic data flows trigger additional cybersecurity compliance layers.
Market Dynamics
SFDA's tightened quality certification requirements for imported diagnostic devices are accelerating local distributor consolidation while hospital laboratories across the Kingdom expand automated testing platforms to manage rising chronic disease burdens.
Growth Catalysts
- Ministry of Health procurement standardization:The National Transformation Program directs interoperable analyzer platform adoption, locking in multi-year reagent supply contracts across government hospital networks.
- Molecular testing expansion:PCR-based oncology panels are displacing traditional histopathology workflows as SFDA accelerates approval pathways for nucleic acid-based diagnostics.
- Jeddah-Riyadh reagent blending infrastructure:Domestic consumable production facilities are restructuring supply chains to reduce import dependency for temperature-sensitive reagents.
Market Restraints
- BIS-equivalent electromagnetic conformity assessments:Analyzer import timelines face extended validation periods, constraining distributor partnerships to pre-certified European OEMs.
- Reagent cold-chain concentration risk:Temperature-sensitive consumables depend on concentrated air freight corridors through King Abdulaziz International Airport, creating single-point vulnerability.
- ELISA technology lock-in:Blood bank networks maintain entrenched serology screening infrastructure, slowing flow cytometry platform adoption despite superior immunophenotyping capabilities.
Strategic Opportunities
- Eastern Province laboratory capacity gaps:Dammam and Khobar tertiary facilities present underpenetrated demand for automated chemistry analyzers serving industrial corridor workforces.
- Cloud-connected analyzer software-as-medical-device pathways:SFDA's evolving guidance for remote diagnostic data flows creates first-mover advantage for cybersecurity-compliant platform vendors.
- Multi-year reagent bundling contracts:Integrated automation agreements that lock in consumable recurring revenue streams are displacing standalone analyzer sales in Ministry of Health procurement cycles.
Industry Challenges
- Biomedical engineering talent scarcity:Localized technical service team deployment requires specialized training pipelines that outpace Saudi Arabia's current vocational education output.
- Legacy analyzer integration complexity:Interoperability mandates force hospital laboratories to reconcile proprietary data formats from mixed-vendor installed bases.
- Post-market surveillance compliance timelines:SFDA-mandated local stability testing for reagent shelf-life validation extends product launch cycles beyond distributor working capital tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia in-Vitro Diagnostics (IVD) Market |
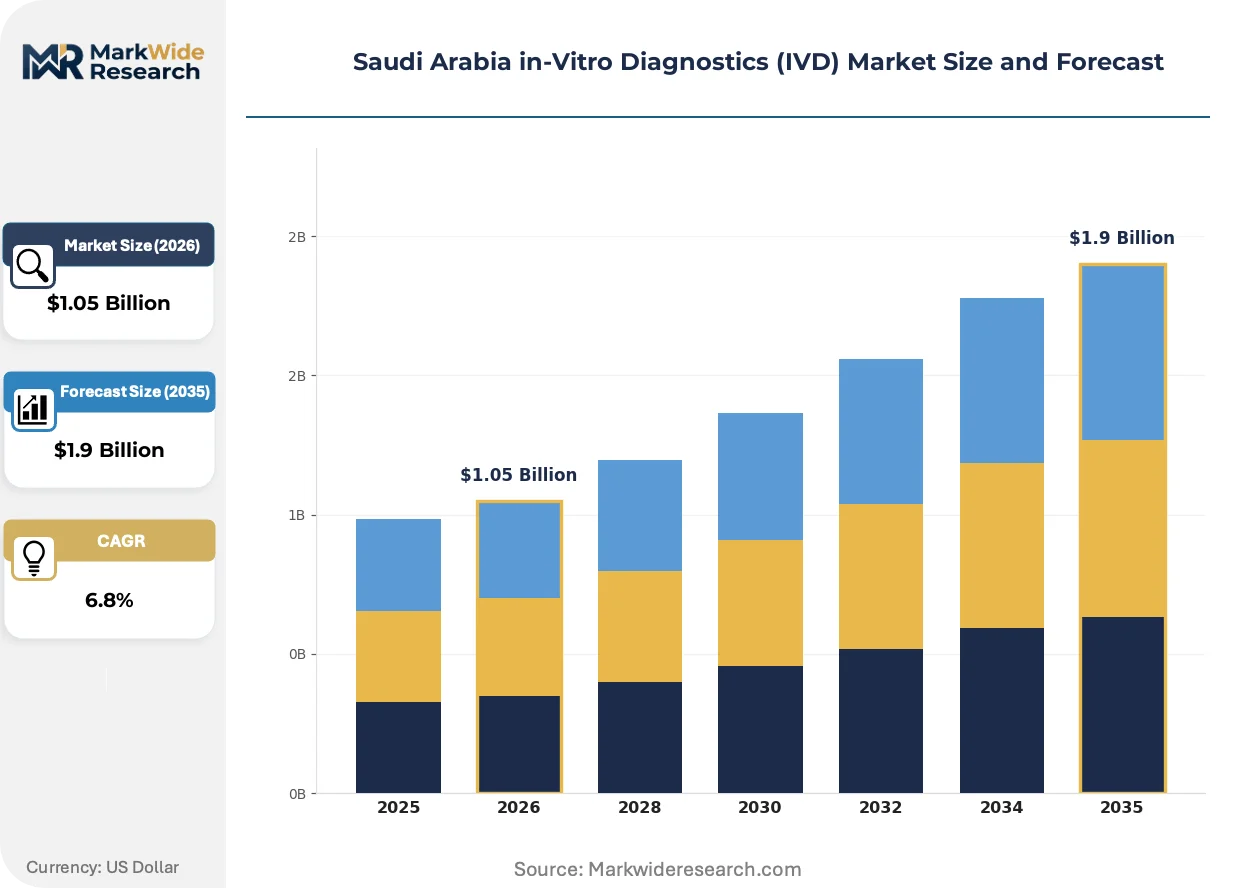
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Consumables, Systems Application: Clinical Diagnosis, Blood Testing, Pathogen Detection, Molecular Testing Technology: ELISA, PCR, Microarrays, Flow Cytometry End User: Hospitals, Laboratories, Blood Banks, Clinics |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Danaher, Bio-Rad Laboratories, Becton Dickinson, bioMérieux, Sysmex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia in-Vitro Diagnostics (IVD) Market Strategic Shifts & Innovations
Automated platform consolidation and regulatory data governance are compressing vendor margins while reshaping how hospital laboratories procure and operate diagnostic infrastructure across the Kingdom.
Integrated chemistry-immunoassay analyzers are consolidating previously discrete testing workflows into unified specimen processing pipelines. Ministry of Health flagship facilities in Riyadh are adopting these platforms at accelerated replacement cycles. This consolidation is compressing the addressable market for standalone specialty analyzers while elevating reagent contract negotiation leverage.
SFDA's software-as-medical-device guidance for cloud-connected analyzers is mandating additional cybersecurity compliance layers for remote diagnostic data transmission. Industrial consequence includes extended pre-market registration timelines and mandatory local server hosting requirements. Molecular testing segments are responding fastest, with PCR platform vendors restructuring data architecture to satisfy patient privacy mandates.
Hospital procurement committees are unbundling after-sales service contracts from analyzer purchase agreements, forcing distributors to compete on technical response time rather than capital equipment financing. Ministry of Health reference laboratories are leading this disintermediation, establishing direct service level agreements with third-party biomedical engineering firms. This pattern is most visible in Riyadh's tertiary medical cluster, where procurement autonomy concentrates at individual facility level.
Saudi Arabia in-Vitro Diagnostics (IVD) Market Segmentation
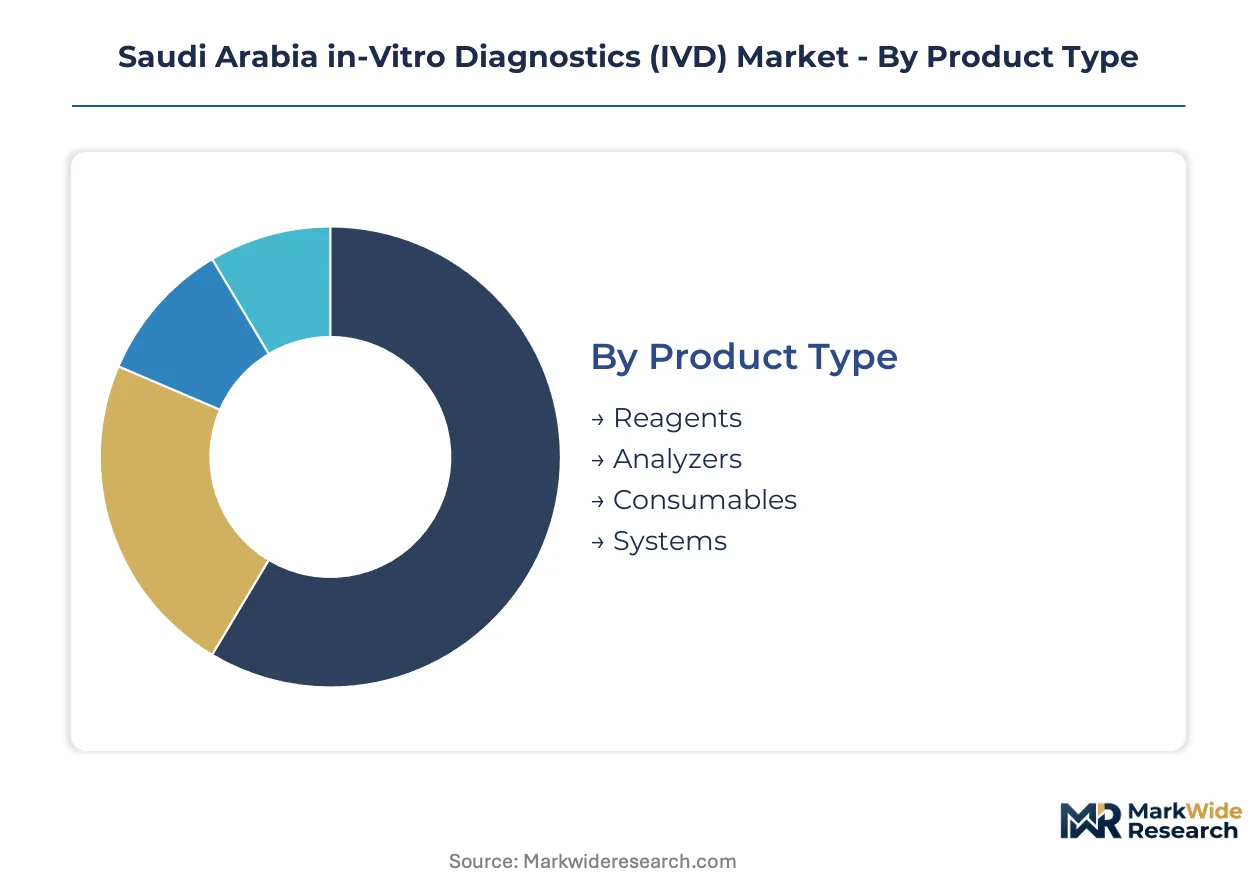
Hospital procurement committees across the Kingdom are unbundling analyzer purchases from reagent contracts, forcing vendors to compete on segment-specific upgrade cycles rather than bundled financing. Replacement timelines now diverge sharply between automated platforms and legacy manual systems.
Product Type:
Upgrade cycles for capital equipment are compressing as Ministry of Health facilities prioritize interoperability mandates over extended depreciation schedules.
- Reagents:Temperature-sensitive biochemical and immunological formulations require cold-chain integrity through King Abdulaziz International Airport corridors. Demand concentrates in Riyadh's tertiary medical cluster where multi-year supply agreements lock in recurring revenue streams for distributors meeting SFDA stability testing requirements.
- Analyzers:Automated chemistry-immunoassay platforms consolidate previously discrete testing workflows into unified specimen processing pipelines. Eastern Province hospitals in Dammam and Khobar present underpenetrated demand as industrial corridor workforces drive testing volume expansion.
- Consumables:Single-use pipette tips, cuvettes, and reaction vessels face procurement standardization under the National Transformation Program.
- Systems:Integrated automation contracts bundle hardware with multi-year service agreements across government hospital networks.
Volume placements concentrate in Reagents; the faster expansion belongs to Analyzers.
Application:
Cost tier differentiation separates high-throughput screening programs from specialized reference testing with premium reimbursement profiles.
- Clinical Diagnosis:Routine biochemistry and hematology panels dominate daily test volumes across Ministry of Health flagship facilities. Riyadh's tertiary medical cluster anchors procurement volume as chronic disease burdens drive platform utilization rates.
- Blood Testing:Serology screening for transfusion safety maintains entrenched ELISA infrastructure across Saudi blood bank networks. SFDA quality certification requirements for imported diagnostic devices are accelerating local distributor consolidation in this segment.
- Pathogen Detection:Infectious disease panels serve Hajj and Umrah health screening mandates.
- Molecular Testing:PCR-based oncology panels displace traditional histopathology workflows as nucleic acid diagnostics gain SFDA approval pathway acceleration.
Clinical Diagnosis captures the highest absolute placement volumes; Molecular Testing is climbing the fastest.
Technology:
Application maturity creates divergent margin profiles between commoditized screening methods and specialized immunophenotyping platforms.
- ELISA:Enzyme-linked immunosorbent assay technology retains dominance in routine serology screening across blood bank networks. Temperature-sensitive reagent dependency constrains supply chain flexibility despite established validation protocols.
- PCR:Polymerase chain reaction platforms expand fastest as SFDA accelerates approval pathways for nucleic acid-based oncology diagnostics. Cloud-connected data architecture restructuring addresses evolving software-as-medical-device cybersecurity mandates.
- Microarrays:High-density nucleic acid probing enables multiplexed genetic screening in specialized reference centers.
- Flow Cytometry:Fluorescence-activated cell sorting gains share in immunology reference centers despite slower blood bank adoption.
ELISA maintains the largest installed base; PCR shows the steepest expansion trajectory.
End User:
Customer type determines procurement autonomy levels and technical service response requirements across the Kingdom's healthcare hierarchy.
- Hospitals:Tertiary medical centers in Riyadh anchor analyzer procurement volume through Ministry of Health flagship facilities. Automated platform consolidation is compressing addressable market for standalone specialty equipment while elevating reagent contract negotiation leverage.
- Laboratories:Reference facilities unbundle after-sales service contracts from analyzer purchases, establishing direct service level agreements with third-party biomedical engineering firms. Procurement autonomy concentrates at individual facility level within Riyadh's medical cluster.
- Blood Banks:National transfusion services maintain standardized serology screening infrastructure with extended replacement cycles.
- Clinics:Primary care point-of-care testing adoption remains constrained by biomedical engineering talent scarcity for localized technical support.
Hospitals dominate capital placement volumes; Laboratories are gaining share fastest through procurement disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent cold-chain logistics through King Abdulaziz International Airport anchor supply-side configuration across Saudi Arabia's diagnostic market.
Riyadh
Ministry of Health flagship facilities drive automated platform procurement through the National Transformation Program. SFDA's pre-market registration requirements shape vendor qualification timelines. The Riyadh tertiary medical cluster concentrates multi-year reagent contract negotiations and anchors national testing volume.
Eastern Province
Dammam and Khobar industrial corridor workforces generate underpenetrated demand for high-throughput chemistry analyzers. The region's petrochemical workforce health screening mandates expand infectious disease panel requirements. Eastern Province laboratory capacity gaps present automated platform placement opportunities.
Western Region
Jeddah's domestic reagent blending facilities reduce import dependency for temperature-sensitive consumables. Hajj and Umrah health screening mandates sustain pathogen detection testing volumes. King Abdullah Economic City hosts centralized distribution infrastructure serving western hospital networks.
NEOM Northwest
Giga-project healthcare infrastructure plans incorporate interoperable analyzer platforms from greenfield commissioning. The zone's regulatory sandbox framework may accelerate software-as-medical-device pilot programs. NEOM's integrated health city concept targets cloud-connected diagnostic architecture deployment.
Saudi Arabia in-Vitro Diagnostics (IVD) Market Key Industry Players
Global majors compete with regional champions across analyzer platform integration and reagent supply contract structures. The market exhibits tiered concentration around multi-year Ministry of Health procurement agreements. Three strategic archetypes dominate: integrated automation bundlers, specialized molecular testing vendors, and regional service-embedded distributors. Competitive moves concentrate on reagent contract lock-in and localized technical service team deployment.
Among Swiss-headquartered diagnostics conglomerates, Roche Diagnostics occupies a position exemplifying integrated platform-reagent bundling. Abbott Laboratories represents the service-embedded archetype through localized technical team structures. Siemens Healthineers anchors the automation-focused tier with multi-year analyzer supply agreements. These three exemplify distinct competitive positioning vectors within SFDA-regulated procurement cycles.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher |
| Bio-Rad Laboratories |
| Becton Dickinson |
| bioMérieux |
| Sysmex |
| Others |
Cost & Logistics Intelligence
Horizontal integration through reagent blending facilities in Jeddah and Riyadh anchors supply positioning while compressing distributor pricing power. SFDA's local stability testing mandates force foreign OEMs to partner with domestic facilities, transferring margin capture from importers to blended-product operators.
Pricing Analysis
Warranty and technical service unbundling from analyzer purchases is reshaping contract structures across Ministry of Health procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates integrated automation bundles from standalone equipment and consumable-only supply agreements. Pricing pressure stems from procurement committees negotiating multi-year reagent contracts that lock in volume discounts. Government hospital networks exhibit highest price sensitivity due to National Transformation Program budget standardization, while private reference laboratories tolerate premium tiers for specialized molecular testing platforms.
Supply Chain Analysis
Temperature-sensitive reagent formulations rest on concentrated air freight corridors through King Abdulaziz International Airport, with European and American specialty chemical producers dominating upstream biochemical inputs. Diagnostic enzymes, monoclonal antibodies, and nucleic acid primers draw from Swiss, German, and US biotechnology manufacturing bases. Single-point vulnerability at the Jeddah logistics hub creates exposure to seasonal Hajj cargo congestion. Distribution runs through centralized hubs in King Abdullah Economic City serving western hospital networks, with direct-to-laboratory replenishment for Riyadh's tertiary cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's tightening quality certification requirements are forcing distributor consolidation, eliminating undercapitalized intermediaries unable to fund local stability testing infrastructure.
For Market Incumbents: Acquire domestic reagent blending capacity in Jeddah or Riyadh to secure SFDA compliance pathways and capture margin from temperature-sensitive consumables. Backward integration into cold-chain logistics addresses single-point vulnerability at King Abdulaziz International Airport. Lock in multi-year exclusive reagent contracts with Eastern Province hospitals before automated platform procurement accelerates in Dammam and Khobar. For New Entrants and Emerging Players: Launch via cloud-connected analyzer software-as-medical-device pathways targeting NEOM's regulatory sandbox for cybersecurity-compliant pilot programs. Eastern Province laboratory capacity gaps present the most penetrable geography, with industrial corridor workforce screening mandates driving chemistry analyzer demand. Partner with third-party biomedical engineering firms to bypass incumbent technical service team advantages in government hospital networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global diagnostics conglomerates seeking Saudi market access through SFDA-registered distribution assets. Long-term viability favors regional champions with captive reagent blending facilities and embedded Ministry of Health relationships. Watch SFDA's evolving software-as-medical-device guidance enforcement as inflection indicator for cloud-connected platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Blending Facility Acquisition | Captures SFDA compliance margin and reduces import dependency for temperature-sensitive consumables. |
| Cloud-Connected Analyzer Certification | Addresses evolving cybersecurity mandates for remote diagnostic data flows in NEOM pilot zones. |
| Eastern Province Distribution Expansion | Secures first-mover position in Dammam and Khobar automated chemistry analyzer procurement cycles. |
| Technical Service Team Localization | Meets biomedical engineering talent requirements for Ministry of Health reference laboratory contracts. |
| Multi-Year Reagent Bundling Contracts | Locks in recurring revenue streams and displaces standalone analyzer sales in government procurement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Saudi Arabia IVD market assessment. Primary interviews with hospital procurement managers, biomedical engineering directors, and SFDA regulatory affairs specialists combined with SFDA device registration databases, Ministry of Health procurement disclosures, and King Abdulaziz International Airport cargo manifests. Bottom-up analyzer placement tallies and top-down reagent consumption estimates were triangulated against distributor revenue patterns.
Segment-level modeling addressed product type, application, technology, and end user dimensions across the projection horizon. CAGRs were derived from trend extrapolation of automated platform adoption curves and molecular testing approval velocities. Reagent cold-chain logistics capacity, SFDA inspection timelines, and National Transformation Program procurement standardization schedules served as industry-specific forecast inputs.
SFDA regulatory reinterpretation, Hajj logistics disruption, and Ministry of Health budget reallocation are the dominant revision risks for this analysis. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Global Immunoassay Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
US Influenza Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market