
 Global Bioplastic Composites Market | 2026-2036
Global Bioplastic Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioplastic Composites Market Foresight
Automotive OEMs is rotating demand away from conventional petroleum-based composites toward bio-based alternatives for interior trim and structural components. Braskem leverages its Brazilian sugarcane feedstock chain to anchor global PLA supply. BASF SE competes through specialized polyamide and PBAT composite formulations for high-heat automotive applications. NatureWorks LLC dominates North American PLA resin production, sustaining capacity expansions to serve tier-one compounders.
Bioplastic composites combine bio-derived polymer matrices with natural fiber or mineral reinforcements to achieve mechanical properties comparable to glass-filled thermoplastics, typically processed through injection molding or extrusion at temperatures below 220°C to preserve fiber integrity. PLA composites and starch blends lead volume consumption in food packaging trays and disposable cutlery where biodegradability commands shelf-space premiums. PHA composites and PBAT composites represent faster-growing segments in medical devices and agricultural mulch films, where marine biodegradability and soil-composting certifications unlock differentiated pricing.
The EU Green Deal and REACH restrictions on persistent microplastics are reshaping material specifications across European packaging and automotive supply chains. FDA food-contact approvals and EPA guidelines on compostable products govern US market access, while China's GB standards and dual carbon goals are tightening domestic bioplastic content requirements. Stakeholders must monitor evolving certification gaps between industrial composting infrastructure availability and product biodegradability claims.
Market Dynamics
Automotive OEMs are consolidating bioplastic composite specifications around sugarcane-derived PLA and natural fiber reinforcements as EU Green Deal mandates harden into binding material substitution targets for interior components.
Growth Catalysts
- EU REACH microplastic restrictions:The European Chemicals Agency's classification of persistent microplastics as restricted substances is forcing compounders to reformulate glass-filled thermoplastics with biodegradable alternatives in packaging and automotive applications.
- Automotive interior mandates:BMW and Volkswagen have established minimum biobased content thresholds for dashboard panels and door trim, creating anchored demand that stabilizes compounder capacity planning across German supply chains.
- PHA marine biodegradability certification:The material's ASTM D6691 compliance for seawater degradation is unlocking medical device and agricultural film segments where disposal infrastructure remains undeveloped.
Market Restraints
- Feedstock price volatility:Brazilian sugarcane ethanol pricing swings directly transmit to PLA resin costs, compressing compounder margins when petroleum-based polypropylene remains competitively priced.
- Natural fiber supply concentration:Flax and hemp reinforcement sourcing clusters in France and Belgium, exposing processors to regional weather disruptions and limited alternative suppliers.
- Processing temperature ceilings:Natural fiber degradation above 220°C restricts high-heat automotive under-hood applications, capping addressable market share against glass-filled nylons.
Strategic Opportunities
- India packaging conversion:The FSSAI's draft guidelines on compostable food-contact materials and BIS certification pathways are opening import substitution opportunities for PLA tray and cutlery compounders.
- Construction sector penetration:Temporary formwork and scaffolding panels represent an untapped volume sink where biodegradability eliminates removal labor costs on remote infrastructure projects.
- 3D printing filament convergence:PLA composite formulations optimized for fused deposition modeling are displacing petroleum-based ABS in architectural modeling and medical prototyping workflows.
Industry Challenges
- Industrial composting infrastructure gaps:Product biodegradability certification under EN 13432 requires facilities operating at 58°C that remain scarce outside Germany, the Netherlands, and select US municipalities, creating claim-verification disputes.
- Natural fiber-matrix adhesion chemistry:Silane coupling agent selection and fiber surface treatment protocols demand polymer science expertise that compounders must build in-house or license from specialized additive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioplastic Composites Market |
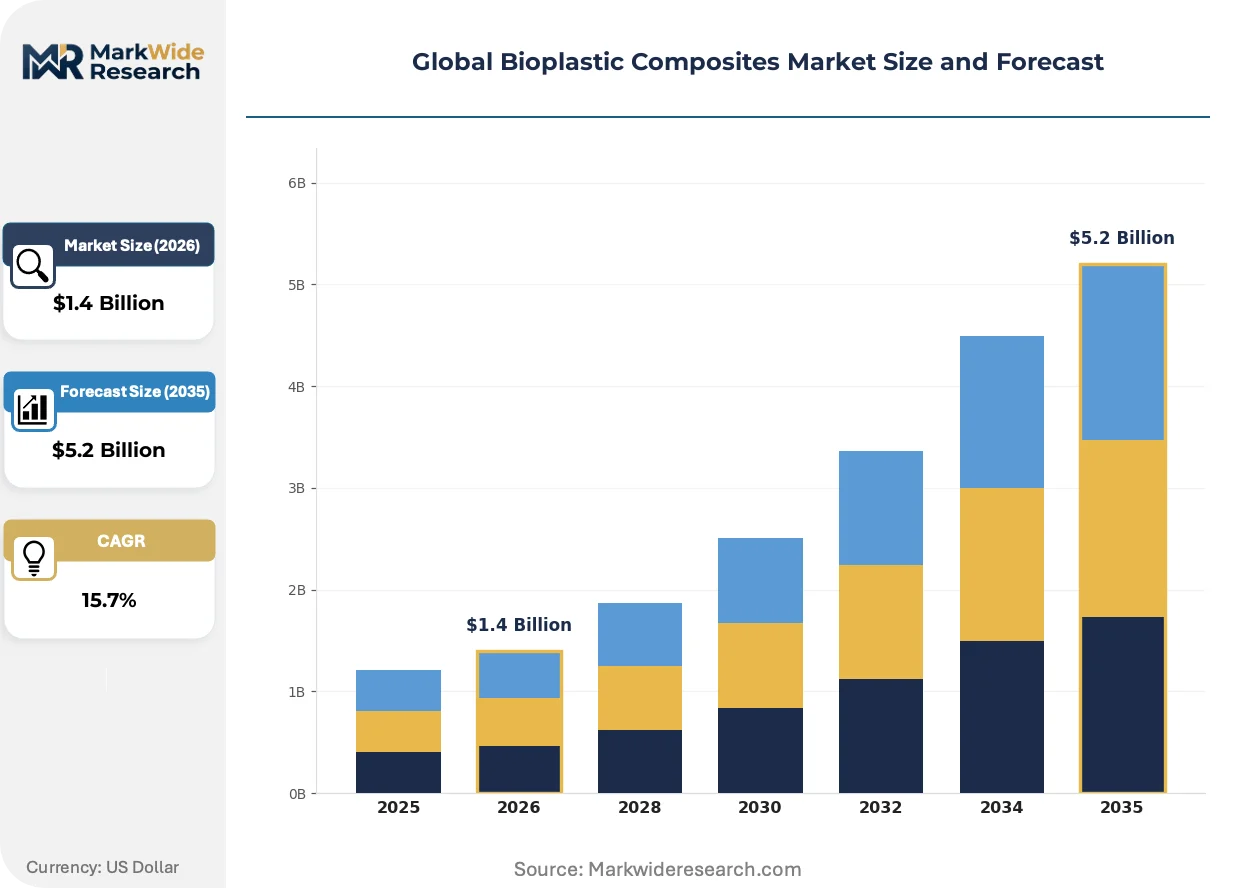
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.2 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA Composites, Starch Blends, PHA Composites, PBAT Composites End User: Packaging, Automotive, Consumer Goods, Electronics Application: Food Packaging, Automotive Interiors, Household Items, Medical Devices Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Braskem, Arkema, Mitsubishi Chemical Group Corporation, Dow Inc., BASF SE, NatureWorks LLC, Owens Corning, Toray Industries, TotalEnergies Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioplastic Composites Market Shifts & Advancements
Continuous fiber-reinforced bioplastic tapes and reactive extrusion compounding are compressing cycle times and expanding structural load-bearing applications beyond disposable packaging into semi-durable goods.
Hybrid flax-carbon fiber laminates are displacing glass-reinforced polypropylene in automotive seatback structures and interior load floors. Audi and Mercedes-Benz procurement teams have qualified these materials for 2027 model year applications where weight reduction targets intersect with sustainability scorecard requirements. The displacement is compressing traditional glass mat thermoplastic supplier relationships as tier-one molders retool compression presses for natural fiber handling.
China's GB standards for biodegradable plastics and dual carbon intensity targets are tightening domestic bioplastic content requirements for e-commerce packaging and express delivery logistics. The Ministry of Ecology and Environment enforcement protocols are accelerating local PLA and PBAT resin capacity builds, though quality consistency gaps persist against imported European compound grades. Domestic brands are responding by consolidating procurement around state-affiliated compounders with guaranteed feedstock access.
Automotive sustainability scorecards now weight material circularity alongside cost and performance, compressing traditional supplier evaluation cycles from annual to quarterly reviews. Tier-one interior suppliers are responding by embedding compounders earlier in design-for-recycling workflows and demanding mass-balance certification for bio-attributed feedstocks. This behavioral shift is most visible in German OEM supply chains where CSRD reporting requirements cascade disclosure obligations down to tier-three material suppliers.
Global Bioplastic Composites Market Segmentation
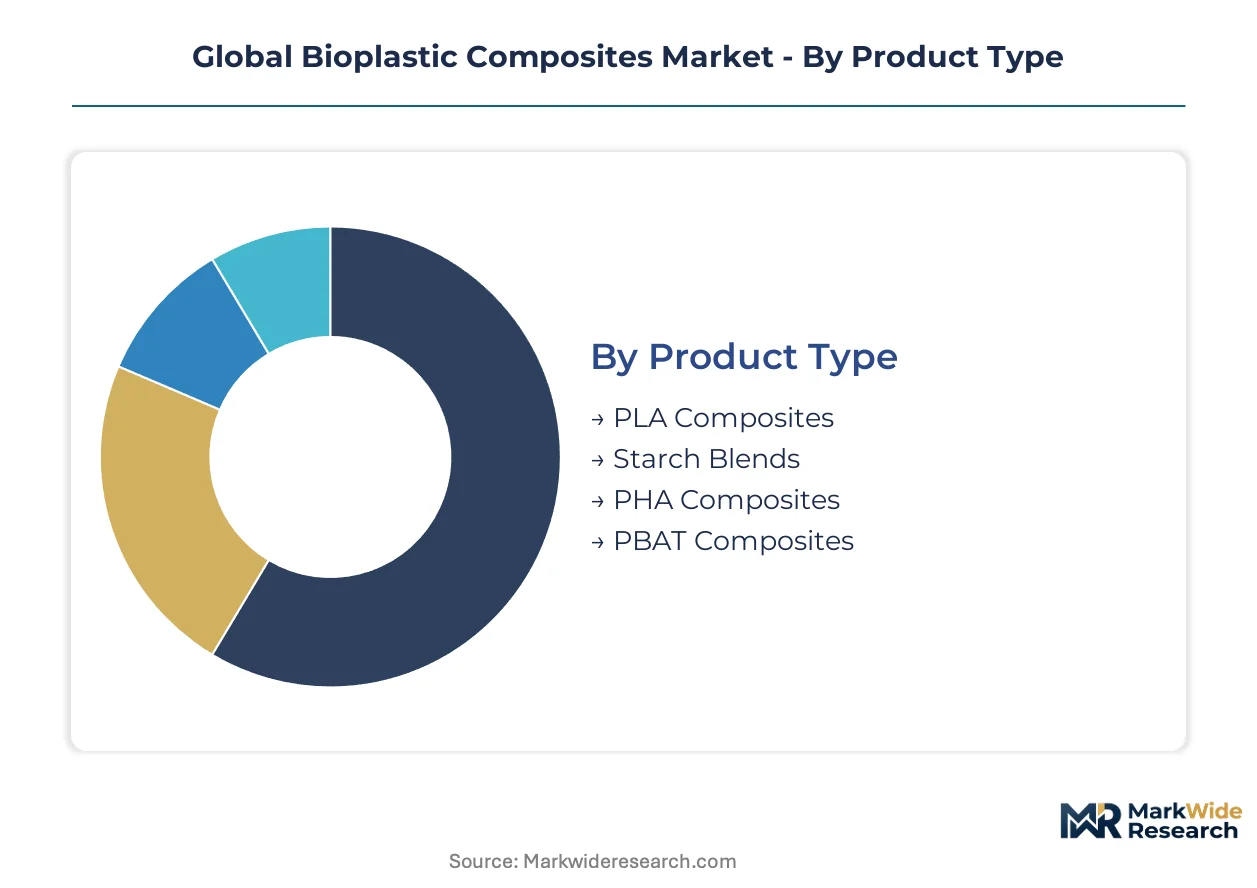
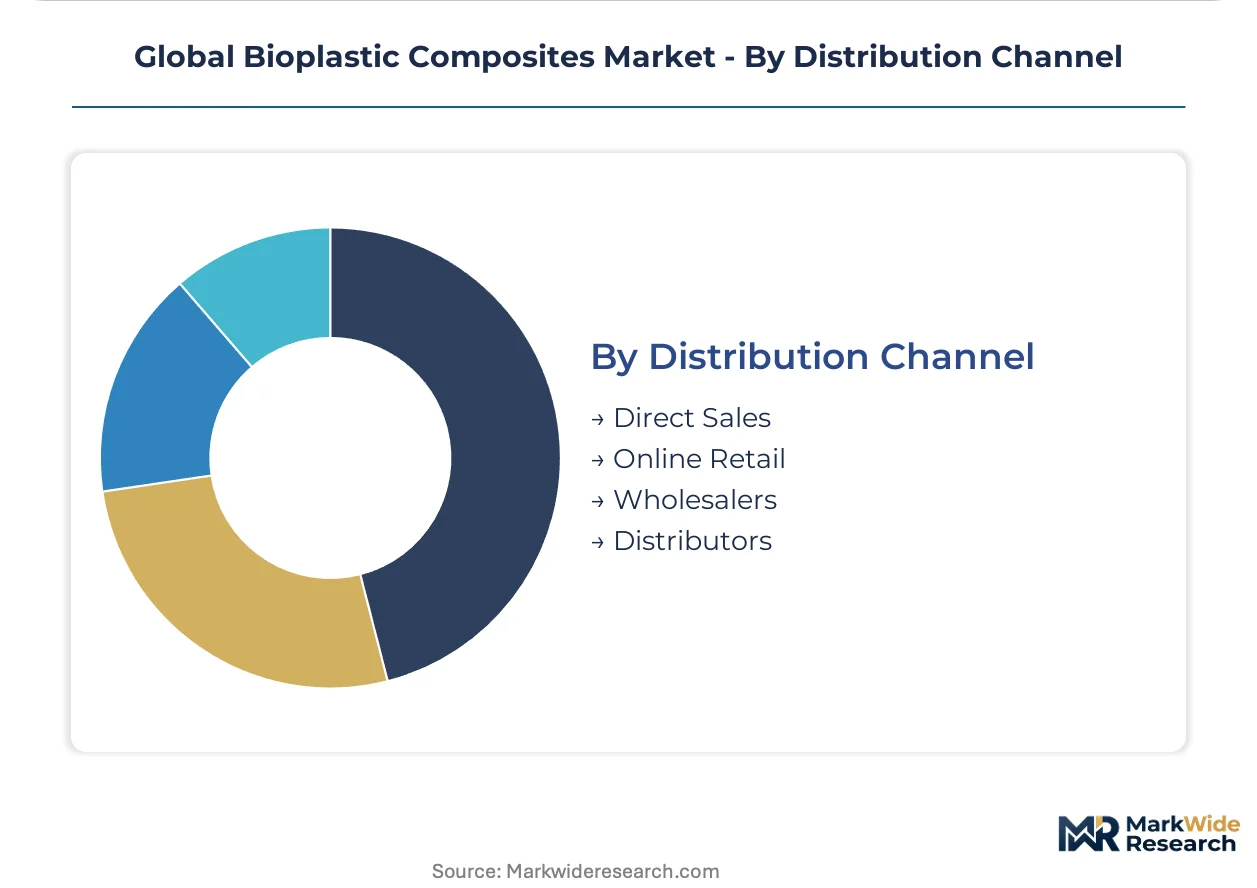
Bioplastic composites fragment across four distinct dimensions, with product chemistry and end-use specifications determining channel strategy. Compounders route high-volume automotive contracts through direct sales teams, while packaging grades flow through distributor networks to mid-sized converters.
Product Type:
Channel strategy diverges sharply: automotive-qualified grades move through direct technical sales, while commodity packaging compounds reach processors via distributors.
- PLA Composites:Polylactic acid matrices reinforced with flax or hemp fibers deliver stiffness comparable to glass-filled polypropylene at densities 15% lower. BMW and Volkswagen procurement teams in Germany have anchored multi-year supply agreements for dashboard substrates, insulating compounders from sugarcane feedstock volatility.
- PHA Composites:Polyhydroxyalkanoate formulations achieve marine biodegradability certification under ASTM D6691, unlocking agricultural mulch films and medical device applications where composting infrastructure remains undeveloped. Pricing premiums of 40-60% over conventional plastics persist due to fermentation-scale constraints.
- Starch Blends:Thermoplastic starch matrices blended with aliphatic polyesters serve disposable cutlery and food trays through wholesale distribution channels in India and Southeast Asia.
- PBAT Composites:Polybutylene adipate terephthalate copolymers provide flexibility and tear resistance for flexible packaging films, with Chinese e-commerce logistics driving domestic capacity expansion.
By volume, PLA Composites leads. By growth pace, PHA Composites is climbing the fastest.
End User:
Cost-tier stratification separates premium automotive specifications from commodity packaging volumes, with margin structures diverging by 300-400 basis points.
- Packaging:Food-contact trays, cutlery, and flexible films dominate tonnage consumption, with FSSAI draft guidelines in India and China's GB standards tightening compostability verification requirements for importers.
- Automotive:Interior panels and structural load floors command specification rigor, with Audi and Mercedes-Benz qualifying hybrid flax-carbon laminates for 2027 model year applications where sustainability scorecards intersect with weight reduction mandates.
- Consumer Goods:Durable goods manufacturers specify bioplastic composites for brand differentiation in European markets, though price sensitivity limits penetration in mass-market segments.
- Electronics:Casing and housing applications remain nascent, constrained by natural fiber degradation above 220°C that conflicts with high-heat soldering processes.
Packaging absorbs the highest absolute volumes. Automotive generates the steepest margin expansion.
Application:
Volume concentration in food-contact packaging contrasts with emerging medical device demand, where certification complexity extends sales cycles.
- Food Packaging:Trays, clamshells, and films for fresh produce and prepared meals flow through industrial composting streams in Germany and the Netherlands, where EN 13432-certified facilities operate at scale.
- Automotive Interiors:Door panels, seatback structures, and load floors integrate continuous fiber-reinforced tapes, with tier-one molders retooling compression presses for natural fiber handling.
- Household Items:Storage containers and kitchenware segments compete with petroleum-based polypropylene on cost, limiting bioplastic penetration outside premium retail channels.
- Medical Devices:Single-use surgical instruments and drug delivery systems leverage PHA marine biodegradability, with FDA 510(k) pathways and MDR compliance in Europe extending development timelines.
Food Packaging anchors current volumes. Medical Devices is expanding most quickly.
Distribution Channel:
Customer-type segmentation separates multinational OEMs requiring technical service from price-sensitive converters buying on specification.
- Direct Sales:Automotive and medical device manufacturers negotiate multi-year contracts with compounders, embedding quality engineers in design-for-recycling workflows and demanding mass-balance certification for bio-attributed feedstocks.
- Distributors:Regional plastics distributors stock standard PLA and PBAT grades for packaging converters, with inventory positions concentrated in Hamburg, Rotterdam, and Singapore port zones.
- Wholesalers:Volume traders supply commodity starch blends to Indian and Southeast Asian processors, with FSSAI and BIS certification requirements filtering supplier qualification.
- Online Retail:3D printing filament formulations for fused deposition modeling reach architectural modelers and medical prototypers through specialized e-commerce channels, displacing petroleum-based ABS in niche workflows.
Distributors move the highest tonnage. Direct Sales captures the steepest value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive procurement teams anchor premium-grade demand through multi-year supply agreements, while Chinese e-commerce logistics and Indian food-contact regulations are opening volume-tier opportunities for commodity compounders.
Germany
BMW and Volkswagen procurement specifications for dashboard substrates and door trim panels concentrate demand among Bavarian and Lower Saxon compounders. The EU Green Deal's binding material substitution targets and CSRD disclosure obligations cascade through tier-three supplier networks. Stuttgart and Wolfsburg industrial clusters host technical service teams embedded in OEM design-for-recycling workflows.
United States
PLA resin production capacity expansions in Nebraska and Minnesota serve North American packaging converters and 3D printing filament distributors. FDA food-contact approvals and EPA compostable product guidelines govern market access, with industrial composting infrastructure concentrated in California and select Northeast municipalities. Midwestern agricultural processing corridors supply corn-derived feedstock to regional compounders.
China
Domestic PBAT and PLA resin capacity builds accelerate around Yangtze River Delta chemical parks to serve e-commerce packaging and express delivery logistics. The Ministry of Ecology and Environment enforces GB standards for biodegradable plastics alongside dual carbon intensity targets. Zhejiang and Jiangsu provinces concentrate compounding operations with state-affiliated feedstock guarantees.
India
FSSAI draft guidelines on compostable food-contact materials and BIS certification pathways are opening import substitution opportunities for tray and cutlery compounders. Maharashtra and Gujarat industrial corridors host emerging PLA processing capabilities. Mumbai and Ahmedabad converter clusters demand certification support from compounders establishing local technical presence.
Brazil
Sugarcane ethanol feedstock concentration in São Paulo state underpins Braskem's global PLA supply chain positioning. ANVISA pharmaceutical regulations and agricultural mulch film demand from Mato Grosso soybean operations create dual market anchors. Campinas and Piracicaba chemical processing hubs sustain fermentation-scale biopolymer production.
Global Bioplastic Composites Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with bio-attributed feedstock divisions and specialized biopolymer pure-plays with dedicated fermentation assets. Structure concentrates around three strategic archetypes: sugarcane-integrated resin producers, natural fiber reinforcement specialists, and automotive-qualified compounders with OEM-embedded technical service. Dominant competitive moves include backward integration into captive agricultural feedstock supply and strategic partnerships with tier-one automotive molders for qualification workflows.
Among the sugarcane-integrated tier, Braskem anchors Brazilian feedstock dominance, while NatureWorks LLC exemplifies North American PLA specialization. BASF SE occupies a position within the diversified chemical conglomerate archetype, leveraging polyamide and PBAT formulation expertise for high-heat automotive applications.
| Leading Market Players |
|---|
| Braskem |
| Arkema |
| Mitsubishi Chemical Group Corporation |
| Dow Inc. |
| BASF SE |
| NatureWorks LLC |
| Owens Corning |
| Toray Industries |
| TotalEnergies Corbion |
| Others |
Supply & Pricing Matrix
EU REACH microplastic restrictions gate both supplier qualification and price differentiation simultaneously, forcing compounders to absorb certification costs for biodegradable alternatives while petroleum-based competitors retain cost advantages in non-regulated segments.
Pricing Analysis
Next-generation PHA composite formulations command 40-60% premiums over current-generation PLA grades due to marine biodegradability certification under ASTM D6691, while prior-generation starch blends face commoditization in Indian and Southeast Asian cutlery markets. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified grades with mass-balance certification from commodity packaging compounds and wholesale starch blends. Cost compression in commodity PLA tiers is intensifying because Brazilian sugarcane ethanol pricing volatility transmits directly to resin costs. Packaging converters in India and Southeast Asia exhibit highest price sensitivity, while German automotive OEM procurement teams prioritize sustainability scorecard compliance over unit economics.
Supply Chain Analysis
Brazil anchors global PLA resin feedstock through São Paulo state sugarcane ethanol concentration, while Germany and China concentrate compounding capacity for automotive and e-commerce packaging applications respectively. Natural fiber reinforcement sourcing draws from French and Belgian flax and hemp cultivation, with Chinese PBAT resin capacity expanding around Yangze River Delta chemical parks. Single-source vulnerability in Brazilian sugarcane supply exposes compounders to regional weather disruptions and ethanol pricing swings. Distribution runs through direct technical sales for automotive OEMs, regional distributors in Hamburg and Rotterdam port zones for packaging converters, and specialized e-commerce channels for 3D printing filament formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German automotive OEM procurement consolidation around BMW and Volkswagen sustainability mandates has shifted negotiating power toward buyers, compressing compounder margins and accelerating qualification timeline demands.
For Market Incumbents: Secure multi-year feedstock offtake agreements with Brazilian sugarcane processors to insulate against ethanol price volatility, while embedding technical service teams within Stuttgart and Wolfsburg OEM design-for-recycling workflows to defend against emerging Chinese compounders with state-affiliated feedstock guarantees. Certification investment in EN 13432 and ASTM D6691 compliance represents the critical lever for maintaining premium positioning as REACH restrictions harden. For New Entrants and Emerging Players: Anchor in Indian packaging conversion opportunities opened by FSSAI draft guidelines on compostable food-contact materials, where import substitution demand outpaces domestic PLA processing capabilities. Maharashtra and Gujarat industrial corridors offer the most penetrable geography for tray and cutlery compounders establishing local technical presence with BIS certification support. Direct sales to Mumbai and Ahmedabad converter clusters provides the optimal go-to-market angle versus distributor-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified petrochemical conglomerates with underperforming bio-attributed feedstock divisions lacking OEM-embedded technical service capabilities. Long-term viability across the analysis window hinges on compounders capturing automotive qualification workflows before incumbent relationships solidify. Watch for inflection in Chinese GB standards enforcement protocols as the signal indicating domestic capacity quality convergence against European import grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugarcane Feedstock | Braskem's Brazilian ethanol supply chain demonstrates how captive agricultural sourcing stabilizes PLA resin cost structures against commodity volatility. |
| Automotive OEM Technical Partnership | BMW and Volkswagen multi-year supply agreements validate how embedded design-for-recycling workflows anchor premium-grade demand. |
| Marine Biodegradability Certification | ASTM D6691 compliance unlocks agricultural mulch and medical device segments where composting infrastructure remains undeveloped. |
| Regional Compounding Capacity Expansion | Chinese Yangtze River Delta PBAT builds respond to Ministry of Ecology and Environment GB standards enforcement for e-commerce logistics. |
| Natural Fiber Surface Treatment Licensing | Silane coupling agent protocols address the fiber-matrix adhesion chemistry gap constraining high-performance automotive applications. |
Research Methodology
Initial hypotheses were tested against primary input from automotive Tier 1 procurement managers, bioplastic compounder technical directors, natural fiber reinforcement suppliers, and packaging converter operations heads, and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and OEM sustainability disclosure documents. Bottom-up volume estimates from individual compounder capacity announcements were triangulated against top-down demand projections derived from EU Green Deal material substitution targets and automotive sustainability scorecard weightings.
Variance decomposition across the projection horizon isolates feedstock price volatility, regulatory enforcement timing, and automotive qualification cycle duration as primary uncertainty sources. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, distribution channel structure, and regional regulatory cluster. CAGRs were synthesized from historical capacity utilization trends and announced expansion timelines. Industry-specific forecast inputs incorporate sugarcane ethanol pricing correlation coefficients and EN 13432-certified composting facility deployment rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU REACH enforcement and stable Brazilian agricultural output; material deviation in either driver would warrant model refresh. Recalibration cycles align with quarterly CSRD disclosure obligations and annual automotive platform specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
US Bioplastics Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biodegradable Microbeads Market