
 Global Synthetic and Bio Based Biodegradable Plastics Market | 2026-2036
Global Synthetic and Bio Based Biodegradable Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic and Bio Based Biodegradable Plastics Market Intelligence
Significant new production capacity from Asian manufacturers is rebalancing the supply landscape for polylactic acid (PLA). NatureWorks LLC leverages its established production scale in the United States to maintain market leadership. In Europe, BASF SE competes through its portfolio of certified compostable polymers for specific applications. Novamont S.p.A. specializes in starch-based bioplastics, differentiating its offerings for agricultural films.
Synthetic and bio-based biodegradable plastics are polymers designed to break down into water, carbon dioxide, and biomass under specific environmental conditions. These materials, such as polylactic acid (PLA), are derived from renewable resources like corn starch or from fossil fuels but are engineered for microbial decomposition. PLA and Starch Blends currently dominate production volume, especially for rigid food packaging applications. The Packaging end-use segment holds the largest share, while materials for agricultural films represent a high-growth area.
Regulatory frameworks such as the EU Green Deal and China's national GB standards for degradable plastics are creating firm market-access requirements. In the United States, the FTC's Green Guides govern marketing claims, ensuring clarity on biodegradability and compostability for consumers. Future material selection will hinge on aligning polymer performance with specific end-of-life infrastructure, such as industrial composting facilities versus marine environments.
Market Dynamics
Regulatory frameworks requiring circularity are the central force shaping the biodegradable plastics market. Mandates like the EU Green Deal and China's national GB standards create firm market-access requirements, compelling polymer producers to align material science with specific end-of-life infrastructures.
Growth Catalysts
- EU Single-Use Plastics Directive:This directive's restrictions on conventional plastic items create direct substitution demand for certified compostable PLA and starch-based materials in food service and packaging.
- Sustainable Food Packaging Demand:Major consumer packaged goods companies are adopting bio-based films and rigid containers to meet corporate sustainability goals and respond to consumer preference for greener packaging.
- Chinese Policy Support:National policies in China promote degradable materials for applications like agricultural mulch films and e-commerce mailers, creating massive domestic volume supported by the nation's manufacturing scale.
Market Restraints
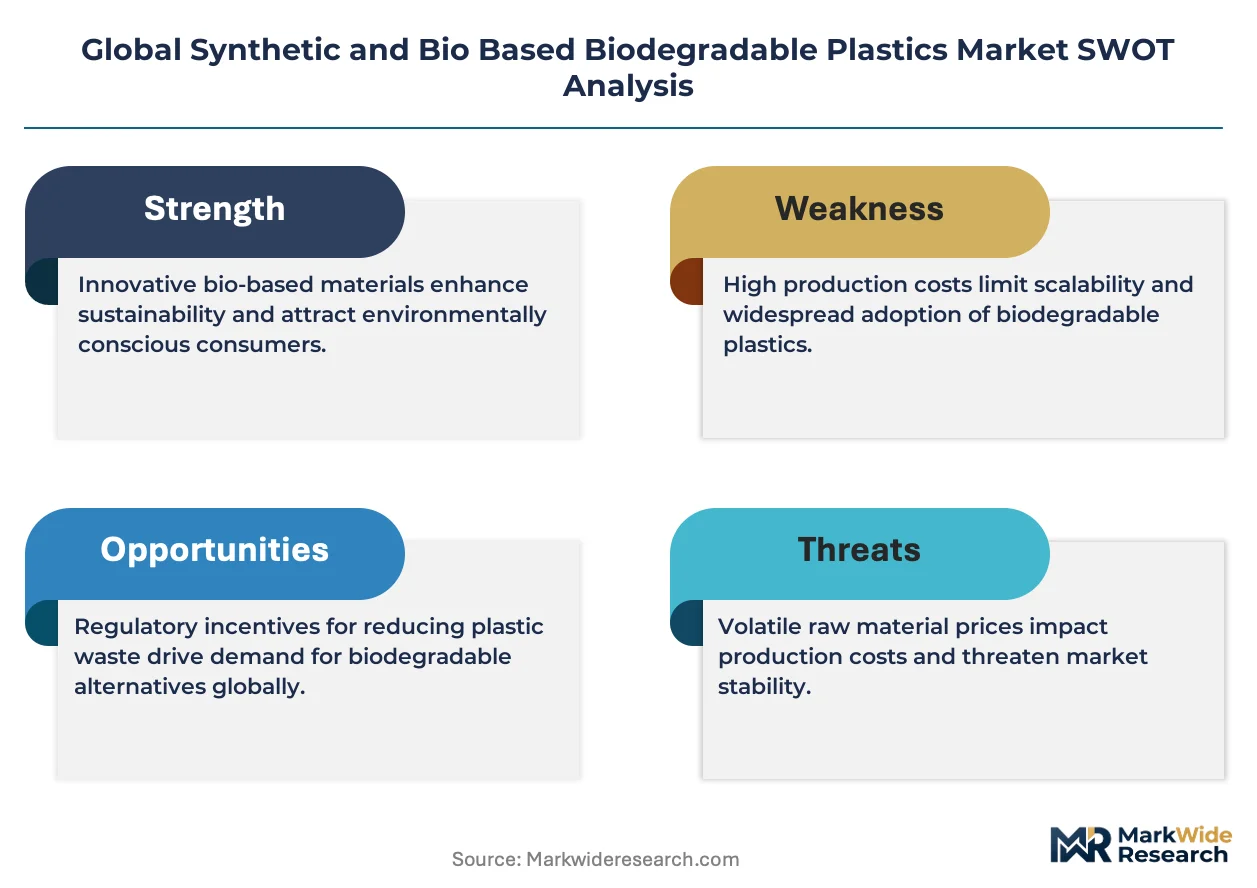
- Feedstock Price Volatility:The cost of agricultural inputs like corn and sugarcane, which are primary feedstocks for PLA, is subject to fluctuations in global commodity markets, impacting polymer price stability.
- Technical Performance Gaps:Certain bio-based polymers exhibit lower heat resistance and barrier properties compared to petroleum-based plastics, limiting their use in demanding applications like hot-fill containers.
- Limited Composting Infrastructure:The lack of widespread industrial composting facilities in many regions, including large parts of the United States, hinders the proper end-of-life disposal pathway for many biodegradable products.
Strategic Opportunities
- High-Performance Agricultural Films:Developing biodegradable mulch films with degradation rates tailored to specific crop cycles offers a significant opportunity to replace polyethylene films that cause soil contamination.
- Marine-Degradable Polymers:Formulating new polymers, such as specific PHA grades, that are certified to biodegrade in marine environments directly addresses global concerns over ocean plastic pollution.
- Indian Market Entry:India's national phase-out of many single-use plastics presents a vast, underpenetrated market for biodegradable alternatives, particularly in the food service and retail packaging sectors.
Industry Challenges
- Confusing Labeling Standards:A lack of globally harmonized standards for terms like "biodegradable" and "compostable" creates consumer confusion and complicates marketing, subject to oversight from bodies like the FTC.
- End-of-Life Sorting Complexity:The contamination of conventional plastic recycling streams with biodegradable plastics presents a significant operational challenge for material recovery facilities (MRFs) worldwide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic and Bio Based Biodegradable Plastics Market |
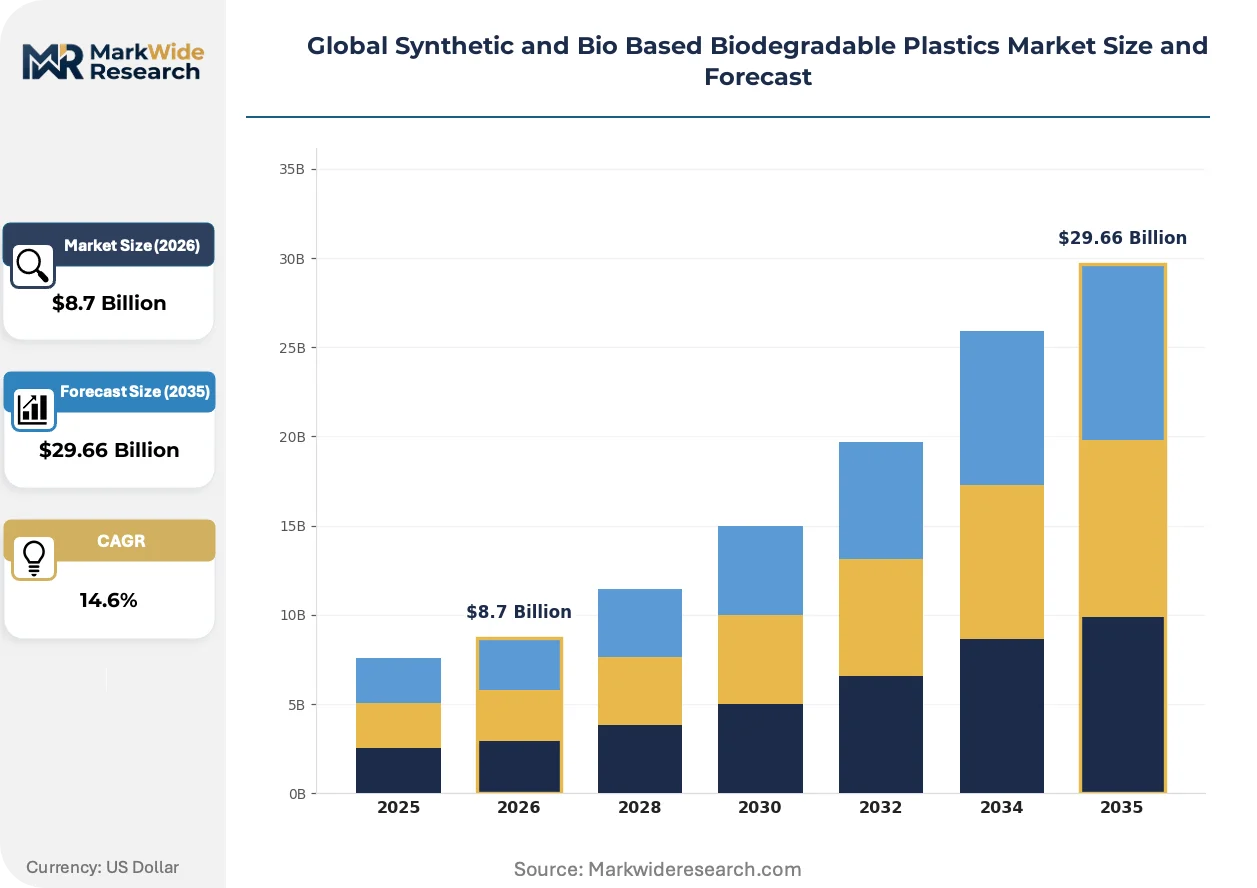
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, PBS End User: Packaging, Agriculture, Consumer Goods, Textiles Form: Film, Foam, Sheet, Granules Application: Food Packaging, Medical Devices, Disposable Cutlery, Agricultural Films |
| Companies Covered | NatureWorks LLC, BASF SE, TotalEnergies Corbion, Novamont S.p.A., Mitsubishi Chemical Group Corporation, Danimer Scientific, Biome Bioplastics, Braskem S.A., Futerro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic and Bio Based Biodegradable Plastics Market Strategic Shifts & Innovations
Material science is advancing beyond simple substitution toward achieving performance parity with conventional plastics. The innovation focus is now on designing polymers for specific, verifiable end-of-life scenarios, from industrial compost facilities to soil and marine environments.
High-heat resistant PLA grades are engineered to withstand higher temperatures, addressing a key performance limitation of standard polylactic acid. The food service and durable goods sectors are adopting these materials for applications such as reusable cups and automotive interior components. This development of performance-enhanced bioplastics is electrifying the competition with engineering thermoplastics like ABS and polycarbonate in non-packaging applications.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on circular economy performance and material lifecycle impacts. This policy forces companies to quantify and report the environmental footprint of their packaging choices, moving beyond simple marketing statements. The consumer goods and food packaging sectors are most affected, now requiring verifiable data on biodegradability and compostability from their polymer suppliers.
Brand owners are moving from material-agnostic purchasing to specifying polymers based on compatibility with regional end-of-life infrastructure. This shift disrupts the one-size-fits-all sales model, favoring suppliers who offer a portfolio of materials certified for different disposal pathways like industrial versus home composting. This behavior is most visible in Western Europe, where municipal waste collection systems are highly segmented.
Global Synthetic and Bio Based Biodegradable Plastics Market Segmentation
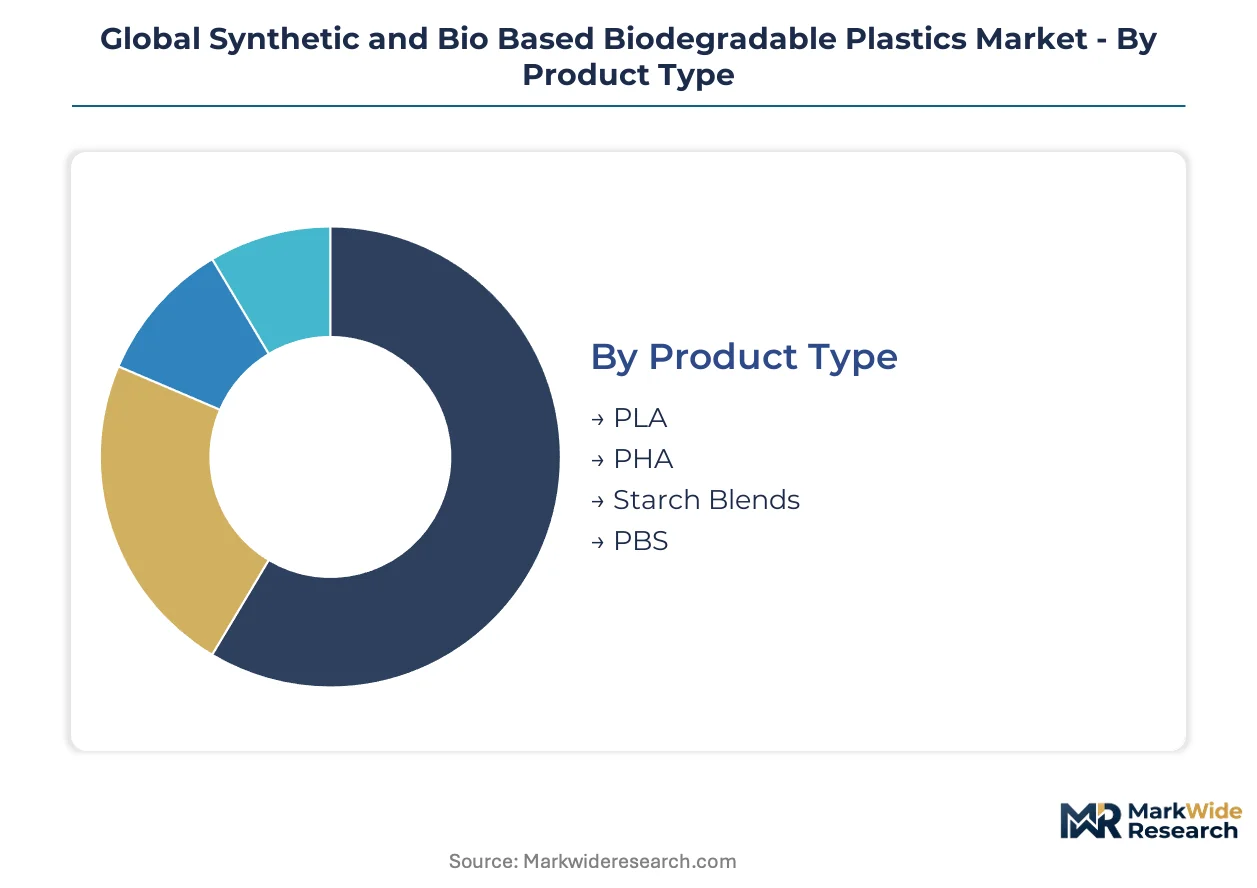
The segmentation of the global synthetic and bio based biodegradable plastics market illuminates distinct material science pathways and end-use applications. Understanding these segments is critical for polymer producers to align product development with specific regulatory requirements and infrastructure availability.
Product Type:
The market for biodegradable plastics differentiates between materials designed for standalone use and those integrated into complex systems.
- PLA:This bio-based polymer, derived from renewable resources like corn starch, undergoes microbial decomposition under industrial composting conditions. Demand concentrates in rigid food packaging applications across Europe and the United States, driven by circular economy mandates.
- PHA:Polyhydroxyalkanoates are biodegradable polyesters produced by bacteria, known for their potential to degrade in marine environments. Specific PHA grades are gaining traction for addressing ocean plastic pollution concerns, particularly in packaging and single-use items.
- Starch Blends:These materials combine starch with other polymers to enhance biodegradability and processability, often certified for industrial composting. Chinese national policies significantly support their volume in agricultural films and e-commerce mailers.
- PBS:Polybutylene succinate is a synthetic biodegradable polyester that can be derived from both fossil fuels and bio-based succinic acid, offering good heat resistance. It finds use in packaging films and some durable goods where moderate thermal stability is required.
PLA leads volumes today; PHA is gaining share fastest.
End User:
Market segmentation by end user reveals how different industries adopt biodegradable plastics to meet their specific application needs.
- Packaging:This segment encompasses both rigid and flexible solutions for protecting and containing products, from food containers to consumer goods wraps. The EU Single-Use Plastics Directive and consumer preference for sustainable packaging significantly influence material selection in this sector.
- Agriculture:Biodegradable polymers are employed in agricultural films, such as mulch films and seedling pots, to reduce plastic waste and soil contamination. China's national policies actively promote degradable materials for these applications, leveraging the country's vast agricultural sector.
- Consumer Goods:This category includes items like disposable cutlery, personal care product containers, and some durable components. Performance-enhanced bioplastics, including high-heat resistant PLA, are expanding their footprint in these applications, replacing conventional plastics.
- Textiles:Biodegradable plastics are being explored for fibers and non-woven fabrics in applications ranging from disposable hygiene products to sustainable apparel. Innovations focus on achieving comparable performance to traditional textile materials.
Packaging holds the largest market share, while agriculture demonstrates significant expansion.
Form:
The market also segments by the physical form in which biodegradable plastics are supplied, influencing their processing and final application.
- Film:This form includes thin, flexible sheets used primarily for wrapping, bags, and agricultural covers. Bio-based films are replacing conventional polyethylene in food packaging and mulch applications, driven by regulatory pressures and sustainability goals.
- Foam:Biodegradable foams offer lightweight cushioning and insulation properties for protective packaging and disposable food service items. These materials provide alternatives to expanded polystyrene in various sectors.
- Sheet:Rigid sheets of biodegradable plastics are thermoformed into trays, containers, and other structural components. They serve as direct substitutes for petroleum-based plastics in applications like food packaging and consumer product housing.
- Granules:Granules represent the pelletized raw material form of biodegradable polymers, used by converters for extrusion, injection molding, and other manufacturing processes. This form is the primary input for most downstream processing of biodegradable plastics.
Film products command the highest volume, with granules serving as the fundamental input for manufacturing.
Application:
Segmentation by application highlights the specific uses where biodegradable plastics deliver functional benefits and meet market demand.
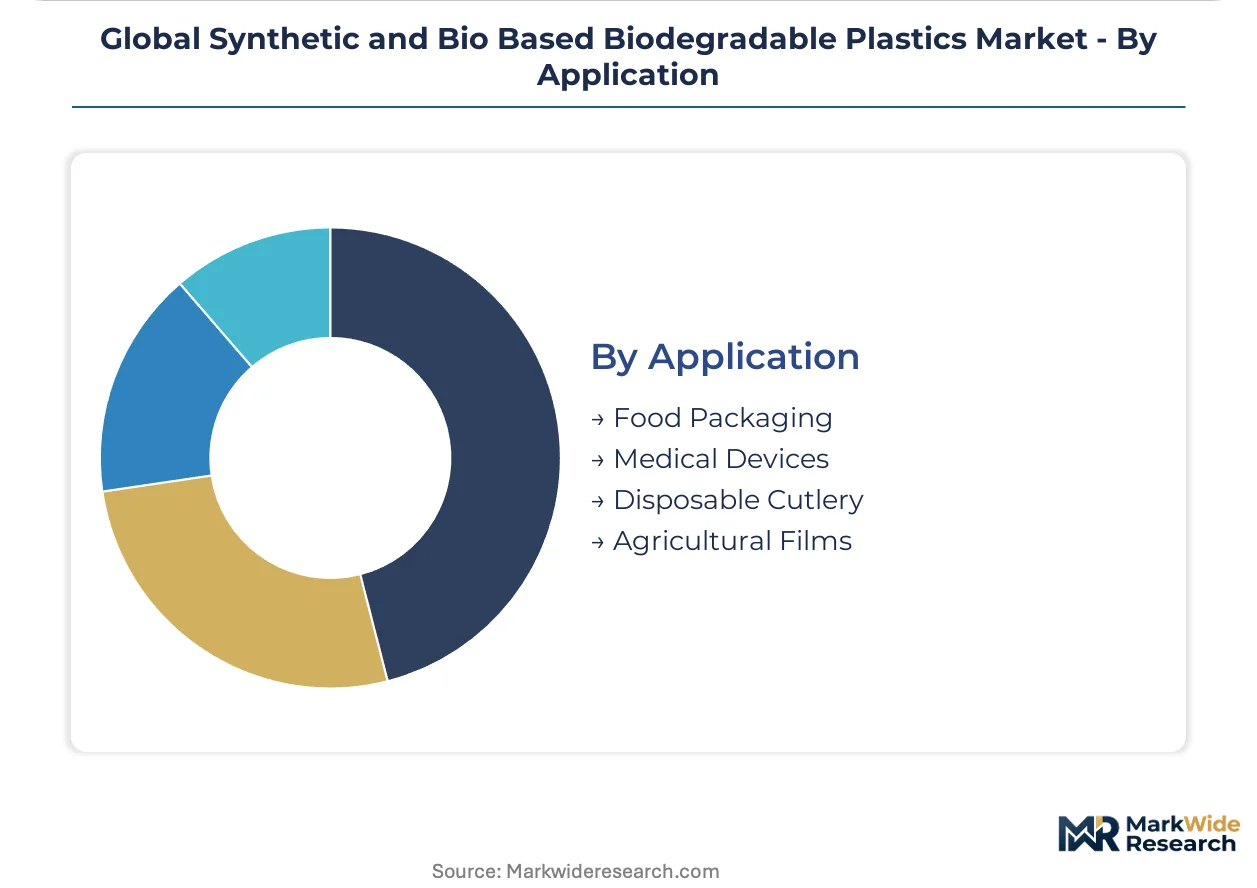
- Food Packaging:This dominant application includes rigid containers, flexible films, and coatings for various food products. Regulatory frameworks like the EU Green Deal compel brands to adopt certified compostable materials for food contact applications.
- Medical Devices:Biodegradable polymers are utilized in specialized medical applications such as dissolvable sutures, drug delivery systems, and temporary implants. Biocompatibility and controlled degradation rates are critical performance parameters in this sector.
- Disposable Cutlery:Single-use items like forks, spoons, and knives made from biodegradable plastics address environmental concerns associated with conventional plastic waste. The EU Single-Use Plastics Directive specifically restricts many traditional plastic items, driving demand here.
- Agricultural Films:This segment covers mulch films, greenhouse films, and other agricultural coverings designed to degrade in soil after their useful life. China's national GB standards promote the use of degradable agricultural films to prevent persistent plastic pollution.
Food packaging currently absorbs the largest share, and agricultural films are experiencing rapid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between developed and emerging markets drives a significant arbitrage opportunity, where production and innovation often migrate to regions with favorable policy environments or lower compliance costs. This dynamic influences material selection and end-of-life infrastructure development across diverse geographies. Market players must navigate differing national standards and consumer preferences to establish effective supply chains.
China
Chinese demand for degradable materials is propelled by national policies promoting sustainable materials in agriculture and e-commerce. The national GB standards for degradable plastics create firm market-access requirements for domestic and international suppliers. Manufacturing hubs in the Yangtze River Delta actively scale up production of starch blends and PLA to meet this massive domestic volume.
United States
Consumer preference for sustainable packaging and corporate sustainability goals drive demand for bio-based plastics in the United States. The FTC's Green Guides govern marketing claims, ensuring clarity on biodegradability and compostability for consumers. Key industrial clusters in the Midwest, particularly around corn-producing regions, support feedstock availability and polymer production facilities.
Germany
European Union directives, such as the EU Single-Use Plastics Directive, stimulate demand for certified compostable PLA and starch-based materials within Germany. The country's robust waste management infrastructure and emphasis on circular economy principles support the adoption of biodegradable plastics. Research and development centers in Bavaria and North Rhine-Westphalia focus on high-performance bioplastic formulations.
India
India's national phase-out of many single-use plastics presents a vast, underpenetrated market for biodegradable alternatives. The Bureau of Indian Standards (BIS) is developing standards for compostable plastics to facilitate wider adoption. Major metropolitan areas like Mumbai and Delhi are experiencing increased demand for biodegradable packaging in the food service and retail sectors.
Japan
Sustainable product innovation and a strong focus on environmental responsibility characterize the Japanese market for biodegradable plastics. METI policies encourage the development and use of eco-friendly materials across various industries. Research institutions and chemical manufacturers in the Kanto region actively develop advanced biodegradable polymers for diverse applications.
Global Synthetic and Bio Based Biodegradable Plastics Market Key Industry Players
North American and European producers anchor one tier of the market, focusing on high-performance materials and certified solutions, while Asian manufacturers hold significant scale advantages in volume production. The market structure exhibits a tiered approach, with established chemical giants competing with specialized bioplastics producers. Strategic partnerships for feedstock security and capacity expansion represent dominant competitive moves.
Within the established producer tier, NatureWorks LLC, a US-based company, consistently leverages its production scale in polylactic acid (PLA) to maintain market leadership. German chemical giant BASF SE exemplifies an archetype focused on a broad portfolio of certified compostable polymers for specific applications. Italian specialist Novamont S.p.A. occupies a position as a leader in starch-based bioplastics, differentiating its offerings for agricultural films and other specialized uses.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| TotalEnergies Corbion |
| Novamont S.p.A. |
| Mitsubishi Chemical Group Corporation |
| Danimer Scientific |
| Biome Bioplastics |
| Braskem S.A. |
| Futerro |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, with its stringent circular economy principles, gates access to qualified biodegradable plastic supply and enables premium-tier pricing for certified materials. This regulatory framework ensures that compliant polymers command higher value.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for biodegradable plastics, especially for high-volume packaging and agricultural applications. The dominant pricing structure is contract-based long-term offtake agreements, with price differentiation driven by certification level, such as industrial compostability, and volume scale. Pricing pressure stems from feedstock price volatility, particularly for corn and sugarcane. Consumer packaged goods companies are highly price-sensitive, while specialized medical device manufacturers prioritize performance.
Supply Chain Analysis
Logistics and freight costs significantly influence final polymer prices, particularly for bulk shipments from major Asian manufacturing hubs to Europe and the United States. Geographic supply concentration centers on China, with its vast PLA and starch blend production, and the United States, home to NatureWorks LLC's large-scale PLA facilities. Raw material dependencies include corn starch, sugarcane, and fossil-derived succinic acid. A structural risk is single-source vulnerability for specialized PHA grades, and distribution runs through established chemical distributors and direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a stable compounder, driven by global regulatory mandates like the EU Single-Use Plastics Directive that consistently stimulate demand for certified biodegradable materials. Consistent policy support underpins steady expansion.
For Market Incumbents:Deepen strategic partnerships with feedstock suppliers to mitigate commodity price volatility and secure long-term input stability. Incumbents must also invest in R&D for high-performance bio-based polymers to counter the threat of petroleum-based plastic alternatives in demanding applications. Expanding certified production capacity in regions like Europe and the United States reinforces market access against stricter environmental regulations.
For New Entrants and Emerging Players:Regional food service providers in India and Southeast Asia represent an underserved buyer archetype, offering a clear entry point for biodegradable packaging alternatives. Target the agricultural mulch film segment in developing economies with cost-effective, soil-degradable solutions. A direct-to-consumer sales model for specialized e-commerce packaging offers a focused go-to-market angle.
For Investors and Strategic Acquirers:Roll-up economics work for specialized bioplastics producers due to structural fragmentation across niche material science and regional end-of-life infrastructure. The market's long-term viability, spanning the next decade, rests on consistent regulatory tailwinds. Target mid-cap companies with strong intellectual property in marine-degradable polymers or established industrial composting certifications. Expansion of industrial composting facilities in North America is a critical signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases global supply volume for polylactic acid, rebalancing market dynamics. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal objectives for polymer production. |
| Long-term Supply Agreement | Secures consistent feedstock supply for starch-based bioplastics, stabilizing production costs. |
| Product Launch: High-Heat PLA | Addresses performance limitations, expanding bioplastic use in demanding consumer goods. |
| Joint Venture for PHA Production | Accelerates development of marine-degradable polymers to combat ocean plastic pollution. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research involved discussions with polymer producers, downstream converters, packaging solution providers, and agricultural film specialists. Secondary sources included national GB standards, EU Green Deal directives, and corporate sustainability disclosures. Bottom-up market sizing was triangulated with top-down validation.
Historical data from comparable periods anchored the forecast window. The analytical framework modeled segmentation dimensions including product type, end-user industry, material form, and application. Compound annual growth rates were derived from projected shifts in demand drivers and supply-side capacity additions. Key forecast inputs included feedstock price trends and industrial composting facility deployments.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in granular regional infrastructure data introduce uncertainty bands. Forecasts reflect assumptions regarding future policy enforcement. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Europe Bioplastics Market
Bioplastics
North America Bioplastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biopolymers Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biodegradable Disposable Tableware Market