
 Global Beauty Supplements Market | 2026-2036
Global Beauty Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beauty Supplements Market Foresight
The capital-intensity divergence between pharmaceutical-grade manufacturers and commodity formulators is redrawing competitive boundaries in beauty supplements. Amway Corporation leverages its direct-sales infrastructure across Asia to sustain premium positioning in collagen and botanical formulations. Nestlé Health Science anchors its portfolio through clinically validated ingredients, while HUM Nutrition Inc. competes via subscription-based personalization that dominates the online retail channel.
Beauty supplements comprise orally administered nutraceuticals containing bioactive compounds—collagen peptides, hyaluronic acid, ceramides, polyphenols, and carotenoids—formulated in capsules, powders, or liquid shots to support dermal matrix integrity, keratin synthesis, and oxidative stress modulation from within. Collagen and antioxidants lead product-type revenue pools due to established consumer recognition and visible-results positioning, while botanicals represent the fastest-expanding category as adaptogenic and Ayurvedic ingredients gain traction in specialty stores and salons. Skin health and anti-aging applications command the largest application share, though hair strengthening segments show accelerated growth in professional and male consumer demographics.
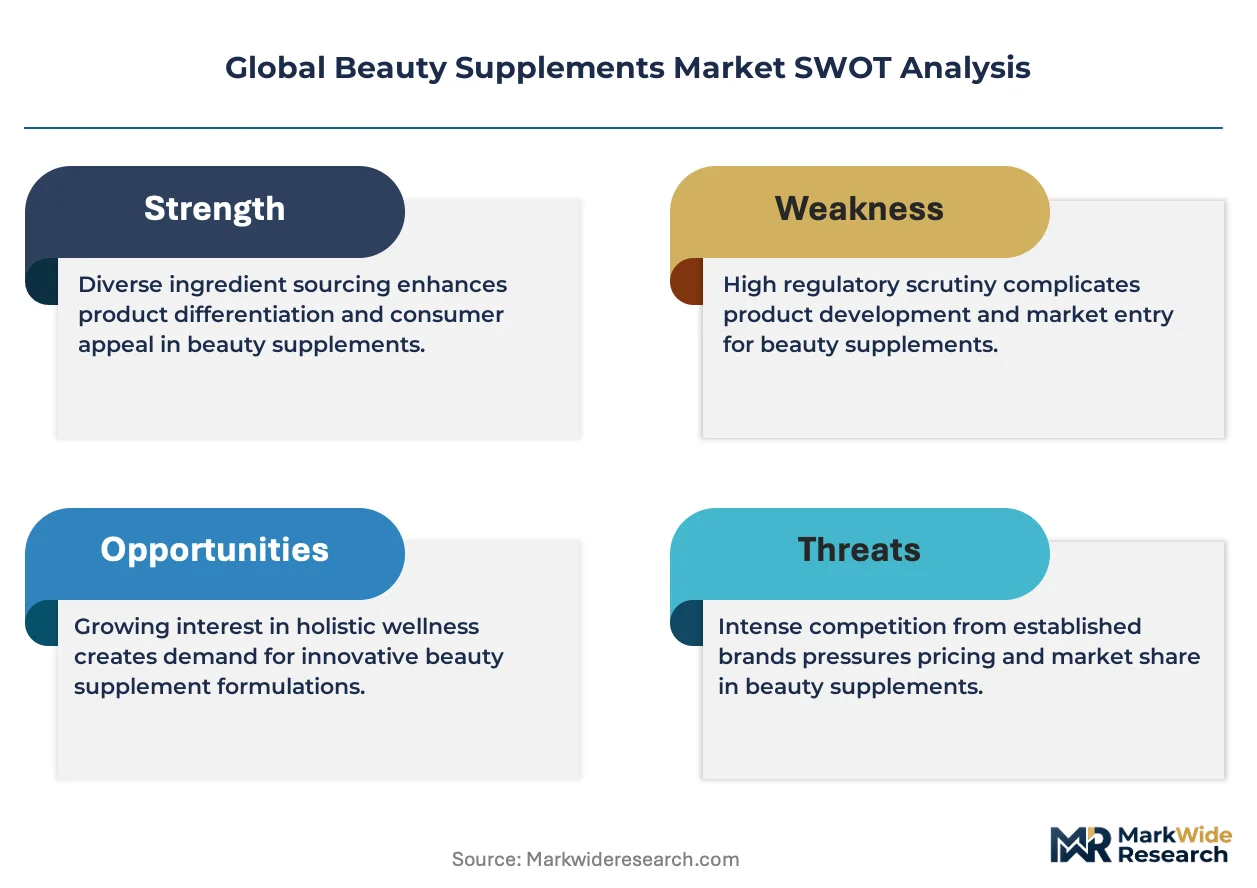
FDA oversight of dietary supplement Good Manufacturing Practices, EFSA health-claims substantiation under EU Regulation 1924/2006, and China's SAMR registration requirements for imported health foods collectively elevate compliance costs and favor scaled players with regulatory affairs capabilities. The EU's forthcoming tightening of beauty-specific health claims will force reformulation or delisting of unsubstantiated products. Stakeholders must monitor evolving borderline classifications between cosmetics, foods, and drugs as regulators scrutinize beauty-positioned supplements with drug-like mechanism claims.
Market Dynamics
The EU's Nutrition and Health Claims Regulation is forcing clinical substantiation investments that separate pharmaceutical-grade manufacturers from commodity formulators, redrawing competitive boundaries across collagen, botanical, and antioxidant segments.
Growth Catalysts
- Direct-to-Consumer Channel Expansion:Millennial and Gen-Z cohorts in the United States and South Korea are accelerating ingestible beauty regimen adoption through subscription models and social commerce platforms.
- SAMR Registration Pathway:China's streamlined health food import procedures under SAMR are lowering market entry barriers for collagen peptide and hyaluronic acid formulations in professional skincare channels.
- EFSA Substantiation Framework:The EU's tightening beauty-from-within claim requirements are pushing brands toward dermatological clinical trials, creating premium tier separation.
Market Restraints
- Marine Collagen Supply Concentration:Wild-caught and aquaculture-sourced marine collagen peptides face input volatility from North Atlantic and Southeast Asian fishery quotas.
- Botanical Extract Standardization Costs:Adaptogenic ingredient suppliers in India and China struggle with batch-to-batch polyphenol consistency, elevating quality assurance expenditures.
- Cross-Border E-Commerce Friction:Divergent customs classifications between cosmetics, foods, and drugs in EU member states create fulfillment complexity for direct-to-consumer brands.
Strategic Opportunities
- Male Demographic Penetration:Hair strengthening and skin health applications in the United States and South Korea show underdeveloped professional channel presence relative to female-skewed positioning.
- Ayurvedic Ingredient Premiumization:Ashwagandha and turmeric formulations in specialty retail and salon channels are capturing margin expansion as adaptogenic positioning gains clinical validation.
- Liquid Shot Format Innovation:Ready-to-drink beauty shots in China's tier-one cities are displacing capsule and powder formats among time-constrained urban professionals.
Industry Challenges
- Clinical Trial Talent Scarcity:Dermatological endpoint expertise for beauty-from-within substantiation concentrates in contract research organizations in Switzerland and Germany, creating recruitment bottlenecks.
- Dual-Use Facility Capex:Pharmaceutical-grade collagen hydrolysate production requires ISO 22000 and GMP co-certification, elevating facility investment thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beauty Supplements Market |
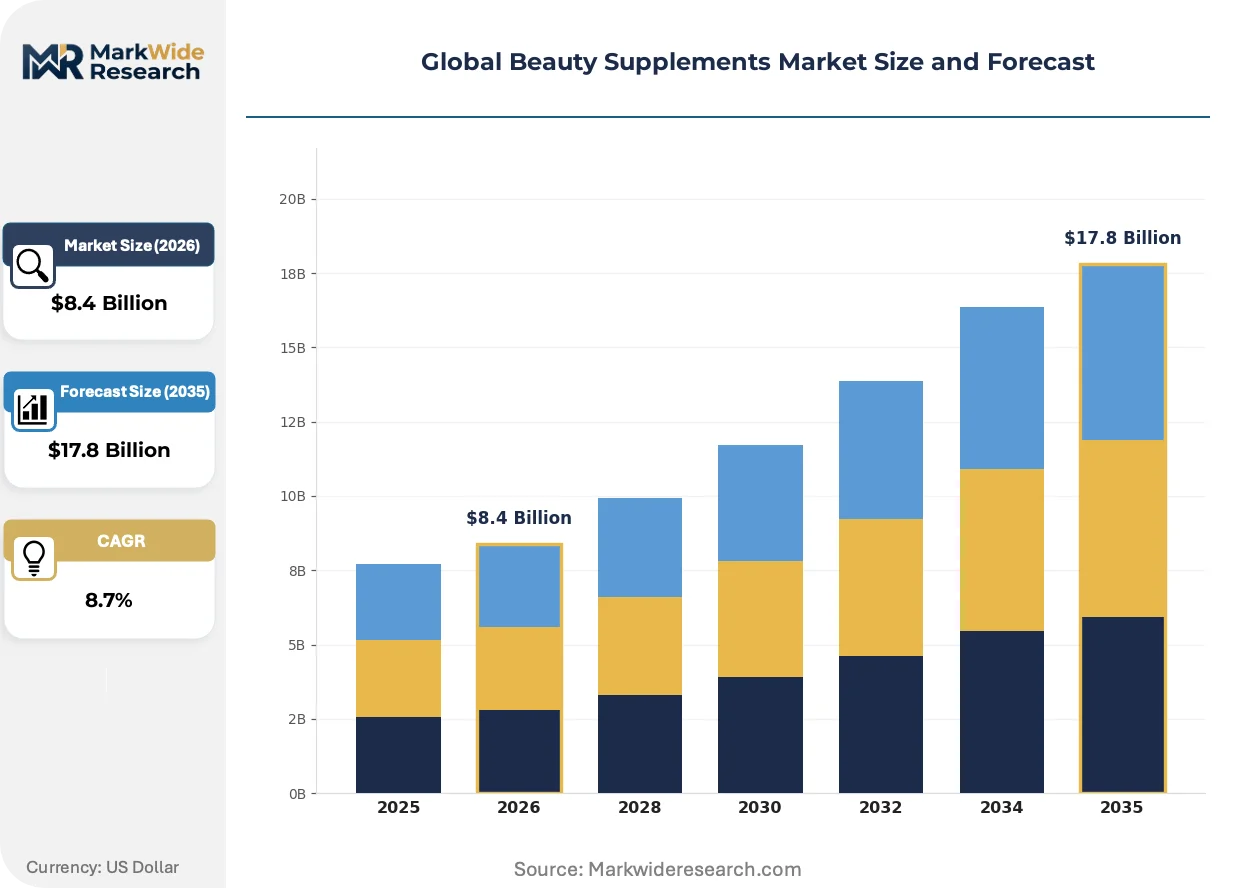
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Vitamins, Minerals, Omega Fatty Acids, Antioxidants, Botanicals Application: Skin Health, Hair Strengthening, Nail Care, Anti-Aging, Brightening, Hydration Consumer Demographic: Women, Men, Seniors, Millennials, Athletes, Professionals Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets, Direct Sales, Salons |
| Companies Covered | Amway Corporation, Nestlé Health Science, Herbalife International of America, Inc., Nu Skin Enterprises, Inc., Meiji Holdings Co., Ltd., Unilever PLC, HUM Nutrition Inc., Gelita, Vital Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beauty Supplements Market Shifts & Advancements
Biotechnology-derived ingredients and precision fermentation are displacing conventional extraction methods, while regulatory convergence between food and cosmetic frameworks is forcing reformulation strategies across major markets.
Precision fermentation of ceramides and hyaluronic acid precursors is decomposing the traditional botanical and animal-derived supply base for dermal matrix support ingredients. Biotech startups in South Korea and the Netherlands are scaling tank-based production of bio-identical compounds at cost parity with marine and plant sources. This technology is compressing lead times from agricultural harvest cycles to weeks, enabling just-in-manufacturing for personalized beauty supplement subscriptions.
EFSA's forthcoming tightening of beauty-specific health claims under EU Regulation 1924/2006 is forcing delisting or reformulation of polyphenol and carotenoid products lacking randomized controlled trial support. The regulation compresses marketing timelines as brands accelerate dermatological endpoint studies. Professional skincare channels in Germany and France are most affected, with salons and medi-spas demanding certificate-of-analysis documentation for ingestible inventory.
Subscription-based personalization platforms are capturing Millennial and Gen-Z consumers through algorithmic skin assessment and monthly regimen customization. The model displaces one-time retail purchases in the United States and United Kingdom, with direct-to-consumer brands building proprietary microbiome and lifestyle datasets. Male consumers in urban China represent the fastest-emerging subscriber cohort for hair-focused botanical formulations.
Global Beauty Supplements Market Segmentation
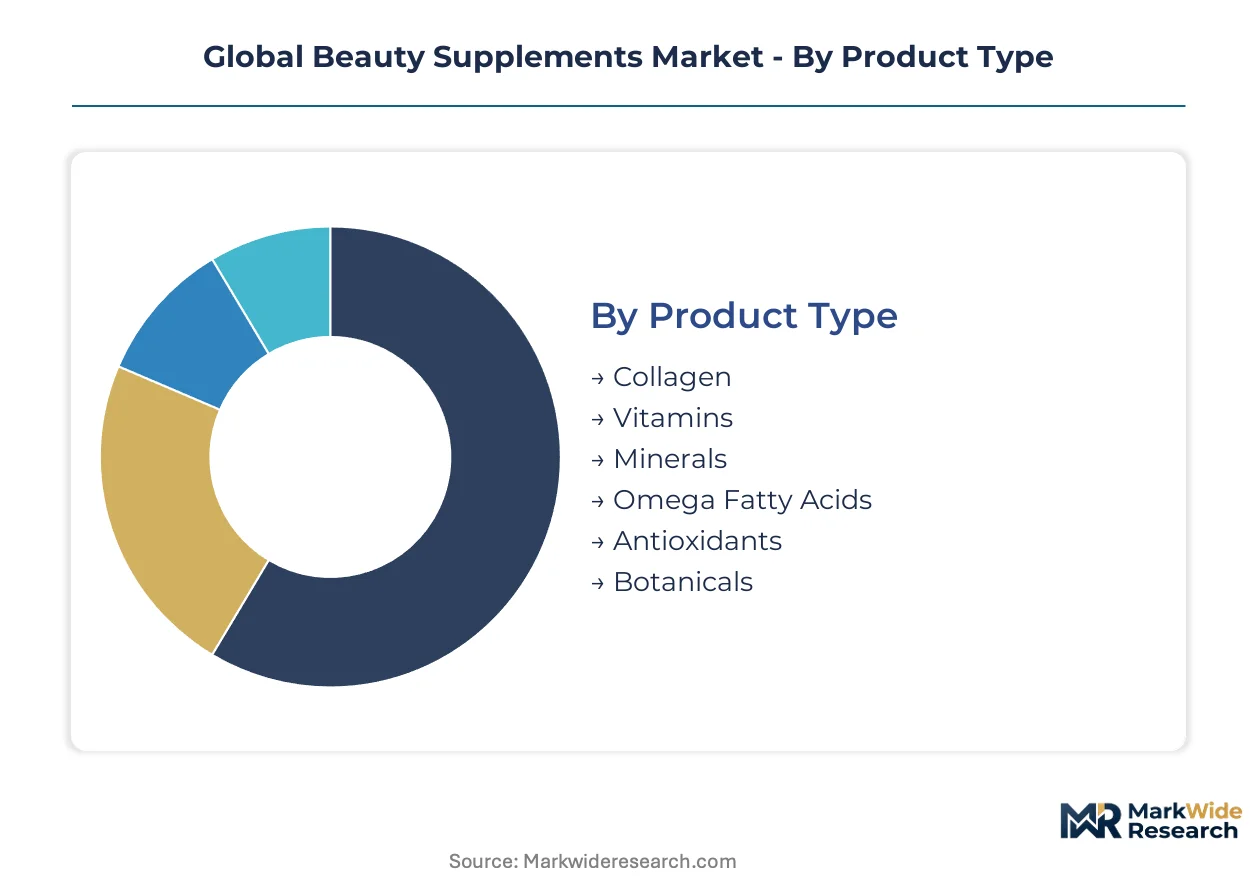
Beauty supplements fragment across four distinct category axes, each carrying divergent margin profiles and regulatory exposure. Product type and application segments concentrate value capture, while demographic and channel splits determine go-to-market economics and brand positioning costs.
Product Type:
Premium tier separation concentrates in collagen and antioxidant formulations, where clinical substantiation investments create defendable price positioning against commodity botanicals.
- Collagen:Hydrolyzed peptide formulations dominate professional skincare channel placement in South Korea and the United States. Marine-sourced variants command price premiums over bovine alternatives, though North Atlantic fishery quotas constrain supply elasticity for premium positioning.
- Antioxidants:Carotenoid and polyphenol complexes require EFSA-compliant randomized controlled trials for EU beauty-from-within claims. Dermatological endpoint validation in Germany and France separates pharmaceutical-grade suppliers from commodity formulators facing delisting pressure.
- Vitamins:Biotin and vitamin C complexes serve entry-level positioning with minimal regulatory friction.
- Minerals:Zinc and selenium formulations target hair and nail applications with established safety profiles.
- Omega Fatty Acids:Marine and plant-derived options compete on sustainability credentials and oxidation stability.
- Botanicals:Ashwagandha and turmeric adaptogens expand fastest in specialty retail and salon channels, though Indian and Chinese suppliers struggle with batch-to-batch polyphenol consistency.
The dominant share belongs to collagen, while botanicals are closing the gap fastest as adaptogenic positioning gains clinical validation.
Application:
Volume concentration skews toward visible-results categories where consumer trial and repurchase correlation remains strongest.
- Skin Health:Dermal matrix integrity formulations—collagen peptides, hyaluronic acid, ceramides—anchor professional channel penetration in China and South Korea. SAMR registration requirements for imported health foods elevate compliance costs, favoring scaled players with regulatory affairs capabilities.
- Anti-Aging:Oxidative stress modulation claims face EFSA tightening under EU Regulation 1924/2006, forcing reformulation or delisting of unsubstantiated polyphenol products.
- Hair Strengthening:Keratin support segments show accelerated growth in male demographics across the United States and South Korea.
- Nail Care:Biotin-centered positioning targets female professionals with convenience-driven format preferences.
- Brightening:Glutathione and carotenoid complexes concentrate demand in East Asian markets with distinct tone-equity positioning.
- Hydration:Hyaluronic acid precursors face displacement threat from precision fermentation alternatives scaling in the Netherlands and South Korea.
Skin health commands the largest revenue pool, though hair strengthening is expanding most quickly as male channel penetration deepens.
Consumer Demographic:
Subscription model viability concentrates in urban professional cohorts with elevated willingness-to-pay for personalization and convenience.
- Women:Traditional category anchor with established salon and specialty store channel presence across all major markets.
- Millennials:Direct-to-consumer adoption leaders in the United States and United Kingdom, driving algorithmic skin assessment and monthly regimen customization platforms.
- Men:Fastest-emerging subscriber cohort for hair-focused botanical formulations in urban China, with underdeveloped professional channel presence relative to female-skewed positioning.
- Seniors:Joint-skin dual-benefit positioning captures pharmacy channel placement with clinical validation requirements.
- Athletes:Performance-recovery crossover demand for collagen and antioxidant formulations in sports nutrition retail.
- Professionals:Time-constrained urban cohorts in China's tier-one cities displace capsule formats with ready-to-drink beauty shots.
Women retain the dominant share, while men are gaining share fastest as male-specific positioning escapes stigma through professional channel normalization.
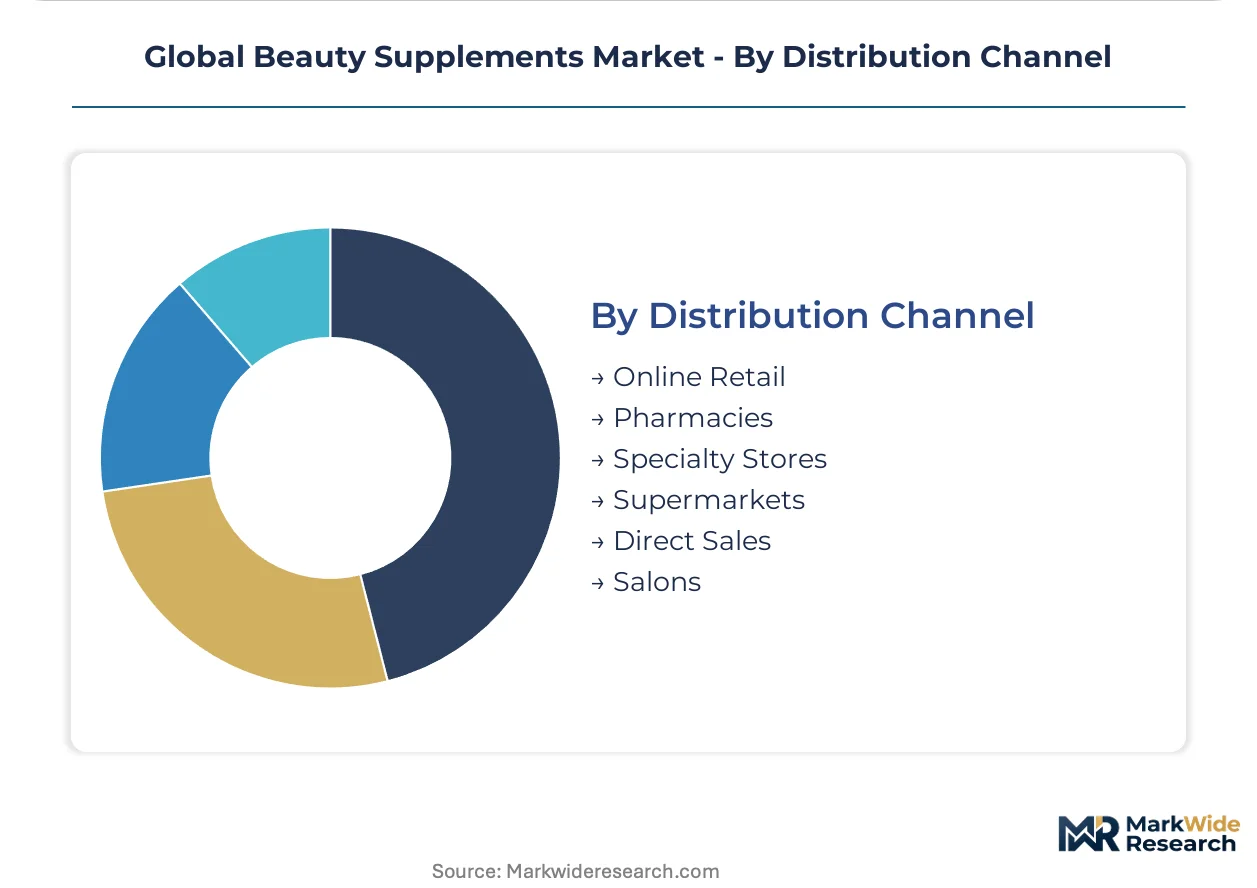
Distribution Channel:
Margin structure inverts between high-touch professional placement and scaled online retail, with regulatory friction determining viable channel mix by geography.
- Online Retail:Subscription-based personalization dominates Millennial and Gen-Z acquisition in the United States and South Korea. Divergent EU member state customs classifications between cosmetics, foods, and drugs create fulfillment complexity for cross-border direct-to-consumer brands.
- Direct Sales:Amway Corporation leverages infrastructure across Asia to sustain premium positioning, though social commerce platforms erode traditional model advantages.
- Pharmacies:Clinical validation requirements align with pharmaceutical-grade manufacturer capabilities in Germany and Switzerland.
- Specialty Stores:Ayurvedic ingredient premiumization captures margin expansion as adaptogenic positioning gains traction.
- Salons:Medi-spa channel in France and Germany demands certificate-of-analysis documentation for ingestible inventory under EFSA pressure.
- Supermarkets:Mass-market entry point with compressed margins and minimal service component.
Online retail holds the dominant share, while salons are climbing the fastest as professional skincare channels deepen beauty-from-within integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in beauty supplements tilt toward net-importing advanced economies with stringent regulatory gatekeeping, while manufacturing clusters concentrate where raw material access and formulation expertise intersect.
United States
Direct-to-consumer subscription platforms capture Millennial and Gen-Z cohorts through algorithmic personalization. FDA dietary supplement GMP enforcement elevates compliance costs for cross-border entrants. Los Angeles and New York anchor influencer-driven brand launches with social commerce integration.
China
Urban professionals in tier-one cities displace capsule formats with ready-to-drink beauty shots. SAMR streamlined health food import procedures lower barriers for collagen peptide formulations. Shanghai and Beijing concentrate professional skincare channel penetration where salon-medi-spa integration deepens.
South Korea
Precision fermentation startups scale bio-identical ceramide production at cost parity with marine sources. MFDS borderline classification scrutiny between cosmetics and foods elevates substantiation requirements. Seoul Capital Area anchors biotechnology-derived ingredient manufacturing with compressed agricultural-to-tank lead times.
Germany
Pharmacy channel placement demands pharmaceutical-grade manufacturer capabilities with ISO 22000 and GMP co-certification. EFSA tightening under EU Regulation 1924/2006 forces delisting of unsubstantiated polyphenol products. Berlin and Munich concentrate dermatological endpoint contract research organization capacity.
France
Medi-spa and salon channels demand certificate-of-analysis documentation for ingestible inventory under EFSA pressure. Botanical extract standardization costs strain adaptogenic ingredient suppliers with batch-to-batch polyphenol inconsistency. Paris anchors luxury positioning for beauty-from-within claims with clinical validation requirements.
Global Beauty Supplements Market Competitive Landscape
Concentration sits with pharmaceutical-grade manufacturers capable of ISO 22000 and GMP co-certification, while commodity formulators face margin compression from regulatory substantiation requirements. Direct-sales infrastructure and subscription-based personalization platforms represent distinct strategic archetypes with divergent customer acquisition economics. Competitive moves center on clinical trial investments for EFSA compliance and precision fermentation capacity expansion for biotechnology-derived ingredients.
Within the direct-sales archetype, Amway Corporation leverages its Asia-Pacific infrastructure to sustain premium positioning in collagen and botanical formulations. Nestlé Health Science anchors the clinically validated ingredients tier through pharmaceutical-grade substantiation capabilities. HUM Nutrition Inc. occupies a position within the subscription-based personalization vector that dominates online retail channel acquisition.
| Leading Market Players |
|---|
| Amway Corporation |
| Nestlé Health Science |
| Herbalife International of America, Inc. |
| Nu Skin Enterprises, Inc. |
| Meiji Holdings Co., Ltd. |
| Unilever PLC |
| HUM Nutrition Inc. |
| Gelita |
| Vital Proteins |
| Others |
Supply & Pricing Matrix
ISO 22000 and GMP co-certification requirements gate both supply qualification and price differentiation simultaneously, elevating facility investment thresholds that separate pharmaceutical-grade manufacturers from commodity formulators while compressing margins for unsubstantiated botanical suppliers.
Pricing Analysis
Professional channel buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the beauty supplements market. Pharmaceutical-grade collagen hydrolysate with dermatological clinical validation commands substantial premiums over commodity peptide formulations, while batch-to-batch polyphenol inconsistency in Indian and Chinese botanical suppliers intensifies cost compression in the adaptogenic tier. Subscription-based personalization platforms capture elevated willingness-to-pay from Millennial and Gen-Z cohorts, though cross-border e-commerce friction in EU member states elevates fulfillment costs that squeeze direct-to-consumer margins.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints elevate inbound logistics costs for marine collagen peptide shipments from North Atlantic and Southeast Asian fisheries. Supply concentrates in South Korea for precision fermentation-derived ceramides, China for hyaluronic acid precursors, and Germany for pharmaceutical-grade collagen hydrolysate. Wild-caught marine collagen faces input volatility from fishery quotas, while precision fermentation alternatives in Dutch and Korean biotechnology facilities decompress agricultural harvest cycle dependencies. Distribution runs through professional skincare channels in China and South Korea, direct-to-consumer platforms in the United States, and pharmacy networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global beauty supplements market sits in early-cycle expansion as male demographic penetration and precision fermentation technology adoption accelerate category normalization beyond female-skewed legacy positioning.
For Market Incumbents: Fortify clinical substantiation capabilities through dermatological endpoint contract research organization partnerships in Switzerland and Germany, locking in EFSA-compliant randomized controlled trial pipelines before tightening EU Regulation 1924/2006 enforcement delists unsubstantiated polyphenol competitors. Expand precision fermentation capacity in South Korea and the Netherlands to secure bio-identical ceramide and hyaluronic acid precursor supply at cost parity with marine and botanical sources. For New Entrants and Emerging Players: SAMR streamlined registration fast-tracks lower barriers for collagen peptide and hyaluronic acid formulations entering China's professional skincare channels, creating accessible entry points for scaled entrants with regulatory affairs capabilities. Target male hair-strengthening segments in urban China and the United States where professional channel presence remains underdeveloped relative to female-skewed positioning. Lead with ready-to-drink beauty shot formats displacing capsules among time-constrained urban professionals. For Investors and Strategic Acquirers: EFSA's forthcoming tightening of beauty-specific health claims under EU Regulation 1924/2006 reshapes the acquisition landscape toward pharmaceutical-grade manufacturers with ISO 22000 and GMP co-certification and existing dermatological clinical trial portfolios. Long-term viability favors vertically integrated players with captive precision fermentation capacity and subscription-based personalization platform infrastructure. Monitor SAMR registration approval velocity for imported health foods as the signal for China market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | EFSA-compliant randomized controlled trials separate pharmaceutical-grade suppliers from delisting risk in Germany and France. |
| Precision Fermentation Scale-Up | South Korean and Dutch biotechnology facilities compress agricultural-to-tank lead times for ceramide and hyaluronic acid precursors. |
| Subscription Platform Development | Algorithmic skin assessment and monthly regimen customization capture Millennial and Gen-Z cohorts in the United States and United Kingdom. |
| Male Channel Penetration | Hair-strengthening positioning in professional skincare channels normalizes beauty supplement adoption beyond female-skewed legacy markets. |
| SAMR Registration Fast-Track | Streamlined health food import procedures lower market entry barriers for collagen peptide formulations in Shanghai and Beijing. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs directors at pharmaceutical-grade manufacturers, dermatological clinical trial principal investigators, subscription platform chief technology officers, and professional skincare channel procurement managers, then refined through secondary validation against FDA dietary supplement enforcement actions, EFSA health claims substantiation databases, SAMR health food registration filings, and South Korean MFDS borderline classification rulings. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring.
Variance decomposition across product type, application, consumer demographic, and distribution channel dimensions drove analytical framework construction throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and regulatory inflection timing. Forecast inputs incorporated precision fermentation capacity expansion timelines, EFSA enforcement phase-in assumptions, and SAMR registration approval velocity patterns.
Underlying assumptions cover EFSA claim substantiation compliance rates, SAMR import pathway stability, and marine collagen supply elasticity from North Atlantic fisheries, with deviation risk concentrated in regulatory enforcement timing and biotechnology scale-up execution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Medicinal Mushroom Powder Market