
 Glucosamine Market | 2026-2036
Glucosamine Market Size, Share, and Industry Trends Forecast 2026-2036
Glucosamine Market Outlook
Project finance and asset-light contract manufacturing is reshaping competitive entry in glucosamine production, lowering capital barriers for mid-scale fermentation and extraction operations. Cargill Incorporated leverages its integrated agricultural supply chain to secure consistent chitin feedstock for glucosamine derivatives. TSI Group Ltd. anchors its position through vertical control over quality-certified glucosamine sulfate production for pharmaceutical-grade applications. Nutramax Laboratories, Inc. differentiates via specialized veterinary formulations that command premium positioning in pet health channels.
Glucosamine refers to an amino sugar compound, typically C6H13NO5, derived from crustacean shell chitin or produced through microbial fermentation, functioning primarily as a cartilage synthesis precursor in joint health therapeutics and supplements. The compound serves industrial and commercial purposes across human nutraceuticals, veterinary care, and functional food fortification where chondroprotective claims require substantiated bioactive content. Glucosamine Sulfate dominates product type revenue due to superior clinical validation and European pharmacopoeia acceptance, while N-Acetyl Glucosamine represents the fastest-growing variant driven by cosmetic and gut barrier research applications. Dietary Supplements anchor application volume through direct-to-consumer channels, though Pharmaceuticals capture concentrated margin pools where prescription-grade certification commands price premiums.
The FDA enforces cGMP standards for dietary supplement glucosamine sourcing and labeling, while the EPA regulates crustacean processing waste streams that supply chitin feedstock, and ISO certification frameworks govern international ingredient consistency for cross-border pharmaceutical supply. These regulatory layers elevate compliance costs for new entrants but protect established producers with validated quality systems. Stakeholders must monitor evolving EFSA health claim evaluations and emerging fermentation-derived glucosamine pathways that could decouple production from marine resource constraints.
Market Dynamics
Fermentation-derived glucosamine pathways are decoupling production from marine resource constraints, reshaping feedstock economics and supplier geography across the value chain. This biotechnology shift is redrawing competitive boundaries between crustacean-extraction incumbents and microbial-production entrants.
Growth Catalysts
- EFSA Health Claim Pathways:The European Food Safety Authority's ongoing evaluations of joint health substantiation are creating regulatory clarity for glucosamine-containing functional foods, expanding permissible marketing claims beyond supplement categories.
- Veterinary Wellness Expansion:Pet owners in the United States are integrating chondroprotective supplements into preventive care regimens for aging companion animals, sustaining demand for species-specific formulations.
- Fermentation Infrastructure:Bioprocessing advances are enabling industrial-scale microbial production of glucosamine from corn-derived glucose, reducing dependency on seasonal crustacean harvesting cycles.
Market Restraints
- Chitin Supply Concentration:Coastal processing facilities in Southeast Asia dominate raw material aggregation, exposing glucosamine sulfate producers to climate-related supply disruptions and logistics bottlenecks.
- FDA cGMP Compliance Burden:The Food and Drug Administration's current good manufacturing practice requirements for dietary supplements impose substantial validation costs on small-scale fermentation entrants seeking quality certification.
- Vegetarian Substitute Competition:Methylsulfonylmethane and undenatured collagen type II are gaining traction among consumers seeking non-shellfish joint health alternatives, pressuring traditional glucosamine positioning.
Strategic Opportunities
- Cosmeceutical N-Acetyl Penetration:South Korean and Japanese skincare formulators are incorporating N-Acetyl Glucosamine for barrier repair and hydration claims, opening premium pricing tiers outside traditional joint health applications.
- Direct-to-Consumer Subscription Models:Specialized e-commerce platforms are capturing recurring revenue through personalized dosing protocols and automated replenishment for chronic joint management regimens.
- EU Green Deal Alignment:Fermentation-based production pathways qualify for sustainability-linked financing under European Union decarbonization frameworks, attracting ESG-mandated capital to capacity expansion projects.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:European Pharmacopoeia compliance for glucosamine sulfate requires 18-24 month validation cycles, delaying market entry for fermentation-derived alternatives seeking prescription-channel access.
- Cross-Border Ingredient Traceability:ISO 22000 and FSSC 22000 certification gaps between crustacean processors in Vietnam and finished goods manufacturers in Europe are creating audit complexity and documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucosamine Market |
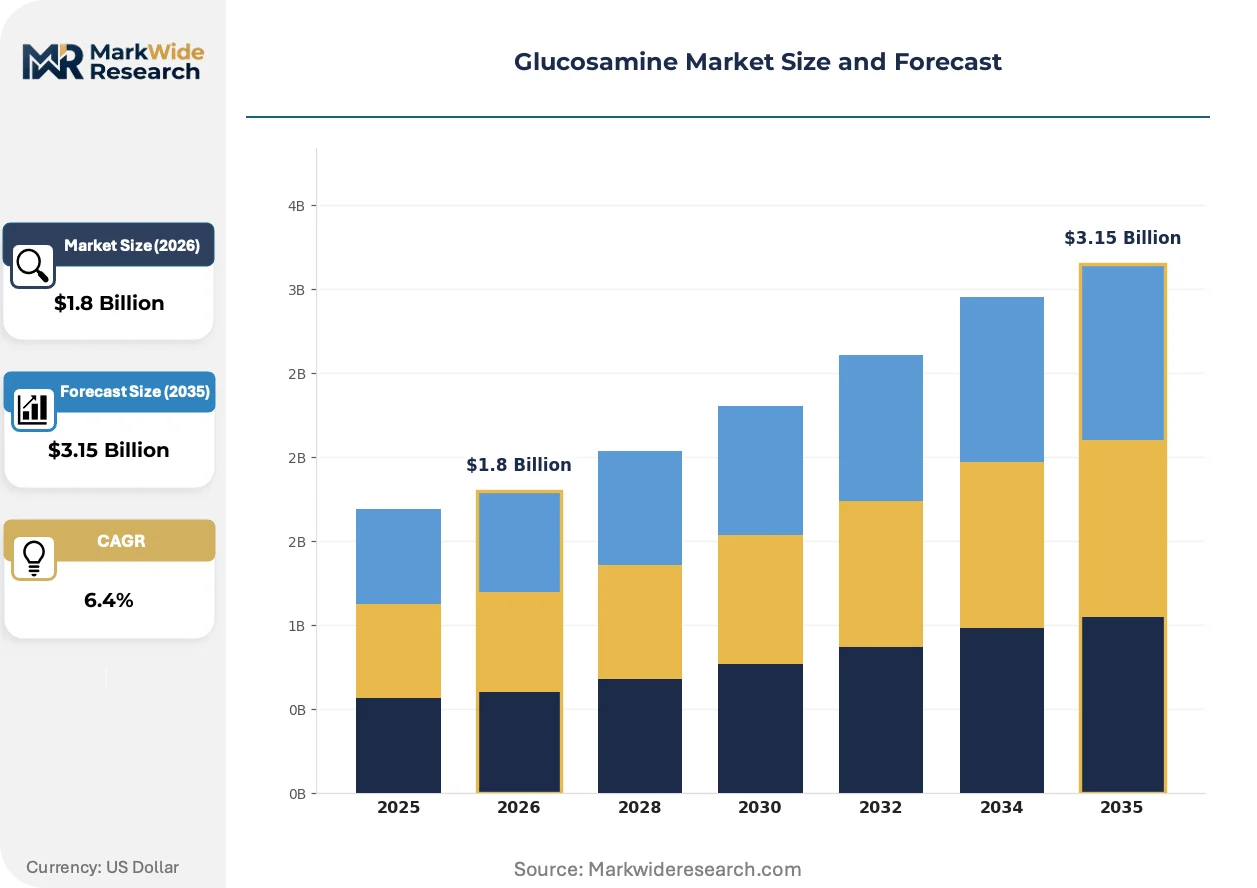
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucosamine Sulfate, Glucosamine Hydrochloride, N-Acetyl Glucosamine, Others Application: Dietary Supplements, Pharmaceuticals, Functional Foods, Others End User: Adults, Elderly, Athletes, Pets Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Cargill Incorporated, TSI Group Ltd., Amway Corporation, Koyo Chemical Co., Ltd., Nutramax Laboratories, Inc., Bio-gen Extracts Pvt. Ltd., Panvo Organics Pvt Ltd, Zhejiang Aoxing Biotechnology Co., Ltd., CELLMARK AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucosamine Market Strategic Shifts
Bioprocess automation and regulatory science convergence are compressing development cycles for novel glucosamine derivatives while expanding addressable indications beyond osteoarthritis management.
Continuous bioreactor systems equipped with real-time metabolite monitoring are digitizing fermentation control parameters, enabling precision adjustment of pH, dissolved oxygen, and nutrient feed rates. Mid-scale glucosamine producers in the Netherlands and Germany are adopting these platforms to achieve pharmaceutical-grade consistency without batch-to-batch variation. The technology is digitizing quality assurance workflows, reducing manual sampling and laboratory testing burdens while accelerating release timelines for export markets.
REACH registration requirements for chitin-derived intermediates are tightening substance documentation obligations across European supply chains, forcing importers to establish comprehensive dossiers on crustacean sourcing geography and processing chemistry. The regulation is elevating compliance costs for traders lacking backward visibility into Southeast Asian processor operations. Small-volume specialty glucosamine sulfate suppliers are responding by consolidating procurement through vertically integrated feedstock partnerships.
Practitioner-channel influence is reasserting itself as pharmacists and veterinary clinicians reclaim recommendation authority from algorithm-driven e-commerce platforms. Professional education programs sponsored by ingredient suppliers are rebuilding prescriber confidence in bioavailability distinctions between glucosamine salts. This behavioral recalibration is most pronounced in Germany and France, where pharmacy-led distribution maintains structural advantages over direct-to-consumer alternatives for chronic condition management.
Glucosamine Market Segmentation
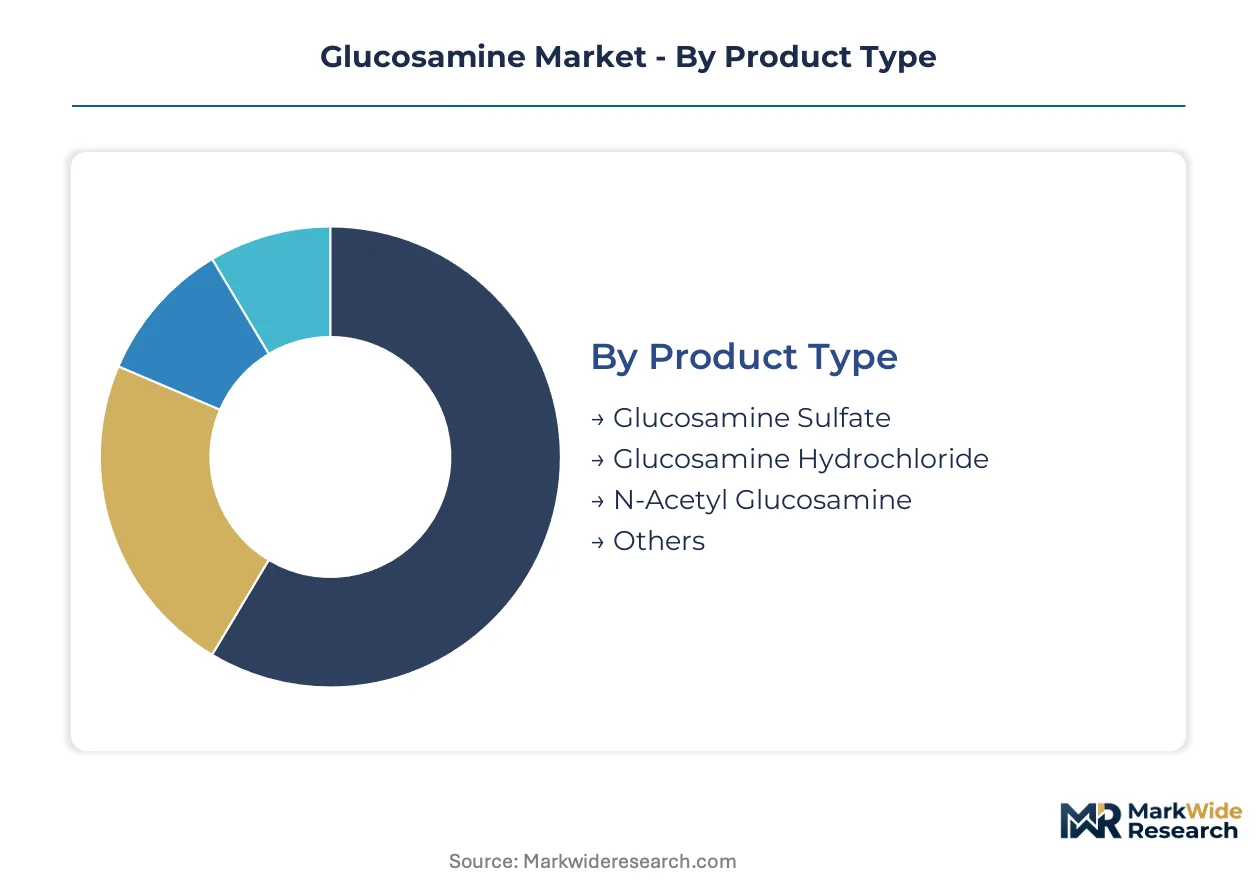
Segmentation in the glucosamine market reveals divergent growth mechanics across molecular variants, therapeutic applications, and species-specific demand pools. Each dimension carries distinct margin structures, certification requirements, and channel dependencies that reshape supplier priorities.
Product Type:
Mature clinical validation separates established salts from emerging derivatives, with fermentation economics now disrupting traditional extraction hierarchies.
- Glucosamine Sulfate:The stabilized salt form bound to potassium or sodium dominates prescription-grade applications through superior bioavailability documentation. European pharmacopoeia acceptance sustains its position in reimbursed osteoarthritis protocols across Germany and France.
- N-Acetyl Glucosamine:This acetylated derivative bypasses first-pass metabolism constraints, enabling dermal penetration for cosmeceutical formulations. South Korean skincare laboratories and Japanese functional food developers are expanding procurement volumes for barrier repair and gut microbiome applications.
- Glucosamine Hydrochloride:Higher purity specifications at lower molecular weight suit compressed tablet manufacturing for high-dose supplement regimens.
- Others:Specialty derivatives including glucosamine sulfate 2KCl and custom complex salts serve niche pharmaceutical compounding requirements.
Glucosamine Sulfate retains volume leadership; N-Acetyl Glucosamine holds the steepest expansion curve.
Application:
Channel economics and regulatory burden create tiered margin pools, with prescription certification commanding substantial price premiums over commodity supplement positioning.
- Dietary Supplements:Direct-to-consumer capsules, tablets, and powders constitute the volume anchor, distributed through Amazon, iHerb, and specialized longevity platforms. FDA cGMP compliance remains mandatory, though substantiation requirements stay below pharmaceutical thresholds.
- Pharmaceuticals:Prescription-grade glucosamine sulfate for osteoarthritis management requires EMA marketing authorization or national equivalent pathways. European reimbursement eligibility in Italy and Spain sustains concentrated margin capture for validated manufacturers.
- Functional Foods:Beverage fortification and fortified dairy applications in Japan leverage FOSHU regulatory frameworks for joint health claims.
- Others:Veterinary compounding and research-grade biochemical supply serve fragmented specialty demand.
Dietary Supplements anchor volume throughput; Pharmaceuticals concentrate margin extraction.
End User:
Demographic concentration and species-specific formulation requirements fragment demand across human and companion animal segments with divergent dosing protocols.
- Elderly:Sustained consumption for chronic osteoarthritis management in adults over 65 drives reimbursement-eligible prescription volumes in France and Japan. Knee and hip degeneration prevalence sustains long-tenure patient relationships with rheumatology specialists.
- Pets:Canine and feline chondroprotective formulations command premium positioning through veterinary clinic channels and Chewy.com subscription models. Aging Labrador and Golden Retriever demographics in the United States sustain species-specific tablet and liquid demand.
- Adults:Preventive supplementation among 35-55 year-olds concentrates in fitness-adjacent channels and corporate wellness programs.
- Athletes:Collagen-glucosamine combination products target CrossFit and endurance sports recovery segments through specialized retailers.
Elderly consumption retains volume leadership; Pet applications are climbing the fastest.
Distribution Channel:
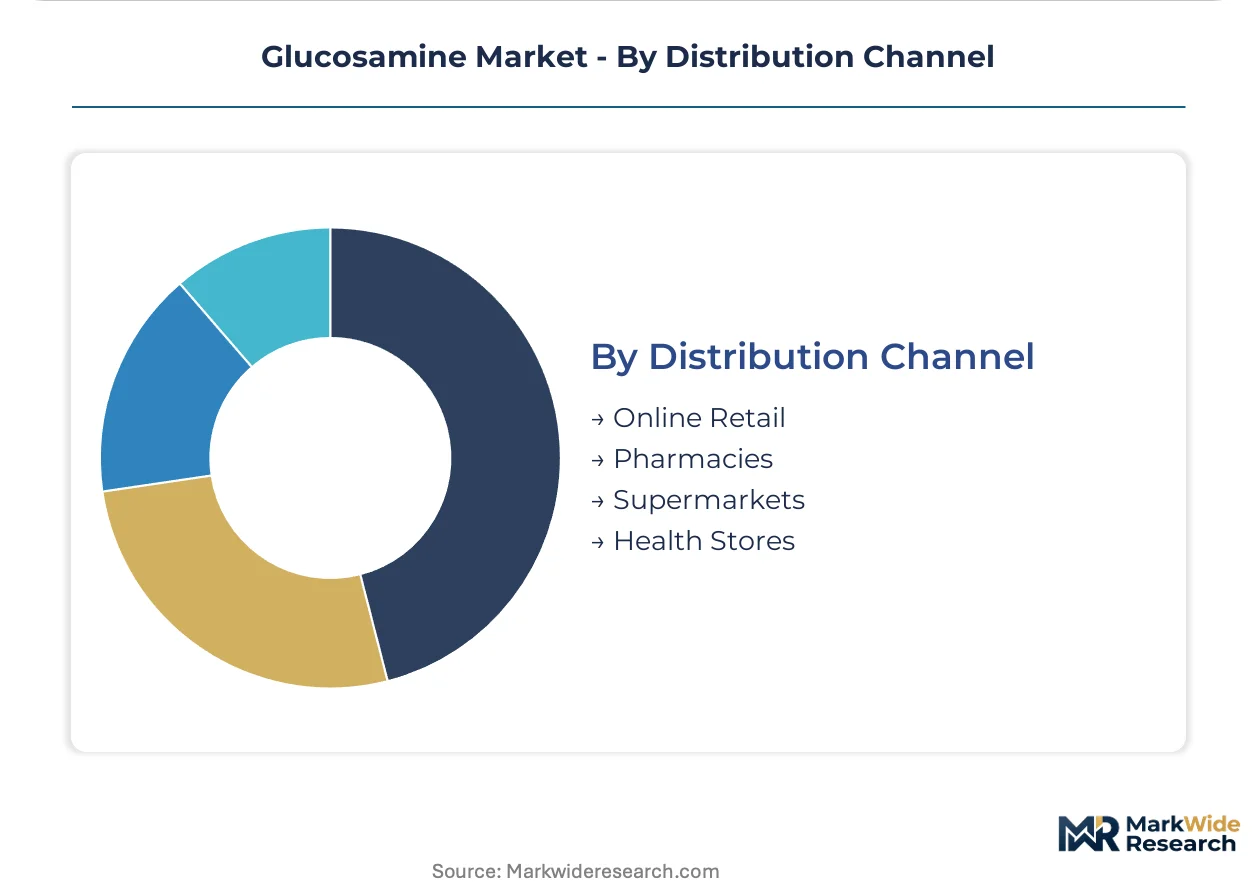
Channel control determines pricing power and customer data access, with digital platforms eroding traditional pharmacy dominance in routine replenishment scenarios.
- Online Retail:Amazon, iHerb, and brand-direct subscription platforms capture recurring revenue through auto-ship algorithms and personalized dosing protocols. Customer acquisition costs have stabilized as retention economics dominate unit economics.
- Pharmacies:German and French pharmacy networks maintain structural advantages for prescription-grade and pharmacist-recommended SKUs, with professional counseling reinforcing adherence.
- Supermarkets:Mass-market glucosamine in Costco, Walmart, and Carrefour serves price-sensitive, first-time purchasers through high-visibility endcap placement.
- Health Stores:GNC, Holland & Barrett, and regional cooperatives cater to ingredient-conscious consumers seeking non-GMO or fermentation-derived certifications.
Online Retail is gaining share fastest; Pharmacies retain prescription-channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Joint health supplement buyers cluster in aging populations and companion animal households, with procurement patterns tracking veterinary channel density and pharmacy reimbursement structures across five national markets.
United States
Pet wellness expenditures and Medicare-eligible osteoarthritis patients drive sustained glucosamine consumption through Chewy.com subscriptions and Walgreens pharmacy networks. The FDA's dietary supplement cGMP regulations enforce quality documentation for crustacean-derived ingredients entering interstate commerce. Nutramax Laboratories anchors veterinary formulation production in Lancaster, South Carolina, serving clinic channels nationwide.
Germany
Pharmacy-led distribution for reimbursed glucosamine sulfate prescriptions sustains volume concentration among adults over 65 with knee osteoarthritis. The BfArM maintains strict marketing authorization pathways for prescription-grade joint therapeutics. Heidelberg and Mannheim host fermentation technology clusters where microbial glucosamine production is scaling pharmaceutical-grade capacity.
Japan
FOSHU regulatory frameworks enable functional food fortification claims, expanding glucosamine inclusion in beverage and dairy applications beyond supplement capsules. The Ministry of Health, Labour and Welfare oversees substantiation requirements for joint health labeling. Kobe and Osaka house chitin processing facilities serving domestic nutraceutical manufacturers with consistent crustacean feedstock supply.
South Korea
Cosmeceutical demand for N-Acetyl Glucosamine in barrier-repair skincare formulations is accelerating procurement from fermentation suppliers. The MFDS regulates cosmetic ingredient safety assessments for dermal application claims. Seoul metropolitan area biotech clusters are commercializing microbial production pathways reducing dependency on shellfish extraction.
Netherlands
ESG-mandated institutional capital is financing fermentation-based glucosamine capacity under EU Green Deal sustainability-linked frameworks. The NVWA enforces novel food regulations for microbial-derived ingredients seeking market authorization. Rotterdam bioprocessing facilities are adopting continuous bioreactor systems for pharmaceutical-grade consistency in export markets.
Glucosamine Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered margin pools, creating a bifurcated structure where scale-driven agricultural conglomerates face biotechnology-focused fermentation entrants. The vendor base separates into crustacean-extraction incumbents with coastal feedstock integration, microbial-production specialists with bioprocessing IP, and veterinary-formulation developers with clinic-channel relationships. Dominant competitive moves include backward integration into chitin sourcing and strategic partnerships with bioreactor technology licensors.
Within the agricultural supply chain tier, Cargill Incorporated exemplifies feedstock-integrated positioning through its grain and processing assets. TSI Group Ltd. and Nutramax Laboratories, Inc. occupy specialist positions, with the former representing pharmaceutical-grade certification capabilities and the latter anchoring veterinary application expertise through clinic-channel formulations.
| Leading Market Players |
|---|
| Cargill Incorporated |
| TSI Group Ltd. |
| Amway Corporation |
| Koyo Chemical Co., Ltd. |
| Nutramax Laboratories, Inc. |
| Bio-gen Extracts Pvt. Ltd. |
| Panvo Organics Pvt Ltd |
| Zhejiang Aoxing Biotechnology Co., Ltd. |
| CELLMARK AB |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility directly shapes margin allocation between crustacean-extraction incumbents and fermentation-derived entrants, compressing price spreads for pharmaceutical-grade glucosamine sulfate while amplifying premiums for ESG-certified microbial production.
Pricing Analysis
Cost-plus contracts indexed to chitin feedstock spot prices dominate long-term supply agreements between Southeast Asian processors and European pharmaceutical manufacturers. Three-tier pricing structure across pharmaceutical-grade, dietary supplement, and commodity feedstock levels separates certification-burdened prescription channels from mass-market capsules. Pricing pressure stems from fermentation-derived volume expansion in the Netherlands and Germany. Mass-market supplement buyers exhibit highest price sensitivity; veterinary clinic channels show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with TSI Group Ltd., Nutramax Laboratories, and Zhejiang Aoxing Biotechnology, which collectively anchor pharmaceutical-grade and veterinary formulation capacity. Geographic supply concentrates in Vietnam, China, and India for crustacean-derived chitin; the Netherlands and Germany for fermentation-based production. Raw material dependencies include crustacean shell waste, corn-derived glucose, and potassium chloride for salt stabilization. Single-source vulnerability runs through Southeast Asian coastal processing facilities exposed to climate disruption. Distribution runs through pharmacy networks in Germany and France, direct-to-consumer platforms in the United States, and veterinary clinic channels for companion animal formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery driven by fermentation technology maturation, which is compressing production costs and expanding addressable supply beyond marine resource constraints.
For Market Incumbents: Build regulatory certification moats by accelerating European Pharmacopoeia compliance timelines for fermentation-derived alternatives before microbial entrants achieve prescription-channel access. Deepen backward integration into Vietnamese and Indonesian chitin processing to secure feedstock priority during harvest disruptions. Counter methylsulfonylmethane substitution threats through practitioner education on bioavailability differentials. For New Entrants and Emerging Players: Pursue cosmeceutical N-Acetyl Glucosamine white space in South Korean and Japanese skincare supply chains, where barrier-repair claims command premium positioning outside saturated joint health channels. Target veterinary subscription models through Chewy.com and clinic-direct formulations for aging canine demographics. Deploy sustainability-linked financing narratives to attract ESG-mandated capital for fermentation capacity buildout. For Investors and Strategic Acquirers: Fermentation-technology specialists with pharmaceutical-grade bioreactor infrastructure represent the most defensible acquisition archetype for long-term positioning across the analysis window. Monitor EFSA joint health claim authorization timelines as the critical inflection signal for functional food market expansion beyond supplement categories. Track EPA crustacean waste stream enforcement intensity as a proxy for extraction-incumbent cost pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chitin Sourcing | Cargill's agricultural supply chain control secures consistent feedstock for sulfate production. |
| Fermentation Capacity Expansion | Netherlands bioprocessing facilities leverage EU Green Deal financing for microbial glucosamine scale-up. |
| Pharmaceutical-Grade Certification Investment | EMA marketing authorization pathways unlock reimbursed prescription volumes in Germany and France. |
| Veterinary Formulation Development | Species-specific tablets for aging Labradors capture recurring revenue through Chewy.com subscriptions. |
| Cosmeceutical N-Acetyl Penetration | South Korean skincare laboratories incorporate barrier-repair claims for premium pricing outside joint health. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation technology directors, veterinary formulation scientists, pharmaceutical procurement managers, and dietary supplement brand managers and refined through secondary validation against FDA cGMP guidance documents, EFSA health claim evaluations, EPA crustacean processing regulations, and European Pharmacopoeia monographs. Bottom-up volume modeling triangulated with top-down market sizing across molecular variant, application, and species-specific demand segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application tier, end-user demographic, and distribution channel. CAGRs derived from elasticity-adjusted consumption trajectories incorporated fermentation cost curves, veterinary channel expansion rates, and cosmeceutical adoption patterns as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight rates, corn commodity prices, or ESG capital allocation would shift the trajectory for fermentation-derived volume penetration. Quarterly review of EPA enforcement actions, EFSA claim authorizations, and bioreactor capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Nootropic Products Market