
 Pet Skin and Coat Health Supplement Market | 2026-2036
Pet Skin and Coat Health Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Skin and Coat Health Supplement Market Insights
Premium clinical-grade formulation is rotating toward the center of competitive strategy as pet owners demand veterinarian-backed efficacy claims. Nestlé Purina PetCare leverages its therapeutic nutrition infrastructure to bridge over-the-counter and prescription-grade positioning. Mars Petcare anchors its portfolio through specialty retail partnerships that emphasize traceable omega-3 sourcing. Zoetis differentiates by integrating its pharmaceutical R&D pipeline into dermatological supplement development.
Pet skin and coat health supplements comprise orally administered nutritional formulations containing bioactive lipids, micronutrients, and botanical compounds, typically standardized to minimum concentrations of EPA/DHA or specific polyphenol extracts, designed to modulate epidermal barrier function and reduce inflammatory skin responses in companion animals. Fatty acid supplements occupy the largest revenue pool due to established veterinary endorsement and measurable biomarker outcomes, while probiotics represent the fastest-expanding category as gut-skin axis research deepens. Among end users, veterinary clinics capture the highest margin transactions through prescription-tier dispensing, though online retailers are eroding this advantage with telehealth-integrated subscription models.
FDA Center for Veterinary Medicine oversight governs ingredient safety and label claims in the United States, while the EU's Feed Additives Regulation and EFSA novel food assessments constrain botanical ingredient introductions in European markets. The EU Green Deal's deforestation-free supply chain mandates are forcing reformulation of fish oil and plant extract sourcing across multinational portfolios. Stakeholders must weigh captive ingredient sourcing against flexible supplier networks as regulatory transparency requirements intensify and consumer traceability expectations harden.
Market Dynamics
Veterinary telehealth platforms are compressing the traditional clinic dispensing channel, redirecting prescription-grade supplement volumes toward direct-to-consumer subscription models that bypass established veterinary practice economics.
Growth Catalysts
- EPA/DHA biomarker standardization:Measurable fatty acid outcomes in serum lipid panels are securing veterinary endorsement and justifying premium pricing tiers in clinical settings.
- EU Green Deal deforestation mandates:Supply chain transparency requirements are accelerating certified sustainable sourcing programs for fish oil and botanical extracts.
- Gut-skin axis research:Microbiome sequencing advances are validating probiotic formulations for atopic dermatitis, expanding addressable indications beyond conventional lipid therapy.
Market Restraints
- Wild-caught fish oil concentration:Peruvian anchovy quota volatility and El Niño disruptions expose formulation pipelines to raw material cost spikes.
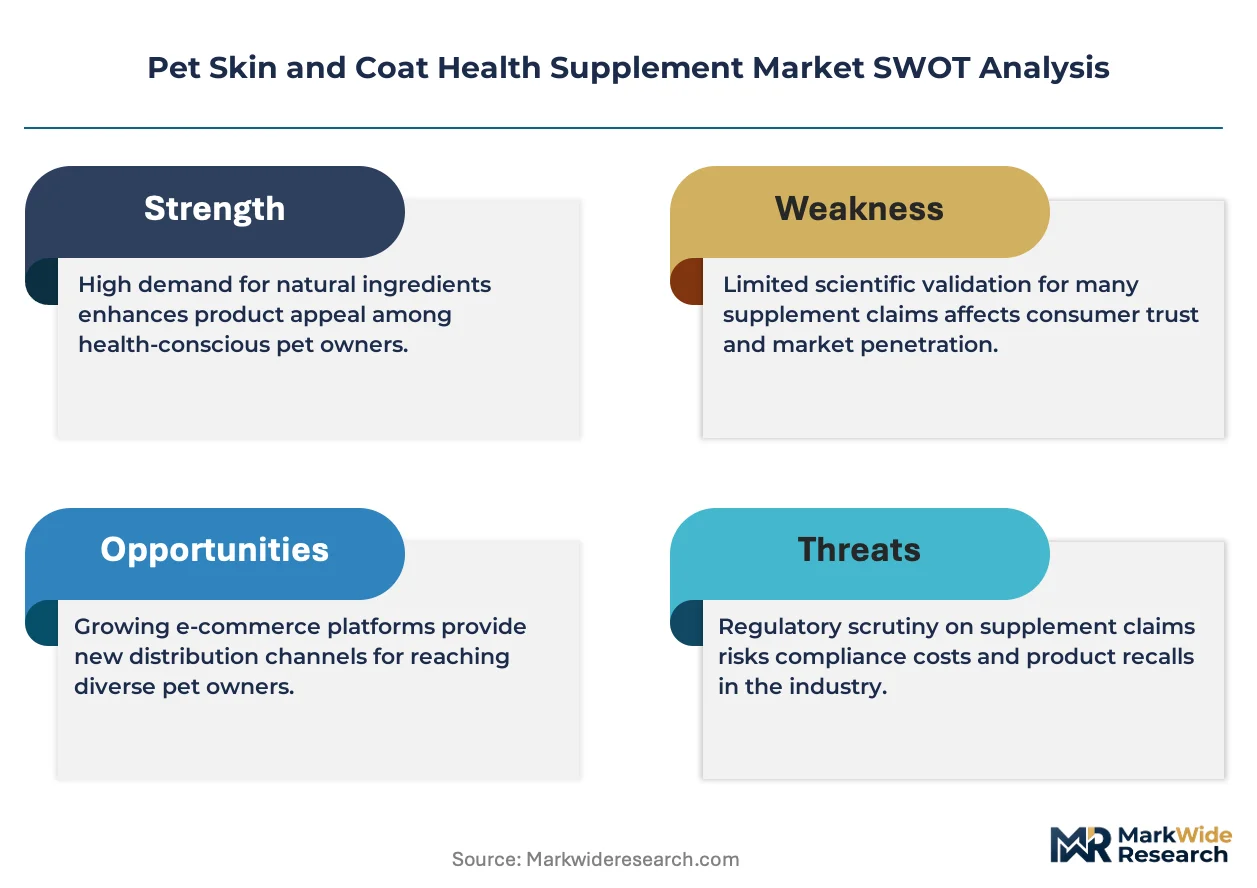
- EFSA novel food assessments:Botanical ingredient approvals in Europe face 18-24 month evaluation timelines, delaying product launches relative to US market entry.
- Plant-based omega-3 conversion inefficiency:ALA-to-EPA/DHA bioconversion rates in canines limit algae and flaxseed efficacy compared to marine sources.
Strategic Opportunities
- Veterinary clinic underpenetration in India:Rising pet ownership in Tier-1 cities and expanding specialty retail networks create first-mover positioning for clinically positioned brands.
- Telehealth-integrated subscription dispensing:Remote consultation platforms are capturing recurring revenue streams previously locked within physical practice walls.
- CSRD supply chain disclosure rules:Mandatory EU sustainability reporting is creating competitive differentiation for vertically integrated producers with traceable ingredient sourcing.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulation expertise bridging pharmaceutical R&D and companion animal dermatology commands premium compensation and limits scaling.
- Multi-jurisdiction label compliance:Divergent FDA Center for Veterinary Medicine and EFSA claim standards force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Skin and Coat Health Supplement Market |
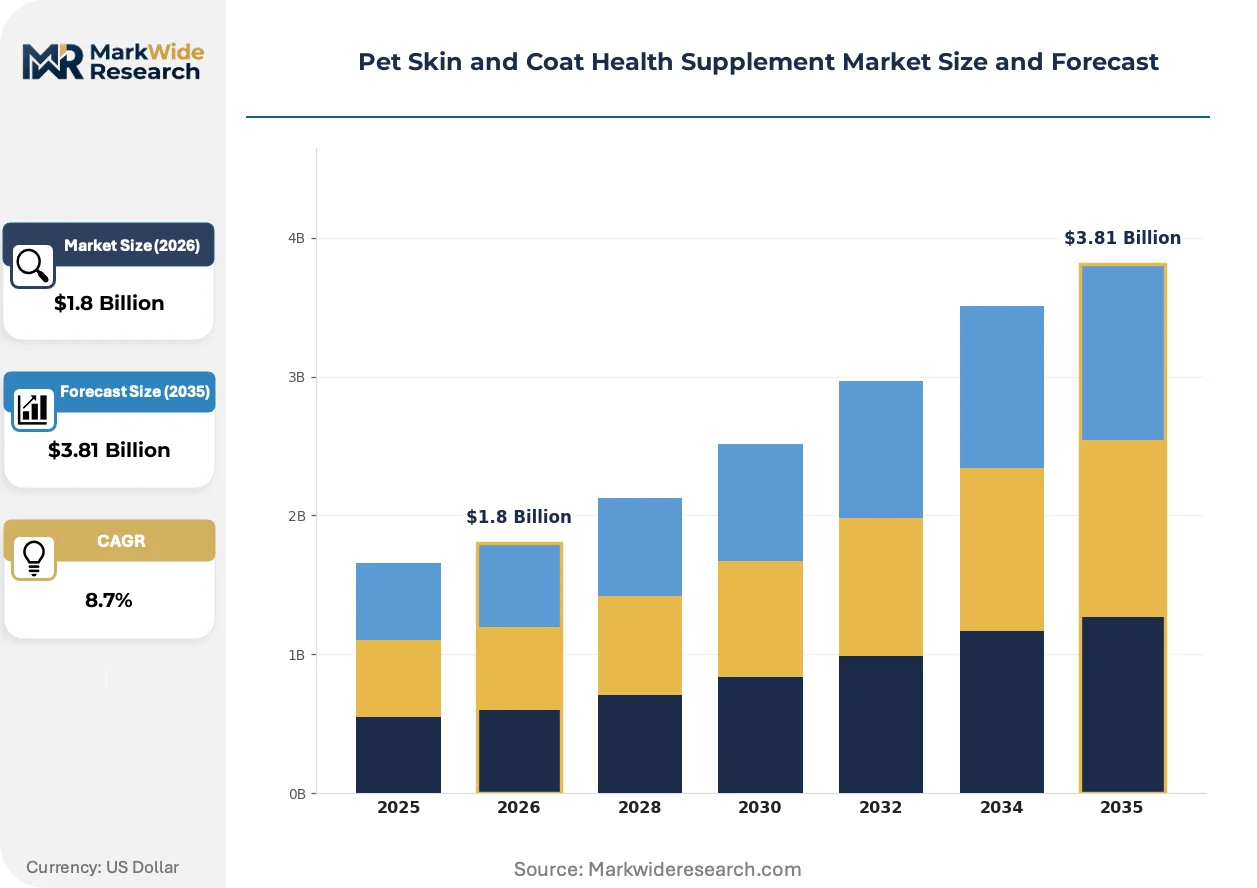
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Acid Supplements, Multivitamins, Herbal Extracts, Probiotics, Amino Acids Application: Flea Allergy Dermatitis, Seborrhea, Hot Spots, Dandruff, Dry Skin End User: Veterinary Clinics, Pet Owners, Animal Hospitals, Grooming Centers, Specialty Retailers Distribution Channel: Pet Specialty Stores, Online Retailers, Veterinary Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill's Pet Nutrition, Zoetis, Virbac, Vetoquinol, Nutramax Laboratories, H&H Group, Swedencare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Skin and Coat Health Supplement Market Trends and Innovations
Biotechnology-enabled ingredient production and regulatory transparency mandates are converging to reshape sourcing strategies and competitive positioning across the value chain.
Precision fermentation-derived EPA/DHA is displacing wild-caught marine oils in premium formulations. Biotechnology firms in the Netherlands and California are scaling algal and microbial lipid production. Nestlé Purina and Mars Petcare are trialing these sources in limited veterinary channels. This displacement is compressing traditional fish oil procurement contracts and rewriting supplier qualification protocols.
REACH substance registration requirements are tightening botanical extract documentation for European markets. ECHA compliance deadlines are forcing reformulation of polyphenol and terpene-based supplements. Mid-tier producers without dedicated regulatory affairs capacity are exiting or partnering with larger entities. German and French markets show the most pronounced supplier consolidation.
Subscription-based auto-replenishment is capturing recurring purchase occasions previously managed through clinic visits. Chewy and Amazon's veterinary storefronts are integrating telehealth consultations to validate prescription-tier dispensing. Millennial pet owners in US coastal metropolitan areas demonstrate highest adoption. This channel shift is eroding veterinary practice revenue and triggering defensive dispensing platform investments.
Pet Skin and Coat Health Supplement Market Segmentation
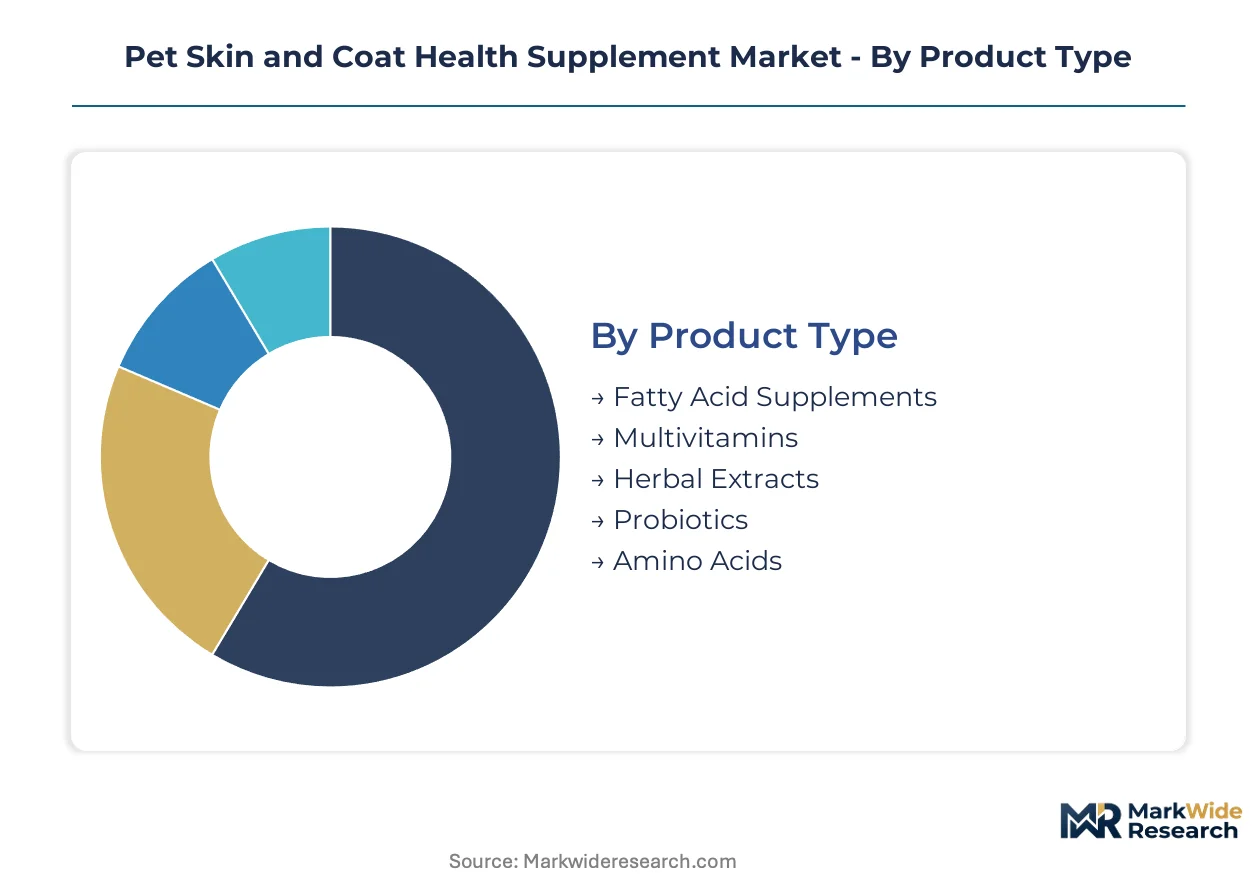
Segmentation in the pet skin and coat health supplement market reveals distinct channel economics and clinical positioning strategies. Veterinary endorsement tiers and sourcing transparency requirements create divergent margin structures across product categories.
Product Type:
Fatty acid formulations flow predominantly through veterinary pharmacies and specialty retail, while probiotics and herbal extracts concentrate in direct-to-consumer channels.
- Fatty Acid Supplements:Formulations standardized to minimum EPA/DHA concentrations modulate epidermal barrier function through lipid membrane incorporation. Demand concentrates in US specialty retail and veterinary clinics where serum biomarker validation justifies premium positioning against wild-caught fish oil supply volatility.
- Probiotics:Live microbial formulations targeting the gut-skin axis leverage microbiome sequencing advances for atopic dermatitis indications. Expansion concentrates in telehealth-integrated subscription models as FDA Center for Veterinary Medicine oversight creates compliance barriers for direct import competitors.
- Multivitamins:Broad-spectrum micronutrient blends addressing keratinization disorders occupy mass-market shelves in supermarkets and pet specialty stores.
- Herbal Extracts:Polyphenol and terpene-based botanicals face EFSA novel food assessment timelines that delay European launches relative to US market entry.
- Amino Acids:Keratin precursor formulations for coat density target grooming center dispensing and show circuit channels.
Fatty acid supplements dominate installed base. Probiotics are where expansion concentrates.
Application:
Condition severity determines whether formulations route through prescription-tier veterinary channels or over-the-counter retail.
- Flea Allergy Dermatitis:Chronic inflammatory condition requiring long-term immune modulation drives recurring subscription purchases through Chewy and Amazon veterinary storefronts.
- Seborrhea:Keratinization disorder with secondary infection risk channels through veterinary clinic dispensing where diagnostic confirmation precedes supplement recommendation.
- Hot Spots:Acute pyotraumatic dermatitis generates episodic demand in pet specialty stores and online retailers with expedited shipping.
- Dandruff:Mild scaling conditions accessible to self-diagnosis concentrate in supermarket and mass retail channels with lower price elasticity.
- Dry Skin:Seasonal and environmental triggers create replenishment cycles captured by auto-replenishment platforms in coastal US metropolitan markets.
Flea allergy dermatitis applications dominate installed base. Hot spots represent the fastest-growing trajectory for impulse and emergency purchase channels.
End User:
Professional versus consumer decision-making splits the market between clinical validation requirements and convenience-driven purchasing.
- Veterinary Clinics:Prescription-tier dispensing captures highest-margin transactions through diagnostic-integrated recommendations, though telehealth platforms are compressing this channel's volume.
- Pet Owners:Direct purchasing concentrates in millennial demographics in US coastal cities, with subscription adoption eroding traditional clinic visit frequency.
- Animal Hospitals:Emergency and specialty referral centers dispense therapeutic nutrition during acute dermatological episodes.
- Grooming Centers:Visual coat assessment creates upsell opportunities for aesthetic-focused supplements in premium service packages.
- Specialty Retailers:Knowledgeable staff and traceable sourcing credentials attract sustainability-conscious consumers responding to EU Green Deal transparency mandates.
Veterinary clinics dominate installed base. Pet owner direct purchasing is where expansion concentrates.
Distribution Channel:
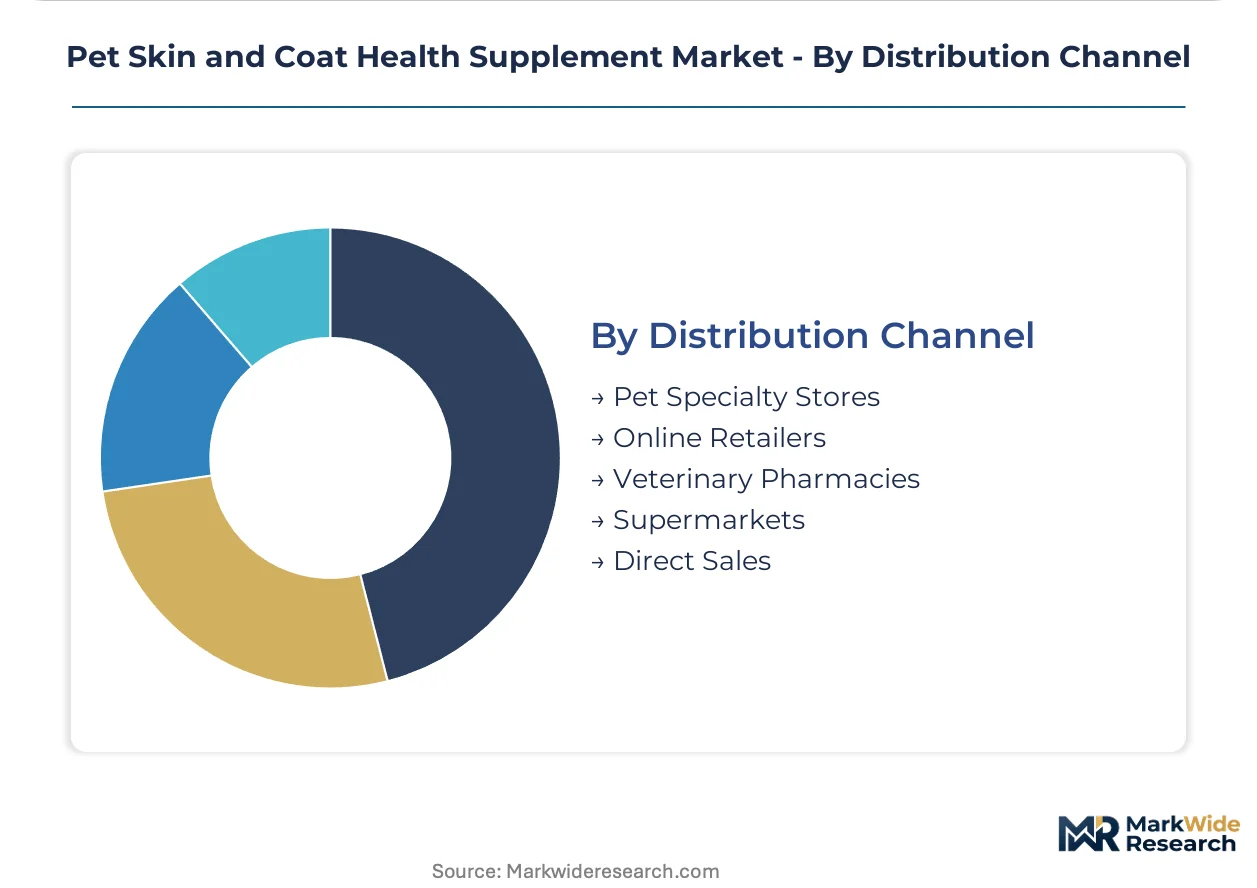
Channel selection determines regulatory exposure and margin capture, with veterinary pharmacies facing FDA Center for Veterinary Medicine oversight that supermarket and direct channels bypass.
- Pet Specialty Stores:Knowledge-based selling environment supports premium positioning for traceable omega-3 sourcing and certified sustainable ingredients.
- Online Retailers:Chewy and Amazon veterinary storefronts integrate telehealth consultations to validate prescription-tier dispensing, capturing recurring revenue through subscription auto-replenishment.
- Veterinary Pharmacies:Clinic-integrated dispensing maintains highest margin structure but faces volume pressure from remote consultation platforms.
- Supermarkets:Mass-market placement for multivitamins and basic fatty acid formulations with lower concentration specifications.
- Direct Sales:Manufacturer-controlled channels bypass retail margin capture for clinically positioned brands with established veterinary endorsement.
Pet specialty stores dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in omega-3 raw materials concentrate formulation capacity in import-dependent markets while export-oriented producers capture upstream margins. The United States runs substantial fish oil deficits against Peruvian and Norwegian suppliers. European markets face deforestation compliance costs that reshape sourcing networks.
United States
Specialty pet retail expansion in coastal metropolitan areas drives premium supplement absorption. FDA Center for Veterinary Medicine oversight governs label claims and ingredient safety documentation. Telehealth-integrated subscription platforms in California and New York erode traditional veterinary clinic dispensing volumes.
Germany
REACH substance registration deadlines force botanical extract reformulation across polyphenol-based supplements. ECHA compliance requirements accelerate supplier consolidation among mid-tier producers. Berlin and Munich host regulatory affairs clusters serving EU-wide market access strategies.
China
Precision fermentation capacity for algal EPA/DHA scales rapidly in Yangtze River Delta biotech corridors. NMPA and SAMR dual oversight governs novel ingredient introductions and cross-border e-commerce claims. Shanghai and Suzhou concentrate contract manufacturing for export-oriented brands.
United Kingdom
Post-Brexit divergence from EFSA assessments creates parallel approval pathways for botanical ingredients. Veterinary telehealth adoption in London and Southeast England redirects prescription-tier volumes toward direct channels. Manchester and Leeds specialty retail networks emphasize traceable omega-3 sourcing credentials.
India
Rising pet ownership in Mumbai and Delhi Tier-1 corridors creates first-mover positioning for clinically positioned brands. FSSAI and CDSCO joint oversight governs import registration and veterinary pharmaceutical claims. Bangalore and Hyderabad telehealth platforms trial subscription dispensing models adapted from US precedents.
Pet Skin and Coat Health Supplement Market Competitive Landscape
Listed leaders compete with private specialists across formulation sophistication and channel access dimensions. The market structures around three tiers: multinational consumer goods conglomerates with therapeutic nutrition infrastructure, pharmaceutical-derived animal health divisions with R&D pipelines, and independent specialists with concentrated dermatological positioning. Consolidation pressure intensifies as regulatory compliance costs escalate and raw material traceability requirements harden. Capacity expansion in precision fermentation and strategic partnerships with biotechnology suppliers represent dominant competitive vectors.
Within the pharmaceutical-derived tier, Zoetis and Virbac exemplify R&D-anchored positioning that bridges prescription and over-the-counter dispensing. Nestlé Purina PetCare occupies the consumer goods conglomerate archetype with therapeutic nutrition infrastructure spanning clinic and retail channels. These three entities represent divergent strategic bets on whether clinical validation or scale economics will capture margin in an increasingly regulated environment.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| Zoetis |
| Virbac |
| Vetoquinol |
| Nutramax Laboratories |
| H&H Group |
| Swedencare |
| Others |
Pricing and Supply Chain Analysis
Peruvian anchovy quota volatility and El Niño disruptions concentrate formulation cost leverage among marine oil processors with multi-year supply contracts. This scale concentration creates price floors for EPA/DHA standardization while compressing margins for mid-tier brands without captive sourcing.
Pricing Analysis
Veterinary clinic buyers anchor subscription pricing through diagnostic-integrated dispensing that justifies premium serum biomarker validation. Three-tier pricing structure across prescription-grade, veterinary-endorsed retail, and mass-market economy levels separates clinical validation tiers. Pricing pressure stems from telehealth-integrated platforms eroding traditional clinic markups. Millennial pet owners in coastal US metropolitan areas demonstrate lowest price sensitivity for traceable omega-3 sourcing credentials.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints disrupt algal EPA/DHA fermentation shipments from Yangtze River Delta biotech corridors. Supply concentrates in Peru, Norway, and China for wild-caught and precision-fermented marine lipids. Formulation pipelines draw from Peruvian anchovy fisheries, algal fermentation bioreactors, and flaxseed agricultural networks. Single-source vulnerability runs through Peruvian anchovy quota allocations. Distribution runs through veterinary pharmacy networks, pet specialty retail, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation biotechnology and EU Green Deal deforestation mandates are disrupting ingredient economics faster than incumbent reformulation cycles can absorb. Veterinary telehealth platforms are compressing traditional channel margins while creating new subscription revenue pools.
For Market Incumbents: Compound therapeutic nutrition infrastructure advantages by integrating pharmaceutical R&D pipelines into dermatological supplement development. Secure multi-year precision fermentation offtake agreements with Netherlands and California biotechnology suppliers before algal EPA/DHA capacity tightens. Defend clinic dispensing relationships through diagnostic-integrated recommendation platforms that telehealth competitors cannot replicate without veterinary network access.
For New Entrants and Emerging Players: Lead with gut-skin axis probiotic formulations targeting atopic dermatitis indications where microbiome sequencing advances create first-mover validation opportunities. White-space concentrates in Indian Tier-1 city veterinary clinic underpenetration and European botanical extract niches delayed by EFSA novel food timelines. Go-to-market should anchor through telehealth-integrated subscription models bypassing established veterinary practice economics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-enabled ingredient producers with REACH-compliant documentation and deforestation-free supply chain certification. Long-term viability hinges on vertical integration into precision fermentation capacity and regulatory affairs capacity spanning FDA Center for Veterinary Medicine and EFSA novel food pathways. Acquisition targets should demonstrate traceable omega-3 sourcing credentials and telehealth platform partnerships. Signal to watch: algal EPA/DHA production cost parity with wild-caught marine oils.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Algal and microbial EPA/DHA production displaces wild-caught fish oil dependency for Nestlé Purina and Mars Petcare formulations. |
| Telehealth Platform Integration | Chewy and Amazon veterinary storefronts capture recurring subscription revenue previously locked within physical clinic dispensing. |
| EU Green Deal Compliance Certification | Deforestation-free supply chain documentation creates competitive differentiation for German and French market access. |
| Veterinary Network Partnership | Diagnostic-integrated recommendation platforms defend clinic channel margins against direct-to-consumer erosion. |
| Botanical Extract Reformulation | REACH substance registration and ECHA compliance deadlines force polyphenol-based supplement supplier consolidation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, EFSA novel food assessments, and EU Green Deal supply chain documentation. Veterinary dermatologists, pet specialty retail category managers, and precision fermentation biotechnology executives provided operational perspective. Secondary validation drew from clinical trial registries, customs trade data for omega-3 raw materials, and SEC disclosures from publicly listed animal health entities. Bottom-up segment sizing triangulates against top-down market reconstruction.
Segmentation dimensions modeled span product type, application severity tier, end-user decision authority, and distribution channel regulatory exposure across the projection horizon. CAGRs derive from elasticity-adjusted volume trajectory analysis incorporating veterinary endorsement coefficient effects and telehealth adoption curves. Industry-specific inputs include serum biomarker validation rates, Peruvian anchovy quota volatility scenarios, and EFSA novel food assessment timeline distributions.
The analysis sits within stated boundaries; outcomes outside precision fermentation cost reduction trajectories and sustained veterinary telehealth platform growth would require recalibration. Forecasts reflect documented assumptions regarding regulatory approval timelines, raw material supply stability, and consumer willingness-to-pay for traceable sourcing credentials. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Diabetes Supplements Market