
 Bisglycinate Market | 2026-2036
Bisglycinate Market Size, Share, and Industry Trends Forecast 2026-2036
Bisglycinate Market Analytics
Subscription-based replenishment programs for mineral supplements is rebalancing how bisglycinate reaches chronic-condition consumers. Albion Laboratories leverages its TRAACS chelation technology to sustain premium positioning in practitioner channels. BASF SE anchors European pharmaceutical-grade supply through its Ludwigshafen manufacturing complex. Jost Chemical Co. specializes in USP-grade mineral chelates for compounding pharmacies.
Bisglycinate denotes a chelated mineral complex where glycine molecules bind a central metal ion through coordinate covalent bonds, typically achieving 80-90% solubility at intestinal pH for enhanced absorption without gastric irritation. Magnesium bisglycinate dominates product type volumes due to its anxiolytic and sleep-support positioning in nutraceuticals. Powder form leads manufacturing throughput for bulk ingredient supply to tablet and capsule finishers, while liquid bisglycinate posts the fastest growth in pediatric and geriatric compliance segments. Animal feed applications remain a margin-diluted volume channel constrained by commodity mineral pricing.
FDA's 21 CFR 101.93 health claim enforcement and EFSA's Article 13.1 general function claims process shape bisglycinate labeling and market access across North America and Europe. India's FSSAI fortification standards and CDSCO drug-approval pathways for prescription chelated minerals create additional compliance layers for multinational suppliers. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and JP standards to preempt batch-release bottlenecks.
Market Dynamics
Pharmaceutical formulators are pivoting toward chelated mineral complexes as EFSA's novel food substantiation requirements and FDA's 21 CFR 101.93 enforcement raise the bar for bioavailability claims, compressing demand for inorganic salt alternatives.
Growth Catalysts
- EFSA Article 13.1 pathways:General function health claims for magnesium bisglycinate's sleep and anxiety benefits are unlocking premium positioning in practitioner-dispensed supplements across Germany, France, and Italy.
- Precision nutrition clusters:Contract manufacturers in Baden-Württemberg serve pan-European nutraceutical brands with validated TRAACS chelation protocols, reducing batch-to-batch absorption variability.
- Pediatric compliance formats:Liquid bisglycinate solutions are capturing geriatric and pediatric segments where tablet swallowing creates adherence barriers in institutional care settings.
Market Restraints
- Glycine input volatility:Amino acid feedstock costs fluctuate with Chinese industrial glycine output and fertilizer-grade demand cycles, squeezing chelate producer margins.
- Pharmacopeial divergence:Non-harmonized monograph requirements between USP, EP, and JP standards create redundant stability testing and release bottlenecks for multinational suppliers.
- Commodity mineral substitution:Animal feed compounders default to zinc oxide and copper sulfate when chelate premiums exceed 40% of inorganic alternatives, capping volume upside in livestock applications.
Strategic Opportunities
- India's FSSAI fortification mandate:Edible oil and wheat flour mineral fortification standards are creating institutional procurement channels for pharmaceutical-grade bisglycinate suppliers.
- Subscription replenishment platforms:Direct-to-consumer auto-ship models for chronic-condition mineral supplementation are bypassing retail pharmacy markups and capturing lifetime value.
- CDSCO prescription pathways:Drug-approval frameworks for chelated minerals in therapeutic dosages are opening hospital formulary access distinct from nutraceutical positioning.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in coordination chemistry, regulatory dossier preparation, and scale-up manufacturing command premium compensation and extend hiring timelines.
- Validation protocol complexity:Demonstrating 80-90% intestinal solubility for TRAACS certification requires specialized dissolution apparatus and reference standard access that smaller compounders struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bisglycinate Market |
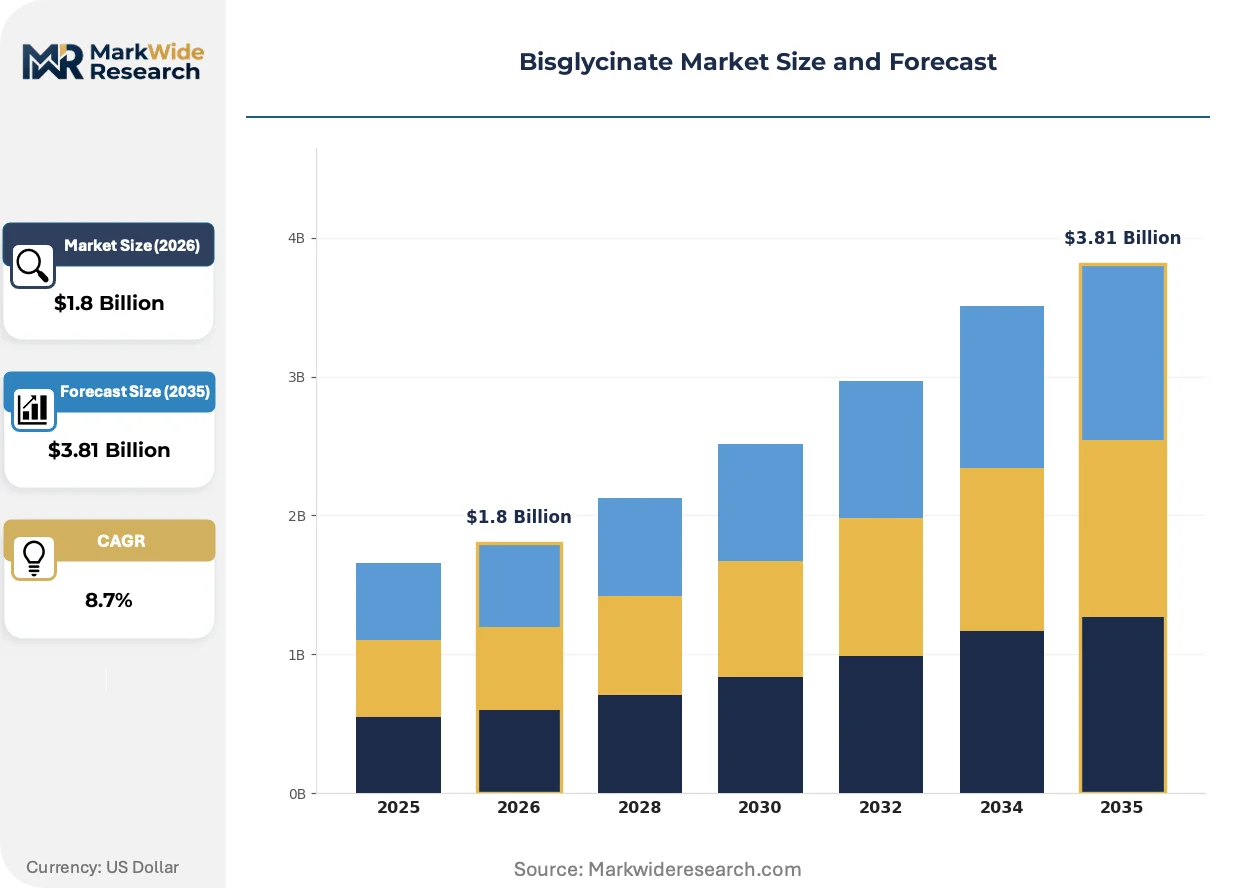
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Bisglycinate, Zinc Bisglycinate, Iron Bisglycinate, Calcium Bisglycinate End User: Pharmaceuticals, Nutraceuticals, Food Supplements, Animal Feed Form: Powder, Capsules, Tablets, Liquid Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Albion Laboratories, BASF SE, Jost Chemical Co., Novotech Nutraceuticals, Balchem Corporation, Solgar Inc., NOW Foods, Nature's Way, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bisglycinate Market Evolving Landscape
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times for chelated mineral production, while regulatory science investments separate validated suppliers from commodity traders.
Albion's TRAACS chelation verification technology is overtaking conventional complexometric titration methods for establishing mineral-amino acid binding ratios. Pharmaceutical manufacturers in Ludwigshafen and Mumbai are adopting it to preempt EFSA substantiation challenges. The technology is overtaking legacy approaches by embedding spectroscopic fingerprinting into routine QC, reducing third-party assay costs and accelerating batch release.
REACH registration requirements for glycine derivatives and metal chelates are forcing raw material suppliers to consolidate substance dossiers and share vertebrate study costs through consortia. The European Chemicals Agency's 2024 updated guidance on complex substances is triggering re-registration waves for existing bisglycinate entries. German and Swiss suppliers with pre-2018 grandfathered registrations are leveraging compliance continuity to capture share from newer market entrants facing full data cost burdens.
Practitioner channel consolidation is concentrating purchasing power among integrative medicine networks and functional medicine clinics that demand certificate-of-analysis transparency and lot-specific absorption data. These buyers are displacing retail pharmacy distribution for high-dose magnesium and zinc bisglycinate formulations. The shift is most visible in Australia's TGA-registered practitioner-only lines and US compounding pharmacy networks serving chronic fatigue and anxiety protocols.
Bisglycinate Market Segmentation
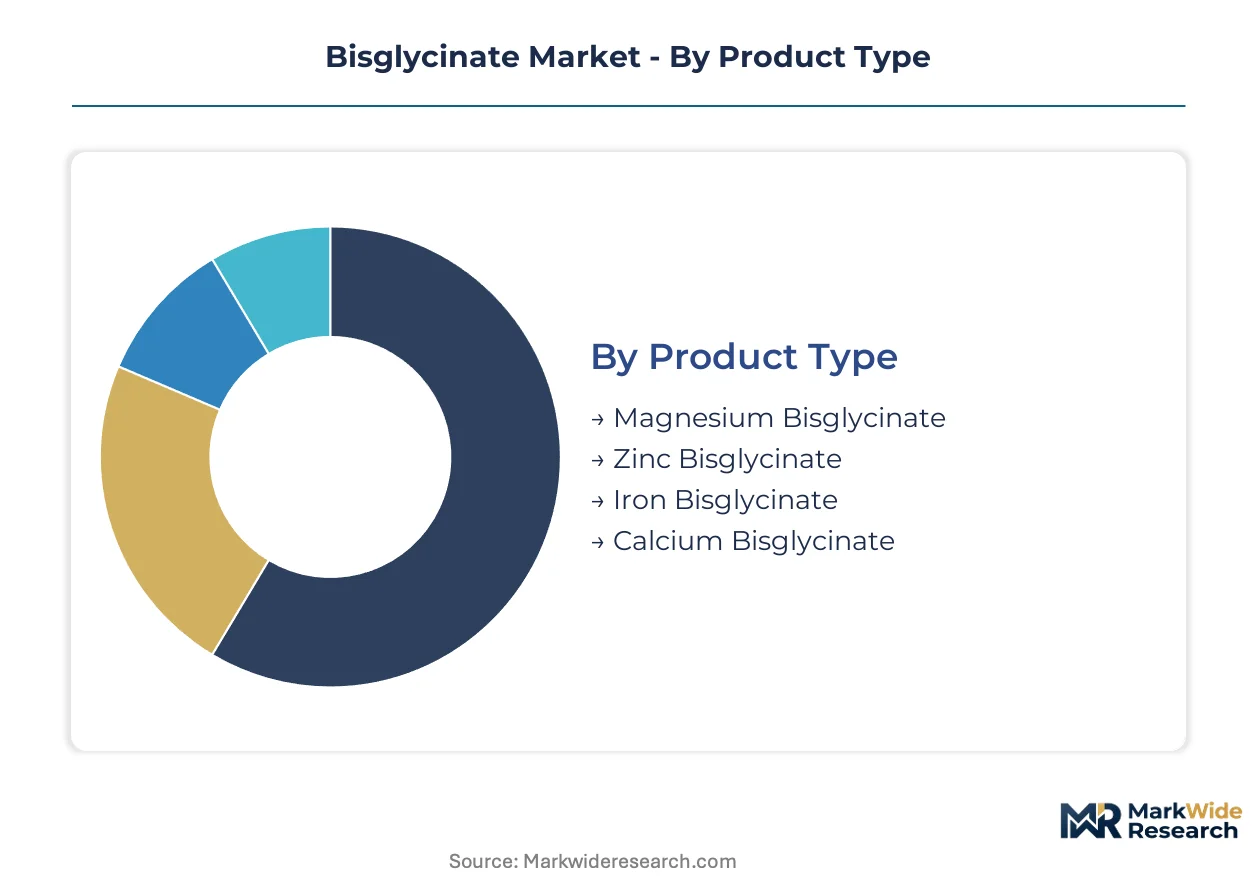
Bisglycinate segmentation reflects divergent bioavailability requirements across therapeutic versus wellness applications. Formulators select chelated mineral grades based on gastric tolerability thresholds, absorption kinetics, and finished dosage compliance needs.
Product Type:
Cost tier differentiation separates commodity mineral positioning from premium therapeutic formulations.
- Magnesium Bisglycinate:Chelated complex with two glycine molecules bound to magnesium via coordinate covalent bonds, achieving superior intestinal solubility at physiological pH. Demand concentrates in Germany's practitioner-dispensed sleep and anxiety protocols, where EFSA Article 13.1 substantiation requirements favor validated TRAACS chelation over generic mineral salts.
- Zinc Bisglycinate:Amino acid chelate delivering elemental zinc without the gastric irritation associated with zinc sulfate. India's FSSAI edible oil fortification mandates are driving institutional procurement volumes for immune-support positioning in mass-market consumer goods.
- Iron Bisglycinate:Hemoglobin-support chelate with reduced oxidative reactivity compared to ferrous salts. Pediatric anemia protocols in institutional care settings favor this form for tolerability.
- Calcium Bisglycinate:Bone health chelate competing against carbonate and citrate salts on absorption efficiency metrics. Osteoporosis prevention formulations in Japan's aging demographic show concentrated uptake.
Volume sits with magnesium variants; growth tilts toward zinc as fortification mandates expand across Asia-Pacific regulatory jurisdictions.
End User:
Application maturity determines specification stringency and margin capture potential.
- Pharmaceuticals:Prescription-grade bisglycinate meeting USP, EP, and JP pharmacopeial monographs for therapeutic mineral replacement. CDSCO drug-approval pathways in India and hospital formulary access in Germany concentrate demand for validated bioavailability documentation.
- Nutraceuticals:Practitioner-channel supplements leveraging TRAACS certification for premium positioning in integrative medicine networks. Australia's TGA-registered practitioner-only lines and US compounding pharmacies drive specification intensity.
- Food Supplements:Mass-market mineral fortification in functional foods and beverages. EFSA novel food substantiation requirements constrain health claim permissibility.
- Animal Feed:Livestock mineral supplementation constrained by commodity pricing pressure from zinc oxide and copper sulfate alternatives. Margin dilution limits chelate penetration when premiums exceed input cost thresholds.
Pharmaceutical specifications command highest margins; nutraceutical channels are expanding most quickly through subscription replenishment models.
Form:
Customer compliance barriers shape format selection across demographic segments.
- Powder:Bulk active pharmaceutical ingredient supplied to tablet and capsule finishers. Contract manufacturers in Baden-Württemberg process powder bisglycinate for pan-European nutraceutical brands with validated chelation protocols.
- Liquid:Pediatric and geriatric compliance solutions addressing tablet swallowing barriers in institutional care settings. Fastest-growing trajectory driven by aging population demographics and hospital formulary requirements.
- Capsules:Unit-dose convenience format for practitioner-dispensed protocols and direct-to-consumer subscription channels.
- Tablets:Mass-market solid dosage form competing on cost efficiency against capsules in retail pharmacy distribution.
Manufacturing throughput favors powder; steepest expansion trajectory belongs to liquid formats for compliance-critical patient populations.
Distribution Channel:
Procurement patterns fragment across institutional, retail, and direct-access pathways.
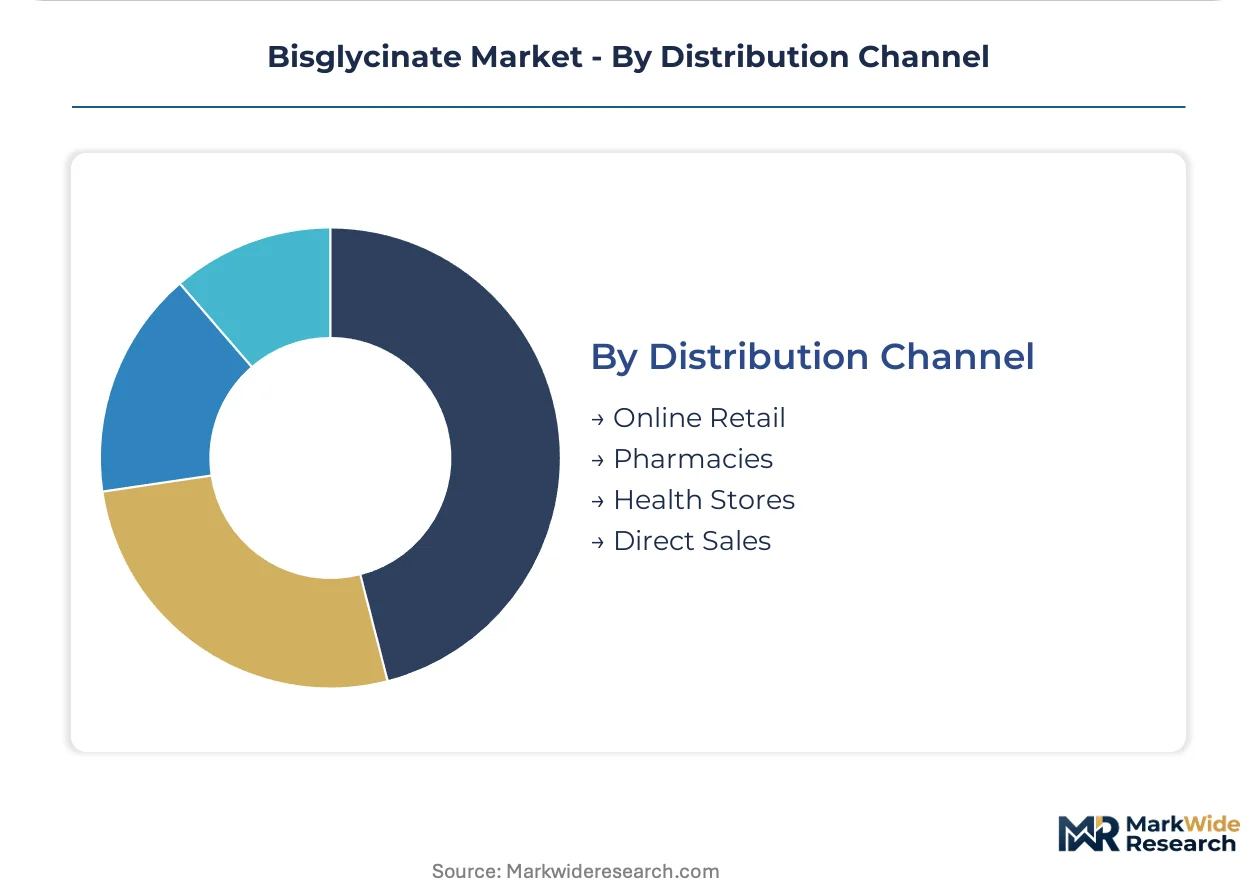
- Online Retail:Direct-to-consumer platforms capturing subscription-based replenishment for chronic-condition mineral supplementation. Auto-ship models bypass retail pharmacy markups and establish lifetime value capture.
- Pharmacies:Traditional dispensing channel for OTC and prescription bisglycinate formulations. Consolidating purchasing power among pharmacy chains pressures supplier margins.
- Health Stores:Specialty retail serving wellness-focused consumers with premium-positioned chelated mineral lines.
- Direct Sales:Practitioner-only distribution through integrative medicine networks demanding certificate-of-analysis transparency and lot-specific absorption data.
Pharmacy volume remains dominant; channel share is gaining fastest through online subscription platforms and practitioner-direct procurement networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany's chemical corridor while consumption spreads across aging populations in Japan and fortification-driven markets in India. Supply-side concentration in Central Europe serves demand nodes spanning three continents.
Germany
Precision nutrition clusters in Baden-Württemberg process TRAACS-certified bisglycinate for practitioner-dispensed protocols across France and Italy. EFSA's Article 13.1 health claim substantiation requirements favor validated chelation over generic mineral salts. BASF's Ludwigshafen complex anchors pharmaceutical-grade supply serving hospital formularies throughout the EU.
United States
Compounding pharmacy networks and integrative medicine clinics drive specification intensity for high-dose magnesium and zinc formulations. FDA's 21 CFR 101.93 health claim enforcement shapes labeling compliance for direct-to-consumer subscription channels. Utah and California house contract manufacturers supplying practitioner-only lines with certificate-of-analysis transparency.
India
FSSAI edible oil and wheat flour fortification mandates create institutional procurement channels for pharmaceutical-grade zinc bisglycinate. CDSCO drug-approval pathways for prescription chelated minerals open hospital formulary access distinct from nutraceutical positioning. Maharashtra-based formulators serve domestic mass-market mineral fortification requirements.
Japan
Aging demographics concentrate demand for calcium bisglycinate in osteoporosis prevention formulations competing against carbonate and citrate salts. PMDA oversight of therapeutic mineral replacement products mandates validated bioavailability documentation. Tokyo-Osaka corridor houses finished dosage manufacturers targeting geriatric compliance segments.
Australia
TGA-registered practitioner-only supplement lines displace retail pharmacy distribution for premium chelated mineral positioning. Integrative medicine networks demand lot-specific absorption data and spectroscopic verification. Sydney and Melbourne clusters serve Oceania-wide practitioner channel consolidation.
Bisglycinate Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade supply chains, while mid-scale compounders populate nutraceutical and feed-grade segments. The structure splits between validated chelation technology holders and commodity mineral traders. Three archetypes dominate: integrated chemical conglomerates with amino acid chelation expertise, specialist mineral formulators serving practitioner channels, and regional compounders supplying fortification markets. Capacity expansion and technology licensing constitute the primary competitive moves.
Among TRAACS-certified specialists, Albion Laboratories exemplifies premium positioning through chelation verification protocols. BASF SE occupies a position within integrated chemical supply serving pharmaceutical-grade specifications. Jost Chemical Co. represents USP-grade mineral chelate fabrication for compounding pharmacy networks.
| Leading Market Players |
|---|
| Albion Laboratories |
| BASF SE |
| Jost Chemical Co. |
| Novotech Nutraceuticals |
| Balchem Corporation |
| Solgar Inc. |
| NOW Foods |
| Nature's Way |
| Glanbia plc |
| Others |
Value Network & Pricing Analysis
Continuous manufacturing adoption for TRAACS-certified bisglycinate is compressing unit economics while concentrating production among Ludwigshafen and Baden-Württemberg facilities capable of real-time release testing, simultaneously lowering per-kilogram costs and raising barriers for batch-process compounders.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects REACH re-registration cost burdens and glycine feedstock volatility from Chinese industrial output cycles. Three-tier pricing structure across TRAACS-certified, USP-grade, and feed-grade specifications separates validated chelation from commodity mineral salts. Cost-down pressure on animal feed applications accelerates because zinc oxide and copper sulfate substitutes trade at 40% discounts, forcing chelate producers to absorb margin erosion or cede livestock volume. Nutraceutical subscription channels exhibit lowest price sensitivity due to practitioner-dispensed positioning, while mass-market food supplement buyers drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with glycine feedstock concentration in Chinese fertilizer-grade production corridors. Manufacturing gravity centers on Germany, India, and the United States for finished chelate output, drawing from glycine, magnesium oxide, and zinc sulfate precursor streams. Tariff exposure on amino acid imports from Asia threatens margin stability for European compounders lacking backward integration into glycine synthesis. Distribution runs through contract manufacturer networks in Baden-Württemberg serving pan-European nutraceutical brands, with direct-to-consumer subscription platforms gaining fastest channel share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EFSA novel food substantiation requirements and FDA 21 CFR 101.93 enforcement raise compliance capital thresholds, forcing undercapitalized commodity traders toward exit.
For Market Incumbents: Hedge glycine input exposure through long-term offtake agreements with Chinese industrial suppliers or captive synthesis investments. Defend TRAACS certification premium by embedding spectroscopic fingerprinting into routine QC protocols that commodity competitors cannot replicate. Prioritize capacity addition in India's Maharashtra corridor to capture FSSAI fortification mandate procurement before domestic compounders scale pharmaceutical-grade output. For New Entrants and Emerging Players: Compounding pharmacy networks in the United States represent the most penetrable channel wedge, as practitioner demand for certificate-of-analysis transparency outpaces validated supplier availability. Target liquid bisglycinate formats for pediatric and geriatric compliance segments where tablet swallowing barriers create pricing power. Pursue white-label manufacturing partnerships with Baden-Württemberg contract manufacturers rather than greenfield capacity builds. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking amino acid chelation expertise. Five-to-ten year viability favors specialists with pre-2018 REACH grandfathered registrations that newer entrants cannot economically replicate. Monitor CDSCO prescription pathway approvals for chelated minerals as inflection signal for hospital formulary access expansion distinct from nutraceutical positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycine Synthesis | Captive supply of amino acid feedstock insulates margin from Chinese output volatility and REACH re-registration waves. |
| TRAACS Certification Investment | Spectroscopic verification protocols embed quality differentiation that EFSA substantiation requirements now mandate. |
| Continuous Manufacturing Scale-Up | Real-time release testing compresses batch cycle times and accelerates hospital formulary access in Germany. |
| Subscription Platform Partnership | Direct-to-consumer auto-ship models capture lifetime value from chronic-condition mineral supplementation demand. |
| India Manufacturing Footprint | Maharashtra-based production positions suppliers for FSSAI edible oil fortification mandate procurement channels. |
Research Methodology
Multi-period observation of TRAACS certification adoption rates, REACH registration status changes, and CDSCO approval timelines anchored the trend analysis, supplemented by interviews with pharmaceutical formulation chemists, contract manufacturing executives in Baden-Württemberg, regulatory affairs leads at chelated mineral suppliers, and hospital formulary directors in Germany and India. Secondary validation drew from EFSA Article 13.1 health claim submissions, USP pharmacopeial monograph updates, FSSAI fortification standard notifications, and customs trade data on glycine derivative imports. Bottom-up volume estimates by product type, end user, and form were cross-checked against top-down market sizing through expenditure-flow analysis.
Input-output matrices modeled demand drivers across pharmaceutical, nutraceutical, food supplement, and animal feed applications, with segmentation dimensions spanning mineral type, grade certification tier, finished dosage form, and regional regulatory cluster. CAGRs were derived from slope analysis of historical penetration curves adjusted for policy inflection points including EFSA novel food enforcement waves and India's fortification mandate expansion. Forecast inputs incorporated glycine feedstock cost trajectories, practitioner channel consolidation rates, and pharmacopeial harmonization progress between USP, EP, and JP standards.
Caveats apply where glycine supply disruptions, abrupt REACH substance evaluation outcomes, or CDSCO regulatory pathway delays could materially shift the outlook. Forecasts reflect assumptions on chelation technology adoption curves and practitioner channel purchasing power concentration that may revise with unexpected competitor entry or input cost shocks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Nootropic Products Market