
 Global Slimming Aids Market | 2026-2036
Global Slimming Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Slimming Aids Market Foresight
China's contract manufacturing base for botanical extracts is hardening as quality certification requirements tighten. Herbalife Nutrition Ltd. leverages its direct-selling infrastructure across Latin America and Asia. Novo Nordisk anchors prescription-grade appetite management through its metabolic science pipeline. Glanbia Plc. competes in sports nutrition crossover segments with whey-protein-based weight management formulations.
Slimming aids comprise ingestible products designed to reduce body mass, suppress appetite, accelerate metabolism, or enhance fat oxidation, typically formulated with active compounds such as green tea catechins, conjugated linoleic acid, or soluble fiber matrices at standardized concentrations. Their primary commercial purpose centers on assisting consumers in achieving caloric deficit or metabolic efficiency without surgical intervention. Dietary supplements occupy the largest revenue pool given repeat-purchase economics and lower regulatory barriers, while fat burners generate premium pricing among gym-attached consumers. Online retailers represent the fastest-growing distribution vector as subscription models displace pharmacy counter sales.
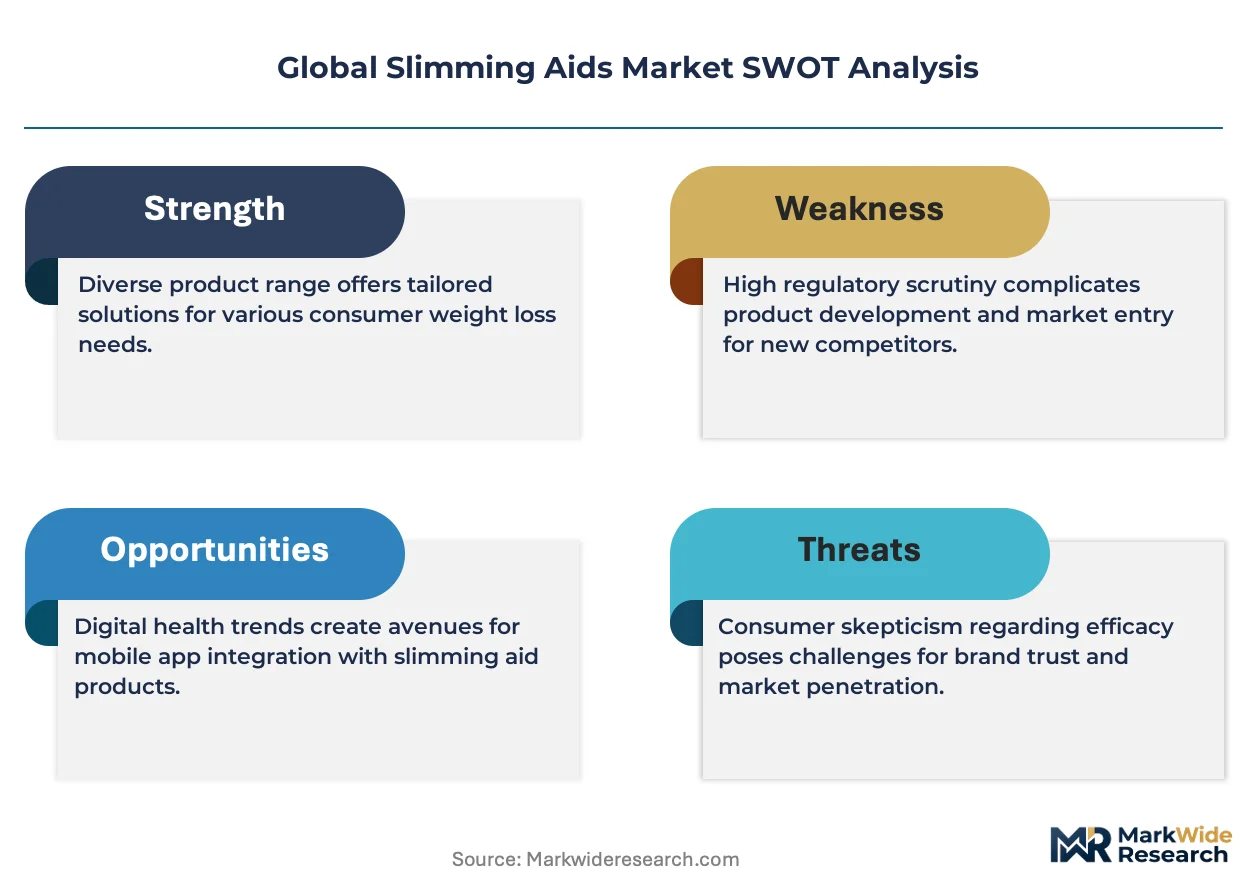
The FDA oversees over-the-counter slimming aid labeling and adverse event reporting in the United States, while the EMA coordinates pharmacovigilance for prescription crossover products in Europe, and China's NMPA enforces registration requirements for imported functional foods. These frameworks elevate compliance costs for new entrants but protect incumbent brands with established dossiers and testing protocols. Stakeholders must monitor evolving borderline classifications between food supplements and medicinal products as regulators recalibrate risk thresholds.
Market Dynamics
Direct-to-consumer subscription platforms are compressing traditional pharmacy and retail distribution, forcing incumbent brands to rebuild fulfillment infrastructure around recurring revenue models rather than point-of-sale transactions.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Standardized substantiation requirements across member states create predictable compliance pathways for cross-border formulation launches, reducing duplicate testing costs.
- Fitness-attached consumers:Gym ecosystem penetration drives premium-tier fat burner demand through bundled coaching and supplement protocols at commercial fitness chains.
- Botanical extract standardization:Advances in chromatographic fingerprinting enable consistent catechin and alkaloid potency claims, supporting clinical trial investment by contract manufacturers.
Market Restraints
- Raw material concentration:Green tea extract supply clusters in Zhejiang and Fujian provinces, exposing formulators to regional climate volatility and logistics bottlenecks.
- FDA adverse event surveillance:Mandatory serious adverse event reporting elevates legal exposure for stimulant-containing formulations, constraining ephedra-alternative innovation.
- Protein-fortified meal replacements:Whey and plant-protein shakes capture overlapping weight management budgets, particularly among male demographic segments.
Strategic Opportunities
- Brazil's ANVISA functional food pathway:Recent regulatory clarity for satiety claim submissions opens direct-selling penetration in Latin America's largest consumer base.
- Continuous glucose monitor integration:Pairing metabolic tracking wearables with personalized supplement protocols creates data-linked subscription stickiness.
- Pharmacy-to-digital channel migration:Telehealth platforms in Germany and France enable prescription-crossover product distribution without physical retail footprint.
Industry Challenges
- Pharmacovigilance staffing scarcity:Qualified safety data managers command premium compensation in European hubs, delaying dossier preparation for NMPA and EMA parallel submissions.
- Legacy ERP integration:Batch record digitization for FDA 21 CFR Part 11 compliance requires substantial middleware investment from mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Slimming Aids Market |
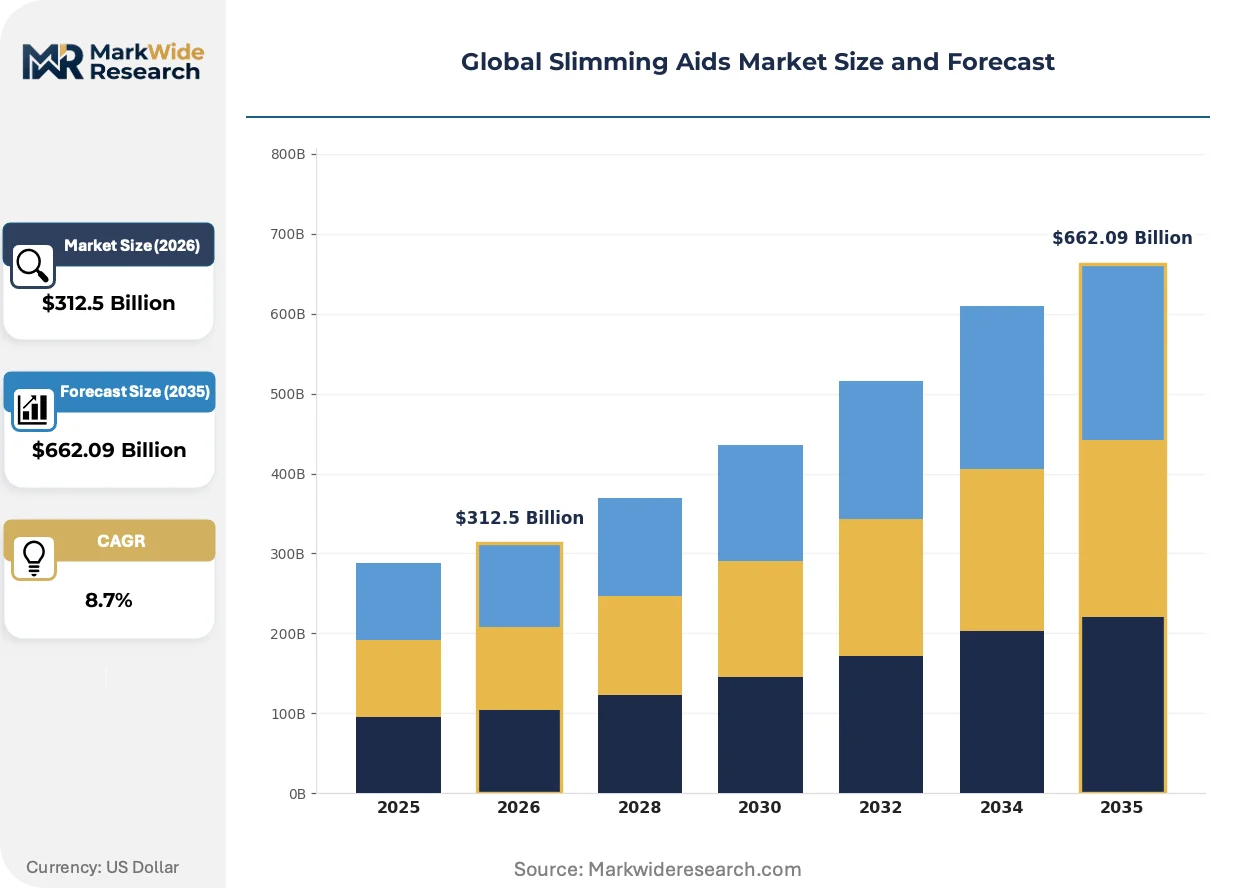
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $662.09 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Herbal Extracts, Appetite Suppressants, Fat Burners, Detox Products Application: Weight Management, Metabolic Boost, Body Shaping, Detoxification, Energy Enhancement Distribution Channel: Pharmacies, Online Retailers, Specialty Stores, Wellness Clinics, Direct Selling Customer Type: Fitness Enthusiasts, Nutritionists, Wellness Centers, Health Coaches, Dietitians |
| Companies Covered | Amway, Herbalife Nutrition Ltd., Nestle SA, Glanbia Plc., Novo Nordisk, GlaxoSmithKline PLC, Abbott Laboratories, GNC Holdings LLC, Iovate Health Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Slimming Aids Market Shifts & Advancements
Microbiome-targeted formulations and AI-driven personalization engines are redirecting R&D expenditure away from single-ingredient thermogenics toward systems-based metabolic interventions.
Postbiotic slimming aids leveraging Akkermansia muciniphila and butyrate precursors are expanding into premium subscription tiers. Functional medicine clinics in California and New York prescribe these formulations alongside dietary protocols. The technology is expanding into mass-market positioning as fermentation costs decline and strain-specific patent estates mature.
China's NMPA revised registration requirements for imported functional foods in 2023, mandating local clinical trial data for satiety and fat metabolism claims. Multinational brands now partner with domestic CROs to generate China-specific efficacy dossiers. This regulatory friction most affects botanical matrix products with historical reliance on foreign-sourced trial literature.
Subscription bundling with wearable devices is displacing standalone supplement purchases among affluent urban consumers. Peloton and Apple Fitness integrations drive quarterly replenishment cycles with biometric feedback loops. This pattern concentrates in United States coastal metros where wellness spending correlates with health data engagement.
Global Slimming Aids Market Segmentation
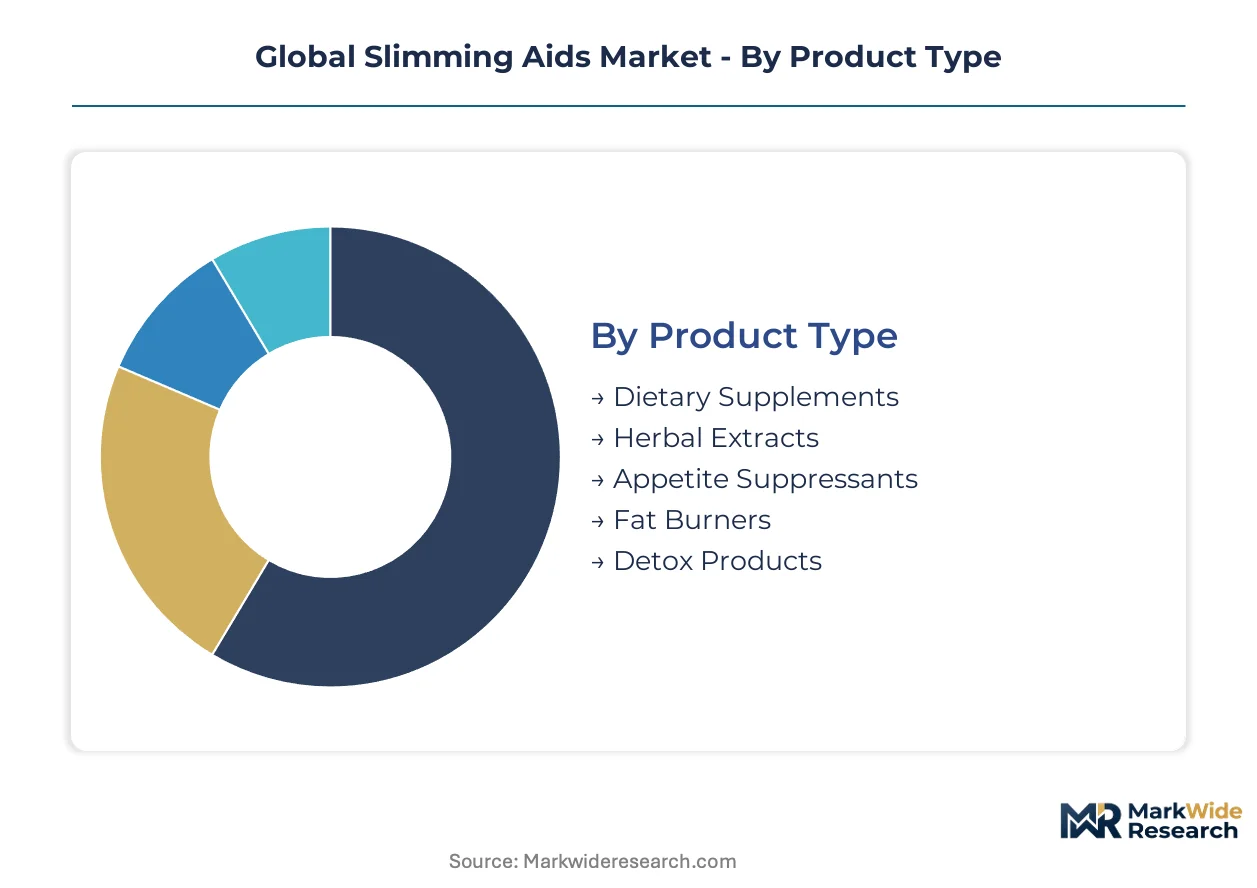
Slimming aids fragment across four distinct taxonomies that determine pricing power, regulatory pathway, and customer lifetime value. Each segmentation dimension carries divergent margin profiles and compliance burdens that reshape how manufacturers allocate R&D and distribution investment.
Product Type:
Purchase frequency and repeat-buying economics drive buyer selection more than single-transaction efficacy claims in this category.
- Dietary Supplements:Formulations combining soluble fibers, conjugated linoleic acid, and micronutrient matrices at standardized concentrations. Demand concentrates in the United States through pharmacy chains and subscription platforms, where FDA labeling requirements favor established dossiers over novel entrants.
- Fat Burners:Thermogenic compounds featuring green tea catechins, caffeine derivatives, and capsaicinoids engineered for metabolic acceleration. Gym-attached consumers in Germany and California sustain premium pricing through bundled coaching protocols and biometric tracking integration.
- Herbal Extracts:Botanical matrices sourced from Zhejiang and Fujian provinces, standardized through chromatographic fingerprinting for alkaloid consistency.
- Appetite Suppressants:Glucomannan, garcinia cambogia, and prescription-crossover compounds targeting satiety signaling pathways.
- Detox Products:Colon-cleansing and liver-support formulations leveraging milk thistle, dandelion root, and activated charcoal adsorbents.
Dietary supplements lead on scale; fat burners lead on momentum.
Application:
End-use outcomes determine formulation complexity and the regulatory borderline between food supplement and medicinal product.
- Weight Management:Caloric-deficit assistance through meal replacement matrices and macronutrient modulation. Wellness centers in France and dietitian networks in Australia drive institutional procurement with outcome-based protocols.
- Metabolic Boost:Thermogenic and mitochondrial efficiency formulations targeting basal metabolic rate elevation. Fitness enthusiasts in Brazil and South Korea sustain the steepest expansion trajectory through wearable-integrated subscription models.
- Body Shaping:Targeted fat oxidation and water-weight management for aesthetic outcomes.
- Detoxification:Elimination-focused protocols addressing environmental toxin accumulation and digestive reset.
- Energy Enhancement:Stimulant and adaptogen blends for training performance and daily vitality.
Weight management commands the largest addressable base; metabolic boost gains share fastest among younger demographics.
Distribution Channel:
Channel selection dictates margin retention, customer data access, and the speed of adverse event response.
- Online Retailers:Subscription platforms and marketplace aggregators with biometric feedback integration. The United States coastal metros and German urban centers concentrate demand where telehealth adjacencies enable prescription-crossover sales.
- Direct Selling:Person-to-person networks with coaching attachment and community accountability structures. Latin American markets and Southeast Asian tier-2 cities sustain volume through Herbalife-style infrastructure.
- Pharmacies:Brick-and-counter retail with pharmacist consultation and immediate fulfillment.
- Specialty Stores:Sports nutrition boutiques and organic retailers with curated assortment and education staff.
- Wellness Clinics:Functional medicine and aesthetic centers prescribing premium-tier protocols.
Online retailers expand most quickly; direct selling retains the highest per-customer economics.
Customer Type:
Professional credentialing and institutional purchasing authority segment price sensitivity and formulation sophistication.
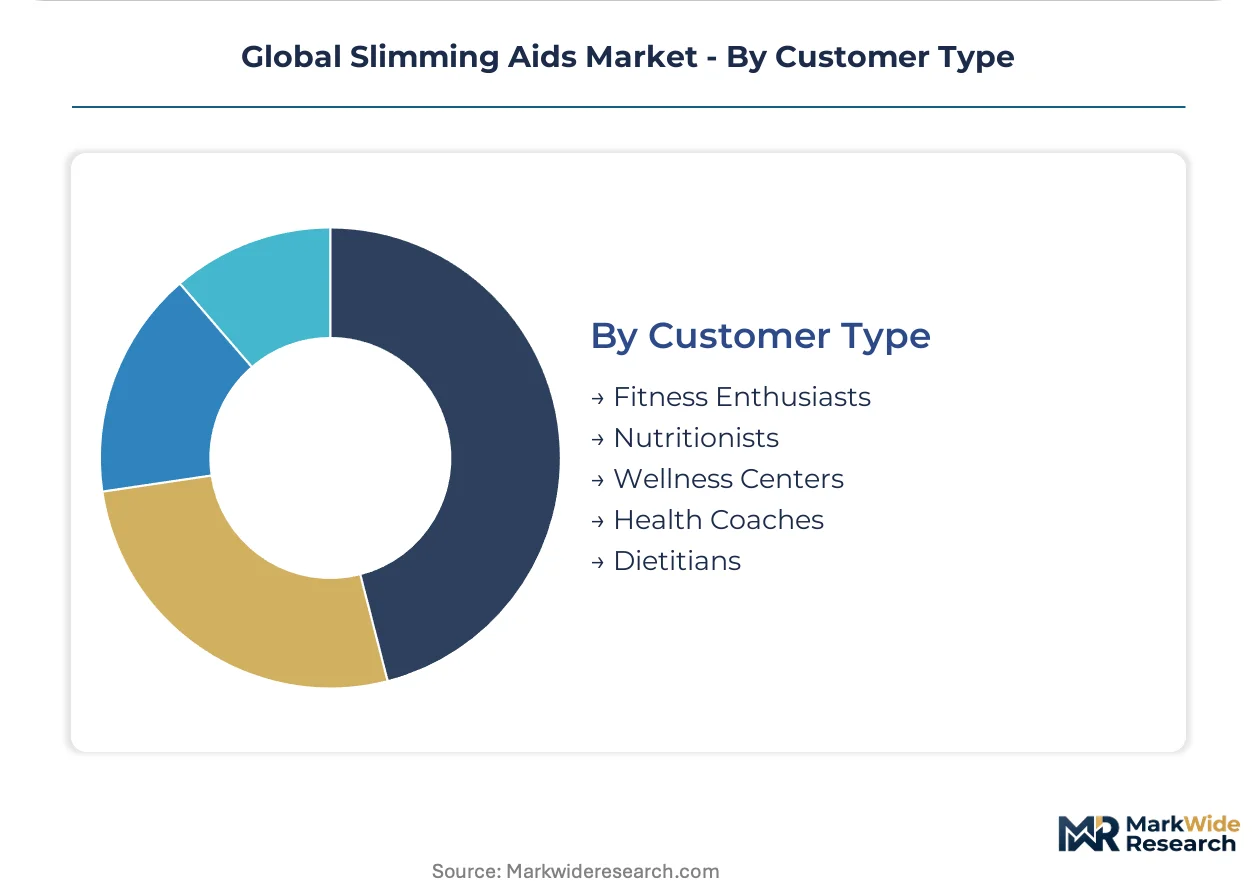
- Fitness Enthusiasts:Self-directed consumers with gym ecosystem attachment and social media-influenced brand discovery. Commercial fitness chains in California and New York bundle supplements with membership tiers.
- Nutritionists:Credentialed professionals recommending evidence-backed formulations to client bases.
- Wellness Centers:Institutional purchasers with protocol standardization and bulk procurement power.
- Health Coaches:Behavior-change specialists integrating supplements into accountability programs.
- Dietitians:Clinical nutrition professionals with hospital system affiliations and insurance-adjacent recommendation authority.
Fitness enthusiasts dominate volume; dietitians anchor the highest-compliance premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting contract manufacturing flows, with brands seeking testing efficiencies in markets offering streamlined dossier pathways while maintaining premium pricing power in high-compliance destinations.
United States
FDA adverse event reporting requirements and direct-selling infrastructure sustain premium-tier economics. California and New York coastal metros concentrate subscription platform demand through wearable-integrated wellness spending. The country's pharmacovigilance framework elevates compliance costs but protects incumbent brands with established safety databases.
Germany
EMA-coordinated pharmacovigilance and telehealth platform expansion enable prescription-crossover distribution without physical retail. Bavaria and North Rhine-Westphalia host functional medicine clinics driving postbiotic protocol adoption. The country's Nutrition and Health Claims Regulation implementation creates predictable substantiation pathways for cross-border launches.
China
NMPA registration mandates for imported functional foods are hardening quality certification requirements across Zhejiang and Fujian extraction clusters. Shanghai and Beijing urban centers concentrate affluent consumer demand for biometric-linked subscription models. The 2023 clinical trial data requirement redirects multinational partnership strategies toward domestic CRO networks.
Brazil
ANVISA regulatory clarity for satiety claim submissions opens direct-selling penetration in Latin America's largest consumer base. São Paulo and Rio de Janeiro anchor person-to-person network density with coaching attachment protocols. The country's functional food pathway reduces duplicate testing costs for botanical matrix products.
Japan
METI standards coordination and PMDA oversight maintain high barriers for stimulant-containing formulations while enabling premium positioning for evidence-backed ingredients. Tokyo and Osaka metropolitan areas concentrate aging-population demand for metabolic efficiency products. The country's fermentation technology base supports declining cost curves for microbiome-targeted formulations.
Global Slimming Aids Market Competitive Landscape
United States producers anchor the premium-tier and subscription-platform vector; European specialists hold the regulatory-compliance and clinical-positioning tier. The vendor base stratifies across direct-selling infrastructure owners, sports nutrition crossover players, and prescription-grade metabolic science developers. Three archetypes dominate: network-marketing distributors with coaching ecosystems, contract manufacturers with chromatographic standardization capabilities, and pharmaceutical-cosmetic hybrids leveraging pharmacovigilance infrastructure. Competitive moves concentrate on M&A for subscription technology assets and capacity expansion in botanical extraction clusters.
Within the direct-selling archetype, Herbalife Nutrition Ltd. and Amway exemplify network-marketing infrastructure at scale. Glanbia Plc. occupies a position bridging sports nutrition and weight management formulation. Novo Nordisk anchors the prescription-crossover tier through metabolic science positioning. These three represent divergent competitive vectors: person-to-person distribution, sports nutrition hybridization, and pharmaceutical-grade appetite management.
| Leading Market Players |
|---|
| Amway |
| Herbalife Nutrition Ltd. |
| Nestle SA |
| Glanbia Plc. |
| Novo Nordisk |
| GlaxoSmithKline PLC |
| Abbott Laboratories |
| GNC Holdings LLC |
| Iovate Health Sciences |
| Others |
Supply & Pricing Matrix
Fitness-attached consumer preference for biometric-linked subscription protocols is compressing traditional pharmacy markups and forcing formulators to absorb chromatographic standardization costs while defending premium positioning in direct-to-consumer channels.
Pricing Analysis
Distributor margins in direct-selling networks absorb coaching infrastructure costs that pharmacy channels avoid. Three-tier pricing structure across premium, standard, and economy levels separates wearable-integrated protocols from standalone supplements and bulk botanical powders. Price differentiation hinges on certification grade and geographic delivery cost, with NMPA-registered imports commanding substantial premiums over domestic Chinese formulations. Cost compression in standard-tier dietary supplements is intensifying because protein-fortified meal replacements capture overlapping weight management budgets. Fitness enthusiasts demonstrate lowest price sensitivity while pharmacy walk-in consumers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through contract manufacturing partnerships in Zhejiang and Fujian provinces. Raw material supply draws from green tea catechin extraction clusters in China, whey protein processing facilities in Ireland, and glucomannan konjac farming operations in Japan. Chromatographic fingerprinting equipment, specialized fermentation bioreactors, and FDA-compliant packaging materials constitute critical component dependencies. Single-source vulnerability concentrates in Zhejiang botanical extraction where climate volatility disrupts alkaloid consistency. Distribution runs through subscription platforms, direct-selling networks, and telehealth-adjacent pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Nutrition and Health Claims Regulation compliance costs in member states diverge sharply from Brazil's ANVISA functional food pathway savings.
For Market Incumbents: Hedge against protein-fortified meal replacement substitution by securing captive supply of chromatography-standardized botanical extracts in Fujian province. Expand subscription technology assets through targeted acquisition of biometric-integrated platform operators. Defend margin position by deepening backward integration into fermentation capacity for postbiotic formulations. For New Entrants and Emerging Players: Telehealth-adjacent pharmacy channels in Germany and France offer the most penetrable route for prescription-crossover product distribution without physical retail footprint. Target metabolic boost applications among Brazilian fitness enthusiasts through wearable-integrated subscription models. Pursue white-label manufacturing partnerships with established Zhejiang extraction facilities to bypass NMPA registration timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing chromatographic standardization capabilities and domestic Chinese CRO relationships. Long-term viability centers on microbiome-targeted formulation pipelines with strain-specific patent estates. Acquisition focus should concentrate on mid-tier manufacturers with batch record digitization infrastructure. The signal to watch is NMPA approval velocity for imported functional foods with satiety claims.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Acquisition | Captures recurring revenue economics and biometric data feedback loops in United States coastal metros. |
| Domestic CRO Partnership | Generates China-specific efficacy dossiers satisfying NMPA's 2023 clinical trial data mandate. |
| Chromatography Standardization Investment | Enables consistent alkaloid potency claims supporting premium pricing in German gym ecosystems. |
| Postbiotic Fermentation Scale-Up | Reduces unit costs for Akkermansia muciniphila formulations targeting California functional medicine clinics. |
| Telehealth Channel Integration | Opens prescription-crossover distribution through German and French digital pharmacy platforms. |
Research Methodology
Multiple input streams — regulatory filing databases, customs trade records, and subscription platform transaction data — were reconciled against primary interviews with formulation scientists at botanical extraction facilities, regulatory affairs leads at multinational supplement brands, procurement directors at commercial fitness chains, and pharmacovigilance managers at EMA-coordinated hubs. Secondary validation drew from FDA adverse event reporting system extracts, NMPA registration filings, ANVISA functional food submissions, and EU Nutrition and Health Claims Regulation substantiation dossiers. Bottom-up channel volume estimates and top-down macroeconomic anchoring were cross-referenced for triangulation.
Historical growth trajectories were benchmarked against expert panel assessments of regulatory pathway evolution and technology adoption curves across the projection horizon. Segmentation modeling incorporated product type, application outcome, distribution channel, and customer credentialing tier. CAGRs were derived from slope analysis of normalized revenue trajectories adjusted for regulatory friction coefficients. Forecast inputs included botanical raw material price indices, wearable device penetration rates, and direct-selling network expansion metrics.
The model assumes a particular technology adoption path; alternative pathways for microbiome-targeted formulations would alter the outlook if fermentation cost decline accelerates or strain-specific patent cliffs emerge earlier than anticipated. Forecasts reflect base-case assumptions about regulatory stability in major jurisdictions and sustained consumer willingness to pay for biometric-linked protocols. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Pet Allergy Immune Supplements Market