
 Sleep Aid Supplements Market | 2026-2036
Sleep Aid Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Aid Supplements Market Analytics
Personalized nutrition algorithms is fragmenting how sleep aid supplements reach consumers, replacing mass-market SKUs with microbiome-matched and chronotype-targeted formulations. Natrol leverages its pharmaceutical-grade melatonin supply chain to sustain quality positioning across retail and clinical channels. OLLY competes through gummy-format innovation that anchors brand recognition among younger demographics. GNC dominates brick-and-mortar distribution, controlling shelf space in fitness-adjacent retail environments.
Sleep aid supplements comprise orally administered non-prescription products containing melatonin, L-theanine, valerian root, magnesium glycinate, or GABA analogues, formulated to reduce sleep latency or improve sleep architecture without hypnotic dependency. These products serve consumers seeking alternatives to prescription sedative-hypnotics, particularly those with occupational restrictions or polypharmacy concerns. Melatonin formulations lead volume due to established efficacy literature and minimal next-day impairment, while gummy delivery modes capture the fastest growth as palatability drives compliance among supplement-naive users. Online retail channels concentrate margin pools through subscription economics, though pharmacies retain trust-sensitive senior and first-time buyer segments.
The FDA oversees dietary supplement manufacturing through cGMP rules and NDI notifications, while the FTC polices advertising substantiation for sleep-related structure-function claims. EFSA in Europe maintains stricter Novel Food assessments for melatonin dosages above 0.5 mg, creating divergent formulation strategies across Atlantic markets. Stakeholders must monitor how pharmacovigilance databases track adverse event signals for high-dose melatonin and emerging adaptogen combinations, as regulatory thresholds for safety documentation appear likely to tighten.
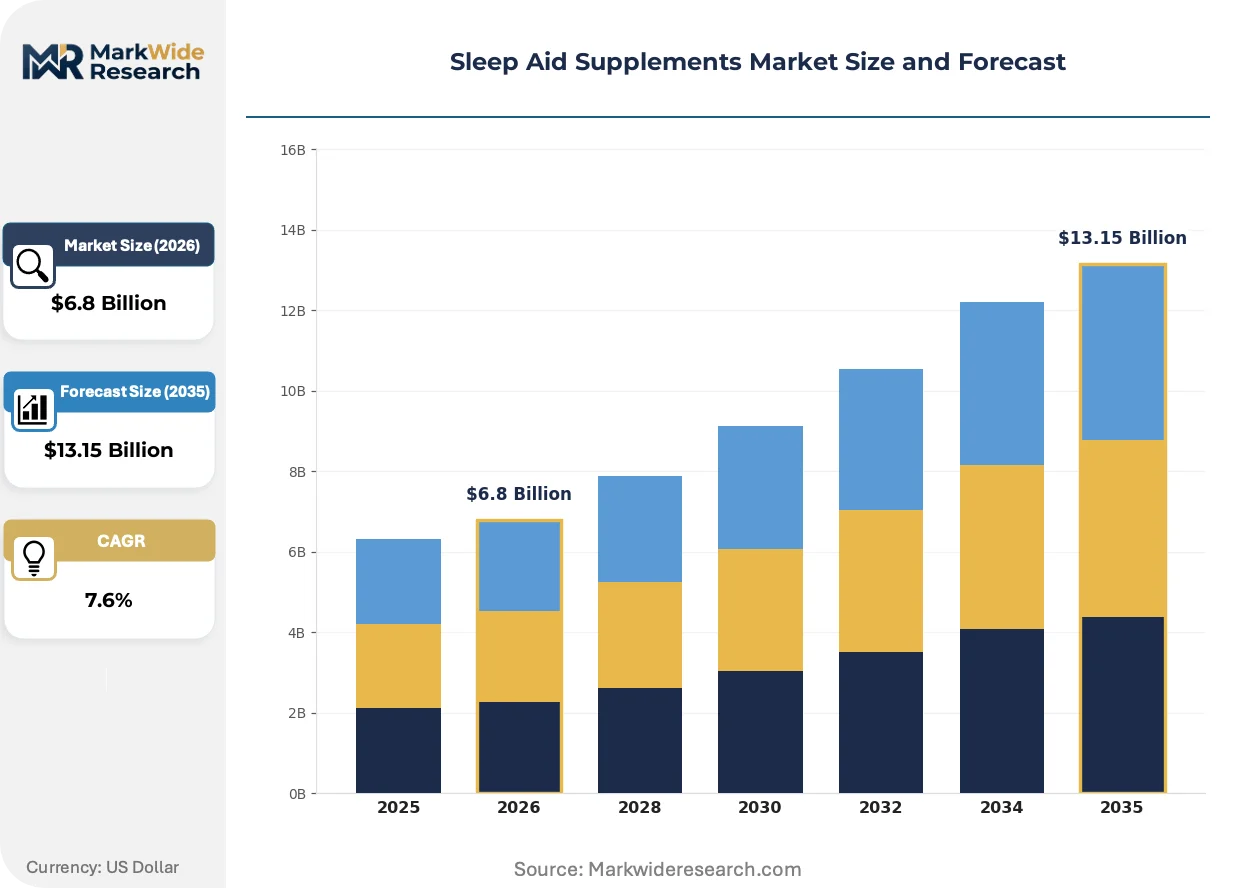
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins while forcing incumbent brands to rebuild their fulfillment infrastructure around recurring revenue mechanics rather than transactional shelf turnover.
Growth Catalysts
- FDA cGMP enforcement:Stricter manufacturing audits are elevating quality barriers that favor scaled producers with in-house analytical laboratories, consolidating supply toward pharmaceutical-grade ingredient sourcing.
- Working-age stress demographics:High-intensity professionals in technology and healthcare sectors now drive category volume as occupational restrictions limit prescription hypnotic use.
- Magnesium glycinate bioavailability advances:Chelated mineral formulations demonstrate superior sleep architecture outcomes in peer-reviewed literature, expanding clinical recommendation beyond melatonin monotherapy.
Market Restraints
- Melatonin raw material concentration:Pharmaceutical-grade supply chains concentrate among three primary API manufacturers, creating vulnerability to batch contamination events or geopolitical trade friction.
- EFSA Novel Food thresholds:European dosage caps at 0.5 mg force dual-SKU strategies that fragment production runs and inflate per-unit packaging costs for Atlantic-crossing brands.
- Prescription sedative-hypnotic substitution:Generic zolpidem and eszopiclone remain accessible through telehealth platforms, competing on immediate efficacy for acute insomnia episodes.
Strategic Opportunities
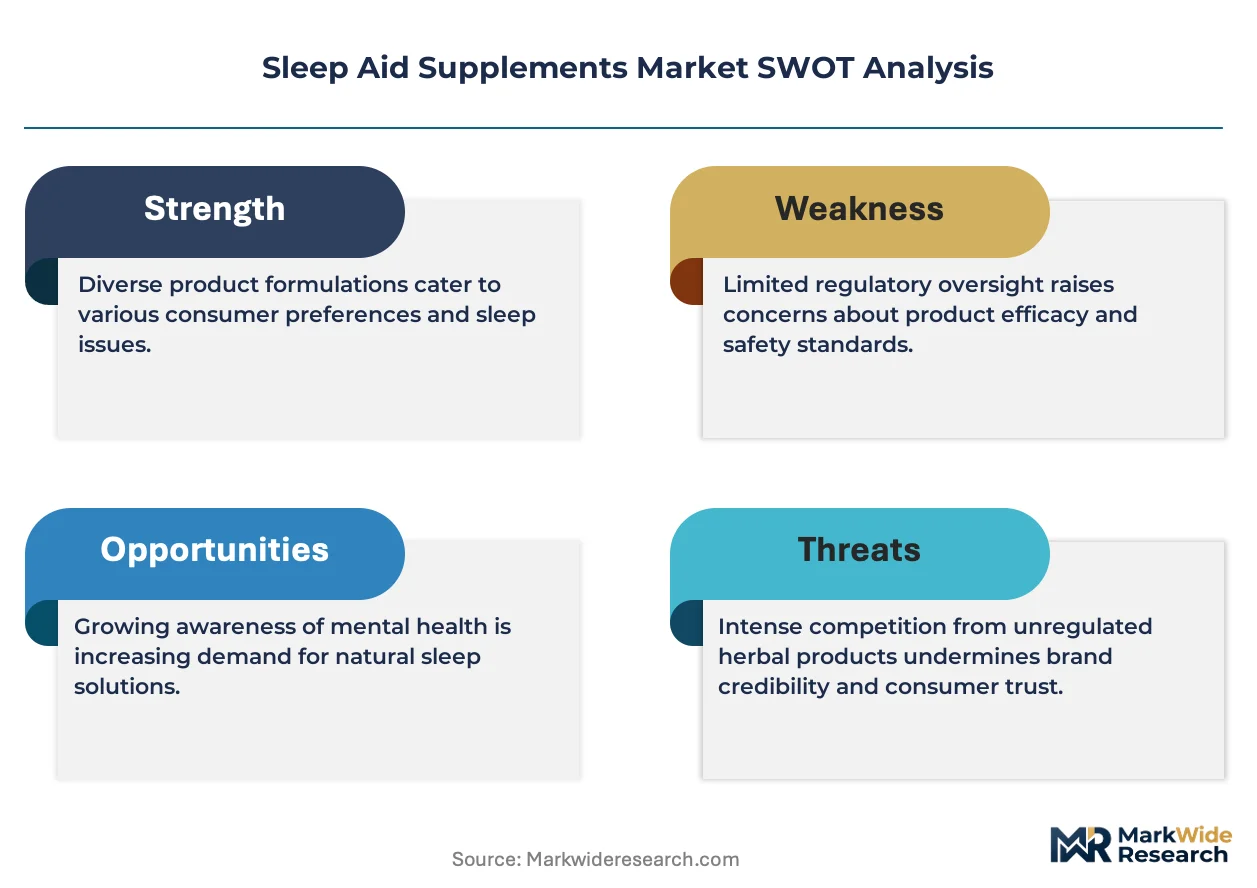
- Microbiome-matched formulations:Gut-sleep axis research enables personalized SKU development targeting circadian rhythm modulation through targeted probiotic-sleep ingredient combinations.
- Pharmacy retail integration:White-label partnerships with CVS and Walgreens place house brands adjacent to prescription pickup, capturing trust-sensitive first-time buyers.
- Chronotype-targeted delivery systems:Delayed-release melatonin matrices matched to individual sleep-wake phenotypes command premium positioning in employer wellness programs.
Industry Challenges
- Structure-function claim substantiation:FTC enforcement actions against unqualified sleep benefit language require costly clinical dossiers that strain mid-tier marketing budgets.
- Adaptogen supply traceability:Ashwagandha and rhodiola sourcing from Indian and Siberian wild-collection networks demands blockchain-verified chain-of-custody documentation for quality-sensitive channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Aid Supplements Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Melatonin, Amino Acids, Vitamins Delivery Mode: Tablets, Capsules, Gummies, Powders End User: Adults, Seniors, Athletes, Students Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Nature's Bounty, Natrol, OLLY, Herbalife Nutrition, Life Extension, GNC, Pure Encapsulations, Swanson Health Products, Goli Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Aid Supplements Market Evolving Landscape
Formulation science is converging with digital health infrastructure to create feedback-loop products where biometric data directly shapes ingredient dosing and delivery timing.
Gummy delivery matrices is hybridizing with pharmaceutical-grade active coating technologies, enabling precise melatonin release curves previously achievable only in tablet formats. Younger supplement-naive consumers drive adoption velocity, with palatability now outweighing cost-per-dose in purchase decisions. This convergence compresses the traditional advantage of legacy pill manufacturers while elevating contract manufacturers with confectionery expertise.
EFSA's tightening Novel Food assessments for melatonin dosages above 0.5 mg are fragmenting Atlantic formulation strategies, forcing separate SKU development for European and American markets. Brands now maintain dual manufacturing lines with divergent excipient profiles and stability testing protocols. Smaller exporters without regulatory affairs capacity are exiting European distribution entirely, ceding shelf space to established pharmaceutical-backed supplement divisions.
Subscription auto-replenishment now dominates direct-to-consumer channel economics, with churn management replacing customer acquisition as the primary operational metric. Amazon Subscribe & Save and specialized wellness platforms disintermediate pharmacy impulse purchases, concentrating buyer data in platform hands. This shift is most visible in United States metropolitan markets where same-day delivery infrastructure supports just-in-time household inventory management.
Sleep Aid Supplements Market Segmentation
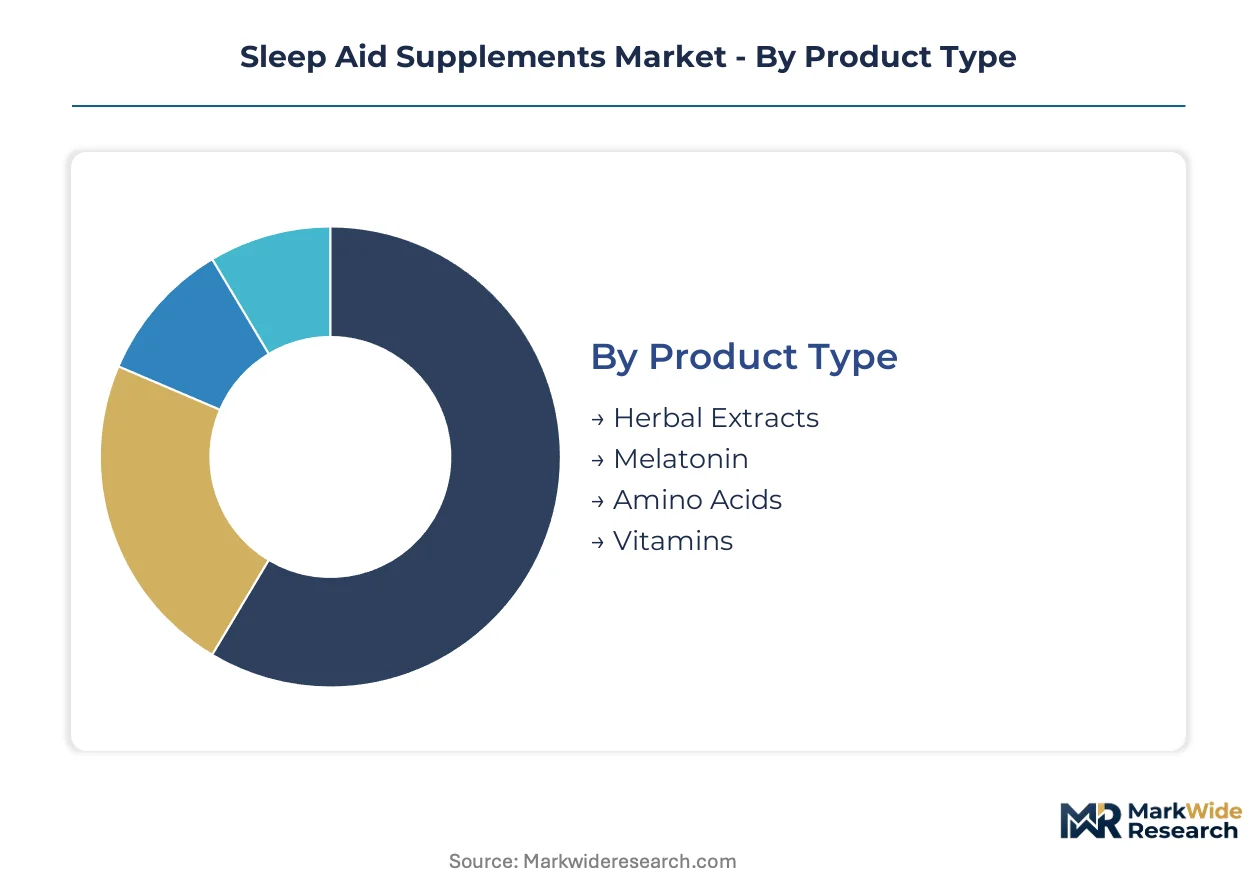
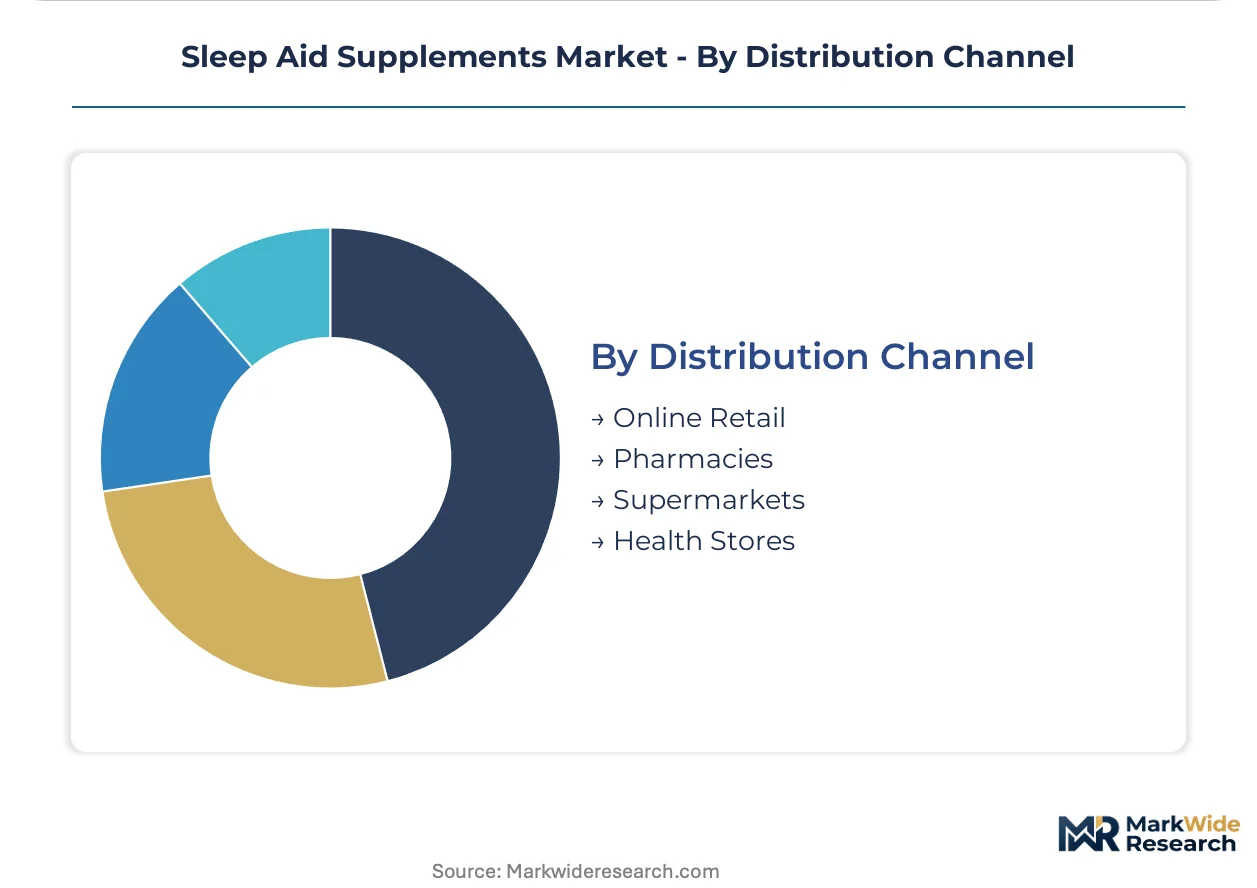
Sleep aid supplement segmentation reveals divergent velocity profiles across formulation types and channel economics. Product lifecycle compression varies dramatically between fast-turning gummy formats and stable tablet franchises, reshaping inventory strategies and margin capture across the value chain.
Product Type:
Inventory velocity separates botanical extracts with seasonal harvest dependencies from synthetic actives with year-round manufacturing continuity.
- Melatonin:Synthetic pineal hormone analogues standardized to USP-grade purity specifications dominate pharmacy and clinical recommendation channels. Working-age professionals in high-stress occupations drive sustained replenishment cycles through subscription platforms, with occupational restrictions on prescription hypnotics reinforcing preference for this non-scheduled alternative.
- Herbal Extracts:Valerian root, passionflower, and hops standardized extracts require extended cultivation lead times and batch-to-batch phytochemical variability management. European demand concentrates in Germany and France where traditional medicine frameworks elevate botanical credibility, though EFSA Novel Food assessments constrain dosage innovation.
- Amino Acids:L-theanine and glycine formulations target GABAergic modulation without next-day impairment. Athletes and shift workers in United States metropolitan markets sustain above-average repurchase frequency.
- Vitamins:Magnesium glycinate and B6 complexes leverage established nutrient deficiency framing for shelf placement adjacent to general wellness SKUs. Seniors seeking polypharmacy alternatives drive pharmacy channel concentration.
Melatonin dominates installed base. Herbal extracts are where expansion concentrates.
Delivery Mode:
Manufacturing complexity stratifies across solid-dose legacy formats and confectionery-hybrid innovations with divergent equipment requirements.
- Gummies:Gelatin and pectin matrices with pharmaceutical-grade active coating enable precise release curves previously limited to tablets. Younger demographics in United States direct-to-consumer channels prioritize palatability over unit cost, compressing traditional pill manufacturer advantages.
- Tablets:Compressed melatonin and magnesium formulations with established dissolution profiles retain pharmacy trust and senior segment loyalty. cGMP-scaled producers with in-house analytical laboratories control this stable, high-volume category.
- Capsules:Two-piece gelatin and vegetable cellulose shells accommodate heat-sensitive botanical extracts and probiotic combinations. Health store channels favor this format for ingredient transparency signaling.
- Powders:Bulk amino acid and magnesium formulations serve biohacking enthusiasts and athletic populations seeking dose titration flexibility. Online retail subscription models capture this niche with flavor innovation.
Tablets dominate installed base. Gummies are where expansion concentrates.
End User:
Occupational constraints and physiological life stage create distinct purchasing cadences and efficacy expectation profiles across demographic clusters.
- Adults:Working-age populations in technology and healthcare sectors face occupational restrictions on prescription sedative-hypnotics. Direct-to-consumer subscription economics concentrate in United States metropolitan markets with same-day delivery infrastructure.
- Seniors:Polypharmacy concerns and fall-risk avoidance elevate preference for non-hypnotic alternatives. Pharmacy retail integration captures this trust-sensitive segment adjacent to prescription pickup workflows.
- Athletes:Anti-doping compliance requirements and recovery optimization drive demand for NSF Certified for Sport formulations. Magnesium glycinate and tart cherry extract combinations gain traction in fitness-adjacent retail.
- Students:Academic pressure and irregular schedules sustain seasonal demand spikes aligned with examination periods. Gummy formats with lower per-dose costs penetrate this price-sensitive cohort.
Adults dominate installed base. Athletes are where expansion concentrates.
Distribution Channel:
Channel economics fragment between recurring-revenue platform models and transactional trust-based retail environments with divergent working capital requirements.
- Online Retail:Amazon Subscribe & Save and specialized wellness platforms concentrate buyer data and disintermediate pharmacy impulse purchases. Churn management replaces customer acquisition as the primary operational metric in United States markets.
- Pharmacies:CVS and Walgreens house brand placement adjacent to prescription pickup captures first-time buyers and senior trust. White-label partnerships enable scaled producers to access this channel without brand marketing overhead.
- Supermarkets:Mass-market melatonin SKUs compete for shelf space with general wellness and pain management categories. Price compression favors high-volume contract manufacturers with pharmaceutical-grade supply chain integration.
- Health Stores:GNC and independent retailers control fitness-adjacent environments where magnesium glycinate and adaptogen combinations command premium positioning. Staff recommendation influence sustains higher margins than mass retail.
Pharmacies dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working-age professionals in high-stress occupations concentrate demand in developed economies where occupational restrictions limit prescription hypnotic use. Subscription auto-replenishment models dominate in metropolitan markets with same-day delivery infrastructure. Regulatory divergence between FDA cGMP enforcement and EFSA Novel Food thresholds fragments formulation strategies across Atlantic markets.
United States
Technology and healthcare sector professionals drive volume through direct-to-consumer subscription platforms. FDA cGMP enforcement elevates quality barriers that favor scaled producers with pharmaceutical-grade supply chains. The San Francisco Bay Area and New York Metro anchor employer wellness program adoption of chronotype-targeted formulations.
Germany
Traditional medicine frameworks elevate botanical credibility for valerian and hops extracts. EFSA Novel Food assessments constrain melatonin dosage innovation above 0.5 mg thresholds. The Baden-Württemberg region concentrates pharmaceutical-backed supplement divisions with dual-SKU manufacturing for Atlantic markets.
United Kingdom
Shift workers in financial services and transportation sectors sustain above-average amino acid formulation demand. MHRA guidelines on novel psychoactive substances create compliance complexity for adaptogen combinations. London's wellness startup ecosystem drives microbiome-matched product development through venture-backed nutrition platforms.
Japan
Aging demographics and polypharmacy avoidance elevate pharmacy channel trust for non-hypnotic alternatives. PMDA oversight of functional food claims requires clinical substantiation dossiers for sleep-specific marketing. The Kanto region around Tokyo concentrates retail pharmacy integration with white-label house brand placement.
Australia
Athletic populations seeking NSF Certified for Sport formulations drive magnesium glycinate demand in fitness-adjacent retail. TGA scheduling of melatonin as pharmacy-only above certain dosages channels distribution through pharmacist consultation workflows. Sydney and Melbourne anchor subscription platform concentration with same-day delivery infrastructure.
Sleep Aid Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Pharmaceutical-grade manufacturers with cGMP-scaled laboratories consolidate supply toward quality-sensitive pharmacy and clinical channels. Three archetypes dominate: legacy nutraceutical conglomerates with retail shelf control, direct-to-consumer native brands with subscription infrastructure, and pharmaceutical-backed supplement divisions with regulatory affairs capacity. Competitive moves concentrate on white-label pharmacy partnerships and gummy-format manufacturing capability acquisition.
Among legacy retail-anchored players, Nature's Bounty and GNC exemplify channel-control archetypes with established pharmacy and health store shelf presence. Natrol and OLLY occupy positions on the product-specialist vector, with the former representing pharmaceutical-grade supply chain integration and the latter exemplifying format innovation through confectionery-hybrid delivery systems. These four entities anchor the competitive structure without exhausting its variation.
| Leading Market Players |
|---|
| Nature's Bounty |
| Natrol |
| OLLY |
| Herbalife Nutrition |
| Life Extension |
| GNC |
| Pure Encapsulations |
| Swanson Health Products |
| Goli Nutrition |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade melatonin API production concentrates among three primary manufacturers in China and India, anchoring downstream margin pools in subscription-platform brands with direct-to-consumer pricing power rather than traditional retail intermediaries. Cost pass-through mechanics favor scaled producers with captive supply agreements, while smaller brands absorb volatility through formula simplification.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade melatonin suppliers index to raw material spot markets, creating margin compression risk for brands without backward integration into API sourcing. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from pharmacy-grade tablets and mass-market gummies. Pricing pressure stems from Amazon Subscribe & Save mechanics that reward volume scale over brand premium. Students and price-sensitive first-time buyers exhibit highest price elasticity, while seniors in pharmacy channels accept modest premiums for trust-adjacent placement.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms now structure relationships between gummy-format contract manufacturers and emerging direct-to-consumer brands, easing working capital constraints for subscription-heavy revenue models. Active pharmaceutical ingredient production draws from China, India, and select European facilities with USP-grade certification. Raw material dependencies include synthetic melatonin, gelatin and pectin matrices, and chelated magnesium compounds. Single-source vulnerability concentrates in pharmaceutical-grade melatonin API where batch contamination events cascade downstream. Distribution runs through Amazon fulfillment networks and specialized wellness platforms that disintermediate traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as employer wellness programs normalize daily sleep supplementation among working-age professionals previously restricted from prescription hypnotics.
For Market Incumbents: Harden quality positioning through in-house analytical laboratory investment that exceeds FDA cGMP enforcement thresholds, consolidating supply toward pharmaceutical-grade ingredient sourcing as smaller competitors exit under compliance cost pressure. Defend pharmacy channel access through white-label partnerships with CVS and Walgreens that capture trust-sensitive senior segments adjacent to prescription pickup workflows. For New Entrants and Emerging Players: European markets under 0.5 mg melatonin dosage caps present white-space opportunity for probiotic-sleep combination formulations that circumvent EFSA Novel Food thresholds through functional food positioning. Target Germany and France where traditional medicine frameworks elevate botanical credibility. Pursue pharmacy retail integration through regional distributor partnerships rather than direct platform competition with established subscription brands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed direct-to-consumer brands possessing subscription infrastructure but lacking regulatory affairs capacity for Atlantic-crossing expansion. Five-to-ten year viability hinges on consolidation into pharmaceutical-backed supplement divisions with dual-SKU manufacturing capabilities. Watch FDA pharmacovigilance database entries for high-dose melatonin adverse event signals as early indicator of tightening safety documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy White-Label Partnership | CVS and Walgreens house brand placement captures trust-sensitive first-time buyers without marketing overhead. |
| Gummy-Format Manufacturing Acquisition | Confectionery-hybrid capabilities with pharmaceutical-grade active coating enable precise release curve differentiation. |
| Dual-SKU Atlantic Strategy | Separate manufacturing lines for FDA and EFSA compliance requirements fragment production but preserve European access. |
| Microbiome-Matched Formulation Launch | Gut-sleep axis research enables personalized SKU development targeting circadian modulation through probiotic combinations. |
| Subscription Infrastructure Buildout | Churn management capabilities replace customer acquisition as primary operational metric in direct-to-consumer channels. |
Research Methodology
Cross-validation between primary interviews with supplement brand executives, contract manufacturing procurement leads, and pharmacy category buyers anchors the qualitative findings against FDA cGMP audit records and EFSA Novel Food assessment databases. Bottom-up demand modeling triangulates against top-down market sizing from customs trade data and Nielsen retail audit information.
Calibration against historical subscription platform churn rates and pharmacy channel inventory turns refines volume assumptions across the projection horizon. Segmentation dimensions include product type, delivery mode, end-user occupation, and distribution channel economics. CAGRs derive from installed base penetration curves and replacement rate analysis specific to gummy versus tablet format lifecycles.
Practitioners should monitor FDA pharmacovigilance adverse event reporting and EFSA Novel Food reassessment timelines for early signals of regulatory threshold tightening. Forecasts reflect documented assumptions about subscription adoption velocity and employer wellness program penetration. Macroeconomic recession impacts on discretionary supplement spending, regulatory deviation on melatonin dosage caps, or technological disruption in biometric sleep tracking would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Global Beauty Supplements Market