
 Global Effervescent Tablet Market | 2026-2036
Global Effervescent Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Effervescent Tablet Market Foresight
Sports nutrition buyers is collapsing the historical dominance of general wellness consumers in effervescent tablet demand. Pfizer Inc. leverages its pharmaceutical manufacturing scale to supply healthcare-grade effervescent lines to hospital systems worldwide. Sandoz Group AG anchors the generic effervescent segment with cost-optimized production for European pharmacy chains. Bayer AG differentiates through consumer brand recognition in vitamin and pain relief effervescents across multiple continents.
Effervescent tablets are solid dosage forms containing acid-base reactants, typically citric acid and sodium bicarbonate, that generate carbon dioxide upon contact with water to produce a rapidly dissolving solution with bioavailability advantages over conventional tablets. The formulation technology dimension reveals critical structural variation: direct compression dominates high-volume vitamin production for its speed, while freeze drying commands premium positioning in pediatric and geriatric applications where rapid disintegration determines therapeutic efficacy. Within application sectors, sports nutrition and geriatric nutrition represent the fastest-expanding margin pools as aging populations and fitness cultures simultaneously reshape consumption patterns.
FDA oversight in the United States and EMA frameworks in Europe govern pharmaceutical-grade effervescent claims, while ISO standards and national pharmacopeias set dissolution and stability benchmarks that determine market access across jurisdictions. The EU Green Deal's chemical sustainability targets are forcing reformulation of effervescent effluents and packaging materials, particularly affecting German and Swiss production hubs. Stakeholders must monitor regulatory divergence between FDA bioequivalence pathways and EMA centralized procedures, as this friction will determine which formulation technologies receive investment priority and which geographic production clusters capture disproportionate capacity expansion.
Market Dynamics
The EU F-Gas Regulation and REACH compliance requirements are compressing formulation choices across European manufacturing hubs, forcing acid-base chemistry substitutions and cleaner effluent protocols that reshape competitive cost structures in pharmaceutical-grade production.
Growth Catalysts
- Electrolyte delivery protocols:Sports nutrition buyers are expanding procurement volumes as athletes prioritize rapid hydration absorption over conventional tablet formats. This shift concentrates demand in performance-oriented formulations.
- REACH chemical sustainability targets:The European Union's Green Deal mandates are accelerating reformulation investments toward biodegradable effervescent matrices and recyclable packaging substrates.
- Geriatric nutrition expansion:Aging populations in Japan and Germany are driving demand for rapid-disintegration pediatric and geriatric formulations where swallowing conventional tablets presents adherence barriers.
Market Restraints
- Citric acid and sodium bicarbonate price volatility:Input cost swings for these essential acid-base reactants compress margin predictability for high-volume vitamin producers dependent on direct compression economics.
- Swiss and German production hub concentration:Formulation expertise clusters around HERMES PHARMA GmbH and Bayer AG facilities, creating geographic supply vulnerability for healthcare-grade effervescent lines.
- Freeze-drying capex intensity:Premium pediatric and geriatric applications require capital-intensive lyophilization equipment that barriers mid-scale manufacturers from margin-rich therapeutic segments.
Strategic Opportunities
- Indian pharmacy chain penetration:Underpenetrated distribution in India's retail pharmacy sector offers white space for cost-optimized generic effervescent formats targeting price-sensitive wellness consumers.
- Dual carbon goals in China:NMPA green chemistry incentives are creating regulatory tailwinds for domestic manufacturers adopting cleaner effervescent production technologies.
- Direct-to-athlete subscription channels:Sports nutrition brands are bypassing traditional retail through personalized electrolyte subscription models that capture recurring revenue and consumption data.
Industry Challenges
- Pharmaceutical formulation chemist scarcity:Specialized expertise in acid-base stability modeling and moisture-controlled manufacturing is concentrating among legacy European facilities, constraining capacity expansion.
- FDA-EMA bioequivalence pathway divergence:Friction between United States and European dissolution testing standards creates certification timeline delays for multi-jurisdictional product launches.
- Legacy packaging line retrofit costs:Existing tablet compression facilities face capital-intensive upgrades to handle effervescent moisture sensitivity requirements without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Effervescent Tablet Market |
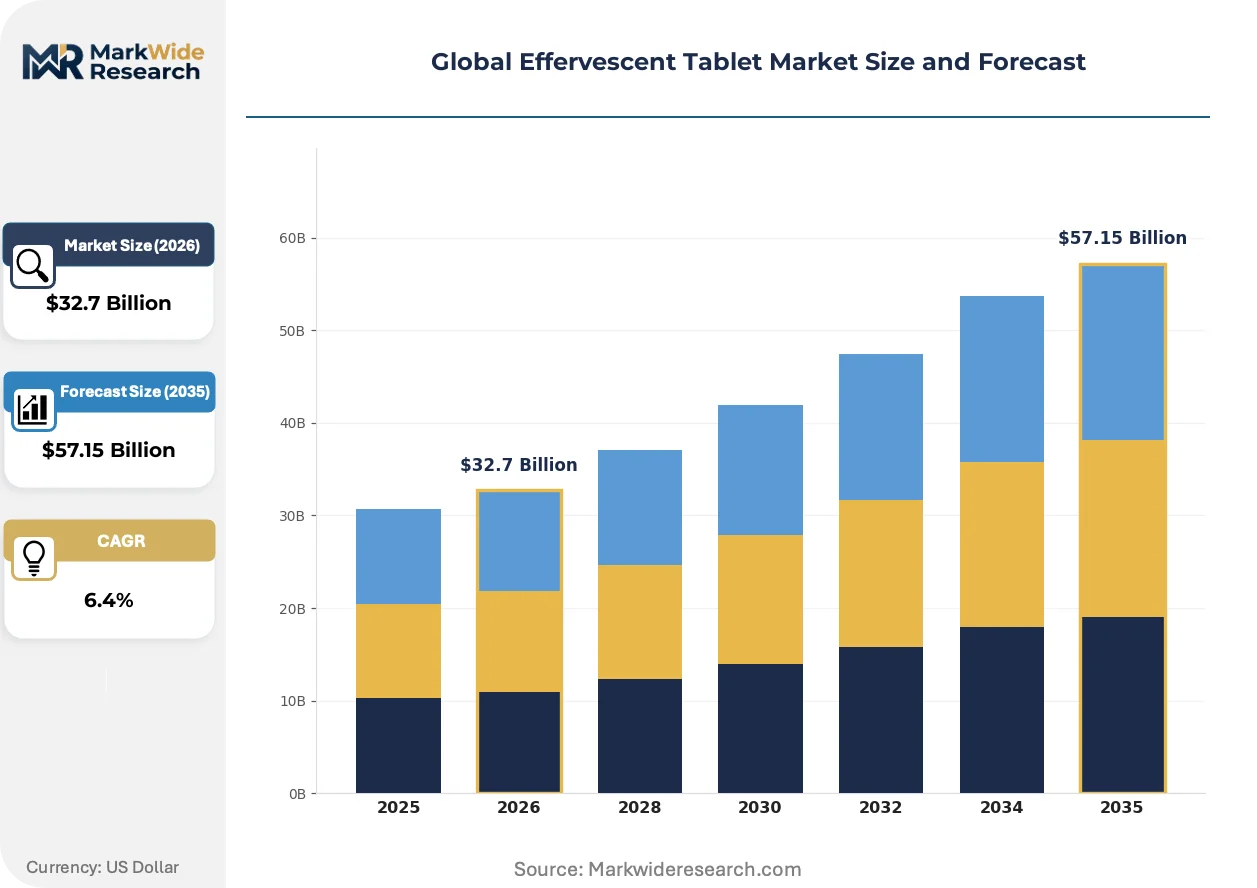
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $57.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Supplements, Pain Relievers, Antacids, Electrolyte Replenishers, Digestive Aids, Others Formulation Technology: Direct Compression, Dry Granulation, Wet Granulation, Freeze Drying, Spray Drying Application Sector: Sports Nutrition, Geriatric Nutrition, Pediatric Care, Wellness Products, Veterinary Use End Consumer Type: Pharmacies, Healthcare Facilities, Online Retailers, Specialty Stores, Supermarkets |
| Companies Covered | Pfizer Inc., Sandoz Group AG, Bayer AG, Vitaquest International, Perrigo Co. Plc, GlaxoSmithKline Plc, HERMES PHARMA GmbH, Handian Nutrition, Reckitt Benckiser Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Effervescent Tablet Market Shifts & Advancements
Formulation technology is bifurcating between speed-optimized direct compression and efficacy-driven freeze drying, while regulatory chemistry mandates and consumption pattern shifts simultaneously reshape production priorities and channel structures.
Lyophilization technology for effervescent matrices is miniaturizing. This freeze-drying approach preserves active pharmaceutical integrity while enabling rapid disintegration critical for geriatric and pediatric therapeutic efficacy. Hospital systems and long-term care facilities are adopting these premium formats at accelerating rates. The technology is miniaturizing equipment footprints and process economics, compressing the historical scale advantage of direct compression and opening specialist manufacturing to mid-cap entrants.
REACH chemical restrictions and the EU F-Gas Regulation are forcing acid-base reactant substitutions across German and Swiss production hubs. These frameworks prohibit specific effervescent effluent chemistries and mandate biodegradable packaging transitions. Pharmaceutical-grade manufacturers are responding with reformulation R&D investments that prioritize citric acid alternatives and sodium bicarbonate sourcing from verified sustainable suppliers.
Athletes and fitness consumers are consolidating purchase decisions around rapid electrolyte delivery formats that bypass traditional pharmacy and retail channels. Sports nutrition brands are disintermediating conventional distribution through direct subscription models and team-based bulk procurement. This pattern is most visible in North American and Australian markets where performance-oriented consumption cultures prioritize convenience and personalization over brand loyalty.
Global Effervescent Tablet Market Segmentation
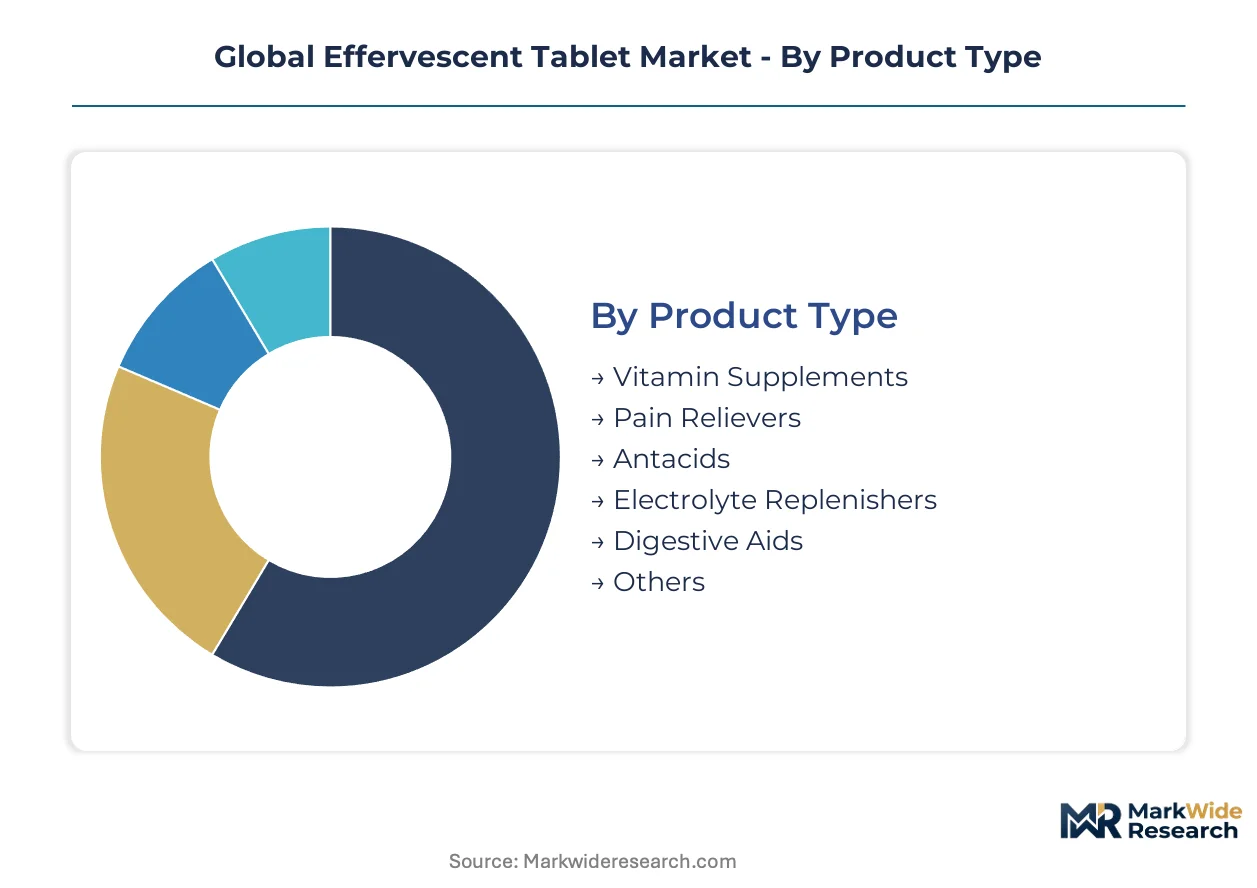
Effervescent tablet segmentation reveals how formulation chemistry, distribution channel, and end-user physiology intersect to determine pricing power and regulatory pathway. Manufacturers configure production lines around specific segment requirements rather than attempting universal coverage.
Product Type:
FDA and EMA bioequivalence standards diverge sharply across therapeutic categories, forcing manufacturers to maintain parallel certification dossiers for pharmaceutical-grade segments versus wellness-positioned formats.
- Vitamin Supplements:Citric acid-sodium bicarbonate matrices dominate this high-volume category, with direct compression economics enabling cost-optimized production for German and Swiss manufacturing hubs. Demand concentrates in pharmacy chains across Germany and India where consumers prioritize daily adherence convenience.
- Electrolyte Replenishers:Rapid-disintegration formulations leverage optimized particle size distribution for sub-60-second dissolution, critical for athletic hydration protocols. Sports nutrition procurement in Australia and the United States is displacing traditional retail volumes as direct-to-athlete channels capture recurring revenue.
- Pain Relievers:Buffered analgesic formulations require moisture-barrier packaging and stability testing under ICH guidelines.
- Antacids:Sodium bicarbonate-heavy compositions target GERD management in aging populations.
- Digestive Aids:Enzyme-cofactor combinations address post-meal discomfort in wellness-oriented consumers.
- Others:Niche therapeutic categories including cold remedies and hangover formulations.
Established volume favors Vitamin Supplements; emerging adoption favors Electrolyte Replenishers.
Formulation Technology:
Capital intensity separates scalable direct compression from premium lyophilization, with equipment amortization schedules determining which manufacturers can serve hospital-grade versus retail-grade demand.
- Direct Compression:High-speed rotary tablet presses process pre-blended acid-base powders without intermediate granulation, achieving throughput rates that support vitamin supplement economics. German facilities anchor global capacity for this speed-optimized approach.
- Freeze Drying:Sublimation-based moisture removal preserves heat-sensitive actives while producing porous matrices with sub-30-second disintegration, essential for pediatric and geriatric therapeutic efficacy. Hospital systems in Japan and Switzerland adopt these premium formats at accelerating rates.
- Dry Granulation:Roller compaction improves flow properties for moisture-sensitive formulations without liquid binders.
- Wet Granulation:Fluid bed processing enables uniform distribution of low-dose actives.
- Spray Drying:Atomization-based particle engineering creates customized dissolution profiles for specialty applications.
Direct Compression commands the largest installed base; Freeze Drying exhibits the steepest expansion trajectory.
Application Sector:
Demographic tailwinds and consumption culture shifts are reallocating R&D investment across physiological target groups with divergent swallowing capability and absorption priority.
- Sports Nutrition:Electrolyte-focused formulations prioritize rapid gastric emptying and intestinal absorption for athletic performance. North American and Australian markets show strongest procurement concentration through team-based bulk channels.
- Geriatric Nutrition:Rapid-disintegration formats address dysphagia prevalence among aging populations in Japan and Germany, with long-term care facilities driving formulary adoption.
- Pediatric Care:Palatability-engineered matrices with masking technologies improve compliance.
- Wellness Products:General health maintenance formats target pharmacy retail in India and Brazil.
- Veterinary Use:Species-specific dosing and flavor profiles serve companion animal markets.
Geriatric Nutrition offers the deepest margin pool; Sports Nutrition is climbing the fastest.
End Consumer Type:
Channel economics determine packaging format and regulatory labeling burden, with healthcare facilities demanding unit-dose compliance packaging that supermarkets reject as cost-prohibitive.
- Pharmacies:Professional counseling environments support premium-positioned therapeutic and preventive formulations with pharmacist-driven recommendation protocols. European pharmacy chains concentrate procurement through centralized generic purchasing.
- Healthcare Facilities:Hospital formularies and long-term care institutions require pharmaceutical-grade certification with batch-level traceability. Swiss and German production hubs supply these quality-sensitive channels.
- Online Retailers:Direct-to-consumer fulfillment enables subscription-based replenishment and personalization.
- Specialty Stores:Sports nutrition and wellness boutiques curate performance-oriented assortments.
- Supermarkets:Mass-market vitamin and antacid formats compete on shelf price.
Pharmacies retain the largest transaction volume; Healthcare Facilities command the highest per-unit pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sports nutrition procurement in Australia and the United States is compressing pharmacy-channel dominance as direct-to-athlete subscriptions capture recurring revenue. German healthcare facilities maintain the deepest formulary penetration for pharmaceutical-grade formats. Japanese long-term care institutions drive rapid-disintegration adoption among aging populations.
Germany
Healthcare facilities in Bavaria and North Rhine-Westphalia anchor European demand for pharmaceutical-grade effervescent lines with batch-level traceability requirements. The EU F-Gas Regulation and REACH compliance frameworks mandate acid-base chemistry substitutions and cleaner effluent protocols. HERMES PHARMA GmbH and Bayer AG facilities in Frankfurt-Rhine-Main and Leverkusen concentrate formulation expertise and pharmaceutical-grade manufacturing capacity.
United States
Athletes and fitness consumers in California and Texas are consolidating purchase decisions around rapid electrolyte delivery formats that bypass traditional pharmacy channels. FDA bioequivalence pathways govern pharmaceutical-grade claims while dissolution testing standards determine certification timelines. Hospital systems in Greater Boston and the Research Triangle source healthcare-grade effervescent lines from pharmaceutical manufacturing scale suppliers.
Japan
Aging populations in Kanto and Kansai regions drive demand for rapid-disintegration pediatric and geriatric formulations where swallowing conventional tablets presents adherence barriers. METI and PMDA frameworks regulate pharmaceutical-grade stability and dissolution benchmarks. Long-term care facilities in Tokyo-Osaka corridor adopt lyophilization-based formats at accelerating rates for dysphagia management.
Australia
Performance-oriented consumption cultures in New South Wales and Victoria prioritize convenience and personalization over brand loyalty in sports nutrition procurement. TGA dissolution and stability standards set market access benchmarks for imported formulations. Team-based bulk channels and direct subscription models in Sydney and Melbourne are displacing traditional retail volumes for electrolyte-focused formats.
India
Price-sensitive wellness consumers in Maharashtra and Gujarat create white space for cost-optimized generic effervescent formats through underpenetrated retail pharmacy distribution. CDSCO and FSSAI govern pharmaceutical-grade and wellness-positioned claims respectively. Pharmacy chains in Mumbai-Ahmedabad corridor concentrate procurement through centralized generic purchasing for daily adherence convenience.
Global Effervescent Tablet Market Competitive Landscape
Player mix skews toward pharmaceutical conglomerates with captive manufacturing scale and specialized effervescent formulation houses with regional expertise concentration. Tiered competitive structure separates healthcare-grade certification holders from wellness-positioned mass-market suppliers. Strategic archetypes include pharmaceutical-scale manufacturers leveraging hospital system relationships, generic specialists optimizing cost structures for pharmacy chains, and sports nutrition disruptors building direct subscription channels. Dominant competitive moves encompass capacity expansion in German and Swiss production hubs and strategic partnerships bridging formulation expertise with distribution reach.
Among pharmaceutical-scale manufacturers, Pfizer Inc., Bayer AG, and HERMES PHARMA GmbH occupy positions representing distinct competitive vectors. Pfizer exemplifies the healthcare-grade supplier archetype with hospital system relationships worldwide. Bayer represents the consumer brand recognition model spanning vitamin and pain relief effervescents across multiple continents. HERMES PHARMA anchors the specialized formulation expertise cluster with pharmaceutical-grade manufacturing concentration in German production hubs.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sandoz Group AG |
| Bayer AG |
| Vitaquest International |
| Perrigo Co. Plc |
| GlaxoSmithKline Plc |
| HERMES PHARMA GmbH |
| Handian Nutrition |
| Reckitt Benckiser Group Plc |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for citric acid and sodium bicarbonate lock in supply access and price visibility for German and Swiss pharmaceutical-grade manufacturers, insulating them from spot market volatility while compressing margin flexibility for generic producers dependent on variable input costs.
Pricing Analysis
Cost-plus contracts with citric acid indexation dominate pharmaceutical-grade procurement, anchoring price stability for Bayer AG and HERMES PHARMA GmbH facilities. Three-tier pricing structure across lyophilization, direct compression, and wet granulation tiers reflects certification grade and dissolution speed specifications. Pricing pressure stems from REACH-mandated chemistry substitutions that reformulate acid-base matrices at elevated R&D cost. Pharmacy chains in India exhibit highest price sensitivity, while hospital systems in Japan accept premium positioning for rapid-disintegration formats.
Supply Chain Analysis
Strait of Malacca transit for sodium bicarbonate feedstock from Chinese chemical parks underwrites cost structures for Asian generic manufacturers, creating logistics vulnerability for European formulation hubs. Raw material dependencies center on citric acid from Brazilian fermentation facilities, sodium bicarbonate from Solvay's European soda ash operations, and specialty packaging films from South Korean converters. Single-source vulnerability concentrates in pharmaceutical-grade acid suppliers certified under EU F-Gas Regulation. Distribution runs through pharmacy chain central purchasing in Germany, hospital GPO contracts in the United States, and direct-to-athlete subscription platforms in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as sports nutrition procurement fragments demand across performance-oriented formats, creating niches between pharmaceutical-grade certification holders and mass-market vitamin suppliers.
For Market Incumbents: Compound formulation expertise advantages by acquiring lyophilization capacity in Switzerland and securing exclusive sodium bicarbonate offtake from verified sustainable suppliers. Freeze-drying equipment scarcity threatens margin-rich geriatric segments; backward integration into acid-base raw material processing defends cost position against REACH-driven chemistry substitution costs. For New Entrants and Emerging Players: Direct-to-athlete subscription fulfillment gaps expose under-served performance consumers in Australian and North American markets. White space concentrates in personalized electrolyte dosing platforms and team-based bulk procurement channels. Penetrate through sports nutrition specialty retail partnerships before scaling to pharmacy distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sports nutrition subscription platforms with consumption data capture capabilities. Long-term viability favors specialized formulation houses with pharmaceutical-grade certification and captive lyophilization capacity. Monitor FDA-EMA bioequivalence pathway convergence as inflection signal for multi-jurisdictional product launch economics.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Captures geriatric nutrition margin pool in Japanese long-term care facilities requiring sub-30-second disintegration. |
| REACH-Compliant Chemistry Reformulation | Secures EU market access under F-Gas Regulation mandates prohibiting legacy effervescent effluent protocols. |
| Direct-to-Athlete Subscription Launch | Bypasses pharmacy channel margin compression through recurring revenue models in Australian performance markets. |
| Indian Pharmacy Chain Penetration | Exploits under-distributed generic effervescent white space through centralized purchasing in Mumbai-Ahmedabad corridor. |
| Sustainable Sourcing Certification | Differentiates sodium bicarbonate supply under EU Green Deal chemical sustainability targets for biodegradable matrices. |
Research Methodology
Operator-level perspectives from pharmaceutical formulation chemists, hospital formulary directors, sports nutrition procurement managers, and pharmacy chain category buyers anchored the qualitative base. Primary interviews combined with secondary validation from FDA bioequivalence filings, EMA centralized procedure documentation, REACH substance registration databases, and national pharmacopeia dissolution standards. Bottom-up capacity modeling across German and Swiss production hubs triangulated against top-down demand segmentation.
Sensitivity analysis tested input cost volatility scenarios for citric acid and sodium bicarbonate across the projection horizon. The analytical framework modeled product type, formulation technology, application sector, and end consumer type dimensions. CAGRs derived from volume trajectory analysis incorporating regulatory chemistry substitution timelines and channel shift elasticity. Forecast inputs included lyophilization equipment installation rates and sports nutrition subscription adoption curves.
Forecasts assume regulatory continuity in FDA bioequivalence pathways and EMA centralized procedures; material policy shifts would require re-modeling certification timeline assumptions. REACH chemical restriction expansion and F-Gas Regulation enforcement intensity represent specific risk factors that could revise capacity expansion forecasts. Practitioners should keep alternative scenarios live as trans-Atlantic regulatory divergence and green chemistry mandate acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Herbal Tincture Market