
 Hair Supplements Market | 2026-2036
Hair Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Supplements Market Outlook
The end-use vertical mix is broadening beyond aging consumers toward younger demographics seeking preventive hair health solutions. GNC Holdings, Inc. leverages its retail footprint and sports nutrition heritage to cross-sell into men's hair wellness. Nature's Bounty sustains mass-market dominance through pharmacy and supermarket shelf presence across North America. Nutraceutical Wellness Inc. (Unilever) competes by integrating hair supplements into broader beauty and personal care portfolios.
Hair supplements are oral nutritional products containing biotin, zinc, iron, marine collagen, and saw palmetto extracts, formulated to support keratin synthesis, follicle cycling, and scalp microcirculation. These products serve both cosmetic appearance goals and dermatological adjuvant therapy in clinical hair loss management. The vitamins segment anchors the market due to established consumer familiarity with biotin and B-complex formulations, while gummies represent the fastest-growing form as palatability drives compliance among younger users. Online retail channels capture expanding margin pools by bypassing traditional wholesale markups and enabling subscription-based recurring revenue models.
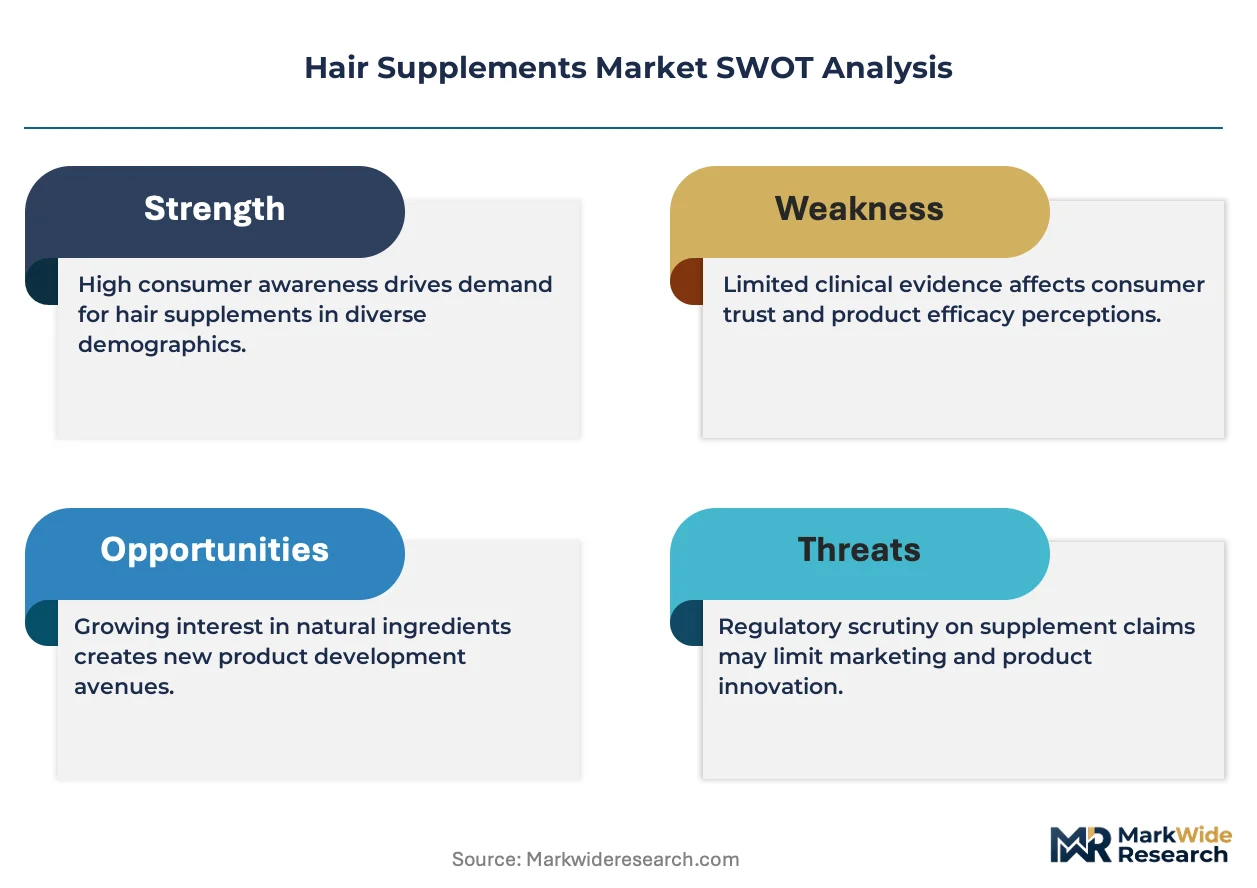
The FDA's dietary supplement CGMP rules and the EU's Nutrition and Health Claims Regulation constrain marketing language and mandate substantiation for structure-function claims. China's NMPA and SAMR enforce stricter cross-border e-commerce rules for imported health products, reshaping market entry strategies for foreign brands. Stakeholders must monitor evolving substantiation standards for botanical ingredients and adapt channel strategies as pharmacy, specialty store, and direct-to-consumer platforms fragment across regulatory jurisdictions.
Market Dynamics
Direct-to-consumer digital channels are compressing traditional wholesale margins while elevating subscription-based recurring revenue models as the dominant commercial architecture for hair supplement distribution.
Growth Catalysts
- CGMP Enforcement:The FDA's dietary supplement Current Good Manufacturing Practice rules are elevating quality standards that weed out marginal suppliers and consolidate trust around substantiated brands.
- Preventive Wellness Pivot:Women aged 25-45 are driving category expansion as self-directed purchasing replaces reactive treatment-seeking for hair health maintenance.
- Marine Collagen Bioavailability:Advances in hydrolyzed peptide extraction are improving keratin synthesis efficacy and expanding clinical adjuvant applications.
Market Restraints
- Ingredient Substantiation Costs:The EU's Nutrition and Health Claims Regulation mandates expensive clinical validation for structure-function claims, raising barriers for botanical entrants.
- Cross-Border Friction:China's SAMR enforcement of stricter e-commerce rules for imported health products is complicating market access for foreign brands.
- Iron Formulation Instability:Oxidation sensitivity in mineral complexes limits shelf life and complicates gummy matrix compatibility.
Strategic Opportunities
- Professional Salon Channel:Trichologist and dermatologist recommendation networks remain underexploited for clinical-grade formulations in Germany and the United States.
- Men's Segment White Space:Saw palmetto and DHT-blocking formulations targeting androgenetic alopecia show penetration gaps versus women's biotin dominance.
- Subscription Personalization:AI-driven hair health assessments paired with customized nutrient stacks are creating retention moats in direct-to-consumer platforms.
Industry Challenges
- Regulatory Fragmentation:Divergent substantiation standards across FDA, EFSA, and NMPA jurisdictions force redundant clinical investments for global launches.
- Supply Chain Reconfiguration:Botanical raw material sourcing from multiple origins complicates batch consistency and traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Supplements Market |
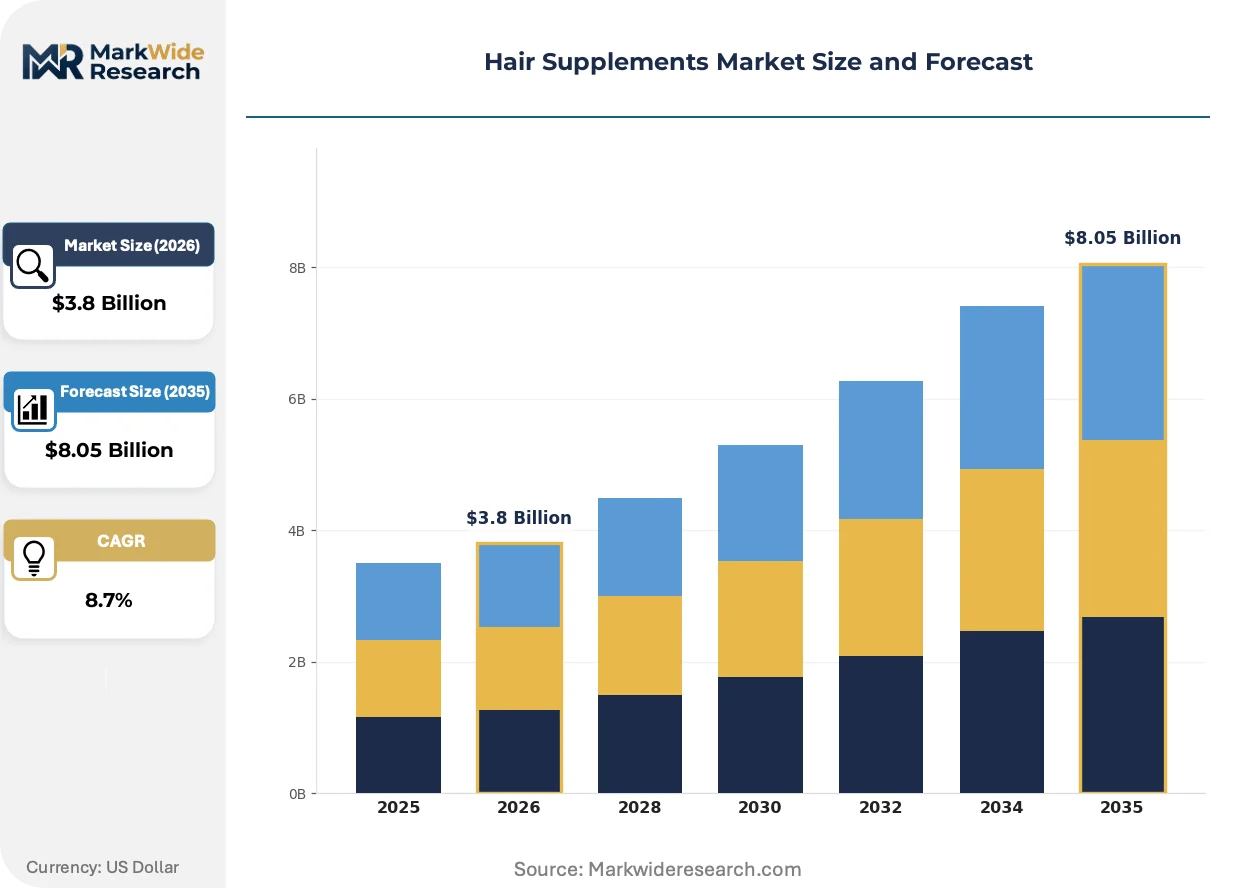
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids Form: Tablets, Capsules, Powders, Gummies Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores End User: Women, Men, Children, Seniors |
| Companies Covered | GNC Holdings, Inc., Nature's Bounty, Nutraceutical Wellness Inc. (Unilever), Swisse Wellness, Herbalife Nutrition Ltd., Viviscal Limited (Church & Dwight), Nutrafol, InVite Health, Amway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Supplements Market Strategic Shifts
Microbiome science and at-home diagnostic integration are redefining how consumers personalize hair nutrition regimens beyond generic multivitamin formulations.
At-home trichoscopy devices paired with smartphone applications are decentralizing follicle health assessment from clinical dermatology offices to consumer bathrooms. Women in the 25-45 demographic are adopting these diagnostic tools fastest, with subscription services bundling imaging hardware with customized supplement protocols. This shift is decentralizing professional gatekeeping over hair loss treatment initiation and compressing the path from symptom recognition to product purchase.
REACH enforcement on novel botanical extracts is tightening safety data requirements for European market entry, particularly for Ayurvedic and Traditional Chinese Medicine ingredients. Manufacturers must now submit full toxicological dossiers that were previously accepted under mutual recognition. Small and mid-sized brands dependent on rapid ingredient cycling are responding by narrowing portfolios to GRAS-listed compounds or acquiring existing safety dossiers.
Pharmacy channel buyers are consolidating around private-label gummy formulations that replicate mass-market leader ingredient decks at 30-40% price points. This preference compression is displacing branded shelf space in CVS, Walgreens, and Boots locations across the United States and United Kingdom. The shift is most visible in urban markets where younger consumers prioritize palatability compliance over legacy brand loyalty.
Hair Supplements Market Segmentation
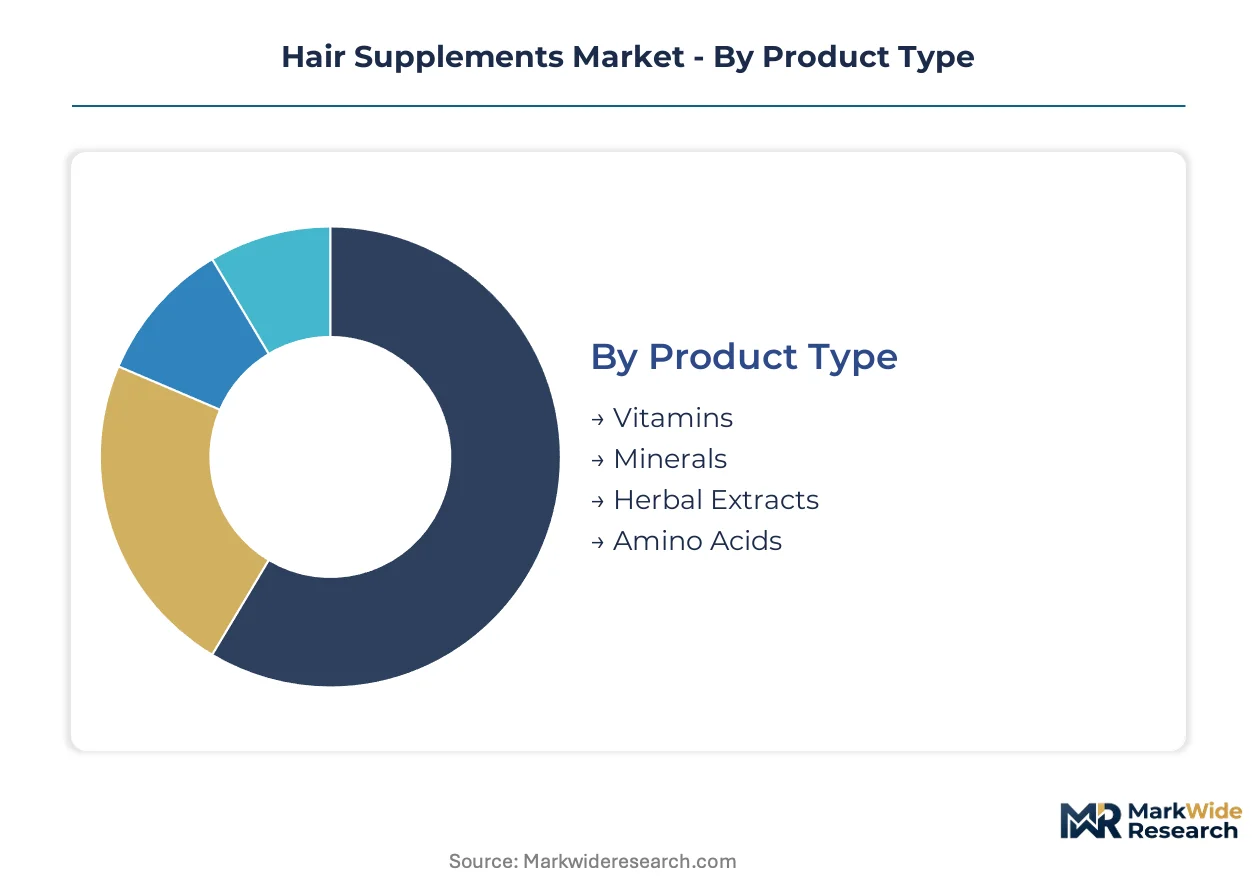
Hair supplement segmentation reveals how formulation science, consumption preferences, and channel economics fragment commercial opportunity across distinct buyer journeys. Understanding these divides enables targeted positioning against divergent compliance behaviors and purchasing triggers.
Product Type:
Vitamin and mineral complexes anchor the technical specification hierarchy, with bioavailability profiles determining clinical adjuvant utility versus cosmetic positioning.
- Vitamins:Biotin and B-complex formulations dominate shelf presence due to established consumer literacy around keratin synthesis support. Demand concentrates among women aged 25-45 in the United States and Germany, where self-directed preventive purchasing has displaced reactive dermatologist visits.
- Minerals:Iron and zinc complexes address documented deficiencies in follicle cycling disruption, though oxidation sensitivity constrains gummy matrix compatibility. China and India drive volume for mineral-focused SKUs as traditional medicine frameworks prioritize elemental supplementation over botanical approaches.
- Herbal Extracts:Saw palmetto and horsetail formulations target DHT modulation and silica-driven tensile strength, with European EFSA substantiation requirements raising clinical validation barriers for Ayurvedic entrants.
- Amino Acids:Cysteine and methionine precursors support disulfide bond formation in keratin architecture, finding niche adoption among salon-channel professional recommendations.
Vitamins lead on scale; herbal extracts lead on momentum as botanical substantiation investments mature.
Form:
Delivery mechanism selection reflects compliance psychology and matrix stability constraints across demographic segments.
- Tablets:Compressed mineral and vitamin matrices offer cost-efficient manufacturing and extended shelf stability. Germany and Japan maintain disproportionate tablet preference due to pharmacy-channel professional endorsement patterns.
- Capsules:Gelatin and vegetable-shell encapsulation protects oxidation-sensitive actives like iron and marine collagen. The United States dominates capsule volume through direct-to-consumer subscription platforms that emphasize clinical-grade positioning.
- Powders:Bulk collagen and protein blends integrate into functional beverage routines, with China driving adoption via cross-border e-commerce channels targeting younger male consumers.
- Gummies:Palatability-driven compliance has propelled gummies to the steepest expansion trajectory, particularly among women aged 25-45 prioritizing adherence over legacy format loyalty.
Tablets lead on scale; gummies lead on momentum.
Distribution Channel:
Channel selection determines margin architecture and customer acquisition economics, with digital platforms compressing traditional wholesale structures.
- Online Retail:Direct-to-consumer platforms capture expanding margin pools through subscription-based recurring revenue models, bypassing pharmacy and supermarket markups. FDA CGMP compliance and EU novel food substantiation requirements filter marginal suppliers from premium digital positioning.
- Pharmacies:CVS, Walgreens, and Boots locations consolidate around private-label gummy formulations replicating mass-market ingredient decks at reduced price points, displacing branded shelf space in urban United States and United Kingdom markets.
- Supermarkets:Mass-market vitamin SKUs depend on Nature's Bounty heritage presence across North American retail footprints, with impulse placement driving trial among non-condition-specific buyers.
- Specialty Stores:GNC Holdings leverages sports nutrition heritage to cross-sell men's hair wellness formulations, while professional salon networks in Germany and the United States remain underexploited for clinical-grade trichologist recommendations.
Online retail leads on momentum; pharmacies lead on absolute volume.
End User:
Demographic targeting reflects divergent hair loss etiologies and purchasing autonomy patterns across life stages.
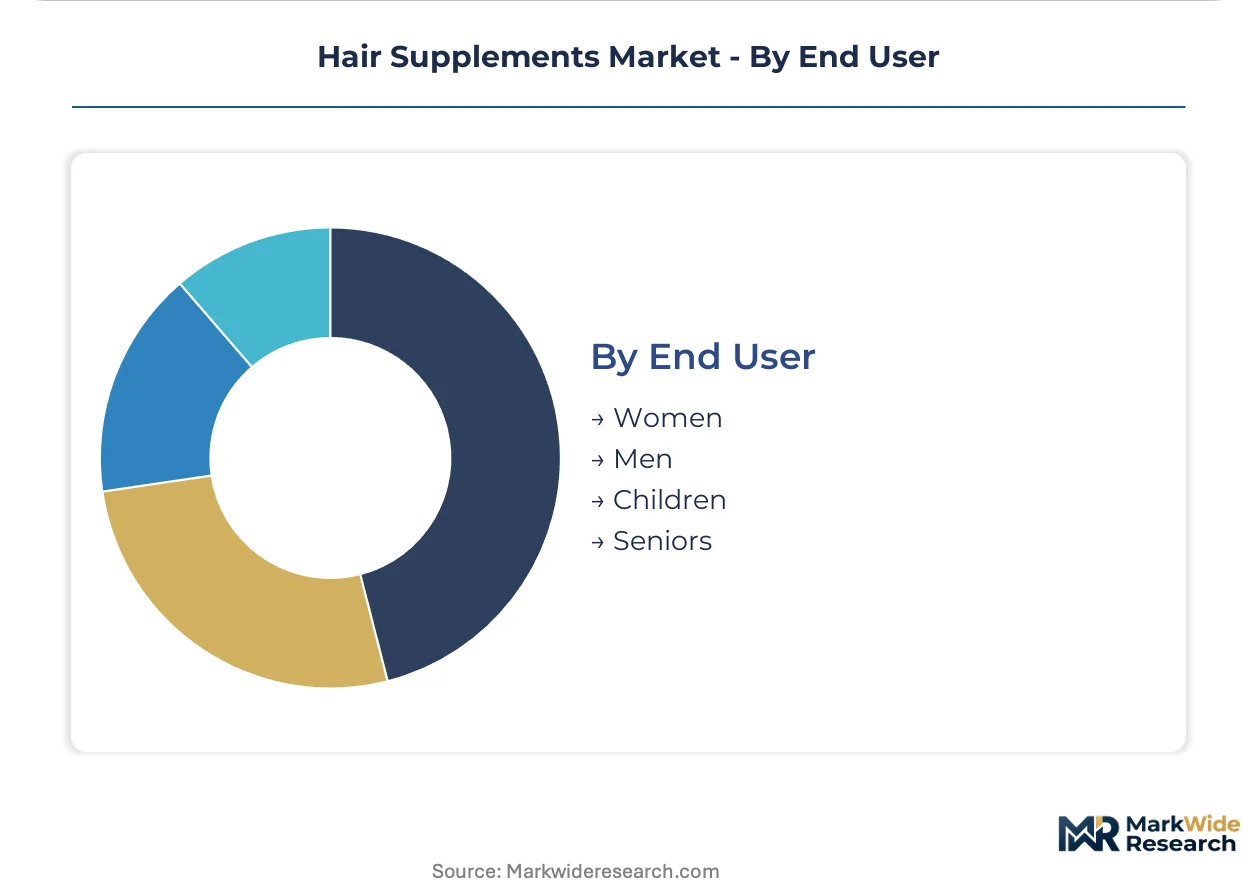
- Women:The 25-45 age bracket drives category expansion through preventive wellness pivoting, with biotin familiarity and at-home diagnostic tool adoption accelerating self-directed purchase initiation.
- Men:Saw palmetto and DHT-blocking formulations show penetration gaps versus women's biotin dominance, presenting white space for androgenetic alopecia-specific positioning in the United States and China.
- Children:Pediatric formulations concentrate on iron and zinc deficiency correction in India and China, where nutritional screening programs identify subclinical insufficiencies affecting hair texture indicators.
- Seniors:Age-related thinning drives collagen and keratin peptide demand in Japan and Germany, with pharmacy-channel professional endorsement remaining critical for purchase confidence.
Women lead on scale; men lead on momentum as gender-specific formulation science matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as brands relocate production to jurisdictions with lower substantiation-cost burdens while maintaining premium positioning in high-enforcement markets.
United States
Direct-to-consumer subscription platforms and pharmacy-channel private-label consolidation drive volume concentration. FDA CGMP enforcement elevates quality barriers that marginal suppliers cannot clear. Los Angeles and New York City anchor influencer-marketing ecosystems that compress customer acquisition timelines for digital-native brands.
China
Cross-border e-commerce demand from younger male consumers accelerates collagen powder adoption through Tmall Global and JD Worldwide channels. NMPA and SAMR enforcement of stricter import rules forces foreign brands toward domestic registration or partnership structures. Shanghai and Hangzhou concentrate brand-operating subsidiaries serving mainland market entry.
Germany
Pharmacy-channel professional endorsement patterns sustain tablet-format preference among older demographics seeking clinical-grade positioning. EFSA substantiation requirements under the Nutrition and Health Claims Regulation filter botanical entrants without full toxicological dossiers. Munich and Berlin host trichologist networks that remain underexploited for professional recommendation channel development.
India
Pediatric iron and zinc formulations address nutritional screening program findings in subclinical deficiency populations. FSSAI standards enforcement tightens manufacturing quality expectations for domestic and imported SKUs alike. Mumbai and Bangalore concentrate contract manufacturing capacity serving price-sensitive mass-market distribution.
Japan
Age-related collagen and keratin peptide demand concentrates among senior demographics requiring pharmacy-channel purchase confidence. METI and PMDA oversight maintains rigorous stability and efficacy documentation standards. Tokyo and Osaka anchor retail pharmacy chains that professionalize supplement consultation for hair wellness categories.
Hair Supplements Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents cross-sell from adjacent wellness categories into hair-specific positioning. The market structure reflects tiered consolidation around mass-market heritage brands, beauty-portfolio integrators, and direct-to-consumer specialists. Three archetypes define competitive positioning: retail-heritage mass marketers, beauty-conglomerate portfolio players, and digital-native subscription operators. M&A activity and channel-specific formulation development represent the dominant competitive vectors as players defend shelf space against private-label encroachment.
Within the retail-heritage tier, GNC Holdings, Inc. and Nature's Bounty exemplify mass-market incumbents leveraging established pharmacy and supermarket footprints to maintain visibility against private-label displacement. Nutraceutical Wellness Inc. (Unilever) occupies a position representing beauty-conglomerate integration strategies that embed hair supplements within broader personal care portfolios. These three anchors illustrate how divergent channel strategies—specialty retail, mass-market shelf presence, and beauty-ecosystem bundling—create distinct competitive moats despite overlapping ingredient formulations.
| Leading Market Players |
|---|
| GNC Holdings, Inc. |
| Nature's Bounty |
| Nutraceutical Wellness Inc. (Unilever) |
| Swisse Wellness |
| Herbalife Nutrition Ltd. |
| Viviscal Limited (Church & Dwight) |
| Nutrafol |
| InVite Health |
| Amway |
| Others |
Value Chain & Pricing Dynamics
Peptide chemist concentrations in South Korea and coastal China create labor-cost differentials that widen pricing-tier spreads between clinical-grade marine collagen formulations and commodity biotin gummies.
Pricing Analysis
Retailer markup compression in pharmacy channels is intensifying as CVS and Boots private-label gummies replicate mass-market ingredient decks at reduced price points. Three-tier pricing structure across premium, standard, and economy levels separates subscription-based DTC capsules with full CGMP documentation from supermarket impulse SKUs and unbranded bulk powders. Pricing pressure stems from iron formulation instability that limits gummy matrix compatibility and raises manufacturing yield losses. Price-sensitive buyers concentrate in urban United States pharmacy channels, while least-sensitive segments pay premiums for salon-channel professional endorsement in Germany.
Supply Chain Analysis
Single-source vulnerability sits with hydrolyzed marine collagen extraction concentrated in South Korea, Japan, and Norway coastal processing facilities. Botanical raw material sourcing from India, China, and Peru complicates batch consistency for saw palmetto and horsetail extracts. Supply chain risk centers on REACH enforcement tightening toxicological dossier requirements for Ayurvedic entrants into European markets. Distribution runs through direct-to-consumer subscription platforms bypassing traditional wholesale markups, with pharmacy and specialty retail channels fragmenting across regulatory jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FDA CGMP enforcement and EFSA substantiation requirements filter marginal suppliers, justifying demand-shift toward clinically documented keratin synthesis formulations over generic multivitamin positioning.
For Market Incumbents: Lock in trichologist and dermatologist recommendation networks in Germany and the United States before digital-native competitors consolidate professional channel access. Acquire GRAS-listed safety dossiers to accelerate botanical ingredient cycling under REACH enforcement. Vertical integration into hydrolyzed peptide extraction in South Korea secures marine collagen supply against single-source vulnerability. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms with AI-driven hair health assessments offer the most penetrable white-space entry against legacy mass-market brands. Target men's DHT-blocking formulations in China and the United States where saw palmetto penetration lags women's biotin dominance. Launch with at-home trichoscopy device bundling to compress path from symptom recognition to purchase initiation. For Investors and Strategic Acquirers: Beauty conglomerates with personal care portfolio integration capabilities are the most active acquirer in this space, seeking clinical-grade supplement assets to complement topical hair wellness positioning. Long-term viability hinges on substantiation investment amortization across multi-jurisdiction regulatory filings. Watch for NMPA domestic registration completion rates as inflection signal for China market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Certification Investment | FDA CGMP compliance and EFSA dossier completion filters marginal competitors from premium positioning. |
| Direct-to-Consumer Platform Launch | Subscription recurring revenue models bypass pharmacy markup compression and capture expanding margin pools. |
| Professional Salon Channel Expansion | Trichologist recommendation networks in Germany and the United States remain underexploited for clinical-grade formulations. |
| Men's Segment Formulation Development | Saw palmetto and DHT-blocking positioning addresses penetration gaps versus women's biotin dominance. |
| AI-Driven Personalization Integration | At-home diagnostic bundling with customized nutrient stacks creates retention moats against commodity competitors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, trichologists, pharmacy category buyers, and DTC platform operators alongside secondary validation from FDA warning letters, EFSA health claim opinions, NMPA registration databases, and customs import records. Bottom-up SKU-level demand modeling triangulated against top-down category spend estimates.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation dimensions spanning product type, delivery form, distribution channel, and end-user demographic. CAGRs derived from fitted growth curves incorporating marine collagen bioavailability advances, regulatory enforcement intensity indices, and channel-shift velocity parameters.
Regulatory enforcement timing, botanical substantiation cost inflation, and cross-border e-commerce policy shifts are the dominant revision risks that could compress or extend forecast ranges. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Global Lipid Regulators Market