
 Womens Health and Beauty Supplements Market | 2026-2036
Womens Health and Beauty Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Womens Health and Beauty Supplements Market Intelligence
Single-serve sachets and subscription bundles is pivoting how women discover and replenish beauty supplements. Amway Corporation leverages its direct-selling infrastructure to sustain recurring purchase patterns across Asia-Pacific markets. Herbalife Nutrition Ltd. anchors its portfolio with personalized nutrition coaching that locks in brand loyalty. Bayer AG competes through pharmacy-grade positioning that commands trust among peri-menopausal buyers.
Womens health and beauty supplements comprise orally administered formulations containing bioactive compounds such as collagen peptides, hyaluronic acid, ceramides, and phytoestrogens, manufactured through spray-drying, microencapsulation, or fermentation processes to preserve stability and bioavailability. These products serve the commercial purpose of addressing dermatological, metabolic, and endocrine concerns through systemic nutrient delivery rather than topical application. Collagen and probiotics dominate current revenue pools due to established clinical visibility and repeat-purchase behavior, while herbal extracts capture the fastest expansion as adaptogenic positioning gains traction in specialty retail. Gummies and powders are displacing traditional tablets among younger demographics, reshaping manufacturing capacity allocation and flavor-system R&D spend.
The US FDA and the FTC jointly govern label claims and advertising substantiation for dietary supplements, creating compliance costs that favor scaled manufacturers with in-house regulatory teams. The EU EFSA and the EU Green Deal's packaging directives are mandating recycled-content thresholds and restricted substance lists that reshape formulation and sourcing decisions for brands selling into European markets. Stakeholders must monitor how evolving pharmacovigilance databases and class-action litigation trends around hormone-active ingredients reshape product liability exposure and insurance costs.
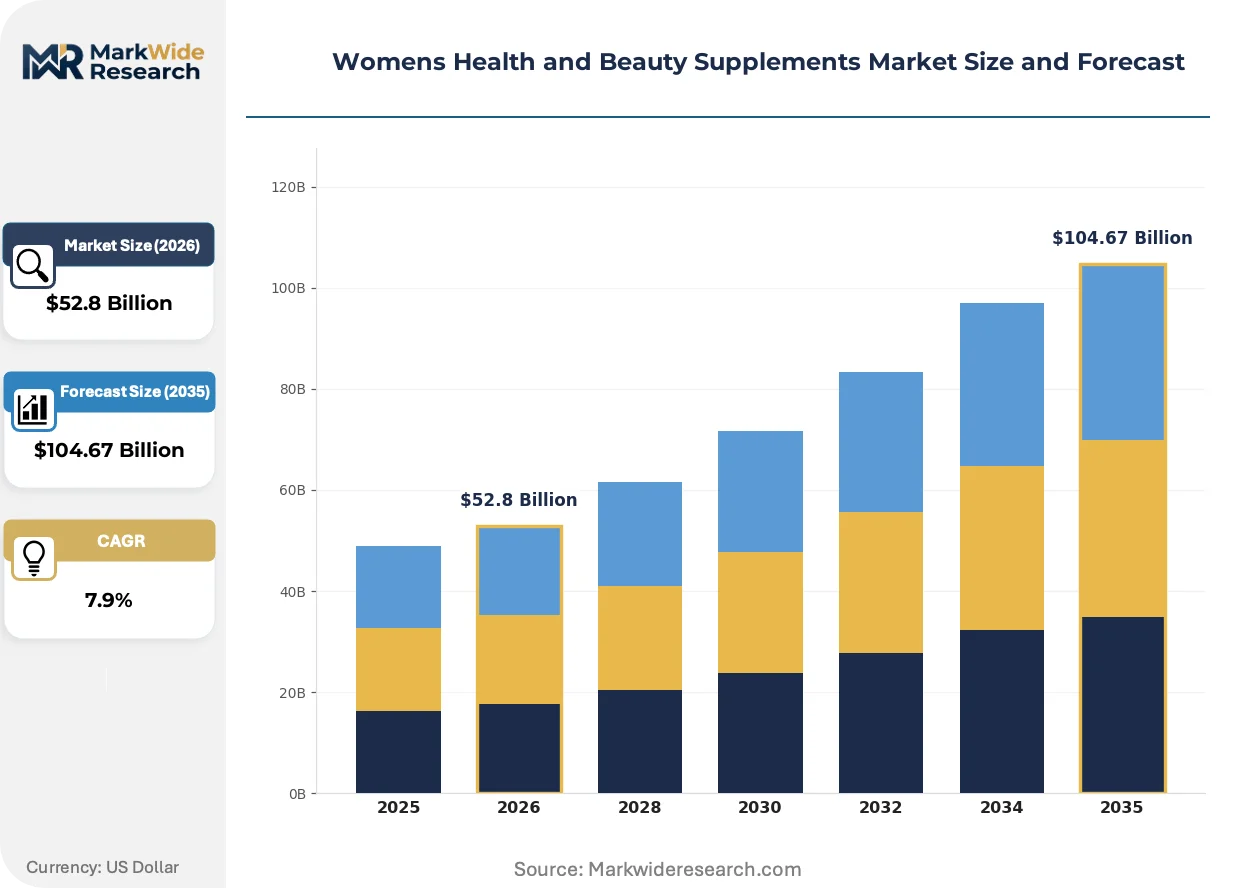
Market Dynamics
Cross-border e-commerce platforms are compressing traditional distribution hierarchies in womens health and beauty supplements, enabling direct manufacturer-to-consumer relationships that bypass pharmacy and specialty retail gatekeepers entirely.
Growth Catalysts
- Collagen peptide bioavailability advances:Microencapsulation and liposomal delivery technologies are expanding therapeutic claims substantiation for dermal hydration and joint mobility applications.
- China SAMR cross-border e-commerce pathways:Pilot zone regulations for bonded import and direct shipping are accelerating foreign brand market access without domestic registration requirements.
- Peri-menopausal demographic concentration:Hormone-active ingredient demand from women aged 45-55 is pulling phytoestrogen and adaptogenic formulations into mainstream retail placement.
Market Restraints
- Marine collagen supply concentration:Over 70% of hydrolyzed collagen derives from Vietnamese and Indonesian tilapia and pangasius processing facilities, creating single-source vulnerability.
- EFSA health claims substantiation costs:The European Food Safety Authority's randomized controlled trial requirements for beauty-from-within claims impose six-figure clinical study barriers for mid-scale entrants.
- Plant-based protein substitution threat:Pea and rice protein isolates are capturing formulation share in meal-replacement positioning, diverting R&D budgets from beauty-specific bioactives.
Strategic Opportunities
- Menopausal hormone therapy adjacency:Co-development with gynecological pharmaceutical pipelines positions supplements as adjuvant or tapering protocols in Germany and France.
- AI-driven personalization engines:Integration of microbiome sequencing and skin diagnostic data is enabling subscription models with dynamic formulation adjustments based on biomarker feedback.
- India PLI scheme for nutraceutical manufacturing:Production-linked incentive structures for fermentation-derived ingredients reduce capital intensity for domestic collagen and hyaluronic acid facilities.
Industry Challenges
- Pharmacovigilance database integration:Spontaneous adverse event reporting systems in the US and EU require real-time signal detection capabilities that strain quality assurance headcount.
- Legacy ERP-to-e-commerce platform interoperability:Direct-to-consumer fulfillment demands are forcing reformulation of batch tracking and expiration management workflows originally designed for wholesale distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Womens Health and Beauty Supplements Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $104.67 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Probiotics, Herbal Extracts, Collagen Application: Skin Care, Hair Growth, Weight Management, Hormonal Balance Form: Tablets, Gummies, Powders, Capsules Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets |
| Companies Covered | Amway Corporation, Herbalife Nutrition Ltd., GNC Holdings, Inc., Bayer AG, The Nature’s Bounty Co., Nestlé Health Science, Blackmores Limited, Swisse Wellness Pty Ltd., Pharmavite LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Womens Health and Beauty Supplements Market Strategic Shifts & Innovations
Biotechnology-enabled ingredient sourcing and regulatory science advances are converging to expand permissible health claims while compressing development timelines for novel bioactive delivery systems.
Liposomal encapsulation technology is electrifying nutrient stability and cellular uptake metrics for fat-soluble vitamins and polyphenols. Premium skincare-cosmetic hybrid brands in Seoul and Shanghai are adopting this format for oral beauty SKUs within 18-month innovation cycles. The structural consequence is a capacity crunch in pharmaceutical-grade phospholipid supply chains originally scaled for injectable drug delivery.
REACH Annex XVII restricted substance list updates are forcing reformulation of preservative systems and coating materials for European market access. The ECHA evaluation of endocrine-disrupting properties in common tablet excipients is accelerating migration toward clean-label positioning even in conventional pharmacy channels. German and Dutch contract manufacturers are absorbing the compliance burden through dedicated regulatory affairs subsidiaries.
Subscription-based replenishment models are displacing episodic retail purchase patterns among urban millennial and Gen Z cohorts. Direct-to-consumer platforms with predictive algorithmic reordering are capturing lifetime value metrics that traditional wholesale relationships cannot match. This behavioral shift is most pronounced in Shanghai, Tokyo, and New York metropolitan corridors where same-day or next-day delivery infrastructure supports just-in-time inventory psychology.
Womens Health and Beauty Supplements Market Segmentation
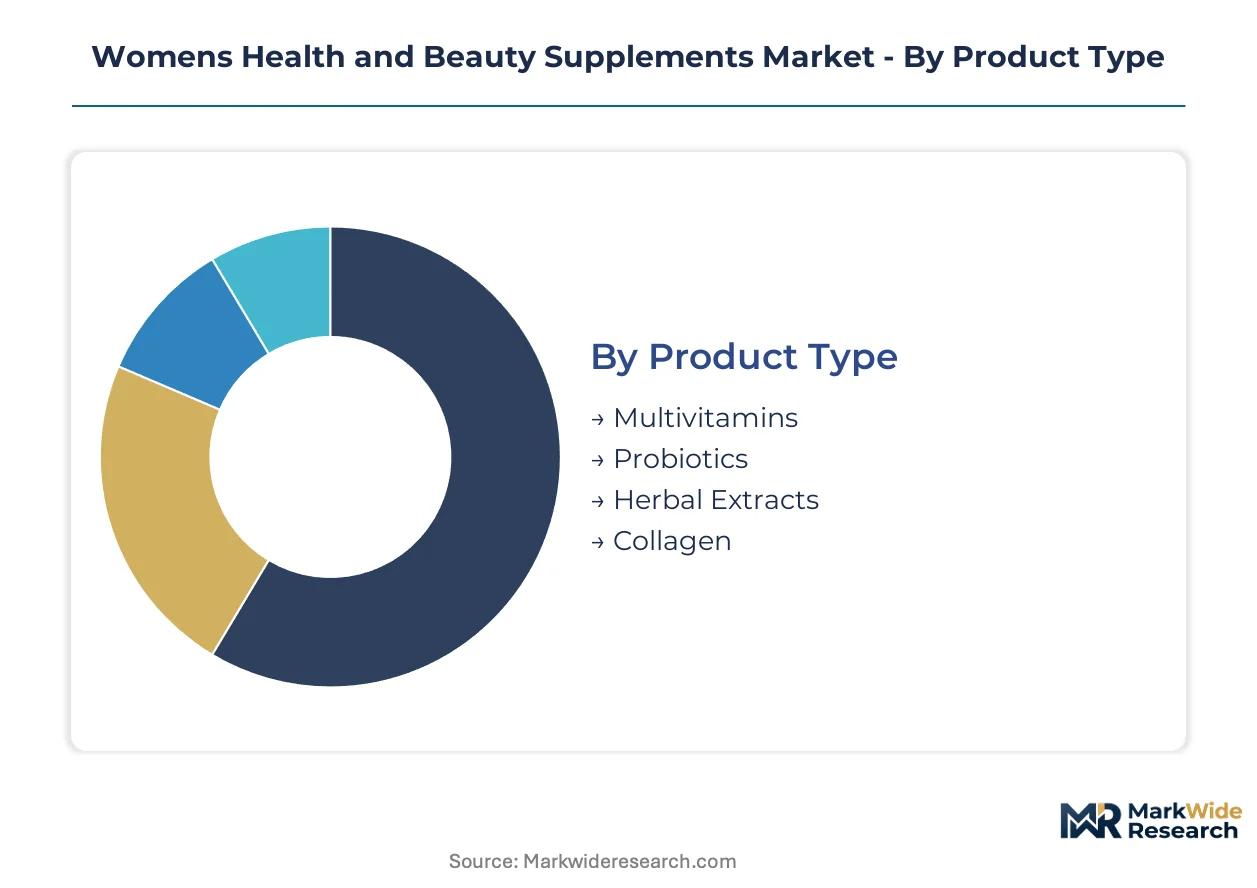
Segmentation in womens health and beauty supplements reveals how formulation complexity, delivery format preferences, and channel economics fragment competitive strategy. Manufacturers must align R&D investment, regulatory dossiers, and supply chain configurations to the specific compliance burdens and margin profiles of each segment cluster.
Product Type:
Certification requirements diverge sharply across product type segments, with collagen peptides triggering novel food dossiers in the EU and probiotic strains demanding strain-specific safety substantiation under EFSA guidelines. Herbal extracts face the heaviest pharmacovigilance obligations due to hormone-active compound variability.
- Collagen:Hydrolyzed peptide formulations derived from marine or bovine sources require allergen labeling protocols and halal/kosher certification for Middle Eastern and Israeli market access. Demand concentrates in Chinese cross-border e-commerce channels where Korean and Japanese brands command premium positioning through clinical substantiation of dermal elasticity claims.
- Probiotics:Live microbial cultures with documented CFU counts at end-of-shelf-life necessitate cold-chain logistics or advanced stabilization technologies. German pharmacy chains and French para-pharmacies represent the core volume concentration, driven by gastroenterologist recommendation networks and reimbursement adjacency for irritable bowel syndrome management.
- Herbal Extracts:Phytoestrogen and adaptogenic formulations face evolving restriction lists under REACH Annex XVII and California Proposition 65.
- Multivitamins:Broad-spectrum micronutrient blends compete primarily on price-per-day metrics in mass retail.
Collagen sits at the top of the volume ranking, with herbal extracts climbing the fastest.
Application:
Application segments stratify by customer lifetime value and reorder frequency, with hormonal balance commanding the highest per-user annual spend due to peri-menopausal demographic concentration. Skin care applications benefit from the strongest cross-category marketing synergies with topical beauty brands.
- Skin Care:Oral beauty positioning targeting dermal hydration and wrinkle reduction leverages clinical trial data from dermatology journals. Shanghai and Seoul metropolitan consumers drive premium tier adoption, with ingestible collagen and ceramide formats displacing topical-only regimens among millennials.
- Hormonal Balance:Phytoestrogen and vitex-based formulations address peri-menopausal symptom management with dosing protocols mimicking pharmaceutical hormone therapy tapering. French and German gynecological clinic recommendation networks anchor demand, with co-prescription models emerging in Swiss and Austrian markets.
- Hair Growth:Biotin and silica combinations compete in subscription-heavy direct-to-consumer channels with high churn and acquisition cost sensitivity.
- Weight Management:Fiber and thermogenic blends face the steepest regulatory scrutiny around metabolic claims in FDA and FTC enforcement actions.
Skin care captures the largest absolute volume, while hormonal balance gains share fastest on per-capita spend expansion.
Form:
Form selection determines manufacturing capital allocation, with gummy production requiring confectionery-grade equipment and powder formats demanding flavor-system R&D investment. Tablet and capsule segments retain pharmacy channel preference due to perceived clinical legitimacy.
- Gummies:Pectin and gelatin-based matrices with stability-protected active ingredients require moisture-barrier packaging and accelerated shelf-life testing. US and UK millennial consumers drive format displacement from tablets, with flavor innovation cycles compressing to six-month refresh schedules.
- Powders:Bulk collagen and protein blends enable flexible dosing and beverage fortification applications. Tokyo and New York fitness-oriented consumers concentrate demand, with single-serve sachet formats capturing travel and workplace consumption occasions.
- Tablets:Compressed formulations with enteric coatings dominate German and Japanese pharmacy placement due to reimbursement familiarity.
- Capsules:Two-piece hardshell and softgel formats accommodate oil-soluble actives with oxidation protection requirements.
Tablets retain volume leadership in pharmacy channels, with gummies expanding most quickly in direct-to-consumer platforms.
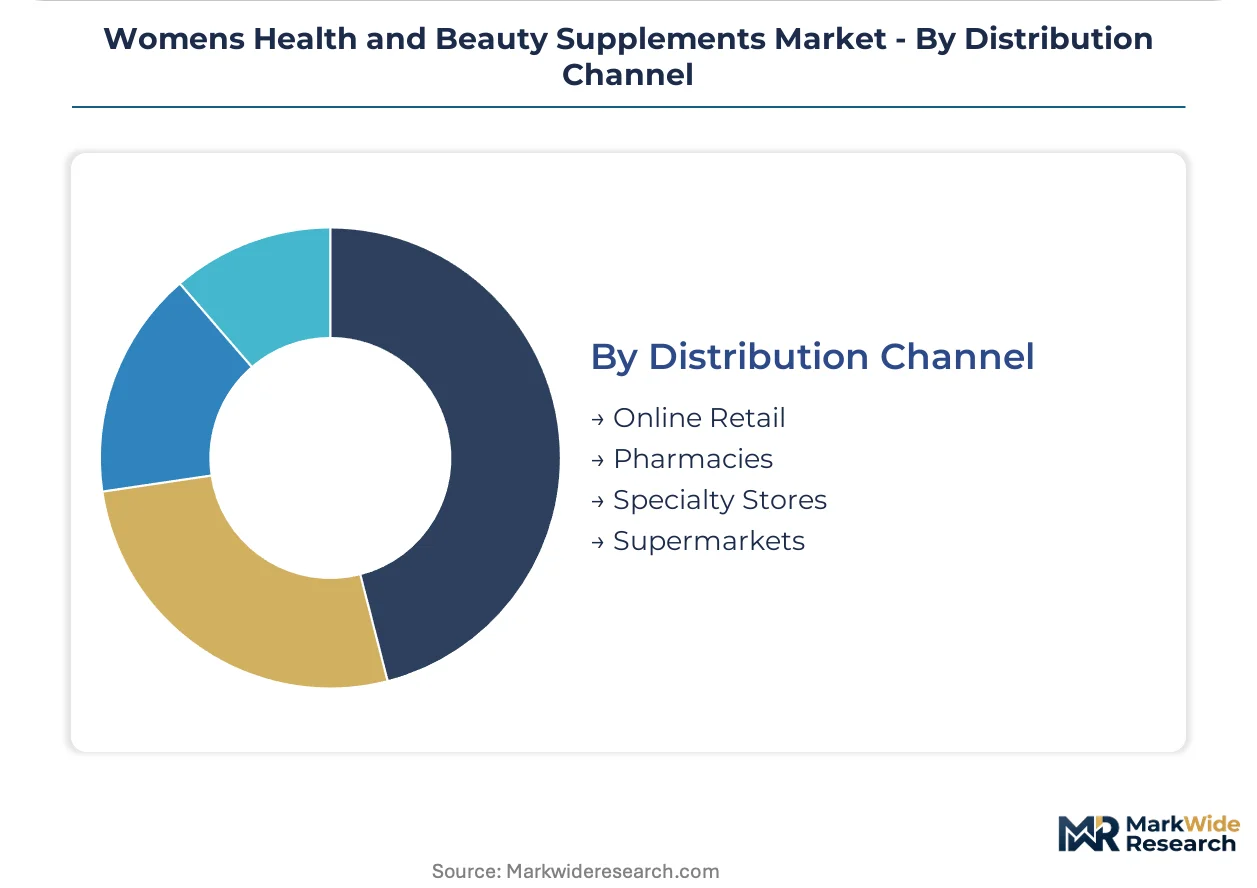
Distribution Channel:
Channel economics reshape margin structures and customer data access, with online retail enabling subscription mechanics and pharmacy channels demanding trade spend and clinical detailing investment. Specialty stores provide brand storytelling environments that mass retail cannot replicate.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts capture first-party purchase data enabling predictive replenishment algorithms. Chinese Tmall Global and cross-border flagship stores accelerate foreign brand entry without domestic registration, though SAMR compliance costs for livestreaming commerce are rising.
- Pharmacies:Brick-and-mortar dispensaries with pharmacist consultation services command trust among peri-menopausal and clinical-condition buyers. French and Italian pharmacy networks retain strong foot traffic, with para-pharmacy formats in Spain and Portugal expanding beauty supplement adjacencies.
- Specialty Stores:Sephora, Ulta, and Douglas beauty retail environments enable sampling and education-driven conversion for premium oral beauty SKUs.
- Supermarkets:Mass retail placement competes on price visibility and promotional intensity with limited consultation support.
Online retail sits at the top of the volume ranking, with specialty stores climbing the fastest on premium positioning and experiential merchandising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Direct-selling networks first scaled women's health supplements through suburban distribution models in the United States during the 1980s, establishing the recurring-purchase infrastructure that now dominates Asia-Pacific e-commerce channels.
United States
Millennial and Gen Z consumers in New York and Los Angeles metropolitan areas are accelerating adoption of gummy and powder formats over traditional tablets. The FDA and FTC jointly enforce label claims substantiation, creating compliance costs that favor manufacturers with in-house regulatory teams. Direct-to-consumer platforms in California's Silicon Valley corridor are pioneering AI-driven personalization engines that integrate microbiome sequencing data.
China
Cross-border e-commerce demand concentrates in Shanghai and Beijing, where domestic brands and foreign entrants compete through Tmall Global flagship stores. SAMR pilot zone regulations for bonded import enable market access without full domestic registration. Korean and Japanese collagen brands command premium positioning through clinical substantiation of dermal elasticity claims in these coastal metropolitan clusters.
Germany
Peri-menopausal women aged 45-55 drive phytoestrogen and adaptogenic formulation demand through pharmacy and para-pharmacy channels. EFSA health claims substantiation requirements impose clinical study barriers that reshape competitive entry dynamics. Bavarian and North Rhine-Westphalia manufacturing clusters host contract manufacturers with dedicated regulatory affairs subsidiaries absorbing REACH Annex XVII compliance burdens.
Japan
Functional food positioning of beauty supplements benefits from FOSHU regulatory familiarity among Tokyo and Osaka consumers. METI oversight of health claim categories enables faster product iteration than pharmaceutical pathways. Kanto region fermentation-derived ingredient facilities supply domestic collagen and hyaluronic acid production with advanced microencapsulation capabilities.
India
Urban millennial women in Maharashtra and Karnataka states are adopting subscription-based replenishment models through direct-to-consumer platforms. The PLI scheme for nutraceutical manufacturing reduces capital intensity for domestic fermentation facilities. Mumbai and Bangalore industrial corridors are attracting contract manufacturing investment for export-oriented collagen peptide production.
Womens Health and Beauty Supplements Market Key Industry Players
Premium-margin players sit above commodity-margin players across clinical substantiation and pharmacy-grade certification dimensions, creating a tiered structure where direct-selling infrastructure and personalized coaching capabilities separate recurring-revenue models from transactional retail placement. The vendor base clusters around three strategic archetypes: multinational pharmaceutical-grade manufacturers with regulatory dossier depth, direct-selling specialists with captive distributor networks, and digitally native brands with first-party data assets. Dominant competitive moves include M&A to acquire fermentation-derived ingredient capacity and strategic partnerships with dermatology clinic networks for co-prescription models.
Within the direct-selling archetype, Amway Corporation and Herbalife Nutrition Ltd. exemplify infrastructure-heavy positioning where recurring purchase patterns sustain lifetime value metrics that wholesale-dependent competitors cannot replicate. Bayer AG anchors the pharmaceutical-grade tier, occupying a position where pharmacy-channel trust among peri-menopausal buyers commands price premiums. These three entities represent the structural divergence between coaching-integrated distribution, clinical legitimacy, and scaled manufacturing that defines competitive fault lines in the sector.
| Leading Market Players |
|---|
| Amway Corporation |
| Herbalife Nutrition Ltd. |
| GNC Holdings, Inc. |
| Bayer AG |
| The Nature's Bounty Co. |
| Nestlé Health Science |
| Blackmores Limited |
| Swisse Wellness Pty Ltd. |
| Pharmavite LLC |
| Others |
Cost & Logistics Intelligence
Marine collagen peptide feedstock costs originating from Vietnamese and Indonesian tilapia processing facilities cascade through three distinct pricing tiers before reaching peri-menopausal consumers in German pharmacies and Shanghai cross-border e-commerce channels. This upstream concentration in aquaculture-derived raw materials compresses margin flexibility for mid-scale brands while rewarding scaled manufacturers with captive fermentation capacity or long-term offtake agreements.
Pricing Analysis
Subscription-based replenishment models with dynamic algorithmic reordering anchor pricing architecture across direct-to-consumer platforms, separating premium clinical-grade collagen with EFSA-substantiated dermal elasticity claims from standard-tier multivitamin blends competing on price-per-day metrics in mass retail. Certification grade under EU novel food dossiers and FDA structure-function claim substantiation creates the primary price differentiation mechanism, with pharmacy-grade positioning commanding substantial premiums over conventional dietary supplement tiers. Pricing pressure stems from plant-based protein substitution in meal-replacement positioning diverting R&D budgets and consumer attention from beauty-specific bioactives. Urban millennial subscribers in New York and Tokyo metropolitan corridors exhibit lowest price sensitivity due to lifetime value capture mechanics, while mass retail tablet buyers in supermarket channels demonstrate highest elasticity.
Supply Chain Analysis
Halal and kosher certification gating for Middle Eastern and Israeli market access forces dedicated production line segregation and audit trail documentation that elevates contract manufacturing minimum order quantities. Raw material sourcing concentrates in Vietnamese and Indonesian marine collagen facilities, Japanese Kanto-region fermentation-derived hyaluronic acid plants, and Bavarian contract manufacturing clusters with REACH Annex XVII compliance capabilities. Phospholipid supply chains originally scaled for pharmaceutical injectables now strain under liposomal encapsulation demand from Seoul and Shanghai oral beauty brands. Single-source vulnerability in Southeast Asian aquaculture processing creates acute exposure to climate-related harvest volatility. Distribution runs through bonded import zones under China SAMR pilot regulations for cross-border e-commerce, bypassing traditional wholesale pharmaceutical distribution hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA and FTC joint enforcement on structure-function claims substantiation accelerates demand for in-house regulatory dossier capabilities that smaller entrants cannot replicate.
For Market Incumbents: Lock in recurring purchase patterns through AI-driven personalization engines that integrate microbiome sequencing and skin diagnostic data into dynamic formulation adjustments, defending against digitally native brands with superior first-party data assets. Deepen backward integration into fermentation-derived collagen and hyaluronic acid capacity through acquisition of Japanese Kanto-region or Indian PLI-supported facilities, securing supply continuity against Vietnamese marine source concentration risk. For New Entrants and Emerging Players: Launch via cross-border e-commerce flagship stores on Tmall Global to access Shanghai and Beijing metropolitan demand without full China SAMR domestic registration burden, exploiting pilot zone bonded import regulations. Target peri-menopausal hormonal balance applications in French and German para-pharmacy channels where gynecological clinic recommendation networks remain underpenetrated by digital-first brands, leveraging co-prescription adjacency to pharmaceutical hormone therapy tapering protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs exceed six-figure clinical study barriers for EFSA health claims substantiation, favoring scaled manufacturers with dedicated regulatory affairs subsidiaries over mid-scale entrants. Long-term viability across the projection horizon hinges on acquiring fermentation-derived ingredient capacity with advanced microencapsulation capabilities rather than commodity-grade formulation assets. Watch for inflection signals in pharmacovigilance database integration requirements that strain quality assurance headcount and trigger distressed divestiture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Personalization Engine Deployment | Microbiome sequencing integration enables subscription models with dynamic formulation adjustments based on biomarker feedback loops. |
| Backward Integration into Fermentation Capacity | Captive collagen and hyaluronic acid production reduces exposure to Vietnamese marine source concentration vulnerability. |
| Cross-Border E-Commerce Flagship Launch | Tmall Global and bonded import zones accelerate China market access without full SAMR domestic registration requirements. |
| Gynecological Clinic Co-Prescription Partnership | Peri-menopausal adjacency to pharmaceutical hormone therapy in Germany and France anchors premium positioning. |
| REACH Annex XVII Compliance Subsidiary Establishment | Dedicated regulatory affairs capabilities absorb EFSA health claims substantiation burdens for European market access. |
Research Approach
Bottom-up cohort modeling of millennial and Gen Z urban consumer segments reconciled against top-down fermentation capacity and marine collagen feedstock tracking forms the analytical core of this study. Primary interviews with brand managers at direct-selling networks, category buyers at Sephora and Douglas beauty retail environments, regulatory affairs leads at scaled manufacturers, and supply planners at Vietnamese aquaculture processing facilities combined with secondary validation against FDA warning letter databases, EFSA novel food dossier filings, China SAMR cross-border e-commerce policy circulars, and Indian PLI scheme disbursement records. Triangulation between demand-side subscription data and supply-side contract manufacturing utilization rates ensures coherence across the analysis window.
Historical trendline analysis of collagen peptide, probiotic, and herbal extract volume trajectories informed the projection framework across product type, application, form, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis of segment-specific growth rates calibrated against regulatory milestone timing and channel shift elasticity parameters. Forecast inputs incorporated EFSA health claims approval pipelines, China bonded import zone expansion schedules, and peri-menopausal demographic concentration shifts in target metropolitan corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA enforcement action escalation or marine collagen supply disruption from climate-related harvest failures. Model assumptions reflect documented regulatory trajectories and supply concentration vulnerabilities specific to hormone-active ingredient pharmacovigilance obligations. A model refresh is warranted upon material change in China SAMR cross-border e-commerce pilot zone regulations or EFSA randomized controlled trial requirement modifications for beauty-from-within claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Hair Supplements Market