
 Medicinal Mushroom Powder Market | 2026-2036
Medicinal Mushroom Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Mushroom Powder Market Foresight
Organic certification under USDA National Organic Program standards is collapsing the supplier base to growers with documented substrate traceability and third-party laboratory verification. Nammex leverages its British Columbia cultivation network to supply raw material to North American extractors. Four Sigmatic competes through beverage-format innovation that masks the bitter compounds of chaga and reishi. Om Mushroom Superfood controls vertical production from spawn to finished powder, insulating margin from raw material volatility.
Medicinal mushroom powder consists of dehydrated, milled fruiting bodies or mycelial biomass standardized to polysaccharide content, typically beta-glucans, and processed through hot-water or dual-extraction methods to concentrate bioactive compounds for therapeutic or functional food applications. The nutraceuticals end-user segment dominates current volume as capsule and powder SKUs populate pharmacy and practitioner channels, while the food and beverage segment is the fastest-growing application as brands infuse adaptogenic properties into ready-to-drink formulations and functional snacks. Reishi powder retains the largest share among product types due to centuries of traditional use and established clinical literature, though lion's mane is displacing it in cognitive health positioning among millennial and Gen-Z consumers.
FDA Current Good Manufacturing Practice regulations for dietary supplements, EU Novel Food catalog listings under EFSA guidance, and USDA Organic certification requirements collectively determine which suppliers can access mainstream retail and direct-to-consumer channels in the United States and European Union. China's NMPA and SAMR oversight of traditional medicine exports adds a compliance layer for reishi and cordyceps sourced from Yunnan and Tibet. Stakeholders must monitor evolving novel food approvals in Europe and organic equivalency agreements that could reroute supply from domestic growers to certified importers.
Market Dynamics
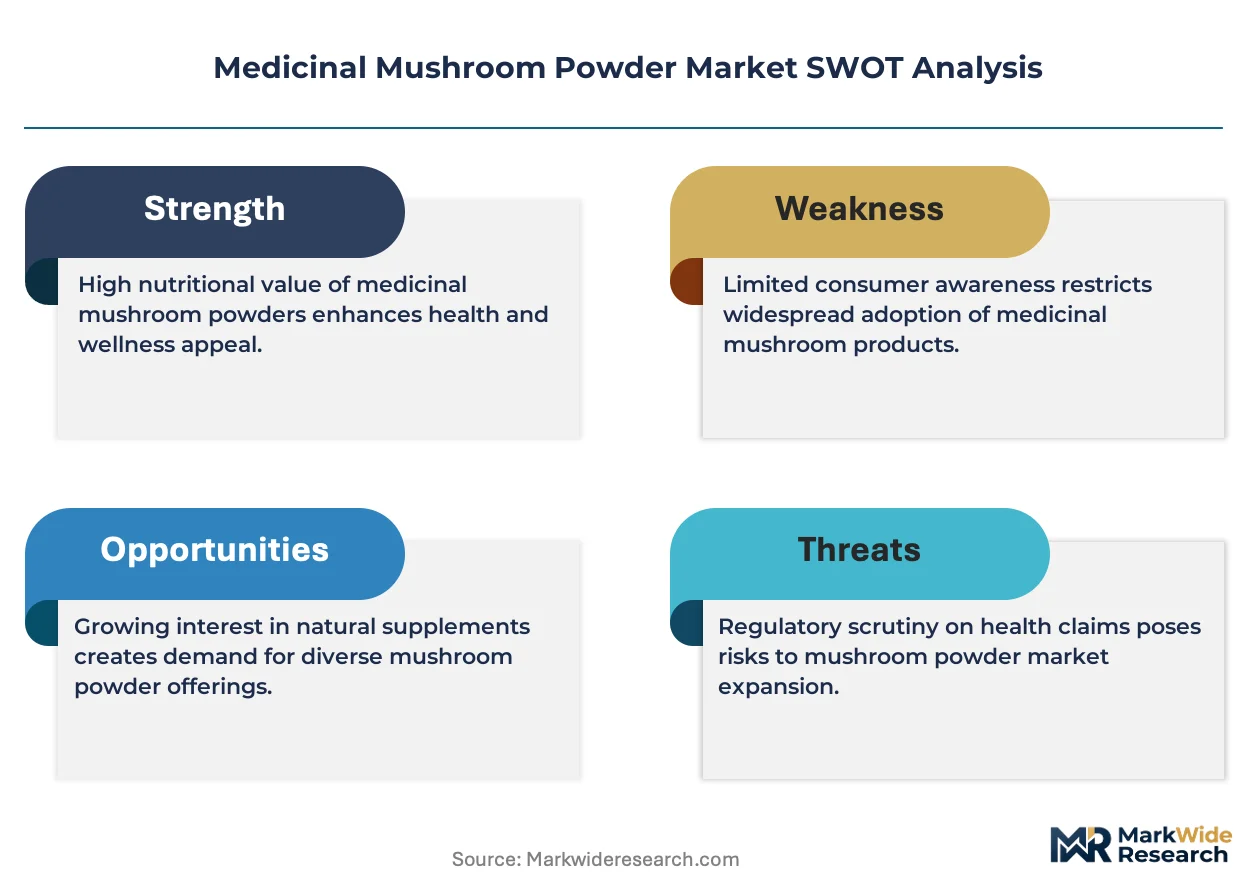
Organic certification requirements under the USDA National Organic Program are compressing the supplier base to growers with documented substrate traceability, forcing mid-tier extractors to consolidate procurement relationships or exit retail channels entirely.
Growth Catalysts
- EU Novel Food catalog expansion:EFSA approvals for lion's mane and cordyceps extracts are opening mainstream retail channels across Germany, France, and the Netherlands.
- Functional beverage formulation:Ready-to-drink brands are embedding adaptogenic powders into coffee alternatives and performance drinks, creating pull-through demand for standardized extracts.
- Practitioner channel expansion:Naturopathic and integrative medicine clinics in the United States are prescribing mushroom powders as adjunct therapies, validating clinical positioning.
Market Restraints
- Substrate input volatility:Hardwood sawdust and organic grain spawn prices fluctuate with lumber and agricultural commodity cycles, squeezing margins for non-integrated growers.
- Yunnan-Tibet supply concentration:Wild-harvested cordyceps and reishi from high-altitude Chinese provinces face export quota uncertainty under SAMR oversight.
- Dual-extraction capex barriers:Hot-water and ethanol processing equipment requires substantial capital investment, limiting entry for small-scale processors.
Strategic Opportunities
- Southeast Asia penetration:Thailand, Vietnam, and Indonesia present underdeveloped demand for cognitive and immune-positioned supplements among urban professional demographics.
- Pet nutrition application:Functional treats and meal toppers for companion animals represent an emerging category with minimal competitive saturation.
- USDA Organic equivalency agreements:Reciprocal certification with Canada and select EU member states could reroute supply to lower-cost certified importers.
Industry Challenges
- Polysaccharide assay standardization:Inconsistent beta-glucan measurement methodologies across laboratories create quality disputes and retail rejection risk.
- Mycologist talent scarcity:Cultivation science expertise for spawn development and contamination control concentrates in British Columbia and the Pacific Northwest, limiting geographic expansion of production.
- Dual-use mycelium IP complexity:Patent thickets around mycelial fermentation processes create licensing friction for novel strain development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Mushroom Powder Market |
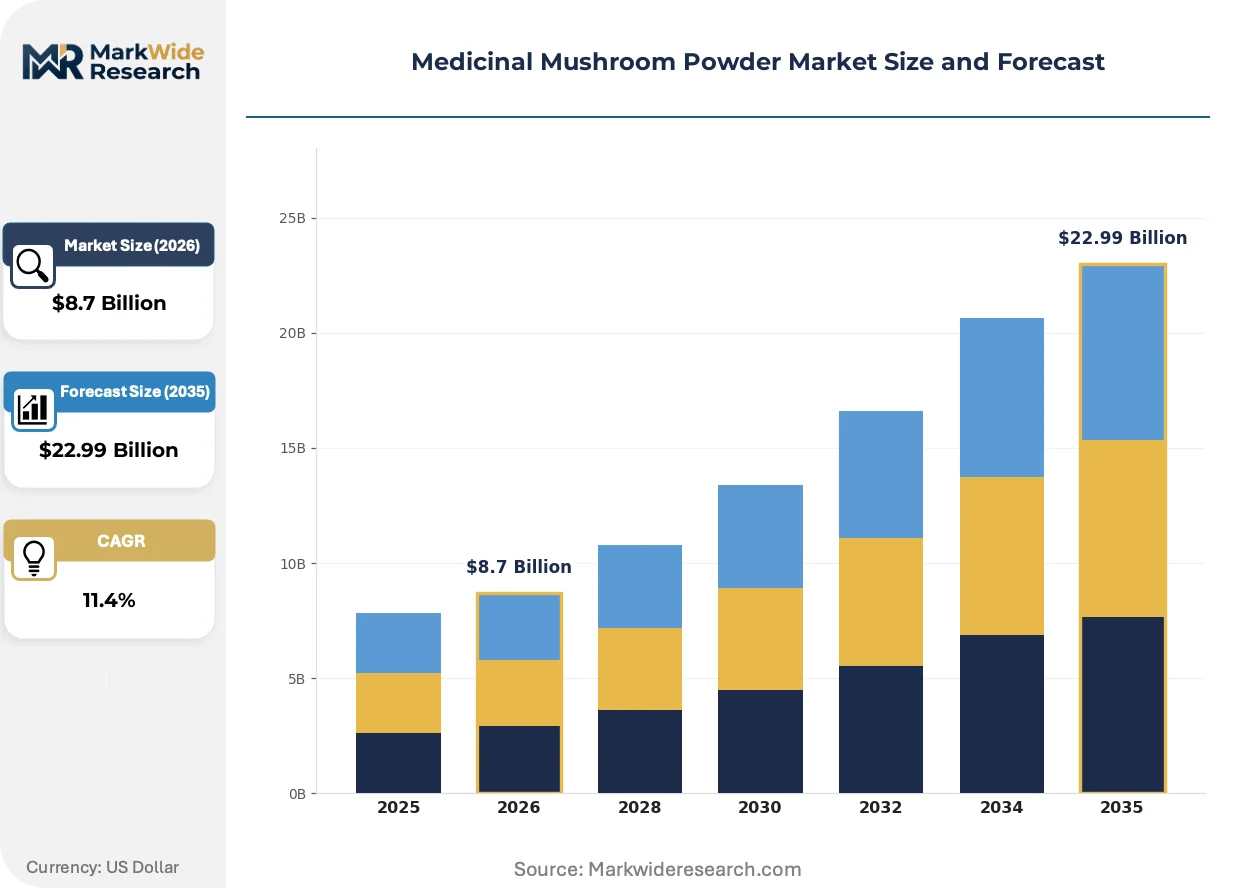
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reishi, Lion's Mane, Chaga, Cordyceps Form: Powder, Capsule, Extract, Liquid End User: Healthcare, Food & Beverage, Cosmetics, Nutraceuticals Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Om Mushroom Superfood, Four Sigmatic, Nammex, Real Mushrooms, Fungi Perfecti, Mushroom Wisdom, MycoTechnology Inc., Host Defense, M2 Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Mushroom Powder Market Shifts & Advancements
Extraction technology advances and shifting regulatory frameworks are reconfiguring how bioactive compounds reach end-users, with implications for product format, channel access, and competitive differentiation across the value chain.
Ultrasonic-assisted extraction is displacing conventional hot-water methods in premium processing facilities. North American nutraceutical contract manufacturers are adopting this technology to achieve higher polysaccharide yields at lower temperatures. The shift is compressing batch processing times and enabling claims around heat-sensitive compound preservation.
EFSA Novel Food guidance updates are tightening substantiation requirements for immune-modulation claims. European brands must now submit comprehensive toxicology and bioavailability data before market entry. Smaller extractors without regulatory affairs capacity are withdrawing from EU distribution, ceding shelf space to established players with dedicated compliance infrastructure.
Direct-to-practitioner sampling programs are replacing traditional retail slotting fees as the primary customer acquisition mechanism. Functional medicine networks in California, Texas, and New York are receiving complimentary clinical education alongside product samples. This channel pivot is most visible among millennial and Gen-Z consumers seeking practitioner-validated supplement protocols.
Medicinal Mushroom Powder Market Segmentation
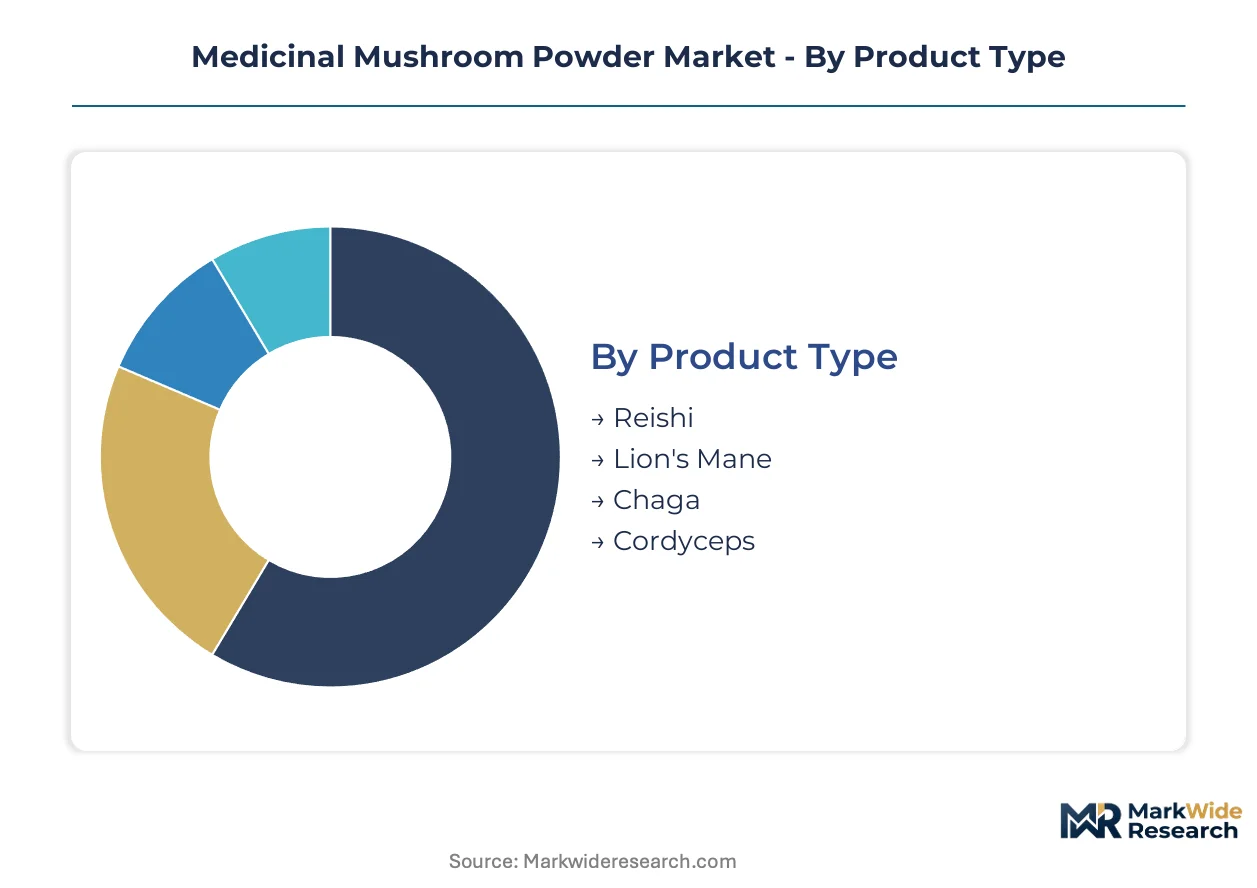
Segmentation in medicinal mushroom powders reveals divergent supply chain configurations and regulatory pathways. Product type determines cultivation geography and extraction complexity. End-user orientation dictates whether suppliers pursue FDA dietary supplement compliance or food-grade certifications.
Product Type:
Domestic cultivation in British Columbia and the Pacific Northwest supplies North American demand for lion's mane and reishi, while cordyceps and wild-harvested chaga remain concentrated in Yunnan and Tibet export channels.
- Reishi:Fruiting body powders standardized to triterpene and beta-glucan content dominate practitioner-directed immune support protocols. Demand concentrates in Germany and the United States where traditional medicine integration drives clinical positioning.
- Lion's Mane:Dual-extracted powders targeting hericenones and erinacines are displacing reishi in cognitive health applications among millennial consumers. North American beverage manufacturers embed this powder into coffee alternatives and nootropic formulations.
- Chaga:Wild-harvested sclerotium from birch forests in Russia and Canada supplies antioxidant-positioned supplements.
- Cordyceps:Militaris cultivation in controlled facilities is reducing dependence on high-altitude sinensis wild harvests from Tibet.
Reishi holds the largest share; momentum sits with lion's mane.
Form:
Cost tier stratification separates premium dual-extract powders from commodity-grade whole mushroom powders, with capsule and liquid formats commanding manufacturing premiums.
- Powder:Bulk fruiting body powders with specified mesh size and polysaccharide content serve contract manufacturers and direct-to-consumer brands. Food and beverage companies in the United States specify hot-water extracts for solubility in ready-to-drink applications.
- Capsule:Pre-dosed gelatin and vegetable cellulose formats populate pharmacy and practitioner channels requiring precise serving standardization.
- Extract:Concentrated liquid and powdered extracts with verified beta-glucan percentages target clinical and premium wellness positioning.
- Liquid:Tincture and dropper formats appeal to bioavailability-focused consumers seeking rapid absorption claims.
Powder dominates volume; extracts are climbing the fastest on value per gram.
End User:
Application maturity varies sharply, with nutraceuticals commanding established extraction standards while cosmetics and functional foods face evolving formulation challenges.
- Nutraceuticals:Capsule and powder SKUs with third-party polysaccharide verification populate practitioner and pharmacy channels. FDA Current Good Manufacturing Practice compliance is mandatory for United States distribution.
- Food & Beverage:Ready-to-drink coffee alternatives and functional snacks are expanding most quickly as brands mask bitter compounds through flavor masking and microencapsulation.
- Healthcare:Hospital and clinic procurement of adjunct therapy powders requires batch-level documentation and stability testing.
- Cosmetics:Topical serums and masks incorporating mushroom extracts for antioxidant claims represent emerging demand with minimal supplier specialization.
Nutraceuticals anchors current revenue; food and beverage shows steepest expansion trajectory.
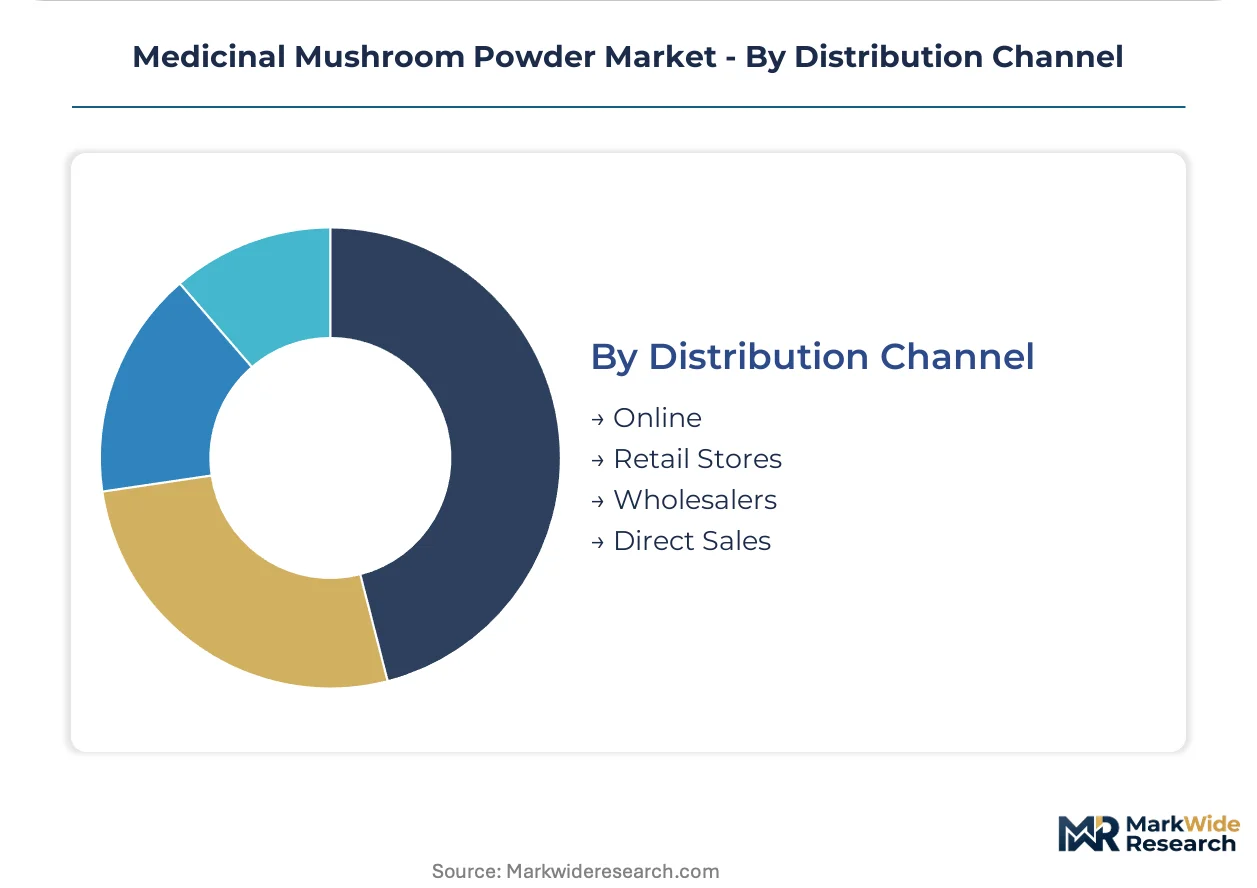
Distribution Channel:
Customer type fragmentation separates institutional procurement through wholesalers from direct-to-consumer subscription models requiring distinct logistics and compliance infrastructure.
- Online:Direct-to-consumer platforms and marketplace listings dominate millennial and Gen-Z acquisition. Subscription models with auto-ship functionality reduce customer acquisition costs for powder brands.
- Retail Stores:Natural products retailers and pharmacy chains require slotting fees and organic certification documentation. United States distribution demands USDA National Organic Program compliance for shelf placement.
- Wholesalers:Bulk powder distributors serve contract manufacturers and smaller brands lacking extraction capacity. Inventory concentration in California and New York distribution centers reduces lead times.
- Direct Sales:Practitioner sampling programs and clinical education initiatives bypass traditional retail margins. Integrative medicine networks in Texas and Florida receive complimentary product with protocol training.
Online channels are gaining share fastest; retail stores retain the largest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Practitioner networks and functional beverage manufacturers concentrate procurement in the United States, Germany, and China, with each geography presenting distinct regulatory pathways and supply chain configurations.
United States
Naturopathic clinics in California, Texas, and Florida drive practitioner-channel demand for standardized reishi and lion's mane powders. FDA Current Good Manufacturing Practice regulations mandate batch documentation and stability testing for dietary supplement distribution. The Pacific Northwest cultivation cluster around British Columbia supplies fruiting body raw material to North American extractors.
Germany
Traditional medicine integration and pharmacy-channel positioning anchor European demand for triterpene-standardized reishi extracts. EFSA Novel Food catalog listings under EU guidance determine market access for lion's mane and cordyceps formulations. The country's federal organic certification framework favors importers with USDA equivalency documentation.
China
Domestic consumption of cordyceps sinensis and reishi remains concentrated in high-altitude Yunnan and Tibet wild-harvest channels. NMPA and SAMR oversight of traditional medicine exports creates compliance layers for international shipment. Controlled militaris cultivation facilities in Sichuan and Hubei are reducing dependence on wild harvest quotas.
Canada
Health Canada Natural Health Product regulations govern mushroom powder licensing through the Natural and Non-prescription Health Products Directorate. British Columbia's mycologist talent concentration supports spawn development and contamination control for North American supply. Vancouver-area extraction facilities serve cross-border demand from United States nutraceutical contract manufacturers.
Australia
TGA listing requirements for complementary medicines create a regulated pathway for beta-glucan standardized powders. Urban professional demographics in Sydney and Melbourne drive demand for cognitive-positioned lion's mane supplements. Import dependence on North American and Chinese raw material exposes distributors to organic equivalency verification requirements.
Medicinal Mushroom Powder Market Competitive Landscape
Player mix skews toward vertically integrated cultivator-extractors and beverage-format innovators, with mid-tier processors facing margin compression from substrate volatility and certification costs. The supplier base compresses around three archetypes: spawn-to-finished-product operators insulating against raw material price swings, contract manufacturers serving private-label demand, and direct-to-consumer brands masking bitter compounds through flavor engineering. Consolidation pressure operates through procurement relationship lock-ins and extraction capacity expansion rather than outright acquisition.
Within the integrated cultivation tier, Om Mushroom Superfood exemplifies backward control from spawn through finished powder, while Nammex anchors raw material supply from its British Columbia network to North American extractors. Four Sigmatic occupies a position in beverage-format innovation, representing the flavor-masking and ready-to-drink positioning archetype that captures millennial and Gen-Z acquisition channels.
| Leading Market Players |
|---|
| Om Mushroom Superfood |
| Four Sigmatic |
| Nammex |
| Real Mushrooms |
| Fungi Perfecti |
| Mushroom Wisdom |
| MycoTechnology Inc. |
| Host Defense |
| M2 Ingredients |
| Others |
Supply & Pricing Matrix
Controlled militaris cultivation displacing wild-harvested cordyceps sinensis redraws procurement geography from Tibet to Sichuan facility networks while compressing per-kilogram input costs and flattening historical altitude premiums. This substitution dynamic reconfigures supplier bargaining power across extraction tiers.
Pricing Analysis
Cost-plus contracts indexed to organic grain spawn and hardwood sawdust commodity benchmarks dominate procurement between British Columbia cultivators and North American extractors. Price differentiation separates USDA Organic-certified dual-extract powders from conventional whole-mushroom grades, with certification tier and volume scale as primary levers. Pricing pressure intensifies in standard-grade powders as mid-tier processors absorb substrate volatility without backward integration. Practitioner-channel buyers exhibit lowest price sensitivity due to clinical protocol stickiness, while bulk food and beverage manufacturers negotiate aggressively on volume commitments.
Supply Chain Analysis
China, Canada, and the United States anchor global supply, with Yunnan and Tibet wild-harvest channels feeding cordyceps and reishi raw material while British Columbia and the Pacific Northwest concentrate domesticated lion's mane and reishi fruiting body production. Hardwood sawdust, organic grain spawn, and ethanol for dual-extraction draw from lumber, agricultural commodity, and chemical feedstock markets respectively. Single-source vulnerability concentrates in high-altitude Chinese wild harvests subject to SAMR export quota uncertainty. Distribution runs through bulk powder wholesalers in California and New York, direct-to-consumer subscription platforms, and practitioner sampling programs bypassing traditional retail slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as synthetic nootropics and lab-grown bioactive compounds threaten to displace mushroom-derived cognitive positioning among millennial and Gen-Z consumers.
For Market Incumbents: Secure spawn-to-finished-product control through backward integration into British Columbia cultivation networks or exclusive procurement lock-ins with documented substrate traceability. Lock practitioner channel relationships through clinical education investments that validate immune-modulation claims against emerging synthetic substitutes. Prioritize EFSA Novel Food compliance infrastructure to defend European shelf access as regulatory barriers rise.
For New Entrants and Emerging Players: Lead with pet nutrition applications where functional treat formulations face minimal incumbent saturation and lower certification barriers than human nutraceuticals. Target Southeast Asian urban professional demographics in Thailand and Vietnam through direct-to-consumer platforms before established brands build localized supply relationships. Emphasize ultrasonic-assisted extraction technology as a premium positioning lever against commodity hot-water processors.
For Investors and Strategic Acquirers: EFSA Novel Food catalog expansion reshapes the acquisition landscape by privileging extractors with dedicated regulatory affairs capacity over pure cultivation plays. Five-to-ten-year viability hinges on organic certification equivalency agreements that could reroute supply to lower-cost certified importers. Target vertically integrated operators with British Columbia spawn development capabilities and existing practitioner channel penetration. Monitor EU Novel Food approval timelines for lion's mane and cordyceps as inflection signals for mainstream retail channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic-Assisted Extraction Adoption | Enables higher polysaccharide yields at lower temperatures for premium positioning against conventional processors. |
| Practitioner Sampling Program Expansion | Bypasses retail slotting fees while building clinical validation networks in California, Texas, and Florida. |
| USDA Organic Equivalency Agreement Pursuit | Opens supply rerouting to lower-cost certified Canadian importers under reciprocal certification frameworks. |
| Pet Nutrition Product Line Launch | Captures emerging functional treat demand with minimal competitive saturation and reduced regulatory complexity. |
| EFSA Novel Food Compliance Investment | Secures mainstream European retail access as toxicology and bioavailability requirements tighten under updated guidance. |
Research Methodology
A spread of perspectives from cultivation facility operators, extraction facility technical directors, nutraceutical contract manufacturing procurement leads, and functional beverage brand formulators converged on the working assumptions. Primary fieldwork with spawn development mycologists and organic certification auditors supplemented secondary validation through FDA dietary supplement warning letters, EFSA Novel Food catalog listings, USDA National Organic Program equivalency agreements, and Health Canada Natural Health Product licensing records. Bottom-up volume builds from facility-level capacity and utilization rates triangulated against top-down demand estimates from channel shipment data.
Segmentation dimensions modeled include product type, extraction method, form factor, end-user application, and distribution channel across the analysis window. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporate organic certification penetration rates, EFSA approval timelines, and practitioner channel adoption curves.
The analysis sits within stated boundaries; outcomes outside maintained regulatory equivalency agreements, stable substrate commodity pricing, and consistent novel food approval timelines would require recalibration. Forecasts reflect documented assumptions subject to revision from SAMR export quota shifts, ultrasonic extraction technology diffusion rates, or synthetic nootropic substitution acceleration. Recalibration cycles align with material shifts in regulatory approval milestones and organic certification framework changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Herbal Supplements Market