
 Global Melatonin Market | 2026-2036
Global Melatonin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Melatonin Market Outlook
Synthetic melatonin is recalibrating cost structures across the nutraceutical supply chain as fermentation-derived alternatives gain manufacturing scale. Natrol leverages vertical integration from raw material sourcing to finished tablet production, sustaining cost advantages in North American retail channels. Pharmavite competes through pharmacist-recommended positioning, while Jamieson Wellness anchors its presence in Canadian and select Asian markets through cold-chain quality protocols.
Melatonin is a tryptamine-based hormone produced endogenously by the pineal gland and synthesized commercially through chemical or microbial fermentation routes, typically standardized to 99% purity for dietary supplement applications. Its primary commercial purpose centers on circadian rhythm modulation for sleep onset, jet lag mitigation, and adjunct anxiety management. Gummies within product type segments are capturing disproportionate margin pools as palatability drives household penetration among reluctant pill consumers, while sleep disorders dominates end user demand yet general wellness represents the fastest-expanding indication as preventive health frameworks expand. Online retail channels are displacing pharmacy dependence among younger demographics, though pharmacies retain higher trust conversion among seniors.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, mandating identity testing that reshapes supplier qualification burdens for melatonin importers. EFSA evaluates novel food applications and health claim substantiation across European member states, constraining marketing language and dosage positioning. China's SAMR oversees blue-hat health food registration, creating dual-track market access for domestic and imported melatonin products. Stakeholders must monitor evolving pharmacovigilance frameworks as regulators reassess melatonin's classification boundary between food supplement and therapeutic agent.
Market Dynamics
Fermentation-derived melatonin production is consolidating manufacturing scale advantages over chemical synthesis, compressing unit economics and forcing raw material suppliers to recalibrate purity specifications or exit contract relationships.
Growth Catalysts
- Aging Demographics:Sleep disorder prevalence among populations over 65 in the United States, Germany, and Japan sustains prescription-to-OTC conversion demand for non-habit-forming alternatives.
- FDA cGMP Enforcement:Identity testing mandates under 21 CFR Part 111 are disqualifying unqualified raw material importers, concentrating volume among validated suppliers with analytical capabilities.
- Microbial Fermentation Scale-Up:Recombinant yeast and bacterial strain optimization is reducing production costs by 40-60% versus traditional chemical routes, enabling margin expansion at standardized 99% purity.
Market Restraints
- Acetonitrile Price Volatility:Chemical synthesis routes remain exposed to solvent cost swings tied to petroleum feedstock indices, constraining margin predictability for non-fermentation producers.
- Chinese Raw Material Concentration:Over 70% of global melatonin API originates from Zhejiang and Jiangsu province manufacturers, creating single-source vulnerability for Western finished goods producers.
- EFSA Health Claim Constraints:Novel food applications and sleep-related marketing language face substantiation barriers across European member states, limiting dosage positioning above 1mg in key markets.
Strategic Opportunities
- Pediatric Formulation White Space:Low-dose gummy and liquid formats for circadian rhythm disorders in children remain underdeveloped relative to adult SKUs, with SAMR blue-hat registration creating dual-track access in China.
- Jet Lag Adjunct Positioning:Combination products with L-theanine or magnesium are capturing business traveler segments through airport retail and direct-to-subscription channels.
- India PLI Scheme Alignment:Contract manufacturing incentives for nutraceuticals under the Production Linked Incentive scheme are attracting fermentation capacity investment for export-oriented supply.
Industry Challenges
- Analytical Chemist Shortage:HPLC-MS identity verification and chiral purity testing capabilities are scarce among mid-tier contract manufacturers, extending supplier qualification timelines.
- Cross-Border Label Harmonization:Divergent maximum daily dosage limits between FDA, EFSA, and SAMR frameworks force SKU proliferation or lowest-common-denominator positioning.
- Cold-Chain Integrity Costs:Temperature-sensitive gummy formats require validated logistics infrastructure that fragments distribution economics versus ambient-stable tablets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Melatonin Market |
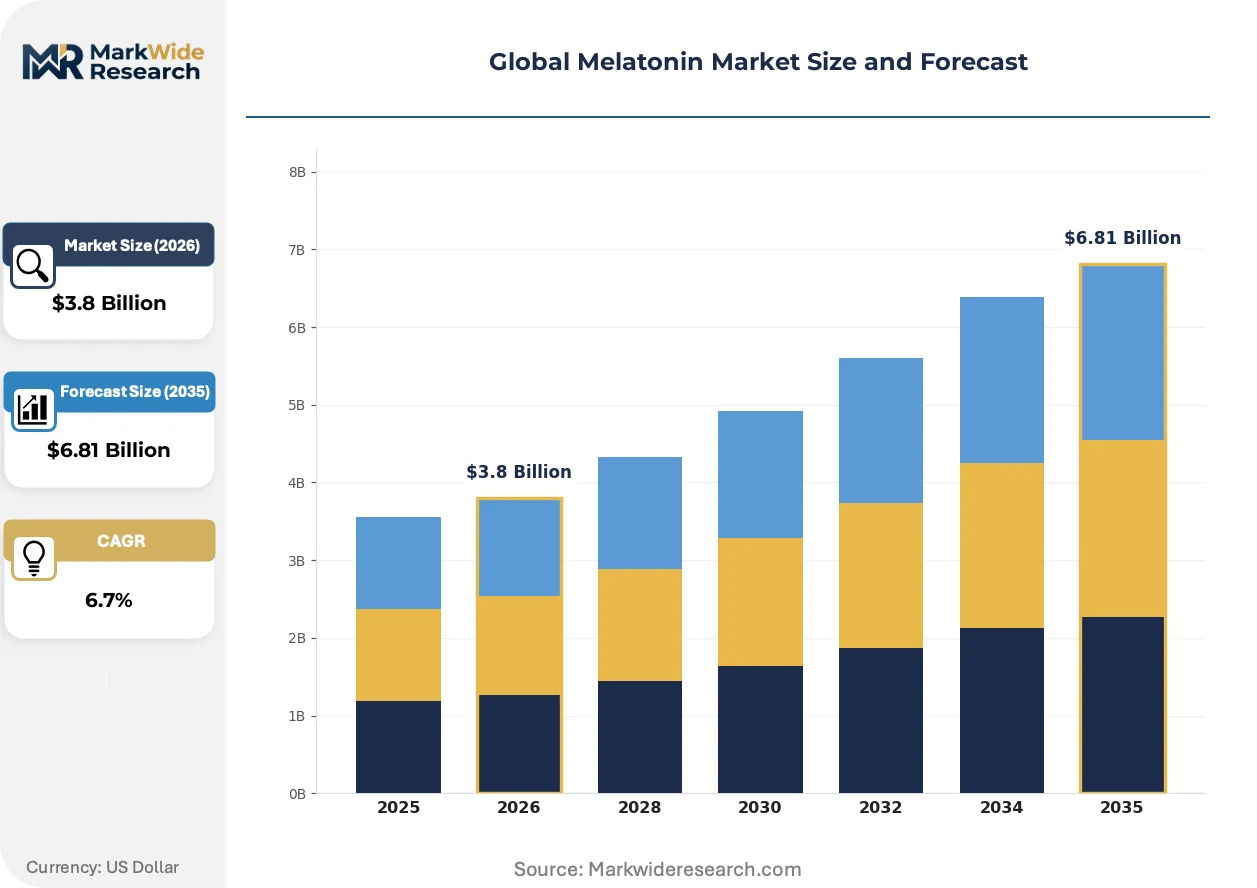
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Gummies, Liquid End User: Sleep Disorders, Anxiety Reduction, Jet Lag, General Wellness Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Age Group: Adults, Seniors, Adolescents, Children |
| Companies Covered | Natrol, Nature’s Bounty, Church & Dwight, Jamieson Wellness, Pharmavite, GNC, Pfizer, NOW Health Group, Solgar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Melatonin Market Strategic Shifts
Biomanufacturing scale-up and regulatory classification debates are simultaneously reshaping cost structures and competitive moats across the melatonin value chain, with format innovation opening household penetration vectors previously blocked by swallowing aversion.
Continuous fermentation systems utilizing genetically optimized Saccharomyces cerevisiae strains are consolidating production economics toward pharmaceutical-grade purity thresholds at dietary supplement price points. North American and European contract manufacturers are adopting these platforms to displace Chinese API dependence. The technology is consolidating supplier tiers by rendering batch chemical synthesis uneconomical below 500kg annual volume.
EFSA's ongoing reassessment of melatonin's novel food status is compressing marketing latitude for sustained-release formulations above 1.5mg across European member states. German and French regulators are requiring additional pharmacokinetic substantiation for modified-release claims. Sustained-release tablet producers are pivoting toward immediate-release positioning or withdrawing from German pharmacy channels pending clarity.
Subscription-based replenishment models are displacing pharmacy impulse purchases among millennials and Generation Z consumers in the United States and United Kingdom. Direct-to-consumer brands are capturing lifetime value through personalized dosage algorithms and sleep-tracking app integration. The channel shift is most visible in coastal US metropolitan markets where pharmacy foot traffic has not recovered to pre-2020 levels.
Global Melatonin Market Segmentation
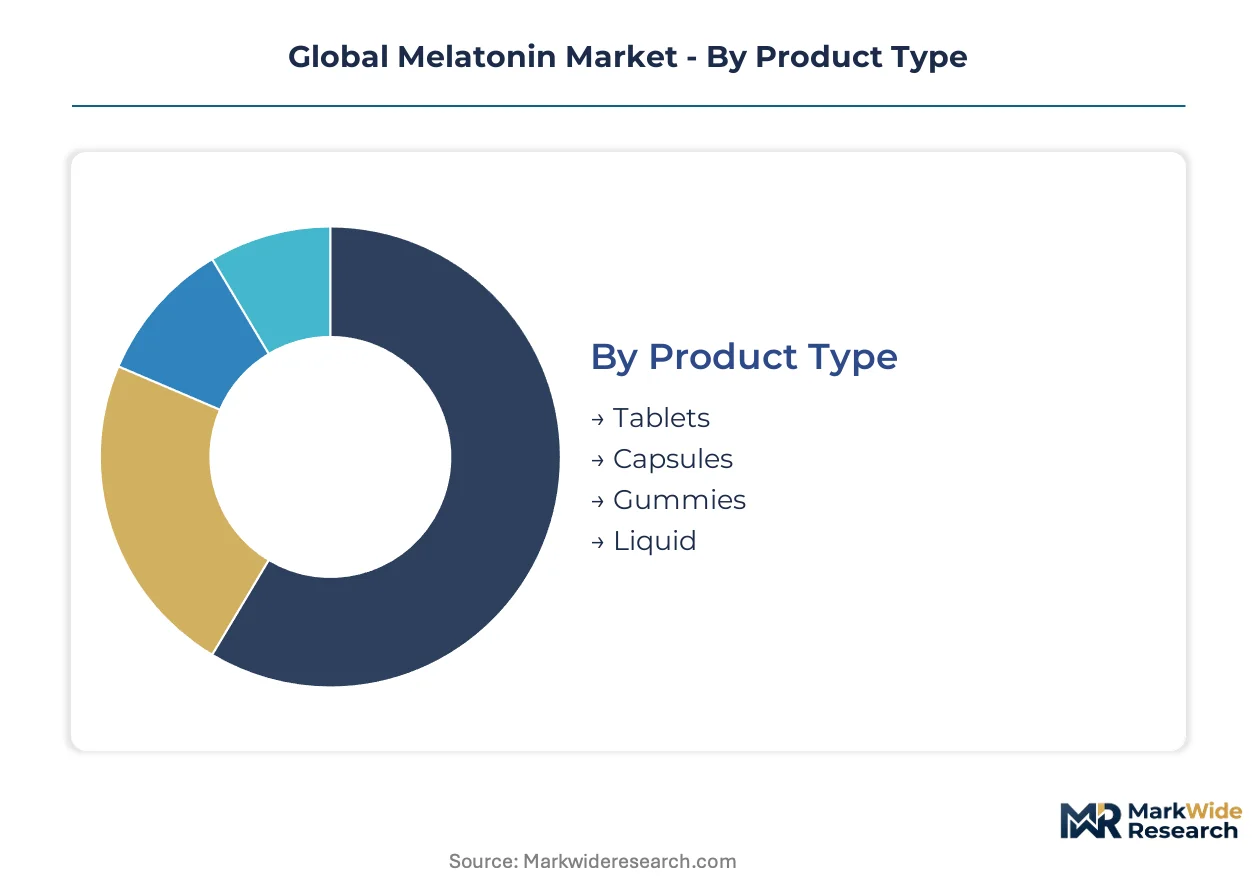
Melatonin manufacturers configure SKU portfolios around swallowing mechanics, regulatory dosage ceilings, and channel-specific margin structures. Format selection determines cold-chain requirements, shelf stability, and household penetration rates across demographic cohorts.
Product Type:
Palatability and portability drive repeat purchase behavior, with format choice correlating to age-related swallowing capability and travel frequency.
- Tablets:Compressed powder or granulated formulations offering precise dosage standardization and ambient stability. Demand concentrates among seniors in Germany and the United States where pharmacy trust conversion remains highest; tablet economics resist cold-chain cost fragmentation.
- Gummies:Gelatin or pectin-based matrices delivering 1-5mg doses with flavor masking for aversion-prone consumers. Growth tilts toward millennial households in coastal US metropolitan markets where subscription replenishment displaces pharmacy impulse purchases; palatability drives household penetration among reluctant pill consumers.
- Capsules:Two-piece gelatin shells containing powder or liquid fill, suited to sustained-release and combination formulations. EFSA dosage constraints above 1mg limit positioning in French and German pharmacy channels.
- Liquid:Aqueous or oil-based suspensions enabling dose titration for pediatric and geriatric populations with dysphagia. SAMR blue-hat registration creates dual-track access in China for low-dose pediatric positioning.
Volume sits with tablets; growth tilts toward gummies.
End User:
Clinical indication determines dosage architecture, with prescription-to-OTC conversion patterns varying by symptom severity and physician consultation norms.
- Sleep Disorders:Insomnia and circadian rhythm disruption applications requiring 1-10mg doses for sleep onset acceleration. Aging demographics in the United States, Germany, and Japan sustain demand for non-habit-forming alternatives to prescription hypnotics.
- General Wellness:Preventive health frameworks expanding melatonin positioning beyond symptomatic relief toward antioxidant and immune modulation claims. This segment is expanding most quickly as wellness-as-prevention reframes purchase motivation among health-optimizing consumers.
- Jet Lag:Transmeridian travel applications combining immediate-release melatonin with L-theanine or magnesium for business traveler segments. Airport retail and direct-to-subscription channels capture frequent flyer cohorts.
- Anxiety Reduction:Adjunct anxiolytic positioning leveraging melatonin's GABAergic modulation for stress-related sleep disruption. Marketing language faces substantiation barriers under EFSA health claim frameworks.
Revenue concentrates in sleep disorder applications; margin expansion follows general wellness positioning.
Distribution Channel:
Channel selection determines customer acquisition cost, trust conversion velocity, and regulatory compliance burden for labeling and storage.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription-based replenishment models. Younger demographics in the United States and United Kingdom drive channel shift where pharmacy foot traffic has not recovered to pre-2020 levels.
- Pharmacies:Brick-and-mortar drugstore and apothecary channels retaining higher trust conversion among seniors. German pharmacy chains enforce quality protocols that disqualify unvalidated suppliers.
- Supermarkets:Mass retail placement capturing impulse purchases in household replenishment shopping trips. Shelf space allocation favors gummy formats with visible packaging differentiation.
- Health Stores:Specialty nutrition retailers serving supplement-committed consumers seeking premium positioning and staff consultation. Cold-chain gummy formats require validated logistics infrastructure that fragments distribution economics.
Foot traffic aggregates in pharmacies; digital penetration climbs fastest in online retail.
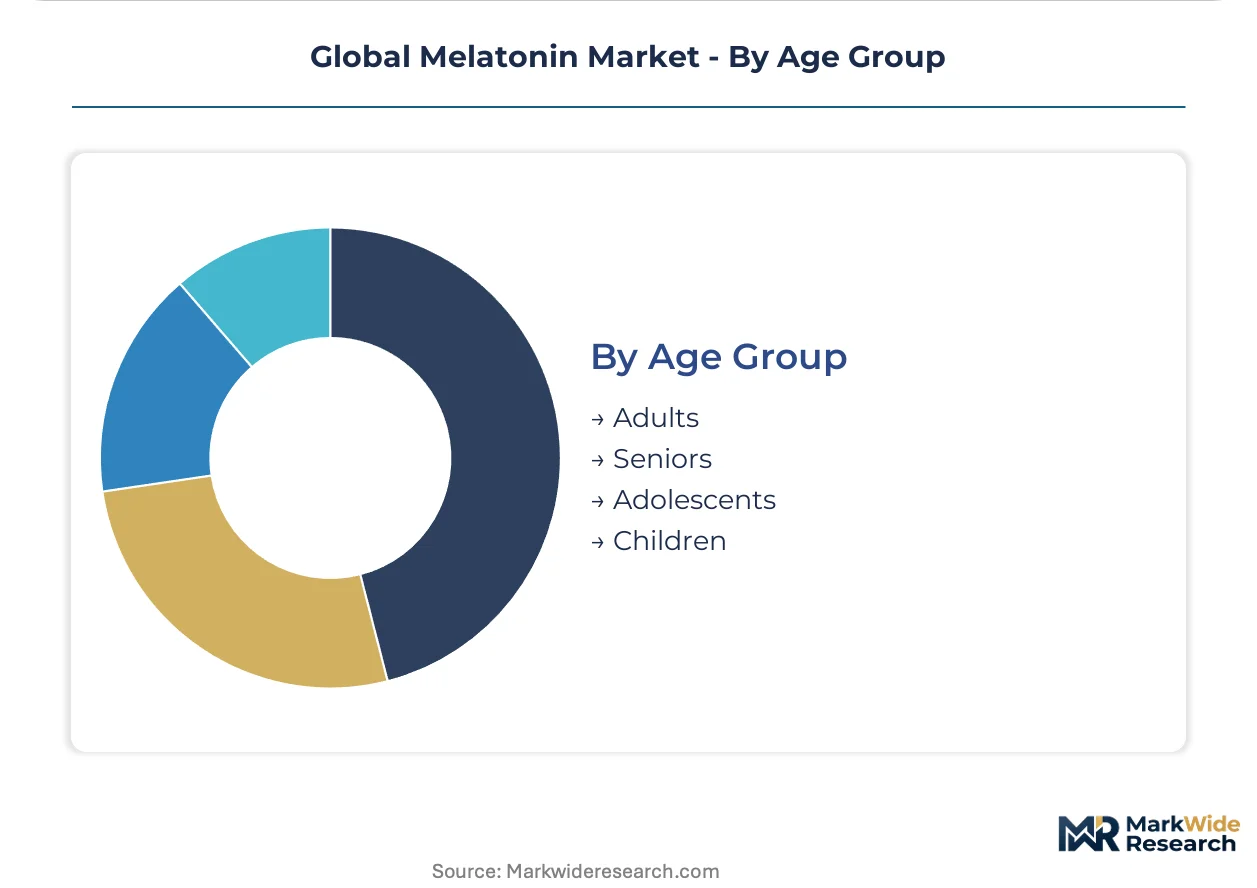
Age Group:
Dosage precision and format adaptability requirements intensify at population extremes, with pediatric and geriatric segments demanding specialized formulation and regulatory pathways.
- Adults:Core demographic consuming 1-5mg doses across tablets, capsules, and gummies for sleep onset and jet lag mitigation. Workforce stress and screen-time disruption expand addressable population.
- Seniors:Population over 65 with elevated sleep disorder prevalence and prescription-to-OTC conversion demand. Swallowing difficulties and polypharmacy interactions favor liquid and gummy alternatives.
- Adolescents:Circadian rhythm disruption from academic pressure and digital device exposure creating demand for low-dose formulations. Parental purchase decisions prioritize palatability and perceived safety.
- Children:Pediatric circadian rhythm disorders and neurodevelopmental sleep disturbances requiring sub-1mg dosing. SAMR blue-hat registration and FDA enforcement of 21 CFR Part 111 create dual qualification burdens for suppliers.
Volume anchors in adult consumption; formulation innovation targets pediatric white space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer expenditure on non-prescription sleep aids concentrates in the United States, Germany, and China, where aging demographics and wellness-prevention frameworks expand addressable populations beyond clinical sleep disorder diagnoses.
United States
Millennial and Generation Z households drive subscription-based replenishment through direct-to-consumer platforms, displacing pharmacy impulse purchases in coastal metropolitan markets. FDA enforcement of 21 CFR Part 111 identity testing mandates disqualifies unqualified raw material importers, concentrating volume among validated suppliers with analytical capabilities. Fermentation-derived production capacity clusters in New Jersey and North Carolina contract manufacturing corridors.
Germany
Pharmacy chains enforce quality protocols that disqualify unvalidated suppliers, sustaining trust conversion among seniors over 65 with elevated sleep disorder prevalence. EFSA novel food assessments and health claim substantiation requirements constrain marketing language for sustained-release formulations above 1.5mg. Industrial concentration centers on Bavaria and North Rhine-Westphalia, where apothecary distribution networks maintain rigid cold-chain standards for gummy formats.
China
SAMR blue-hat health food registration creates dual-track market access for domestic and imported melatonin products, with pediatric formulations representing underdeveloped white space. Zhejiang and Jiangsu provinces originate over 70% of global melatonin API, creating single-source vulnerability for Western finished goods producers. Shanghai and Beijing metropolitan areas concentrate e-commerce platform demand for subscription wellness products.
Japan
Population over 65 sustains prescription-to-OTC conversion demand for non-habit-forming alternatives to prescription hypnotics, with METI oversight of functional food claims shaping dosage positioning. PMDA pharmacovigilance frameworks monitor melatonin's classification boundary between food supplement and therapeutic agent. Manufacturing activity clusters in Kanto and Kansai regions, where fermentation-derived ingredient suppliers serve domestic nutraceutical formulators.
India
Production Linked Incentive scheme incentives for nutraceuticals attract fermentation capacity investment for export-oriented supply, targeting North American and European contract manufacturing demand. CDSCO and FSSAI dual regulatory pathways create qualification complexity for finished goods exporters. Maharashtra and Gujarat industrial corridors concentrate API synthesis and formulation capabilities serving global generic supply chains.
Global Melatonin Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertical integration sustaining cost advantages in North American retail channels while pharmacist-recommended positioning commands premium conversion in European pharmacy networks. The vendor base organizes around three strategic archetypes: fermentation-scale producers with captive raw material supply, brand houses with subscription direct-to-consumer infrastructure, and regional formulators with cold-chain logistics specialization. Consolidation pressures concentrate among mid-tier chemical synthesis operations unable to match microbial fermentation unit economics. Competitive moves center on backward integration into fermentation capacity and geographic licensing partnerships for SAMR blue-hat registration access.
Among North American brand houses, Natrol and Pharmavite occupy distinct positioning vectors, with the former exemplifying vertical integration from raw material sourcing through finished tablet production and the latter representing pharmacist-channel trust conversion strategies. Jamieson Wellness anchors Canadian and select Asian market presence through quality protocol differentiation. These three entities illustrate how regional regulatory specialization and channel-specific trust architectures create defensible positioning against private-label encroachment.
| Leading Market Players |
|---|
| Natrol |
| Nature's Bounty |
| Church & Dwight |
| Jamieson Wellness |
| Pharmavite |
| GNC |
| Pfizer |
| NOW Health Group |
| Solgar |
| Others |
Value Chain & Pricing Dynamics
Fermentation-grade tryptophan and acetonitrile solvent costs cascade through melatonin pricing tiers, with Chinese API concentration enabling economy-grade spot pricing while FDA-validated suppliers command premium positioning for pharmaceutical-grade purity in North American pharmacy channels.
Pricing Analysis
Volume concentrates in commoditized 99% purity tablets where Chinese API imports compress margins, while margin pools accrue to sustained-release capsules and cold-chain gummies carrying palatability premiums. Three-tier pricing structure across premium, standard, and economy levels separates pharmacist-recommended brands from private-label supermarket placements and unvalidated import SKUs. Pricing pressure stems from microbial fermentation scale-up reducing unit production costs by 40-60% versus chemical synthesis routes. Price-sensitive mass retail buyers in supermarket channels drive spot-market procurement, while pharmacy and subscription channels absorb premium positioning with lower elasticity.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA cGMP identity testing under 21 CFR Part 111 force Western finished goods producers to qualify multiple API suppliers, fragmenting procurement economics. Manufacturing gravity centers on Zhejiang and Jiangsu provinces in China, with secondary fermentation capacity emerging in New Jersey, North Carolina, and Bavaria. Raw material dependencies include pharmaceutical-grade tryptophan, acetonitrile solvent, and gelatin or pectin matrices for gummy formats. Single-source vulnerability pervades the China-dependent API tier, compounded by SAMR blue-hat registration creating bifurcated access for domestic versus imported finished goods. Distribution runs through validated cold-chain logistics for gummy formats, while ambient-stable tablets exploit conventional pharmaceutical wholesaling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Melatonin Market functions as a cost-of-compliance arena where FDA cGMP identity testing mandates under 21 CFR Part 111 erect analytical capability barriers that disqualify mid-tier entrants and concentrate volume among validated suppliers with captive HPLC-MS infrastructure.
For Market Incumbents: To counter microbial fermentation scale-up by Chinese API producers eroding chemical synthesis margins, incumbents must secure backward integration into recombinant yeast strain development or captive fermentation capacity in North American contract manufacturing corridors, while reinforcing pharmacist-channel trust conversion through 21 CFR Part 111 certification visibility that private-label competitors cannot replicate. For New Entrants and Emerging Players: Capture pediatric formulation white space in low-dose gummy and liquid formats where SAMR blue-hat registration creates dual-track access in China and FDA enforcement gaps persist below 1mg positioning, leveraging direct-to-consumer subscription infrastructure with sleep-tracking app integration to bypass pharmacy gatekeeper dependence in coastal US metropolitan markets. For Investors and Strategic Acquirers: SAMR approval of novel pediatric indications is the leading indicator that fermentation-derived melatonin capacity will command strategic scarcity premiums over chemical synthesis assets. Long-term viability favors acquisition targets with validated cold-chain logistics infrastructure and dual regulatory qualification under FDA and SAMR frameworks, with EFSA novel food reassessment serving as the critical inflection signal for European market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Recombinant yeast scale-up reduces unit costs 40-60% versus chemical synthesis routes, consolidating supplier tiers. |
| Regulatory Qualification Investment | 21 CFR Part 111 identity testing capabilities create FDA-mandated moats disqualifying unvalidated API importers. |
| Pediatric Formulation Development | Low-dose gummy and liquid formats exploit SAMR blue-hat registration white space in underdeveloped child segments. |
| Subscription Infrastructure Buildout | Direct-to-consumer replenishment models with sleep-tracking integration displace pharmacy impulse purchases among millennials. |
| Cold-Chain Logistics Partnership | Temperature-validated distribution networks enable gummy format penetration where ambient-stable competitors cannot compete. |
Study Parameters
Multi-period observation of FDA warning letter trends, SAMR blue-hat registration approvals, and EFSA novel food assessment timelines anchored the trend analysis, supplemented by interviews with contract manufacturing executives, analytical laboratory directors, pharmacy chain procurement managers, and dietary supplement brand managers. Secondary validation drew from FDA 483 inspection observations, SAMR health food registration databases, EFSA scientific opinions, customs import records, and SEC 10-K disclosures from publicly traded nutraceutical firms. Bottom-up volume modeling triangulated against top-down expenditure estimates from national health survey data.
Segment-weighting applied product type, end user indication, distribution channel, and age group dimensions across the modeling period, with fermentation-derived versus chemical synthesis route splits incorporated as a cross-cutting cost structure variable. CAGRs derived from logistic adoption curves fitted to prescription-to-OTC conversion patterns and subscription channel penetration trajectories. Forecast inputs included aging demographic projections, regulatory enforcement intensity indices, and microbial fermentation yield improvement curves.
The model holds under steady FDA cGMP enforcement intensity and stable acetonitrile feedstock pricing; deviation in SAMR pediatric indication approvals or EFSA sustained-release dosage restrictions would shift capacity investment geography and margin pool distribution materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Nootropic Products Market