
 Australia Nicotine Replacement Therapy Market | 2026-2036
Australia Nicotine Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Nicotine Replacement Therapy Market Insights
Australian pharmaceutical manufacturers is broadening production capacity for nicotine replacement formats to serve rising domestic demand. Johnson & Johnson leverages its consumer health division to sustain pharmacy shelf presence across major Australian retail networks. GlaxoSmithKline anchors the hospital procurement channel through established formulary relationships with state health departments. Perrigo Company plc competes aggressively on generic pricing, occupying the value tier that attracts price-sensitive smokers attempting cessation.
Nicotine Replacement Therapy comprises pharmacological products delivering controlled nicotine doses through transdermal patches, oral gum, inhalation devices, and sublingual lozenges to alleviate withdrawal symptoms during tobacco cessation. These formulations typically contain polacrilex resin matrices, ethylene-vinyl acetate membranes, or nicotine base suspensions engineered for sustained plasma concentration curves over eight to twenty-four hour intervals. Patches dominate volume sales through pharmacy networks due to once-daily application simplicity and predictable absorption kinetics. Online retailers represent the fastest-growing delivery channel as subscription pricing models reduce per-unit costs and automate replenishment cycles for recurring users.
Australia's Therapeutic Goods Administration regulates nicotine content thresholds and packaging standards, while the Pharmaceutical Benefits Scheme determines subsidy eligibility that directly shapes patient out-of-pocket expenditure. State-level health departments coordinate quitline services that generate prescribing referrals to pharmacies and clinics, creating institutional demand pipelines distinct from over-the-counter purchases. Stakeholders must monitor potential rescheduling deliberations that could expand supermarket distribution or restrict pharmacy-only access, fundamentally altering channel economics and competitive positioning.
Market Dynamics
Australia's Therapeutic Goods Administration scheduling framework for nicotine-containing products is compressing distribution into pharmacy channels while redirecting consumer purchases away from unregulated sources, fundamentally restructuring competitive access and margin allocation across the value chain.
Growth Catalysts
- Pharmaceutical Benefits Scheme subsidies:Out-of-pocket expenditure reductions through PBS eligibility are expanding patient access to prescription NRT formats across metropolitan and regional catchments.
- Quitline institutional pipelines:State health department cessation services in New South Wales and Victoria are generating structured referral flows that direct smokers toward pharmacy dispensing channels.
- Subscription automation:Online retailers deploying recurring replenishment models are capturing adherence-driven demand through reduced per-unit economics and automated delivery cycles.
Market Restraints
- Active pharmaceutical ingredient concentration:Global nicotine base supply concentrates among a limited set of specialized chemical manufacturers, creating input vulnerability for domestic formulators.
- TGA scheduling friction:Pharmacy-only access restrictions prevent supermarket and convenience retail distribution, constraining impulse purchase occasions and geographic reach.
- Heat-not-burn substitution:Tobacco heating devices are capturing cessation-intended smokers who perceive these products as reduced-harm alternatives to combustible cigarettes.
Strategic Opportunities
- Regional pharmacy network expansion:Underserved catchments in Queensland and Western Australia present whitespace for formulary placement and pharmacist-led cessation counseling programs.
- Digital therapeutic convergence:Integration of NRT dosing with smartphone-based behavioral support apps is creating adherence-tracking value propositions for payers and employers.
- General practitioner prescribing automation:Electronic medical record prompts and automated referral protocols are embedding NRT into standard chronic disease management workflows.
Industry Challenges
- Pharmacist counseling capacity constraints:Smoking cessation training requirements and consultation time allocation are limiting the scalability of pharmacy-based intervention models.
- Cold chain logistics complexity:Gum and lozenge formats requiring temperature-controlled storage are increasing distribution costs and expiry risk in remote and tropical supply corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Nicotine Replacement Therapy Market |
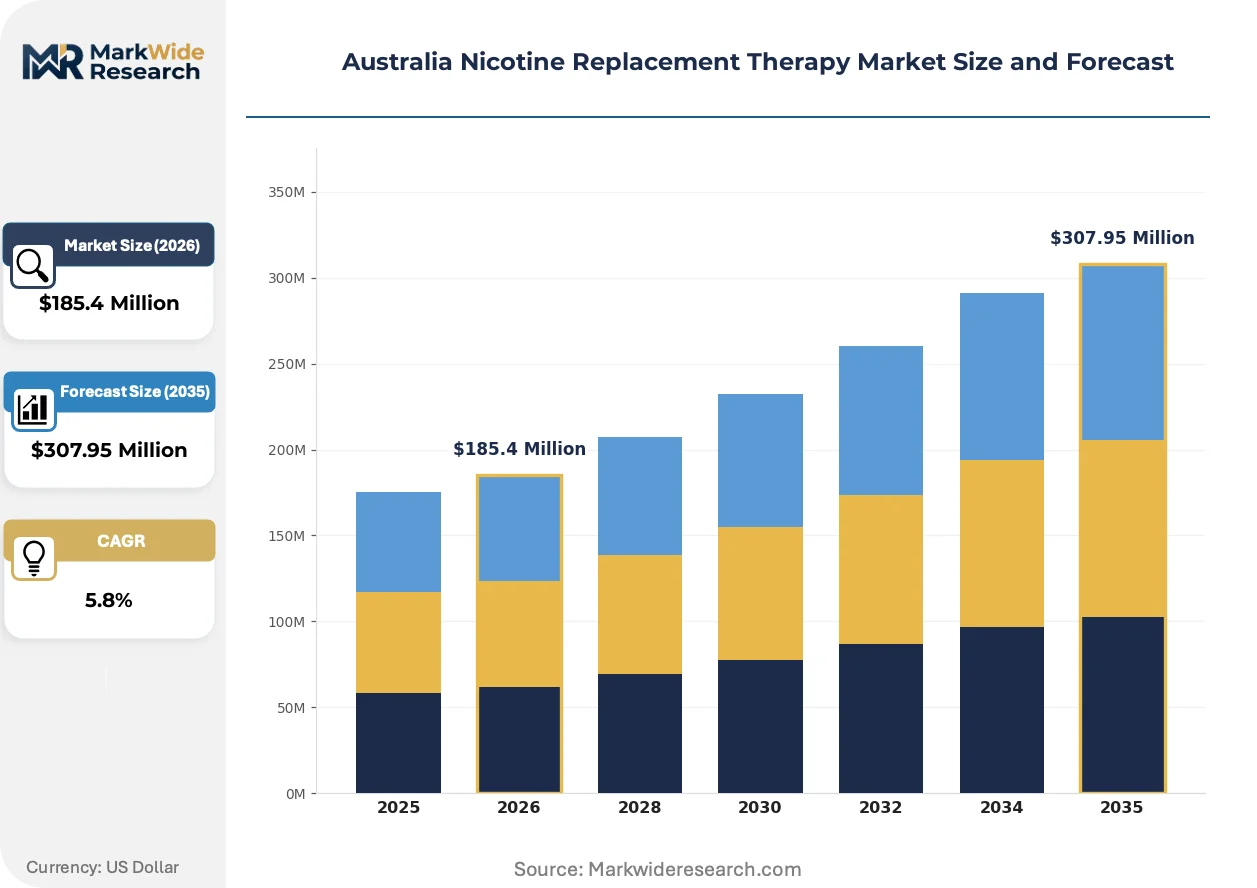
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patches, Gum, Inhalers, Lozenges Delivery Mode: Transdermal, Oral, Inhalation, Sublingual End User: Hospitals, Pharmacies, Clinics, Online Retailers Pricing Model: Generic, Branded, Subscription, Discounted |
| Companies Covered | Haleon Group of Companies, GlaxoSmithKline, Pfizer Inc., Philip Morris Products S.A., British American Tobacco p.l.c., Perrigo Company plc, Johnson & Johnson, Novartis International AG, Cipla Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Nicotine Replacement Therapy Market Trends and Innovations
Formulation science and channel automation are converging to reshape how nicotine replacement reaches Australian smokers, with sustained-release technologies and digital adherence tools displacing conventional dosing paradigms.
Transdermal patch systems incorporating ethylene-vinyl acetate membrane matrices are expanding into precision-dosing applications that match plasma concentration curves to individual withdrawal severity profiles. Hospital formulary committees and occupational health programs are adopting these customizable formats at accelerated rates. The technology is expanding into employer-sponsored cessation benefits where predictable pharmacokinetics reduce program dropout rates and improve return-on-investment metrics for corporate wellness budgets.
Australia's Therapeutic Goods Administration tightened packaging and scheduling requirements for nicotine-containing products, mandating child-resistant formats and pharmacy-exclusive distribution. This regulatory compression has eliminated competing unregulated channels and consolidated purchasing into TGA-audited supply chains. Generic manufacturers and private-label suppliers are responding by accelerating product registration timelines and investing in compliance infrastructure to maintain formulary access.
Subscription-based replenishment models are displacing episodic over-the-counter purchasing as the dominant online channel behavior, with automated delivery cycles locking in recurring revenue streams. Pharmacy chains and direct-to-consumer platforms are capturing this shift through loyalty-integrated apps that synchronize dosing reminders with refill shipments. Victoria and New South Wales metropolitan corridors exhibit the highest concentration of these digitally enabled adherence programs, where quitline referral volumes and e-commerce penetration overlap most densely.
Australia Nicotine Replacement Therapy Market Segmentation
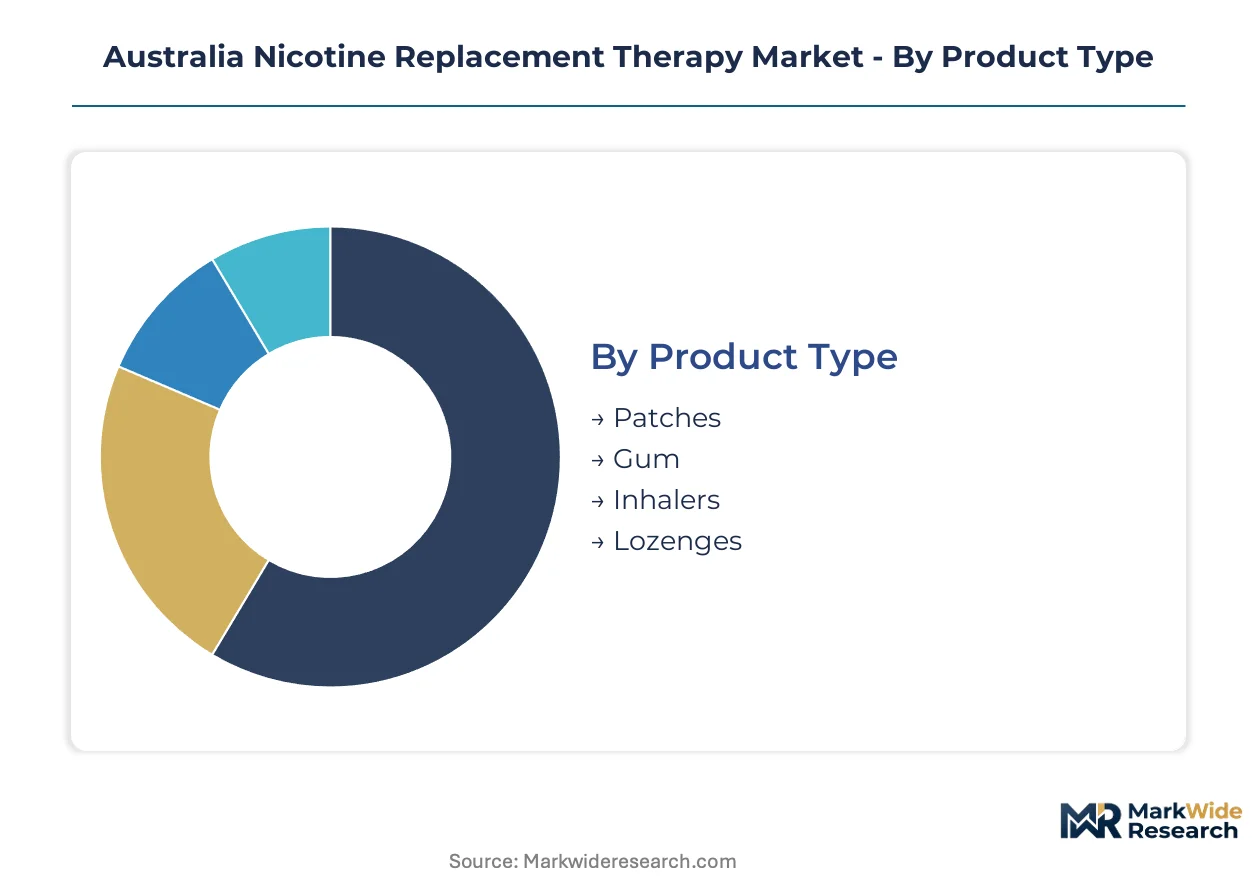
NRT segmentation in Australia reflects channel regulation by the Therapeutic Goods Administration and the Pharmaceutical Benefits Scheme subsidy architecture. Product format and delivery mode choices directly determine pharmacy formulary placement, reimbursement eligibility, and patient adherence patterns across metropolitan and regional catchments.
Product Type:
Volume sales concentrate in formats offering once-daily application simplicity, while premium positioning attaches to rapid-onset delivery systems for acute withdrawal management.
- Patches:Ethylene-vinyl acetate membrane matrices enable sustained nicotine plasma concentration over 16-24 hour intervals. Metropolitan Sydney and Melbourne pharmacies report highest turnover where quitline referral density supports prescription-driven dispensing. TGA scheduling mandates child-resistant packaging and pharmacy-exclusive distribution, eliminating competing unregulated channels.
- Gum:Polacrilex resin matrices deliver acute nicotine bursts through buccal absorption, targeting immediate craving relief. Cold chain logistics complexity elevates distribution costs in Queensland and Western Australia tropical corridors, constraining regional penetration despite strong hospital formulary demand.
- Inhalers:Handheld vaporization devices mimic behavioral rituals of combustible smoking. Specialist smoking cessation clinics in Victoria deploy these for behavioral substitution protocols.
- Lozenges:Sublingual dissolution formats combine discreet administration with rapid systemic absorption. Subscription automation through direct-to-consumer platforms is climbing the fastest among all product types.
Mature deployment sits with Patches. Newer deployment is concentrated in Lozenges.
Delivery Mode:
Pharmacokinetic precision determines formulary tier placement, with sustained-release technologies commanding hospital procurement premiums over acute-onset alternatives.
- Transdermal:Membrane-controlled diffusion maintains steady-state nicotine levels without dosing peaks. Occupational health programs across New South Wales manufacturing corridors adopt these for predictable cessation outcome metrics.
- Oral:Buccal and gastrointestinal absorption routes require patient education on proper chewing technique and consumption timing. Pharmacist counseling capacity constraints in regional pharmacies limit scalable deployment.
- Inhalation:Pulmonary deposition mimics cigarette inhalation kinematics, addressing behavioral dependency dimensions. Hospital smoking cessation wards in Melbourne cluster procurement around metered-dose inhaler formats.
- Sublingual:Rapid venous uptake through sublingual vasculature bypasses first-pass hepatic metabolism. Digital therapeutic convergence with smartphone adherence tracking is expanding most quickly in employer-sponsored wellness programs.
Established procurement patterns favor Transdermal. Innovation investment flows toward Sublingual.
End User:
Institutional prescribing volumes diverge from over-the-counter commerce, with state health department quitline infrastructure directing patient flows toward subsidized channels.
- Hospitals:Inpatient smoking cessation protocols and pre-surgical preparation mandates generate concentrated demand for patch and inhaler formats. GlaxoSmithKline anchors this channel through established formulary relationships with state health departments.
- Pharmacies:Community dispensing represents the dominant volume channel following TGA scheduling compression into pharmacy-only access. Shelf space expansion across New South Wales and Victoria pharmacy chains reflects program traction.
- Clinics:General practitioner prescribing automation through electronic medical record prompts embeds NRT into chronic disease management workflows. Victoria metropolitan corridors exhibit highest e-prescribing integration density.
- Online Retailers:Subscription pricing models reduce per-unit costs and automate replenishment cycles. This channel is gaining share fastest as recurring revenue platforms displace episodic purchasing.
Institutional volume concentrates in Hospitals. Patient-directed growth centers on Online Retailers.
Pricing Model:
Reimbursement eligibility through the Pharmaceutical Benefits Scheme creates a bifurcated market between subsidized prescription access and full-fare over-the-counter commerce.
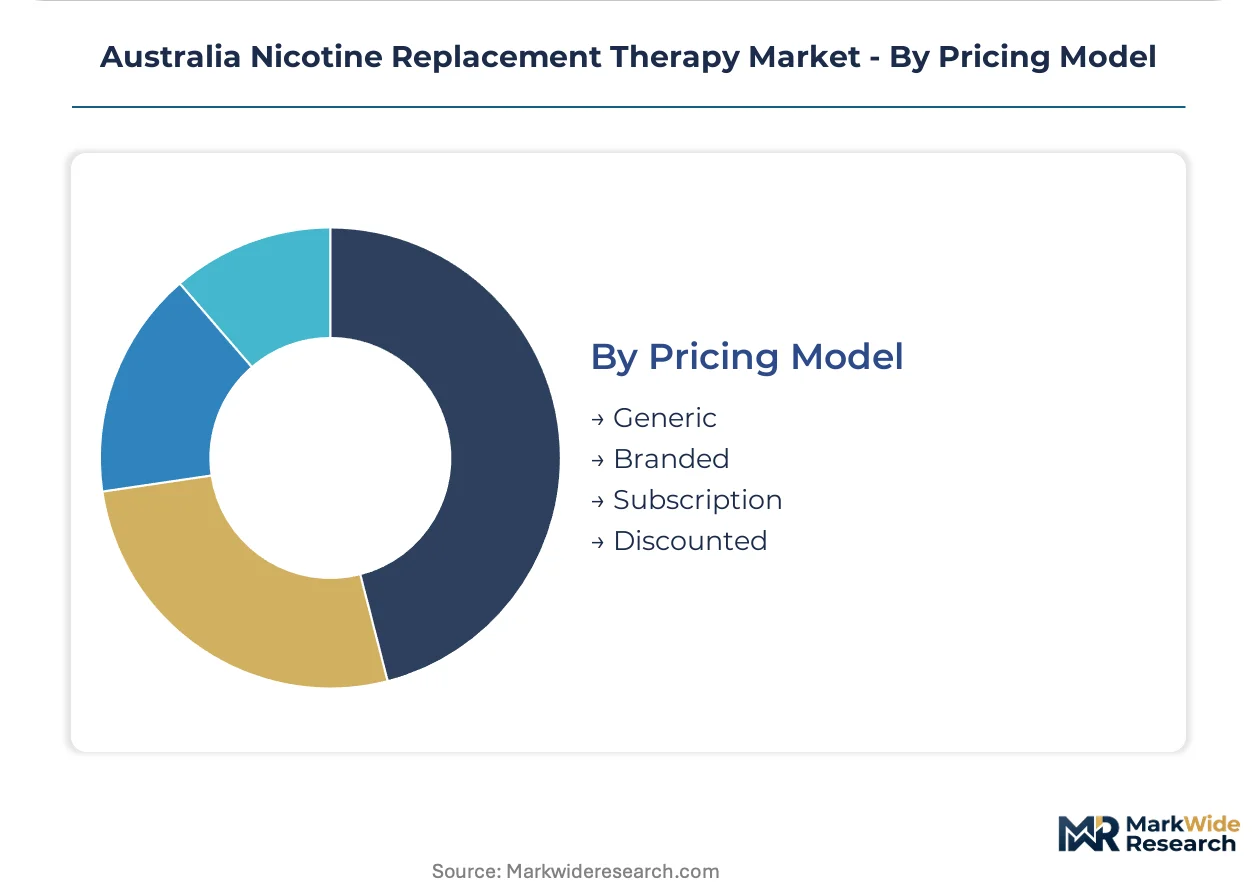
- Generic:Private-label and unbranded formulations compete on unit economics for price-sensitive cessation attempts. Perrigo Company plc occupies this tier aggressively across Australian retail networks.
- Branded:Johnson & Johnson consumer health division sustains pharmacy shelf presence through brand equity and clinician familiarity. Premium positioning supports margin defense against generic erosion.
- Subscription:Automated replenishment cycles lock in recurring revenue through loyalty-integrated apps synchronizing dosing reminders with refill shipments. Sydney and Melbourne metropolitan penetration exceeds regional catchments.
- Discounted:Bulk procurement arrangements and employer-sponsored cessation benefits reduce out-of-pocket expenditure. Queensland and Western Australia present whitespace for formulary placement expansion.
Volume leadership resides with Generic. Value capture is shifting toward Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nicotine base feedstock for Australian NRT manufacturing flows primarily through specialized chemical importers concentrated in Port Botany and Melbourne's chemical handling precincts.
New South Wales
Quitline referral volumes from Sydney metropolitan health districts drive prescription NRT dispensing through community pharmacy networks. The state's Therapeutic Goods Administration scheduling enforcement redirects purchases from unregulated channels into audited pharmacy supply chains. Port Botany chemical handling facilities anchor import logistics for nicotine active pharmaceutical ingredients serving domestic formulators.
Victoria
Melbourne's hospital smoking cessation wards generate concentrated procurement demand for patch and inhaler formats through state health department formulary relationships. Electronic medical record prompts in Victorian general practice clinics embed NRT prescribing into chronic disease management workflows. The Melbourne metropolitan corridor exhibits Australia's highest density of digitally enabled subscription adherence programs.
Queensland
Cold chain logistics complexity for gum and lozenge formats elevates distribution costs across tropical supply corridors, constraining regional penetration despite hospital formulary demand. The state's health department coordinates quitline services generating pharmacy referral flows in Brisbane and Gold Coast catchments. Whitespace exists for pharmacy network expansion and pharmacist-led cessation counseling in underserved regional areas.
Western Australia
Perth metropolitan pharmacies report lower NRT turnover density compared to eastern seaboard states, reflecting reduced quitline infrastructure penetration. Temperature-controlled storage requirements for oral formats increase expiry risk in remote supply chains serving the state's vast geography. Employer-sponsored cessation benefits in Western Australia mining corridors present targeted opportunities for occupational health program formulary placement.
Australia Nicotine Replacement Therapy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent reduced-harm nicotine delivery systems outside TGA-regulated pharmacy channels. The market structure consolidates around three strategic archetypes: multinational consumer health divisions sustaining pharmacy shelf presence through brand equity, generic manufacturers competing on unit economics for price-sensitive cessation attempts, and tobacco industry incumbents pivoting toward heat-not-burn substitution products. Dominant competitive moves include portfolio diversification across NRT formats and strategic partnerships with state health departments for formulary anchoring.
Within the multinational consumer health tier, Johnson & Johnson and GlaxoSmithKline exemplify established pharmacy channel anchoring through clinician familiarity and hospital procurement relationships. Perrigo Company plc occupies the value-tier position, representing aggressive generic pricing strategies that attract cost-conscious smokers attempting cessation. These three entities collectively illustrate the competitive spectrum from premium brand defense to economy-tier volume capture across Australian retail networks.
| Leading Market Players |
|---|
| Haleon Group of Companies |
| GlaxoSmithKline |
| Pfizer Inc. |
| Philip Morris Products S.A. |
| British American Tobacco p.l.c. |
| Perrigo Company plc |
| Johnson & Johnson |
| Novartis International AG |
| Cipla Ltd. |
| Others |
Pricing and Supply Chain Analysis
Pharmacist workforce concentration across New South Wales and Victoria establishes labor-cost differentials that widen pricing-tier spreads between metropolitan pharmacy networks and regional dispensing channels. The Therapeutic Goods Administration's pharmacy-only scheduling mandate amplifies these geographic cost disparities, as counseling-intensive formats require trained personnel unavailable at uniform wage scales nationwide.
Pricing Analysis
Pharmacist counseling service bundling separates prescription-subsidized formats from over-the-counter unbundled transactions, with the Pharmaceutical Benefits Scheme absorbing professional consultation costs for eligible patients. Pricing stratifies across premium branded patches, standard generic gums, and economy-tier private-label lozenges based on formulation complexity and brand equity. Cost compression in the generic tier intensifies as Perrigo Company plc and domestic manufacturers compete on unit economics for price-sensitive first-time quitters. Hospital procurement committees exhibit lowest price sensitivity due to formulary anchoring and outcome-based program budgets, while individual consumers at convenience-oriented online retailers drive hardest bargain-hunting behavior.
Supply Chain Analysis
Temperature-controlled freight costs from Port Botany and Melbourne chemical precincts to Queensland and Western Australia tropical corridors elevate landed costs for oral NRT formats requiring cold chain integrity. Nicotine active pharmaceutical ingredient supply concentrates in India, China, and Switzerland, with domestic formulators drawing from specialized chemical importers rather than captive production. Single-source vulnerability persists for high-purity nicotine base refined through limited European and Asian facilities. Distribution runs through pharmacy wholesale networks anchored by Symbion and Sigma Healthcare, with direct-to-consumer platforms bypassing traditional intermediaries through subscription automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian NRT market sits in a technology-transition phase as digital therapeutic platforms and smartphone adherence tools displace legacy episodic purchasing patterns and pharmacist-dependent counseling models.
For Market Incumbents: Anchor formulary relationships with state health departments through GlaxoSmithKline-style hospital procurement contracts that lock out generic substitution. Deepen backward integration into nicotine API sourcing to mitigate Indian and Chinese supply concentration risks. Defend against heat-not-burn substitution by accelerating precision-dosing patch development for occupational health programs. For New Entrants and Emerging Players: Online pharmacy platforms represent the most penetrable channel partner type for subscription-based lozenge formats bypassing incumbent shelf dominance. Target Queensland and Western Australia regional whitespace where quitline infrastructure remains underdeveloped and pharmacist counseling capacity constraints limit incumbent scalability. Pursue employer-sponsored wellness program direct contracts as a go-to-market angle circumventing pharmacy channel gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with digitally enabled adherence platforms given convergence between NRT dosing and smartphone behavioral support apps. Long-term viability favors assets with subscription automation infrastructure and formulary anchoring rather than pure generic manufacturing. Watch TGA rescheduling deliberations as the inflection signal that could either expand supermarket distribution or entrench pharmacy-exclusive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Therapeutic Integration | Smartphone adherence apps embedding NRT dosing create payer-preferred outcome metrics for employer wellness budgets. |
| Regional Pharmacy Network Expansion | Queensland and Western Australia formulary placement captures underserved catchments beyond Sydney-Melbourne corridor density. |
| Subscription Automation Platform | Recurring replenishment models lock in lifetime value exceeding episodic over-the-counter transaction economics. |
| Precision-Dosing Patch Development | Ethylene-vinyl acetate membrane customization matches plasma curves to individual withdrawal severity profiles. |
| API Supply Security Investment | Backward integration into nicotine base sourcing reduces vulnerability to Indian and Chinese chemical manufacturer concentration. |
Research Methodology
Independent corroboration across pharmacy chain procurement directors, state health department formulary managers, and smoking cessation clinic coordinators underwrites the qualitative findings. Primary interviews with Therapeutic Goods Administration regulatory affairs specialists, nicotine API importers at Port Botany, and subscription platform operators supplemented secondary validation through PBS reimbursement databases, TGA scheduling registers, and hospital procurement contract disclosures. Bottom-up pharmacy dispensing volume estimates triangulate against top-down manufacturer shipment data.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation modeling incorporates product format, delivery mode, end-user channel, and pricing model dimensions alongside regional regulatory cluster variations. CAGRs derive from fitted trend extrapolation calibrated to PBS subsidy expansion trajectories and quitline referral volume growth patterns. Forecast inputs include TGA scheduling enforcement intensity and heat-not-burn product penetration rates as scenario variables.
Caveats apply where TGA rescheduling deliberations, nicotine API supply disruptions, or heat-not-burn substitution acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Global Slimming Aids Market