
 Ipriflavone Market | 2026-2036
Ipriflavone Market Size, Share, and Industry Trends Forecast 2026-2036
Ipriflavone Market Analytics
Aftermarket service revenue from formulation consulting is narrowing as raw material suppliers consolidate technical support in-house. DSM Nutritional Products leverages its backward integration into fermentation-derived precursors to sustain margin capture. BASF SE anchors European supply through its specialty chemical network. Zhejiang Medicine Co., Ltd. competes on cost-optimized synthetic routes for bulk pharmaceutical-grade output.
Ipriflavone is a synthetic isoflavone derivative with the chemical formula C18H16O3, manufactured through multi-step organic synthesis from phenolic intermediates and used primarily as an anti-osteoporotic agent that inhibits bone resorption without estrogenic effects on breast or uterine tissue. Tablet and capsule formats dominate current revenue as healthcare professionals prescribe standardized doses for osteoporosis management, while powder formulations capture expanding demand from contract manufacturers serving private-label dietary supplement brands. The geriatric population segment concentrates value as demographic aging across developed economies drives prescription-grade bone health protocols.
The FDA oversees dietary supplement GMP compliance and New Dietary Ingredient notifications for ipriflavone-containing products in the United States, while Japan's PMDA enforces pharmaceutical-grade isoflavone purity standards that shape export qualification requirements for Asian manufacturers. China's NMPA regulates domestic ipriflavone production through drug master file submissions and active pharmaceutical ingredient certification. Stakeholders must monitor evolving pharmacovigilance requirements for synthetic isoflavones as regulatory bodies reassess long-term bone metabolism safety data.
Market Dynamics
Pharmaceutical-grade purity requirements are concentrating ipriflavone supply among fermentation-capable manufacturers with backward integration into phenolic precursor production, filtering out synthetic-only suppliers across Japan, China, and India.
Growth Catalysts
- PMDA pharmaceutical-grade standards:Japan's stringent isoflavone purity thresholds create qualification barriers that reward certified suppliers with premium pricing and long-term contracts from geriatric-focused formulators.
- Geriatric bone health protocols:Aging demographics across developed economies drive prescription-grade demand for anti-osteoporotic agents without estrogenic side effects on breast or uterine tissue.
- Fermentation-derived precursors:Biotechnological manufacturing routes reduce reliance on petroleum-based phenolic intermediates while improving batch-to-batch consistency for API certification.
Market Restraints
- Phenolic intermediate volatility:Petrochemical feedstock price swings compress margins for synthetic route manufacturers lacking captive precursor supply.
- East Asian supply concentration:Volume production concentrates in Zhejiang and Jiangsu provinces, creating single-source vulnerability for European and North American formulators.
- Estrogenic safety reassessments:Evolving pharmacovigilance requirements for synthetic isoflavones extend regulatory approval timelines for new therapeutic indications.
Strategic Opportunities
- Contract manufacturing expansion:Private-label dietary supplement brands in North America seek toll manufacturers with dual pharmaceutical and nutraceutical GMP certification.
- India's CDSCO pathway:Domestic API registration reforms accelerate market entry for bone-health formulations targeting the country's expanding middle-class geriatric population.
- Powder formulation growth:Bulk ingredient demand from functional food developers creates volume opportunities beyond traditional tablet and capsule formats.
Industry Challenges
- Multi-jurisdiction GMP harmonization:Simultaneous compliance with FDA dietary supplement rules, PMDA pharmaceutical standards, and NMPA drug master file requirements strains quality management systems.
- Synthetic organic chemistry talent scarcity:Specialized expertise in multi-step phenolic derivatization limits production scale-up for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ipriflavone Market |
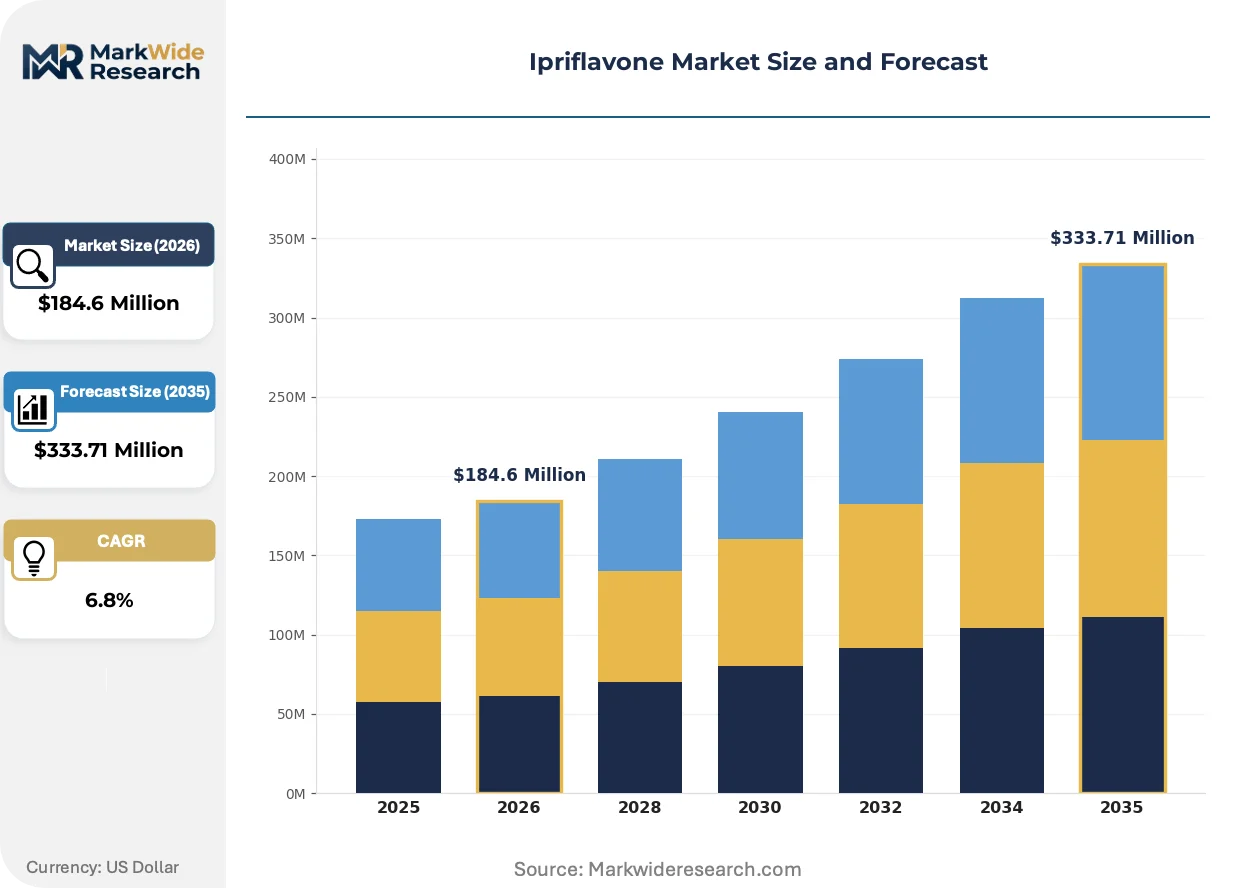
| Market Size in 2026 | $184.6 Million |
| Market Size in 2035 | $333.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Liquid Application: Bone Health, Osteoporosis, Menopause Symptoms, Dietary Supplements End User: Healthcare Professionals, Retail Consumers, Fitness Enthusiasts, Geriatric Population Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | DSM Nutritional Products, BASF SE, Zhejiang Medicine Co., Ltd., CSPC Pharmaceutical Group, Shanghai Freemen LLC, Xi’an Natural Field Bio-Technique, Hangzhou Think Chemical, Hubei Yuancheng Pharmaceutical, Shaanxi Pioneer Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ipriflavone Market Evolving Landscape
Process analytical technology and continuous manufacturing are transforming ipriflavone production economics, compressing batch cycle times while real-time quality monitoring reduces rejected lots.
Continuous flow chemistry is digitizing synthetic route optimization through automated parameter control and predictive modeling. Mid-scale pharmaceutical manufacturers in Germany and Switzerland adopt these systems to compete with high-volume Asian fermentation operations. The technology is digitizing quality assurance workflows, enabling real-time release testing that shortens inventory holding periods.
REACH authorization requirements for phenolic intermediates are tightening supply chain documentation obligations across European formulators. Manufacturers must now demonstrate substance volume tracking and exposure scenario assessments for downstream uses. Specialty chemical distributors in the Netherlands and Belgium are consolidating technical dossier management services to absorb compliance costs.
Healthcare practitioner prescribing patterns favor standardized-dose protocols over compounded alternatives, concentrating demand with established tablet and capsule suppliers. Hospital formulary committees in Japan and South Korea increasingly require bone metabolism biomarker data supporting therapeutic claims. This certification-driven preference shift rewards manufacturers with published clinical evidence packages.
Ipriflavone Market Segmentation
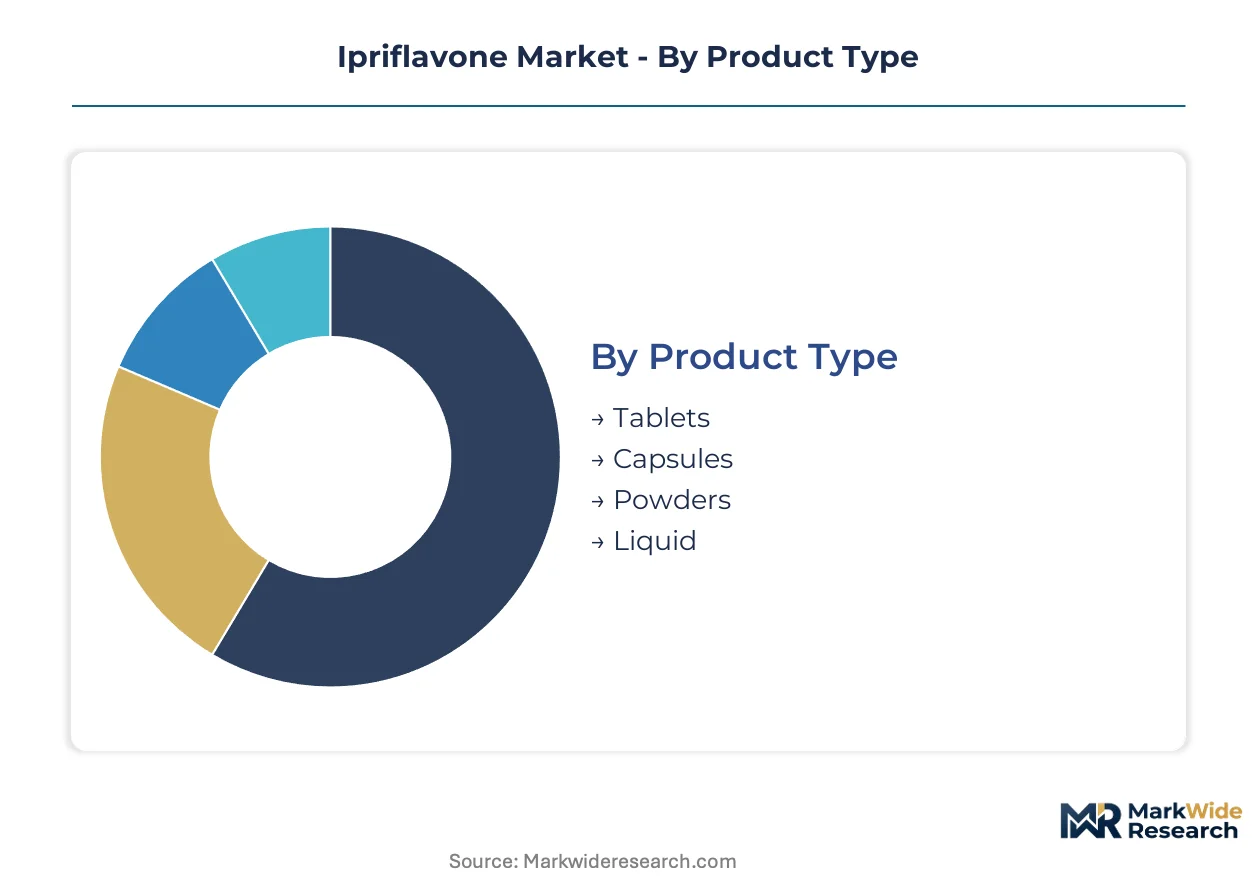
Ipriflavone's position between pharmaceutical and nutraceutical regulatory frameworks fragments demand across distinct product formats and prescribing contexts. Segmentation reveals how bone-health protocols concentrate value in standardized-dose formats while private-label supplement brands drive powder volume.
Product Type:
Mature tablet and capsule formats dominate prescription workflows, while emerging powder and liquid formats capture functional food innovation and compounding pharmacy demand.
- Tablets:Compressed dosage forms with standardized isoflavone content enable precise osteoporosis management protocols. Hospital formulary committees in Japan and South Korea require these formats for bone metabolism biomarker-supported therapeutic claims, locking in premium positioning for certified manufacturers.
- Capsules:Gelatin or vegetable-based shells mask the bitter phenolic taste of synthetic isoflavones while enabling modified-release formulations. North American geriatric-focused supplement manufacturers prefer capsules for combination products pairing ipriflavone with calcium and vitamin D.
- Powders:Bulk ingredient format serving contract manufacturers and functional food developers seeking formulation flexibility.
- Liquid:Emerging format for pediatric and dysphagia patient populations requiring dose titration.
Tablets retain volume leadership; powders hold the steepest expansion curve.
Application:
Cost tier stratification separates prescription-grade bone metabolism indications from over-the-counter wellness positioning.
- Bone Health:Prophylactic and therapeutic protocols targeting age-related bone density loss concentrate demand in pharmaceutical-grade supply chains. Japan's PMDA certification requirements filter suppliers for this indication, rewarding fermentation-capable manufacturers with backward integration into phenolic precursors.
- Osteoporosis:Confirmed diagnosis indication requires API-grade documentation and clinical evidence packages. Hospital procurement in Germany and Switzerland demands continuous manufacturing quality metrics that synthetic-only suppliers struggle to satisfy.
- Menopause Symptoms:Positioned as non-hormonal alternative for vasomotor symptom management with limited regulatory recognition.
- Dietary Supplements:General wellness positioning with lower purity thresholds and price-sensitive procurement.
Osteoporosis commands premium pricing; dietary supplements are gaining share fastest.
End User:
Customer type fragmentation splits volume between institutional prescribing and direct-to-consumer purchasing patterns.
- Healthcare Professionals:Physicians and specialists prescribing standardized protocols drive demand for tablet and capsule formats with published clinical evidence. China's NMPA drug master file requirements shape supplier qualification for hospital procurement.
- Geriatric Population:Aging demographics across developed economies concentrate value as this segment requires anti-osteoporotic agents without estrogenic effects on breast or uterine tissue. Japan's demographic trajectory sustains long-term contract demand.
- Retail Consumers:Self-directed purchasers responding to bone health marketing in pharmacies and online channels.
- Fitness Enthusiasts:Niche segment seeking bone density support for high-impact training regimens.
Healthcare professionals anchor revenue stability; the geriatric population is climbing the fastest.
Distribution Channel:
Geography of procurement determines compliance burden and margin structure across channel types.
- Pharmacies:Regulated dispensing channels in Japan, Germany, and Switzerland require cold chain documentation and batch traceability. Pharmacist counseling reinforces standardized-dose protocols over compounded alternatives.
- Online Retail:Cross-border e-commerce platforms concentrate volume for private-label dietary supplement brands seeking toll manufacturers with dual pharmaceutical and nutraceutical GMP certification.
- Health Stores:Specialized retailers serving wellness-focused consumers with practitioner-grade supplement lines.
- Supermarkets:Mass-market placement for economy-tier products with limited therapeutic positioning.
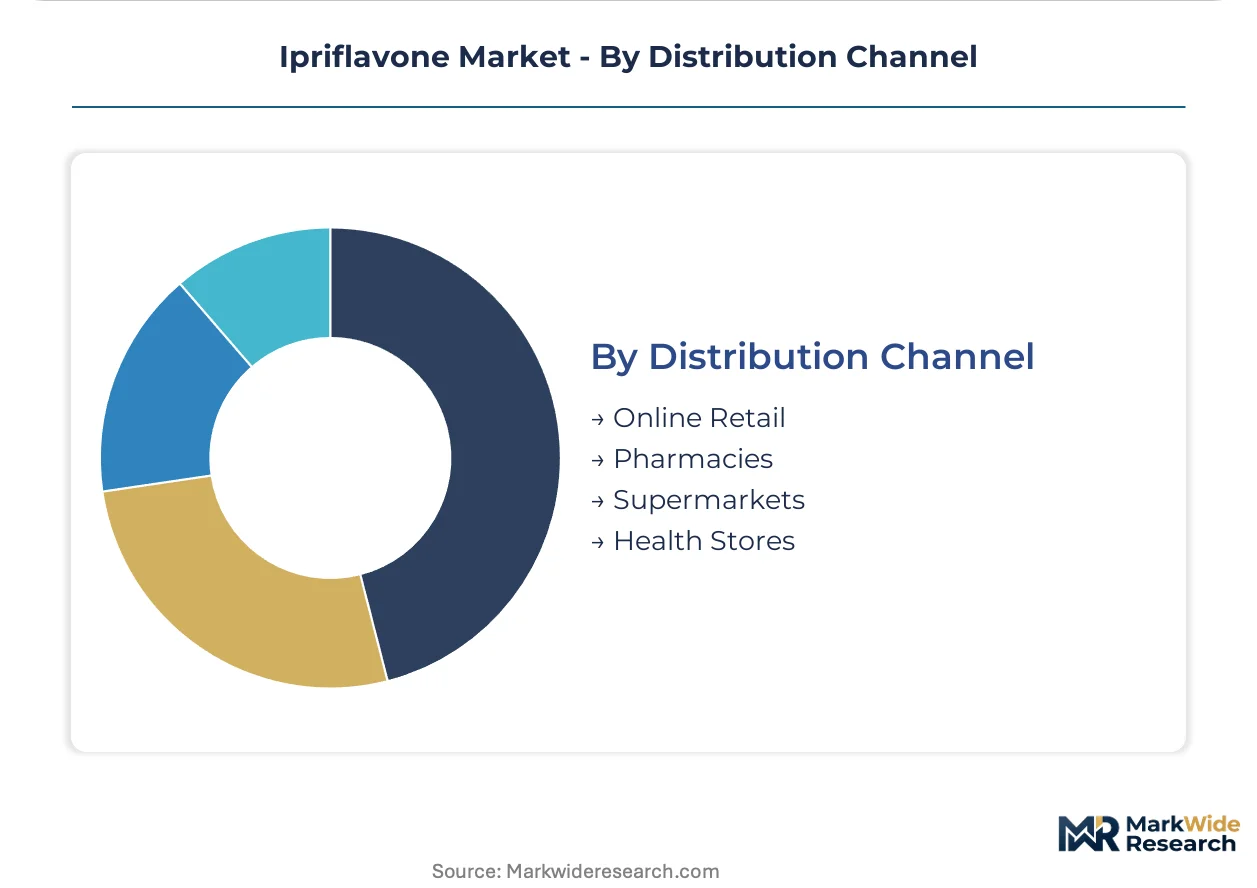
Pharmacies maintain margin leadership; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit acute price sensitivity, driving procurement toward cost-optimized synthetic routes, while Japanese and German purchasers absorb premium pricing for fermentation-derived pharmaceutical-grade certification.
Japan
PMDA pharmaceutical-grade isoflavone purity thresholds filter low-grade suppliers from geriatric-focused formulator contracts. The regulator's bone metabolism biomarker documentation requirements lock in premium positioning for certified manufacturers. Tokyo and Osaka pharmaceutical clusters concentrate demand for anti-osteoporotic agents without estrogenic side effects.
China
NMPA drug master file submissions and active pharmaceutical ingredient certification shape domestic production compliance. Volume procurement concentrates in Zhejiang and Jiangsu provinces for bone-health formulations serving both domestic and export markets. Shanghai and Hangzhou chemical parks anchor synthetic route manufacturing with cost-optimized output.
India
CDSCO domestic API registration reforms accelerate market entry for bone-health formulations targeting the expanding middle-class geriatric population. Hyderabad and Ahmedabad pharmaceutical clusters compete on fermentation-capable manufacturing with backward integration into phenolic precursors. Mumbai-based formulators drive toll manufacturing demand for private-label dietary supplement brands.
Germany
REACH authorization requirements for phenolic intermediates tighten supply chain documentation obligations for European formulators. EMA-aligned hospital procurement demands continuous manufacturing quality metrics that synthetic-only suppliers struggle to satisfy. Basel-proximate chemical distributors consolidate technical dossier management services to absorb compliance costs.
United States
FDA dietary supplement GMP compliance and New Dietary Ingredient notifications shape ipriflavone-containing product market entry. New Jersey and North Carolina pharmaceutical corridors concentrate prescription-grade tablet and capsule manufacturing for standardized osteoporosis protocols. Boston-area geriatric research institutions drive clinical evidence requirements for hospital formulary placement.
Ipriflavone Market Competitive Landscape
Capability concentration sits with fermentation-backed manufacturers holding captive phenolic precursor supply; scale advantage sits with high-volume synthetic operators in East Asian chemical parks. The market structures around three tiers: pharmaceutical-grade certified suppliers, nutraceutical-focused toll manufacturers, and commodity bulk ingredient traders. Strategic moves center on backward integration into fermentation-derived precursors and dual pharmaceutical-nutraceutical GMP certification acquisition.
Within the fermentation-capable tier, DSM Nutritional Products exemplifies backward integration into precursor production, while BASF SE anchors European supply positioning through specialty chemical network density. Zhejiang Medicine Co., Ltd. occupies the cost-optimized synthetic route segment for bulk pharmaceutical-grade output. These three archetypes represent the competitive vectors shaping qualification barriers and margin capture across Japan, China, and India procurement channels.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| BASF SE |
| Zhejiang Medicine Co., Ltd. |
| CSPC Pharmaceutical Group |
| Shanghai Freemen LLC |
| Xi'an Natural Field Bio-Technique |
| Hangzhou Think Chemical |
| Hubei Yuancheng Pharmaceutical |
| Shaanxi Pioneer Biotech |
| Others |
Value Network & Pricing Analysis
Phenolic intermediate price volatility compresses margins for synthetic route manufacturers lacking captive precursor supply, determining both the three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and commodity bulk tiers and the geographic clustering of fermentation-capable producers in East Asian chemical parks.
Pricing Analysis
Formulation consulting revenue from aftermarket services drives lifetime value for raw material suppliers consolidating technical support in-house. Pricing stratifies across PMDA-certified pharmaceutical-grade, dual GMP nutraceutical-grade, and uncertified commodity bulk tiers. Cost compression in synthetic-only manufacturing intensifies because petroleum-based phenolic feedstock swings erode batch economics. Contract manufacturers serving private-label brands exhibit acute price sensitivity, while Japanese geriatric-focused formulators absorb premium pricing for fermentation-derived API certification.
Supply Chain Analysis
Toll manufacturers with dual pharmaceutical and nutraceutical GMP certification hold contract manufacturing concentration for North American private-label brands. Volume production concentrates in Zhejiang and Jiangsu provinces, with secondary fermentation capacity in Hyderabad and Ahmedabad. Supply draws from phenolic intermediates, fermentation-derived precursors, and gelatin or vegetable-based capsule shells. Single-source vulnerability in East Asian chemical parks threatens European and North American formulators. Distribution runs through specialty chemical distributors in the Netherlands and Belgium consolidating technical dossier management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow chemistry digitization is reshaping competitive positioning in ipriflavone production, as real-time quality monitoring and automated parameter control compress batch cycle times for mid-scale pharmaceutical manufacturers competing with high-volume Asian fermentation operations.
For Market Incumbents: Insulate PMDA-certified supply positions by deepening backward integration into fermentation-derived phenolic precursors and acquiring dual GMP certification assets in India before CDSCO registration reforms accelerate domestic API competition. Synthetic-only manufacturers face displacement from fermentation-capable competitors with captive precursor supply.
For New Entrants and Emerging Players: Establish a beachhead in powder formulations for functional food developers seeking formulation flexibility beyond traditional tablet and capsule formats. India's expanding middle-class geriatric population offers the most penetrable geography, with toll manufacturing partnerships providing the fastest go-to-market angle for CDSCO-registered bone-health formulations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-capable manufacturers with backward integration into phenolic precursors over synthetic-only operators. Long-term viability over the next decade hinges on regulatory certification moats rather than scale economics alone. Watch for PMDA pharmacovigilance reassessments of synthetic isoflavone safety data as the inflection indicator triggering qualification barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Precursors | DSM Nutritional Products captures margin through in-house phenolic precursor production, filtering synthetic-only competitors from PMDA-certified supply chains. |
| Dual GMP Certification Acquisition | Toll manufacturers serving North American private-label brands qualify for hospital formulary and online retail channels simultaneously. |
| Continuous Flow Chemistry Adoption | German and Swiss mid-scale pharmaceutical manufacturers compress batch cycle times to compete with high-volume Asian fermentation operations. |
| CDSCO Domestic API Registration | Hyderabad and Ahmedabad pharmaceutical clusters accelerate market entry for bone-health formulations targeting India's geriatric expansion. |
| Powder Formulation Capacity Expansion | Contract manufacturers capture functional food innovation demand beyond standardized-dose tablet and capsule formats. |
Research Methodology
Operator-level perspectives from pharmaceutical manufacturing executives, regulatory affairs leads at API certification bodies, hospital formulary committee members, and private-label supplement brand procurement managers anchored the qualitative base. These primary insights combined with secondary validation from FDA New Dietary Ingredient notifications, PMDA pharmaceutical-grade isoflavone purity standards, NMPA drug master file submissions, and REACH authorization requirements for phenolic intermediates. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verified demand estimates.
Scenario-bracketing around regulatory approval timelines, phenolic feedstock price volatility, and pharmacovigilance reassessment outcomes framed the analytical approach across the analysis window. Segmentation dimensions included product format, application indication, end-user type, and distribution channel, with additional modeling of certification grade tiers. CAGRs derived from volume-demand elasticity curves and pricing power indices specific to pharmaceutical-grade versus nutraceutical-grade supply chains. Forecast inputs incorporated geriatric demographic trajectories and hospital procurement biomarker documentation requirements.
Sensitivities concentrate around PMDA purity threshold adjustments, REACH authorization scope expansion for phenolic intermediates, and CDSCO registration reform implementation pace. Forecasts reflect documented assumptions on regulatory stability and feedstock cost trajectories. Quarterly review of PMDA pharmacovigilance bulletins, NMPA drug master file approval velocities, and East Asian chemical park capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Sleep Supplement Market