
 Global Equine Pharmaceuticals and Supplements Market | 2026-2036
Global Equine Pharmaceuticals and Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Equine Pharmaceuticals and Supplements Market Foresight
Veterinary pharmacy distribution is fragmenting as online retailers and direct-to-barn channels erode traditional feed-store dominance. Zoetis Inc leverages its biologics manufacturing scale to control vaccine supply chains across North American racing circuits. Boehringer Ingelheim GmbH anchors its position through respiratory therapy specialization, while Merck & Co Inc competes on anthelmintic R&D intensity.
Equine pharmaceuticals and supplements comprise veterinary-grade therapeutics and nutritional adjuncts formulated for horses, including NSAIDs with specific plasma withdrawal periods, probiotics with colony-forming unit guarantees, and vaccines meeting potency standards for equid herpesvirus and influenza strains. Their primary commercial purpose is maintaining performance animal health while satisfying racing commission medication rules and export certification requirements. Nutritional supplements occupy the deepest margin pools as owners self-direct preventive spending, whereas musculoskeletal therapies lead prescription value due to joint injection protocols in sport horses. Vaccines represent the most mature segment with established annual revaccination schedules limiting expansion velocity.
The FDA's Center for Veterinary Medicine oversees pharmaceutical approvals and tissue residue limits, while the EU's EMA veterinary committee enforces antimicrobial marketing restrictions under revised regulations. Compliance with these frameworks shapes product development timelines and determines market access for novel therapeutics. Stakeholders must monitor evolving antimicrobial stewardship mandates and adapt portfolio weights toward biologics and nutritional categories ahead of regulatory tightening.
Market Dynamics
Antimicrobial stewardship mandates are compressing the therapeutic window for traditional pharmaceuticals while redirecting R&D investment toward biologics and nutritional categories across racing and sport horse segments.
Growth Catalysts
- Thoroughbred racing stables:Performance animal owners are expanding preventive care budgets to maintain competitive eligibility and reduce lay-up periods from musculoskeletal injuries.
- FDA veterinary feed directive:The Center for Veterinary Medicine's tightened oversight on medicated feeds is accelerating veterinary consultation rates and prescription product adherence.
- Equine cluster concentration:Dense veterinary infrastructure around Lexington, Kentucky and Ocala, Florida is shortening product distribution cycles and enabling rapid clinical feedback loops.
Market Restraints
- Active pharmaceutical ingredient volatility:Fluctuating costs for NSAID precursors and biologic fermentation substrates are compressing formulation margins.
- EU antimicrobial marketing restrictions:The EMA veterinary committee's revised regulations are extending product registration timelines and limiting label claims for conventional therapeutics.
- Joint injection substitution risk:Regenerative medicine protocols using autologous biologics are displacing synthetic intra-articular products in high-value sport horses.
Strategic Opportunities
- Brazilian equine sports expansion:FEI eventing growth and Olympic equestrian investment are creating demand for performance veterinary services outside traditional North American and European markets.
- Direct-to-barn distribution:Online pharmacy platforms and veterinary telemedicine integration are bypassing feed-store intermediaries and capturing margin previously lost to retail markups.
- Digital health convergence:Wearable biometric monitors combined with cloud-based herd management software are enabling predictive intervention models and supplement subscription bundling.
Industry Challenges
- Withdrawal period compliance:Racing commission medication rules vary across jurisdictions, creating complexity for trainers managing horses with multi-state competition schedules.
- Vaccine cold chain integrity:Equid herpesvirus and influenza potency standards require uninterrupted refrigeration from manufacturing through barn administration, straining rural distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Equine Pharmaceuticals and Supplements Market |
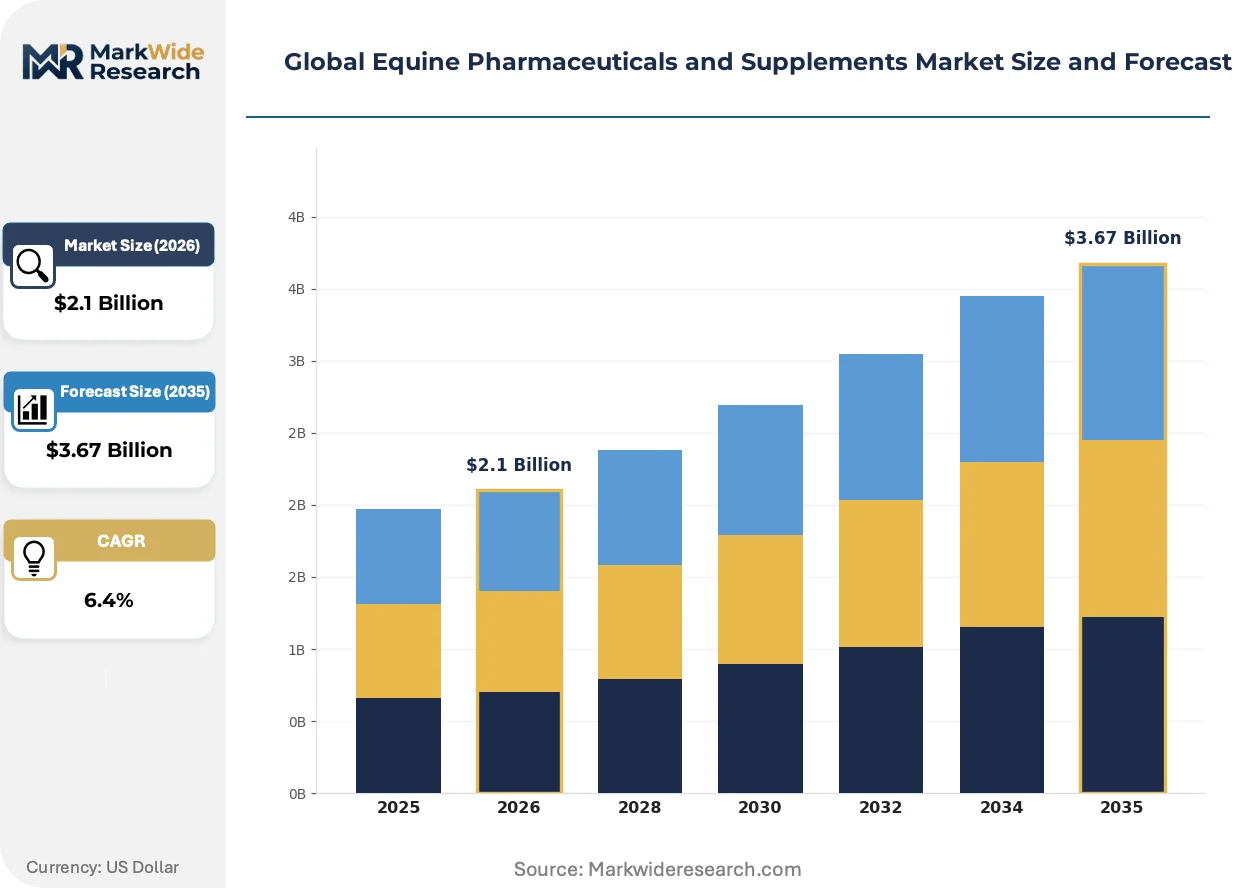
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-inflammatory, Nutritional Supplements, Anthelmintics, Antibiotics, Vaccines Therapy Area: Musculoskeletal, Respiratory, Digestive, Dermatological, Cardiovascular End User: Veterinary Clinics, Equine Hospitals, Specialty Practices, Research Facilities Distribution Channel: Online Retailers, Veterinary Pharmacies, Direct Sales, Feed Stores, Agricultural Supply Outlets |
| Companies Covered | Zoetis Inc, Boehringer Ingelheim GmbH, Merck & Co Inc, Elanco Animal Health Inc, Bayer AG, Ceva Sante Animale SA, Virbac SA, Vetoquinol SA, Kentucky Equine Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Equine Pharmaceuticals and Supplements Market Shifts & Advancements
Telemedicine platforms and predictive analytics are virtualizing traditional veterinary service delivery, while regulatory pressure on antimicrobial use is accelerating biologics development and nutritional formulation sophistication.
Telemedicine consultation systems are virtualizing routine veterinary assessments for non-emergency cases. Racing stables and breeding operations are adopting these platforms at accelerating rates to reduce veterinary travel costs and enable faster triage decisions. The technology is virtualizing the first-point-of-contact role previously held by field veterinarians, compressing response times while expanding specialist access for remote facilities.
The EU's revised veterinary medicinal product regulation is mandating enhanced environmental risk assessments for pharmaceutical residues. Manufacturers must now submit extended data packages on ecotoxicity before gaining marketing authorization. Respiratory therapy and anthelmintic categories face the steepest compliance burdens, with several active ingredients under formal review for restriction or withdrawal.
Subscription-based supplement programs are displacing transactional feed-store purchases among owner-operators managing fewer than ten horses. Digital platforms offering automated replenishment and veterinary-curated protocols are capturing this segment from traditional retail. The shift is most visible in the United States, where direct-to-consumer pharmacy licenses and telehealth regulations have enabled integrated preventive care bundles combining diagnostics, nutrition, and remote consultation.
Global Equine Pharmaceuticals and Supplements Market Segmentation
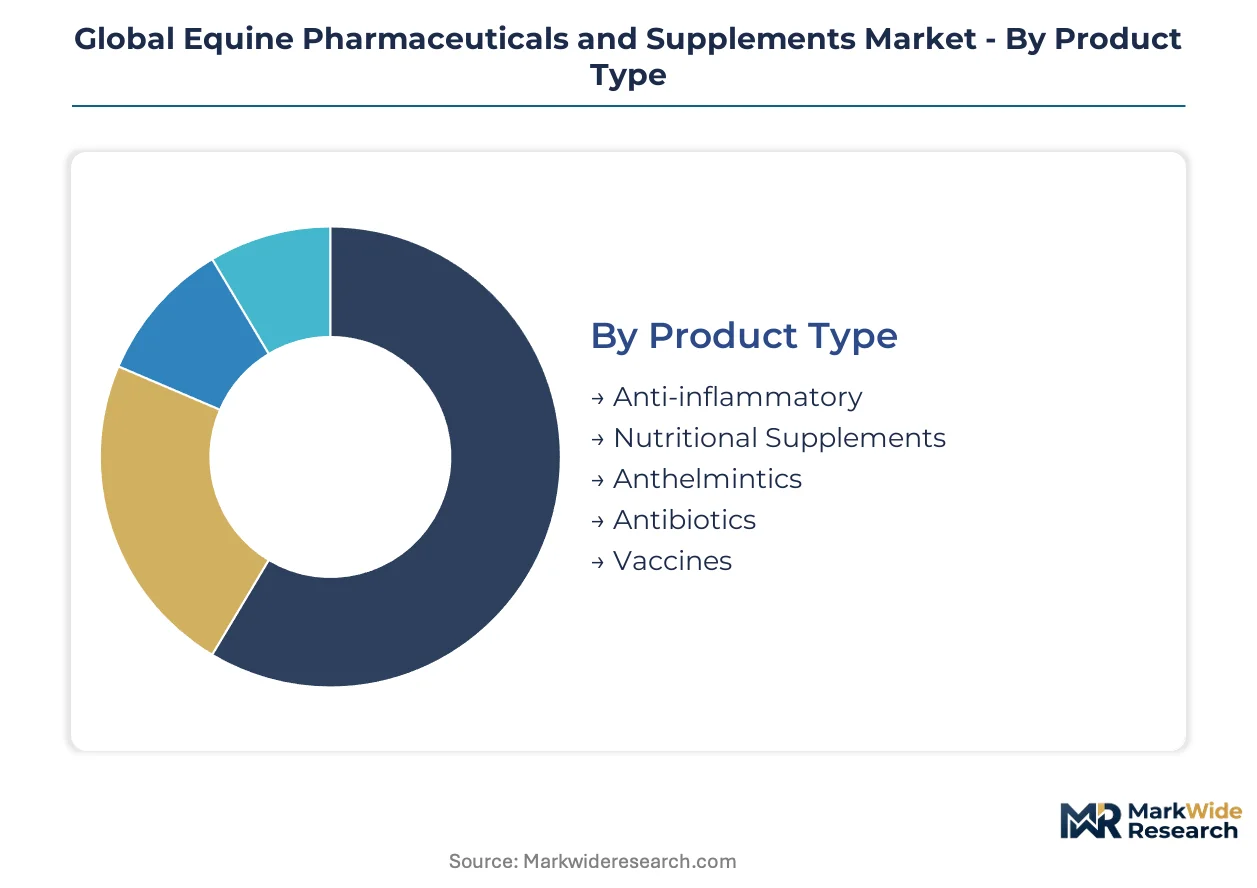
Segmentation in equine pharmaceuticals reveals divergent margin structures and regulatory exposure across therapeutic categories. Cycle times vary dramatically from annual vaccine revaccination to episodic joint injection protocols, reshaping inventory management and customer relationship economics for manufacturers and distributors alike.
Product Type:
Cycle times range from quarterly supplement replenishment to multi-year vaccine development pipelines, with anti-inflammatory and nutritional categories turning inventory fastest while anthelmintics face seasonal deworming concentration.
- Anti-inflammatory:NSAID formulations with species-specific plasma withdrawal periods dominate prescription volume in racing jurisdictions. Kentucky and Florida stables drive demand for phenylbutazone and firocoxib products as trainers manage competition schedules across multiple state racing commissions with varying medication rules.
- Nutritional Supplements:Probiotic, joint support, and electrolyte formulations with colony-forming unit guarantees or glucosamine purity standards. Owner-operators in the United States self-direct preventive spending through subscription platforms, displacing traditional feed-store purchases with automated replenishment protocols.
- Anthelmintics:Benzimidazole and macrocyclic lactone dewormers facing resistance management protocols.
- Antibiotics:Systemic antibacterial therapies constrained by FDA veterinary feed directive and EU antimicrobial stewardship mandates.
- Vaccines:Equid herpesvirus and influenza products with established annual revaccination schedules and stringent cold chain requirements.
Nutritional supplements anchors the volume base while anti-inflammatory gains share at the steepest rate.
Therapy Area:
Cost tiers stratify sharply, with musculoskeletal therapies commanding premium pricing for intra-articular protocols while dermatological and digestive categories compete on volume through over-the-counter channels.
- Musculoskeletal:Joint injection products and systemic therapies for performance horses. Sport horse disciplines in Germany and the Netherlands generate concentrated demand for hyaluronic acid and polysulfated glycosaminoglycan formulations as owners invest in competition longevity.
- Respiratory:Bronchodilators and corticosteroid therapies for exercise-induced pulmonary hemorrhage and inflammatory airway disease. Racing stables in Ireland and the United Kingdom prioritize respiratory management given high-intensity training regimens and damp climatic conditions.
- Digestive:Ulcer prophylaxis and colic management products, including omeprazole formulations.
- Dermatological:Topical antimicrobial and anti-fungal preparations for wound care and skin conditions.
- Cardiovascular:Diuretics and vasoactive agents for race-day bleeding control, heavily regulated by racing authorities.
Musculoskeletal commands the premium pricing tier while respiratory expands most quickly through biologics substitution.
End User:
Customer sophistication determines procurement patterns, with specialty practices driving protocol innovation while research facilities anchor validation requirements for novel therapeutic categories.
- Veterinary Clinics:General practice settings managing preventive care and first-line therapeutics. Clinics in Texas and California handle high caseloads from recreational horse populations with distributed geographic coverage.
- Equine Hospitals:Referral centers performing surgery and intensive care with 24-hour pharmacy capabilities. Rood and Riddle Equine Hospital in Kentucky and Palm Beach Equine Clinic in Florida set procurement standards for complex cases.
- Specialty Practices:Reproduction, dentistry, and sports medicine focused operations.
- Research Facilities:University veterinary schools and pharmaceutical development sites conducting clinical trials.
Equine hospitals concentrate the highest-value transactions while specialty practices climb fastest through telemedicine integration.
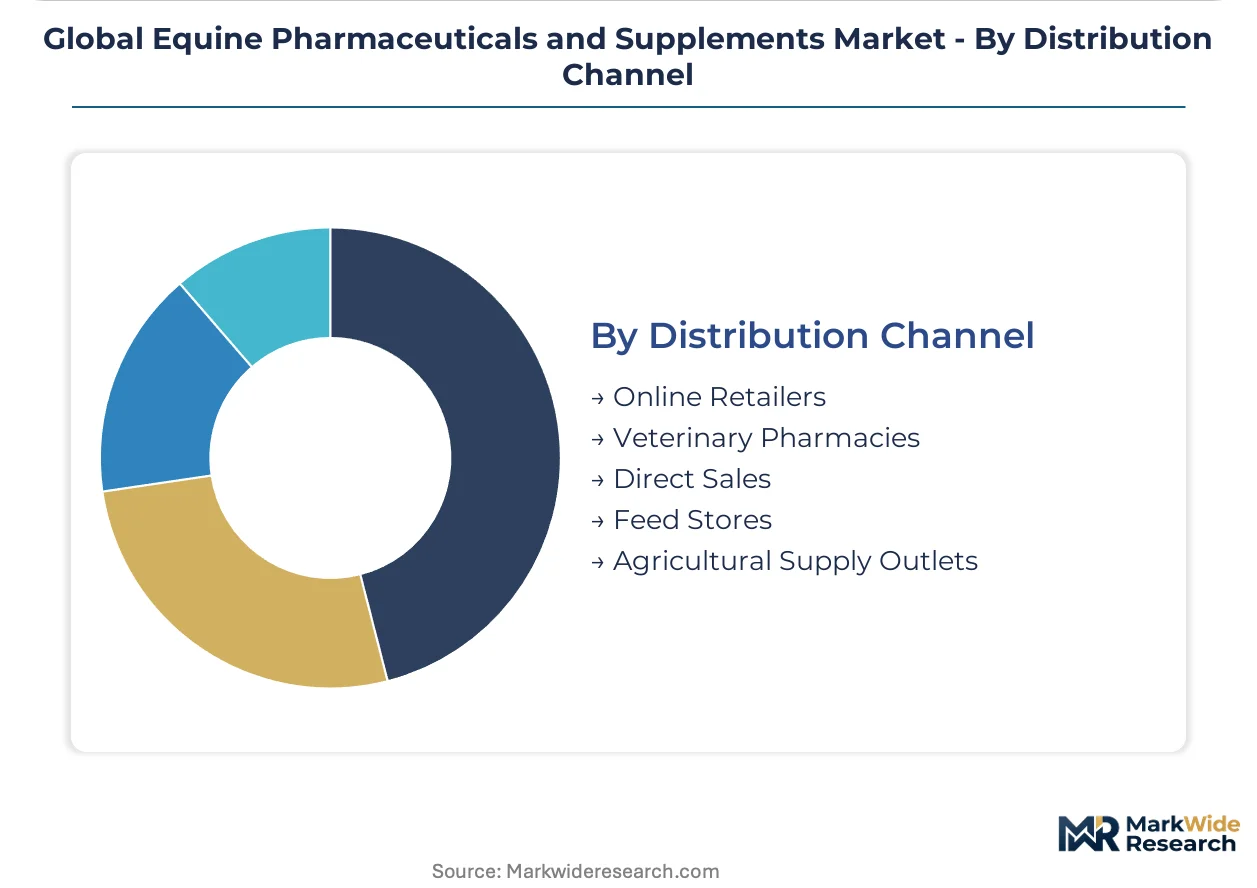
Distribution Channel:
Supply concentration is fragmenting as digital platforms capture margin previously absorbed by retail intermediaries, with cold chain capabilities determining viable channel participation for temperature-sensitive biologics.
- Online Retailers:Pharmacy platforms with direct-to-barn fulfillment and telemedicine integration. Chewy and Valley Vet Supply in the United States leverage veterinary prescription verification systems to capture supplement and pharmaceutical volume from traditional retail.
- Veterinary Pharmacies:Clinic-dispensed products with immediate availability and professional consultation. European veterinary pharmacies in France and Germany maintain compounding capabilities for customized formulations.
- Direct Sales:Manufacturer-to-stable relationships for large racing and breeding operations.
- Feed Stores:Traditional agricultural retail facing erosion from digital competitors.
- Agricultural Supply Outlets:Rural cooperatives serving dispersed recreational horse owners.
Veterinary pharmacies retain the prescription-therapy core while online retailers seize the steepest expansion trajectory in preventive categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by roughly 30 percent for equivalent NSAID formulations, while Brazilian and Australian markets trade at intermediate tiers reflecting veterinary infrastructure density and import tariff structures.
United States
Thoroughbred racing stables in Kentucky and Florida drive concentrated demand for phenylbutazone and firocoxib products with jurisdiction-specific withdrawal protocols. The FDA's Center for Veterinary Medicine enforces tissue residue limits and veterinary feed directive compliance that shape product registration timelines. Lexington's equine hospital cluster and Ocala's breeding operations generate rapid clinical feedback loops shortening distribution cycles for novel therapeutics.
Germany
Sport horse disciplines in Lower Saxony and North Rhine-Westphalia generate premium demand for intra-articular hyaluronic acid and polysulfated glycosaminoglycan formulations. The EMA veterinary committee applies REACH-aligned environmental risk assessments extending authorization timelines for respiratory and anthelmintic categories. Warendorf's equestrian federal center and the surrounding Münsterland region concentrate veterinary sports medicine expertise driving protocol innovation.
United Kingdom
Racing stables in Newmarket and Lambourn prioritize respiratory management for exercise-induced pulmonary hemorrhage given high-intensity training regimens. The Veterinary Medicines Directorate enforces antimicrobial stewardship mandates compressing therapeutic windows for conventional pharmaceuticals. The Newmarket cluster's diagnostic laboratory infrastructure enables rapid resistance surveillance informing deworming protocols across British racing circuits.
Brazil
FEI eventing expansion and Olympic equestrian investment in São Paulo and Rio de Janeiro states are creating demand for performance veterinary services outside traditional markets. ANVISA's pharmaceutical registration pathways for veterinary products require local stability studies extending market entry timelines. The São Paulo state equestrian federation's training centers are adopting preventive care budgets modeled on North American thoroughbred operations.
Australia
Thoroughbred breeding operations in the Hunter Valley and recreational horse populations in Victoria generate distributed demand across veterinary general practices. The APVMA's chemical review program is reassessing several anthelmintic active ingredients under revised ecotoxicity standards. Scone's equine hospital and the surrounding Upper Hunter region concentrate reproductive veterinary services supporting the country's yearling export trade.
Global Equine Pharmaceuticals and Supplements Market Competitive Landscape
Human-health pharmaceutical conglomerates and animal-dedicated biologics specialists split the market into distinct capability tiers with divergent R&D intensity and manufacturing scale. Consolidation pressure concentrates around vaccine supply chains and respiratory therapy portfolios where regulatory compliance costs favor scale. Three archetypes dominate: diversified pharmaceutical conglomerates with veterinary divisions, animal-health pure-plays with biologics manufacturing depth, and regional nutritional formulators with direct-to-barn distribution reach. Competitive moves center on biologics capacity expansion and telemedicine platform partnerships bypassing traditional veterinary pharmacy intermediaries.
Within the diversified pharmaceutical tier, Zoetis Inc and Boehringer Ingelheim GmbH occupy positions reflecting contrasting strategic anchors. Zoetis represents the animal-health pure-play archetype with dedicated biologics manufacturing infrastructure controlling vaccine supply chains across racing circuits. Boehringer Ingelheim exemplifies the human-health conglomerate model leveraging respiratory therapy specialization developed across human and veterinary portfolios. Merck & Co Inc sits within the anthelmintic innovation vector where R&D intensity determines competitive positioning against resistance management protocols.
| Leading Market Players |
|---|
| Zoetis Inc |
| Boehringer Ingelheim GmbH |
| Merck & Co Inc |
| Elanco Animal Health Inc |
| Bayer AG |
| Ceva Sante Animale SA |
| Virbac SA |
| Vetoquinol SA |
| Kentucky Equine Research |
| Others |
Supply & Pricing Matrix
Overcapacity in biologics fermentation suites across Ireland and Belgium is forcing contract manufacturers to absorb margin compression while racing stables exploit buyer power for vaccine procurement. This utilization squeeze cascades into pricing posture, as suppliers trade volume guarantees against price erosion in the preventive care segment while tightening cold chain investments to retain premium positioning in temperature-sensitive categories.
Pricing Analysis
The customization-premium spread between compounded formulations and standard NSAID products runs 40-60 percent above base pricing, with phenylbutazone protocols configured to Kentucky Racing Commission withdrawal rules commanding substantial markups over generic equivalents. Subscription-based supplement programs operate on per-animal monthly fees with volume discounts at 50-plus head thresholds, while one-time joint injection therapies price per procedure with hyaluronic acid purity grades as the primary differentiation driver. Cost compression in the anthelmintic tier is intensifying because resistance management protocols are shortening product lifecycles and forcing faster reformulation. Owner-operators managing fewer than ten horses show highest price sensitivity, whereas Kentucky and Florida racing stables prioritize compliance guarantees over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration for equine biologics rests with Lonza's Portsmouth, New Hampshire facility and Boehringer Ingelheim's Ridgefield, Iowa site, with European capacity anchored by Ceva's Lyon complex. Active pharmaceutical ingredient sourcing draws from India for NSAID precursors, China for fermentation substrates, and Switzerland for high-purity excipients. Single-source vulnerability concentrates in cold chain logistics providers serving rural veterinary networks, where uninterrupted refrigeration from manufacturing through barn administration hinges on specialized last-mile carriers. Distribution runs through three parallel channels: direct-to-barn platforms for supplements, veterinary pharmacy networks for prescription therapeutics, and manufacturer-direct relationships for large racing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as telemedicine platforms disintermediate traditional veterinary pharmacy relationships, creating niches for digital-native entrants to capture preventive care bundling while incumbents defend high-value prescription segments.
For Market Incumbents: Build regulatory data moats through expanded environmental risk assessment capabilities ahead of EMA's tightened ecotoxicity mandates. Consolidate position by acquiring Brazilian distribution networks before ANVISA registration pathways mature, and invest in backward integration into biologics fermentation to secure vaccine supply chain control against Lonza capacity constraints. For New Entrants and Emerging Players: Brazilian equine sports expansion represents the most penetrable white-space target, with São Paulo state training centers adopting North American preventive care budgets but lacking established veterinary infrastructure. Target sport horse disciplines in Germany's Münsterland region through telemedicine-integrated supplement subscriptions, leveraging the gap between owner-operators' spending willingness and local veterinary pharmacy coverage. Partner with FEI-accredited training facilities for protocol validation and rapid clinical feedback loops. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing as cold chain compliance costs and environmental risk assessment burdens reshape facility economics. Long-term viability favors animal-health pure-plays with dedicated equine manufacturing infrastructure over human-health conglomerate divisions facing portfolio rationalization pressure. Watch for inflection signals in Brazilian import tariff structures and ANVISA approval velocity for imported veterinary products.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Uninterrupted refrigeration from Lonza's Portsmouth facility to Ocala breeding operations secures vaccine potency compliance. |
| Telemedicine Platform Integration | Virtual consultation systems bypass Kentucky veterinary pharmacy intermediaries and capture margin from feed-store erosion. |
| Brazilian Distribution Network Buildout | ANVISA registration expertise and local stability study capabilities accelerate market entry ahead of FEI eventing growth. |
| Environmental Risk Assessment Investment | EMA-aligned ecotoxicity data packages preempt respiratory and anthelmintic category restrictions under revised regulations. |
| Subscription-Based Preventive Care Bundles | Automated replenishment protocols displace transactional feed-store purchases among United States owner-operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equine hospital pharmacy directors, racing stable trainers, regulatory affairs specialists at animal health manufacturers, and veterinary telemedicine platform operators; and secondary validation through FDA Center for Veterinary Medicine filings, EMA veterinary committee submissions, state racing commission medication rule databases, and customs records tracking pharmaceutical ingredient trade flows. Bottom-up segmentation modeling triangulated against top-down market sizing from veterinary pharmaceutical distribution data.
Forecast inputs considered therapeutic category growth vectors, regulatory timeline compression effects, and channel shift velocities across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end-user sophistication tier, and distribution channel cold chain capability. CAGRs were derived from regression analysis of historical prescription volumes against stable population growth and preventive care budget expansion rates, with biologics substitution curves and antimicrobial stewardship policy trajectories as industry-specific modifiers.
Practitioners should monitor EMA veterinary committee restriction announcements, Brazilian ANVISA registration pathway modifications, and Lonza biologics capacity utilization reports for early signals of forecast revision. Quarterly review of Kentucky and Florida racing commission medication rule harmonization progress, EU environmental risk assessment submission volumes, and direct-to-barn platform customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market