
 Fertility Supplements Market | 2026-2036
Fertility Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Supplements Market Intelligence
The customer base for fertility supplements is broadening beyond specialized clinics to include direct-to-consumer e-commerce platforms and general wellness centers. This shift creates new channel dynamics for market participants. Fairhaven Health specializes in a comprehensive range of products for both male and female fertility. Vitabiotics Ltd. leverages its established brand presence in retail pharmacy channels, while Orthomol positions its offerings in the premium, practitioner-dispensed segment in Germany.
Fertility supplements are dietary formulations designed to support reproductive health through targeted nutrient delivery. These products often contain specific active ingredients like Coenzyme Q10, myo-inositol, and antioxidants at dosages intended to enhance reproductive outcomes. Capsules and tablets remain the dominant forms due to dosing precision and stability. While the female fertility application continues to hold the largest market share, formulations specifically for male fertility, incorporating minerals and herbal extracts, are experiencing accelerated uptake.
The market operates under strict regulatory scrutiny regarding health claims and product safety. In the United States, the FDA enforces regulations under the Dietary Supplement Health and Education Act, while the European Food Safety Authority evaluates the scientific evidence for nutrient-related health claims. Australia's Therapeutic Goods Administration also imposes stringent requirements. Success depends on substantiating product efficacy with clinical evidence to navigate these complex regulatory frameworks for marketing approval.
Market Dynamics
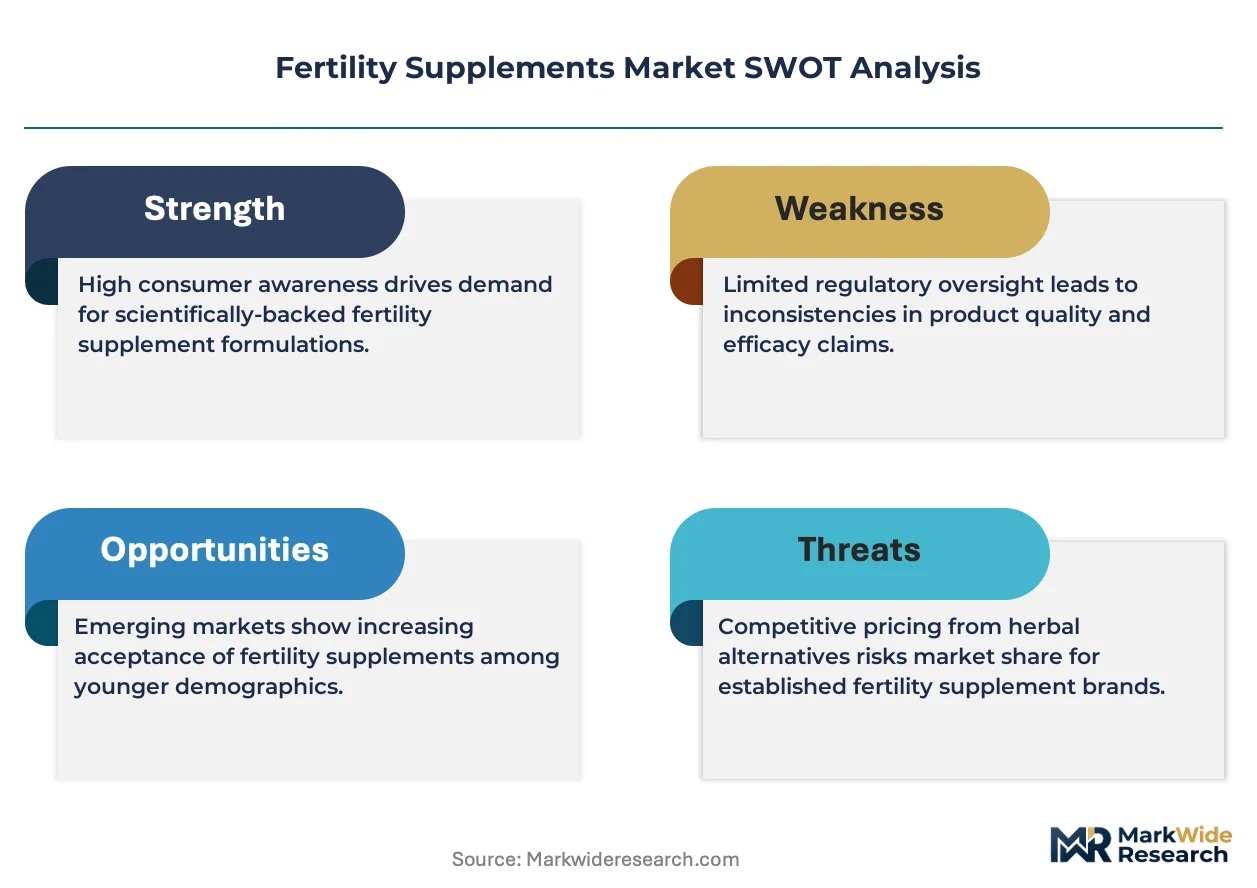
The central dynamic in the fertility supplements market is the tension between growing consumer demand for non-pharmaceutical reproductive support and the rigorous scientific substantiation required by regulators, which dictates product formulation, marketing claims, and market access.
Growth Catalysts
- Clinical Integration:Fertility clinics are increasingly incorporating specific supplement protocols into patient treatment plans, lending credibility and driving adoption of formulations with ingredients like myo-inositol and Coenzyme Q10 for both male and female patients.
- Favorable Demographics:In developed nations such as the United States and Germany, delayed parenthood and higher disposable incomes create a sustained consumer base actively seeking products to support reproductive health and wellness.
- Ingredient Research:An expanding body of scientific literature substantiating the efficacy of specific vitamins, minerals, and antioxidants in improving reproductive parameters provides a solid foundation for product development and consumer trust.
Market Restraints
- Regulatory Scrutiny:Health claim restrictions imposed by the European Food Safety Authority (EFSA) and the FDA limit marketing language, requiring significant investment in clinical data to legally associate a product with a specific health benefit.
- High Ingredient Costs:The procurement of high-purity, clinically-studied active ingredients like Coenzyme Q10 adds significant expense to the final product, potentially placing it out of reach for a segment of consumers.
- Threat of Substitution:Consumers may opt for less expensive, general-purpose multivitamins or make dietary changes rather than purchasing premium-priced, specialized fertility formulations, limiting market penetration.
Strategic Opportunities
- Emerging Market Entry:There is significant white space in large, developing economies where rising incomes and increasing health awareness create a nascent but fast-growing market for specialized dietary supplements.
- Personalized Formulations:Leveraging data from at-home diagnostic tests offers an opportunity to develop and market customized supplement regimens tailored to an individual's specific nutritional deficiencies or health profile.
- Channel Expansion:Broadening distribution beyond practitioner-led channels into direct-to-consumer e-commerce and mainstream wellness centers allows brands to build direct customer relationships and capture a wider audience.
Industry Challenges
- Consumer Education Gap:A primary operational challenge is educating consumers on the appropriate use and realistic outcomes of supplements while adhering to strict regulatory constraints on health claims.
- Supply Chain Integrity:Maintaining a consistent and verifiable supply chain for globally sourced botanical extracts and specialty nutrients is a constant challenge, requiring rigorous quality control to ensure potency and safety.
- Clinical Validation Timelines:The lengthy and costly process of conducting randomized controlled trials to meet evidence standards set by bodies like Australia's TGA creates a significant barrier to market entry and claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Supplements Market |
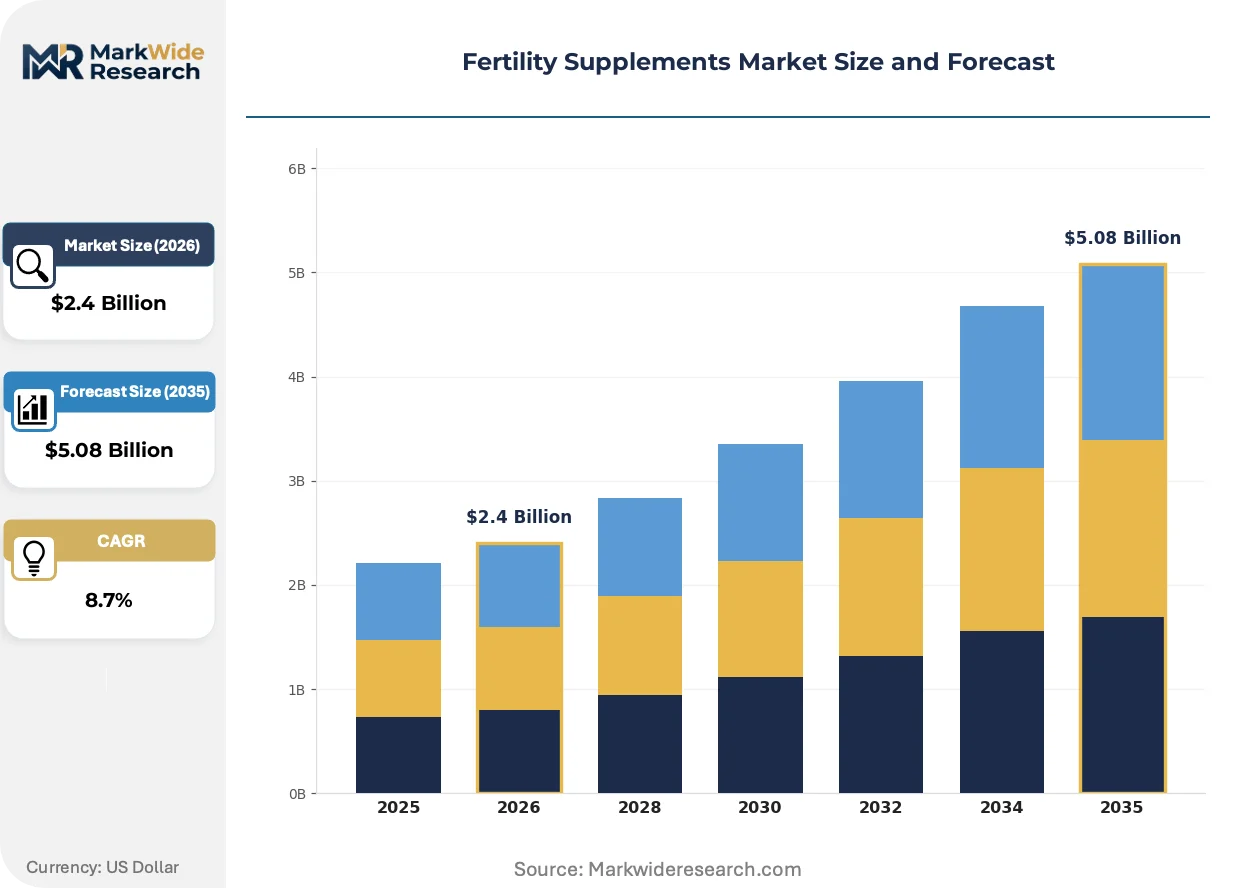
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Antioxidants, Amino Acids Form: Capsules, Tablets, Powders, Liquids, Softgels Application: Female Fertility, Male Fertility, IVF Support, Hormonal Balance, Prenatal Care End User: Fertility Clinics, Gynecologists, Nutritionists, Wellness Centers, Pharmacies |
| Companies Covered | Fairhaven Health, Coast Science, LENUS Pharma GesmbH, Exeltis USA, Inc., Vitabiotics Ltd., Active Bio Life Science GmbH, Orthomol, Bionova, Fertility Nutraceuticals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Supplements Market Strategic Shifts & Innovations
Product development is pivoting toward evidence-based formulations and personalized nutrition. This shift is driven by a more discerning consumer base and regulatory bodies demanding higher standards of proof for health-related claims, pushing the market toward greater scientific rigor.
Advanced formulation technology now enables the creation of personalized supplement blends based on individual diagnostic data. This approach is gaining traction among consumers seeking tailored wellness solutions. This data-driven formulation strategy is converging with digital health applications, creating integrated platforms that monitor health metrics and dynamically adjust nutritional support for users.
The European Food Safety Authority (EFSA) continues to enforce stringent evaluation of nutrient-related health claims under Regulation (EC) No 1924/2006. Its rigorous scientific assessment process directly influences which ingredients and dosages can be marketed with specific fertility-related benefits. Formulations containing ingredients without an approved EFSA health claim are most affected, forcing manufacturers in the EU to focus marketing on general well-being or invest heavily in new clinical data.
A significant change in consumer behavior is the adoption of subscription-based purchasing, particularly for male and female fertility regimens. This model disrupts the traditional, one-time purchase cycle common in brick-and-mortar pharmacies and is being popularized by direct-to-consumer brands online. The trend is especially visible in the United States, where the model offers convenience, cost savings, and ensures uninterrupted adherence to a supplement protocol.
Fertility Supplements Market Segmentation
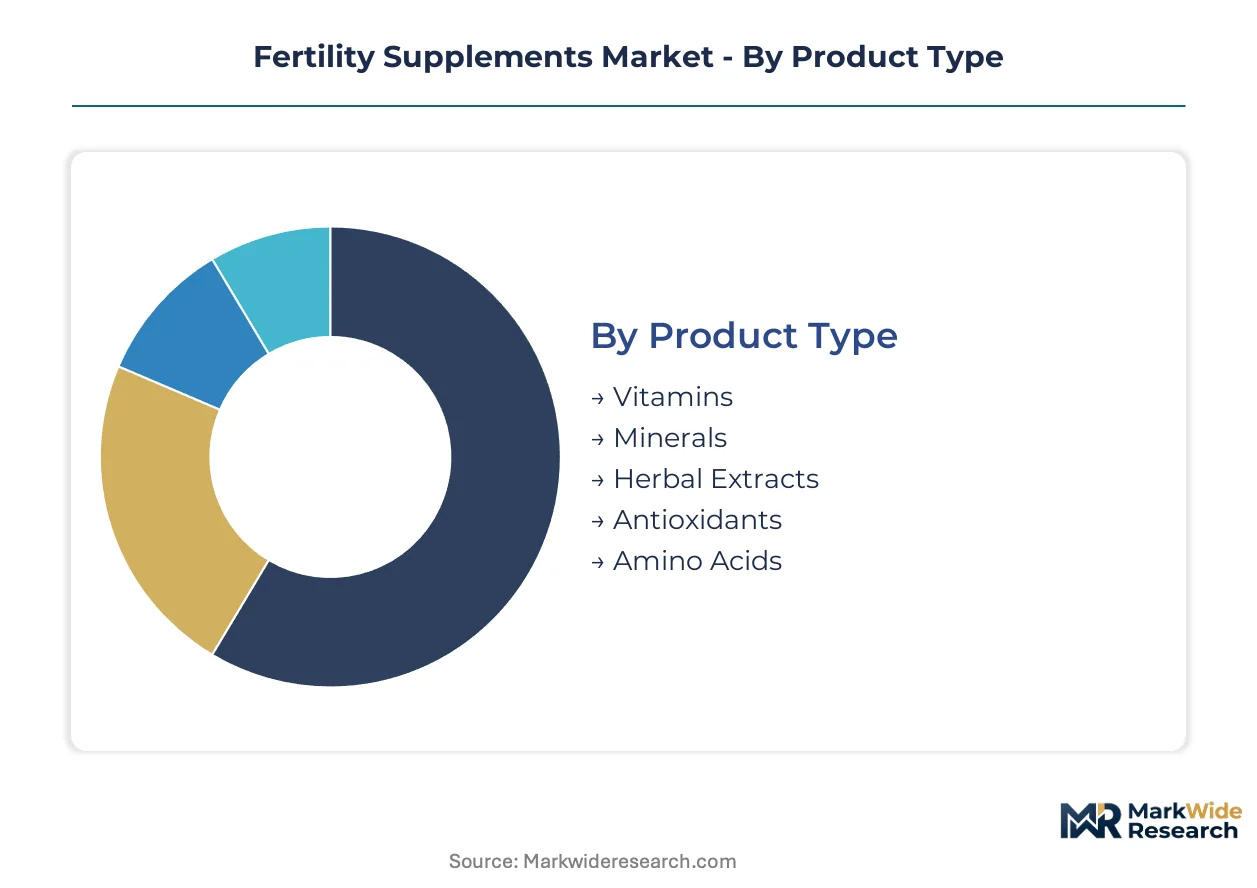
Understanding the market segmentation for fertility supplements is crucial for participants to tailor product development and marketing strategies effectively. This detailed breakdown reveals specific consumer needs, preferred product forms, and the most impactful distribution channels, guiding resource allocation and competitive positioning.
Product Type:
The product type segmentation highlights the spectrum from highly standardized nutrient compounds to more customized botanical blends. Manufacturers balance broad appeal with targeted efficacy based on ingredient profiles.
- Vitamins:Essential micronutrients like Folic Acid and Vitamin D are fundamental for reproductive health, supporting cellular division and hormonal regulation. Demand concentrates in prenatal care applications across North America, driven by widespread public health recommendations.
- Antioxidants:Compounds such as Coenzyme Q10 and N-acetyl cysteine protect reproductive cells from oxidative stress, enhancing gamete quality. This segment sees high demand from fertility clinics in Germany, where practitioners integrate specific antioxidant protocols into patient treatment plans.
- Minerals:Zinc and Selenium are critical trace elements supporting hormone production and sperm development.
- Herbal Extracts:Botanicals like Maca root and Chasteberry are used for traditional reproductive support and hormonal balance.
- Amino Acids:L-arginine and L-carnitine contribute to sperm motility and uterine blood flow.
Most installed capacity flows through Vitamins. Expansion is steepest in Antioxidants.
Form:
The form of fertility supplements directly impacts user convenience, dosage precision, and ingredient stability, influencing consumer preference and adherence to treatment protocols.
- Capsules:Encapsulated formulations offer precise dosing, protect sensitive ingredients, and provide ease of consumption. This form dominates sales in the United States due to consumer familiarity and convenience.
- Tablets:Compressed solid doses allow for high ingredient concentration and extended shelf life, often featuring controlled-release mechanisms. Tablets are widely preferred in European retail pharmacies for their stability and cost-effectiveness.
- Powders:Soluble powders offer flexible dosing and faster absorption, often mixed into beverages for consumption.
- Liquids:Liquid supplements provide an alternative for individuals with swallowing difficulties and can offer enhanced bioavailability.
- Softgels:Gelatin-based softgels are ideal for oil-soluble nutrients, improving absorption and reducing gastric irritation.
Market volume is predominantly driven by Capsules, while Powders show significant upward momentum.
Application:
Application segmentation illustrates the specific reproductive health concerns addressed by these supplements, from general wellness to targeted clinical support, reflecting diverse patient needs.
- Female Fertility:Formulations targeting ovulation, egg quality, and hormonal balance dominate this segment, often containing myo-inositol and folic acid. This application holds the largest market share globally, reflecting a broader consumer base seeking reproductive support.
- Male Fertility:Products designed to improve sperm count, motility, and morphology, frequently incorporating zinc and L-carnitine, are experiencing accelerated uptake. Demand for male fertility supplements is notably increasing in developed countries like the United States.
- IVF Support:Specialized supplements complement in-vitro fertilization protocols, aiming to optimize outcomes for patients undergoing assisted reproductive technologies.
- Hormonal Balance:These supplements help regulate endocrine functions crucial for reproductive health in both sexes.
- Prenatal Care:Products supporting maternal health before and during pregnancy, focusing on essential nutrients for fetal development.
The largest portion of market revenue is generated by Female Fertility applications. Male Fertility applications are expanding most quickly.
End User:
The end-user segment outlines the primary channels through which fertility supplements reach consumers, from clinical recommendations to direct retail purchases, shaping distribution strategies.
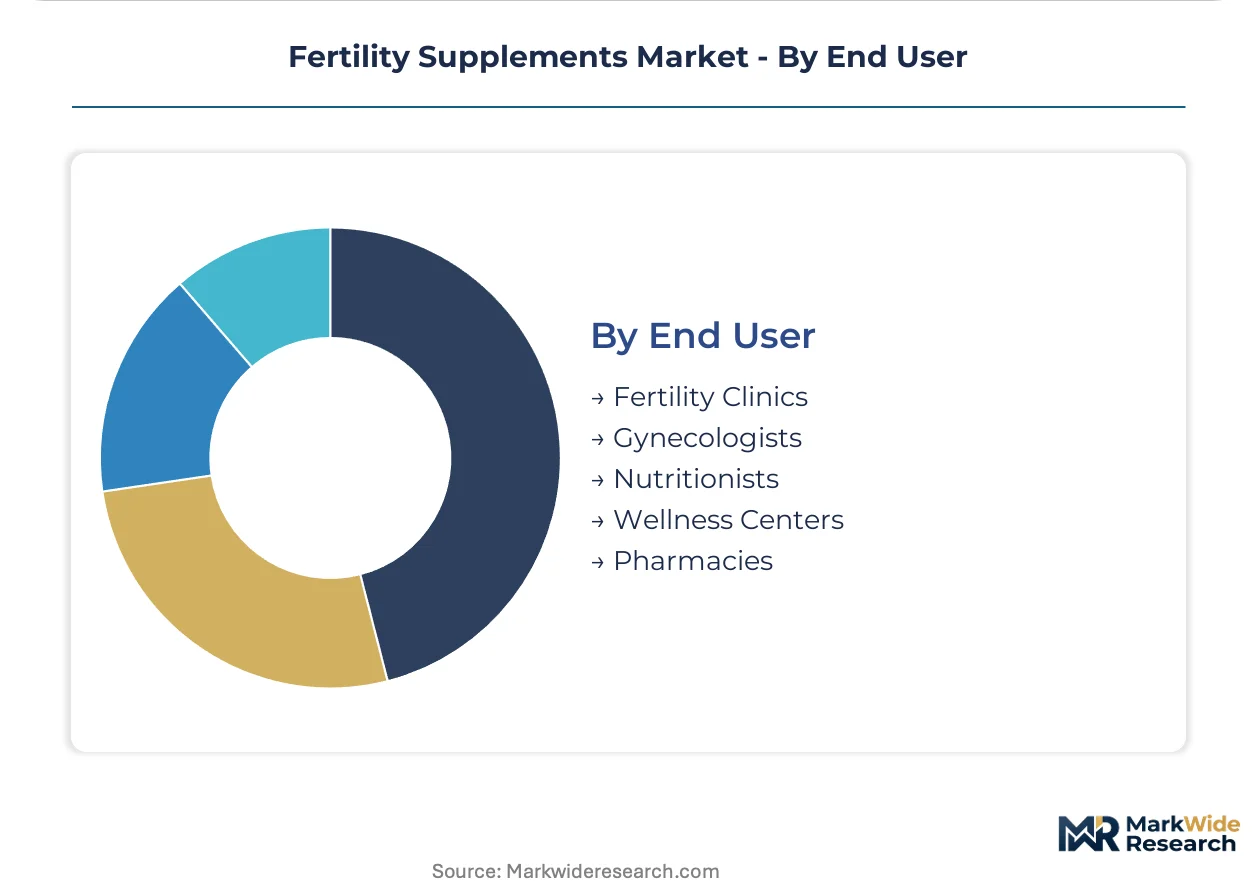
- Fertility Clinics:These specialized medical centers increasingly recommend specific supplement protocols as part of comprehensive patient treatment plans. Clinical integration drives adoption of evidence-backed formulations among patients seeking professional guidance.
- Pharmacies:Retail pharmacies serve as a traditional and accessible point of purchase for over-the-counter fertility supplements, leveraging established consumer trust and convenience. This channel is critical for brand visibility and widespread distribution in regions like Europe.
- Gynecologists:OB/GYN practitioners advise patients on reproductive health, including dietary interventions and supplement use.
- Nutritionists:Health and wellness coaches provide personalized dietary and supplement recommendations to support fertility goals.
- Wellness Centers:Holistic health centers offer fertility-focused programs that may include supplement recommendations.
The primary distribution channel remains Fertility Clinics. Wellness Centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fertility supplements shows a clear divergence between highly aware consumers in the United States and the stringent regulatory environment in Germany. This market's trajectory is deeply influenced by regional economic conditions and local health policies. Consumers in developed nations exhibit higher engagement with specialized health products.
United States
Delayed parenthood and higher disposable incomes drive significant consumer demand for fertility supplements across the United States. The FDA regulates these products under the Dietary Supplement Health and Education Act, ensuring product safety and appropriate labeling. California's health and wellness sector fosters innovation, particularly in personalized formulations and direct-to-consumer sales channels.
Germany
Clinical integration of specific supplement protocols into patient treatment plans fuels adoption in Germany. The European Food Safety Authority (EFSA) rigorously evaluates health claims, impacting product formulation and marketing strategies for German manufacturers. Companies in Bavaria specialize in premium, practitioner-dispensed supplements, often requiring extensive clinical data for market positioning.
Australia
Stringent regulatory requirements and a focus on clinical evidence shape the Australian fertility supplements market. The Therapeutic Goods Administration (TGA) mandates rigorous validation for product claims, influencing local product development cycles. Sydney's burgeoning health-tech sector facilitates the development of new, clinically validated formulations and supports market access strategies.
United Kingdom
Established retail pharmacy channels and increasing consumer awareness contribute to steady demand for fertility supplements in the United Kingdom. The MHRA ensures product safety and regulates advertising claims, aligning with broader European standards for dietary supplements. London's vibrant e-commerce landscape enables direct-to-consumer brands to expand their reach and offer subscription-based models.
Fertility Supplements Market Key Industry Players
United States producers anchor one tier, often prioritizing direct-to-consumer e-commerce models and broad accessibility, while European specialists hold strong positions in practitioner-dispensed and clinical-grade segments. The market structure exhibits fragmentation, characterized by a blend of established pharmaceutical companies and agile, specialized nutraceutical firms. Archetypes include broad-spectrum wellness brands, condition-specific formulators, and premium clinical-grade suppliers focusing on scientific substantiation. Companies primarily engage in portfolio diversification to address various fertility needs and pursue geographic expansion into high-growth regions to secure market share.
Specialists in comprehensive reproductive health solutions include Fairhaven Health, offering a wide array of products for both male and female fertility support. Vitabiotics Ltd. occupies a strong position within retail pharmacy channels, leveraging its established brand presence for broad consumer access. Orthomol, a German-based entity, exemplifies the premium, practitioner-dispensed segment, targeting consumers seeking clinical-grade formulations through expert recommendations. These entities represent distinct approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| Fairhaven Health |
| Coast Science |
| LENUS Pharma GesmbH |
| Exeltis USA, Inc. |
| Vitabiotics Ltd. |
| Active Bio Life Science GmbH |
| Orthomol |
| Bionova |
| Fertility Nutraceuticals LLC |
| Others |
Cost & Logistics Intelligence
High-purity active ingredient costs, particularly for compounds like Coenzyme Q10, flow directly into the premium pricing observed across specialized fertility formulations. This cost structure significantly influences downstream product accessibility and market segmentation.
Pricing Analysis
Capacity additions in India and China for key active ingredients are reshaping price floors across the fertility supplements market. The dominant pricing structure is per-unit transactional, with a clear premium-mid-economy pricing differentiation. Price differentiation stems from clinical validation evidence and ingredient purity. Pricing softness reflects intense competition in the direct-to-consumer segment, particularly for general wellness formulations. Consumers seeking practitioner-dispensed products exhibit lower price sensitivity, while e-commerce buyers are highly price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with specialized chemical manufacturers in China and India for critical active ingredients like Coenzyme Q10 and myo-inositol. The supply chain for botanical extracts also concentrates in regions like South America and parts of Asia. This market heavily relies on high-purity vitamins, minerals, and herbal extracts. Commodity price volatility for these specialized nutrients presents a significant structural risk. Distribution runs through a hybrid model, combining direct-to-consumer e-commerce with established pharmacy and clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fertility supplements market acts as a regulatory compounder, where the European Food Safety Authority's (EFSA) rigorous health claim evaluations drive product innovation and consumer trust. This scrutiny, while challenging, ultimately strengthens market credibility and patient adoption.
For Market Incumbents: To counter the threat of generic substitution, established players should deepen vertical integration into active ingredient sourcing. This ensures supply chain integrity and cost control for premium formulations. Investing in randomized controlled trials to substantiate efficacy with bodies like Australia's TGA strengthens brand premium. Expanding product portfolios to include personalized formulations also protects market share.
For New Entrants and Emerging Players: Consumers in emerging economies seeking affordable, evidence-backed reproductive support represent a significant white space. Targeting male fertility applications in these regions, often with localized herbal extracts, offers high penetrability. A direct-to-consumer e-commerce model with subscription options provides an effective go-to-market angle. Leveraging at-home diagnostic data for personalized regimens creates a distinct value proposition.
For Investors and Strategic Acquirers: Roll-up economics work for specialized nutraceutical firms because market fragmentation across product types and geographies creates consolidation opportunities. The long-term viability of this market is strong, driven by delayed parenthood trends. Acquisition targets should be agile, science-backed brands with strong clinical validation. Increased clinical integration of supplements by fertility clinics is the signal to watch for accelerated growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Investment | Substantiating product efficacy with randomized controlled trials secures marketing approval from bodies like the FDA. |
| Personalized Formulation Development | Leveraging individual diagnostic data allows brands to offer tailored supplement regimens, enhancing consumer adherence. |
| Direct-to-Consumer Channel Expansion | Building direct customer relationships through e-commerce platforms captures a wider audience beyond traditional clinics. |
| Geographic Expansion into Emerging Markets | Entering large, developing economies with rising incomes creates new growth avenues for specialized dietary supplements. |
| Supply Chain Diversification | Reducing reliance on single-source suppliers for active ingredients mitigates commodity price volatility and ensures production stability. |
Research Approach
Bottom-up patient application modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with fertility clinic directors, nutraceutical R&D leads, and e-commerce platform managers provided qualitative insights. This was validated against secondary data from EFSA health claim evaluations, FDA filings, and industry association reports. This approach ensured comprehensive market understanding.
Historical trendline analysis, projecting growth trajectories over the forecast period, informed the quantitative framework. Segmentation dimensions modeled include product type, form, application, and end-user, alongside regional regulatory adherence. Compound annual growth rates were derived from a multi-variant regression model incorporating demographic shifts. Delayed parenthood statistics served as a key industry-specific forecast input.
Underlying measurement precision varies by segment; clinically integrated applications carry tighter precision than general wellness formulations. Forecasts reflect assumptions regarding regulatory stability and consumer health awareness. Unexpected shifts in public health recommendations or ingredient supply could revise outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Sleep Aid Supplements Market