
 Glucosamine Salt Market | 2026-2036
Glucosamine Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Glucosamine Salt Market Analytics
China is tilting glucosamine salt capacity toward fermentation-based production at industrial scale. Koyo Chemical Co., Ltd. leverages proprietary extraction methods to sustain premium positioning in Asian nutraceutical channels. Cargill, Incorporated anchors North American supply through its integrated agricultural processing infrastructure. Zhejiang Aoxing Biotechnology Co., Ltd. specializes in bulk glucosamine sulfate for global pharmaceutical and supplement formulators.
Glucosamine salt denotes crystalline or amorphous salts of glucosamine, typically manufactured as sulfate or hydrochloride forms with purity grades exceeding 98 percent for pharmaceutical and nutraceutical applications. The compound functions primarily as a chondroprotective agent in oral joint health formulations and as a building block in glycosaminoglycan synthesis. Glucosamine sulfate occupies the dominant revenue position due to established clinical validation and broader reimbursement acceptance in European health systems. Powder formulations lead volume consumption among contract manufacturers, while capsule and tablet forms capture higher unit margins through branded retail positioning. Sports nutrition represents the fastest-growing application segment as athletic populations age and seek preventive joint maintenance protocols.
The FDA's cGMP regulations for dietary supplements and the EFSA's health claims framework collectively determine market access and labeling permissions for glucosamine salt products across transatlantic markets. China's NMPA oversees pharmaceutical-grade glucosamine registration, while SAMR monitors food supplement compliance under revised national food safety standards. Stakeholders must monitor evolving pharmacopeial monograph revisions and sustainability certifications for crustacean-derived raw materials.
Market Dynamics
China's industrial-scale fermentation pivot is compressing crustacean-derived supply chains and redrawing cost curves for pharmaceutical-grade glucosamine sulfate production.
Growth Catalysts
- Sports Nutrition Expansion:Aging athletic populations in Germany and Australia are integrating preventive joint maintenance into training regimens, pulling sulfate formulations into performance nutrition portfolios.
- EFSA Health Claims Framework:Validated structure-function claims for osteoarthritis symptom relief enable premium positioning and pharmacy channel access across EU member states.
- Fermentation Technology Maturation:Microbial cell culture methods eliminate seasonal shellfish supply volatility and reduce allergen cross-contamination risks for vegan-labeled products.
Market Restraints
- Chitin Input Cost Volatility:Crab and shrimp shell prices fluctuate with aquaculture harvest cycles and climate-induced catch variability in Southeast Asian waters.
- Zhejiang Production Concentration:Over half of global glucosamine HCl capacity sits within 200 kilometers of Hangzhou Bay, creating single-point-of-failure exposure.
- Clinical Efficacy Skepticism:Mixed results in NIH-funded osteoarthritis trials dampen physician recommendation rates in US managed care networks.
Strategic Opportunities
- Indian Dietary Supplement Liberalization:FSSAI's streamlined health supplement notification pathway opens direct-to-consumer e-commerce channels for sulfate and HCl combinations.
- Cosmeceutical Topical Delivery:Transdermal glucosamine formulations for skin barrier repair are penetrating K-beauty and prestige dermatology lines in Seoul and Tokyo.
- EU Green Deal Biomanufacturing Incentives:Horizon Europe funding streams support carbon-negative fermentation scale-up for pharmaceutical-grade salt production.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and ChP monograph specifications for sulfate content and residual protein create batch-release bottlenecks for multi-territory suppliers.
- Specialized Fermentation Talent Scarcity:Industrial microbiologists with scale-up experience in fungal chitosan-to-glucosamine conversion command premium compensation in Shanghai and Rotterdam hiring markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucosamine Salt Market |
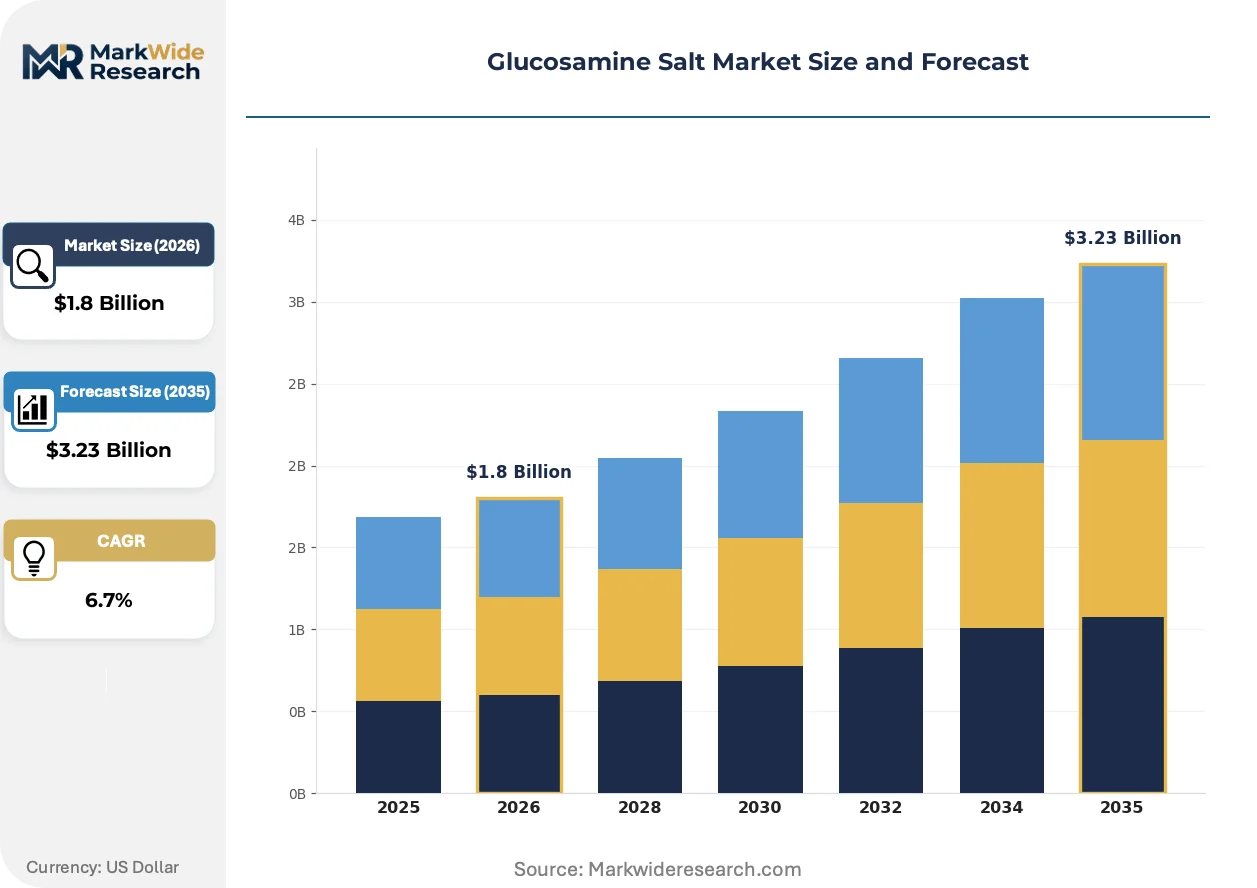
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucosamine Sulfate, Glucosamine Hydrochloride, N-Acetyl Glucosamine, Others Form: Powder, Capsule, Liquid, Tablet Application: Joint Health, Osteoarthritis Treatment, Dietary Supplement, Sports Nutrition Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | Cargill, Incorporated, Koyo Chemical Co., Ltd., Zhejiang Aoxing Biotechnology Co., Ltd., TSI Group Ltd., CELLMARK AB, Bio-gen Extracts Pvt. Ltd., Panvo Organics Pvt Ltd., Mylan N.V., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucosamine Salt Market Evolving Landscape
Fermentation-derived production methods, evolving pharmacopeial standards, and shifting procurement behaviors are restructuring competitive advantage across the glucosamine salt value chain.
Continuous fermentation systems with real-time metabolite monitoring are rendering obsolete batch-mode shellfish hydrolysis operations that dominated output for three decades. European contract manufacturers are retrofitting facilities in the Netherlands and Denmark to capture carbon credit benefits and secure vegan certification premiums. The technology is compressing capital recovery timelines from seven years to under four for greenfield bioreactor installations.
REACH registration requirements for chitosan-derived intermediates are tightening traceability documentation across EU supply chains. Importers must now demonstrate crustacean species origin and fishing zone compliance for hydrolysis-based inputs. German and French formulators are accelerating supplier audits and dual-sourcing fermentation-based alternatives to preempt authorization delays.
Direct procurement from Chinese fermentation specialists is displacing layered distributor networks for North American and European supplement brands. Volume buyers are establishing quality agreements with Zhejiang and Shandong producers, bypassing traditional Hong Kong and Rotterdam trading houses. This channel compression is most advanced among US sports nutrition brands with in-house regulatory affairs capabilities and annual sulfate purchases exceeding fifty metric tons.
Glucosamine Salt Market Segmentation
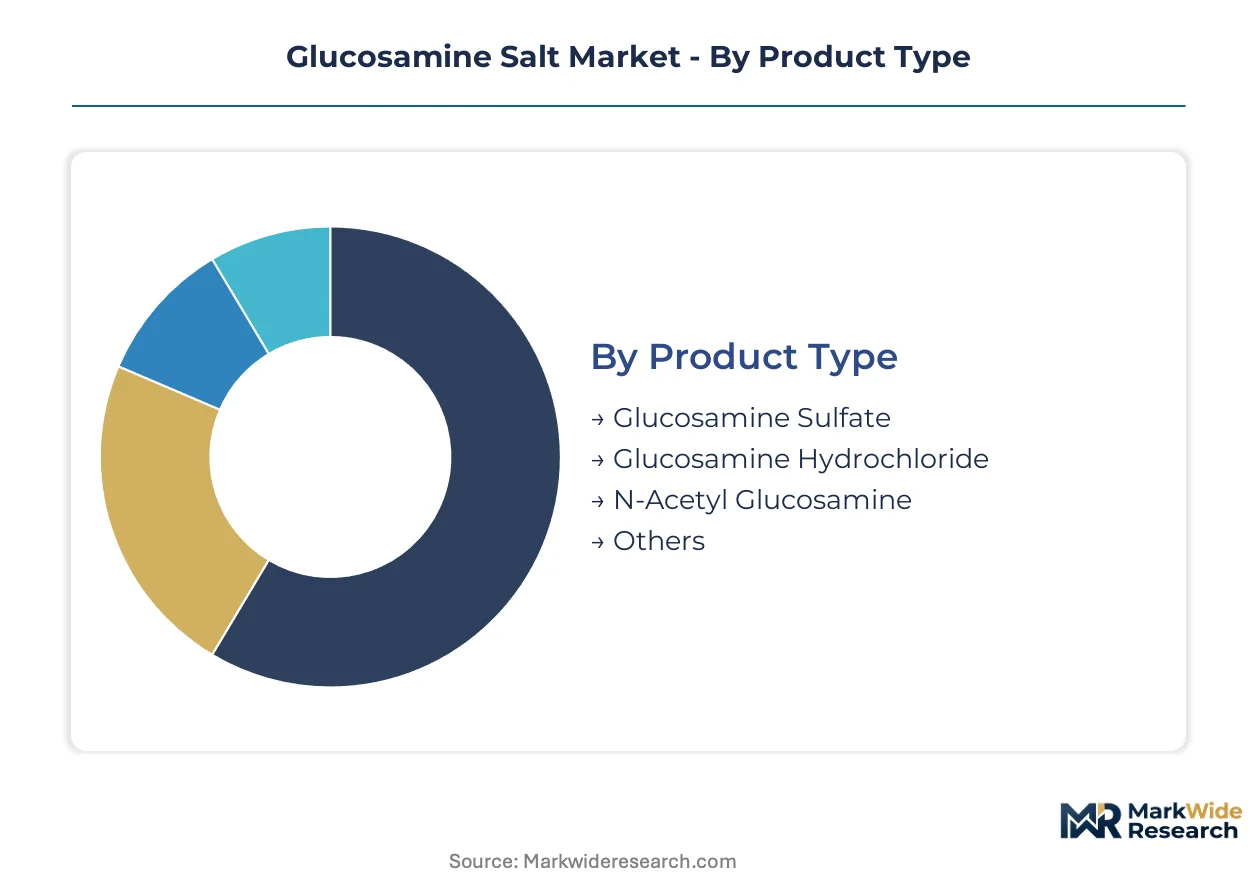
Glucosamine salt segmentation reveals how crystalline purity grades, dosage forms, and channel economics fragment procurement behaviors across pharmaceutical, nutraceutical, and sports nutrition buyers. Manufacturers configure production lines around sulfate versus hydrochloride crystallization economics, while fermentation-derived alternatives are compressing legacy crustacean supply tiers.
Product Type:
Cost tier differentiation separates fermentation-based alternatives from shellfish-derived standards, with purity premiums clustering around pharmaceutical-grade specifications.
- Glucosamine Sulfate:Crystalline salt with 98%+ purity and established pharmacopeial monographs across USP, EP, and ChP standards. Demand concentrates in Germany and France where pharmacy reimbursement protocols favor sulfate for osteoarthritis symptom management. EFSA-validated structure-function claims sustain premium positioning against hydrochloride alternatives.
- Glucosamine Hydrochloride:Chloride salt form with higher glucosamine base content by molecular weight, preferred by US contract manufacturers for tablet compression efficiency. Zhejiang fermentation specialists are rotating capacity toward HCl as vegan certification premiums expand in North American sports nutrition channels.
- N-Acetyl Glucosamine:Acetylated derivative targeting cosmeceutical and skin barrier repair applications in Seoul and Tokyo dermatology lines.
- Others:Specialty salts including glucosamine phosphate and custom complex forms for veterinary joint formulations.
Glucosamine sulfate holds installed capacity. N-acetyl derivatives are rotating up the share rankings.
Form:
Volume concentration in powder reflects contract manufacturing economics, while margin capture concentrates in finished dosage formats.
- Powder:Bulk crystalline or spray-dried material for encapsulation and tableting operations. Demand concentrates among US and European contract manufacturers purchasing fifty-metric-ton annual volumes direct from Zhejiang and Shandong fermentation specialists. Powder commands lowest unit margins but anchors volume throughput for multi-product supplement facilities.
- Capsule:Hard gelatin or HPMC shells delivering 500-750mg unit doses for direct-to-consumer brands. Sports nutrition buyers in Australia and Germany are pulling sulfate capsules into performance portfolios as aging athletic populations adopt preventive joint protocols.
- Liquid:Aqueous suspensions and syrups targeting pediatric and geriatric compliance segments in Japan and South Korea.
- Tablet:Compressed bilayer and enteric-coated formats for pharmacy channel distribution with extended-release claims.
Powder dominates volume throughput. Capsule formats are climbing the fastest in margin contribution.
Application:
Customer type stratification separates reimbursed pharmaceutical use from discretionary supplement and sports nutrition purchasing.
- Joint Health:Preventive maintenance formulations targeting adults over fifty in Japan and Germany. Chondroprotective positioning relies on glycosaminoglycan synthesis support claims rather than disease treatment language to navigate FDA and EFSA regulatory boundaries.
- Osteoarthritis Treatment:Symptom management protocols with physician recommendation in EU pharmacy channels. EMA and national health technology assessment bodies in France and Italy condition reimbursement on sulfate form and minimum purity thresholds.
- Dietary Supplement:General wellness positioning in US direct-to-consumer and health store channels. FDA cGMP compliance and New Dietary Ingredient notification requirements shape formulation and labeling pathways for sulfate and HCl combinations.
- Sports Nutrition:Preventive joint maintenance integrated into training regimens by aging athletes in Australia and Germany. This segment is expanding most quickly as performance nutrition brands add glucosamine to protein and recovery portfolios.
Osteoarthritis treatment holds reimbursed volume. Sports nutrition is gaining share fastest.
Distribution Channel:
Supply concentration in Chinese fermentation capacity is compressing traditional distributor layers and reshaping how brands access raw material.
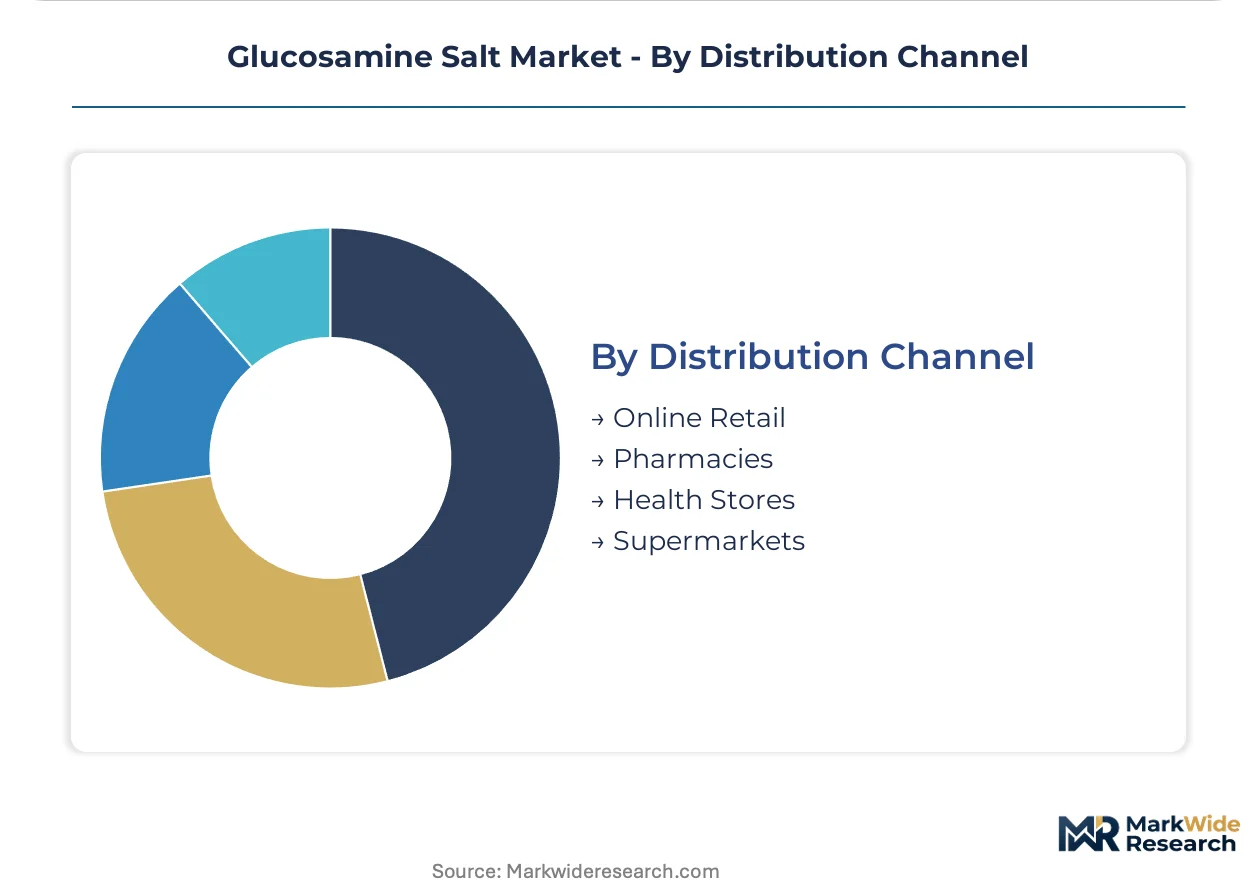
- Online Retail:Direct-to-consumer platforms and brand-owned e-commerce bypassing traditional wholesale tiers. Amazon and specialized supplement marketplaces in the US and EU are absorbing volume as sports nutrition brands build in-house regulatory affairs capabilities.
- Pharmacies:Brick-and-mortar and mail-order pharmacy channels with pharmacist recommendation in Germany, France, and Japan. Reimbursement eligibility for sulfate products sustains pharmacy preference over supplement retail.
- Health Stores:Specialized retailers including GNC and European pharmacy-adjacent supplement chains with trained staff consultation.
- Supermarkets:Mass-market retail placement in US and Australian grocery channels with price-competitive private label offerings.
Pharmacies hold reimbursed positioning. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR and NMPA jointly supervise China's glucosamine salt sector through food supplement and pharmaceutical-grade registration pathways. The country's fermentation capacity expansion is compressing global supply curves and redirecting trade flows toward direct procurement relationships.
China
Hangzhou Bay industrial clusters host over half of global glucosamine HCl fermentation capacity, with Zhejiang and Shandong provinces supplying bulk sulfate to North American and European formulators. NMPA pharmaceutical-grade registration requirements and SAMR's revised national food safety standards shape domestic compliance pathways. Zhejiang Aoxing Biotechnology Co., Ltd. anchors bulk production for global pharmaceutical and supplement customers from this coastal manufacturing belt.
Germany
Pharmacy reimbursement protocols for osteoarthritis symptom management sustain sulfate formulation demand among aging populations in Bavaria and North Rhine-Westphalia. EFSA-validated structure-function claims enable premium positioning and pharmacist recommendation across EU member states. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on health technology assessments that condition sulfate reimbursement eligibility.
United States
FDA cGMP regulations and New Dietary Ingredient notification requirements structure compliance pathways for dietary supplement manufacturers purchasing sulfate and HCl combinations. Sports nutrition brands with in-house regulatory capabilities are establishing direct procurement relationships with Chinese fermentation specialists, bypassing traditional distributor tiers. Midwest contract manufacturers and West Coast performance nutrition clusters absorb rising volumes for preventive joint maintenance formulations.
Japan
PMDA oversight of pharmaceutical-grade glucosamine and METI coordination on functional food claims shape market access for sulfate and N-acetyl derivatives. Aging demographics in Tokyo and Osaka metropolitan areas drive sustained demand for chondroprotective supplements. Koyo Chemical Co., Ltd. leverages proprietary extraction methods to sustain premium positioning in domestic nutraceutical channels and adjacent Asian markets.
Australia
TGA regulation of complementary medicines and therapeutic goods labeling governs glucosamine salt importation and retail distribution. Aging athletic populations in Sydney and Melbourne are integrating preventive joint maintenance into training regimens, pulling sulfate formulations into sports nutrition portfolios. Direct-to-consumer e-commerce channels are compressing traditional pharmacy and health store distribution layers for volume supplement brands.
Glucosamine Salt Market Competitive Landscape
Fermentation-based specialists and crustacean-derived traditionalists split the market along vegan-certification and cost-curve vectors. Capacity concentration in Chinese coastal provinces has compressed margin structures for shellfish-hydrolysis operations that dominated output for three decades. Three archetypes define competitive positioning: industrial-scale fermentation operators, premium extraction method specialists, and integrated agricultural processors. Dominant competitive moves include backward integration into raw material supply and geographic expansion through quality agreements with volume buyers.
Within the fermentation-specialist tier, Zhejiang Aoxing Biotechnology Co., Ltd. and Koyo Chemical Co., Ltd. exemplify divergent strategic approaches to purity-grade positioning. Cargill, Incorporated represents the integrated agricultural processor archetype, leveraging captive supply infrastructure to anchor North American distribution. These three entities collectively illustrate how production technology choices crystallize into distinct market access strategies across pharmaceutical, nutraceutical, and sports nutrition channels.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Koyo Chemical Co., Ltd. |
| Zhejiang Aoxing Biotechnology Co., Ltd. |
| TSI Group Ltd. |
| CELLMARK AB |
| Bio-gen Extracts Pvt. Ltd. |
| Panvo Organics Pvt Ltd. |
| Mylan N.V. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Zhejiang production concentration risk determines both three-tier pricing structure across pharmaceutical, nutraceutical, and feed-grade levels and supply chain redundancy investments by North American buyers. Fermentation capacity clustering within Hangzhou Bay industrial zones compresses cost curves for sulfate and hydrochloride salts while amplifying single-point-of-failure exposure for global formulators.
Pricing Analysis
Price spreads between Chinese fermentation-origin and European crustacean-derived material exceed thirty percent at pharmaceutical-grade purity thresholds. Premium-mid-economy pricing differentiation separates vegan-certified fermentation sulfate from shellfish-hydrolysis alternatives, with EFSA-validated health claims commanding pharmacist-recommendation premiums in German and French pharmacy channels. Pricing pressure stems from Indian FSSAI liberalization opening direct-to-consumer e-commerce pathways that bypass traditional wholesale markups. Sports nutrition contract manufacturers exhibit highest price sensitivity, while reimbursed osteoarthritis treatment protocols in EU pharmacy channels demonstrate lowest elasticity.
Supply Chain Analysis
REACH registration requirements for chitosan-derived intermediates restrict EU-bound flows of crustacean-origin material lacking species-traceability documentation. Raw material sourcing draws from Zhejiang and Shandong fermentation clusters, Southeast Asian shrimp and crab shell aquaculture operations, and Corn Belt agricultural processing infrastructure for Cargill's integrated supply. Single-source vulnerability concentrates in Hangzhou Bay, where over half of global HCl capacity sits within two hundred kilometers. Distribution runs through direct procurement agreements between Chinese fermentation specialists and North American sports nutrition brands with in-house regulatory capabilities, displacing traditional Hong Kong and Rotterdam trading house layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports nutrition segment expansion represents early-cycle penetration tailwind as aging athletic populations integrate preventive joint maintenance into training regimens across Australia and Germany.
For Market Incumbents: Build certification moats around vegan-labeled fermentation production to defend against Zhejiang capacity entrants and European green manufacturing transitions. Secure dual-sourcing agreements with Shandong fermentation specialists to mitigate Hangzhou Bay concentration risk. Invest in USP-EP-ChP harmonization capabilities to preempt batch-release bottlenecks for multi-territory pharmaceutical customers. For New Entrants and Emerging Players: Indian dietary supplement channels offer underpenetrated white-space as FSSAI streamlined notification pathways compress regulatory lead times versus legacy markets. Target cosmeceutical topical delivery formulations in Seoul and Tokyo dermatology lines where N-acetyl derivative premiums exceed oral supplement margins. Pursue quality agreements with Australian TGA-registered brands seeking sulfate supply outside established Chinese distributor networks. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors fermentation-specialist acquisition targets with pharmaceutical-grade purity capabilities and established NMPA registration pathways. Long-term viability hinges on carbon-negative production credentials securing EU Green Deal biomanufacturing incentives and vegan certification premiums. Watch for NIH-funded clinical trial outcomes as inflection indicator for physician recommendation rates in US managed care networks.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Zhejiang and Shandong producers capture carbon credit benefits through continuous bioreactor installations. |
| Backward Integration into Chitosan Supply | Specialists secure captive raw material streams eliminating seasonal shellfish harvest volatility. |
| Pharmacopeial Harmonization Investment | Multi-territory suppliers preempt USP-EP-ChP specification divergence causing batch-release delays. |
| Direct Procurement Channel Development | North American sports nutrition brands bypass Hong Kong and Rotterdam distributor markups. |
| Vegan Certification Program | Fermentation-derived sulfate commands premium positioning in European pharmacy and sports nutrition channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with dietary supplement formulators, pharmaceutical procurement managers, fermentation plant engineers, and regulatory affairs specialists at FDA and EMA submission levels. Secondary validation drew from NMPA pharmaceutical registration databases, SAMR food supplement compliance filings, EFSA health claims registers, and US customs import records. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs across the analysis window.
Calibration against historical capacity utilization rates and announced bioreactor installations shaped projection parameters. Segmentation dimensions modeled include product type crystallization economics, dosage form manufacturing cost structures, application reimbursement eligibility, and distribution channel regulatory complexity. CAGRs were derived from elasticity-adjusted demand curves incorporating sports nutrition penetration rates and pharmacy reimbursement protocol changes. Industry-specific forecast inputs comprised EMA health technology assessment timelines and FSSAI notification pathway processing speeds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported fermentation scale-ups or EU carbon-border adjustment implementations would shift outcomes. Material shifts in NIH clinical trial efficacy findings or REACH chitosan authorization requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Pediatric Supplements Market