
 France Automotive Lubricants Market | 2026-2036
France Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Lubricants Market Foresight
Aftermarket service revenue is reshaping profit pools across the France automotive lubricants sector as OEM-affiliated workshops capture a growing share of high-margin synthetic oil changes. TotalEnergies leverages its integrated refinery network in Normandy to secure feedstock cost advantages for premium formulations. FUCHS anchors its position through specialized industrial partnerships with French fleet operators requiring extended-drain solutions. Motul competes in the performance segment, where racing-grade certifications command substantial price premiums over standard formulations.
France automotive lubricants comprise formulated petroleum-derived or synthetic base stocks combined with additive packages to reduce friction, dissipate heat, and prevent wear in internal combustion engines and driveline components; typical engine oils carry SAE viscosity grades ranging from 0W-16 to 15W-40 and must meet ACEA sequences for European vehicle specifications. Synthetic technology leads value generation due to longer drain intervals and OEM factory-fill specifications, while bio-based alternatives remain nascent despite France's national bioeconomy incentives. Engine oil dominates volume throughput across passenger vehicles and commercial trucks, though transmission fluid generates higher per-liter margins in the aftermarket channel.
France's lubricant formulations fall under REACH chemical registration through ECHA and must comply with EU F-Gas Regulation for fluorinated compound content in specialty applications. ANSM and France's national environmental agency enforce waste oil collection and recycling quotas that elevate operational costs for independent blenders. Stakeholders must monitor how the EU Green Deal's carbon border adjustments and evolving ACEA oil sequences for hybrid powertrains will redirect formulation investments and channel economics across the French supply base.
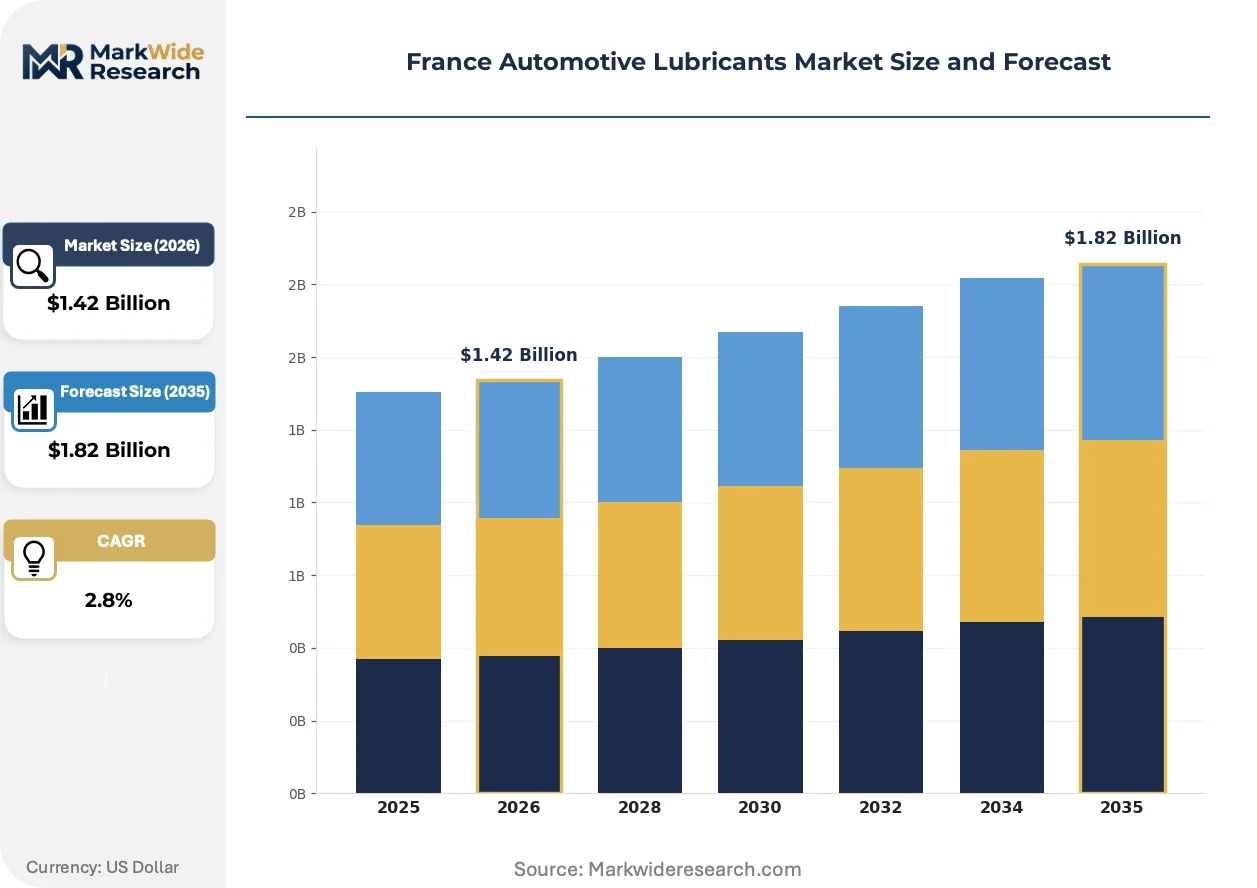
Market Dynamics
EU Green Deal carbon intensity benchmarks are forcing rapid reformulation across France's automotive lubricants supply base, compressing margins for conventional mineral oil producers while rewarding synthetic capacity investments.
Growth Catalysts
- Extended-drain synthetic technology:Fleet operators in the Ile-de-France logistics corridor are mandating ACEA C5/C6 low-viscosity grades to reduce vehicle downtime and maintenance labor costs.
- ANSM waste oil recycling quotas:France's national environmental agency enforces collection mandates that create captive feedstock loops for re-refined base oil producers.
- Hybrid powertrain factory-fill specifications:OEM assembly plants between Paris and Lyon require specialized thermal management fluids for electrified drivelines.
Market Restraints
- Group II/III base oil import dependence:France lacks domestic API Group III capacity, exposing blenders to Middle Eastern and Asian refinery margin volatility.
- REACH registration cost escalation:ECHA chemical dossier maintenance consumes disproportionate resources versus larger EU lubricant markets.
- Bio-based formulation performance gap:Rapeseed-derived esters fail to match PAO thermal stability for turbocharged direct-injection engines.
Strategic Opportunities
- Auvergne-Rhône-Alpes industrial cluster:Lyon-based automotive suppliers lack dedicated lubricant technical centers, creating white space for formulation partnerships.
- EU F-Gas Regulation phase-down:Refrigeration lubricant converters need PFAS-free alternatives for electric vehicle thermal systems.
- Direct-to-fleet digital procurement:Telematics-enabled oil analysis services bypass traditional distributor markups for large transport operators.
Industry Challenges
- Additive chemist talent scarcity:France's specialized lubricant formulation programs graduate fewer than fifty masters-level engineers annually.
- ACEA 2025 sequence compliance timelines:New low-speed pre-ignition tests require eighteen-month validation cycles before factory-fill approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Lubricants Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.82 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid, Coolant, Hydraulic Oil Technology: Synthetic, Semi-Synthetic, Mineral, Bio-Based, High Mileage, Racing Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Agricultural Vehicles, Construction Equipment, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Service Stations, Fleet Operators, Dealerships |
| Companies Covered | Royal Dutch Shell Plc, FUCHS, TotalEnergies, LIQUI MOLY, Eni SpA, BP PLC (Castrol), Motul, IGOL, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Lubricants Market Shifts & Advancements
Digital oil condition monitoring is compressing traditional drain interval assumptions while regulatory chemistry restrictions force base stock diversification beyond petroleum-derived feedstocks.
Artificial intelligence-driven predictive maintenance platforms are virtualizing the conventional fixed-interval oil change model. Fleet telematics providers deploy real-time viscosity and oxidation sensors to trigger service events based on actual lubricant degradation rather than mileage thresholds. Major French transport operators are virtualizing their maintenance scheduling through API-connected diagnostics, collapsing the aftermarket revenue predictability that lubricant distributors historically relied upon.
REACH authorization restrictions on zinc dialkyldithiophosphate concentrations are forcing anti-wear additive package redesigns. ECHA's sunset date assessments for specific ZDDP chemistries compel blenders to accelerate ashless phosphorus-sulfur alternatives. The passenger vehicle segment bears the highest compliance burden, with ACEA C6 sequences already mandating reduced sulfated ash content that constrains traditional EP additive loading.
Workshop consolidation around OEM-affiliated service networks is concentrating high-margin synthetic oil demand. Independent garages in Provence-Alpes-Côte d'Azur face exclusion from proprietary diagnostic systems required for hybrid powertrain servicing. This channel compression redirects volume toward manufacturer-captive lubricant specifications, eroding the open aftermarket's share of premium formulation sales despite lower per-liter pricing at independent outlets.
France Automotive Lubricants Market Segmentation
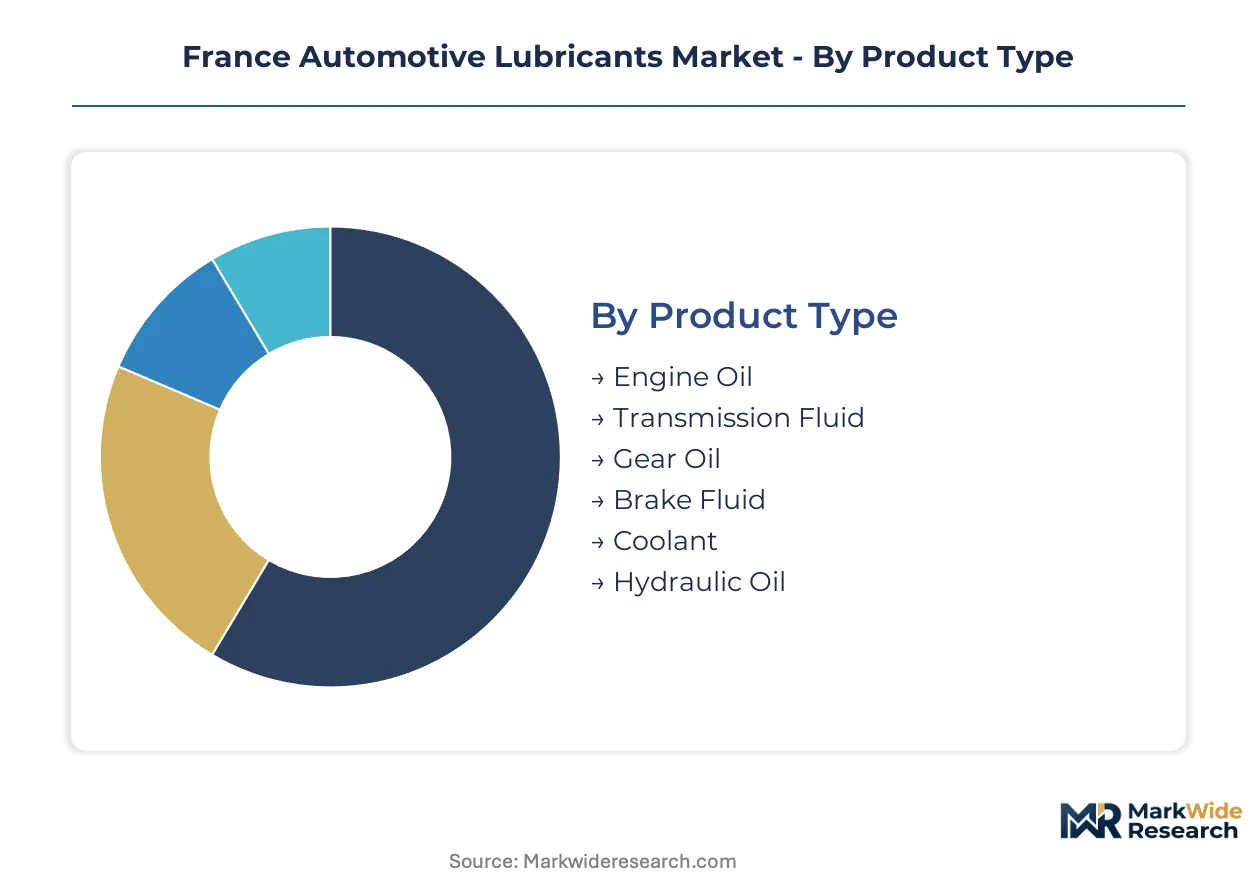
Segmentation in France's automotive lubricants market reveals how formulation chemistry, vehicle electrification, and channel consolidation are redistributing value across distinct product and customer categories. Understanding these divisions exposes where margin compression threatens conventional suppliers and where premium positioning rewards specialized capabilities.
Product Type:
Use-case spectrum spans thermal management in electrified powertrains to friction reduction in legacy drivelines, with each product category commanding different technical specifications and service intervals.
- Engine Oil:Formulated base stocks with detergent-dispersant and anti-wear additive packages meeting ACEA C5/C6 sequences for European OEM factory-fill. Demand concentrates in Ile-de-France fleet operations where extended-drain synthetics reduce vehicle downtime for logistics operators facing driver shortage pressures.
- Transmission Fluid:Specialized formulations for dual-clutch and continuously variable transmissions requiring precise friction modification. The Auvergne-Rhône-Alpes automotive manufacturing corridor between Paris and Lyon drives factory-fill specifications for hybrid thermal management systems.
- Gear Oil:Extreme-pressure additives protect hypoid gear sets in commercial truck differentials.
- Brake Fluid:Glycol-ether or silicone-based formulations meeting DOT 4/DOT 5.1 specifications for hydraulic brake systems.
- Coolant:Ethylene glycol or propylene glycol mixtures with corrosion inhibitors for engine thermal regulation.
- Hydraulic Oil:Anti-wear formulations for construction equipment and agricultural machinery power transmission systems.
Established volume favors engine oil; emerging adoption favors transmission fluid.
Technology:
Cost tier separation reflects raw material input differentials and performance certification requirements that dictate channel positioning and pricing power.
- Synthetic:Polyalphaolefin and ester-based formulations manufactured through catalytic cracking and isomerization of petroleum feedstocks. TotalEnergies leverages its Normandy refinery integration to secure cost-advantaged Group III base oil supply for premium passenger vehicle factory-fill contracts.
- Semi-Synthetic:Blends combining Group II mineral bases with synthetic components to balance cost and performance. Independent workshops in Provence-Alpes-Côte d'Azur favor these formulations for price-sensitive maintenance services on aging vehicle parc.
- Mineral:Solvent-refined Group I base stocks derived from crude oil vacuum distillation.
- Bio-Based:Rapeseed-derived esters and vegetable oil formulations eligible for France's national bioeconomy incentives.
- High Mileage:Seal conditioners and anti-leak additives formulated for vehicles exceeding 100,000 kilometers.
- Racing:Motul produces these formulations with ester core technology for motorsport applications commanding substantial price premiums.
Volume concentration remains with semi-synthetic; margin expansion concentrates in synthetic.
Application:
Customer type diversity across vehicle categories determines specification complexity and service channel requirements.
- Passenger Vehicles:ACEA-graded engine oils for gasoline and diesel engines spanning viscosity grades 0W-16 through 5W-40. OEM-affiliated workshops in Ile-de-France capture synthetic oil change revenue through proprietary diagnostic-locked servicing.
- Commercial Trucks:Heavy-duty engine oils meeting ACEA E6/E8 sequences for Euro VI emission compliance. Fleet operators mandate telematics-enabled oil analysis to virtualize maintenance scheduling and collapse traditional distributor markups.
- Two-Wheelers:JASO MA2/MA certified oils for motorcycle wet clutch compatibility.
- Agricultural Vehicles:Universal tractor transmission oils serving hydraulic, brake, and gearbox functions.
- Construction Equipment:High-viscosity index hydraulic oils for excavator and loader hydraulic systems.
- Specialty Vehicles:Military, emergency service, and motorsport applications requiring custom formulation.
Aftermarket revenue concentrates in passenger vehicles; fleet digitization is accelerating most quickly in commercial trucks.
End User:
Supply concentration varies dramatically between captive OEM channels and fragmented independent distribution.
- OEMs:Factory-fill specifications negotiated directly with lubricant blenders for new vehicle assembly. The Paris-Lyon manufacturing corridor requires specialized thermal management fluids for electrified driveline integration.
- Aftermarket Suppliers:Independent distributors serving non-affiliated repair networks face margin pressure from workshop consolidation.
- Vehicle Assemblers:Contract manufacturers requiring just-in-time lubricant delivery for production line supply.
- Service Stations:High-volume oil change operations competing on speed and convenience.
- Fleet Operators:Large transport companies in Ile-de-France deploying direct digital procurement to bypass traditional channel markups.
- Dealerships:Manufacturer-captive service networks controlling proprietary diagnostic access for hybrid powertrain maintenance.
Channel control favors OEMs; procurement autonomy is expanding fastest among fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across French sub-regions, with fleet-dense logistics corridors absorbing premium synthetic markups while rural independent workshops resist formulation upgrades. The report maps demand elasticity against regulatory enforcement intensity and manufacturing concentration.
Île-de-France
Paris-region fleet operators mandate ACEA C5/C6 low-viscosity synthetics to minimize vehicle downtime amid chronic driver shortages. ANSM waste oil recycling quotas enforce closed-loop collection systems across Seine-Saint-Denis logistics parks. The Roissy-Charles de Gaulle freight cluster drives factory-fill specifications for electrified last-mile delivery vans.
Auvergne-Rhône-Alpes
Lyon-based automotive suppliers source specialized thermal management fluids for hybrid powertrain assembly. EU Green Deal carbon intensity benchmarks accelerate reformulation timelines for Saint-Étienne component manufacturers. The Grenoble precision engineering corridor lacks dedicated lubricant technical centers, creating partnership opportunities for formulation specialists.
Provence-Alpes-Côte d'Azur
Marseille-Fos port logistics operators deploy telematics-enabled oil analysis to virtualize maintenance scheduling. Independent garages in Nice and Toulon favor semi-synthetic formulations for price-sensitive services on aging vehicle parc. REACH registration cost escalation disproportionately burdens smaller blenders serving this fragmented aftermarket channel.
Hauts-de-France
Lille metropolitan fleet operators negotiate direct digital procurement contracts bypassing traditional distributor markups. The Dunkirk industrial zone hosts re-refined base oil capacity feeding circular economy mandates. Calais cross-channel logistics corridors demand extended-drain solutions for high-utilization commercial trucks.
Occitanie
Toulouse aerospace suppliers extend lubricant specification expertise into adjacent automotive applications. Montpellier agricultural machinery dealers specify universal tractor transmission oils serving combined hydraulic-brake-gearbox functions. Bio-based rapeseed-derived formulations gain trial adoption under France's national bioeconomy incentives despite thermal stability limitations.
France Automotive Lubricants Market Competitive Landscape
Capability concentration sits with integrated energy majors possessing captive refinery networks; scale advantage sits with specialized lubricant blenders serving niche performance segments. The French market structures around three archetypes: refinery-integrated majors leveraging feedstock cost advantages, independent specialists commanding racing and industrial certifications, and regional distributors fighting margin compression from workshop consolidation. Competitive moves center on synthetic capacity expansion and direct-to-fleet digital procurement platforms that collapse traditional channel economics.
Within the refinery-integrated tier, TotalEnergies exemplifies upstream-backward advantage through its Normandy operations. FUCHS occupies a position as the industrial-specialist archetype, while Motul anchors the performance-segment premium tier. These three names represent distinct competitive vectors: feedstock security, technical partnership depth, and motorsport certification equity respectively.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| FUCHS |
| TotalEnergies |
| LIQUI MOLY |
| Eni SpA |
| BP PLC (Castrol) |
| Motul |
| IGOL |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Normandy's refinery complex anchors feedstock cost advantages that cascade through synthetic lubricant pricing tiers, with integrated majors capturing margin expansion that independent blenders cannot replicate. The Paris-Lyon manufacturing corridor concentrates OEM purchasing power, compressing aftermarket pricing flexibility for distributors serving fragmented independent workshops.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture, with OEM-affiliated workshops bundling synthetic oil changes into proprietary diagnostic-locked maintenance programs. Three-tier pricing structure across premium, standard, and economy levels separates factory-fill synthetics from semi-synthetic service fills and mineral-based economy offerings. Cost compression in the independent channel intensifies because workshop consolidation redirects volume toward manufacturer-captive specifications. Fleet operators in Ile-de-France show least price sensitivity due to downtime cost calculus, while rural independent garages in Provence-Alpes-Côte d'Azur resist formulation upgrades.
Supply Chain Analysis
Extended payment terms from Middle Eastern and Asian Group II/III base oil suppliers strain working capital for French independent blenders lacking refinery integration. Geographic supply concentration rests on Middle Eastern API Group III capacity, Asian Group II refinery output, and limited European re-refined base oil production. Raw material dependencies hinge on polyalphaolefin feedstocks, detergent-dispersant additive packages, and viscosity modifier polymers. Single-source vulnerability runs through Middle Eastern Group III supply routes. Distribution runs through national lubricant distributors, direct fleet procurement platforms, and OEM-captive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lubricant formulation expertise functions as the constraining asset in this market, with fewer than fifty masters-level engineers graduating annually from French technical programs. This capability bottleneck shapes competitive outcomes across synthetic development and regulatory compliance timelines.
For Market Incumbents: Build captive technical center moats through Auvergne-Rhône-Alpes formulation partnerships that preempt emerging specialist entrants. Anchor backward integration into re-refined base oil capacity at Dunkirk to secure circular economy compliance ahead of ANSM quota expansion. Defend against telematics-enabled procurement disintermediation by embedding oil analysis services within fleet management platforms.
For New Entrants and Emerging Players: The Grenoble precision engineering corridor offers underpenetrated white space for hybrid thermal management fluid partnerships lacking dedicated lubricant technical centers. Target direct-to-fleet digital procurement channels in Hauts-de-France where transport operators bypass traditional distributor markups. Pursue PFAS-free refrigeration lubricant development for electric vehicle thermal systems under EU F-Gas Regulation phase-down timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors re-refined base oil producers with captive collection network access and ACEA C5/C6 formulation certification. Long-term viability hinges on synthetic capacity expansion and circular economy integration rather than mineral oil legacy assets. Watch for inflection signals in ACEA 2025 sequence compliance timelines that accelerate eighteen-month validation cycle bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Capacity Expansion | Group III base oil investments at Normandy secure factory-fill contracts with Paris-Lyon OEM assembly plants. |
| Direct-to-Fleet Digital Procurement | Telematics-enabled oil analysis platforms collapse distributor markups for Ile-de-France logistics operators. |
| Re-Refined Base Oil Scale-Up | Dunkirk circular economy capacity captures ANSM waste oil recycling quota advantages. |
| Hybrid Thermal Management Partnership | Auvergne-Rhône-Alpes technical centers address electrified driveline fluid specification gaps. |
| PFAS-Free Refrigeration Lubricant Development | EU F-Gas Regulation compliance opens electric vehicle thermal system conversion opportunities. |
Research Methodology
Initial hypotheses were tested against primary input from lubricant plant managers, OEM procurement leads at Tier 1 suppliers, aftermarket distribution channel partners, and technical R&D directors at formulation houses, then refined against customs trade data, ACEA oil sequence documentation, ANSM regulatory filings, and SEC disclosures from integrated energy majors. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, base oil technology tier, vehicle application class, and end-user channel structure. CAGRs were derived from regression analysis against vehicle parc growth, electrification penetration curves, and synthetic substitution rates. Industry-specific forecast inputs incorporated ACEA sequence adoption timelines and ANSM waste oil collection mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive synthetic capacity expansion by Middle Eastern national oil companies or accelerated EU Green Deal carbon border adjustments would shift outcomes. Macroeconomic contraction in Ile-de-France logistics, regulatory deviation in REACH authorization timelines, or breakthrough bio-based formulation performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Steel Cords for Radial Tyres Market