
 Speed Bump Market | 2026-2036
Speed Bump Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Bump Market Analytics
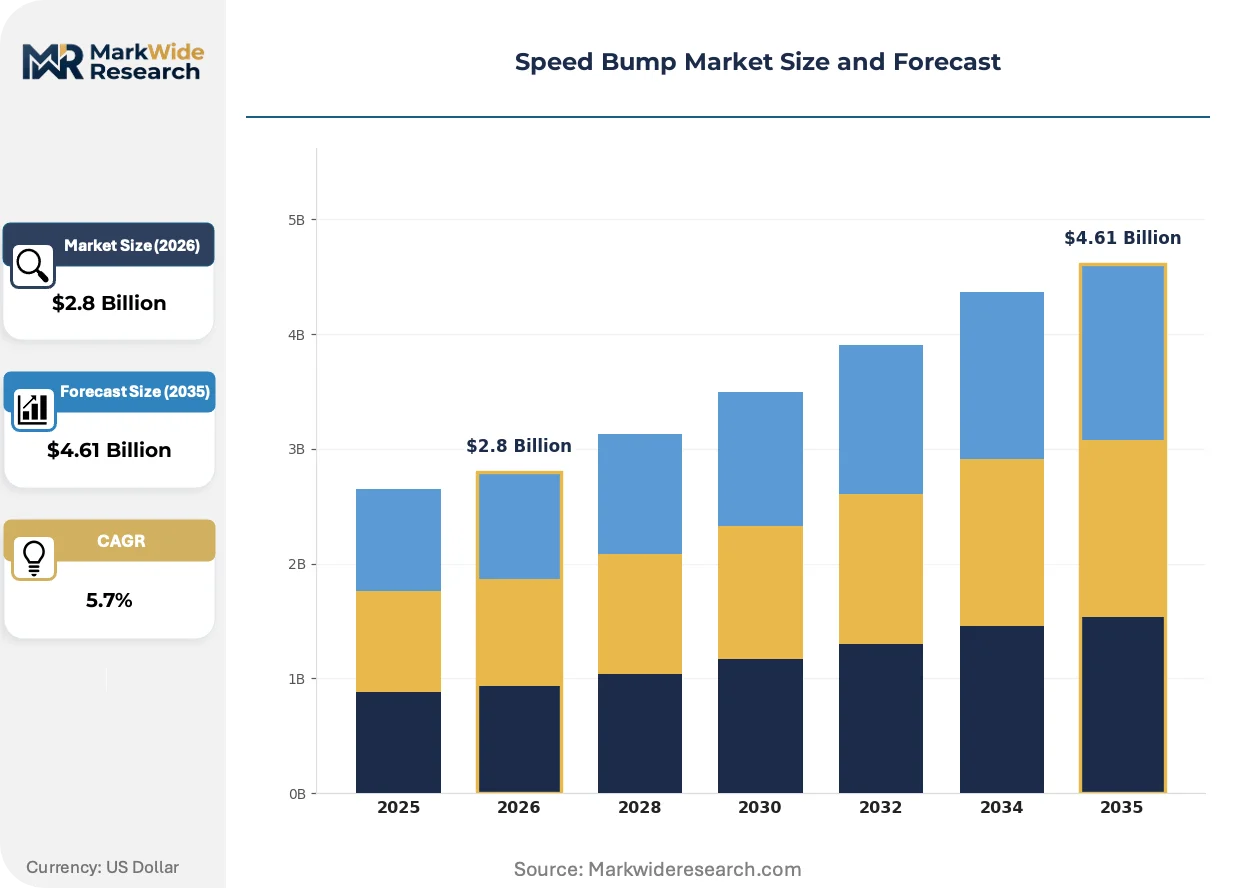
Municipal infrastructure budgets are rotating toward traffic calming investments as commercial property developers scale back non-essential roadway spending. CABKA Group leverages recycled polymer compounding to anchor supply contracts with European municipal aggregators. Reliance Foundry sustains foundry-grade ductile iron production for permanent installations across Canadian provinces. Innoplast competes through portable, interlocking modular systems targeting event management and construction zone temporary needs.
Speed bumps are raised longitudinal traffic control devices, typically 50-100 mm in height and 300-600 mm in width, engineered to reduce vehicle speeds to 15-25 km/h through vertical displacement. They are cast, extruded, or molded from rubber compounds, thermoplastics, asphalt overlays, or reinforced concrete to protect pedestrian corridors and structure perimeters. Rubber speed bumps lead volume due to lower installed cost and surface adaptability, while modular systems represent the fastest-growing installation category as cities prioritize removable, winter-compatible configurations. Concrete speed bumps retain margin concentration in heavy-duty commercial loading zones where load ratings exceed 40 tonnes.
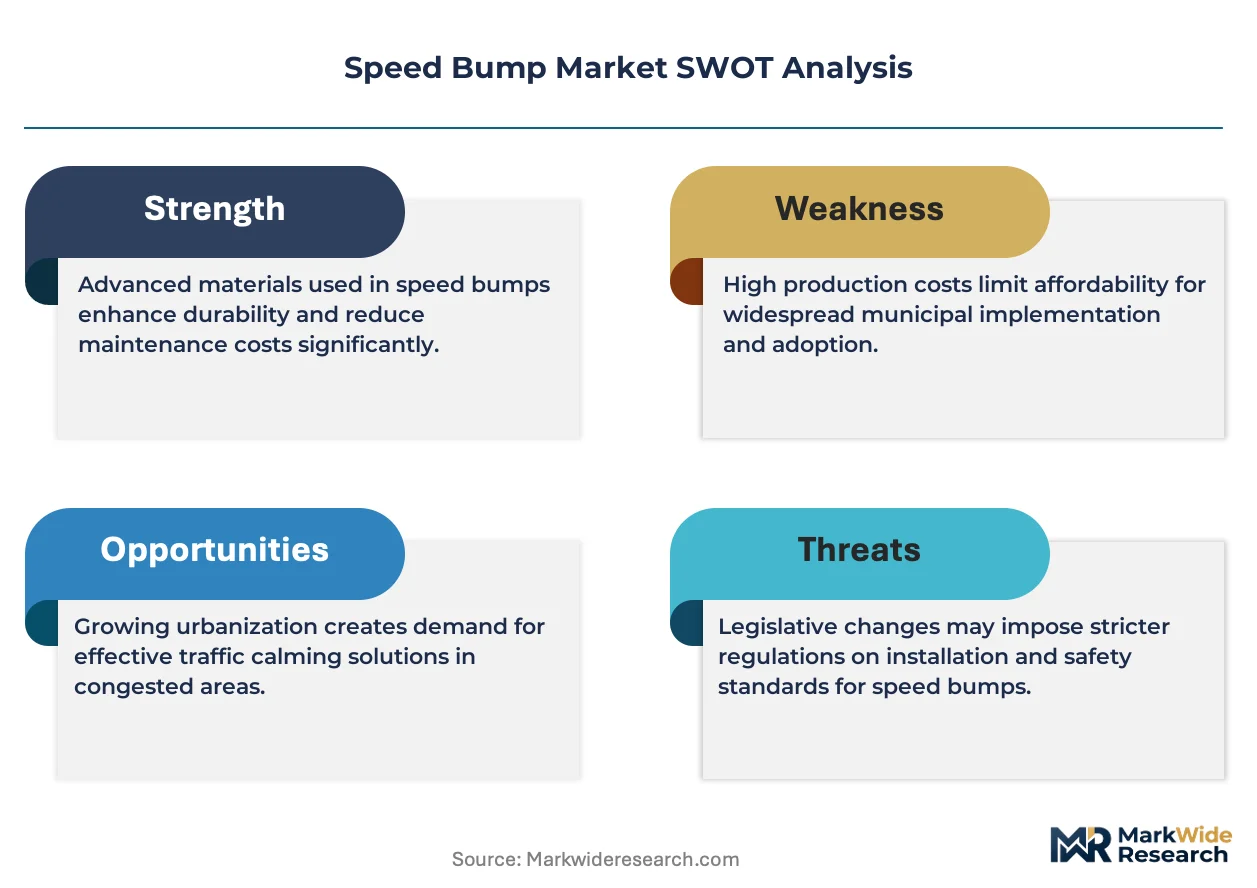
FHWA, AASHTO, and the EU Road Safety Directive collectively shape product geometry, retroreflectivity, and placement spacing across North America and Europe. ADA compliance requirements in the United States mandate detectable warning surfaces at speed bump-adjacent crosswalks, adding material and labor complexity to municipal bids. Stakeholders must monitor evolving low-emission procurement rules and recycled content thresholds that will soon disqualify virgin-only product lines from public sector eligibility.
Market Dynamics
Municipal procurement departments are rotating capital toward removable traffic calming systems as winter maintenance costs and ADA compliance mandates reshape specification requirements. This structural pivot favors modular polymer compounds over permanent concrete installations.
Growth Catalysts
- School Zone Retrofit Mandates:FHWA guidance on Safe Routes to School programs is accelerating rubber speed bump deployment across US districts. District transportation coordinators specify 50 mm height profiles with embedded reflectors.
- Recycled Content Thresholds:EU Green Deal procurement rules now require minimum 30% post-consumer polymer in municipal infrastructure. CABKA Group and competitors are reformulating compounds to meet these benchmarks.
- Event Management Logistics:Temporary modular systems are displacing sandbag barriers at German festival sites and Japanese construction zones. Interlocking designs reduce installation labor by half.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic rubber and thermoplastic elastomer input costs fluctuate with crude oil indices. Compounders lack pricing power to pass through spikes to locked municipal contracts.
- Foundry Concentration Risk:Ductile iron speed bump production clusters in Chinese and Indian foundry districts. Buyers face extended lead times and quality inconsistency during regional power rationing events.
- Concrete Substitution Ceiling:Heavy commercial loading docks above 40 tonne ratings require reinforced concrete. Polymer alternatives cannot achieve equivalent compressive strength without prohibitive material thickness.
Strategic Opportunities
- Smart City Integration:Pressure-sensitive speed bumps with embedded IoT sensors are enabling real-time traffic flow monitoring. Barcelona and Singapore pilot programs validate data monetization potential.
- Winter-Compatible Modular Designs:Snowplow-resistant quick-release anchoring systems open Nordic and Canadian markets previously closed to permanent installations. Municipalities in Sweden and Finland are trialing spring-loaded retraction mechanisms.
- Low-Emission Procurement Incentives:Germany's KBA and US state DOTs are introducing carbon-weighted bid scoring. Products with verified lifecycle assessments gain tender preference regardless of upfront cost.
Industry Challenges
- Retroreflectivity Certification Delays:ASTM F3013 testing backlog at third-party labs extends product approval timelines. Manufacturers face 12-16 week waits for reflectivity validation reports.
- ADA Detectable Warning Integration:Crosswalk-adjacent installations require truncated dome surface integration. Fabricators must coordinate with tactile paver suppliers, complicating project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Bump Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Speed Bumps, Plastic Speed Bumps, Asphalt Speed Bumps, Concrete Speed Bumps Installation Type: Permanent Installations, Temporary Installations, Modular Systems, Embedded Systems Application: Residential Areas, Commercial Zones, School Zones, Parking Lots Compliance Standard: AASHTO Standards, Local Government Regulations, International Safety Guidelines, ADA Compliance |
| Companies Covered | Barrier Group, Ecobam Europa, CABKA Group, Innoplast, Gradus, Axelent, BENITO URBAN, JSP, Reliance Foundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Bump Market Evolving Landscape
Material science advances and procurement digitization are compressing product development cycles. Municipal buyers now expect real-time performance data and rapid deployment capabilities alongside traditional durability metrics.
Embedded piezoelectric sensors within rubber speed bump cores are miniaturizing. These devices harvest kinetic energy from vehicle compression to power wireless traffic counters. Dutch highway authorities and Japanese prefectural road departments are deploying pilot networks. The technology is miniaturizing maintenance requirements by eliminating battery replacement cycles and enabling predictive wear monitoring.
REACH restrictions on polycyclic aromatic hydrocarbons in rubber compounding are tightening. Compounders must reformulate curing agents and oil extenders to maintain elasticity without restricted additives. German KBA type approval and French ANSM road safety directives are synchronizing testing protocols. European manufacturers are consolidating supply chains to single-source certified polymer streams.
Aggregated municipal purchasing cooperatives are consolidating specification authority. US county-level procurement alliances and UK combined authorities are issuing framework contracts that displace individual city tenders. Tier-1 compounders now maintain dedicated bid response teams for these centralized bodies. The shift is most pronounced in California, Texas, and England's metropolitan counties where procurement volume justifies specialized account structures.
Speed Bump Market Segmentation
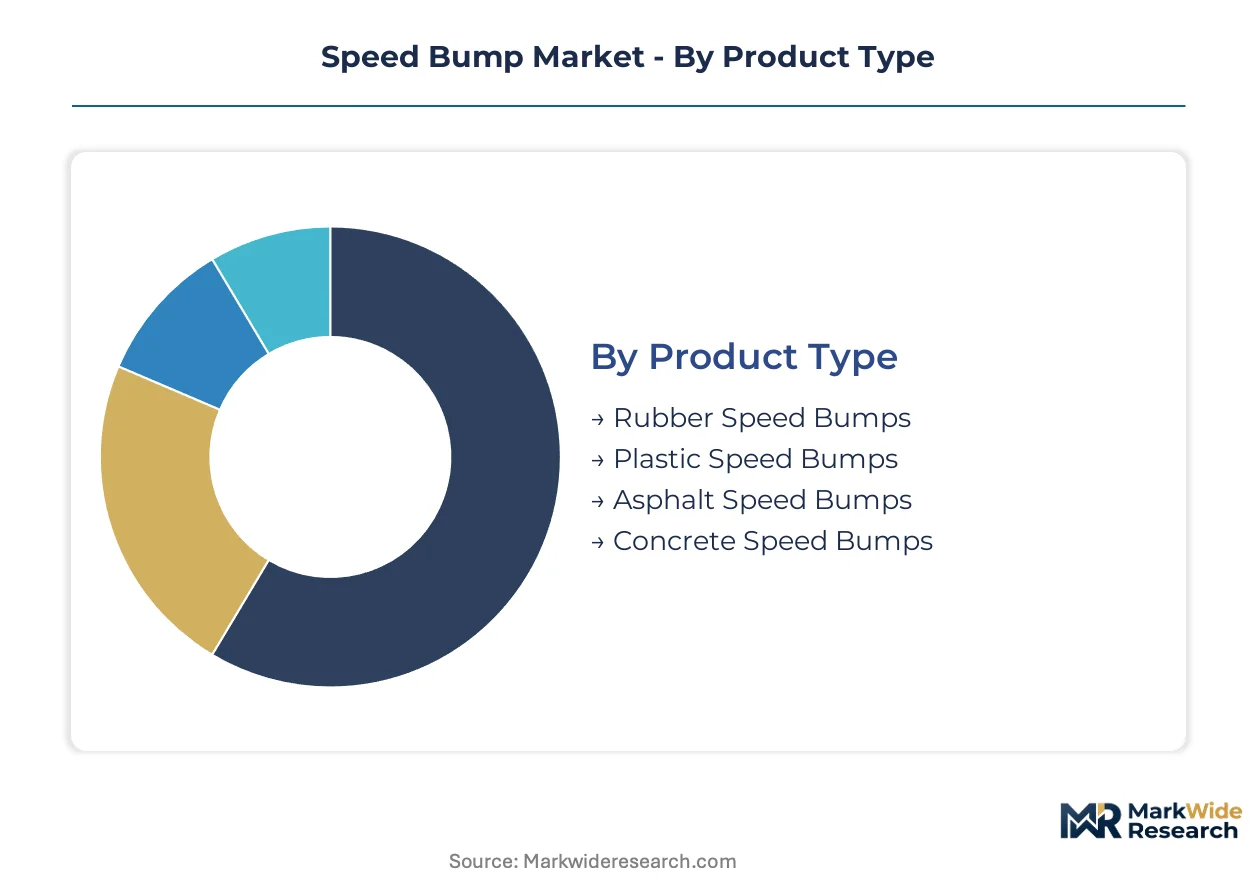
Speed bump procurement patterns diverge sharply across material classes and installation permanence, with municipal buyers prioritizing winter compatibility and ADA alignment over raw durability metrics. Specification authority is consolidating into county-level purchasing cooperatives that demand cross-category compliance documentation.
Product Type:
Rubber and polymer compounds dominate domestic municipal contracts, while concrete and asphalt solutions concentrate in heavy commercial export channels.
- Rubber Speed Bumps:Molded from recycled tire crumb and synthetic elastomer blends, these units achieve 50-75 mm height profiles with embedded glass bead reflectivity. Demand concentrates in US school zone retrofits where FHWA Safe Routes guidance mandates removable configurations for snowplow clearance.
- Plastic Speed Bumps:Extruded thermoplastic and polymer composite systems offer interlocking modularity with compressive ratings up to 15 tonnes. German festival logistics operators and Japanese construction zone managers specify these for rapid deployment cycles under EU Green Deal recycled content thresholds.
- Asphalt Speed Bumps:Hot-mix overlays bonded to existing pavement deliver seamless integration for permanent residential traffic calming.
- Concrete Speed Bumps:Reinforced precast units rated above 40 tonnes anchor heavy-duty loading dock specifications in Canadian provinces.
Rubber Speed Bumps hold the largest share; momentum sits with Plastic Speed Bumps.
Installation Type:
Cost tiers separate capital-intensive permanent foundations from operational expenditure-driven temporary deployments.
- Permanent Installations:Cast-in-place concrete and anchored steel assemblies require excavation and curing cycles of 72+ hours. Canadian provinces and Nordic municipalities specify these for arterial road treatments where frost heave resistance exceeds priority for modularity.
- Modular Systems:Interlocking polymer units with quick-release anchoring enable seasonal removal without surface damage. Swedish and Finnish road authorities are trialing spring-loaded retraction mechanisms to satisfy snowplow compatibility mandates previously blocking polymer adoption.
- Temporary Installations:Sandballast or friction-anchored units deploy for event management and construction phasing.
- Embedded Systems:Flush-mounted piezoelectric sensor networks integrate with smart city traffic monitoring infrastructure.
Permanent Installations retain volume concentration; Modular Systems are climbing the fastest.
Application:
Customer type segmentation reveals divergent procurement rhythms between institutional buyers and private facility managers.
- School Zones:District transportation coordinators specify 50 mm height profiles with ASTM F3013 reflectivity certification and adjacent ADA detectable warning surfaces. US federal Safe Routes program funding is accelerating rubber and modular deployment across state education budgets.
- Parking Lots:Commercial property developers prioritize 75-100 mm profiles for structure perimeter protection with minimal maintenance overhead. Load rating requirements here split procurement between polymer modular systems and reinforced concrete depending on heavy vehicle exposure.
- Residential Areas:Neighborhood association budgets favor lower-cost asphalt overlay solutions.
- Commercial Zones:Retail and logistics facility managers balance durability against installation speed.
School Zones anchor specification-driven volume; Parking Lots show steepest expansion trajectory.
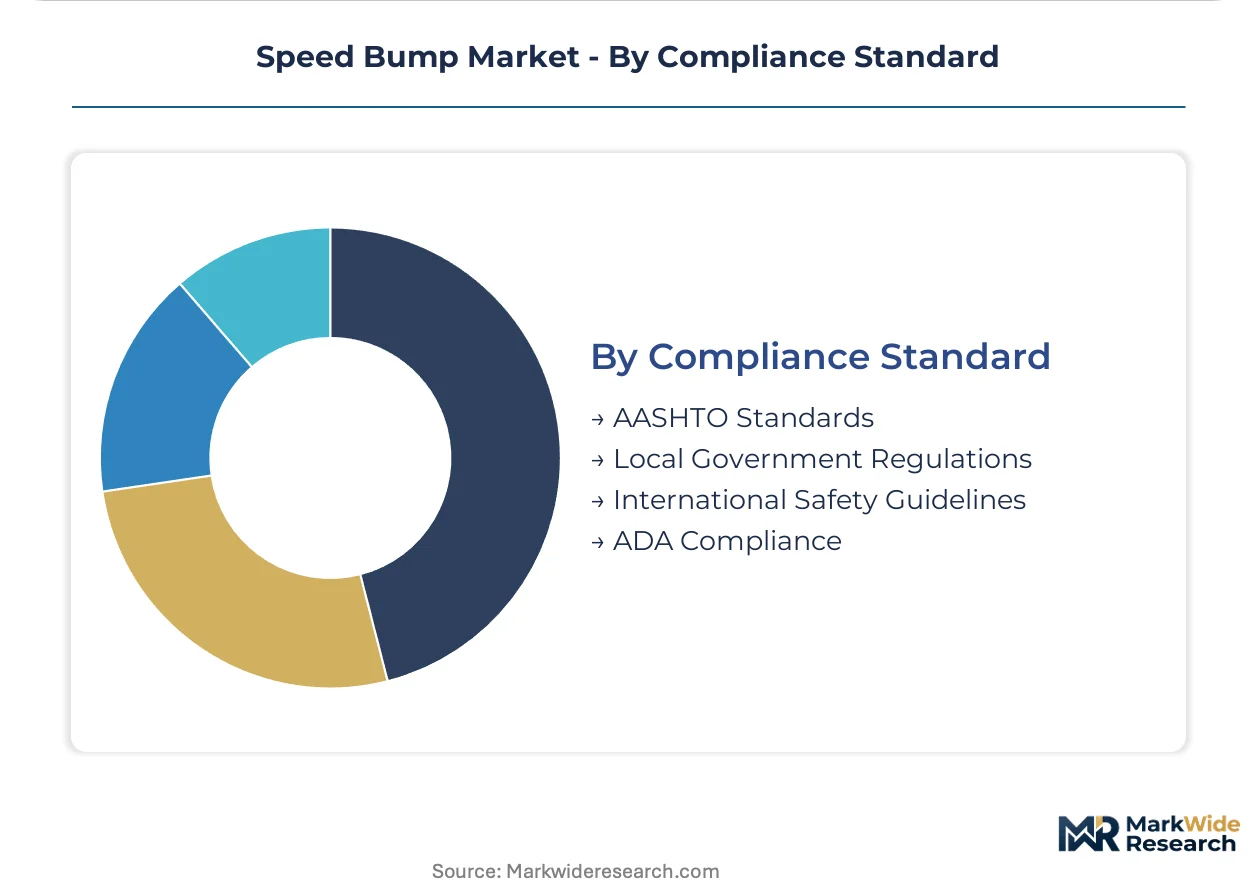
Compliance Standard:
Margin concentration flows toward certified product lines as procurement digitization automates specification filtering.
- AASHTO Standards:Federal highway geometric and retroreflectivity requirements shape US state DOT tender documents. Manufacturers face 12-16 week third-party lab backlogs for ASTM F3013 validation reports, creating bottlenecks for new product launches.
- ADA Compliance:Detectable warning surface mandates at crosswalk-adjacent installations require coordination with tactile paver suppliers. Fabricators integrating truncated dome surfaces command tender preference despite 15-20% material cost premiums.
- Local Government Regulations:Municipal ordinances vary in height, spacing, and signage requirements.
- International Safety Guidelines:ISO and UN road safety protocols govern export market access.
AASHTO Standards capture the dominant procurement filter; ADA Compliance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export modular polymer systems to Swedish and Finnish municipal buyers seeking snowplow-compatible traffic calming. Cross-border procurement frameworks now dominate European specification authority.
United States
FHWA Safe Routes to School funding accelerates rubber speed bump deployment across district transportation budgets. State DOTs enforce AASHTO geometric standards and ASTM F3013 retroreflectivity certification. California county-level purchasing cooperatives consolidate tender authority for polymer and modular systems.
Germany
KBA type approval mandates synchronize with French ANSM road safety directives across REACH-compliant rubber compounding. EU Green Deal procurement rules require minimum post-consumer polymer thresholds. Bavarian municipal aggregators source recycled-content modular systems for festival logistics and construction zone applications.
Japan
Prefectural road departments pilot piezoelectric sensor networks embedded in rubber speed bump cores for traffic monitoring. METI standards govern product geometry and reflectivity specifications. Tokyo metropolitan procurement channels concentrate demand for interlocking portable systems at event management sites.
Sweden
Road authorities trial spring-loaded retraction mechanisms for modular polymer installations to satisfy winter maintenance mandates. National procurement frameworks prioritize snowplow-resistant quick-release anchoring. Stockholm regional transport planners specify removable configurations for arterial road treatments.
Canada
Provincial infrastructure budgets split between foundry-grade ductile iron for permanent installations and modular alternatives for seasonal removal. Health Canada guidelines align with US ADA detectable warning surface requirements. Ontario municipal procurement cooperatives consolidate orders for heavy-duty loading dock specifications.
Speed Bump Market Competitive Landscape
Player mix skews toward specialized compounders and foundry operators with divergent material expertise. The vendor base separates cleanly between polymer specialists serving municipal retrofit cycles and metal fabricators anchoring permanent commercial infrastructure. Two strategic archetypes dominate: recycled-content compounders competing on EU Green Deal compliance thresholds, and foundry operators leveraging load-rating superiority for heavy-duty specifications. Competitive moves concentrate on supply chain consolidation for certified polymer streams and geographic expansion through county-level procurement cooperative frameworks.
Within the recycled-polymer tier, CABKA Group and Innoplast occupy positions as European and North American anchors respectively. Reliance Foundry exemplifies the foundry-grade archetype for permanent installations. These three entities represent the material-technology fault line shaping specification outcomes across municipal and commercial bid environments.
| Leading Market Players |
|---|
| Barrier Group |
| Ecobam Europa |
| CABKA Group |
| Innoplast |
| Gradus |
| Axelent |
| BENITO URBAN |
| JSP |
| Reliance Foundry |
| Others |
Value Network & Pricing Analysis
Fourteen-week lead times for ASTM F3013 retroreflectivity certification concentrate pricing power with incumbent compounders holding validated inventory positions, while municipal buyers locked into annual procurement cycles absorb cost pass-through from petrochemical feedstock volatility.
Pricing Analysis
Current-generation rubber speed bump systems command 20-35% premiums over prior-generation asphalt overlay solutions, while next-generation piezoelectric-embedded units remain pre-commercial with project-based pilot pricing. Three-tier pricing structure across premium certified-grade, standard municipal-grade, and economy temporary-grade levels stratifies procurement outcomes. Cost compression in standard-grade polymer compounds intensifies as recycled-content thresholds harden under EU Green Deal rules. School zone retrofit buyers exhibit highest price sensitivity due to federal grant funding caps, while heavy commercial loading dock operators prioritize load-rating certification over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound inbound logistics costs for synthetic rubber and thermoplastic elastomer feedstocks. Manufacturing concentrates in China, Germany, and the United States, with compounding operations drawing from petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor. Raw material dependencies rest on styrene-butadiene rubber, recycled tire crumb, and glass bead reflector supply. Single-source vulnerability clusters in Chinese foundry-grade ductile iron production. Distribution runs through municipal procurement cooperatives and construction supply distributors serving commercial facility managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speed bump market incumbents face substitution pressure from integrated smart-city sensor networks that monetize traffic data beyond physical traffic calming, requiring defensive positioning around certification moats and recycled-content compliance.
For Market Incumbents: Secure captive supply of REACH-certified recycled polymer streams to defend margin position against EU Green Deal threshold escalation. Anchor specification authority through backward integration into tactile paver manufacturing for ADA-compliant bundled offerings. Prioritize certification investment in piezoelectric sensor integration to offset displacement risk from standalone IoT traffic monitoring deployments.
For New Entrants and Emerging Players: ASTM F3013 fast-track validation partnerships with third-party labs offer entry acceleration into US school zone retrofit channels. White-space concentrates in Nordic spring-loaded retraction mechanism designs for snowplow-compatible modular systems. Target German festival logistics operators with rapid-deployment interlocking polymer units certified under EU Green Deal post-consumer content mandates.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory divergence between EU recycled-content rules and US ADA mandates creates multi-jurisdictional capability premiums. Acquisition candidates should demonstrate validated polymer compounding expertise plus established municipal cooperative relationships. Monitor carbon-weighted bid scoring adoption in German KBA and US state DOT tender frameworks as inflection signal for low-emission procurement preference crystallization.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polymer Reformulation | EU Green Deal 30% post-consumer thresholds disqualify virgin-only product lines from municipal eligibility. |
| ADA Bundled Offering Development | Truncated dome surface integration commands tender preference despite material cost premiums at crosswalk-adjacent installations. |
| Piezoelectric Sensor Integration | Embedded kinetic harvesting enables predictive wear monitoring and smart city data monetization pilots in Barcelona and Singapore. |
| Spring-Loaded Retraction Mechanism | Swedish and Finnish road authority trials open Nordic markets previously closed to permanent polymer installations. |
| County-Level Procurement Cooperative Penetration | California, Texas, and England metropolitan county frameworks consolidate tender authority away from individual city contracts. |
Research Methodology
A standing panel of municipal procurement directors, traffic engineering consultants, polymer compounding technical leads, and construction supply distributors provided ongoing calibration throughout data collection. Primary interviews with these stakeholders combined with secondary validation against FHWA Safe Routes program documentation, ASTM F3013 testing protocols, EU Green Deal procurement directives, and KBA type approval records. Bottom-up unit shipment estimates triangulated against top-down municipal infrastructure budget allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including AASHTO geometric standard adoption rates and county-level purchasing cooperative contract disclosures. The analytical framework modeled product type, installation permanence, application segment, and compliance standard dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical procurement cycles and policy mandate implementation timelines, with specific inputs including school zone retrofit funding trajectories and recycled-content threshold phase-in schedules.
Underlying assumptions cover municipal budget continuity, petrochemical feedstock price band stability, and certification backlog normalization, with deviation risk concentrated in EU Green Deal threshold acceleration and extended ASTM F3013 testing delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Air Brake Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Global Automotive Muffler Tip Market