
 Asia-Pacific Molecular Sieve Market | 2026-2036
Asia-Pacific Molecular Sieve Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Molecular Sieve Market Outlook
Modular pellet-and-bead bundling is consolidating procurement preferences among mid-scale petrochemical operators who seek standardized desiccant kits over bulk powder purchases. Tosoh Corporation leverages its integrated alumina-to-zeolite manufacturing chain to anchor supply security for Japanese electronics gas purifiers. Clariant competes through specialty catalysis grades tailored to Chinese methanol-to-olefin complexes. JIUZHOU CHEMICALS dominates domestic powder formulations for Shandong province's refinery maintenance cycles.
A molecular sieve is a microporous aluminosilicate or synthetic crystalline material with precise pore apertures, typically measured in angstroms, engineered to selectively adsorb molecules based on size and polarity for industrial separation and purification processes. Synthetic zeolite formulations command the widest application footprint due to their tunable SiO2/Al2O3 ratios and thermal stability above 600°C, though natural zeolite retains cost advantages in bulk water treatment deployments. Gas separation applications are deepening fastest as LNG pretreatment and hydrogen purification expand across Australia and Southeast Asia, while catalysis remains the most margin-intensive segment tied to fluidized catalytic cracker units. Pellet form factors lead volume shipments because they minimize pressure drop in packed columns, yet bead configurations are gaining traction in pharmaceutical drying where attrition resistance protects active pharmaceutical ingredients.
China's MEE enforces stricter volatile organic compound limits that elevate demand for high-performance adsorption media in refinery off-gas recovery. Japan's METI promotes hydrogen economy infrastructure that requires ultra-high-purity molecular sieves for fuel cell feedstock conditioning. India's BIS certification mandates for drinking water treatment create compliance-driven replacement cycles for municipal adsorption systems. Stakeholders must weigh captive zeolite synthesis against third-party supply as regional energy transition timelines harden feedstock specifications.
Market Dynamics
China's dual carbon goals are compressing upgrade cycles across Shandong and Jiangsu refinery corridors, forcing synthetic zeolite replacements ahead of planned maintenance windows and rewiring procurement priorities toward higher-efficiency formulations.
Growth Catalysts
- MEE emission standards:China's Ministry of Ecology and Environment mandates volatile organic compound recovery systems that require high-performance molecular sieves in refinery off-gas treatment. Petrochemical operators in Ningbo and Dalian are retrofitting catalytic cracking units to comply.
- India's pharmaceutical corridor expansion:API manufacturers around Hyderabad and Ahmedabad are building moisture-controlled processing environments that specify 3A and 4A zeolite desiccants for active pharmaceutical ingredient stability.
- Japan's hydrogen economy infrastructure:METI-backed fuel cell deployment creates demand for ultra-high-purity molecular sieves in feedstock conditioning systems for Tokyo and Osaka industrial gas networks.
Market Restraints
- Alumina supply concentration:Synthetic zeolite production depends on specialized alumina feedstocks concentrated among limited Japanese and Chinese suppliers, exposing formulators to input volatility.
- Natural zeolite cost floor:Bulk water treatment applications in Indonesia and Vietnam retain natural zeolite for cost-sensitive municipal contracts, capping price realization for synthetic grades in adjacent segments.
- REACH-equivalent alignment friction:Chinese exporters face testing cost burdens as EU F-Gas Regulation and product safety standards tighten documentation requirements for zeolite catalysts bound for European markets.
Strategic Opportunities
- Vietnam's emerging LNG infrastructure:New regasification terminals in Thi Vai and Son My require pretreatment molecular sieves for mercury and moisture removal, opening greenfield specification battles.
- Australia hydrogen export corridors:Queensland and Western Australia liquefaction projects need large-scale pressure swing adsorption systems for hydrogen purification ahead of export to Japanese and Korean buyers.
- Modular desiccant kit standardization:Mid-scale petrochemical operators are consolidating procurement around pre-bundled pellet-and-bead configurations that reduce inventory complexity and enable vendor-managed replenishment.
Industry Challenges
- Zeolite synthesis talent scarcity:Captive production decisions require crystallization chemists and hydrothermal process engineers concentrated in Japan and eastern China, constraining regional capacity expansion timelines.
- BIS certification cycle compression:India's Bureau of Indian Standards mandates for drinking water treatment adsorption systems force municipal suppliers through extended testing protocols that delay replacement contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Molecular Sieve Market |
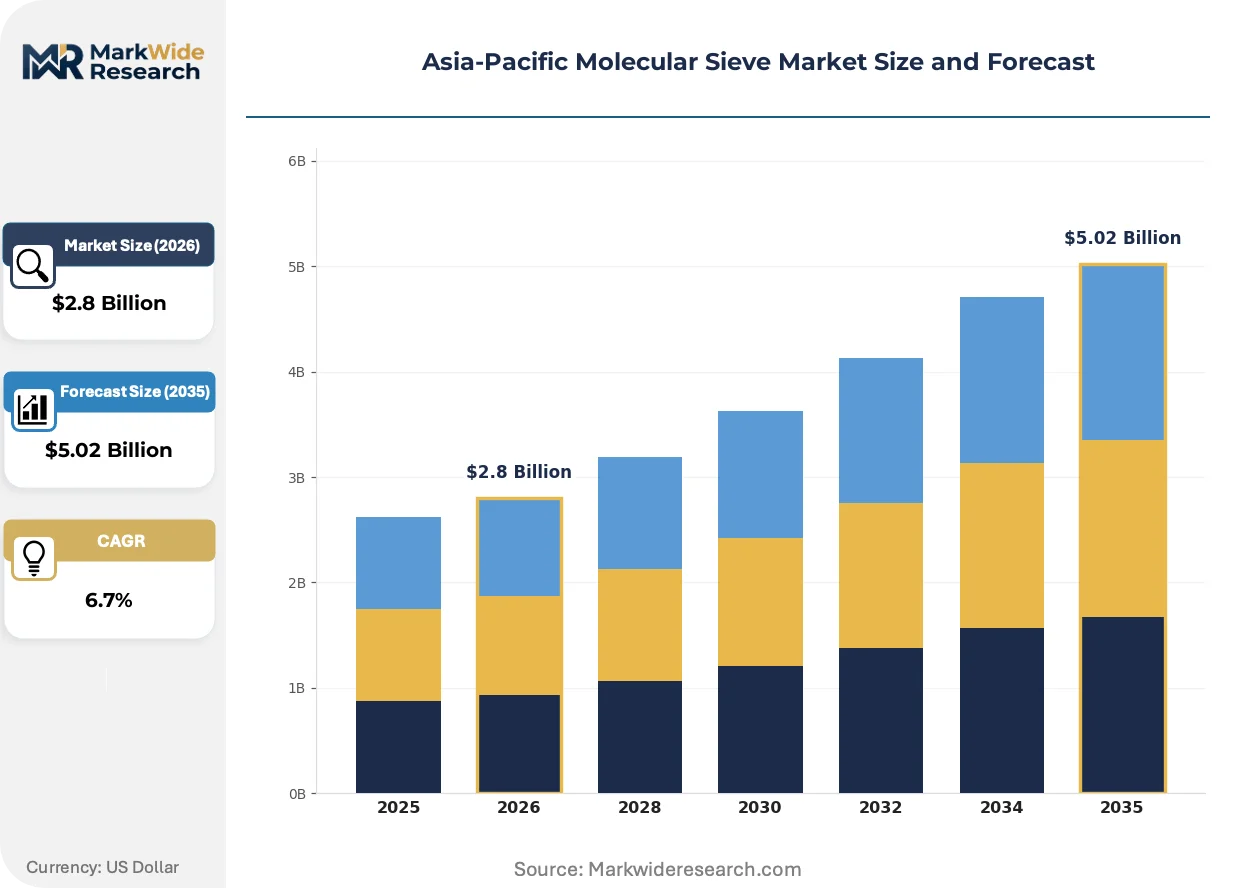
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Zeolite, Synthetic Zeolite, Activated Alumina, Silica Gel Application: Drying Agent, Adsorption, Catalysis, Gas Separation End User: Petrochemical, Pharmaceutical, Chemical, Water Treatment Form: Pellets, Powder, Granules, Beads |
| Companies Covered | Tosoh Corporation, Clariant, Arkema Group, Zeochem AG, BASF SE, Honeywell International Inc, W. R. Grace & Co.-Conn., JIUZHOU CHEMICALS, Sorbead India, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Molecular Sieve Market Strategic Shifts
Formulation science and regulatory chemistry are tightening their grip on competitive positioning across Asia-Pacific molecular sieve markets, with three distinct vectors reshaping how value is captured and defended.
Synthetic zeolite membranes with sub-nanometer pore precision are converging with traditional packed-bed configurations in hydrogen purification applications. Korean petrochemical operators are piloting these hybrid systems at Daesan and Yeosu complexes to reduce pressure drop while maintaining separation selectivity. The technology is converging with conventional pellet economics by enabling smaller footprint designs that offset higher unit costs through reduced infrastructure spend.
China's GB standards for industrial emissions are hardening testing protocols for adsorption media used in refinery catalytic cracking units. The regulatory tightening forces domestic formulators to recertify existing product lines under stricter thermal stability and crush strength benchmarks. Shandong province's refinery maintenance cycles are accelerating specification upgrades as MEE inspectors enforce documented zeolite performance degradation curves.
Mid-scale operators are unbundling after-sales technical service from bulk desiccant supply contracts, treating zeolite replacement as a commodity purchase while sourcing application engineering separately. This procurement pattern disrupts traditional full-service distributors concentrated in Singapore and Shanghai trading hubs. The shift is most visible among Indian specialty chemical manufacturers who now specify molecular sieves through direct mill relationships while engaging third-party consultants for column design validation.
Asia-Pacific Molecular Sieve Market Segmentation
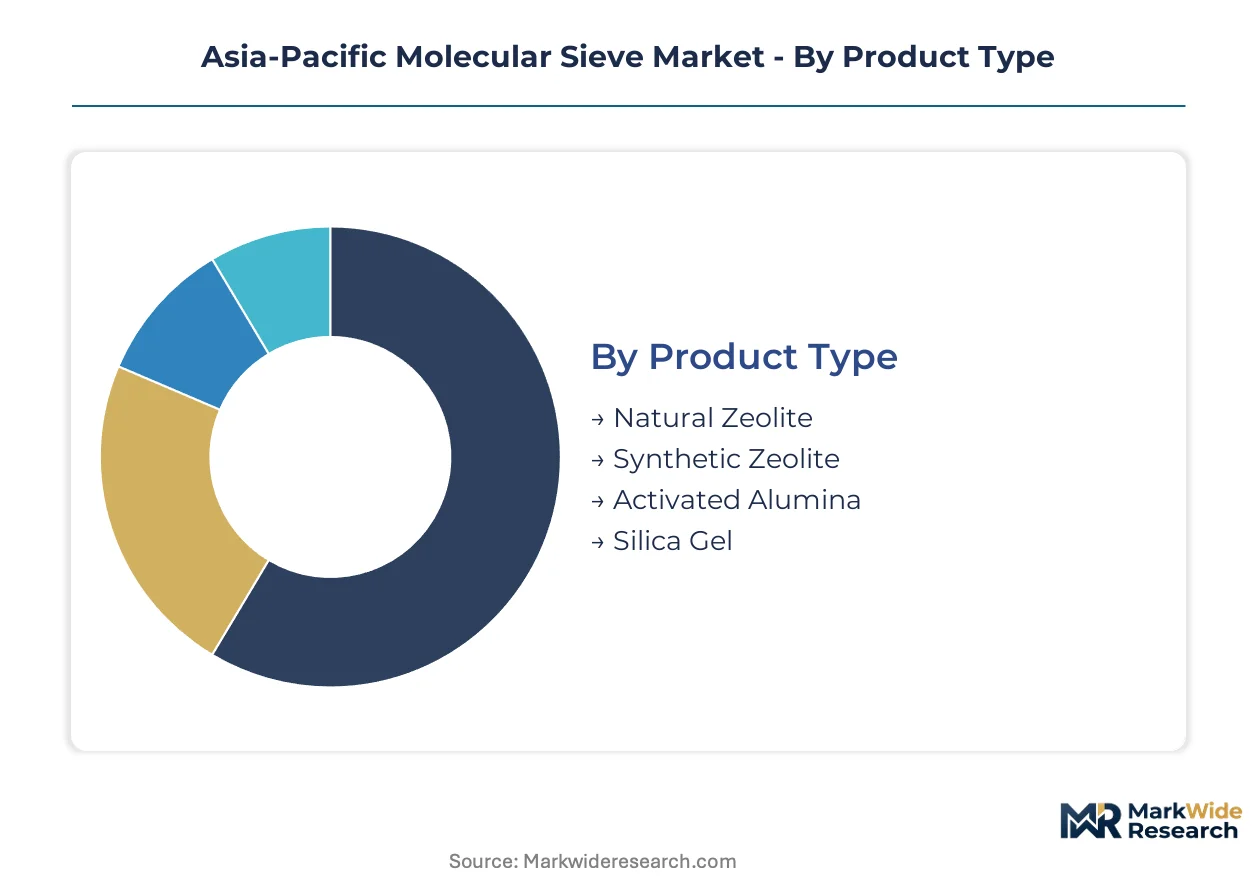
Segmentation in the Asia-Pacific molecular sieve market reveals how procurement priorities diverge across industrial buyers. Refinery operators prioritize thermal stability and crush strength under MEE pressure, while pharmaceutical manufacturers specify attrition-resistant bead configurations for API protection.
Product Type:
Buyers weigh tunable pore precision against feedstock cost floors when selecting aluminosilicate formulations.
- Synthetic Zeolite:Engineered crystalline structures with tunable SiO2/Al2O3 ratios deliver thermal stability above 600°C. Petrochemical refiners in Shandong and Jiangsu specify these formulations to meet MEE volatile organic compound recovery mandates.
- Natural Zeolite:Cost-mineralized volcanic aluminosilicates with fixed pore distributions. Municipal water treatment contracts in Indonesia and Vietnam retain this grade for budget-constrained bulk adsorption deployments.
- Activated Alumina:High-surface-area transition alumina for moisture and fluoride removal. Desiccant manufacturers in Gujarat integrate this into compressed air drying systems.
- Silica Gel:Amorphous silicon dioxide with indicator dye options for visual saturation monitoring. Electronics packaging operations in South Korea specify this for humidity-controlled shipping environments.
Synthetic zeolite leads on scale; activated alumina leads on momentum in hydrogen purification applications.
Application:
Margin intensity tracks how tightly performance specifications bind to regulatory compliance deadlines.
- Catalysis:Zeolite acid sites enable hydrocarbon cracking and isomerization in fluidized catalytic cracker units. Chinese methanol-to-olefin complexes demand specialty grades with controlled mesoporosity to maximize ethylene yields.
- Gas Separation:Pressure swing adsorption systems exploit kinetic or equilibrium selectivity for hydrogen purification and nitrogen rejection. Australian LNG pretreatment facilities and Queensland hydrogen export corridors are expanding this application fastest.
- Drying Agent:Static and dynamic moisture scavenging for process streams and storage environments. API manufacturers around Hyderabad deploy 3A and 4A zeolites in moisture-controlled processing suites.
- Adsorption:Contaminant capture from liquid and gas phases including sulfur compounds and heavy metals. Refinery off-gas treatment units in Ningbo retrofit with high-capacity molecular sieve beds.
Catalysis leads on scale; gas separation leads on momentum.
End User:
Industry-specific certification requirements and replacement cycle timing reshape vendor selection criteria.
- Petrochemical:Integrated refineries and crackers require continuous catalytic regeneration systems. Dalian and Ningbo operators accelerate zeolite replacement ahead of MEE inspection windows.
- Pharmaceutical:API and formulation facilities demand GMP-compliant desiccant systems with documented batch traceability. Ahmedabad manufacturers specify bead configurations to minimize attrition dust in cleanroom environments.
- Chemical:Specialty and commodity chemical producers need solvent drying and purification media. Maharashtra chlor-alkali plants specify 4A zeolites for caustic soda dehydration.
- Water Treatment:Municipal and industrial potable and wastewater facilities deploy adsorption for contaminant removal. BIS certification mandates force extended testing protocols that delay replacement contract awards.
Petrochemical leads on scale; pharmaceutical leads on momentum.
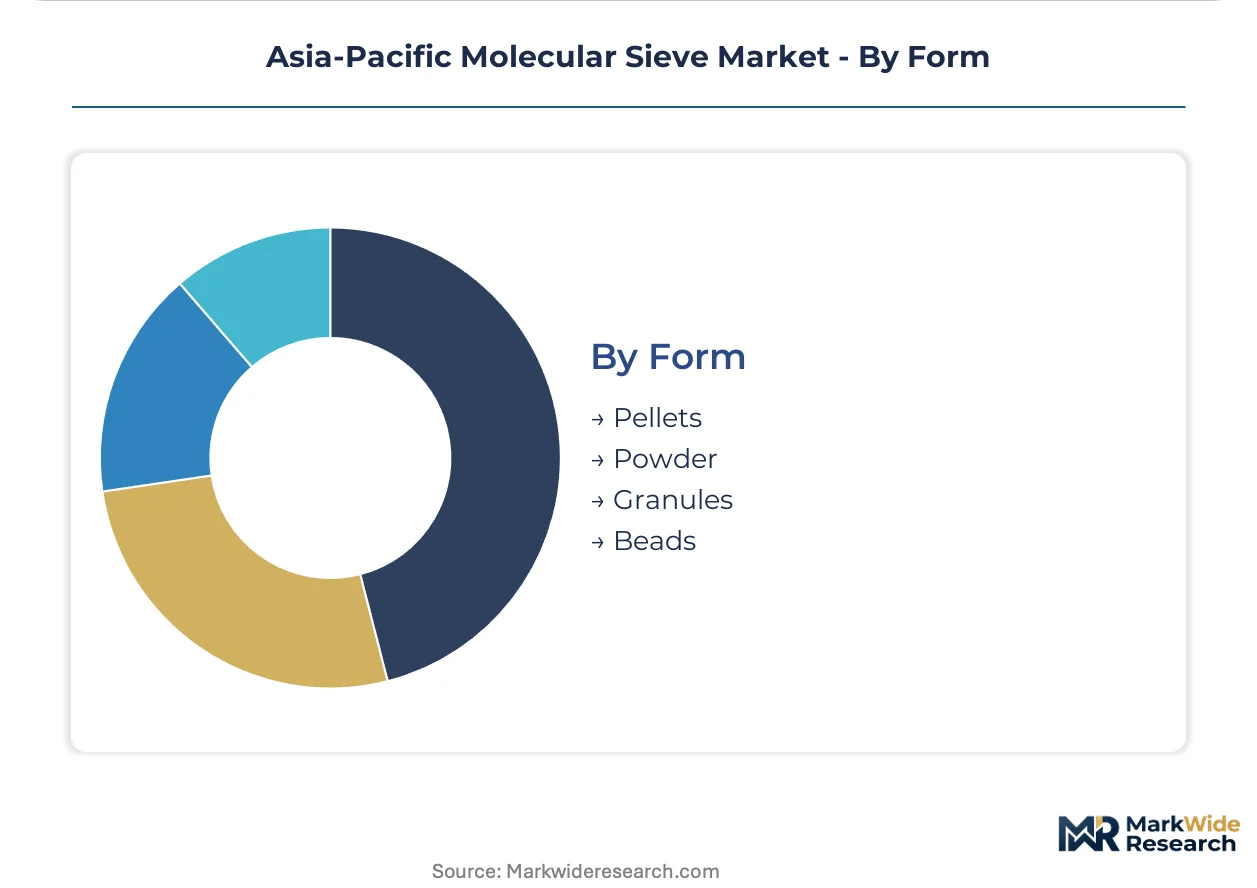
Form:
Mechanical integrity requirements and column hydrodynamics dictate physical configuration selection.
- Pellets:Extruded cylindrical shapes minimize pressure drop in packed columns. Bulk shipments dominate refinery catalytic cracking unit fills across Asia-Pacific.
- Beads:Spherical configurations maximize attrition resistance and flow uniformity. Pharmaceutical drying applications in Hyderabad and Ahmedabad specify this form for API protection.
- Powder:Fine particulate for slurry applications and specialty coating formulations. Shandong province's refinery maintenance cycles consume domestic powder formulations for catalyst reconstitution.
- Granules:Intermediate sizing for fixed-bed applications requiring moderate pressure drop. Water treatment facilities in Vietnam deploy this form for arsenic and fluoride removal.
Pellets lead on scale; beads lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered synthetic zeolite manufacturing for petroleum refining during the 1960s, establishing the technical foundation that now spans Asia-Pacific industrial corridors. The region's molecular sieve consumption clusters around refinery modernization cycles, hydrogen infrastructure buildouts, and pharmaceutical manufacturing expansion.
China
Shandong and Jiangsu refinery corridors dominate regional zeolite consumption as operators accelerate synthetic zeolite replacements ahead of planned maintenance windows. MEE volatile organic compound recovery mandates force catalytic cracking unit retrofits in Ningbo and Dalian. Shandong province's refinery maintenance cycles consume domestic powder formulations from captive suppliers.
Japan
Ultra-high-purity molecular sieve demand concentrates around METI-backed hydrogen economy infrastructure for Tokyo and Osaka industrial gas networks. Electronics gas purifiers require integrated alumina-to-zeolite supply chains anchored by domestic chemical conglomerates. Kanto region fuel cell feedstock conditioning systems specify precision-engineered adsorption media.
India
API manufacturers around Hyderabad and Ahmedabad build moisture-controlled processing environments specifying 3A and 4A zeolite desiccants for active pharmaceutical ingredient stability. BIS certification mandates for drinking water treatment adsorption systems force municipal suppliers through extended testing protocols. Maharashtra chlor-alkali plants deploy 4A zeolites for caustic soda dehydration.
Australia
Queensland and Western Australia hydrogen export corridors require large-scale pressure swing adsorption systems for hydrogen purification ahead of export to Japanese and Korean buyers. LNG pretreatment facilities expand molecular sieve deployment for mercury and moisture removal. New South Wales industrial gas networks upgrade feedstock conditioning infrastructure.
Vietnam
New regasification terminals in Thi Vai and Son My require pretreatment molecular sieves for mercury and moisture removal, opening greenfield specification battles. Municipal water treatment facilities deploy granule configurations for arsenic and fluoride removal. Cost-sensitive bulk adsorption contracts retain natural zeolite for budget-constrained deployments.
Asia-Pacific Molecular Sieve Market Competitive Environment
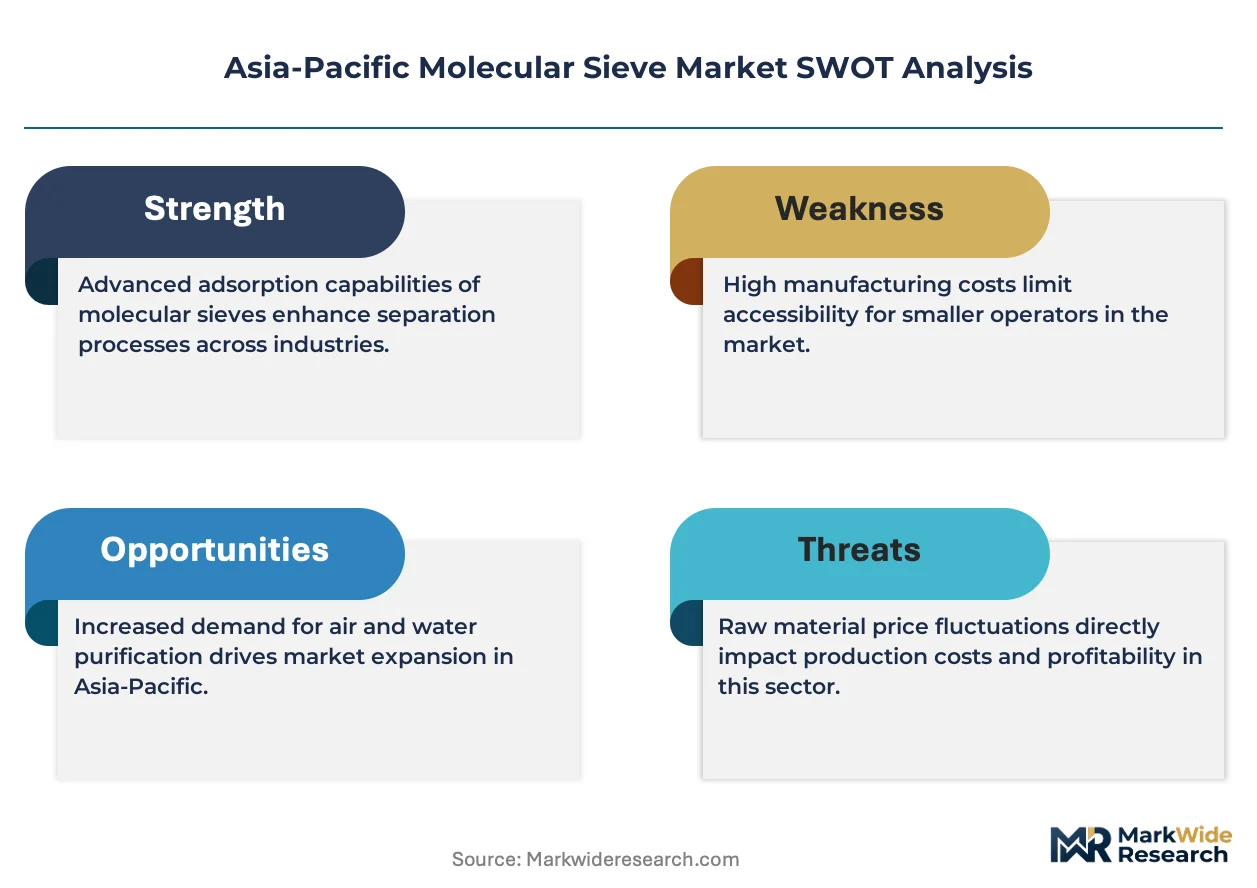
The competitive structure tilts toward integrated chemical conglomerates with captive zeolite synthesis capabilities. Japanese and Chinese suppliers anchor supply security through backward integration into specialized alumina feedstocks. Three archetypes dominate: integrated petrochemical-materials conglomerates with refinery-captive demand; specialty chemical houses serving pharmaceutical and electronics purity tiers; and regional powder formulators aligned with domestic maintenance cycles. Capacity expansion and modular desiccant kit standardization represent the dominant competitive moves as mid-scale operators consolidate procurement preferences.
Among Japan-based integrated producers, Tosoh Corporation occupies a position exemplifying alumina-to-zeolite manufacturing chain control for electronics gas purification applications. Swiss-headquartered Clariant AG and China-based JIUZHOU CHEMICALS represent contrasting archetypes—specialty catalysis grade tailoring versus domestic powder formulation dominance—each anchoring distinct procurement channels across refinery and industrial gas segments.
| Leading Market Players |
|---|
| Tosoh Corporation |
| Clariant |
| Arkema Group |
| Zeochem AG |
| BASF SE |
| Honeywell International Inc |
| W. R. Grace & Co.-Conn. |
| JIUZHOU CHEMICALS |
| Sorbead India |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and family-owned chemical conglomerates in Japan anchor supply discipline through captive alumina refining and long-term offtake contracts with Shandong and Jiangsu refineries. This ownership concentration insulates premium synthetic zeolite grades from commodity volatility while forcing mid-tier formulators into price competition against natural zeolite substitutes in Indonesian municipal water contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Asia-Pacific molecular sieve landscape. Premium tiers command certification-grade positioning for METI-backed hydrogen infrastructure and pharmaceutical GMP compliance, while economy tiers serve bulk water treatment in Vietnam and Indonesia. Price differentiation hinges on thermal stability benchmarks and crush strength documentation under MEE inspection protocols. Cost compression in standard-grade synthetic zeolites is intensifying because Shandong powder formulators expand capacity ahead of maintenance cycle peaks. Municipal water treatment buyers in Southeast Asia exhibit highest price sensitivity; Japanese electronics gas purifiers demonstrate lowest sensitivity due to purity-tier specifications.
Supply Chain Analysis
Freight cost differentials between alumina feedstock origins and zeolite synthesis hubs dictate regional competitive boundaries. Supply concentrates in eastern China, western Japan, and Gujarat processing corridors, with hydrothermal synthesis capacity tethered to specialized bauxite refining infrastructure. Raw material dependencies span high-purity sodium aluminate, colloidal silica, and templating agents for mesoporous grades. Single-source vulnerability runs through Japanese alumina-to-zeolite integrated producers serving Tokyo-Osaka industrial gas networks. Distribution runs through Singapore and Shanghai trading hubs for spot desiccant purchases, while direct mill relationships dominate Indian pharmaceutical corridor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific molecular sieve market functions as a geographic-arbitrage play where MEE emission enforcement in China compresses upgrade cycles faster than BIS certification timelines in India, creating divergent replacement demand curves across the region.
For Market Incumbents: Extend backward integration into specialized alumina feedstocks to defend margin position against emerging Chinese powder formulators. Captive supply of high-purity sodium aluminate insulates Tosoh Corporation and Clariant from input volatility while accelerating Shandong refinery maintenance cycle capture. Invest in modular desiccant kit standardization to lock mid-scale petrochemical operators into vendor-managed replenishment contracts before third-party logistics providers unbundle technical service from bulk supply. For New Entrants and Emerging Players: Capture greenfield specification battles at Vietnam's Thi Vai and Son My LNG regasification terminals where incumbent relationships remain unsettled. Australia's Queensland hydrogen export corridors offer the most penetrable geography given scale requirements that exceed existing supplier capacity commitments. Lead with pressure swing adsorption system integration expertise rather than commodity desiccant supply to differentiate from established trading house distributors. For Investors and Strategic Acquirers: Integrated petrochemical-materials conglomerates with refinery-captive demand represent the most active acquirer category in this space, seeking synthetic zeolite synthesis capabilities to secure catalytic cracking unit supply chains. The acquisition target archetype centers on regional powder formulators with established Shandong maintenance cycle relationships and crystallization chemistry talent pools. Watch MEE inspection window acceleration as the signal indicating upgrade cycle compression that would justify capacity expansion premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstocks | Captive sodium aluminate supply secures synthetic zeolite margins against Shandong input volatility. |
| Modular Desiccant Kit Standardization | Pre-bundled pellet-and-bead configurations reduce inventory complexity for Ningbo refinery operators. |
| Hydrogen Purification System Integration | Pressure swing adsorption expertise opens Queensland export corridor specifications ahead of incumbent response. |
| Pharmaceutical GMP Certification Investment | Documented batch traceability unlocks Hyderabad API manufacturer moisture-controlled processing contracts. |
| Long-term Supply Agreement with Refinery Operators | MEE compliance-driven replacement cycles in Dalian favor contracted volume over spot procurement. |
Study Parameters
Direct dialogue with plant managers at Shandong and Jiangsu refineries, procurement leads at Indian API manufacturers, distribution channel partners in Singapore trading hubs, and technical R&D directors at Japanese electronics gas purifiers grounded qualitative assessment. Secondary validation drew from customs trade data, MEE emission standard filings, BIS certification registries, and SEC disclosures from listed chemical conglomerates. Bottom-up demand modeling across catalysis, gas separation, and drying agent applications triangulated against top-down refinery capacity and pharmaceutical production forecasts.
Segment-level value outputs across synthetic zeolite, natural zeolite, activated alumina, and silica gel categories were projected over the analysis window using application-specific demand elasticities. The modeling framework incorporated petrochemical refinery throughput, hydrogen infrastructure deployment timelines, and pharmaceutical manufacturing expansion curves as primary volume drivers. CAGRs were derived from regression analysis of historical replacement cycle data against regulatory enforcement intensity metrics.
MEE inspection schedule shifts, alumina feedstock supply disruptions, and BIS certification timeline extensions are the dominant revision risks that could compress or extend forecast accuracy. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market