
 Decahydronaphthalene (Decalin) Market | 2026-2036
Decahydronaphthalene (Decalin) Market Size, Share, and Industry Trends Forecast 2026-2036
Decahydronaphthalene (Decalin) Market Outlook
Paint and coatings formulation is pivoting toward high-purity decalin solvents as VOC regulations tighten across industrial hubs. BASF leverages its integrated aromatic chemistry platform to sustain European supply continuity for technical solvent grades. Mitsubishi Gas Chemical anchors Asia-Pacific availability through naphthalene derivative specialization and captive hydrogenation capacity. Evonik Industries differentiates via precision distillation protocols that meet pharmaceutical-grade specifications.
Decahydronaphthalene is a bicyclic saturated hydrocarbon comprising cis- and trans-isomers, produced through catalytic hydrogenation of naphthalene under elevated pressure and temperature, functioning primarily as a high-boiling aprotic solvent and hydrogen transfer medium. Solvent applications dominate current volume flows, while chemical intermediate usage captures expanding margin pools from pharmaceutical and agrochemical synthesis chains. The liquid form category leads distribution logistics, though crystal-grade specifications command premium positioning in electronics cleaning and precision coating segments.
EPA oversight governs VOC content thresholds in US industrial coatings, while REACH registration mandates full toxicological dossiers for European solvent imports, effectively filtering non-compliant suppliers from Western procurement channels. China's GB standards and MEE enforcement increasingly align with OECD chemical safety protocols, raising compliance costs for domestic producers serving export markets. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation requirements and reposition supply chain certifications ahead of enforcement phase-ins.
Market Dynamics
REACH registration dossiers and EPA VOC thresholds are filtering solvent suppliers from Western procurement channels, redirecting volume toward certified hydrogenation facilities with full toxicological documentation.
Growth Catalysts
- Pharmaceutical synthesis expansion:Agrochemical and active pharmaceutical ingredient manufacturers in India and China are scaling decalin purchases as hydrogen transfer media in catalytic reduction steps.
- REACH compliance premiums:Full registration under ECHA mandates creates pricing power for European producers with completed substance dossiers and safety data sheets.
- Electronics cleaning grade demand:Semiconductor fabs in Taiwan and South Korea specify crystal-grade decalin for precision wafer cleaning, absorbing capacity from technical solvent pools.
Market Restraints
- Naphthalene feedstock volatility:Coal tar distillation yields fluctuate with steel production cycles, compressing margins for non-integrated hydrogenation operators.
- Isomer separation energy intensity:Cryogenic fractionation of cis- and trans-decalin consumes disproportionate utilities, limiting geographic expansion of high-purity production.
- Bio-based solvent substitution:Terpene and ester alternatives from renewable feedstocks capture formulation share in decorative coatings and consumer applications.
Strategic Opportunities
- Indian chemical intermediate manufacturing:PLI scheme incentives for specialty chemicals are attracting decalin consumption for dye and pigment precursor synthesis.
- Carbon capture solvent applications:Physical absorption processes using decalin-based formulations are piloting at post-combustion capture facilities in Germany and the Netherlands.
- Direct-to-fab distribution:Bypassing traditional chemical distributors, producers are establishing dedicated supply lines to electronics clusters in Hsinchu and Pyeongtaek.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA good manufacturing practice audits extend qualification periods for new hydrogenation train installations.
- Hydrogen supply security:Electrolyzer project delays and natural gas price spikes disrupt captive hydrogen availability at naphthalene hydrogenation sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decahydronaphthalene (Decalin) Market |
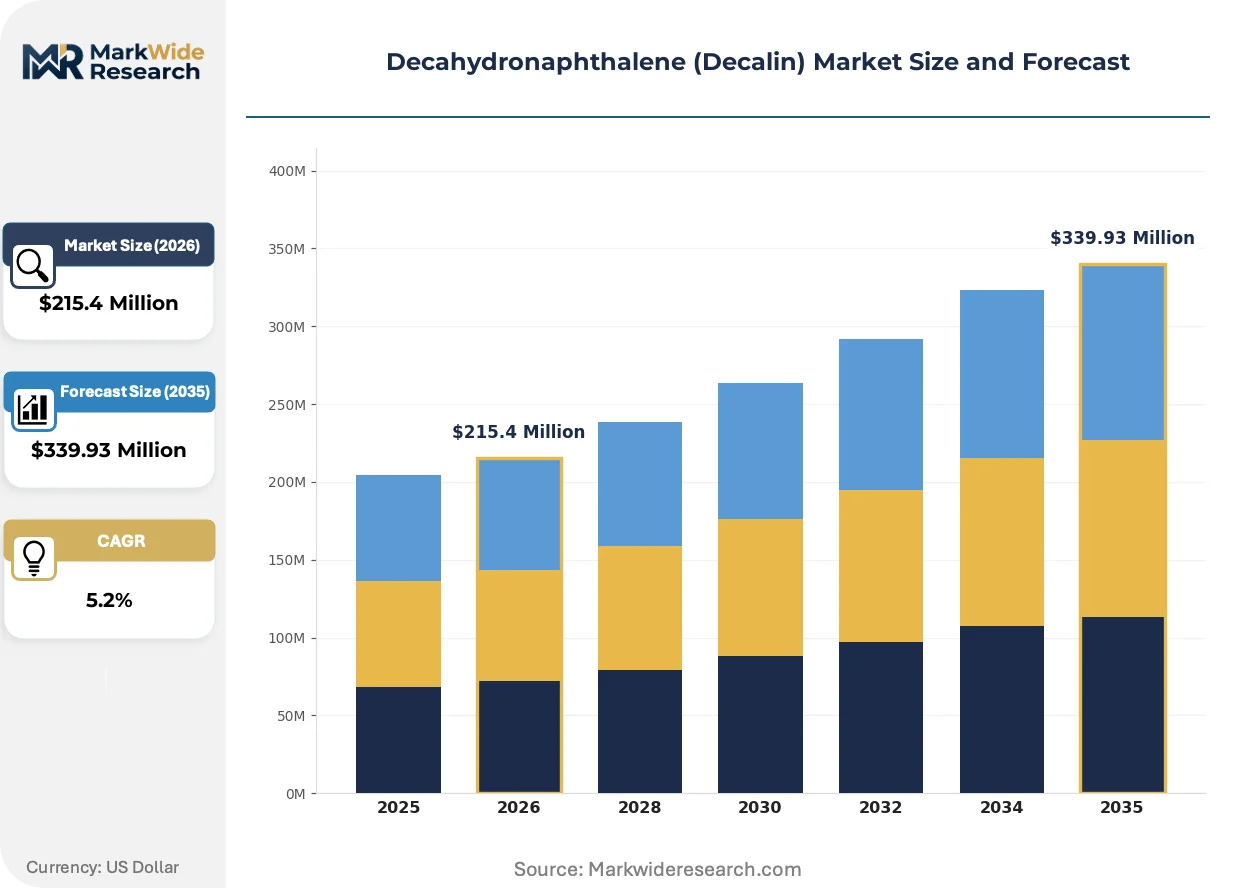
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $339.93 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvent, Chemical Intermediate, Fuel Additive, Carrier Fluid End Use Industry: Pharmaceutical, Automotive, Paints & Coatings, Adhesives Form: Liquid, Solid, Paste, Crystal Distribution Channel: Direct Sales, Online Retail, Distributors, Chemical Brokers |
| Companies Covered | Jiangsu Zhongneng Chemical Technology, Honeywell Specialty Chemicals, Evonik Industries, Advanced Aromatics, Acros Organics, BASF, Mitsubishi Gas Chemical, Puyang Lianzhong Xingye Chemical, Monument Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decahydronaphthalene (Decalin) Market Strategic Shifts
Membrane-based isomer separation and continuous hydrogenation reactor designs are displacing batch processing economics, while regulatory data requirements deepen documentation burdens across supply chains.
Advanced pervaporation membranes for cis-trans isomer splitting are absorbing capital allocation from cryogenic distillation retrofits. Specialty chemical producers in Japan and Germany are piloting these units to reduce energy intensity by forty percent versus conventional fractionation. The technology is absorbing margin pressure from utility cost inflation while enabling location flexibility for new production assets.
EPA New Chemicals Program notifications and REACH substance evaluation workplans are tightening impurity disclosure requirements for solvent imports. Full compositional characterization now precedes market access, extending qualification timelines by six to twelve months for non-European suppliers. Electronics and pharmaceutical end-uses bear the heaviest documentation burden, forcing procurement teams to consolidate supplier panels around pre-certified sources.
Specification-driven contracting is compressing spot market liquidity as buyers lock multi-year supply agreements with embedded quality audits. Coatings formulators in automotive OEM supply chains now require certificate-of-analysis continuity across every drum lot, displacing traditional distributor-stocked inventory models. This pattern is most pronounced in Germany and the US Midwest, where just-in-time manufacturing tolerates minimal solvent variability.
Decahydronaphthalene (Decalin) Market Segmentation
Decalin specification tiers directly determine qualification pathways across regulated end-uses, with pharmaceutical and electronics grades commanding fundamentally different supply chain configurations than technical solvent volumes.
Application:
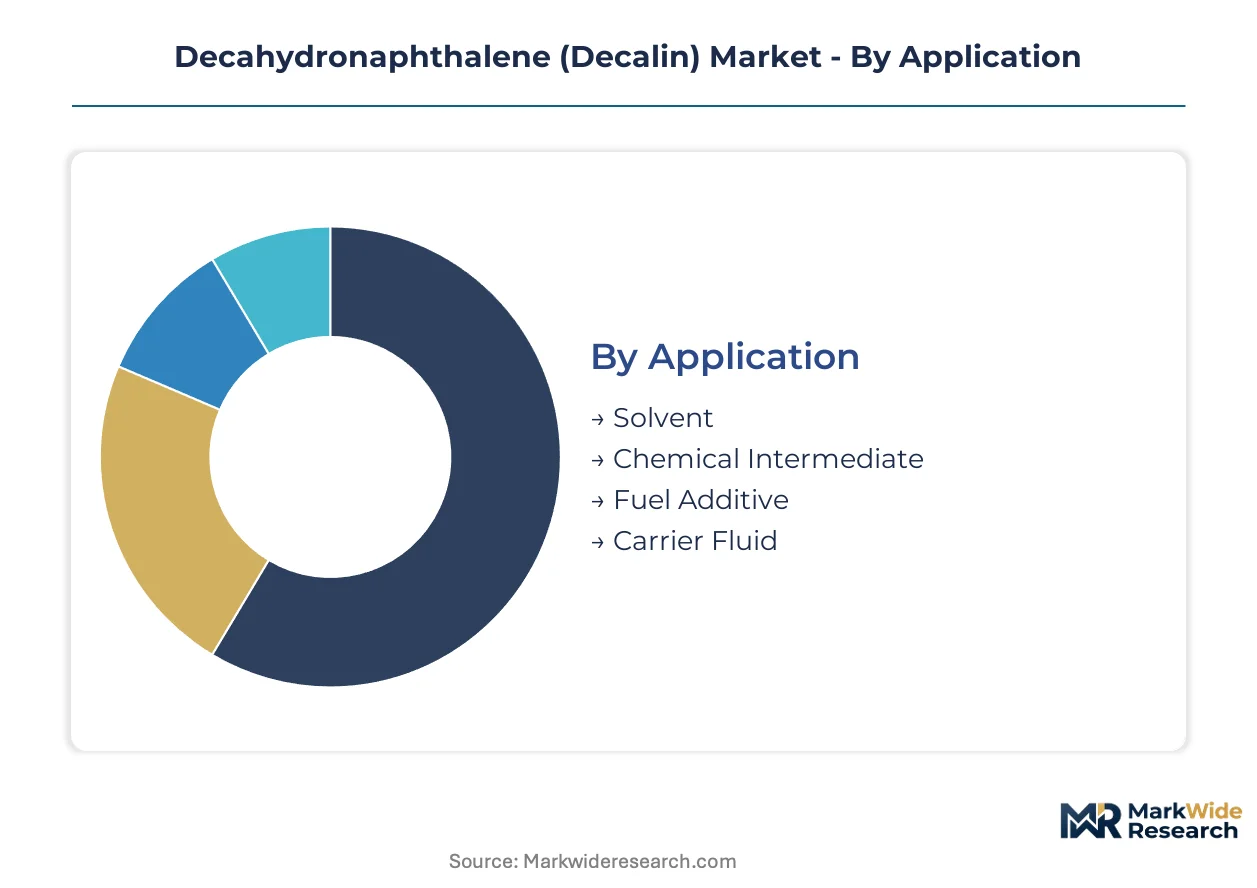
Replacement cycles vary sharply across application tiers, with solvent formulations refreshing every 3-5 years while chemical intermediate qualifications extend over decade-long pharmaceutical approval timelines.
- Solvent:High-boiling aprotic solvent for industrial coatings and cleaning formulations, absorbing the majority of decalin volume flows. Paint manufacturers in Germany and the US Midwest specify technical grades with controlled aromatic content under EPA VOC thresholds and REACH registration requirements.
- Chemical Intermediate:Hydrogen transfer medium in catalytic reduction steps for active pharmaceutical ingredient synthesis. Agrochemical and dye precursor manufacturers in India leverage PLI scheme incentives to scale consumption of certified grades with full ECHA dossier documentation.
- Fuel Additive:Cetane improver and combustion modifier for diesel formulations, primarily serving specialized military and marine applications with military specification compliance.
- Carrier Fluid:Inert transport medium for reactive chemical systems, finding niche adoption in polymerization processes and specialty chemical manufacturing.
Solvent sits at the top of the volume ranking, with chemical intermediate climbing the fastest.
End Use Industry:
Customer procurement sophistication stratifies sharply across end-use tiers, with pharmaceutical buyers demanding certificate-of-analysis continuity while automotive formulators prioritize volume scale and logistics reliability.
- Pharmaceutical:FDA and EMA good manufacturing practice audits govern hydrogenation train qualifications, extending certification timelines for new suppliers. Crystal-grade specifications for precision synthesis command premium positioning over technical solvent pools.
- Paints & Coatings:VOC regulation compliance drives reformulation toward high-purity decalin in industrial hubs. Automotive OEM supply chains in Germany and the US now require embedded quality audits across every drum lot.
- Automotive:Fuel system cleaning formulations and brake fluid applications consume technical grades, with specification requirements less stringent than pharmaceutical or electronics tiers.
- Adhesives:Solvent-borne adhesive formulations for industrial assembly utilize mid-tier technical grades, facing substitution pressure from bio-based terpene alternatives in consumer-facing applications.
Paints & coatings holds the largest installed base, though pharmaceutical is expanding most quickly.
Form:
Physical state determines logistics infrastructure requirements, with liquid grades flowing through standard chemical distribution while solid and crystal forms demand temperature-controlled handling and specialized packaging.
- Liquid:Dominates distribution economics through standard bulk tanker and drum logistics. Technical solvent specifications in liquid form serve coatings and cleaning applications across industrial manufacturing clusters.
- Crystal:Ultra-high purity solid phase for semiconductor wafer cleaning and precision electronics fabrication. Taiwan and South Korea fabs specify crystal-grade material with sub-ppm metallic impurity thresholds.
- Solid:Compressed or flaked material for specialized chemical processing and laboratory applications, requiring controlled atmosphere storage to prevent oxidative degradation.
- Paste:Thickened formulation for specific adhesive and sealant compounding, representing a minor volume fraction with highly specialized handling requirements.
Liquid leads by volume magnitude, while crystal is gaining share fastest.
Distribution Channel:
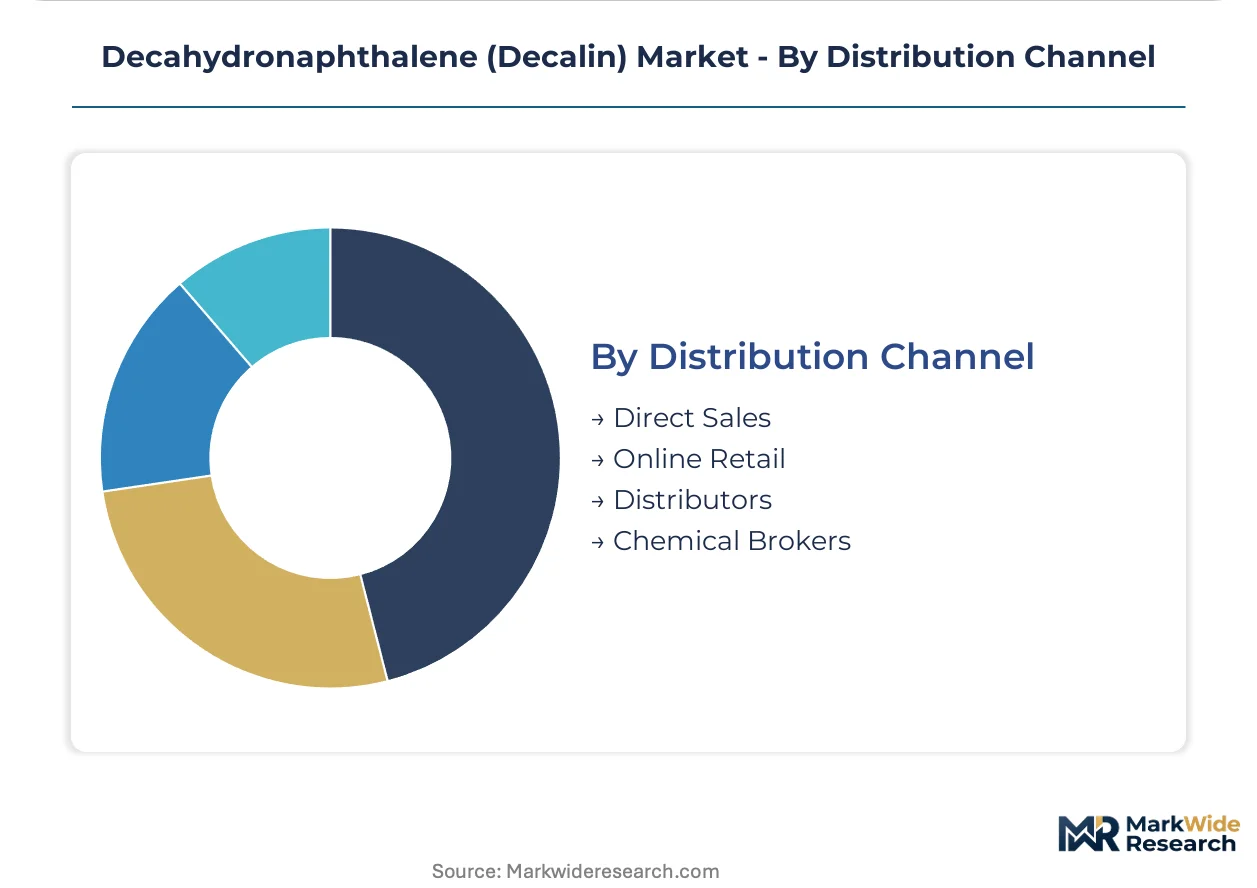
Channel selection reflects buyer scale and specification intensity, with large-volume pharmaceutical and electronics consumers bypassing traditional distribution to secure supply continuity.
- Direct Sales:Producer-to-fab supply lines for electronics clusters in Hsinchu and Pyeongtaek, and pharmaceutical hydrogenation facilities in India. Bypasses distributor margins and enables embedded quality audit protocols.
- Distributors:Traditional chemical distribution networks serving mid-scale coatings and adhesives formulators, though spot market liquidity is compressing as buyers lock multi-year agreements.
- Chemical Brokers:Facilitate spot market transactions and cross-border arbitrage for non-integrated buyers, operating with reduced transparency on origin and certification status.
- Online Retail:Laboratory-scale and research quantity fulfillment, serving academic and small-scale industrial R&D with expedited delivery and credit card purchasing.
Direct sales commands the highest value flows, with distributor volumes still dominant in absolute tonnage terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting decalin production toward jurisdictions with lower compliance documentation burdens, while Western buyers absorb premium pricing for REACH-certified and EPA-registered grades to maintain formulation continuity.
United States
Coatings formulators in Michigan and Ohio industrial corridors drive technical-grade consumption for automotive OEM supply chains. EPA New Chemicals Program notifications enforce full impurity disclosure for solvent imports, extending qualification timelines for non-domestic suppliers. Houston-Gulf Coast petrochemical clusters host hydrogenation capacity serving both domestic coatings demand and export pharmaceutical intermediate markets.
Germany
Pharmaceutical-grade specifications command premium positioning from BASF's Ludwigshafen integrated aromatic chemistry platform. REACH registration dossiers under ECHA mandate create pricing power for producers with completed substance evaluations and safety data sheets. The Ruhr industrial region concentrates technical solvent distribution for coatings manufacturers reformulating under EU VOC directives.
China
Jiangsu and Shandong provinces anchor naphthalene hydrogenation capacity serving expanding dye and agrochemical intermediate synthesis. GB standards alignment with OECD chemical safety protocols raises compliance costs for domestic producers targeting Western export markets. Yangtze River Delta electronics clusters absorb crystal-grade volumes for semiconductor wafer cleaning applications.
India
PLI scheme incentives for specialty chemicals attract decalin consumption for active pharmaceutical ingredient manufacturing in Gujarat and Maharashtra. CDSCO good manufacturing practice audits govern hydrogenation train qualifications, extending certification timelines for new market entrants. Mumbai-Pune chemical corridor concentrates demand from agrochemical and dye precursor synthesis operations.
South Korea
Semiconductor fabs in Pyeongtaek and Hsinchu-linked supply chains specify crystal-grade material with sub-ppm metallic impurity thresholds. MFDS pharmaceutical oversight creates parallel compliance tracks for hydrogenation facilities serving domestic and export markets. Daegu-Gyeongbuk industrial region hosts precision distillation capacity for electronics-grade specification fulfillment.
Decahydronaphthalene (Decalin) Market Competitive Environment
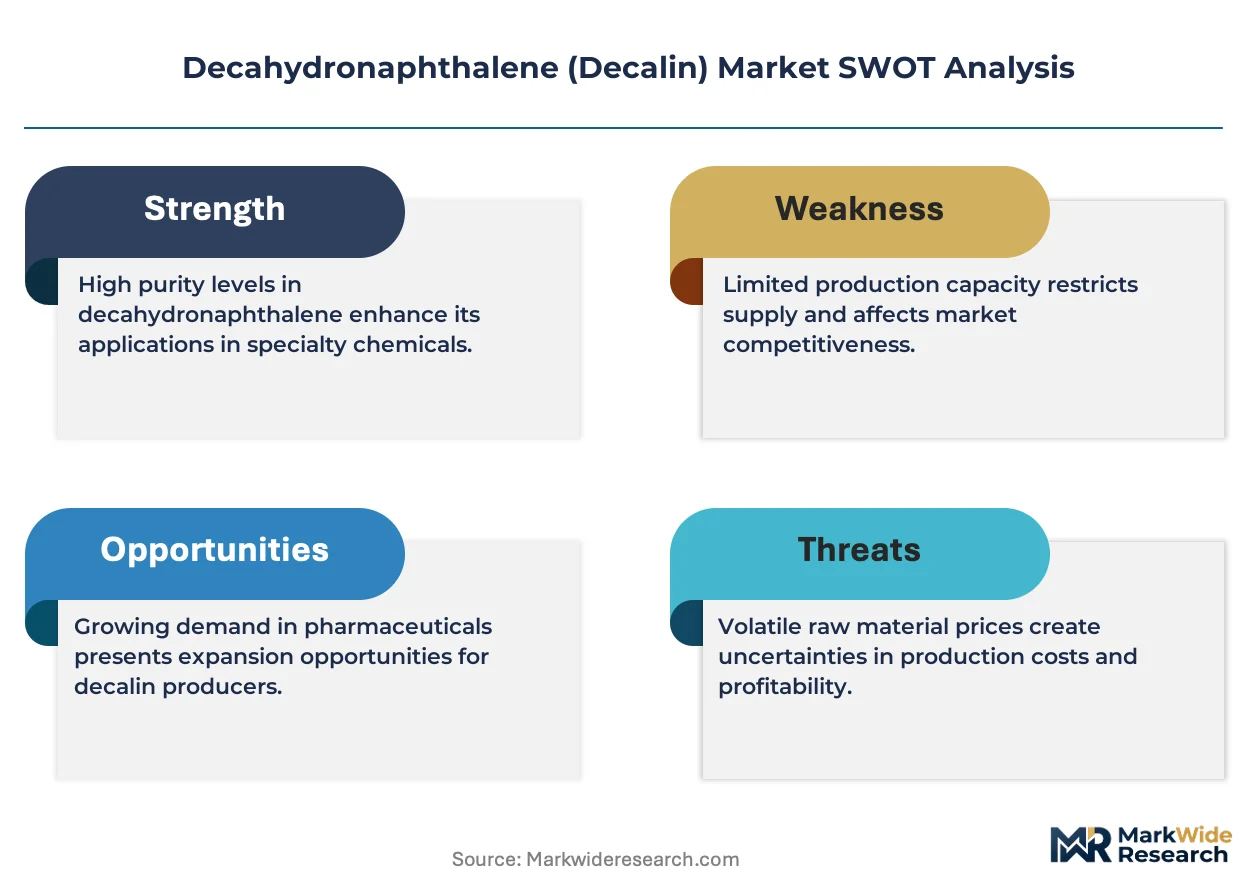
Branded specialists and contract manufacturers split share differently across segments, with integrated aromatic chemistry platforms commanding pharmaceutical-grade premiums while regional hydrogenation operators capture technical solvent volume. The vendor base organizes around three strategic archetypes: naphthalene-integrated producers with captive feedstock security, precision distillation specialists serving electronics and pharmaceutical tiers, and regional chemical processors leveraging coal tar derivative access. Competitive positioning hardens through backward integration into naphthalene supply and multi-year specification-driven contracting with embedded quality audit protocols.
Among integrated chemistry platforms, BASF and Mitsubishi Gas Chemical exemplify the naphthalene-hydrogenation archetype with aromatic derivative specialization, while Evonik Industries occupies a position within the precision distillation tier serving pharmaceutical-grade specifications. Chinese producers including Jiangsu Zhongneng Chemical Technology and Puyang Lianzhong Xingye Chemical represent regional hydrogenation capacity serving technical solvent and intermediate synthesis demand. These groupings illustrate how geographic feedstock access and certification depth stratify competitive positioning across specification tiers.
| Leading Market Players |
|---|
| Jiangsu Zhongneng Chemical Technology |
| Honeywell Specialty Chemicals |
| Evonik Industries |
| Advanced Aromatics |
| Acros Organics |
| BASF |
| Mitsubishi Gas Chemical |
| Puyang Lianzhong Xingye Chemical |
| Monument Chemicals |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade certification requirements from FDA and EMA are forcing hydrogenation operators to absorb extended audit timelines and documentation costs, compressing margins on technical solvent tiers while enabling premium capture for certified producers with completed dossiers. This specification-driven procurement consolidation redirects volume toward pre-qualified suppliers and hardens price stratification across grade tiers.
Pricing Analysis
Distributor margin compression now defines the channel economics, with traditional chemical distributors losing share to direct producer-to-fab supply lines in Hsinchu and Pyeongtaek. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical solvent levels separates crystal-grade premiums from standard industrial volumes. Cost compression in technical grades is intensifying because bio-based terpene alternatives capture decorative coatings share. Small-scale coatings formulators exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for sub-ppm metallic impurity thresholds.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for specialty chemicals are reshaping sourcing patterns, redirecting naphthalene feedstock procurement toward local coal tar derivative operators. Supply concentrates in China, Germany, and India, with Jiangsu and Shandong provinces anchoring hydrogenation capacity. Production draws from coal tar distillation yields, catalytic hydrogenation trains, and cryogenic fractionation units. Single-source vulnerability runs through naphthalene feedstock exposure to steel production cycles. Distribution runs through direct sales for pharmaceutical and electronics tiers, with traditional distributors serving mid-scale coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decahydronaphthalene functions as a stable compounder, with REACH and EPA regulatory tightening creating durable pricing power for certified producers while filtering marginal suppliers from Western procurement channels.
For Market Incumbents: To counter bio-based solvent substitution in decorative coatings, BASF and Mitsubishi Gas Chemical should deepen backward integration into naphthalene supply and lock multi-year specification-driven contracts with embedded quality audit protocols. Captive hydrogen production and membrane-based isomer separation investments defend margin position against utility cost inflation. For New Entrants and Emerging Players: Direct-to-fab digital channels offer the most penetrable route, bypassing traditional distributor networks to serve electronics clusters in Taiwan and South Korea with crystal-grade specifications. Target carbon capture solvent applications in Germany and the Netherlands as pilot-scale entry points, leveraging physical absorption process partnerships with post-combustion capture facilities. For Investors and Strategic Acquirers: Asymmetric upside sits with precision distillation specialists serving pharmaceutical-grade specifications, where FDA and EMA audit completion creates durable moats. The five-to-ten-year viability window favors producers with REACH dossier completion and naphthalene-integrated feedstock security. Watch membrane-based isomer separation technology maturation as the inflection signal for energy cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthalene Supply | Captive feedstock security insulates margins from coal tar distillation yield volatility. |
| Membrane-Based Isomer Separation Deployment | Pervaporation technology cuts energy intensity forty percent versus cryogenic fractionation. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA GMP audit completion unlocks premium pricing in API synthesis chains. |
| Direct-to-Fab Distribution Establishment | Bypassing distributor margins secures supply continuity with Hsinchu and Pyeongtaek electronics clusters. |
| Carbon Capture Solvent Formulation Partnership | Physical absorption pilot programs in Germany and Netherlands open adjacent demand pools. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrogenation plant managers, pharmaceutical procurement leads, coatings formulators, and distribution channel partners with secondary validation from customs trade data, Cefic solvent market reports, SEC 10-K filings of listed chemical producers, and ECHA registration dossiers. Bottom-up volume modeling across grade tiers and end-use segments triangulated against top-down market sizing from trade flow analysis.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical synthesis, electronics cleaning, and coatings solvent applications, with grade tier, end-use industry, and regional production hub as core segmentation dimensions. CAGRs were derived from historical trajectory analysis and forward-looking regulatory enforcement timelines, incorporating naphthalene feedstock cost curves and hydrogen supply availability as industry-specific forecast inputs across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for membrane-based isomer separation would alter the outlook if pervaporation unit deployment accelerates beyond pilot-scale demonstration. Forecasts reflect assumptions about REACH enforcement consistency, EPA VOC threshold maintenance, and PLI scheme continuity in India. A small set of triggers—hydrogen supply disruptions, bio-based solvent cost parity breakthroughs, and semiconductor fab demand shocks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Dynamite Market