
 China Bariatric Surgery Market | 2026-2036
China Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
China Bariatric Surgery Market Outlook
Private hospital chains and municipal medical centers is unwinding the historical dominance of top-tier academic hospitals in bariatric procedure volume. Olympus Corporation leverages its integrated endoscopy platform to anchor service contracts across eastern China surgical suites. Reach Surgical competes on cost-engineered stapling systems tailored to provincial reimbursement tiers. Medtronic PLC sustains robotic-assisted training ecosystems that lock in hospital loyalty beyond device sales.
China bariatric surgery encompasses restrictive and malabsorptive procedures performed to treat morbid obesity and related metabolic disorders, typically involving gastric resection, intestinal bypass, or implanted restriction devices requiring laparoscopic or robotic instrumentation with precision vessel sealing. The primary purpose is durable weight reduction with remission of type 2 diabetes and cardiovascular risk profiles. Sleeve gastrectomy commands the dominant procedure share due to lower complication rates and shorter operative time versus gastric bypass, while robotic-assisted technology captures the fastest expansion as capital subsidies flow to prefecture-level hospitals. Laparoscopic platforms retain the broadest installed base but face margin compression from domestic manufacturers.
NMPA medical device registration and the National Healthcare Security Administration reimbursement catalog jointly determine which surgical technologies achieve commercial scale in Chinese hospitals. BIS technical standards for electrosurgical instruments and the CEA medical pricing framework shape procurement specifications and hospital budget allocations. Stakeholders must monitor how the NMPA's accelerated review pathway for innovative devices interacts with provincial centralized procurement to decide whether premium robotic platforms or cost-optimized laparoscopic systems offer sustainable returns.
Market Dynamics
Robotic-assisted surgical platforms are fragmenting the historical dominance of conventional laparoscopy in China's tier-three hospitals, as provincial governments channel equipment subsidies toward precision metabolic procedures while NMPA accelerates Class III device registrations.
Growth Catalysts
- NMPA Accelerated Review Pathway:Streamlined approvals for innovative surgical devices reduce time-to-market for next-generation stapling and energy platforms, expanding hospital procurement options.
- Provincial Centralized Procurement:Volume-based tendering mechanisms in Jiangsu and Zhejiang provinces drive standardization of laparoscopic instrument specifications across municipal medical centers.
- Metabolic Surgery Program Expansion:Tier-three public hospitals in the Yangtze River Delta cluster are establishing dedicated bariatric units to capture rising patient referrals from primary care networks.
Market Restraints
- Reimbursement Tier Compression:National Healthcare Security Administration catalog adjustments constrain procedure pricing differentials between robotic and laparoscopic modalities.
- Capital Equipment Intensity:Da Vinci system acquisition costs and annual service contracts strain prefecture-level hospital budgets outside Shanghai and Beijing municipal networks.
- Domestic Stapler Supply Concentration:Jiangsu and Zhejiang manufacturing clusters control cost-engineered disposable component output, creating procurement dependency for mid-tier hospitals.
Strategic Opportunities
- Central China Penetration:Hubei and Hunan provinces exhibit surgical volume gaps relative to coastal demand density, offering first-mover positioning for equipment distributors.
- Integrated Training Ecosystems:Robotic platform vendors can lock hospital loyalty through surgeon certification programs that extend beyond device sales into recurring service revenue.
- Dual Carbon Procurement Incentives:SAMR green procurement guidelines favor energy-efficient electrosurgical generators, creating preference shifts in hospital capital planning.
Industry Challenges
- Surgeon Certification Bottlenecks:Robotic-assisted metabolic surgery requires specialized credentialing pathways that lag behind equipment installation timelines in emerging prefecture markets.
- Legacy Laparoscopic Inventory Stranded:Hospitals with recent conventional platform investments face write-down pressure when transitioning to robotic workflows.
- Device-Hospital Data Interoperability:Surgical robotics generate procedure data formats that conflict with existing hospital information system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Bariatric Surgery Market |
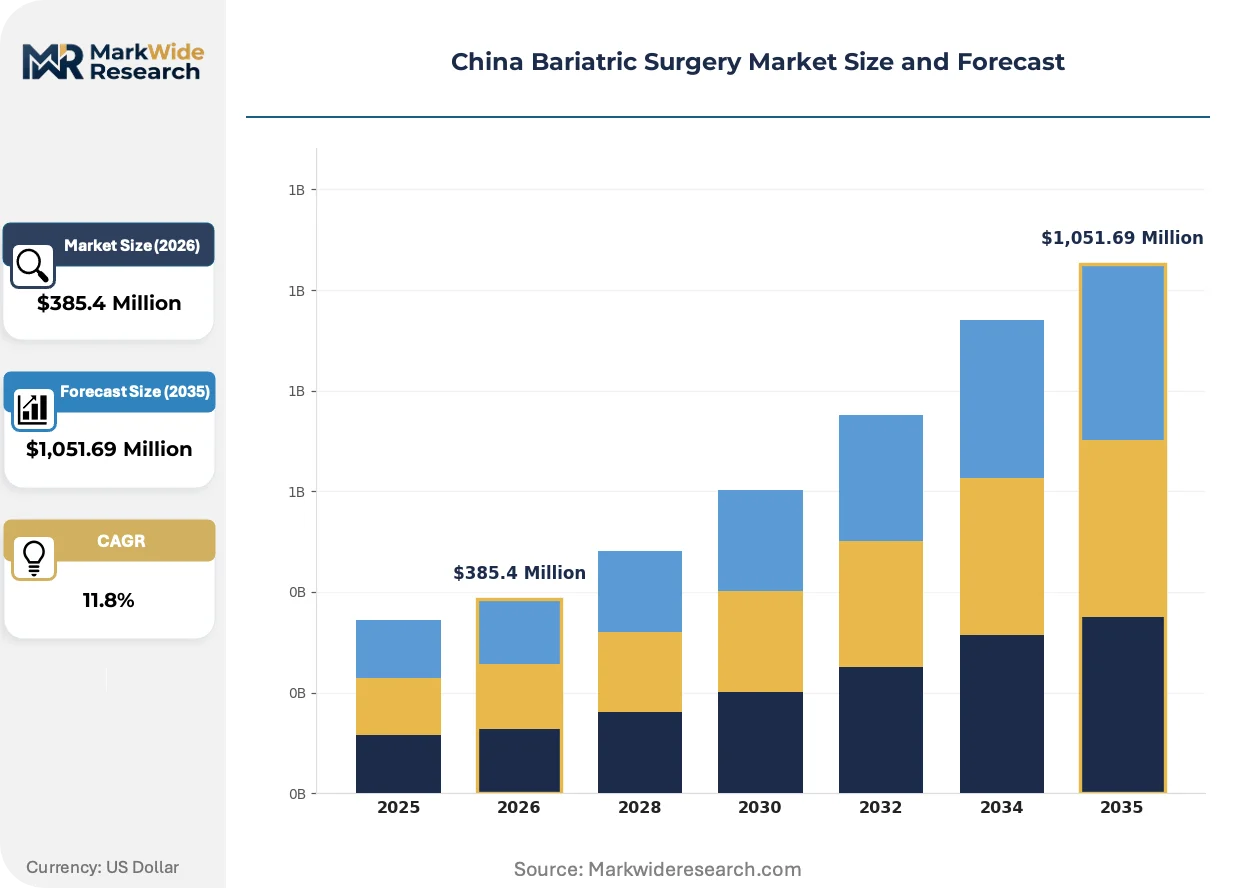
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Technology: Laparoscopic, Robotic-assisted, Endoscopic, Open Surgery Patient Demographics: Adults, Adolescents, Seniors, Obese Patients |
| Companies Covered | Olympus Corporation, Reach Surgical, ReShape Lifesciences Inc, Boston Scientific Corporation, Medtronic PLC, Cousin Biotech, Changzhou Haiers Medical Devices Co Ltd, Precision (Changzhou) Medical Instruments Co Ltd, TransEnterix Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Bariatric Surgery Market Strategic Shifts
Three interconnected developments are compressing traditional equipment procurement cycles while elevating service-contract value capture above standalone device margins.
Single-port robotic platforms are fragmenting the multi-port standard that dominated early Chinese bariatric adoption. Shanghai municipal hospitals and their Jiangsu satellite networks are piloting these systems for sleeve gastrectomy procedures, attracted by reduced incisional complications and faster patient throughput. The technology is fragmenting competitive positioning among international vendors, as domestic manufacturers accelerate comparable platform development.
NMPA's 2023 revised Class III medical device review guidelines are compressing registration timelines for electrosurgical instruments with novel vessel-sealing algorithms. This regulatory recalibration benefits stapling system innovators seeking to differentiate through energy-delivery precision rather than mechanical design alone. Jiangsu-based manufacturers are responding with accelerated clinical trial investments to secure priority review status.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, creating standalone technical support tenders. Municipal medical centers in Zhejiang province are leading this disintermediation, separating multi-year maintenance agreements from initial robotic platform purchases. The shift compresses vendor margins on hardware while elevating recurring revenue competition among service providers.
China Bariatric Surgery Market Segmentation
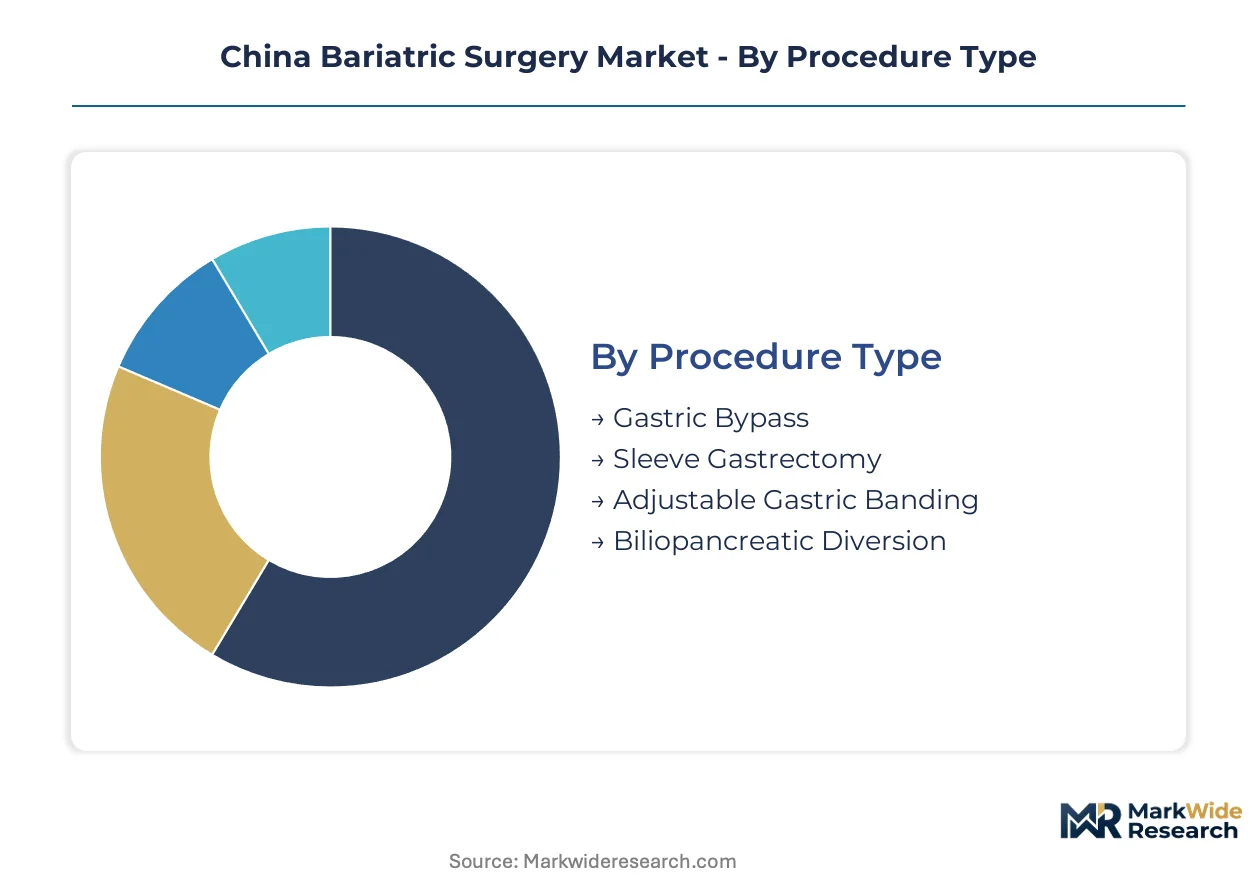
China's bariatric surgery market segments along procedure methodology, care delivery setting, surgical technology, and patient population. NMPA device classification tiers and provincial reimbursement catalogs create divergent commercial pathways across each dimension. Procurement committees weight capital intensity against patient throughput when allocating budget across segments.
Procedure Type:
NMPA Class III registration requirements vary by anatomical modification complexity, creating regulatory differentiation that shapes hospital adoption timelines.
- Sleeve Gastrectomy:Partial gastric resection along the greater curvature reduces stomach volume while preserving pyloric function. Demand concentrates in Shanghai municipal hospitals and Jiangsu satellite networks where NMPA has streamlined stapler system approvals for this lower-complication profile.
- Gastric Bypass:Roux-en-Y reconstruction creates a small gastric pouch with jejunal bypass, delivering superior diabetes remission rates. Yangtze River Delta academic medical centers dominate volume as the procedure requires specialized metabolic surgery credentialing that concentrates in tier-three public hospitals.
- Adjustable Gastric Banding:Silicone band placement with subcutaneous port adjustment offers reversibility but declining NMPA registration interest as long-term complication rates reshape hospital preference.
- Biliopancreatic Diversion:Malabsorptive intestinal bypass reserved for super-obese patients with severe metabolic syndrome; limited to Beijing and Shanghai academic centers with intensive care infrastructure.
Sleeve gastrectomy handles the majority of throughput; gastric bypass is climbing the fastest on share as diabetes remission data hardens.
End User:
Capital equipment subsidies and NHSA reimbursement tiering fragment procurement authority across institutional categories.
- Hospitals:Tier-three public institutions anchor procedure volume through dedicated metabolic surgery units. Zhejiang and Jiangsu provincial health commissions channel equipment subsidies toward municipal medical centers expanding bariatric programs.
- Specialty Centers:Focused metabolic surgery facilities in Shanghai and Beijing private networks capture premium pricing through bundled care pathways. NMPA streamlined registration for single-specialty sites accelerates their robotic platform adoption.
- Ambulatory Surgical Centers:Laparoscopic sleeve procedures migrate to outpatient settings where NHSA pilot programs in Guangdong test same-day discharge reimbursement.
- Clinics:Preoperative assessment and postoperative monitoring concentrate in community settings; surgical intervention remains outside their scope.
Hospitals retain dominant volume position; specialty centers are expanding most quickly as capital flows to focused delivery models.
Technology:
Equipment intensity and service contract structures differentiate margin profiles across surgical platforms.
- Laparoscopic:Multi-port instrumentation with standardized stapling and energy platforms retains broadest installed base. Domestic manufacturers in Jiangsu and Zhejiang compress hardware margins while capturing disposable component volume.
- Robotic-assisted:Da Vinci and competing platforms enable single-port sleeve gastrectomy with reduced incisional complications. Prefecture-level hospitals outside Shanghai face capital constraint despite provincial subsidy programs.
- Endoscopic:Transoral procedures including gastric plication and intragastric balloon placement target non-surgical candidates. NMPA review timelines for novel endoluminal devices lag behind laparoscopic platform registrations.
- Open Surgery:Conversion reserve for revision cases and super-obese patients with extensive adhesions; volume concentrates in academic centers with trauma surgery backup.
Laparoscopic systems manage current throughput; robotic-assisted platforms are gaining share fastest as training ecosystems mature.
Patient Demographics:
Clinical indication criteria and reimbursement eligibility fragment addressable populations.
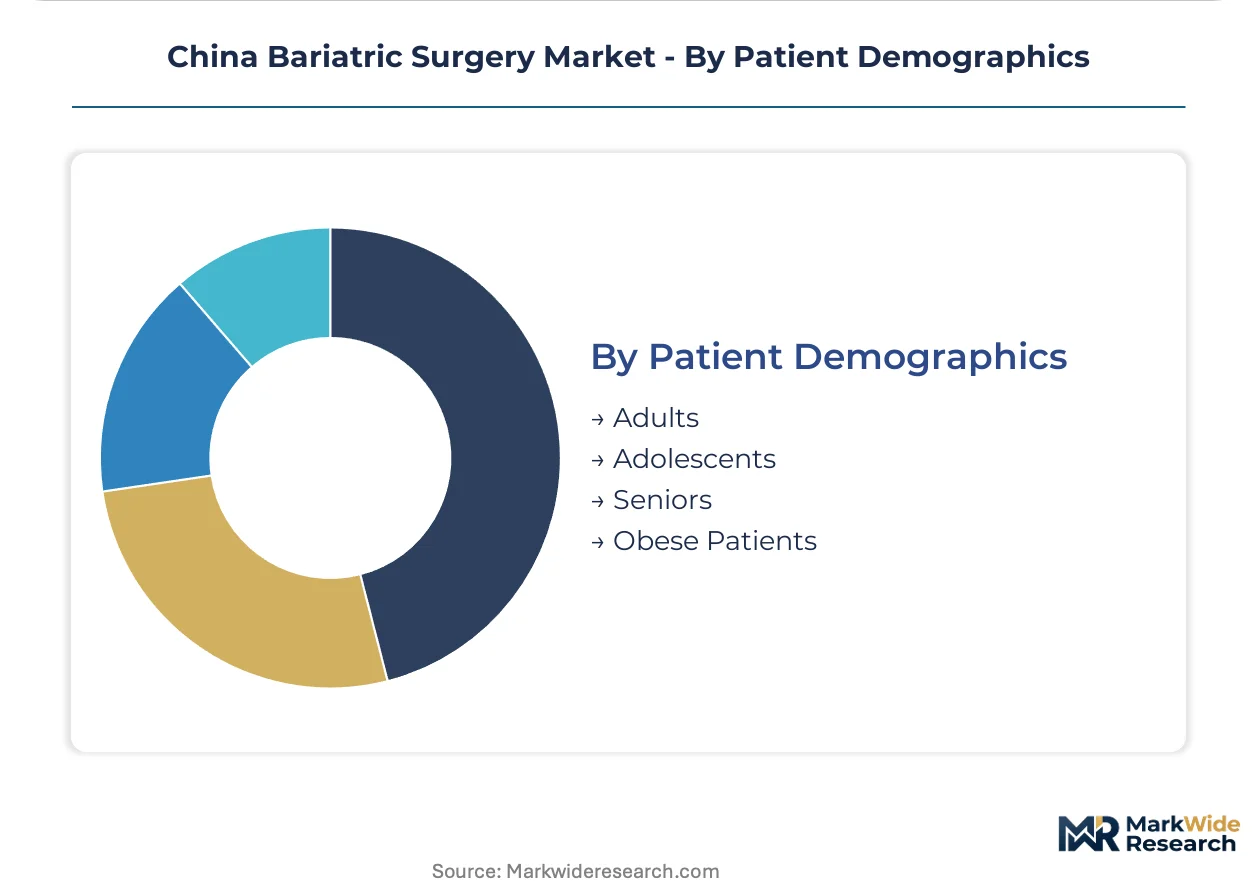
- Adults:BMI thresholds above 32.5 with comorbidities or above 37.5 without dominate surgical candidacy. Working-age patients in coastal provinces drive elective procedure demand.
- Seniors:Cardiovascular risk stratification and frailty assessment concentrate this population in Beijing and Shanghai academic centers with geriatric surgery infrastructure.
- Adolescents:Metabolic surgery for patients under 18 requires multidisciplinary committee approval; limited to tier-one hospitals with pediatric endocrinology integration.
- Obese Patients:Super-obese category with BMI exceeding 50 demands specialized anesthesia and ICU capacity that restricts treatment to major municipal networks.
Adults represent the core throughput base; seniors are expanding most quickly as population aging intersects with metabolic disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports precision surgical stapling systems and robotic instrumentation components to Southeast Asian hospital networks, while importing advanced energy platforms and training ecosystems from Japanese and American manufacturers. This bilateral trade pattern concentrates capital equipment procurement authority in coastal provincial health commissions.
Yangtze River Delta
Shanghai municipal hospitals anchor sleeve gastrectomy volume through dedicated metabolic surgery units. NMPA's accelerated Class III device review pathway streamlines stapler system approvals for Jiangsu satellite networks. Suzhou and Wuxi manufacturing clusters supply cost-engineered disposable components to tier-three hospitals across the delta.
Pearl River Delta
Guangdong province pilots same-day discharge reimbursement for laparoscopic procedures in ambulatory settings. The National Healthcare Security Administration tests procedure pricing differentials between robotic and conventional modalities in Shenzhen municipal networks. Guangzhou academic medical centers concentrate gastric bypass volume for diabetes remission cases.
Beijing-Tianjin-Hebei
Capital region hospitals dominate super-obese patient referrals requiring intensive care infrastructure. SAMR green procurement guidelines favor energy-efficient electrosurgical generators in municipal hospital capital planning. Tianjin port logistics facilitate imported robotic platform distribution to northern provincial networks.
Sichuan-Chongqing
Western China exhibits surgical volume gaps relative to coastal demand density, offering first-mover positioning for equipment distributors. Provincial health commissions channel equipment subsidies toward prefecture-level hospitals expanding bariatric programs. Chongqing municipal networks develop surgeon certification pathways for robotic-assisted metabolic surgery.
Shandong Peninsula
Qingdao and Yantai manufacturing bases produce domestic laparoscopic instrumentation competing on cost-engineered specifications. Provincial centralized procurement mechanisms drive standardization of instrument specifications across municipal medical centers. Jinan academic hospitals anchor training ecosystem partnerships with international robotic platform vendors.
China Bariatric Surgery Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and service contract structures. The vendor base concentrates around three tiers: multinational platform vendors with integrated training ecosystems, domestic manufacturers capturing disposable component volume, and regional distributors bridging procurement committees with provincial reimbursement tiers. Strategic moves center on unbundling after-sales service from hardware contracts and establishing surgeon certification programs that extend beyond device sales.
Among the named participants, Olympus Corporation and Medtronic PLC occupy positions as integrated platform vendors with established service contract networks across eastern China surgical suites. Reach Surgical represents the domestic manufacturing archetype competing on cost-engineered stapling systems tailored to provincial reimbursement tiers. These three companies exemplify the competitive structure where international vendors anchor premium robotic and endoscopy platforms while Chinese manufacturers capture standardized laparoscopic disposable volume.
| Leading Market Players |
|---|
| Olympus Corporation |
| Reach Surgical |
| ReShape Lifesciences Inc |
| Boston Scientific Corporation |
| Medtronic PLC |
| Cousin Biotech |
| Changzhou Haiers Medical Devices Co Ltd |
| Precision (Changzhou) Medical Instruments Co Ltd |
| TransEnterix Inc |
| Others |
Value Chain & Pricing Dynamics
Multi-year service contracts bundled with robotic platform purchases lock in both supply access and price visibility for tier-three hospitals navigating NMPA procurement regulations. This contractual architecture shields municipal medical centers from spot-market volatility in disposable stapling components while compressing hardware margins for international vendors competing against Jiangsu-based domestic manufacturers.
Pricing Analysis
Next-generation robotic-assisted platforms command substantial premiums over conventional laparoscopic systems and legacy open-surgery instruments. Three-tier pricing structure across premium, standard, and economy levels segments procurement committees by capital intensity tolerance, with Beijing and Shanghai academic networks absorbing premium tiers while prefecture-level hospitals concentrate in economy segments. Cost compression in the standard tier is intensifying because domestic manufacturers in Zhejiang and Jiangsu provinces are scaling production of cost-engineered electrosurgical generators. Prefecture-level municipal medical centers exhibit highest price sensitivity, whereas specialty metabolic surgery centers in private Shanghai networks demonstrate lowest sensitivity due to bundled care pathway premiums.
Supply Chain Analysis
Port congestion along the Yangtze River delta trade lane elevates inbound logistics costs for imported robotic instrumentation components arriving through Shanghai customs. Manufacturing concentration centers on China, Japan, and the United States for precision surgical staplers, energy platforms, and robotic arm assemblies respectively. Raw material dependencies span medical-grade stainless steel, high-performance polymers, and semiconductor chips for motion control systems. Single-source vulnerability concentrates in advanced energy-delivery algorithms patented by select multinational vendors. Distribution runs through provincial centralized procurement platforms that aggregate demand across municipal hospital networks before negotiating volume-based tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where robotic-assisted surgical ecosystems are displacing standalone device transactions, driven by NMPA's accelerated review pathway interoperability with hospital information system architectures.
For Market Incumbents: Fortify service-contract revenue streams by unbundling technical support from hardware sales and establishing captive surgeon certification programs that extend beyond device installation. Domestic manufacturers in Jiangsu province threaten disposable component margins through cost-engineered stapling systems. Backward integration into precision polymer molding and semiconductor motion-control sourcing reduces exposure to single-source patent holders. For New Entrants and Emerging Players: NMPA's accelerated Class III review pathway offers fast-track positioning for novel vessel-sealing algorithms and single-port robotic platforms. Central China provinces of Hubei and Hunan present the most penetrable geography given surgical volume gaps relative to coastal density. Go-to-market execution should anchor on prefecture-level hospital equipment subsidy capture through provincial health commission relationship networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated training ecosystem providers with recurring revenue visibility beyond one-time hardware transactions. Long-term viability across the projection horizon hinges on locking hospital loyalty through surgeon certification programs that generate service contract annuities. Watch for NMPA reimbursement catalog adjustments that equalize robotic and laparoscopic procedure pricing as the inflection signal indicating ecosystem commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures procedural volume commitments through dedicated metabolic surgery unit co-development with tier-three public hospitals. |
| Reimbursement Strategy | Aligns robotic platform positioning with NHSA catalog tiers to optimize provincial centralized procurement eligibility. |
| Software Companion Development | Enables procedure data interoperability with existing hospital information system architectures across municipal networks. |
| CE Marking Pathway | Facilitates export positioning for Jiangsu-manufactured stapling systems into Southeast Asian hospital procurement channels. |
| Platform Integration | Consolidates endoscopy, stapling, and energy delivery into unified surgical suites that reduce hospital vendor management burden. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with metabolic surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from NMPA Class III device registration filings, provincial centralized procurement tender databases, hospital procurement system records, and NHSA reimbursement catalog documentation. Bottom-up procedure volume estimates were triangulated against top-down capital equipment shipment data to anchor market sizing.
Across the analysis window, the forecasting framework modeled procedure methodology, care delivery setting, surgical technology platform, and patient population segments. CAGRs were derived from equipment installation trajectories, surgeon certification pipeline data, and reimbursement tier evolution assumptions. Procedure migration patterns from laparoscopic to robotic-assisted platforms and provincial subsidy allocation flows served as key forecast inputs.
Underlying assumptions cover NMPA review timeline stability, provincial equipment subsidy continuity, and surgeon certification pipeline maturation, with deviation risk concentrated in reimbursement catalog adjustments and domestic manufacturer cost-engineering acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
United States Bariatric Surgery Market