
 Regenerative Suspension System Market | 2026-2036
Regenerative Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Suspension System Market Insights
Asset-light leasing structures for advanced suspension hardware are reshaping competitive entry in the regenerative suspension system space. ZF Friedrichshafen AG leverages its integrated chassis electronics portfolio to dominate electromechanical system supply. Continental AG anchors development through captive R&D spending on magnetorheological valve architectures. KYB Corporation specializes in hydraulic energy recovery modules for Asian OEM supply chains.
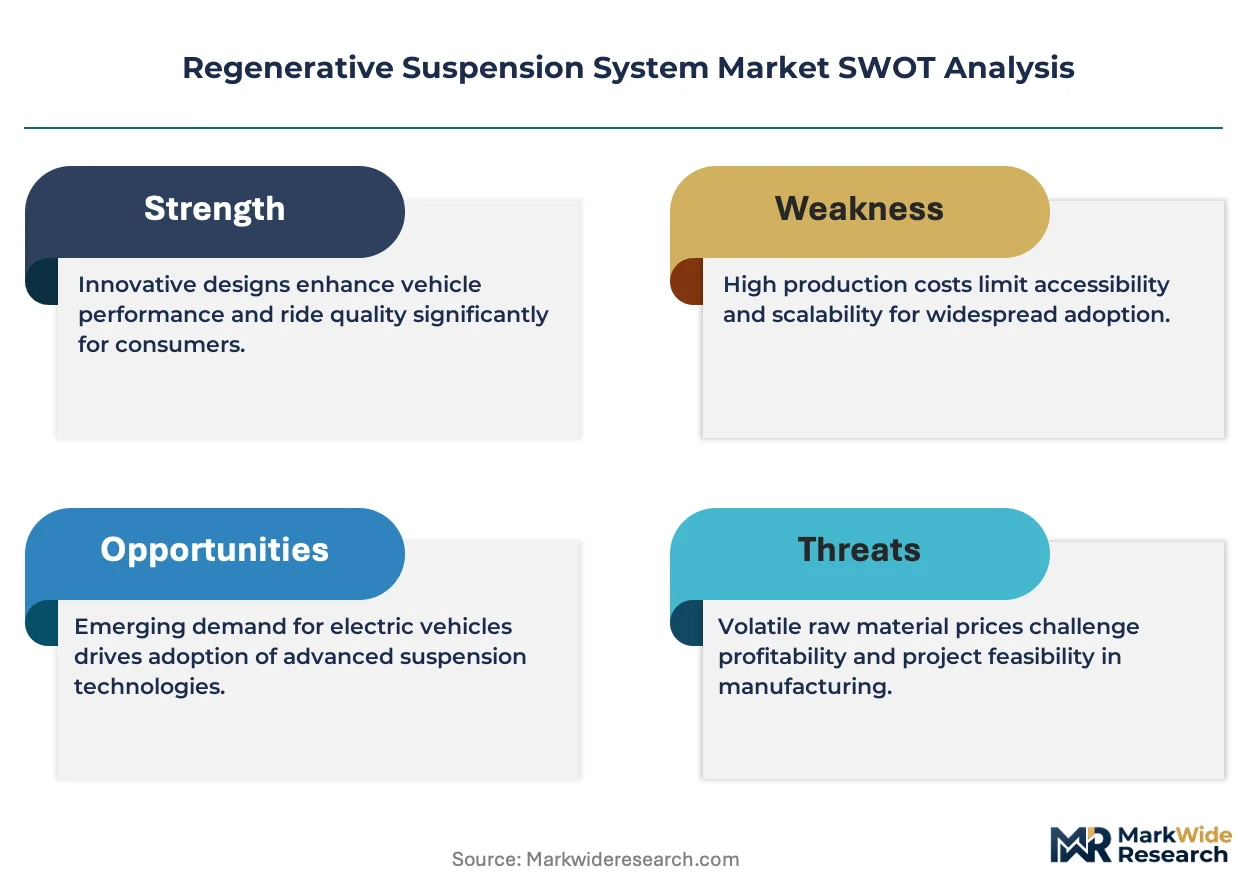
A regenerative suspension system converts kinetic energy from road-induced wheel displacement into electrical power through electromagnetic or hydraulic transduction, typically generating 100-400 watts per corner depending on duty cycle and road severity. The device serves primarily to reduce net vehicle energy consumption while maintaining ride quality targets. Active suspension and hybrid system configurations currently occupy the highest margin pools as OEMs prioritize real-time damping control combined with energy recovery. Electromechanical systems lead technology adoption among passenger car platforms, while hydraulic systems sustain demand in commercial bus applications where duty cycles maximize energy harvest potential.
NHTSA crashworthiness standards and EPA fuel economy regulations in the United States compel automakers to certify regenerative hardware as both safety-critical and efficiency-contributing equipment. The EU Green Deal and CE marking requirements under the F-Gas Regulation restrict pneumatic system refrigerants, accelerating electromechanical alternatives across European assembly plants. Stakeholders must monitor how battery-electric platform architectures redefine suspension energy budgets as thermal management and auxiliary load priorities shift.
Market Dynamics
Electric vehicle platform architectures are forcing suspension suppliers to recalibrate energy budgets as thermal management and auxiliary loads compete for regenerated power. The tension between ride quality optimization and maximum energy harvest is compressing development cycles across Tier 1 chassis suppliers.
Growth Catalysts
- EU Green Deal vehicle efficiency mandates:OEMs face binding CO2 reduction targets that classify regenerative suspension as qualifying efficiency technology. Assembly plants in Germany, France, and Italy are retrofitting lines to accommodate electromechanical damper modules.
- Battery-electric commercial bus duty cycles:Urban transit operators in China and South Korea specify hydraulic energy recovery systems to extend fleet range. Stop-and-go patterns maximize kinetic energy capture per kilometer traveled.
- Electromechanical transduction advances:Permanent magnet linear generators now achieve 100-400 watts per corner under severe road conditions. Passenger car platforms integrate these modules without substantial unsprung mass penalties.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China, exposing electromechanical system costs to export quota volatility and geopolitical friction.
- NHTSA crashworthiness certification timelines:Regenerative dampers must validate as safety-critical components under FMVSS standards, extending homologation cycles by 18-24 months versus conventional passive systems.
- Active air suspension substitution:Premium OEMs in the United States and Germany prioritize pneumatic ride height adjustability over energy recovery, diverting R&D budgets from regenerative alternatives.
Strategic Opportunities
- India PLI scheme for automotive components:Domestic manufacturing incentives cover advanced chassis electronics, attracting joint ventures for electromechanical damper localization. Suppliers can access 13-18% subsidy on incremental sales.
- ISO 26262 functional safety convergence:Integration of ASIL-D rated power electronics with suspension control modules opens new specification tiers for autonomous vehicle platforms requiring fail-operational damping.
- Aftermarket retrofit channels:Independent garages in Japan and South Korea are developing plug-and-play hydraulic recovery kits for hybrid taxi fleets seeking fuel economy improvements without full platform replacement.
Industry Challenges
- Multiphysics simulation talent scarcity:Electromechanical damper development requires coupled magnetic-thermal-structural modeling expertise that competes with electric motor and battery engineering teams for finite element analysis specialists.
- Legacy CAN bus integration complexity:Energy recovery modules must handshake with 20-year-old vehicle network architectures without compromising real-time damping response, forcing redundant sensor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Suspension System Market |
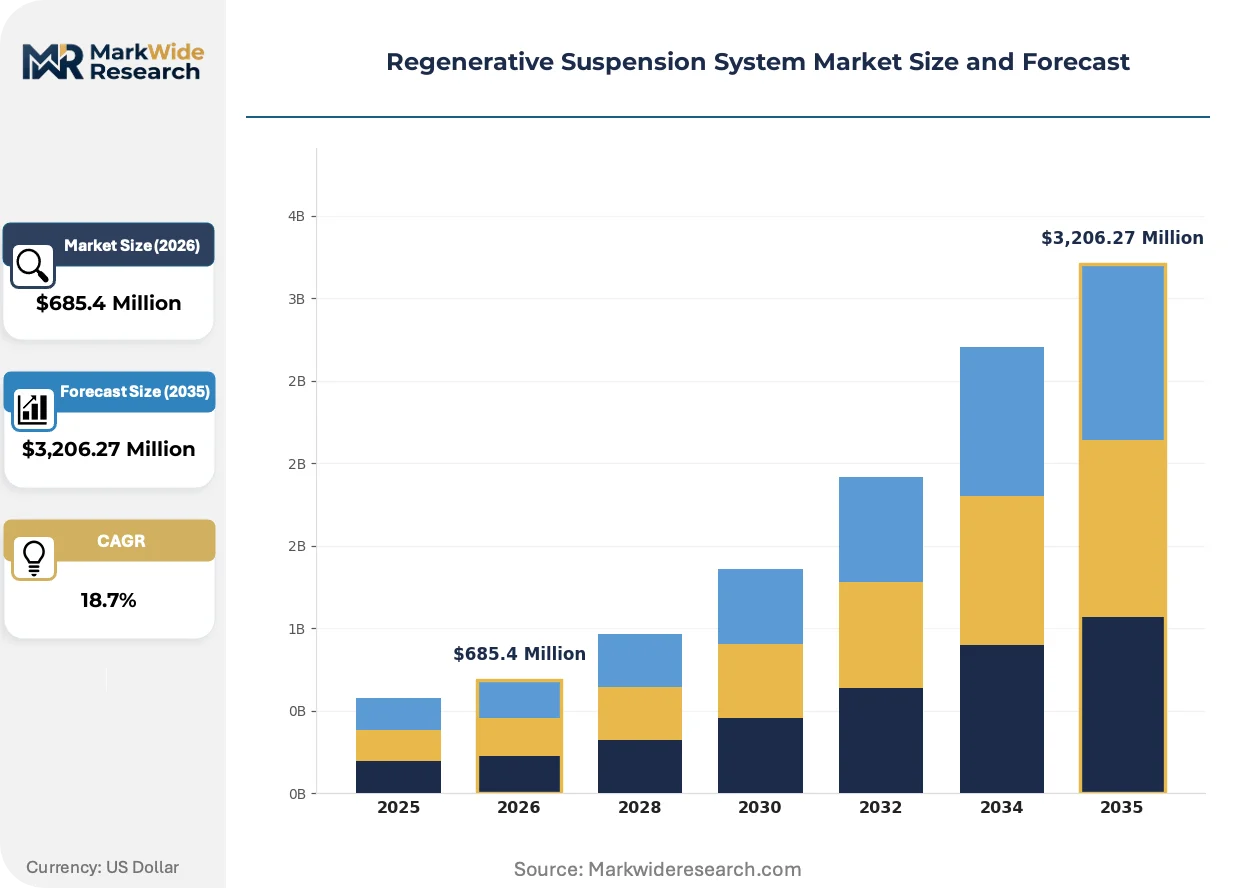
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
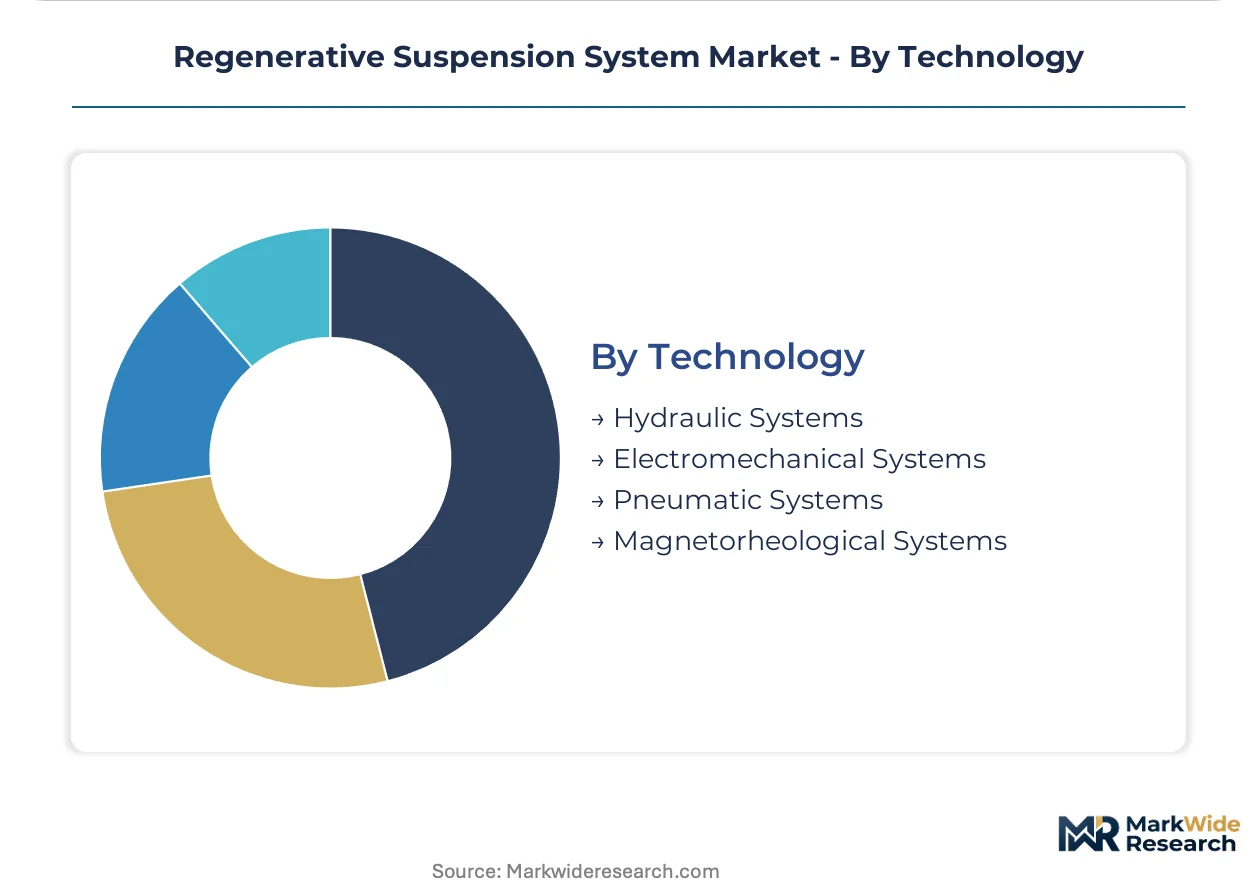
| Segmentation | Product Type: Active Suspension, Passive Suspension, Hybrid System, Adaptive Suspension Application: Automobiles, Buses, Motorcycles, All-Terrain Vehicles End User: OEMs, Aftermarket, Fleet Operators, Private Owners Technology: Hydraulic Systems, Electromechanical Systems, Pneumatic Systems, Magnetorheological Systems |
| Companies Covered | Audi, ZF Friedrichshafen AG, Guident, Intertronic Gresser GmbH, Levant, SoftWheel, Continental AG, KYB Corporation, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Suspension System Market Trends and Innovations
Magnetorheological fluid formulations and solid-state power electronics are converging to enable millisecond-scale damping adjustments with simultaneous energy generation. This technological stack is redefining the boundary between active ride control and auxiliary power supply.
Silicon carbide MOSFETs in regenerative damper power conditioning units are collapsing thermal management overhead for high-frequency switching applications. Tier 1 suppliers are adopting these devices for 800-volt electric vehicle platforms where conventional silicon IGBTs impose cooling penalties. The shift is compressing inverter package volumes by 40% while enabling bidirectional power flow to battery management systems.
REACH restrictions on perfluorinated compounds are accelerating fluorocarbon-free magnetorheological fluid development across European supply chains. The ECHA authorization process has delisted several legacy MR fluid additives, forcing reformulation of valve architectures in Continental and ZF production lines. German OEMs are qualifying new shear-thickening alternatives ahead of 2026 sunset dates for affected substances.
Fleet operators are unbundling suspension energy recovery performance from chassis hardware procurement, demanding guaranteed watt-hour-per-kilometer contracts. Municipal bus authorities in South Korea and Japan now specify outcome-based service agreements where suppliers retain ownership of damper modules and monetize recovered electricity. This model is displacing traditional component sales in high-utilization commercial segments where duty cycle predictability supports energy harvest guarantees.
Regenerative Suspension System Market Segmentation
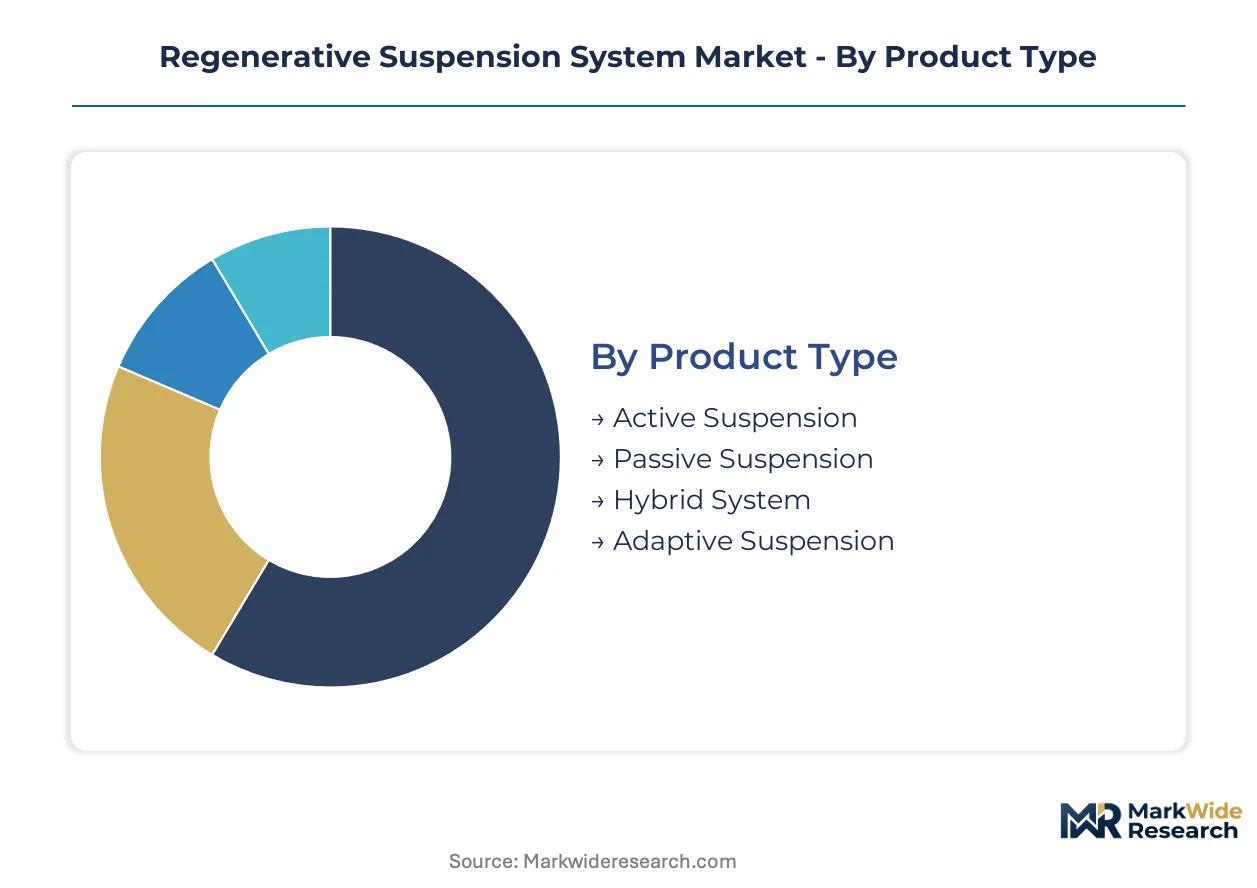
Regenerative suspension procurement cycles diverge sharply across product tiers, with fleet operators replacing commercial bus hardware every 4-6 years while passenger car OEMs lock in platform designs for 8-10 year model lifespans. Technology selection directly determines energy harvest yields and homologation complexity, forcing suppliers to align R&D pipelines with distinct replacement rhythms.
Product Type:
Active suspension modules turn over fastest as OEMs refresh damping algorithms annually, while passive systems persist longest in economy vehicle platforms where hardware replacement lags software updates by multiple product cycles.
- Active Suspension:Electromechanical actuators with real-time damping control and continuous energy recovery dominate premium electric vehicle architectures. German and South Korean automakers specify these systems for flagship sedans where ride quality and range extension justify unit cost premiums.
- Hybrid System:Combines passive spring elements with switchable energy recovery modes, bridging cost gaps for mid-market battery-electric platforms. Chinese OEMs anchor volume demand as domestic manufacturers seek efficiency credentials without full active suspension investment.
- Passive Suspension:Conventional damper architectures with bolt-on energy recovery retrofits serve aftermarket channels and developing market fleet operators.
- Adaptive Suspension:Electronically controlled valve systems with limited energy harvest capability target performance vehicle segments prioritizing handling over auxiliary power generation.
Passive suspension dominates installed base across legacy vehicle fleets. Hybrid systems are where expansion concentrates as OEMs balance efficiency mandates against cost containment pressures.
Application:
Commercial bus duty cycles maximize energy harvest economics through stop-and-go urban patterns, while motorcycle platforms impose severe mass constraints that limit transduction hardware integration.
- Buses:Hydraulic energy recovery systems exploit high-frequency suspension displacement in urban transit duty cycles. South Korean and Japanese municipal operators specify guaranteed watt-hour contracts, converting kinetic capture into measurable fuel cost reductions.
- Automobiles:Electromechanical damper modules integrate with 800-volt electric vehicle architectures, feeding recovered power into battery management systems. Passenger car platforms generate 100-400 watts per corner depending on road severity and vehicle speed profiles.
- Motorcycles:Compact piezoelectric or electromagnetic harvesters target touring bikes with sufficient sprung mass to justify added weight, though adoption remains constrained by packaging limitations.
- All-Terrain Vehicles:Ruggedized hydraulic recovery systems serve mining and agricultural fleet operators operating on unpaved surfaces with high displacement amplitudes.
Automobiles dominate installed base among passenger transportation categories. Buses are where expansion concentrates as fleet electrification accelerates and energy harvest guarantees displace conventional procurement.
End User:
OEM specification cycles stretch 3-5 years for platform integration, while aftermarket channels respond within months to fuel price volatility and retrofit kit availability.
- OEMs:Original equipment manufacturers mandate ASIL-D functional safety certification and multi-year supply agreements, locking suppliers into dedicated production lines for electromechanical damper modules. German automakers anchor development through captive R&D partnerships.
- Fleet Operators:Municipal bus authorities and commercial logistics companies in China and South Korea pilot outcome-based service contracts where suppliers retain hardware ownership and monetize recovered electricity per kilometer.
- Aftermarket:Independent garages in Japan and South Korea develop plug-and-play hydraulic recovery kits for hybrid taxi fleets seeking fuel economy improvements without full platform replacement.
- Private Owners:Enthusiast segments in North America and Europe pursue DIY electromechanical retrofits for performance vehicles, though volume remains limited by installation complexity and warranty concerns.
OEMs dominate installed base through platform-integrated supply agreements. Fleet operators are where expansion concentrates as outcome-based procurement models displace traditional component sales.
Technology:
Electromechanical systems command highest unit margins but face rare earth supply concentration risks, while hydraulic platforms sustain commercial vehicle demand through mature supply chains and service infrastructure.
- Electromechanical Systems:Permanent magnet linear generators achieve 100-400 watts per corner with silicon carbide power conditioning for 800-volt architectures. EU Green Deal efficiency mandates accelerate adoption as OEMs seek qualifying technologies for CO2 reduction targets.
- Hydraulic Systems:Fluid-based energy recovery with accumulator storage maximizes duty cycle harvest in commercial bus applications. Urban transit operators in China specify these systems for fleet range extension under severe stop-and-go patterns.
- Magnetorheological Systems:Shear-thickening fluid formulations enable millisecond damping adjustments with simultaneous energy generation, though REACH restrictions on perfluorinated compounds force European supply chain reformulation.
- Pneumatic Systems:Air-spring based recovery faces F-Gas Regulation constraints on refrigerant gases, compressing deployment to legacy platforms as electromechanical alternatives displace new installations.
Hydraulic systems dominate installed base in commercial vehicle fleets. Electromechanical systems are where expansion concentrates as passenger car electrification and rare earth magnet supply stabilization enable cost scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural surplus in electromechanical suspension exports to European assembly plants while importing rare earth magnets from China. The United States runs a deficit in finished regenerative damper modules, sourcing primarily from German and Japanese Tier 1 suppliers. China's export capacity concentrates in hydraulic energy recovery systems for commercial bus fleets across Asia-Pacific markets.
United States
Detroit Three automakers specify electromechanical dampers for 800-volt electric vehicle platforms launching from 2025. NHTSA crashworthiness certification under FMVSS standards extends homologation timelines by 18-24 months versus conventional systems. Michigan-based engineering clusters anchor validation testing for regenerative hardware destined for North American assembly.
Germany
OEMs in Stuttgart and Munich mandate regenerative suspension as qualifying technology under EU Green Deal CO2 reduction targets. KBA type-approval processes integrate efficiency certification with safety validation for electromechanical systems. Baden-Württemberg supplier parks coordinate magnetorheological fluid R&D with captive polymer chemistry facilities.
China
Domestic battery-electric bus manufacturers specify hydraulic energy recovery systems for urban transit fleets in Beijing and Shenzhen. MIIT new energy vehicle subsidies cover regenerative chassis components under efficiency technology classifications. Yangtze River Delta manufacturing corridors concentrate hydraulic accumulator production for export to Southeast Asian markets.
South Korea
Seoul municipal operators pilot outcome-based service contracts where suppliers retain damper ownership and monetize recovered electricity. MFDS automotive safety standards align with UN ECE regulations for electromechanical suspension homologation. Busan-Ulsan industrial zones host joint ventures for localized electromechanical damper assembly serving domestic OEMs.
Japan
Tokyo taxi fleet operators retrofit hybrid vehicles with plug-and-play hydraulic recovery kits to improve fuel economy without platform replacement. METI carbon neutrality roadmaps classify regenerative suspension as priority efficiency technology for 2030 targets. Kanto region engineering centers specialize in piezoelectric harvester miniaturization for motorcycle applications.
Regenerative Suspension System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying magnetic materials, power electronics, and fluid formulations. Market structure consolidates around five electromechanical system suppliers with captive chassis electronics portfolios, while hydraulic recovery segments fragment across regional fabricators. Two strategic archetypes dominate: integrated chassis electronics houses and specialized energy recovery module developers. Competitive moves concentrate on backward integration into permanent magnet supply chains and strategic partnerships for 800-volt power conditioning technology.
Within the integrated chassis tier, ZF Friedrichshafen AG and Continental AG exemplify platform-level suppliers with captive R&D pipelines spanning damper hardware through vehicle network integration. KYB Corporation occupies a position among specialized hydraulic recovery developers serving Asian commercial vehicle markets. These three entities represent distinct geographic anchoring—German system integration, Japanese hydraulic specialization—while sharing exposure to rare earth magnet cost volatility and REACH-compliant fluid reformulation timelines.
| Leading Market Players |
|---|
| Audi |
| ZF Friedrichshafen AG |
| Guident |
| Intertronic Gresser GmbH |
| Levant |
| SoftWheel |
| Continental AG |
| KYB Corporation |
| Hitachi Astemo |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor cost dynamics amplify rare earth magnet supply concentration into downstream price differentiation for electromechanical damper modules. Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with ASIL-D certification tiers and volume scale driving spreads. Cost compression in standard-tier hydraulic systems is intensifying because Chinese bus fleet operators consolidate procurement under outcome-based contracts. Fleet operators exhibit highest price sensitivity; German premium OEMs demonstrate lowest.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with ASIL-D certification tiers and volume scale driving spreads. Cost compression in standard-tier hydraulic systems is intensifying because Chinese bus fleet operators consolidate procurement under outcome-based contracts. Fleet operators exhibit highest price sensitivity; German premium OEMs demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta manufacturing corridors feed working capital strain into Tier 2 magnet suppliers. Electromechanical system production draws from China, Germany, and Japan, with neodymium processing, silicon carbide wafers, and magnetorheological fluids as critical inputs. Single-source vulnerability concentrates in rare earth magnet separation facilities. Distribution runs through captive OEM supply agreements and fleet operator service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal efficiency mandates are accelerating regenerative suspension from niche technology to platform-standard equipment, compressing adoption timelines across passenger and commercial segments.
For Market Incumbents: Harden permanent magnet supply chains through backward integration into separation facilities or long-term offtake with Australian rare earth developers. Lock ASIL-D certification pipelines ahead of autonomous vehicle platform integration to forestall emerging power electronics specialists from qualifying for fail-operational damping specifications. For New Entrants and Emerging Players: Build out aftermarket retrofit channels for hybrid taxi and municipal bus fleets in South Korea and Japan, where plug-and-play hydraulic kits face minimal incumbent saturation. Target fleet operators with guaranteed watt-hour-per-kilometer service contracts that displace traditional component sales. For Investors and Strategic Acquirers: Magnetorheological fluid formulation specialists with REACH-compliant shear-thickening alternatives command scarcity premia as European sunset dates approach. Watch ECHA authorization timelines for perfluorinated compound delistings as the inflection signal for consolidation urgency in European supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Long-term offtake with Australian or Vietnamese separation facilities insulates electromechanical system costs from Chinese export quota volatility. |
| ASIL-D Functional Safety Certification | Integration with autonomous vehicle platforms requires fail-operational damping validated under ISO 26262 standards. |
| Magnetorheological Fluid Reformulation | REACH-compliant alternatives to delisted perfluorinated compounds secure European OEM qualification ahead of 2026 deadlines. |
| Outcome-Based Service Contract | Suppliers retain hardware ownership and monetize recovered electricity per kilometer in South Korean municipal bus fleets. |
| Silicon Carbide Power Conditioning | 800-volt electric vehicle architectures demand SiC MOSFET inverters that collapse thermal management overhead by 40%. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and vehicle production databases through bottom-up and top-down triangulation. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers informed demand-side validation. Secondary sources include NHTSA FMVSS certification databases, EU type-approval registries, and MIIT new energy vehicle subsidy disclosures.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the analysis window. CAGRs derive from segment-level volume trajectories weighted by technology adoption curves and regulatory compliance deadlines. Electric vehicle platform energy budgets and rare earth magnet supply elasticity serve as industry-specific demand shapers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese hydraulic system fabricators or breakthroughs in rare earth-free magnet formulations would shift outcomes. Macroeconomic contraction in European automotive demand, escalation of export quota restrictions, or delays in NHTSA crashworthiness certification timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Actuators Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automobile Accessories Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Carbon Ceramic Brakes Market