
 Global Electronic Brake Force Distribution System Market | 2026-2036
Global Electronic Brake Force Distribution System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Brake Force Distribution System Market Intelligence
Software-defined feature activation for advanced braking functions is decoupling the hardware sale from the total system value. Robert Bosch GmbH leverages its deep expertise in automotive electronics and software to lead this transition. Continental AG competes through its integrated portfolio of chassis and safety technologies. ZF Friedrichshafen AG specializes in advanced systems for both passenger and commercial vehicle applications, navigating complex OEM requirements.
An electronic brake force distribution system is a technology that dynamically adjusts the braking pressure on each wheel to optimize stopping power and vehicle stability. It works with an anti-lock braking system to prevent wheel lockup under heavy braking. Electronic EBD variants have largely displaced older hydraulic systems in modern vehicles. The integration of EBD with Electronic Stability Control represents the dominant technology configuration, particularly within the passenger cars application segment.
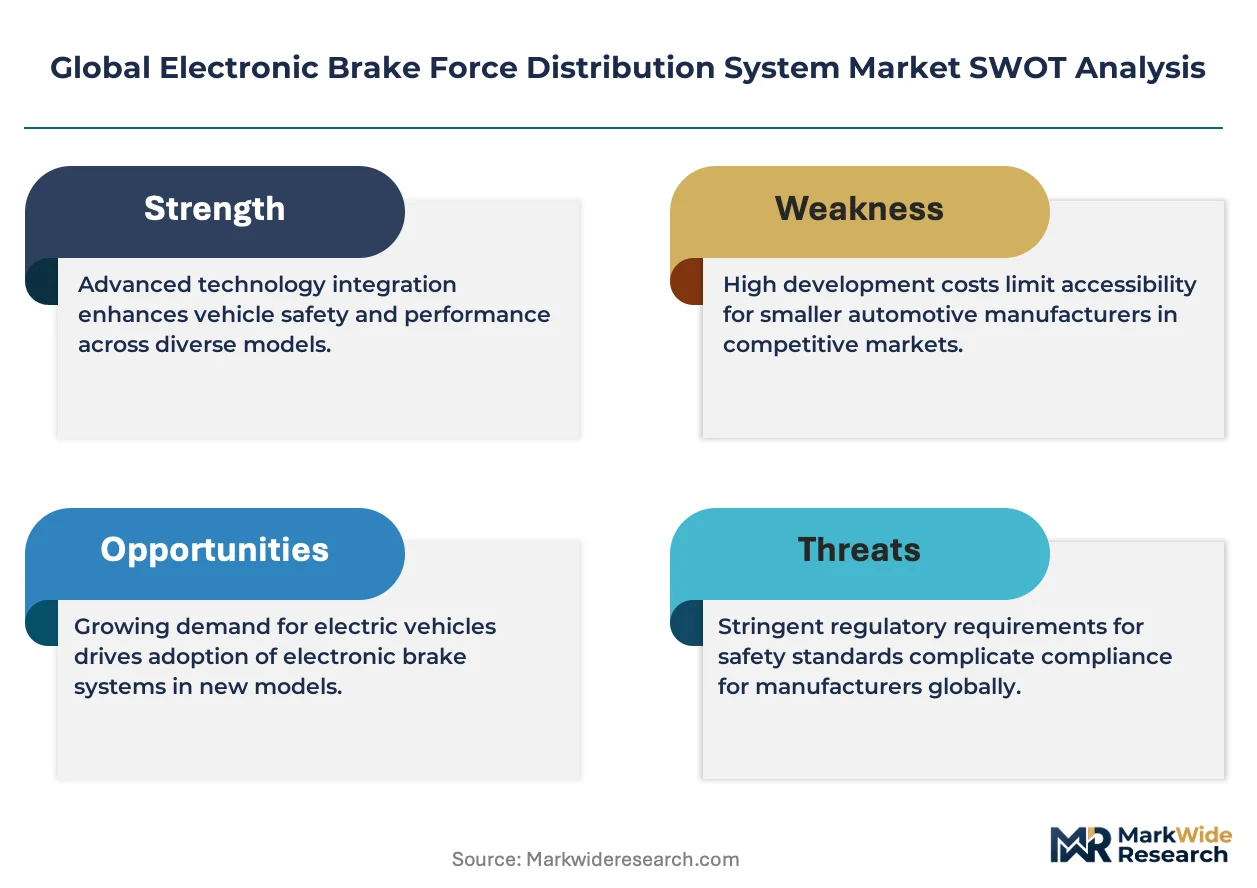
Regulatory mandates are a significant demand driver. Vehicle safety standards set by the United States' NHTSA and Europe's UNECE require anti-lock brakes and stability control, making EBD a non-negotiable component. China's GB standards for new vehicles also align with these global safety benchmarks. The key decision for suppliers now revolves around managing software complexity and meeting diverse regional homologation requirements.
Market Dynamics
The market's central dynamic is the institutionalization of safety through regulation. Mandates from bodies like the NHTSA in the United States and the UNECE in Europe have transformed electronic braking systems from optional features into standard, non-negotiable components for new vehicles.
Growth Catalysts
- Regulatory Mandates:Global vehicle safety standards, including China's GB standards and Europe's General Safety Regulation, require anti-lock braking and electronic stability control, making EBD a default technology on virtually all new passenger cars.
- Commercial Vehicle Safety:Demand is expanding in the heavy-duty truck and bus segments as new regulations target the reduction of accidents, compelling fleet operators and manufacturers to adopt advanced braking systems.
- Technology Integration:The fusion of EBD with broader Electronic Stability Control systems creates a more capable and valuable safety platform, which is the dominant configuration sought by automotive OEMs for new vehicle platforms.
Market Restraints
- Software Homologation Costs:The expense and time required to validate and certify complex braking software for diverse regional standards, such as those in Europe versus China, create significant development overhead for suppliers.
- Semiconductor Dependency:The system's reliance on a concentrated global supply base for specialized microcontrollers and sensors exposes manufacturers to significant price volatility and potential supply chain disruptions.
- Value Capture Complexity:Decoupling software features from hardware sales makes it difficult for suppliers to capture the full value of their innovation, as OEMs push to commoditize the underlying hardware components.
Strategic Opportunities
- Electric Vehicle Systems:Integrating EBD with regenerative braking in electric and hybrid vehicles presents a major opportunity to enhance efficiency, extend battery range, and improve overall braking feel and performance.
- Brake-by-Wire Transition:The automotive industry's shift towards brake-by-wire architectures creates an opportunity for advanced EBD software to become the central control logic for next-generation vehicle dynamics.
- Emerging Market Penetration:As safety regulations tighten in markets across Latin America and Southeast Asia, there is a significant opportunity to supply standardized, cost-effective EBD systems for entry-level and mid-range vehicles.
Industry Challenges
- Functional Safety Expertise:A persistent challenge is the scarcity of software engineers with deep expertise in functional safety standards like ISO 26262, which is critical for developing failure-proof braking control software.
- Platform Integration Complexity:Suppliers face operational difficulties in adapting their EBD software to a wide variety of OEM electronic architectures, each requiring custom integration and extensive validation testing.
- Cybersecurity Vulnerabilities:With increasing connectivity, ensuring the security of braking system software against remote attacks is a paramount challenge, requiring new design methodologies and continuous threat monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Brake Force Distribution System Market |
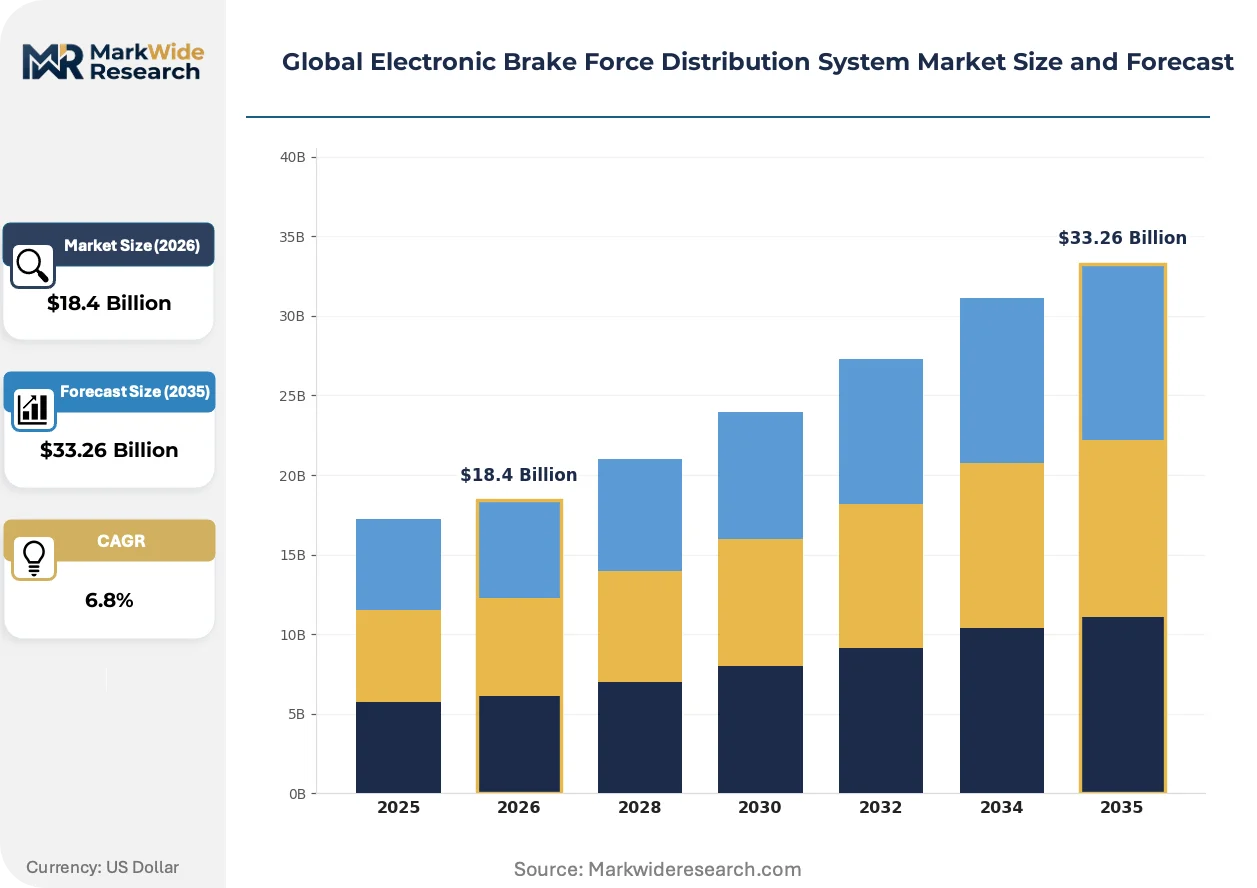
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic EBD, Electronic EBD, Mechanical EBD, Pneumatic EBD Technology: Anti-lock Braking System, Brake Assist System, Traction Control System, Electronic Stability Control, Regenerative Braking Application: Passenger Cars, Commercial Vehicles, Two-wheelers, Construction Vehicles, Agricultural Machinery End User: OEMs, Aftermarket Service Providers, Automotive Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Denso Corporation, Aisin Seiki Co., Ltd., Robert Bosch GmbH, Knorr-Bremse AG, Akebono Brake Industry Co., Ltd., Continental AG, Hyundai Mobis, Mando Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Brake Force Distribution System Market Strategic Shifts & Innovations
The evolution from hardware-centric design to software-defined functionality is the primary theme transforming the electronic brake force distribution system market. This shift redefines system value, focusing on upgradable features and advanced control algorithms rather than purely mechanical components.
Brake-by-wire technology eliminates the need for direct hydraulic or mechanical links, relying on electronic signals for actuation. Premium vehicle manufacturers and electric vehicle startups are leading the adoption of this architecture for its packaging flexibility and rapid response times. This advanced braking architecture is converging with EBD and regenerative braking functions to create a unified, software-controlled system for vehicle dynamics.
Upcoming UNECE regulations on vehicle cybersecurity and software updates are forcing a fundamental change in system design. These mandates require that all electronic control units, including those for EBD, are secure from cyber threats and capable of receiving validated over-the-air updates. The passenger car segment, particularly in Europe and Japan, is most affected, compelling suppliers to build robust software lifecycle management capabilities.
Automakers' procurement models are changing from buying a fixed hardware and software bundle to licensing specific braking functions. This unbundling allows OEMs to activate or upgrade features like enhanced stability control or optimized traction for different vehicle trims post-production. This trend is most apparent in the German and Chinese premium vehicle markets, creating new revenue models based on software activation.
Global Electronic Brake Force Distribution System Market Segmentation
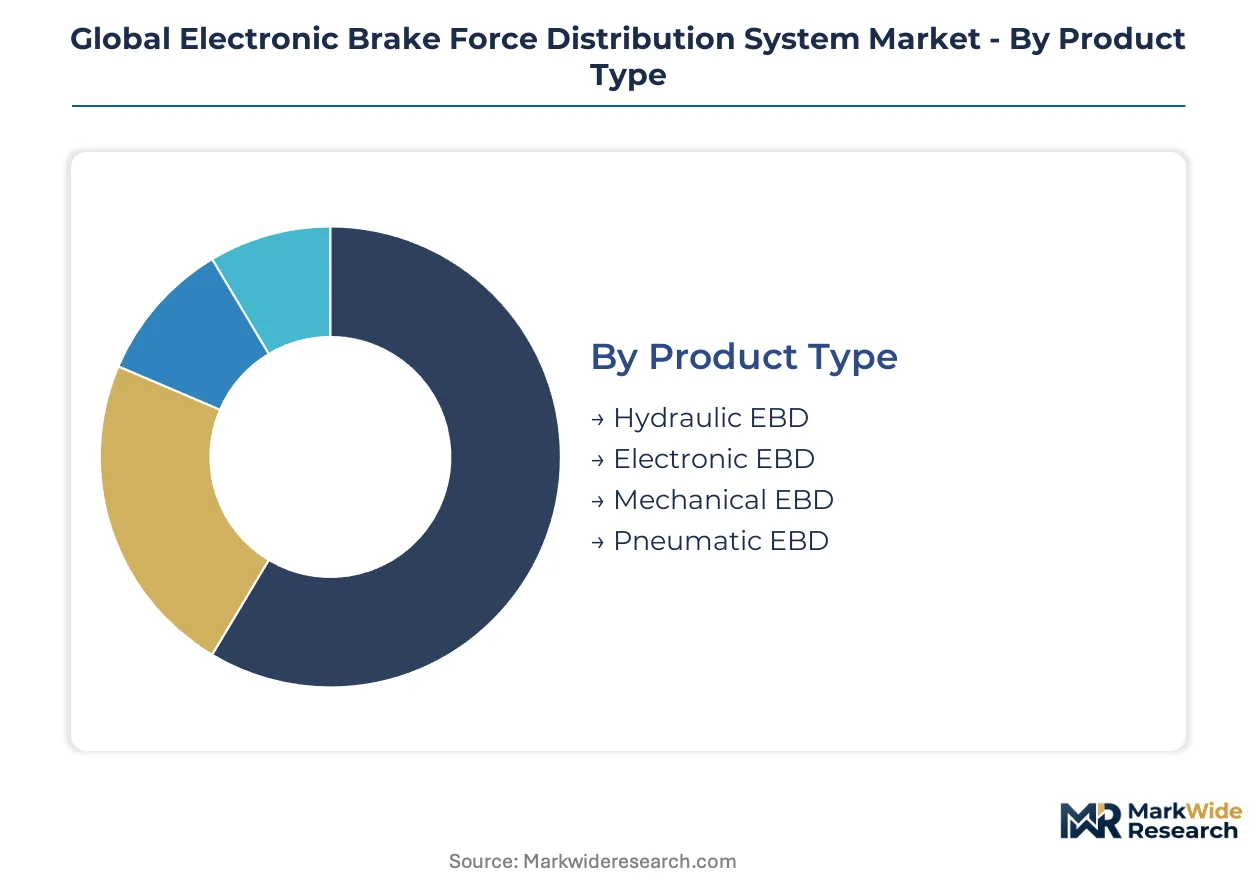
The electronic brake force distribution system market is analyzed across key segments, providing a granular view of technology adoption and end-user demand. Understanding these segments illuminates the diverse requirements influencing product development and market penetration strategies across different vehicle types and regions.
Product Type:
The electronic brake force distribution system market segments by product type, reflecting varying levels of hardware integration and control sophistication.
- Electronic EBD:This advanced system dynamically adjusts braking pressure to each wheel using electronic sensors and control units. Demand concentrates in modern passenger cars and commercial vehicles, driven by mandatory safety regulations and enhanced stability requirements.
- Hydraulic EBD:These systems primarily rely on hydraulic pressure modulation to distribute braking force, typically found in older vehicle models or specific heavy-duty applications. Demand is concentrating in aftermarket replacements for legacy fleets, where system upgrades are not cost-effective.
- Mechanical EBD:Mechanical EBD systems use physical linkages and spring mechanisms to distribute braking force, offering basic functionality in low-cost or older vehicle platforms.
- Pneumatic EBD:Pneumatic systems utilize air pressure for brake force distribution, primarily found in heavy commercial vehicles and trailers where air brakes are standard.
Volume placements concentrate in Electronic EBD; the faster expansion belongs to Electronic EBD as it continues to displace older technologies.
Technology:
The market's technology landscape is defined by the integration and functionality of various braking and stability control systems.
- Electronic Stability Control:This comprehensive system integrates EBD with traction control and anti-lock braking to prevent skidding and loss of control by applying individual wheel brakes. Demand is strong in all new vehicle platforms, particularly in Europe and China, due to stringent safety mandates.
- Regenerative Braking:Regenerative braking systems convert kinetic energy into electrical energy during deceleration, requiring sophisticated EBD integration for optimal braking feel and energy recovery in electric vehicles. Demand is concentrating in electric and hybrid vehicle segments, driven by efficiency and range extension goals.
- Anti-lock Braking System:ABS prevents wheel lock-up during hard braking, maintaining steering control and reducing stopping distances.
- Brake Assist System:BAS detects emergency braking situations and automatically applies maximum braking force, supplementing driver input.
- Traction Control System:TCS prevents drive wheels from losing traction during acceleration, enhancing vehicle stability on slippery surfaces.
The market's technology evolution is heavily influenced by the convergence of Electronic Stability Control with regenerative braking systems.
Application:
Application segments delineate the primary vehicle types where electronic brake force distribution systems are deployed.
- Passenger Cars:This segment includes sedans, SUVs, and hatchbacks, which represent the largest volume segment for EBD systems globally. Demand is concentrating in major automotive production hubs like Germany and China, driven by consumer safety expectations and regulatory compliance.
- Commercial Vehicles:This segment encompasses heavy-duty trucks, buses, and light commercial vehicles, where EBD systems enhance stability and safety under varying load conditions. Demand is expanding in this segment due to new safety regulations targeting accident reduction in fleet operations.
- Two-wheelers:EBD systems are increasingly adopted in motorcycles and scooters to improve braking stability and prevent skidding, especially in premium models.
- Construction Vehicles:Specialized EBD systems are designed for heavy construction equipment to manage braking effectively on uneven terrain and with heavy loads.
- Agricultural Machinery:EBD integration in tractors and other farm equipment enhances stability and control, particularly when operating with large implements or on slopes.
Passenger Cars account for the largest volume, while Commercial Vehicles show the most dynamic growth.
End User:
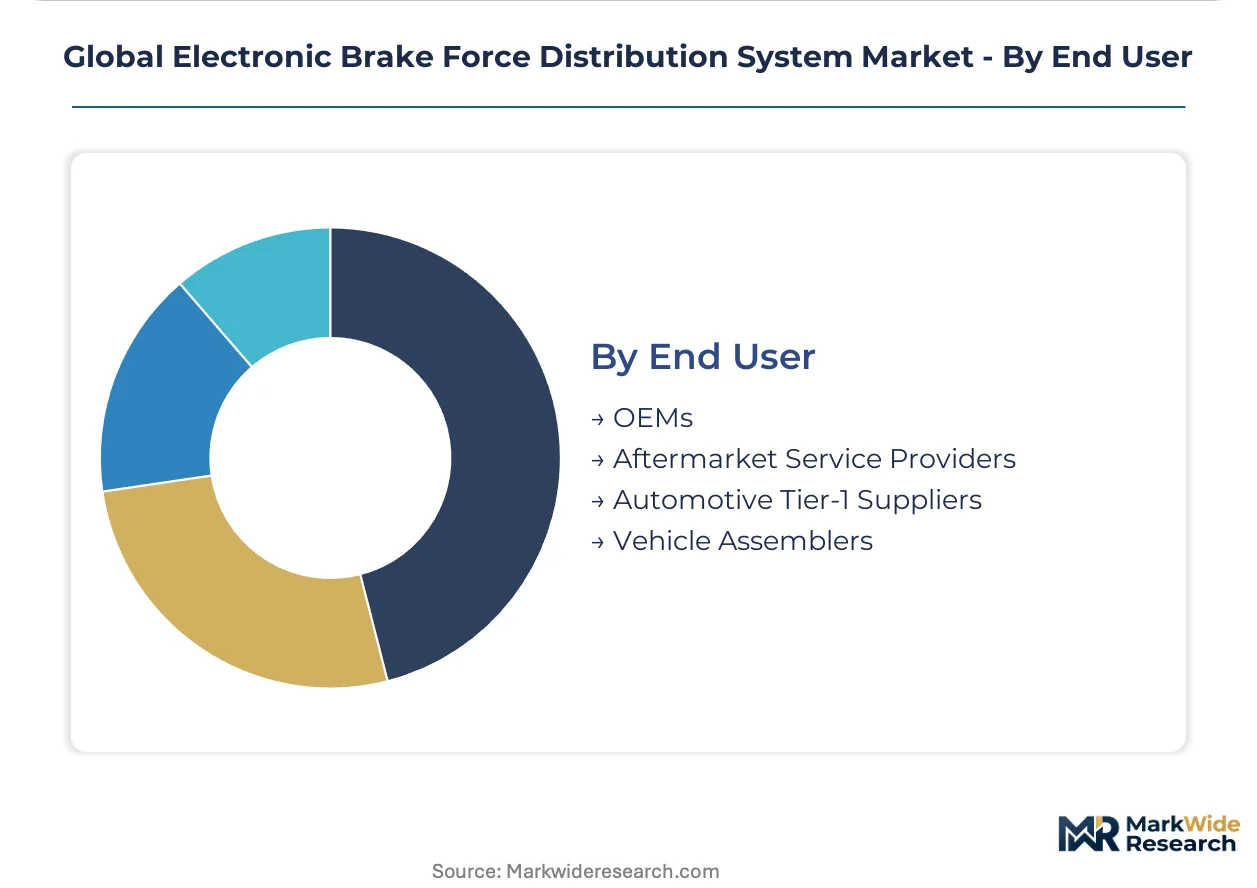
The end-user segmentation reflects the primary purchasers and integrators of electronic brake force distribution systems within the automotive supply chain.
- OEMs:Original Equipment Manufacturers integrate EBD systems directly into new vehicle production lines, often working closely with suppliers for custom solutions. OEMs in Germany and Japan are particularly focused on advanced software-defined braking functionalities.
- Automotive Tier-1 Suppliers:These suppliers develop and manufacture complete EBD systems, often including hardware and software, which are then supplied to OEMs for integration. These suppliers are critical for navigating complex OEM requirements and regional homologation standards.
- Aftermarket Service Providers:These entities offer repair, replacement, and upgrade services for EBD systems in existing vehicles.
- Vehicle Assemblers:Vehicle assemblers integrate components from various suppliers, including EBD systems, into final vehicle builds, particularly in smaller volume or niche manufacturing.
OEMs remain the primary purchasing channel, with Automotive Tier-1 Suppliers driving innovation and integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital-heavy production hubs often contrast with high-consumption regions in the global electronic brake force distribution system market. Demand for advanced EBD systems is driven by stringent safety mandates and technology integration across diverse automotive manufacturing landscapes. Key regions balance local production capabilities with import needs for specialized components.
China
China's automotive market drives significant demand for EBD systems due due to its vast vehicle production volumes. The GB standards for new vehicles mandate anti-lock brakes and stability control, making EBD a default technology. Manufacturing clusters in the Yangtze River Delta region focus on integrating advanced EBD solutions into both domestic and international vehicle platforms.
Germany
Germany represents a core hub for premium automotive technology and EBD innovation. Europe's UNECE regulations and General Safety Regulation require advanced braking systems for all new vehicles. Major automotive centers like Stuttgart and Munich are home to key suppliers developing next-generation software-defined EBD functionalities.
United States
The United States market demonstrates robust demand for EBD systems, particularly in light trucks and SUVs. NHTSA safety standards necessitate anti-lock braking and electronic stability control in all new vehicles. Michigan's automotive corridor, including Detroit, focuses on integrating EBD with evolving electric vehicle architectures.
Japan
Japan's advanced automotive industry prioritizes safety and technological sophistication in EBD systems. METI guidelines encourage the adoption of cutting-edge vehicle safety features for passenger cars. Manufacturing centers in Aichi Prefecture, particularly around Nagoya, lead in developing integrated EBD and regenerative braking solutions.
India
India's growing automotive sector presents an expanding opportunity for EBD system adoption. Regulatory bodies are progressively implementing new safety norms for passenger and commercial vehicles. Production hubs like Pune and Chennai are increasing local manufacturing capabilities for electronic braking components.
Global Electronic Brake Force Distribution System Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the electronic brake force distribution system market. The landscape exhibits a tiered structure, with established Tier-1 suppliers dominating the integrated system segment. Strategic archetypes include large-scale system integrators, specialized software developers, and component manufacturers. Dominant competitive moves involve technology licensing agreements and portfolio diversification into software-defined features.
Among the established Tier-1 suppliers, German-based Robert Bosch GmbH exemplifies a player leveraging deep expertise in automotive electronics and software. Continental AG, another German AG, occupies a similar position, competing through its integrated portfolio of chassis and safety technologies. ZF Friedrichshafen AG, also a German AG, represents a significant entity specializing in advanced systems for both passenger and commercial vehicle applications, addressing complex OEM requirements.
| Leading Market Players |
|---|
| Denso Corporation |
| Aisin Seiki Co., Ltd. |
| Robert Bosch GmbH |
| Knorr-Bremse AG |
| Akebono Brake Industry Co., Ltd. |
| Continental AG |
| Hyundai Mobis |
| Mando Corporation |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Vertical integration by major Tier-1 suppliers into both hardware and software production anchors their supply position and dictates their pricing power in the electronic brake force distribution system market. This strategic choice influences component availability and overall system costs for OEMs.
Pricing Analysis
Cost-down pressure on hardware components accelerates as OEMs push for commoditization of underlying EBD modules. The dominant pricing structure involves per-unit transactional sales for hardware, complemented by licensing or royalty models for advanced software features. Price differentiation stems from software sophistication, adherence to functional safety standards like ISO 26262, and the level of integration with complex OEM electronic architectures. OEMs exhibit high price sensitivity for basic hardware, but less so for critical, certified software functionalities that ensure vehicle safety and performance.
Supply Chain Analysis
Single-source vulnerability sits with specialized semiconductor manufacturers for microcontrollers and sensors, exposing the EBD supply chain to significant disruption. Geographic supply concentration for key components exists in regions like Germany, Japan, and Taiwan. The system's reliance on these advanced electronic inputs creates a risk of commodity price volatility. Distribution runs primarily through Tier-1 suppliers directly to Original Equipment Manufacturers for integration into new vehicle production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players actively pursuing deeper software integration capabilities as a primary lever for future value capture.
For Market Incumbents:Anchor existing OEM relationships by offering comprehensive, software-defined braking platforms that reduce integration complexity for automakers. Deepen expertise in functional safety standards like ISO 26262 to mitigate the threat from new software-focused entrants. Invest in advanced cybersecurity features for EBD systems to address evolving regulatory requirements and protect against potential vulnerabilities. Expand regional software development centers to better meet diverse homologation requirements across key automotive production hubs.
For New Entrants and Emerging Players:Digital licensing models for advanced EBD algorithms represent a penetrable segment for new players, particularly for electric vehicle startups. Target specialized commercial vehicle applications in emerging markets across Latin America and Southeast Asia with cost-effective, standardized EBD solutions. Offer customized software stacks that integrate seamlessly with novel brake-by-wire architectures, providing a strong go-to-market angle. Focus on developing modular EBD software that can be easily adapted to various OEM electronic architectures.
For Investors and Strategic Acquirers:Exit pathways concentrate in software-centric firms specializing in functional safety, brake-by-wire technologies, or automotive cybersecurity, offering robust long-term viability over the next 5-10 years. Target companies with proven expertise in developing and certifying complex automotive software for acquisition. The signal to watch is the increasing proportion of vehicle value attributed to software features by major OEMs, indicating a shift in procurement priorities. Seek firms that can enhance overall system value through advanced algorithm development.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Feature Development | This move enables flexible feature activation and new revenue models for vehicle manufacturers. |
| Functional Safety Certification Investment | Ensuring ISO 26262 compliance is critical for market access and OEM trust. |
| Brake-by-Wire System Integration | This technology offers packaging flexibility and rapid response times for electric vehicles. |
| Cybersecurity Protocol Implementation | Securing EBD software against remote attacks is essential for regulatory compliance and vehicle integrity. |
| Emerging Market Localization | Adapting EBD systems for cost-effective deployment expands access in developing automotive sectors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews with industry stakeholders. We engaged automotive OEM engineers, Tier-1 supplier R&D leads, vehicle safety regulators from NHTSA and UNECE, and fleet managers. This comprehensive approach allowed for bottom-up analysis and top-down validation of market dynamics and forecasts.
Data-stream reconciliation integrated historical market performance with projected technology adoption rates and regulatory timelines across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional production clusters. Compound annual growth rates were derived from historical trends and anticipated shifts in new vehicle sales forecasts and EV penetration rates.
The model holds under stable regulatory environments and consistent automotive production volumes; deviation in geopolitical events impacting semiconductor supply or a faster-than-expected shift to brake-by-wire architectures would shift outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market