
 Automotive Smart Security Device Market | 2026-2036
Automotive Smart Security Device Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Security Device Market Analysis
Market Context
The EU Cyber Resilience Act is expanding the cost-of-entry calculus for aftermarket and OEM security suppliers. Robert Bosch GmbH leverages its embedded electronics portfolio to anchor integrated immobilizer production across European assembly lines. Continental AG sustains R&D intensity in biometric access modules, while Denso Corporation dominates supply contracts with Japanese automakers seeking factory-fitted GPS tracking.
Technical Definition and Structural Segments
Automotive smart security devices encompass electronic and electromechanical systems engineered to prevent unauthorized vehicle access, theft, or remote hijacking, typically operating through encrypted transponder communication, geofencing algorithms, or fingerprint recognition with response times under milliseconds. These devices serve commercial and consumer vehicle owners by reducing insurance liability, enabling fleet recovery, and satisfying OEM cybersecurity mandates. Immobilizers and IoT-enabled GPS trackers capture the deepest margin pools due to recurring connectivity subscriptions and firmware update revenue streams. Biometric technology segments are gaining fastest as facial and fingerprint authentication displace conventional key fobs in premium vehicle configurations.
Regulatory Frame and Outlook
The U.S. NHTSA, European ECHA through REACH substance restrictions on electronic components, and Japan's METI vehicle cybersecurity guidelines collectively shape product standards, testing protocols, and cross-border market access requirements. Compliance with these frameworks determines whether suppliers qualify for OEM procurement or remain relegated to fragmented aftermarket channels. Stakeholders must monitor evolving type-approval harmonization between EU and Japanese regulators to anticipate certification cost trajectories and design-cycle investments.
Market Dynamics
Fleet operators in Germany, Japan, and the United States are accelerating their procurement of connected anti-theft systems as insurance underwriters tighten liability terms for unprotected commercial vehicles. This demand compression is forcing security suppliers to reconfigure product roadmaps around OEM-integrated architectures rather than aftermarket retrofit kits.
Growth Catalysts
- NHTSA Cybersecurity Guidelines:The U.S. regulator's evolving vehicle security mandates are compelling domestic automakers to factory-fit encrypted immobilizers, eliminating retrofit lag in new vehicle configurations.
- Fleet Telematics Integration:Commercial vehicle operators are bundling GPS tracking with driver behavior analytics, creating bundled procurement that expands security device attach rates.
- EU Type-Approval Standards:Brussels-mandated immobilizer certification for cross-border vehicle registration is blocking non-compliant aftermarket suppliers from accessing member-state distribution channels.
Market Restraints
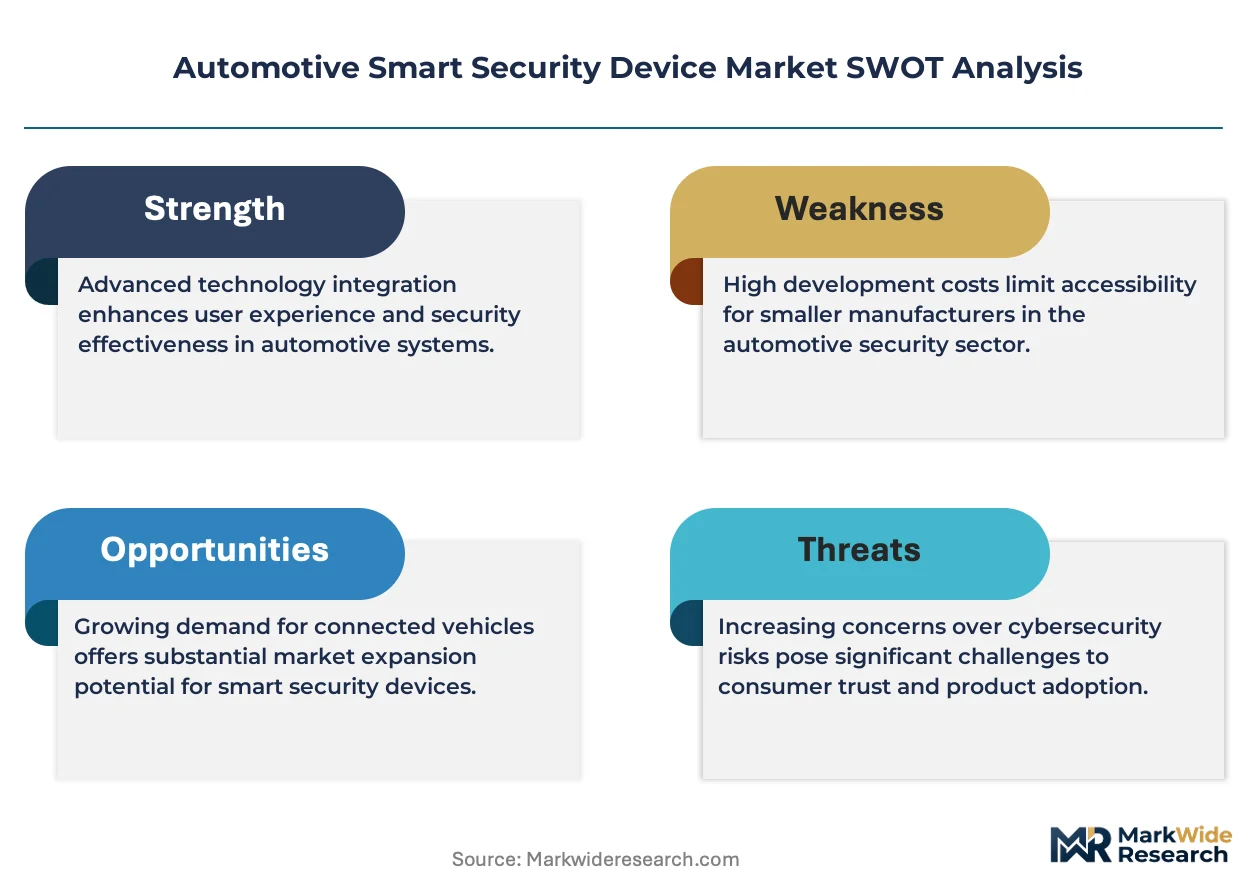
- Semiconductor Input Volatility:Secure element chips and RF transponders face concentrated fabrication in Taiwanese foundries, exposing module assemblers to allocation rationing during supply shocks.
- REACH Substance Restrictions:ECHA limitations on specific electronic component chemistries are forcing redesign cycles that extend qualification timelines for European market entry.
- Smartphone Substitution:Digital key protocols embedded in mobile operating systems threaten standalone biometric fob demand in premium vehicle segments.
Strategic Opportunities
- India Fleet Modernization:Commercial vehicle aggregators in Maharashtra and Gujarat are piloting subscription-based immobilizer services where hardware costs are amortized through monthly connectivity fees.
- AI-Enhanced Geofencing:Machine learning anomaly detection is converging with traditional GPS tracking to predict theft attempts before perimeter breaches occur.
- EU Cyber Resilience Act:The bloc's mandatory security update obligations for connected devices create recurring revenue streams through firmware maintenance contracts.
Industry Challenges
- Embedded Systems Talent Scarcity:Cryptographic firmware engineering and side-channel attack mitigation skills concentrate in semiconductor hubs, forcing security device makers to compete with chip designers for limited personnel.
- Multi-Jurisdiction Certification Lag:Separate NHTSA, KBA, and METI approval processes for biometric authentication modules extend product launch timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Security Device Market |
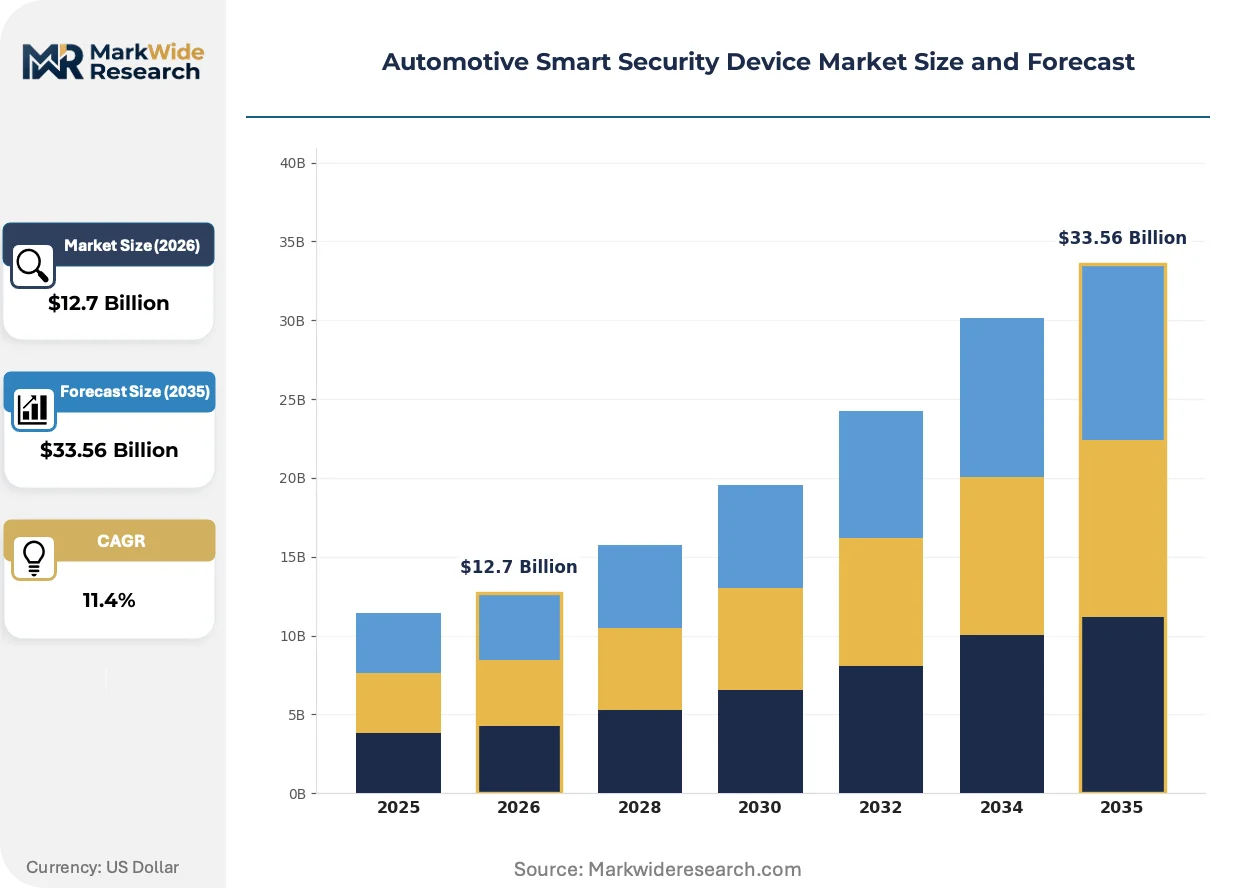
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm Systems, GPS Trackers, Immobilizers, Steering Wheel Locks Technology: Bluetooth, RFID, IoT, Biometric End User: Fleet Operators, Personal Vehicle Owners, Dealerships, Security Service Providers Installation Type: Professional, DIY, Integrated, Portable |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Harman International, Valeo, Autoliv Inc., Aptiv PLC, Lear Corporation, Huf Hülsbeck & Fürst GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Security Device Market Emerging Trajectories
Automotive smart security is pivoting from perimeter defense to continuous vehicle identity verification, with biometric and behavioral authentication displacing static key-based systems. This shift is compressing hardware margins while expanding software and services revenue pools.
Ultrawideband (UWB) positioning technology is converging with Bluetooth Low Energy to enable centimeter-accurate passive entry without relay attack vulnerability. German and Japanese luxury automakers are adopting UWB-enabled digital keys as standard equipment, compressing the addressable market for conventional RF immobilizers while enabling subscription-based key sharing and temporary access credentialing.
The EU Cyber Resilience Act's mandatory vulnerability disclosure and security update requirements are forcing device manufacturers to maintain decade-long firmware support infrastructure. Suppliers serving European OEMs are responding by restructuring engineering organizations around continuous security patch delivery, with compliance costs absorbed through higher module pricing or multi-year service contracts.
Fleet procurement departments are consolidating security device purchasing under telematics platform providers rather than sourcing standalone immobilizers. This channel compression is most visible in the United States, where national trucking operators negotiate enterprise-wide security and tracking bundles, marginalizing independent aftermarket distributors and forcing hardware makers to embed their technology within larger fleet management stacks.
Automotive Smart Security Device Market Segmentation
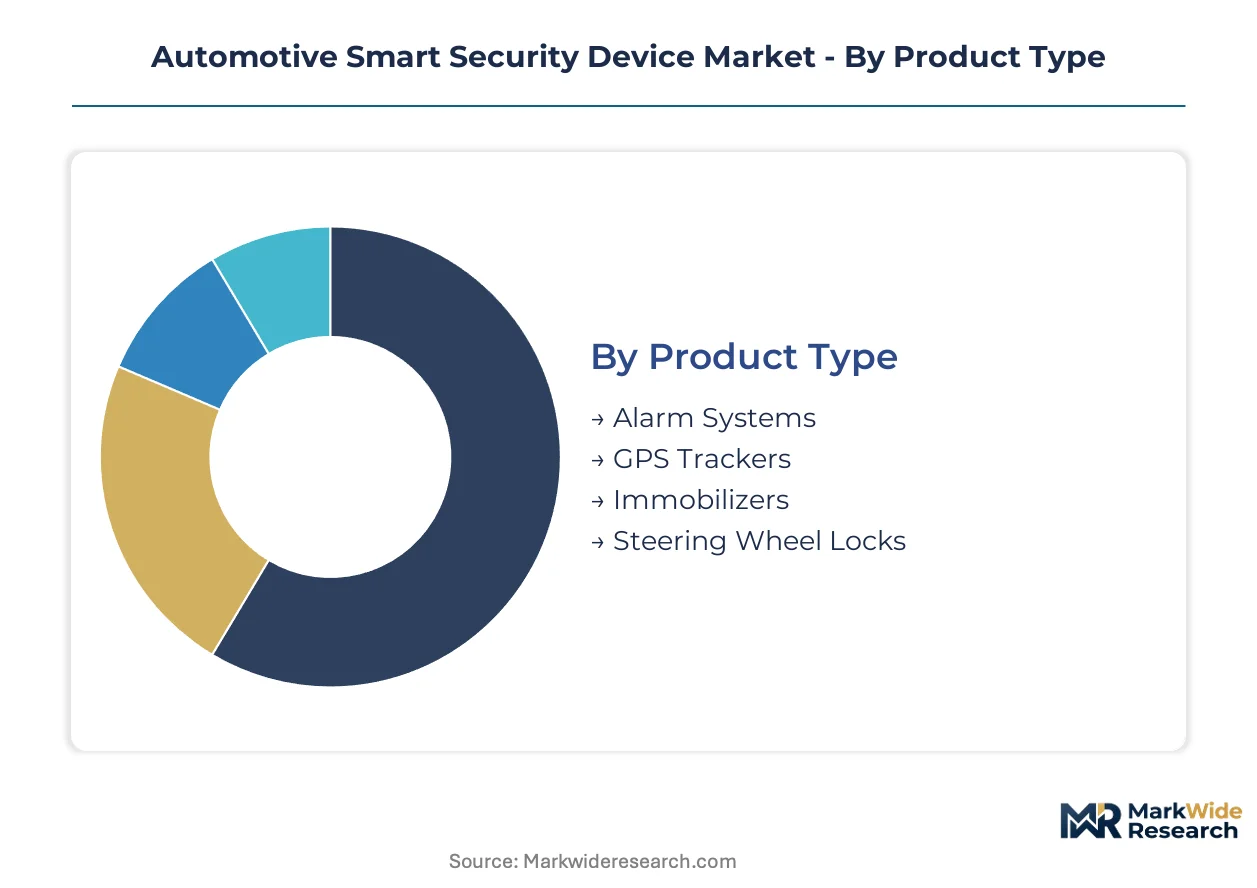
Security device procurement splits sharply between standardized OEM-integrated modules and customized aftermarket configurations. Fleet operators and personal vehicle owners diverge in technical requirements, connectivity preferences, and installation protocols, fragmenting supplier go-to-market strategies across four structural dimensions.
Product Type:
Standardization dominates alarm and immobilizer architectures while GPS trackers and steering wheel locks retain customization flexibility for niche applications.
- Alarm Systems:Piezoelectric and electromagnetic sensors trigger acoustic and visual deterrents with 120+ decibel output. Demand clusters in urban Germany and Japan where parking density amplifies theft risk and neighborhood alert networks prove effective.
- GPS Trackers:Cellular-connected modules transmit location data through encrypted telemetry stacks with geofencing capabilities. Fleet operators in the United States bundle these with telematics platforms, compressing standalone hardware margins while expanding recurring connectivity revenue.
- Immobilizers:Transponder-based engine disable systems meeting EU type-approval standards.
- Steering Wheel Locks:Mechanical deterrents for aftermarket retrofit in price-sensitive segments.
Most installed capacity flows through Immobilizers. Expansion is steepest in GPS Trackers.
Technology:
Cost tier stratification separates mature RF protocols from premium biometric authentication, with Bluetooth occupying the mid-market bridge position.
- Bluetooth:Low-energy protocols enable smartphone-based passive entry with relay attack mitigation through distance-bounding algorithms. German luxury automakers embed these in digital key architectures, displacing conventional fobs in premium configurations.
- Biometric:Fingerprint and facial recognition modules authenticate drivers through capacitive sensors and infrared cameras with sub-500 millisecond response. Japanese OEMs factory-fit these in flagship sedans, though semiconductor input costs constrain mass-market penetration.
- RFID:Passive transponder communication for immobilizer authentication.
- IoT:Cloud-connected security stacks enabling remote monitoring and over-the-air updates.
RFID retains the largest installed base. Biometric authentication is climbing the fastest as premium vehicle configurations multiply.
End User:
Customer type determines procurement channel, with fleet operators consolidating through telematics platforms and personal owners fragmenting across retail and e-commerce.
- Fleet Operators:Commercial vehicle aggregators negotiate enterprise-wide security bundles integrating immobilizers, GPS tracking, and driver behavior analytics. United States national trucking networks drive standardization requirements that cascade to supplier product roadmaps.
- Personal Vehicle Owners:Individual purchasers select aftermarket alarm systems and portable locks through automotive retail chains. Price sensitivity dominates, though smartphone substitution pressures standalone biometric fob demand.
- Dealerships:Value-added resellers packaging security with vehicle financing.
- Security Service Providers:Third-party monitoring firms sourcing white-label hardware.
Fleet procurement captures the deepest volume concentration. Personal vehicle channels are gaining share fastest in emerging subscription-based service models.
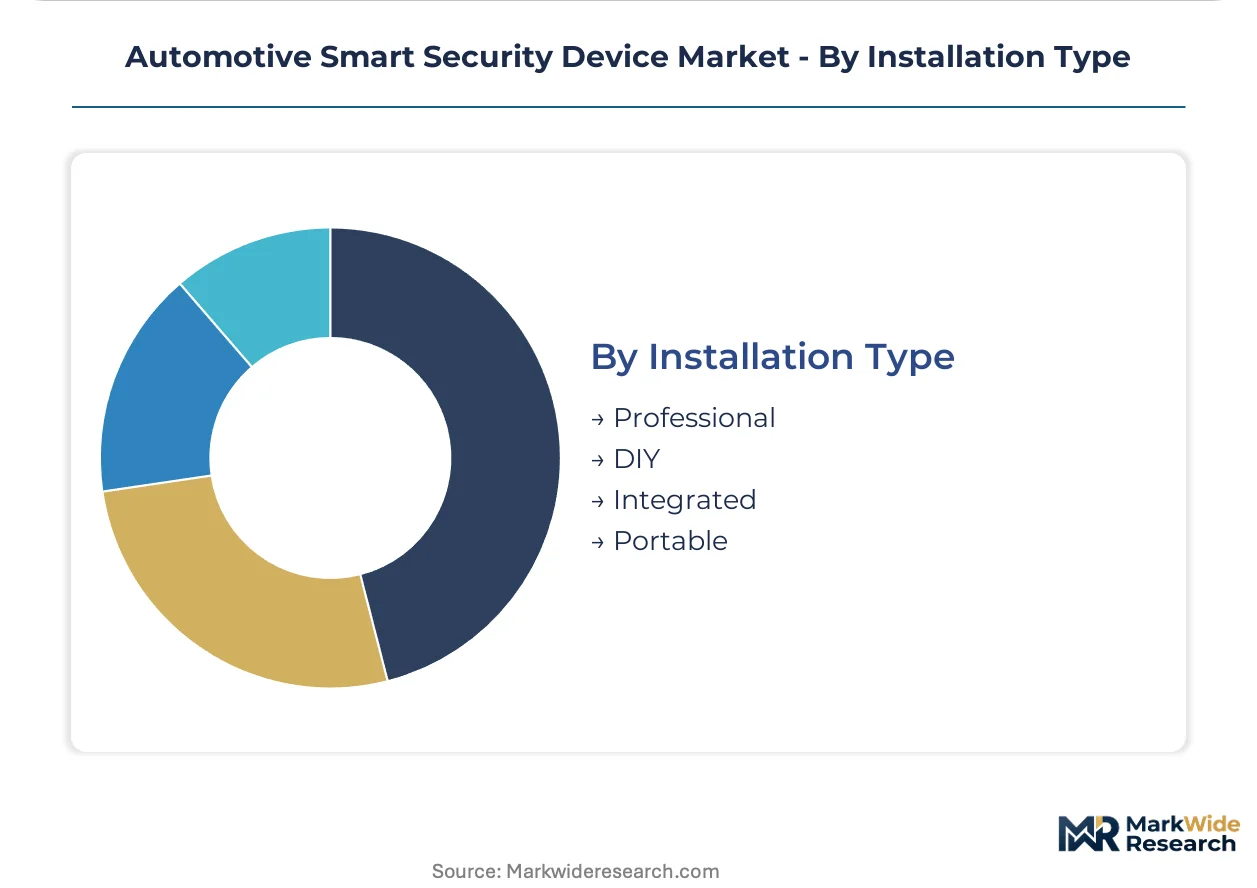
Installation Type:
Maturity gradients separate legacy professional installation from emerging integrated architectures that eliminate aftermarket intervention entirely.
- Integrated:Factory-fitted modules embedded during vehicle assembly with no post-production modification required. EU Cyber Resilience Act compliance mandates decade-long firmware support, forcing OEM suppliers to restructure engineering organizations around continuous security patch delivery.
- Professional:Certified technician installation of aftermarket alarm and tracking systems. Demand persists in commercial vehicle segments where fleet operators require customization beyond OEM specifications.
- DIY:Consumer self-installation of plug-and-play GPS trackers and steering wheel locks.
- Portable:Removable mechanical deterrents requiring no electrical integration.
Integrated systems command the dominant share of new vehicle production. Professional installation maintains expansion in commercial retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered electronic immobilizer standardization through KBA type-approval mandates in the 1990s, establishing regulatory templates later adopted across European and Asian markets. This historical foundation shaped how security architectures now diffuse through OEM supply chains worldwide.
Germany
Luxury automakers in Stuttgart and Munich factory-fit UWB-enabled digital keys as standard equipment, compressing demand for conventional RF immobilizers. KBA enforces decade-long firmware support obligations under EU Cyber Resilience Act implementation. Suppliers cluster in Baden-Württemberg around Continental AG and Robert Bosch GmbH engineering centers.
United States
National trucking networks negotiate enterprise-wide security bundles integrating GPS tracking with driver behavior analytics. NHTSA cybersecurity guidelines compel domestic OEMs to embed encrypted immobilizers in new vehicle configurations. Detroit-area engineering hubs concentrate telematics platform development for fleet procurement consolidation.
Japan
Flagship sedan manufacturers in Tokyo and Nagoya factory-fit biometric authentication modules with sub-500 millisecond response times. METI vehicle cybersecurity guidelines shape design-cycle investments for connected security stacks. Denso Corporation anchors supply contracts with domestic automakers seeking integrated GPS tracking architectures.
India
Commercial vehicle aggregators in Maharashtra and Gujarat pilot subscription-based immobilizer services amortizing hardware costs through monthly connectivity fees. BIS certification requirements for electronic automotive components extend qualification timelines. Bangalore-based engineering centers develop AI-enhanced geofencing algorithms for theft prediction.
South Korea
Hyundai and Kia integrate smartphone-based passive entry systems with relay attack mitigation through distance-bounding algorithms. MFDS-equivalent automotive electronics standards govern secure element chip procurement. Seoul Capital Area semiconductor fabs supply RF transponders to module assemblers serving domestic OEMs.
Automotive Smart Security Device Market Vendor Landscape
The competitive structure tilts toward diversified automotive electronics conglomerates with embedded security portfolios. Tier-1 suppliers dominate OEM procurement through multi-decade platform relationships, while specialized biometric module makers occupy premium vehicle niches. Two archetypes prevail: integrated electronics conglomerates leveraging scale and focused authentication specialists commanding margin premiums. Consolidation accelerates through strategic partnerships for UWB technology licensing and capacity expansion for secure element chip fabrication.
Among German-based diversified suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated conglomerate archetype, anchoring European OEM security architectures through embedded electronics portfolios. Denso Corporation represents the Asia-Pacific supply chain anchor, occupying a position within Japanese automaker factory-fitted configurations. These three entities collectively illustrate how geographic clustering around regulatory hubs shapes competitive positioning.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Harman International |
| Valeo |
| Autoliv Inc. |
| Aptiv PLC |
| Lear Corporation |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU type-approved immobilizers and uncertified aftermarket alternatives splits pricing power across supply chain tiers, with factory-fitted modules commanding premium positioning through KBA-validated firmware while retrofit distributors absorb margin compression from REACH compliance redesigns.
Pricing Analysis
Bundled subscription services versus unbundled hardware-only sales define the dominant pricing split. OEM-integrated security modules capture recurring connectivity revenue through telematics platform contracts, while aftermarket GPS trackers compete on transactional unit economics. Price differentiation rests on firmware certification tier and volume procurement scale, with fleet operators negotiating enterprise discounts that independent retailers cannot match. Pricing pressure intensifies in the biometric fob segment as smartphone-based digital keys displace standalone authentication hardware. Fleet procurement departments exhibit lowest price sensitivity due to insurance liability reduction, while personal vehicle owners in retail channels drive commoditization of basic alarm systems.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Nagoya coordinate hub-and-spoke patterns for just-in-time delivery to assembly lines. Secure element chip fabrication concentrates in Taiwan and South Korea, with RF transponder assembly anchored in German and Japanese electronics clusters. The supply chain draws from concentrated semiconductor inputs including cryptographic processors, UWB positioning modules, and biometric sensor arrays. Single-source vulnerability in Taiwanese foundry capacity exposes module assemblers to allocation rationing during supply shocks. Distribution runs through Tier 1 supplier direct-to-OEM channels for integrated systems, while aftermarket products flow through certified installer networks and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in firmware-as-a-service transitions, where EU Cyber Resilience Act compliance mandates create captive recurring revenue streams that offset hardware commoditization pressures.
For Market Incumbents: Deepen backward integration into secure element chip sourcing to mitigate Taiwanese foundry allocation risk. Anchor OEM platform relationships through decade-long firmware support infrastructure investments required by EU type-approval standards. Defend against smartphone substitution by embedding UWB digital key technology in premium vehicle configurations before mobile operating systems capture passive entry protocols. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched aftermarket distributor networks. Target commercial vehicle aggregators in India piloting subscription-based immobilizer services, where hardware cost amortization through monthly fees lowers entry barriers. Pursue white-label biometric module partnerships with Japanese flagship sedan manufacturers seeking sub-500 millisecond authentication response times. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification capabilities separate viable OEM suppliers from relegated aftermarket players. Position acquisitions around firms holding simultaneous NHTSA, KBA, and METI approvals for connected security stacks, compressing 14-18 month launch timelines through inherited regulatory infrastructure. Watch for inflection when fleet telematics platform providers begin exclusive security device sourcing, signaling channel compression that eliminates independent hardware distributors.| Strategic Initiative | Industry Significance |
|---|---|
| UWB Digital Key Integration | Centimeter-accurate passive entry eliminates relay attack vulnerability for German luxury automakers. |
| Firmware-as-a-Service Infrastructure | EU Cyber Resilience Act mandates decade-long security patch delivery, creating recurring revenue anchoring. |
| Biometric Authentication Module Development | Capacitive fingerprint and infrared facial recognition displace conventional fobs in Japanese flagship sedans. |
| AI-Enhanced Geofencing Investment | Machine learning anomaly detection predicts theft attempts before perimeter breaches for fleet operators. |
| Secure Element Chip Supply Agreement | Captive semiconductor sourcing mitigates Taiwanese foundry allocation rationing exposure for module assemblers. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics operators grounded qualitative findings. Secondary validation drew from NHTSA cybersecurity guideline filings, EU type-approval registries, METI vehicle security documentation, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, end user, and installation type dimensions.
Bottom-up volume modeling tracked immobilizer, GPS tracker, alarm system, and biometric module shipments by OEM integration status and aftermarket channel. Top-down validation assessed total addressable market through fleet operator procurement surveys and insurance underwriter liability term analysis. CAGRs derived from regression against historical adoption curves for connected vehicle security, adjusted for regulatory mandate acceleration effects. Forecast inputs incorporated EU Cyber Resilience Act implementation timelines, NHTSA guideline evolution, and semiconductor supply normalization assumptions across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for smartphone-based digital key protocols would alter the outlook for standalone biometric fob demand. Forecasts reflect assumptions about regulatory harmonization between EU and Japanese type-approval standards, foundry capacity allocation priorities, and fleet procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market