
 Global Parking Meter Apps Market | 2026-2036
Global Parking Meter Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Parking Meter Apps Market Foresight
The gap between premium integrated platforms and basic pay-by-phone utilities is realigning procurement priorities across city governments. ParkMobile, LLC dominates the North American municipal channel through deep API integrations with enforcement systems. Flowbird leverages its hardware legacy to anchor European contracts that bundle apps with physical meter terminals. EasyPark competes in the Nordic-Baltic corridor by specializing in cross-border roaming for commercial fleet operators.
Parking meter apps are software platforms that connect drivers to regulated parking inventory through real-time space availability, digital payment processing, and enforcement integration via license plate recognition or Bluetooth beacon confirmation. Their primary commercial purpose is to maximize curb utilization revenue while reducing traffic congestion from circling vehicles. The on-street parking segment leads absolute transaction volume because municipal authorities command the highest density of regulated spaces with strict enforcement. Off-street parking sustains the fastest expansion as commercial lot operators retrofit legacy garages with app-gated entry systems. Cross-platform deployments concentrate margin pools where single-codebase solutions reduce municipal IT maintenance burdens across Android and iOS user bases simultaneously.
The EU AI Act and GDPR constrain how parking apps process facial imagery from enforcement cameras and retain location history across member states. The US FCC governs Bluetooth beacon and cellular module certifications embedded in smart meter hardware, while municipal procurement codes in cities like Los Angeles and Chicago mandate open payment APIs to prevent vendor lock-in. Stakeholders must monitor whether fragmented national data localization rules fragment app architectures or consolidate platform providers capable of multi-jurisdictional compliance engineering.
Market Dynamics
Municipal procurement offices are consolidating vendor relationships around single-platform curb management systems that bundle payment processing, enforcement integration, and real-time occupancy analytics into unified dashboards.
Growth Catalysts
- EU AI Act compliance frameworks:Municipalities across Germany and France are mandating algorithmic transparency in license plate recognition systems, accelerating replacement of legacy enforcement hardware with certified smart meter terminals that embed compliant software stacks.
- Contactless payment mandates:The European Central Bank's retail payment directives are forcing cash-dependent municipal parking authorities to deploy app-based digital wallets, expanding addressable user bases in Southern and Eastern European cities.
- Fleet operator demand:Commercial logistics providers in Japan and the United Kingdom are requiring centralized billing across multi-city parking transactions, pulling municipal authorities toward interoperable platform architectures.
Market Restraints
- Cellular module certification costs:FCC Part 15 and CE marking requirements for Bluetooth beacon and LTE-M hardware impose six-figure pre-deployment testing burdens on smaller municipal procurement budgets.
- Vendor concentration in meter manufacturing:Three European hardware suppliers control roughly 70% of physical terminal production, creating chokepoints for cities seeking bundled app-plus-hardware contracts.
- Legacy system integration complexity:Decades-old parking management databases in Chicago, Los Angeles, and London require expensive middleware development to achieve real-time API connectivity with modern mobile platforms.
Strategic Opportunities
- India's smart city mission:The Ministry of Housing and Urban Affairs is allocating dedicated funding for intelligent transport systems in 100 designated cities, creating first-mover advantages for platform providers capable of offline-payment architectures.
- Curbside delivery zone monetization:Commercial loading bay reservations for e-commerce logistics fleets represent untapped transaction volume in dense urban cores where traditional parking revenue plateaus.
- Carbon credit integration:EU Green Deal compliance frameworks are enabling parking apps to bundle emissions-offset purchases with transaction fees, creating differentiated revenue streams in environmentally regulated municipalities.
Industry Challenges
- API standardization delays:The absence of unified data exchange protocols between municipal enforcement databases and third-party payment platforms forces redundant integration engineering for each new city deployment.
- Cybersecurity certification timelines:ISO 27001 and SOC 2 compliance requirements for payment processors are extending sales cycles by 8-14 months in risk-averse procurement environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Parking Meter Apps Market |
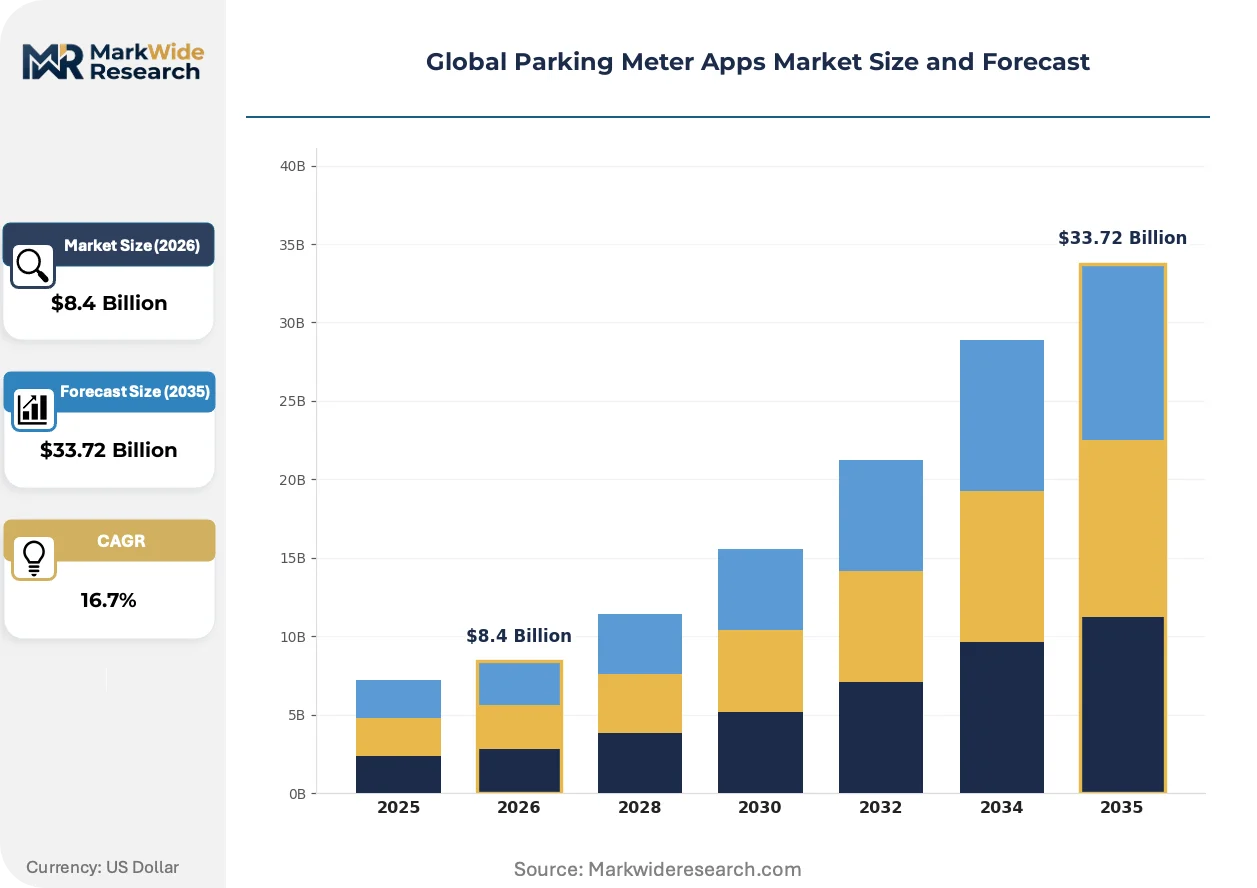
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: On-Street Parking, Off-Street Parking, Event Parking, Airport Parking, Commercial Lot Parking Platform: iOS, Android, Windows, Cross-Platform, Web-Based, Embedded Payment Method: Credit Card, Mobile Wallet, Prepaid Card, Pay-By-Phone, Contactless Payment, SMS Payment Customer Type: Municipal Authorities, Parking Management Companies, Property Owners, Event Organizers, Shopping Centers |
| Companies Covered | ParkMobile, LLC, PASSPORT LABS, INC., PayByPhone, SpotHero, Inc., Flowbird, EasyPark, INRIX, Inc., ParkMobile, JustPark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Parking Meter Apps Market Shifts & Advancements
Computer vision and edge computing are converging to transform how parking inventory is monitored, priced, and enforced. These technologies are compressing the latency between space occupancy and revenue capture.
Edge-based license plate recognition cameras with embedded AI inference chips are automating the transition from manual enforcement patrols to continuous automated violation detection. Municipal authorities in the Netherlands and Singapore are deploying these units at scale, eliminating the 15-45 minute lag between parking expiration and ticket issuance. This compression is accelerating revenue realization cycles and reducing labor costs in enforcement departments.
The EU AI Act's risk classification system for biometric identification is forcing parking app providers to rearchitect facial recognition components in enforcement camera networks. Operators must now maintain audit trails for algorithmic decision-making and enable human oversight interfaces. German and French municipalities are responding by procuring only certified hardware with embedded compliance documentation, effectively filtering non-compliant vendors from public tenders.
Fleet procurement managers are consolidating vendor relationships around single-contract multi-city parking solutions rather than managing separate municipal app registrations. This concentration is displacing the historical model where drivers maintained 8-12 distinct parking accounts across urban travel patterns. Commercial vehicle operators in the United Kingdom and Nordic corridor are driving this shift, demanding unified expense reporting and cross-border tariff transparency.
Global Parking Meter Apps Market Segmentation
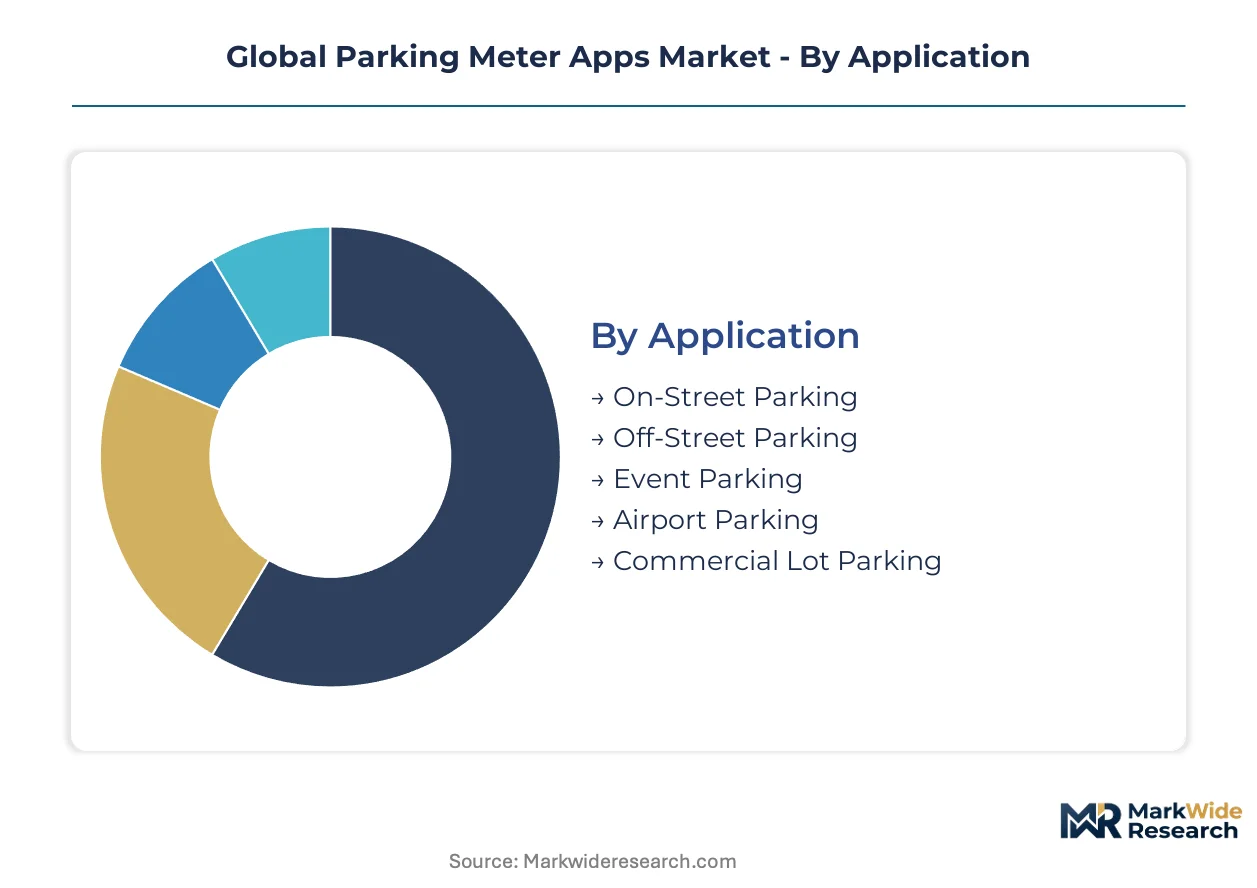
Segmentation in parking meter apps reveals how procurement priorities diverge between high-volume municipal contracts and specialized commercial deployments. Understanding these splits enables vendors to align platform architectures with distinct compliance, integration, and pricing requirements across buyer categories.
Application:
Volume concentrates in regulated curb spaces where enforcement density maximizes transaction throughput, while premium margins emerge from specialized commercial environments requiring custom integration.
- On-Street Parking:Municipal-regulated curb spaces dominate absolute transaction volume through real-time occupancy sensors and license plate recognition enforcement. Demand concentrates in Germany, the United Kingdom, and Japan where legacy meter replacement cycles overlap with mobile-first urban mobility policies and strict EU AI Act compliance requirements for automated enforcement.
- Off-Street Parking:Commercial garages and structured lots sustain the steepest expansion trajectory as operators retrofit legacy entry systems with app-gated barrier integration and pre-booking functionality. Deployment accelerates in Nordic-Baltic corridors where fleet operators demand centralized billing across multi-city commercial portfolios.
- Event Parking:Temporary venue-based deployments for sports and entertainment facilities with surge pricing algorithms and dynamic capacity management.
- Airport Parking:Long-duration structured facilities requiring flight-tracking integration and loyalty program connectivity for business travelers.
- Commercial Lot Parking:Privately operated surface lots serving retail and office parks with basic pay-by-phone functionality and minimal enforcement integration.
Mature deployment sits with On-Street Parking. Newer deployment is concentrated in Off-Street Parking.
Platform:
Customer acquisition costs and IT maintenance burdens diverge sharply between native single-OS deployments and unified cross-platform architectures.
- iOS:Native Apple ecosystem applications leveraging Apple Pay integration and Core Location services for geofenced parking zone detection. Municipal procurement in affluent North American and European cities prioritizes iOS-first deployment due to higher per-transaction revenue demographics.
- Android:Google Play-distributed platforms with broader device compatibility across mid-tier smartphones prevalent in Southern and Eastern European markets. Deployment accelerates where contactless payment mandates from the European Central Bank require rapid digital wallet expansion to cash-dependent user bases.
- Windows:Legacy desktop-administered systems for municipal back-office enforcement integration and parking operations center dashboards.
- Cross-Platform:Single-codebase solutions reducing municipal IT maintenance burdens across simultaneous Android and iOS deployments with unified API endpoints.
- Web-Based:Browser-accessible platforms eliminating app store dependency for occasional users and tourist populations.
- Embedded:Firmware integrated directly into smart meter terminal hardware for offline transaction processing in connectivity-constrained environments.
Fragmented deployment characterizes Windows and Embedded. Consolidated deployment is accelerating through Cross-Platform.
Payment Method:
Regulatory mandates and user demographic profiles determine which payment rails achieve procurement preference in municipal tenders.
- Credit Card:Traditional card-on-file systems with PCI-DSS compliance requirements and chargeback liability allocation between platform providers and municipal authorities.
- Mobile Wallet:Apple Pay, Google Pay, and Samsung Pay integration with tokenized transaction security and biometric authentication. Expansion concentrates in German and French municipalities responding to EU AI Act algorithmic transparency requirements by procuring certified hardware with embedded compliance documentation.
- Prepaid Card:Stored-value instruments favored by municipal authorities seeking reduced payment processing fees and guaranteed revenue capture.
- Pay-By-Phone:Voice-interactive systems serving accessibility requirements and demographic segments with limited smartphone adoption.
- Contactless Payment:NFC tap-to-pay functionality mandated by European Central Bank retail payment directives forcing cash-dependent Southern and Eastern European cities toward app-based digital wallet deployment.
- SMS Payment:Text-message-based transaction initiation requiring minimal smartphone capability and serving legacy user retention.
Regulatory pressure is displacing SMS Payment. Mobile Wallet and Contactless Payment are gaining procurement preference fastest.
Customer Type:
Contract value and sales cycle duration vary dramatically between centralized municipal procurement and fragmented private operator decision-making.
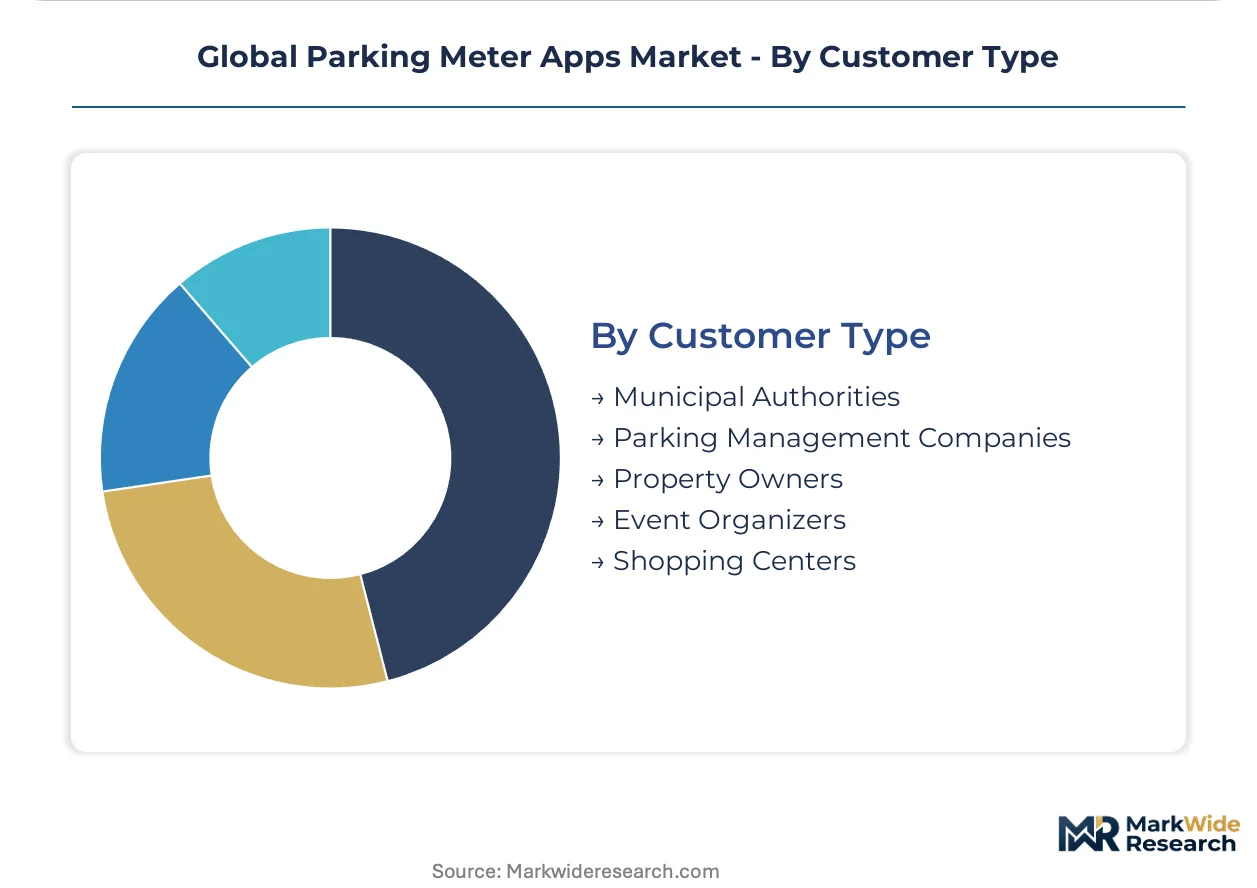
- Municipal Authorities:City and county governments commanding the highest-density regulated space inventories with strict enforcement integration requirements and open API procurement mandates in Los Angeles and Chicago preventing vendor lock-in.
- Parking Management Companies:Third-party operators managing facilities on behalf of property owners with standardized multi-site platform requirements and centralized reporting dashboards.
- Property Owners:Individual commercial real estate holders with limited IT integration needs and price-sensitive basic functionality requirements.
- Event Organizers:Temporary venue operators requiring surge-capable platforms with rapid deployment timelines and revenue-sharing contract structures.
- Shopping Centers:Retail-anchored mixed-use developments seeking loyalty program integration and dwell-time analytics for tenant revenue optimization.
Procurement consolidation centers on Municipal Authorities. Fragmented purchasing persists among Property Owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and Chicago anchor municipal procurement activity through open API mandates that prevent vendor lock-in and accelerate platform interoperability across North American smart city deployments.
Germany
KBA certification requirements for connected vehicle infrastructure drive hardware-software bundling in municipal tenders. The EU AI Act forces algorithmic transparency in license plate recognition systems, filtering non-compliant vendors from public procurement. Berlin and Hamburg lead deployment of certified smart meter terminals with embedded compliance documentation.
United Kingdom
Fleet operators demand centralized billing across multi-city commercial portfolios, pulling authorities toward interoperable architectures. The Competition and Markets Authority scrutinizes payment platform exclusivity in municipal contracts. London's congestion zone integration with parking apps creates template for curb management unification.
Japan
METI smart city directives accelerate replacement of coin-operated meters with app-gated systems in designated urban innovation zones. Commercial logistics providers require cross-border tariff transparency for multi-city parking transactions. Tokyo and Osaka concentrate deployment of real-time occupancy analytics for enforcement integration.
France
CNIL enforcement of GDPR location history retention limits constrains how parking apps process driver data across municipal boundaries. The EU Green Deal enables carbon credit bundling with transaction fees in environmentally regulated cities. Paris and Lyon procure only AI Act-certified hardware with embedded audit trail capabilities.
India
The Ministry of Housing and Urban Affairs allocates dedicated funding for intelligent transport systems across 100 designated smart cities. Offline-payment architectures gain procurement preference in connectivity-constrained environments. Mumbai and Bangalore lead pilot deployments of app-gated entry systems in commercial garage retrofits.
Global Parking Meter Apps Market Competitive Landscape
Capital-heavy hardware manufacturers compete with asset-light platform developers for municipal procurement contracts, creating bifurcated margin structures across the value chain. The vendor base concentrates around three European terminal suppliers controlling physical meter production, while software specialists capture recurring payment processing revenue. Strategic archetypes include integrated hardware-software bundlers, pure-play payment platforms, and enforcement technology specialists. Dominant competitive moves encompass API standardization lobbying and cross-border roaming partnerships for fleet operator capture.
Within the integrated bundler tier, Flowbird leverages its hardware legacy to anchor European contracts combining physical terminals with mobile platforms. ParkMobile, LLC occupies a position representing North American municipal channel dominance through enforcement system API integration. EasyPark exemplifies the cross-border specialization archetype, serving Nordic-Baltic commercial fleet operators with multi-city centralized billing.
| Leading Market Players |
|---|
| ParkMobile, LLC |
| PASSPORT LABS, INC. |
| PayByPhone |
| SpotHero, Inc. |
| Flowbird |
| EasyPark |
| INRIX, Inc. |
| ParkMobile |
| JustPark |
| Others |
Supply & Pricing Matrix
Edge-based license plate recognition deployments are compressing enforcement labor costs while concentrating procurement power among hardware-software bundlers capable of certified AI Act compliance. This technology transition simultaneously elevates upfront platform investment requirements and filters smaller municipal vendors from tender participation.
Pricing Analysis
Value-based pricing anchored to transaction throughput dominates municipal procurement, with platforms commanding premium rates for real-time occupancy analytics and enforcement integration. Price differentiation separates certified EU AI Act-compliant bundles from basic pay-by-phone utilities, while customization for legacy system middleware drives project-based surcharges. Pricing pressure stems from open API mandates in Los Angeles and Chicago that prevent vendor lock-in and commoditize core payment processing. Municipal authorities exhibit highest price sensitivity, whereas commercial fleet operators prioritize cross-border interoperability over per-transaction cost.
Supply Chain Analysis
Single-source vulnerability sits with three European terminal suppliers controlling physical smart meter production. Hardware assembly concentrates in Germany, France, and the Netherlands, drawing from specialized AI inference chip suppliers and LTE-M cellular module manufacturers. Supply chain risk centers on FCC Part 15 and CE marking certification delays that extend deployment timelines. Distribution runs through municipal procurement offices consolidating around unified curb management dashboards rather than fragmented point solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parking meter apps sector sits in a technology-transition phase where computer vision and edge computing are displacing manual enforcement patrols and legacy coin-operated infrastructure.
For Market Incumbents: Acquire enforcement technology specialists to deepen API integration capabilities and defend against pure-play platform entrants. Prioritize backward integration into AI inference chip supply chains to mitigate certification bottlenecks. Consolidate municipal relationships around bundled hardware-software contracts before open API mandates fragment pricing power. For New Entrants and Emerging Players: Direct-to-fleet sales channels offer the most penetrable route, targeting commercial logistics providers demanding centralized multi-city billing. India's smart city mission presents geographic white space where offline-payment architectures gain procurement preference. Lead with curbside delivery zone monetization pilots to demonstrate differentiated value beyond traditional parking revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as municipal procurement offices reduce vendor counts. Long-term viability favors providers with multi-jurisdictional compliance engineering capabilities spanning GDPR, EU AI Act, and FCC certification requirements. Watch for India's 100-city intelligent transport system funding allocation as an inflection indicator for emerging market platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Lobbying | Open payment protocols in Los Angeles and Chicago prevent vendor lock-in and accelerate municipal platform interoperability. |
| Cross-Border Roaming Partnership | Fleet operators in the United Kingdom and Nordic corridor demand unified expense reporting across multi-city parking transactions. |
| AI Act Compliance Certification | German and French municipalities filter non-compliant vendors by procuring only certified hardware with embedded audit trails. |
| Curbside Delivery Monetization | E-commerce logistics fleets in dense urban cores represent untapped transaction volume where traditional parking revenue plateaus. |
| Carbon Credit Integration | EU Green Deal frameworks enable parking apps to bundle emissions-offset purchases with transaction fees in environmentally regulated cities. |
Research Methodology
Trade association filings, municipal procurement databases, and connected vehicle infrastructure reports formed the secondary backbone, supplemented by regulatory documentation from the EU AI Act and FCC Part 15 certification records. Primary interviews with municipal parking directors, fleet procurement managers, smart meter hardware engineers, and enforcement technology specialists validated demand assumptions and integration complexity estimates. Bottom-up transaction volume modeling across on-street and off-street segments triangulated against top-down market sizing from platform provider revenue disclosures.
Historical trendline analysis of legacy meter replacement cycles and mobile payment adoption curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include application type, platform architecture, payment method, and customer procurement archetype, with particular attention to municipal versus commercial operator decision-making divergence. CAGRs were derived from elasticity analysis of enforcement density and digital wallet penetration rates, incorporating fleet operator demand pull and contactless payment mandate compliance timelines as industry-specific inputs.
The model holds under stable regulatory certification timelines and continued municipal smart city funding; deviation in cellular module supply constraints or data localization rule fragmentation would shift deployment trajectories. Forecasts reflect assumptions about open API standardization progress and hardware-software bundling preferences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Alternate Transportation Market