
 United States Automotive Airbag Systems Market | 2026-2036
United States Automotive Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Airbag Systems Market Analytics
Silicon-coated fabrics are displacing conventional neoprene-coated materials in inflator housings and is recalibrating cost structures across the supply base. Autoliv Inc. leverages its vertical manufacturing footprint to control inflator assembly quality from raw fabric to finished module. Continental AG anchors its position through deep integration with German and US-based OEM program teams. ZF Friedrichshafen AG competes on multi-stage deployment algorithms tied to its chassis electronics portfolio.
Automotive airbag systems are pyrotechnic safety devices comprising fabric cushions, gas generators, and electronic control units that deploy within milliseconds of collision detection to mitigate occupant injury. Inflator housings typically use pressed steel or aluminum castings with specified burst pressures exceeding 300 bar to ensure reliable gas release. Frontal airbags retain the largest volume share as NHTSA mandates their presence in all light vehicles sold domestically. Multi-stage deployment systems represent the fastest-expanding segment because they enable force-calibrated responses based on occupant size and crash severity. OEMs command the dominant procurement channel, though aftermarket providers are gaining traction in fleet refurbishment programs.
NHTSA's Federal Motor Vehicle Safety Standard 208 and FMVSS 214 govern frontal and side-impact protection requirements, compelling continuous sensor and algorithm upgrades. The EPA regulates pyrotechnic waste streams from inflator manufacturing, adding environmental compliance costs to production economics. Stakeholders must monitor evolving NCAP protocols and state-level autonomous vehicle testing rules that could redefine occupant positioning and airbag placement logic.
Market Dynamics
Multi-stage deployment algorithms are recalibrating supply chain relationships as tier-one suppliers internalize sensor fusion and inflator control electronics previously sourced separately.
Growth Catalysts
- FMVSS 208 mandates:NHTSA's frontal protection standards compel continuous sensor upgrades and algorithm refinements across all light vehicle platforms sold domestically.
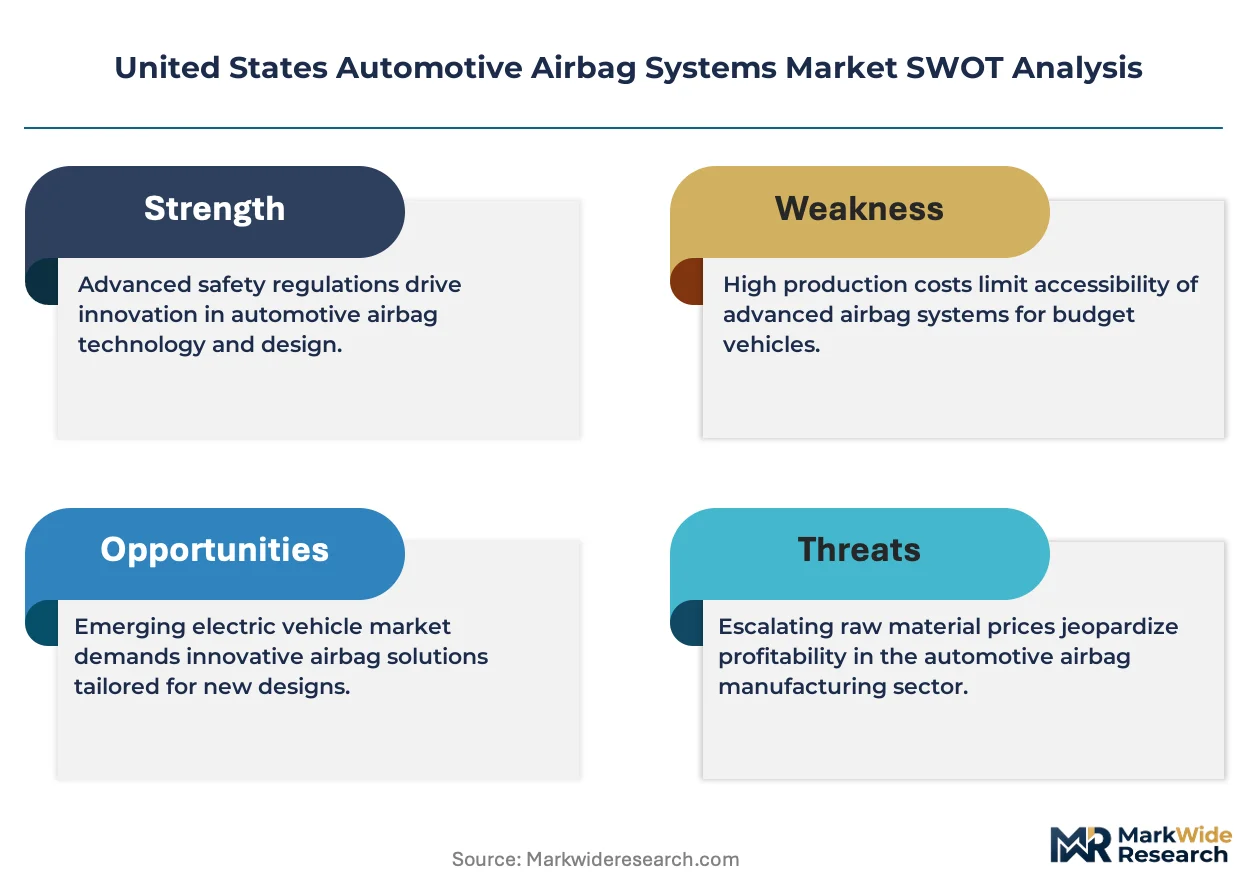
- Electric vehicle cabin architectures:Flat-floor battery layouts enable novel airbag placement configurations that expand addressable surface area for occupant protection systems.
- Michigan manufacturing corridor concentration:Proximity to Detroit-area OEM engineering centers accelerates prototype-to-production cycles for module suppliers.
Market Restraints
- Pyrotechnic material cost volatility:Sodium azide and guanidinium nitrate prices fluctuate with specialty chemical feedstock availability, squeezing inflator margins unpredictably.
- Single-source inflator housing casting:Domestic pressed steel and aluminum casting capacity concentrates among three Midwest suppliers, creating bottleneck vulnerability.
- Recyclability compliance burden:EPA hazardous waste rules for spent inflators add end-of-life processing costs that OEMs increasingly resist absorbing.
Strategic Opportunities
- Autonomous vehicle repositioning:NHTSA's evolving AV testing protocols may mandate new airbag geometries for non-traditional seating orientations in robotaxi configurations.
- Fleet refurbishment channel:Rental and commercial fleet operators are creating standardized replacement schedules for degraded airbag modules outside OEM service networks.
- Silicon-coated fabric convergence:Integration of advanced textile processing with semiconductor-grade coating equipment opens performance tiers previously unreachable with neoprene substrates.
Industry Challenges
- Embedded software validation:Multi-stage deployment algorithms require extensive crash-data correlation that stretches calibration engineering headcount at tier-one suppliers.
- Legacy vehicle integration:Retrofitting modern sensor arrays into platforms engineered for single-point crash detection demands extensive wiring harness reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Airbag Systems Market |
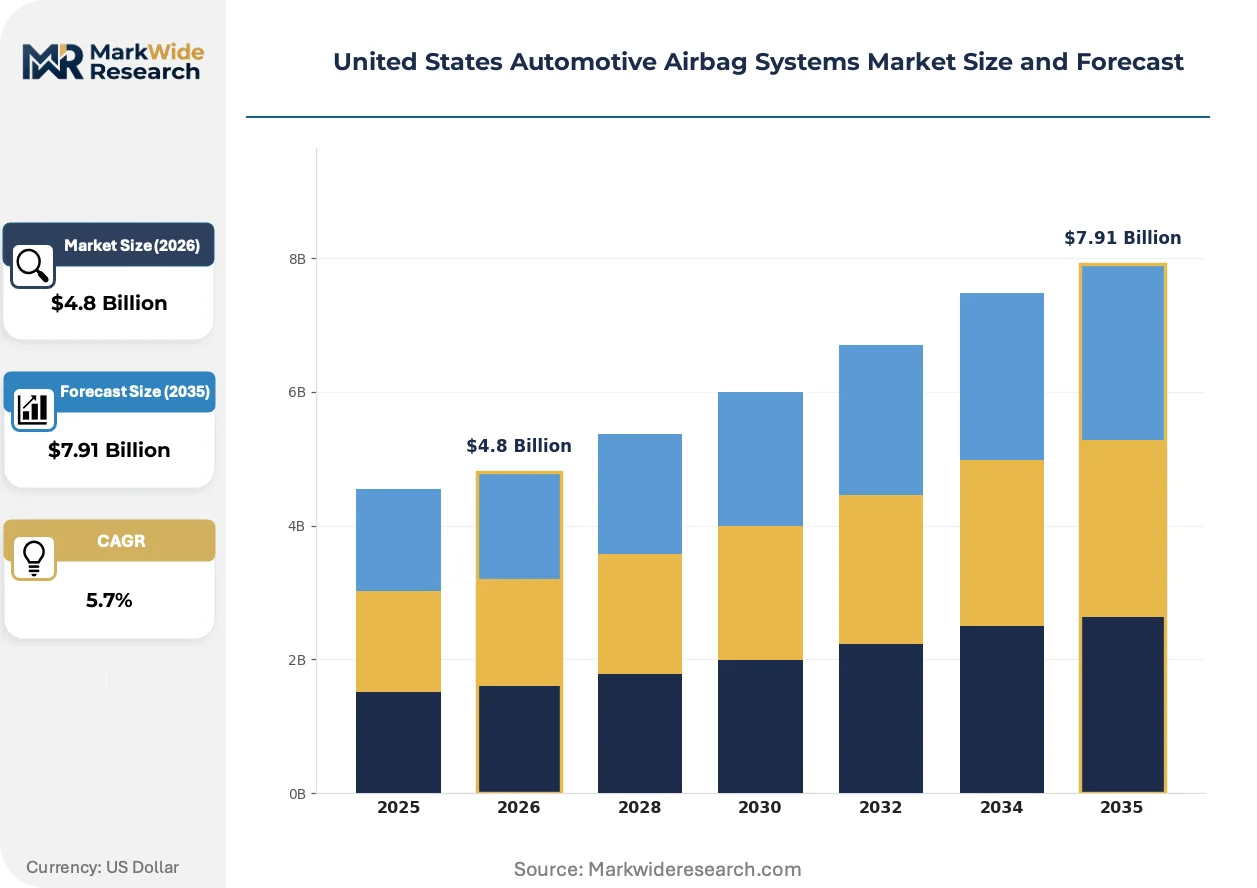
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Deployment: Once-Stage Deployment, Multi-Stage Deployment, Adaptive Deployment, Hybrid Deployment End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Inflatable Curtains, Sensors, Pyrotechnic Devices, Electronic Control Units |
| Companies Covered | Continental AG, Hyundai Mobis Co., Ltd., Joyson Safety Systems, Toyoda Gosei Co., Ltd., Denso Corporation, Autoliv Inc., Robert Bosch GmbH, Sumitomo Corporation, ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Airbag Systems Market Evolving Landscape
Deployment logic sophistication is outpacing hardware refresh cycles, forcing suppliers to decouple software update pathways from physical module replacement schedules.
Silicon-coated aramid fabrics are rewriting inflator housing thermal management capabilities by sustaining burst-pressure integrity at temperatures that degrade conventional neoprene laminates. Tier-one suppliers serving Detroit-based OEM programs have accelerated qualification timelines for these materials across 2024-2025 model year platforms. The shift is compressing qualification windows for incumbent coating technologies while expanding addressable performance specifications for next-generation side-curtain modules.
NHTSA's updated FMVSS 214 side-impact protocols are mandating faster sensor response thresholds and expanded coverage zones for torso and head protection. The regulatory tightening is forcing recalibration of accelerometer placement and algorithm trigger points across all domestic light truck and SUV platforms. Suppliers with integrated sensor-inflator architectures are capturing disproportionate engineering engagement from Michigan-based OEM technical centers.
Fleet operators are consolidating airbag module procurement through direct tier-one relationships rather than franchised dealer service channels. Rental car companies and last-mile delivery fleets in the Midwest are negotiating volume-based replacement schedules that bypass traditional aftermarket distribution. This channel compression is most visible among commercial vehicle operators in Ohio and Indiana seeking predictable maintenance cost structures.
United States Automotive Airbag Systems Market Segmentation
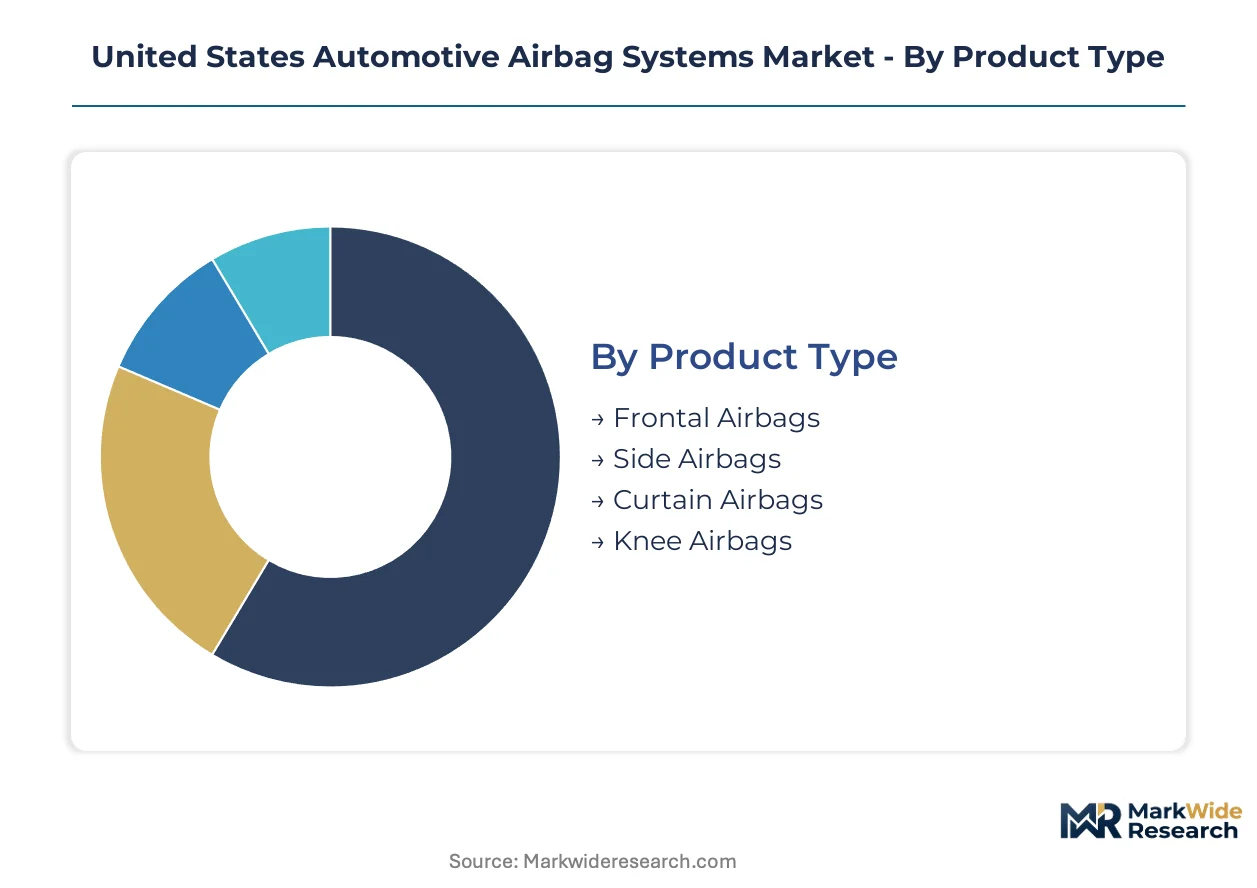
Airbag system segmentation reveals how procurement authority, deployment sophistication, and cabin architecture evolution are fragmenting supplier relationships across the United States. Category boundaries increasingly blur as tier-one suppliers bundle sensors, inflators, and control electronics into integrated modules.
Product Type:
Supply concentration in pressed steel and aluminum casting capacity shapes which product categories command premium engineering resources and fastest qualification timelines.
- Frontal Airbags:Dual-chamber fabric cushions with specified burst pressures exceeding 300 bar remain the baseline occupant protection mandate under NHTSA FMVSS 208. Michigan-based OEM engineering centers allocate the majority of prototype-to-production bandwidth to these modules, driven by universal fitment requirements across light vehicle platforms.
- Curtain Airbags:Silicon-coated aramid fabrics are displacing neoprene laminates in side-curtain modules, sustaining thermal integrity at temperatures that degrade conventional materials. Ohio and Indiana fleet operators are driving replacement demand for these units as commercial vehicle coverage zones expand under updated FMVSS 214 protocols.
- Side Airbags:Torso-focused modules with accelerometer-triggered deployment occupy intermediate cost tiers between frontal and curtain systems.
- Knee Airbags:Lower-dash positioning for femur protection commands niche specification in premium vehicle segments.
Today's leader: Frontal Airbags. Tomorrow's challenger: Curtain Airbags.
Deployment:
Cost tier stratification separates single-point trigger systems from force-calibrated multi-stage architectures with embedded software validation burdens.
- Multi-Stage Deployment:Algorithms correlating occupant size, seating position, and crash severity require extensive crash-data calibration that stretches engineering headcount at tier-one suppliers. Detroit-area technical centers prioritize these systems for mid-cycle platform refreshes seeking differentiation through adaptive protection logic.
- Once-Stage Deployment:Single-threshold pyrotechnic release remains the cost-optimized standard for fleet vehicle procurement and economy platform fitment. Midwest rental car operators specify these modules in volume replacement schedules to minimize per-unit acquisition expense.
- Adaptive Deployment:Real-time sensor fusion enabling deployment force modulation sits at the premium tier of technology roadmaps.
- Hybrid Deployment:Combined pyrotechnic and compressed gas mechanisms occupy emerging specification territory for electric vehicle flat-floor architectures.
Multi-Stage Deployment commands current engineering engagement. Hybrid Deployment represents the steepest expansion trajectory as battery-electric cabin layouts enable novel placement geometries.
End User:
Customer type determines whether procurement flows through franchised dealer networks or direct tier-one relationships with compressed distribution layers.
- OEMs:Integrated program teams at Michigan-based vehicle manufacturers dominate volume procurement, specifying module architectures that bundle inflator housings, fabric cushions, and electronic control units from qualified supplier pools. NHTSA mandate compliance and NCAP rating optimization drive their continuous sensor and algorithm upgrade cycles.
- Fleet Operators:Rental and last-mile delivery companies in Ohio and Indiana are consolidating direct tier-one relationships, negotiating predictable replacement schedules outside traditional aftermarket channels to control maintenance cost structures.
- Aftermarket Providers:Independent service networks capture refurbishment demand from legacy vehicle populations outside warranty coverage.
- Vehicle Assemblers:Contract manufacturing operations with limited engineering authority execute module installation per OEM specification.
OEMs retain volume leadership. Fleet Operators are gaining procurement share fastest through channel compression strategies.
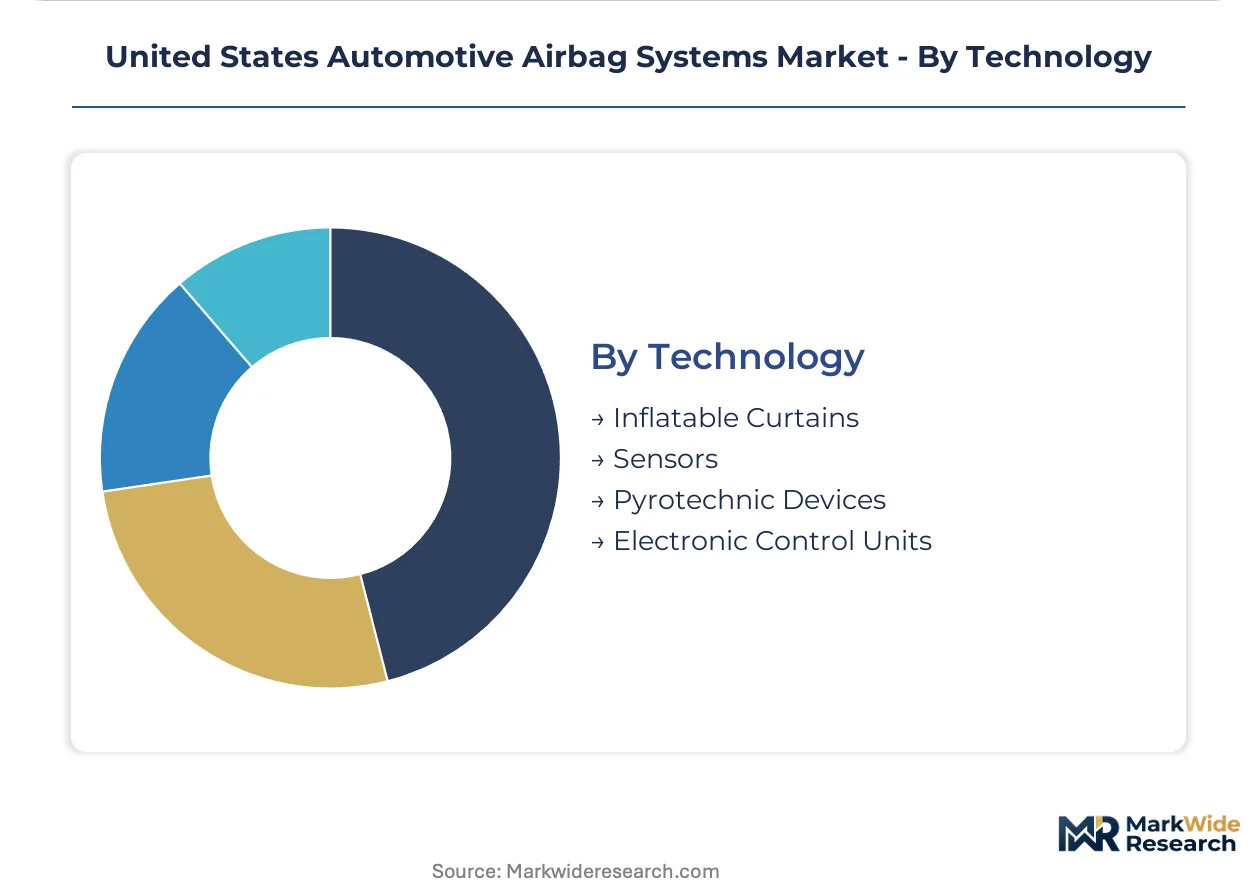
Technology:
Application maturity separates commoditized pyrotechnic components from sensor fusion and control electronics with embedded software validation requirements.
- Sensors:Accelerometer arrays and pressure transducers with placement optimized for FMVSS 214 response thresholds represent the fastest-evolving technology layer. Suppliers with captive sensor-inflator integration are capturing disproportionate engagement from Detroit engineering centers.
- Electronic Control Units:Deployment algorithm processors with multi-stage calibration capabilities concentrate value capture among suppliers with embedded software competencies.
- Inflatable Curtains:Fabric cushion architectures with silicon-coated textile processing are climbing specification tiers.
- Pyrotechnic Devices:Sodium azide and guanidinium nitrate gas generators face feedstock cost volatility and EPA hazardous waste compliance burdens.
Sensors lead technology investment intensity. Electronic Control Units are ascending the value stack through software-defined differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Michigan automotive manufacturing corridor anchors domestic airbag system demand through proximity to Detroit-area OEM engineering centers and tier-one supplier technical facilities.
Midwest
Ohio and Indiana fleet operators drive aftermarket replacement demand for curtain airbag modules as commercial vehicle coverage zones expand under NHTSA protocols. The EPA regulates pyrotechnic waste streams from inflator manufacturing facilities concentrated in this region. Detroit technical centers allocate majority prototype-to-production bandwidth to frontal airbag modules for universal platform fitment.
Southeast
Tennessee and South Carolina vehicle assembly plants generate specification pull for multi-stage deployment systems in mid-cycle platform refreshes. NHTSA's FMVSS 214 side-impact standards compel sensor placement recalibration across light truck and SUV platforms manufactured in this corridor. Atlanta-area logistics hubs facilitate compressed distribution channels for fleet operator direct procurement.
Southwest
Texas-based commercial fleet operators negotiate volume-based replacement schedules outside traditional aftermarket distribution networks. Federal Motor Vehicle Safety Standard 208 mandates drive continuous algorithm upgrades for vehicles registered in high-volume urban markets. Dallas-Fort Worth logistics clusters support direct tier-one relationships with rental and last-mile delivery operators.
West Coast
California electric vehicle manufacturers pioneer novel airbag placement configurations enabled by flat-floor battery architectures. NHTSA's evolving autonomous vehicle testing protocols influence occupant positioning requirements for robotaxi configurations under development in Silicon Valley. Los Angeles-area technical centers focus on adaptive deployment algorithms for premium vehicle segments.
Northeast
New York and New Jersey commercial vehicle operators consolidate procurement through direct supplier relationships to control maintenance cost structures. State-level autonomous vehicle testing rules complement federal NHTSA standards for non-traditional seating orientations. Boston-area engineering clusters contribute embedded software validation capabilities for multi-stage deployment systems.
United States Automotive Airbag Systems Market Competitive Landscape
Backward integration into sensor fusion and inflator control electronics dominates the current competitive landscape as tier-one suppliers internalize capabilities previously sourced separately. The vendor base concentrates among integrated module providers with captive textile processing and pyrotechnic manufacturing capabilities. Three strategic archetypes define positioning: full-system integrators with vertical manufacturing footprints, component specialists with deep OEM program relationships, and diversified automotive suppliers leveraging chassis electronics portfolios. M&A activity and capacity expansion in silicon-coated fabric processing represent the dominant competitive moves reshaping supply relationships.
Among German-based diversified suppliers, Continental AG and ZF Friedrichshafen AG exemplify the full-system integrator archetype through integrated program team structures with domestic OEM engineering centers. Autoliv Inc. anchors the specialist tier with concentrated technical resources in inflator assembly quality control from raw fabric through finished module deployment.
| Leading Market Players |
|---|
| Continental AG |
| Hyundai Mobis Co., Ltd. |
| Joyson Safety Systems |
| Toyoda Gosei Co., Ltd. |
| Denso Corporation |
| Autoliv Inc. |
| Robert Bosch GmbH |
| Sumitomo Corporation |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Multi-stage deployment certification separates premium module suppliers from commodity inflator providers, with that performance gap widening procurement access to Detroit-area OEM engineering centers while compressing margins for single-threshold systems serving Midwest fleet operators. This bifurcation concentrates pricing power among integrated suppliers with captive sensor-inflator architectures and silicon-coated fabric processing, leaving price-takers dependent on volatile pyrotechnic feedstock markets.
Pricing Analysis
Input-cost pass-through from sodium azide and guanidinium nitrate volatility squeezes inflator margins unpredictably, forcing contract-based long-term offtake agreements for specialty chemical security. Price differentiation centers on FMVSS 214 compliance tier and OEM program integration depth, with NHTSA-certified multi-stage systems commanding substantial premiums over economy single-threshold modules. Pricing pressure stems from EPA hazardous waste compliance burdens that OEMs increasingly resist absorbing in end-of-life processing. Fleet operators in Ohio and Indiana exhibit highest price sensitivity through volume-based replacement schedules, while premium vehicle segments prioritize adaptive deployment algorithms over unit cost.
Supply Chain Analysis
Workforce availability constraints in Michigan, Ohio, and Indiana shape pressed steel and aluminum casting capacity allocation for inflator housings, with three Midwest suppliers controlling bottleneck-vulnerable domestic production. The supply chain draws from German and Japanese sensor component sources, Chinese textile processing equipment, and domestic pyrotechnic chemical blending operations. Single-source vulnerability concentrates in housing casting capacity, where limited qualified suppliers create procurement queue risks for module assemblers. Distribution runs through direct tier-one relationships with Detroit OEMs and compressed channels to fleet operators, bypassing traditional aftermarket layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Michigan's engineering-proximity premium and Indiana-Ohio fleet procurement compression, with NHTSA regulatory tightening widening the cost-performance spread between compliant and legacy systems.
For Market Incumbents: Deploy backward integration into silicon-coated fabric processing to defend margin position against neoprene laminate displacement and capture specification upgrades for side-curtain modules. Anchor Detroit-area technical center relationships through embedded engineering teams that accelerate prototype-to-production cycles. Add sensor-inflator integration capacity to counter emerging entrants with modular electronics sourcing. For New Entrants and Emerging Players: FMVSS 214 side-impact protocol updates in the United States open a window for accelerometer placement specialization and algorithm calibration services that tier-one suppliers struggle to resource. Target fleet refurbishment channels in Indiana and Ohio with standardized replacement schedules that bypass franchised dealer networks. Pursue direct procurement relationships with rental car operators seeking predictable maintenance cost structures. For Investors and Strategic Acquirers: Consolidation pressure builds where silicon-coated fabric processing capacity concentrates among suppliers with semiconductor-grade coating equipment and OEM qualification timelines. Long-term viability favors integrated module providers with captive textile-to-inflator manufacturing footprints over component specialists exposed to pyrotechnic feedstock volatility. Watch NHTSA autonomous vehicle testing protocol evolution as the signal for airbag geometry redesign demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Coated Fabric Capacity Expansion | Captures specification upgrades for FMVSS 214-compliant side-curtain modules in Detroit OEM programs. |
| Sensor-Inflator Integration Investment | Consolidates algorithm control and accelerometer placement within single supplier architectures. |
| Fleet Direct Procurement Channel | Bypasses aftermarket distribution layers to capture Ohio and Indiana commercial vehicle replacement demand. |
| Pyrotechnic Feedstock Security Agreement | Locks sodium azide supply pricing against specialty chemical volatility squeezing inflator margins. |
| Autonomous Vehicle Airbag Geometry Development | Positions for NHTSA robotaxi occupant protection mandates requiring non-traditional seating configurations. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core, combining primary interviews with Tier 1 procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors with secondary validation through NHTSA FMVSS compliance filings, EPA hazardous waste regulatory records, vehicle registration databases, and IHS Markit production data. Triangulation across these sources yields volume and value estimates segmented by product type, deployment sophistication, end-user channel, and technology layer.
The input-output matrix framing connects vehicle platform forecasts to airbag content-per-vehicle assumptions across the projection horizon, with segmentation dimensions spanning frontal/curtain/side/knee product categories, single-stage/multi-stage/adaptive/hybrid deployment tiers, OEM/fleet/aftermarket/assembly end-user channels, and sensor/ECU/curtain/pyrotechnic technology layers. CAGRs derive from regression-based correlation with automotive production cycles and regulatory mandate implementation timelines, incorporating electric vehicle cabin architecture evolution and silicon-coated fabric adoption curves as industry-specific forecast inputs.
Revisions become necessary when NHTSA protocol updates, pyrotechnic feedstock supply disruptions, or EPA waste handling rule changes materialize outside baseline assumptions. Forecasts reflect documented conditions at time of analysis with acknowledged sensitivity to autonomous vehicle regulatory acceleration and fleet electrification timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Driving Armor Market